
 Vacuum Forming Plastic Market | 2026-2036
Vacuum Forming Plastic Market Size, Share, and Industry Trends Forecast 2026-2036
Vacuum Forming Plastic Market Insights
Food-contact-grade and medical-grade specification tiers are reorganizing competitive priorities across the vacuum forming plastic supply base. Profile Plastics leverages its specialization in heavy-gauge industrial components to command premium positioning in North American tooling markets. Engineered Plastic Products sustains long-term contracts with automotive OEMs through backward integration into sheet extrusion. Robinson Industries anchors its position in the signage and display channel through proprietary pressure-forming capabilities that extend beyond standard vacuum forming.
Vacuum forming plastic involves heating thermoplastic sheet material until pliable, then drawing it over a mold using vacuum pressure to create precise three-dimensional shapes with wall thickness typically ranging from 0.005 to 0.500 inches. The process serves commercial and industrial applications requiring cost-effective, repeatable production of enclosures, trays, housings, and protective covers with moderate structural complexity. Acrylic and polycarbonate product types lead in optical clarity applications where light transmission exceeds 85%, while PVC dominates price-sensitive packaging segments where flame resistance and chemical stability matter. Thin gauge sheet commands the highest volume in disposable medical tray and blister pack applications, whereas heavy gauge thermoforming captures superior margin pools in permanent equipment housings and transit infrastructure components.
The EPA regulates volatile organic compound emissions from thermoforming operations under Clean Air Act standards, while FDA 21 CFR requirements govern material composition for food-contact and medical-device applications, creating dual compliance thresholds that shape supplier qualification. ISO 9001 quality management certification and ISO 13485 medical device standards further segment the vendor base between general industrial and healthcare-capable producers. Stakeholders must monitor evolving state-level extended producer responsibility laws and resin recycling mandates that will redefine feedstock sourcing economics and capital allocation priorities.
Market Dynamics
Medical device packaging standards are tightening across Germany, the United States, and Japan, forcing converters to recertify production lines and segregate cleanroom-capable capacity from general industrial operations.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon blowing agents is accelerating adoption of lower-emission vacuum forming processes in automotive component manufacturing across Germany and France.
- Healthcare packaging:FDA 21 CFR compliance requirements for sterile barrier systems are pulling investment toward thin-gauge thermoforming lines dedicated to surgical trays and implantable device packaging.
- Automotive lightweighting:Polycarbonate and ABS vacuum formed housings are replacing metal stampings in electric vehicle battery enclosures and charging infrastructure across China's manufacturing belt.
Market Restraints
- Resin price volatility:Acrylic and polycarbonate feedstock costs fluctuate with benzene and bisphenol-A spot markets, compressing margin stability for independent thermoformers without captive extrusion.
- Tooling concentration:Precision aluminum mold fabrication concentrates in southern Germany and northern Italy, creating lead time bottlenecks and geographic supply risk for North American and Asian converters.
- Substitution pressure:Injection molding is reclaiming share in medical device enclosures where wall thickness uniformity exceeds vacuum forming capability, particularly for complex undercut geometries.
Strategic Opportunities
- India pharmaceutical packaging:CDSCO's alignment with EU MDR and impending traceability mandates for medical devices is opening demand for ISO 13485-certified thermoforming capacity in Maharashtra and Gujarat.
- Recycled content integration:EU Green Deal circular economy requirements and Germany's Packaging Act amendments are creating first-mover advantage for converters with validated post-industrial and post-consumer PET sheet supply chains.
- Pressure-forming hybridization:Convergence of vacuum forming with pressure-assist technology is enabling deeper draw ratios and sharper detail for premium automotive interior components and aerospace cabin modules.
Industry Challenges
- Cleanroom certification timelines:ISO 14644 Class 7 and Class 8 validation for medical-grade production requires 12-18 month facility modification cycles, delaying revenue conversion from healthcare contract awards.
- Skilled toolmaker shortage:CNC machining and composite mold fabrication expertise concentrates among aging workforces in Bavaria and Lombardy, constraining expansion of precision forming capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vacuum Forming Plastic Market |
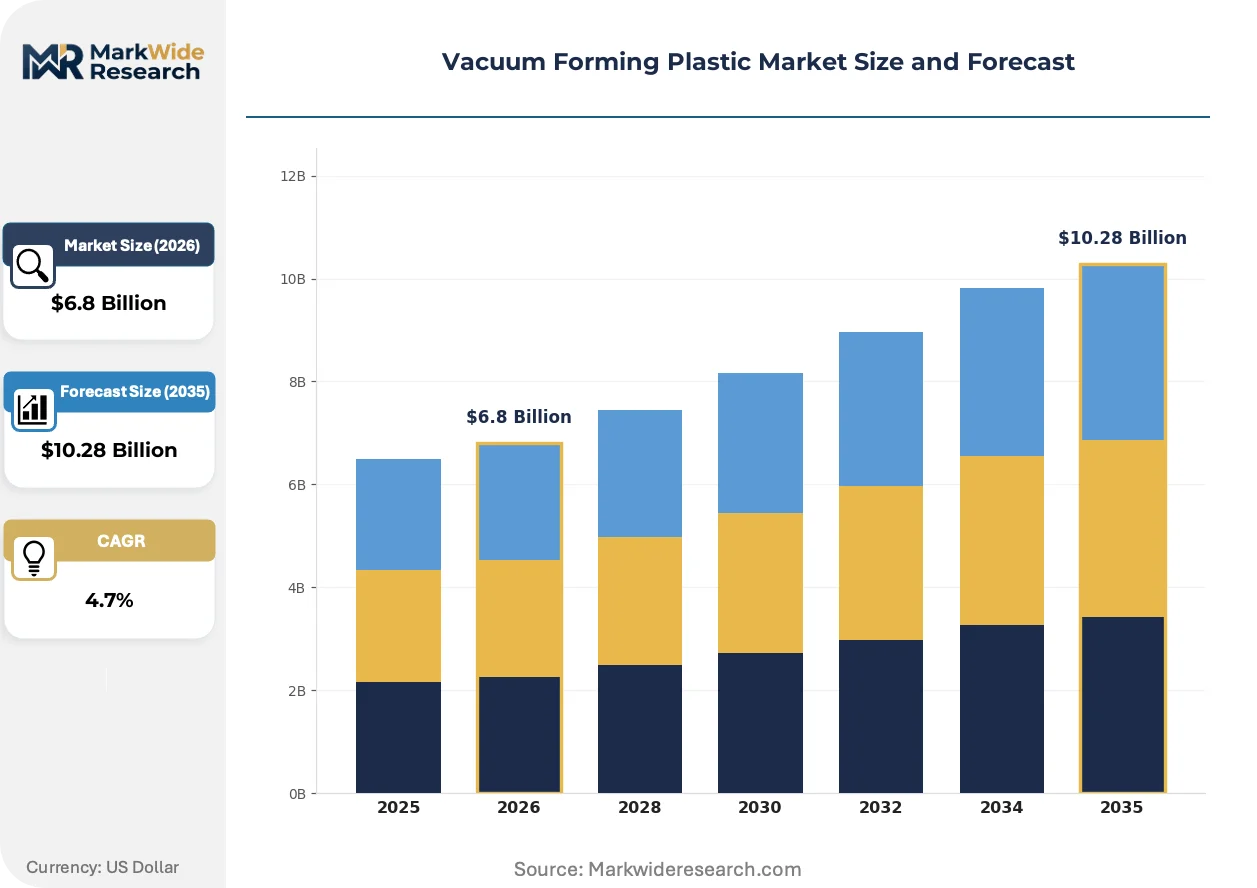
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Polycarbonate, PVC, Polystyrene End User: Automotive, Packaging, Electronics, Consumer Goods Application: Signage, Retail Displays, Medical Devices, Industrial Components Thickness: Thin Gauge, Medium Gauge, Heavy Gauge, Ultra-Heavy Gauge |
| Companies Covered | Conlet Plastics, Profile Plastics, Engineered Plastic Products, Arrowhead, SAY Plastics, Robinson Industries, BCJ Plastic Products, Emco, Multiplastics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vacuum Forming Plastic Market Trends and Innovations
Process digitization and material science advances are compressing development cycles and expanding the geometric complexity achievable through thermoforming, while regulatory pressure on emissions and recyclability is restructuring supplier qualification criteria.
Plug-assist vacuum forming with servo-controlled pressure modulation is supplanting conventional single-stage vacuum processes in automotive interior component production. Tier 1 suppliers in Germany and the United States are retrofitting lines to achieve ±0.1mm wall thickness tolerance for Class A surface finishes. This technology is supplanting traditional methods by enabling direct substitution of injection molded panels in low-to-medium volume electric vehicle programs.
REACH restrictions on phthalate plasticizers and the EU F-Gas Regulation's hydrofluorocarbon phase-down are forcing reformulation of PVC and foam-core sheet stocks. Compounders in Belgium and the Netherlands are commercializing bio-based plasticizer systems and CO2-blown foam cores to maintain processability. Medical packaging converters face the steepest compliance curve, as FDA 21 CFR material master file updates must synchronize with EU MDR technical documentation.
Automotive OEMs are consolidating supplier panels and mandating direct material traceability from resin pellet to formed component. Tier 2 thermoformers in Michigan and Ontario are investing in ERP-integrated batch tracking and blockchain-enabled certificate of analysis systems. This consolidation is most visible in North American electric vehicle battery enclosure supply chains, where single-source accountability requirements are eliminating multi-tier subcontracting arrangements.
Vacuum Forming Plastic Market Segmentation
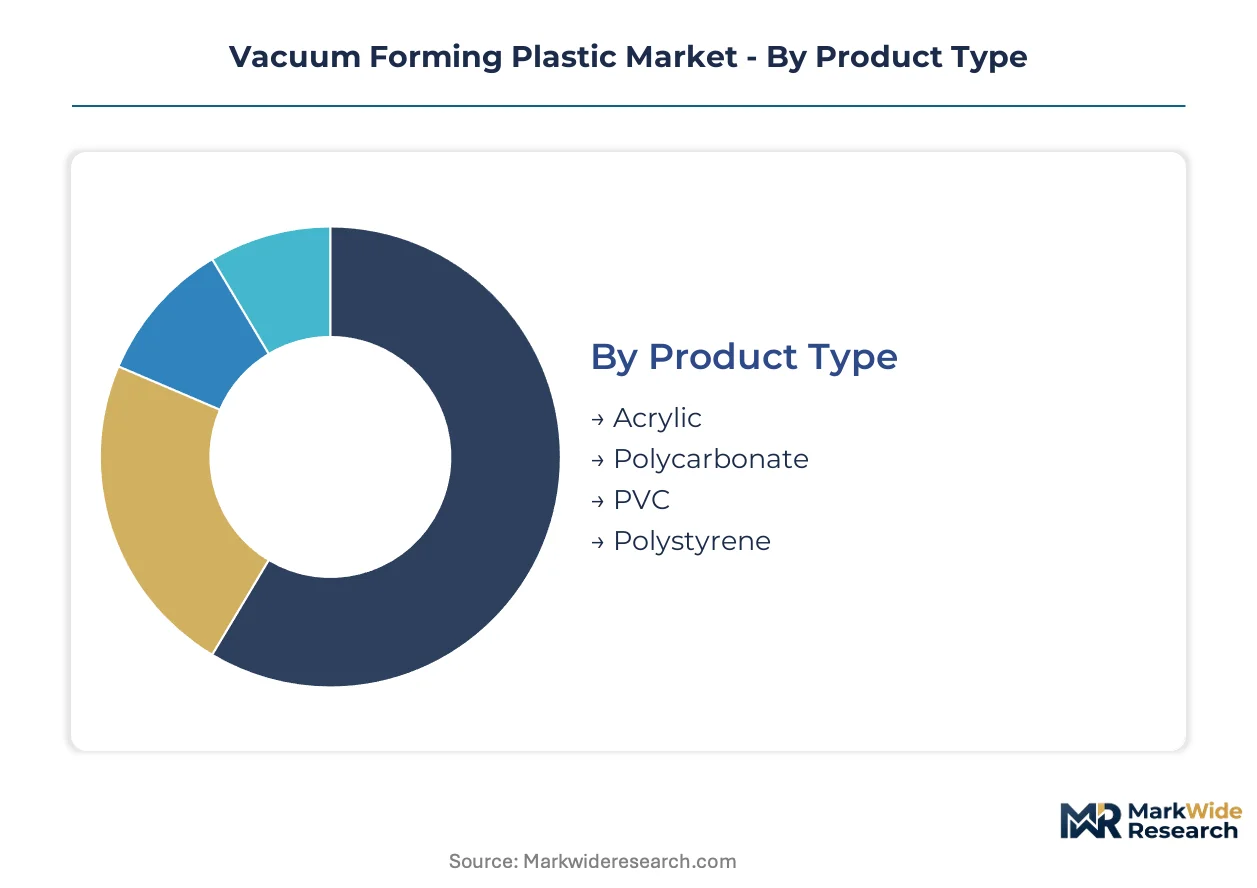
Segmentation in vacuum forming plastic separates commodity-grade volume from specification-driven margin pools. Material chemistry, end-use certification requirements, and gauge thickness collectively determine which converters capture premium pricing versus competing on throughput.
Product Type:
Margin concentration tracks optical clarity performance and regulatory compliance burden rather than raw tonnage.
- Acrylic:Thermoplastic with light transmission exceeding 92% and UV stability for outdoor durability. Demand concentrates in German automotive interior programs and North American retail signage where Class A surface finish commands specification lock-in. REACH compliance on residual monomer content creates qualification barriers that filter out commodity suppliers.
- Polycarbonate:Amorphous thermoplastic delivering impact resistance 250x greater than glass at equivalent thickness. Battery enclosure contracts across China's electric vehicle manufacturing belt are pulling heavy-gauge sheet demand as OEMs substitute metal stampings for weight reduction. FDA 21 CFR material master files for medical-grade grades extend sales cycles but secure multi-year supply agreements.
- PVC:Cost-optimized formulation with inherent flame retardancy and chemical resistance. Price-sensitive packaging segments in India and Southeast Asia dominate volume offtake.
- Polystyrene:Lowest-density option enabling thin-gauge disposable applications. Food-contact compliance limitations restrict expansion beyond single-use trays and blister packs.
Polycarbonate holds installed capacity. Acrylic is rotating up the share rankings.
End User:
Customer type determines whether contracts reward scale economies or certification depth.
- Automotive:Tier 1 suppliers in Michigan, Ontario, and Bavaria specify pressure-forming-capable lines for interior trim and battery housings. Direct OEM accountability requirements are eliminating multi-tier subcontracting, consolidating volume among ISO/TS 16949-certified converters with captive sheet extrusion.
- Packaging:Medical device and pharmaceutical sterile barrier systems dominate value capture. CDSCO alignment with EU MDR in Maharashtra and Gujarat is opening ISO 13485-certified capacity demand.
- Electronics:ESD-dissipative formulations for semiconductor transport trays and equipment housings. Cleanroom-capable production segregates qualified suppliers from general industrial competitors.
- Consumer Goods:Appliance panels and recreational vehicle components. Seasonal demand patterns favor flexible tolling arrangements over dedicated asset commitments.
Automotive commands the steepest expansion trajectory. Electronics is climbing the fastest in margin per square meter.
Application:
Use case complexity determines whether vacuum forming competes with injection molding or owns the specification.
- Medical Devices:Surgical trays, implantable device packaging, and procedural kits requiring ISO 14644 Class 7-8 cleanroom validation. FDA 21 CFR and EU MDR dual compliance extends facility modification cycles to 12-18 months, filtering the supplier base.
- Industrial Components:Permanent equipment housings, machinery guards, and transit infrastructure. Heavy-gauge thermoforming captures superior margin pools through structural performance requirements.
- Signage:Outdoor advertising and architectural displays. Acrylic and polycarbonate optical grades dominate where weathering resistance exceeds 10-year warranties.
- Retail Displays:Point-of-purchase fixtures and merchandising systems. Short-run customization favors rapid-tooling aluminum molds over hardened steel.
Medical Devices holds installed capacity. Industrial Components is rotating up the share rankings.
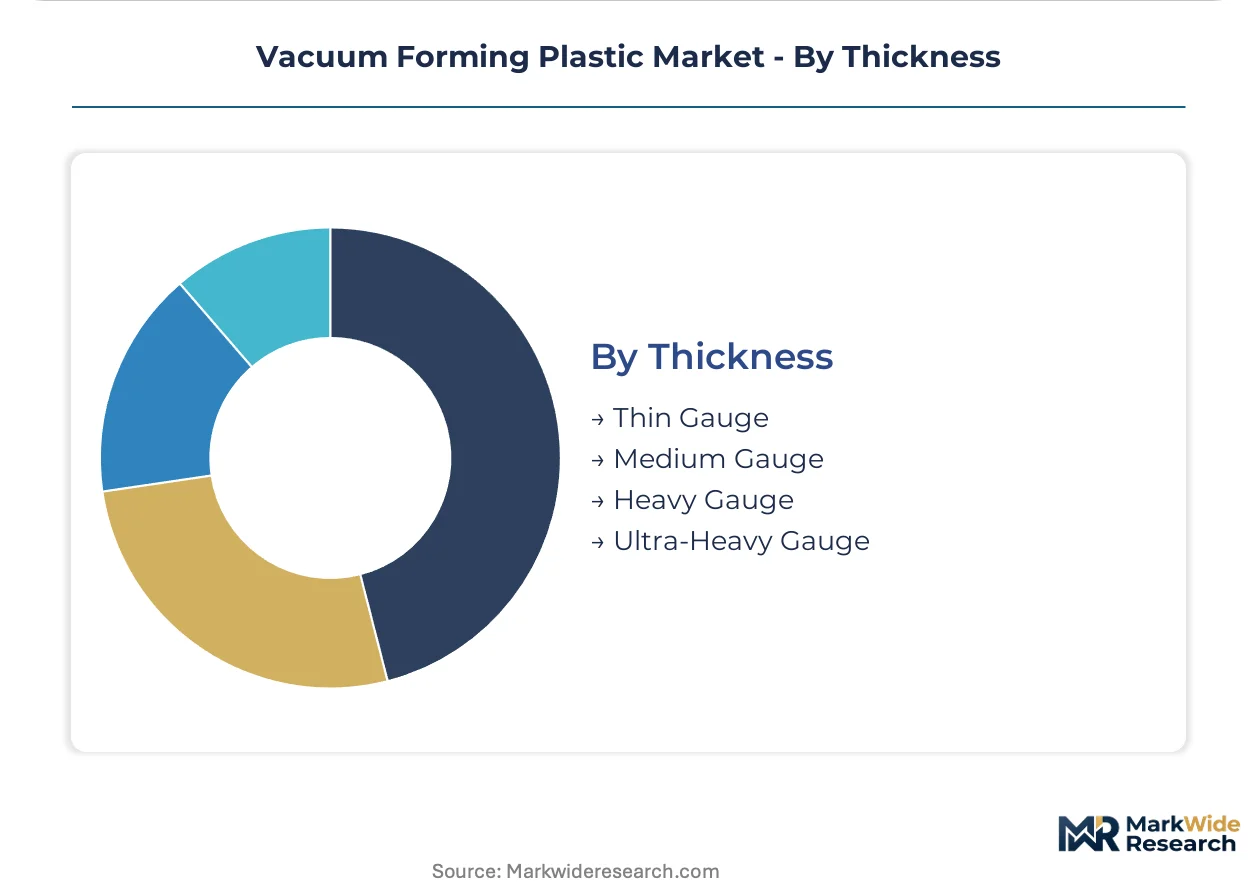
Thickness:
Gauge selection locks converters into distinct capital equipment and customer relationship profiles.
- Thin Gauge:Sheet below 0.060 inches for disposable medical trays, blister packs, and food containers. Thin-gauge lines achieve highest throughput but face resin price volatility compression without captive extrusion.
- Heavy Gauge:Sheet above 0.125 inches for permanent equipment housings, automotive components, and transit infrastructure. Superior margin pools reward precision aluminum mold fabrication and pressure-forming capability.
- Medium Gauge:Intermediate range for appliance panels and recreational vehicle components. Volume splits between commodity converters and specialists with forming-plus-finish integration.
- Ultra-Heavy Gauge:Specialized above 0.500 inches for aerospace cabin modules and heavy equipment enclosures. Limited installed base creates pricing power for qualified suppliers.
Thin Gauge holds installed capacity. Heavy Gauge is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances in vacuum forming plastic tilt toward net exporters in Germany and China, while the United States and India remain import-dependent for medical-grade sheet stocks. Trade flows concentrate around specialized tooling and certified raw materials rather than commodity thermoformed goods.
Germany
Automotive interior programs and battery enclosure contracts pull heavy-gauge polycarbonate demand from Bavarian Tier 1 suppliers. The EU F-Gas Regulation accelerates converter investment in lower-emission forming lines across the Stuttgart manufacturing belt. Munich-area tooling clusters face skilled machinist shortages that extend precision mold lead times.
United States
FDA 21 CFR compliance requirements for sterile barrier systems concentrate thin-gauge medical tray investment in Michigan and Ohio. EPA Clean Air Act enforcement shapes resin sourcing decisions for Midwestern converters. Grand Rapids-area thermoformers retrofit lines for pressure-forming capability to capture electric vehicle battery housing contracts.
China
Electric vehicle battery enclosure demand drives polycarbonate and ABS substitution for metal stampings across the Yangtze River Delta. NMPA medical device packaging standards tighten qualification requirements for export-oriented producers. Suzhou and Wuxi manufacturing clusters attract ISO 13485 certification investment to serve EU MDR-aligned pharmaceutical clients.
India
CDSCO alignment with EU MDR opens ISO 13485-certified thermoforming demand in Maharashtra and Gujarat pharmaceutical corridors. Domestic resin compounding capacity lags, forcing reliance on imported PET and PVC sheet stocks. Ahmedabad-area converters expand cleanroom-capable lines to capture surgical tray contracts from European medical device OEMs.
Japan
PMDA pharmaceutical packaging standards and METI industrial policy support precision thermoforming for semiconductor transport trays. Aging toolmaker workforces in the Nagoya manufacturing belt constrain expansion of pressure-forming capacity. Osaka-area specialists integrate servo-controlled plug-assist technology to maintain ±0.1mm wall thickness tolerance for automotive interior exports.
Vacuum Forming Plastic Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and captive extrusion capability. The vendor base organizes around three tiers: integrated resin-to-form converters with ISO 13485 medical certification, heavy-gauge industrial specialists with pressure-forming assets, and commodity thin-gauge operators serving packaging volume. Strategic moves concentrate on backward integration into sheet extrusion and cleanroom facility expansion to capture healthcare contract premiums.
Among North American fabricators, Profile Plastics and Engineered Plastic Products exemplify the heavy-gauge industrial specialist archetype, while Robinson Industries anchors the diversified converter tier with proprietary forming capabilities. These three entities represent distinct competitive positioning vectors: tooling-intensive premium manufacturing, automotive OEM direct accountability, and multi-channel capability breadth.
| Leading Market Players |
|---|
| Conlet Plastics |
| Profile Plastics |
| Engineered Plastic Products |
| Arrowhead |
| SAY Plastics |
| Robinson Industries |
| BCJ Plastic Products |
| Emco |
| Multiplastics |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between German automotive Tier 1 suppliers and polycarbonate sheet producers lock in both resin access and price visibility, insulating converters from benzene spot volatility while committing capacity years ahead. This structure concentrates bargaining power among buyers with multi-year OEM programs, leaving independent thermoformers exposed to quarterly resin repricing.
Pricing Analysis
Industrial OEM buyers anchor contract-based pricing with volume-commitment tiers that stratify across ISO/TS 16949 certification levels and captive extrusion capability. Three-tier pricing structure across premium, standard, and economy levels separates pressure-forming specialists from commodity thin-gauge operators. Cost compression in standard-grade automotive housings is intensifying because Chinese polycarbonate capacity expansion feeds global spot availability. Packaging converters serving Indian pharmaceutical corridors show highest price sensitivity due to imported PET sheet dependency.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for polycarbonate pellet shipments to North American compounders. Raw material supply concentrates in Germany, China, and Belgium, where bisphenol-A production clusters feed regional sheet extrusion. Feedstock draws from benzene and phthalate anhydride markets tethered to crude oil volatility. Single-source vulnerability concentrates in Bavarian precision aluminum mold fabrication. Distribution runs through Tier 1 supplier consolidation with direct OEM accountability mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated automotive OEM panels that mandate single-source accountability, fragmenting multi-tier subcontracting arrangements and squeezing margin pools for non-integrated converters.
For Market Incumbents: Fortify captive sheet extrusion capacity in Michigan and Ontario to defend against resin price volatility and Chinese polycarbonate import pressure. Deepen ISO 13485 certification coverage to capture surgical tray contract premiums as FDA 21 CFR compliance timelines extend. Prioritize pressure-forming asset retrofitting for electric vehicle battery enclosure specifications. For New Entrants and Emerging Players: Lead with cleanroom-capable production investments in Maharashtra and Gujarat to capture CDSCO-aligned pharmaceutical packaging demand before domestic resin compounding matures. Target ISO 14644 Class 7 validation as the most penetrable barrier to medical-grade margin pools. Pursue tolling partnerships with European medical device OEMs seeking India-based surgical tray supply. For Investors and Strategic Acquirers: Heavy-gauge industrial specialists with pressure-forming assets and automotive OEM direct contracts represent the most defensible acquisition profile. Long-term viability across the analysis window hinges on backward integration into sheet extrusion and geographic diversification beyond German tooling clusters. Monitor EU F-Gas Regulation enforcement intensity as inflection indicator for lower-emission process equipment replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sheet Extrusion | Captive resin supply insulates margin stability from benzene spot volatility for automotive converters. |
| Cleanroom Facility Expansion | ISO 14644 Class 7 validation unlocks multi-year surgical tray contracts with FDA 21 CFR compliance. |
| Pressure-Forming Asset Retrofit | Servo-controlled plug-assist technology achieves Class A surface tolerance for EV battery housings. |
| Recycled Content Supply Chain Validation | Post-industrial PET sourcing secures first-mover positioning under EU Green Deal circular economy mandates. |
| Geographic Manufacturing Footprint Expansion | Maharashtra and Gujarat capacity placement captures CDSCO-aligned pharmaceutical packaging demand growth. |
Research Methodology
The analysis maps thin-gauge medical packaging, heavy-gauge automotive components, and industrial equipment housings, each validated through plant managers at Tier 1 suppliers, procurement leads at OEMs, and technical R&D directors at resin compounders. Primary interviews with cleanroom operations specialists and distribution channel partners combined with secondary validation from customs trade data, SEC 10-K filings, and EPA Clean Air Act enforcement records. Bottom-up capacity utilization estimates and top-down end-use demand projections underwent cross-triangulation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include material chemistry grade, gauge thickness tier, end-use certification requirement, and regional production cluster. CAGRs derived from installed capacity expansion schedules and substitution elasticity assumptions for metal-to-plastic conversion in automotive applications. Forecast inputs incorporated EU F-Gas Regulation compliance timelines and NMPA medical device packaging standard evolution.
The analysis sits within stated boundaries; outcomes outside sustained electric vehicle production growth or accelerated EU MDR enforcement would require recalibration. Forecasts reflect assumptions on resin price stability and tooling lead time normalization. Practitioners should keep alternative scenarios live as CDSCO regulatory alignment and German skilled machinist availability evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Plastic Ready Meal Trays Market
Plastic Packaging
Europe Polyethylene Terephthalate (PET) Market
Plastic Packaging
North America PET Bottle Market
Plastic Packaging
Plastic Ampoules Market
Plastic Packaging
Disposable Straw Market
Plastic Packaging
Germany Plastic Packaging Market
Plastic Packaging
Plastic Aerosol Packaging Market
Plastic Packaging
Africa BOPP Films Market
Plastic Packaging
Canada Plastic Packaging Market
Plastic Packaging
US Lubricant Contaminated HDPE Container Waste Market
Plastic Packaging
Clear Plastic Boxes Market
Plastic Packaging
Global Returnable Plastic Crates Market
Plastic Packaging
United Arab Emirates Plastic Bottles Market
Plastic Packaging
United Arab Emirates Plastic Packaging Market
Plastic Packaging
Plastic Medicine Bottles Market
Plastic Packaging
Plastic Canister Market