
 EV Lighting Market | 2026-2036
EV Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
EV Lighting Market Foresight
Photonics engineering talent is rotating toward automotive semiconductor packaging, tightening the labor pool for legacy incandescent lamp production. Koito Manufacturing leverages in-house LED chip-on-board capabilities to sustain vertical control over headlamp module costs. Hella GmbH anchors its European production network around adaptive driving beam calibration centers in Germany and the Czech Republic.
EV lighting encompasses the complete photonic subsystem architecture for electrified vehicles, spanning solid-state emitters, thermal management housings, and programmable beam-forming controllers that modulate luminous intensity between 600 and 2,500 lumens depending on drive mode. The technology dimension shows LED occupying the dominant value position while laser lighting captures the emerging performance tier for luxury long-range illumination. OEMs command the largest procurement volume within the end-user structure, though aftermarket providers are gaining share as EV fleet aging accelerates replacement part demand.
The US NHTSA Federal Motor Vehicle Safety Standard 108 governs headlamp photometric performance and beam pattern compliance, while ECE regulations administered by European type-approval authorities mandate automatic leveling and cleaning systems for high-intensity discharge installations. China's GB standards through SAMR establish domestic testing protocols for LED module electromagnetic compatibility. Stakeholders must monitor divergence between SAE and ECE beam pattern requirements when designing single-SKU global platforms.
Market Dynamics
OEM procurement of adaptive headlamp systems is accelerating as automakers pursue vehicle differentiation through programmable beam-forming controllers and solid-state emitter architectures. This structural pull is tightening the photonics engineering labor pool and reshaping competitive positioning among tier-1 suppliers.
Growth Catalysts
- ECE R48 tightening:Europe's regulation on vehicle lighting installations mandates stricter compliance for new EV platforms, forcing automakers to source advanced LED matrix systems from certified domestic tier-1 suppliers.
- Adaptive driving beam adoption:Premium EV manufacturers in Germany are integrating automatic leveling and cleaning systems to meet high-intensity discharge requirements under type-approval protocols.
- Laser lighting emergence:Luxury long-range illumination technology is capturing the performance tier as solid-state emitters modulate luminous intensity between 600 and 2,500 lumens across drive modes.
Market Restraints
- Photonics talent scarcity:Engineering talent rotation toward automotive semiconductor packaging is compressing the labor pool available for legacy incandescent lamp production and LED module calibration.
- Regional regulatory divergence:NHTSA Federal Motor Vehicle Safety Standard 108 and ECE regulations enforce incompatible beam pattern requirements, complicating single-SKU global platform design.
- Thermal management complexity:High-lumen LED and laser systems require advanced housing materials and active cooling architectures that inflate module costs and extend validation cycles.
Strategic Opportunities
- Aftermarket channel expansion:EV fleet aging is accelerating replacement part demand as vehicles exit warranty periods, creating procurement volume for independent service providers.
- GB standards alignment:China's SAMR testing protocols for LED electromagnetic compatibility are opening technical pathways for suppliers meeting both ECE and domestic certification.
- Chip-on-board integration:In-house LED packaging capabilities enable tier-1 suppliers to control headlamp module costs and compress lead times against fabless competitors.
Industry Challenges
- Calibration workforce gaps:Adaptive driving beam systems require specialized technicians for pixel-level alignment, and training pipelines have not scaled with OEM deployment timelines.
- Multi-standard certification burden:Suppliers must simultaneously validate against NHTSA photometric performance, ECE automatic leveling mandates, and GB electromagnetic compatibility protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EV Lighting Market |
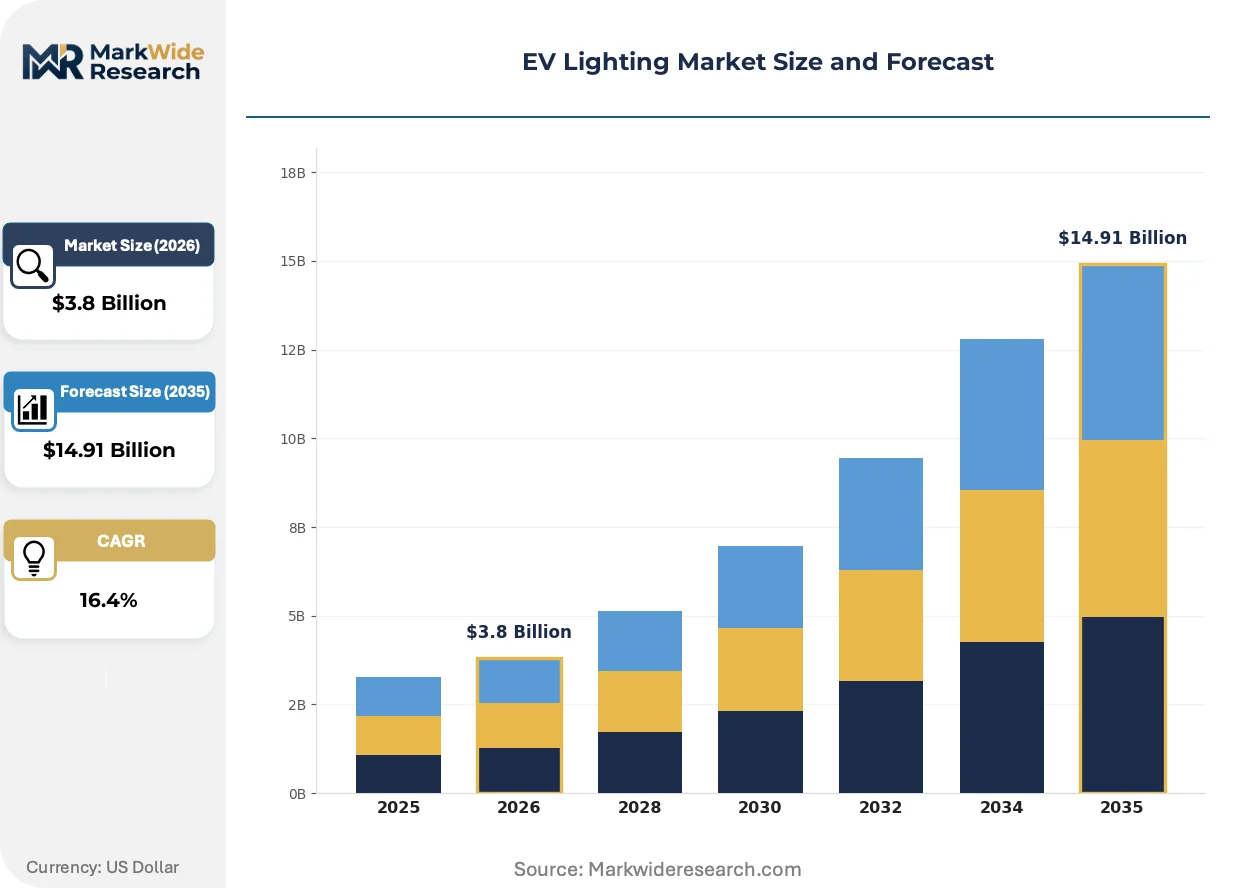
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Headlights, Taillights, Interior Lighting, Signaling Lights Technology: LED, Halogen, HID, Laser Lighting End User: OEMs, Aftermarket Providers, Fleet Operators, Private Owners Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Off-Road Vehicles |
| Companies Covered | Denso Corporation, Hella GmbH, Hyundai Mobis, Koito Manufacturing, Valeo, Robert Bosch GmbH, Osram GmbH, Stanley Electric Co., Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EV Lighting Market Shifts & Advancements
Programmable beam-forming architectures are actively reshaping how lighting subsystems integrate with vehicle electrical platforms. Solid-state emitters, thermal management housings, and controller electronics are converging into modular designs that alter procurement patterns and supplier relationships.
LED matrix technology is decomposing the traditional headlamp supply chain by separating emitter arrays from optical control units. Premium EV manufacturers in Germany are adopting this architecture fastest, sourcing pixel-level controllers separately from domestic tier-1 suppliers. The disaggregation is compressing margins for integrated module producers while opening entry points for semiconductor packaging specialists.
ECE R48 revisions are mandating tighter installation compliance for new EV platforms across European type-approval authorities. The regulatory pressure is forcing automakers to redesign front-end electrical architectures and validate adaptive leveling systems earlier in development cycles. High-intensity discharge installations face the steepest compliance burden, with automatic cleaning systems now required for certification.
Fleet operators are unbundling lighting maintenance from comprehensive service contracts as EV aging patterns become predictable. Third-party aftermarket providers in North America are capturing replacement volume through direct procurement relationships with independent repair networks. This channel shift is most visible in commercial EV segments where downtime costs drive preference for rapid component exchange over OEM-authorized service.
EV Lighting Market Segmentation
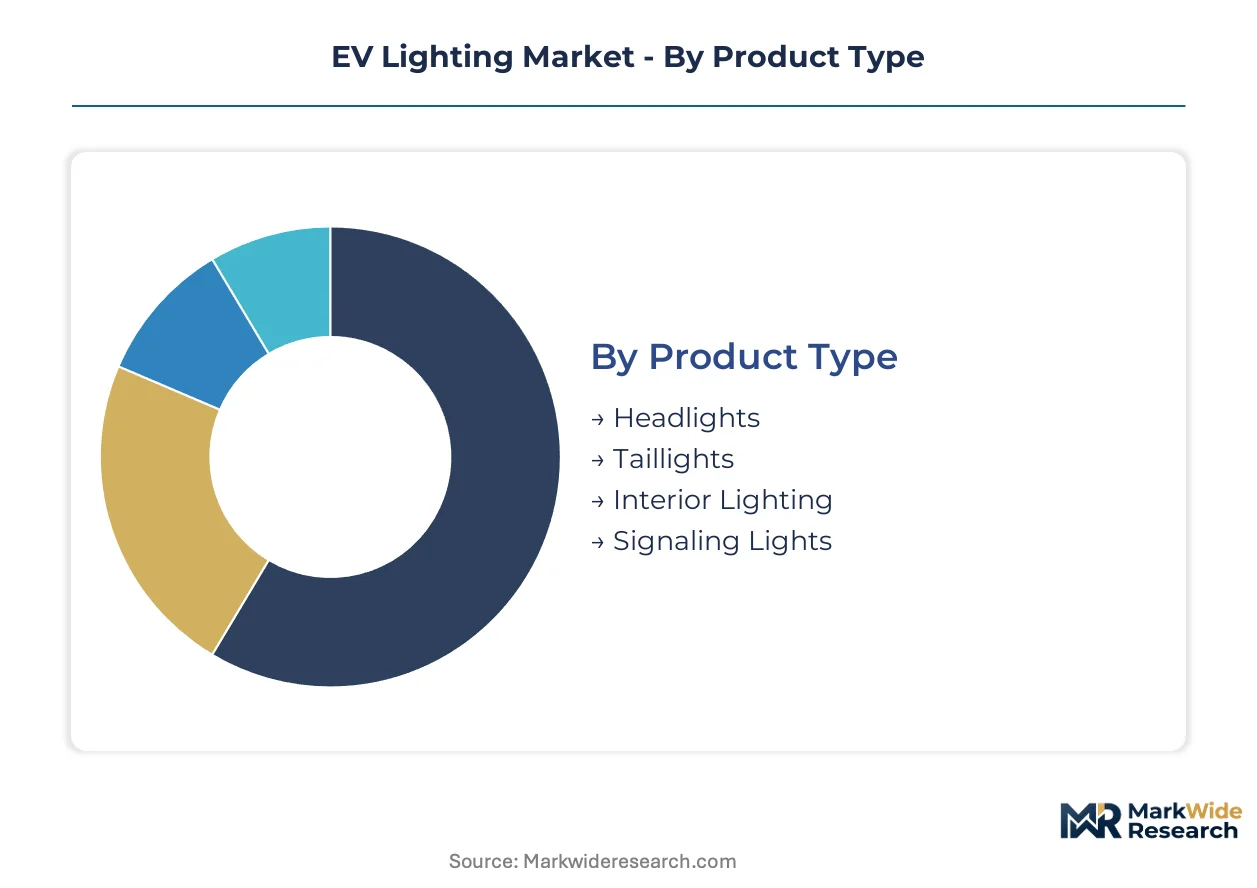
Segmentation in EV lighting reveals how substitution pressures and regulatory divergence fragment procurement strategies across the value chain. Suppliers must navigate distinct technical specifications, certification pathways, and customer price sensitivities that vary sharply by product category and end-use application.
Product Type:
Headlights face the most acute substitution pressure as adaptive driving beam architectures displace conventional fixed-beam designs across premium EV platforms.
- Headlights:Solid-state emitter arrays with programmable beam-forming controllers now dominate front-end electrical architectures. German premium EV manufacturers source LED matrix systems from domestic tier-1 suppliers to satisfy ECE R48 tightening on installation compliance. Headlights retain volume leadership; signaling lights hold the steepest expansion curve.
- Taillights:Sequential and animated rear illumination functions are differentiating EV brands through signature light patterns. Chinese EV producers are driving adoption of full-width LED bars that integrate brake, turn, and hazard functions into unified optical assemblies.
- Interior Lighting:Ambient cabin illumination with tunable color temperature is migrating from luxury to mass-market EV segments. Tier-1 suppliers in the Czech Republic are scaling production of slim LED strips for dashboard and door panel integration.
- Signaling Lights:Dynamic turn indicators and pedestrian warning systems are expanding with autonomous drive mode requirements. US NHTSA photometric standards and ECE regulations enforce incompatible beam pattern specifications for these safety-critical functions.
Headlamp modules command the highest unit values and validation complexity, while interior lighting offers the most accessible entry point for new component suppliers.
Technology:
Cost tier stratification separates established emitter technologies from emerging performance architectures, with mid-range EV platforms driving LED volume and luxury segments absorbing laser lighting premiums.
- LED:Chip-on-board packaging and thermal management housings have matured into standardized module designs. Koito Manufacturing sustains cost control through in-house LED packaging against fabless competitors serving mass-market EV programs.
- Halogen:Legacy incandescent technology persists in emerging market EV variants where cost minimization overrides efficiency targets. Indian and Southeast Asian EV assemblers specify halogen headlamps for entry price-point vehicles.
- HID:High-intensity discharge installations face declining share as ECE R48 mandates automatic leveling and cleaning systems that inflate system cost. European type-approval authorities are accelerating phase-out timelines for non-adaptive HID architectures.
- Laser Lighting:Long-range illumination exceeding 600 meters is capturing the luxury performance tier. German OEMs integrate laser boost modules into matrix headlamp systems for high-speed autobahn operation.
LED maintains absolute volume dominance; laser lighting is climbing the fastest as premium EV manufacturers differentiate through illumination reach.
End User:
Procurement concentration varies sharply by customer type, with OEMs commanding design-in relationships and fleet operators unbundling maintenance from comprehensive service contracts.
- OEMs:Design-in authority over lighting subsystems extends from concept development through platform validation. Hella GmbH anchors its European production network around adaptive driving beam calibration centers in Germany and the Czech Republic to serve OEM procurement timelines.
- Aftermarket Providers:Independent service networks are capturing replacement volume as EV fleet aging accelerates demand for LED module exchanges. North American commercial EV segments prioritize rapid component availability over OEM-authorized service channels.
- Fleet Operators:Predictive maintenance programs are unbundling lighting subsystem replacement from comprehensive service contracts. Logistics operators in Germany and the Netherlands specify standardized LED modules across mixed EV fleets to compress parts inventory.
- Private Owners:Warranty-period dependency on OEM service transitions to price-sensitive independent repair as vehicles age. China's SAMR GB standards for LED electromagnetic compatibility are enabling certified aftermarket alternatives to dealer service.
OEMs retain design-in control; aftermarket providers are gaining replacement volume fastest as early EV cohorts exit warranty coverage.
Application:
Vehicle category determines thermal management requirements and regulatory certification burden, with passenger EVs driving LED matrix adoption and commercial segments prioritizing durability.
- Passenger Vehicles:Premium EV platforms integrate the full spectrum of adaptive lighting functions including automatic leveling and pixel-level beam shaping. German manufacturers lead specification of laser lighting for long-range illumination in luxury sedans and SUVs.
- Commercial Vehicles:Delivery vans and urban trucks prioritize sealed LED modules that withstand vibration and environmental exposure. European fleet operators specify ECE-certified systems to ensure cross-border operational compliance.
- Two-Wheelers:Electric scooters and motorcycles specify compact LED headlamp modules with simplified thermal management. Indian and Southeast Asian producers dominate volume production for this price-sensitive category.
- Off-Road Vehicles:Mining and agricultural EVs require ruggedized lighting with extended temperature operating ranges. Australian and Brazilian equipment manufacturers source specialized housings from tier-1 suppliers with heavy-duty validation capabilities.
Passenger vehicles anchor technology adoption; commercial vehicles are expanding most quickly as electrification penetrates urban logistics and delivery fleets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECE R48 tightening has concentrated European type-approval authority influence over global lighting compliance standards. Germany anchors premium EV platform development through its tier-1 supplier ecosystem. China accelerates domestic certification pathways under SAMR GB standards.
Germany
Premium EV manufacturers source LED matrix systems from domestic tier-1 suppliers to satisfy adaptive driving beam requirements. KBA enforces ECE R48 installation compliance through accelerated type-approval timelines. Hella GmbH operates calibration centers across Bavaria and Baden-Württemberg to serve OEM procurement schedules.
China
Domestic EV assemblers specify full-width LED bars and animated rear illumination for brand differentiation. SAMR GB standards establish electromagnetic compatibility testing protocols for LED module certification. Yangtze River Delta producers dominate volume manufacturing of chip-on-board packaging for export markets.
United States
Commercial EV fleet operators prioritize rapid component availability through independent service networks. NHTSA Federal Motor Vehicle Safety Standard 108 governs headlamp photometric performance and beam pattern compliance. Michigan and Ohio automotive clusters source sealed LED modules for delivery van electrification programs.
Japan
Automotive semiconductor packaging specialists rotate engineering talent toward solid-state emitter controller development. METI industrial policy supports domestic LED chip-on-board capabilities against Korean and Chinese competition. Kansai region producers supply thermal management housings for Southeast Asian EV assembly.
South Korea
Battery-electric platform specialists integrate laser boost modules for high-speed illumination performance. MFDS coordinates with automotive regulators on photobiological safety standards for emerging emitter technologies. Seoul Capital Area suppliers export matrix headlamp controllers to German premium OEMs.
EV Lighting Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the EV lighting value chain. The supplier base organizes around three strategic clusters: integrated tier-1 module producers with captive semiconductor packaging, specialized optical component fabricators, and fabless controller designers sourcing assembly services. Consolidation pressure intensifies as OEMs reduce supplier counts for global platform commonality. Dominant competitive moves include backward integration into LED chip-on-board capabilities and geographic expansion of calibration center networks.
Among Japanese-anchored tier-1 suppliers, Koito Manufacturing and Stanley Electric Co. exemplify the integrated module producer archetype through in-house packaging control. Hella GmbH represents the European calibration-specialist model with production network concentration in Germany and the Czech Republic. Denso Corporation occupies a position bridging Asian scale advantages with Western OEM qualification requirements.
| Leading Market Players |
|---|
| Denso Corporation |
| Hella GmbH |
| Hyundai Mobis |
| Koito Manufacturing |
| Valeo |
| Robert Bosch GmbH |
| Osram GmbH |
| Stanley Electric Co. |
| Continental AG |
| Others |
Supply & Pricing Matrix
Long-term capacity reservation agreements with German tier-1 suppliers lock in LED matrix module access while fixing cost visibility for premium EV platforms facing ECE R48 compliance deadlines. These contractual structures concentrate pricing power among vertically integrated packaging specialists and compress margin flexibility for fabless controller designers.
Pricing Analysis
German-manufactured LED matrix systems command premiums against Czech and Chinese alternatives due to KBA type-approval proximity and calibration labor costs. Three-tier pricing structure across premium, standard, and economy levels separates ECE-certified adaptive driving beam architectures from fixed-beam LED modules and legacy halogen replacements. Cost compression in mid-range LED modules is intensifying because Yangtze River Delta chip-on-board producers are scaling export capacity. Fleet operators exhibit highest price sensitivity through standardized procurement across mixed-vehicle pools, while luxury OEMs absorb laser lighting premiums for autobahn-performance differentiation.
Supply Chain Analysis
Inventory cycles for thermal management housings and programmable controllers now stretch across 12-16 week horizons as automotive semiconductor packaging capacity tightens. Supply concentrates in Germany for adaptive driving beam calibration, the Czech Republic for interior LED strip production, and China's Yangtze River Delta for chip-on-board packaging. The chain draws from gallium nitride substrates, aluminum thermal housings, and silicone encapsulants. Single-source vulnerability clusters around European tier-1 calibration centers serving multiple OEM platforms. Distribution runs through OEM direct procurement for new platforms and independent aftermarket networks for replacement modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as EV fleet aging unbundles lighting maintenance from comprehensive service contracts, creating niches for certified aftermarket providers and semiconductor packaging specialists outside traditional tier-1 hierarchies.
For Market Incumbents: Secure captive LED chip-on-board capabilities to defend margin position against Yangtze River Delta cost competition. Expand calibration center footprint into Central European production corridors to compress lead times for OEM platform schedules. ECE R48 tightening threatens integrated module producers who lack pixel-level controller sourcing relationships.
For New Entrants and Emerging Players: SAMR GB standards fast-track offers entry pathway for electromagnetic compatibility-certified LED modules serving China's independent repair networks. Target commercial EV fleet segments in North America where downtime costs override OEM-authorized service preferences. Pursue direct procurement relationships with logistics operators unbundling lighting maintenance from comprehensive contracts.
For Investors and Strategic Acquirers: Capital is best deployed toward semiconductor packaging specialists with automotive qualification and calibration workforce pipelines. Long-term viability hinges on adaptive driving beam adoption sustaining through mass-market EV penetration. Watch for inflection when ECE R48 phase-out timelines for non-adaptive HID architectures accelerate replacement demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into LED Packaging | Koito Manufacturing's captive chip-on-board capabilities compress module costs against fabless competitors serving mass-market programs. |
| Calibration Center Network Expansion | Hella GmbH's Bavaria and Czech Republic facilities anchor European adaptive driving beam servicing for OEM procurement timelines. |
| Aftermarket Channel Direct Procurement | North American commercial fleet operators bypass OEM-authorized service through independent repair network relationships. |
| Multi-Standard Certification Investment | Suppliers validating against NHTSA, ECE, and SAMR protocols unlock single-SKU global platform opportunities. |
| Laser Boost Module Integration | German luxury OEMs specify long-range illumination exceeding 600 meters for high-speed autobahn operation differentiation. |
Research Methodology
A spread of perspectives from OEM platform engineers, tier-1 supplier procurement leads, aftermarket distributor operations heads, and ECE type-approval authorities converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against vehicle production databases, IHS Markit registration data, KBA certification filings, and SAMR GB standard documentation. Bottom-up module shipment analysis triangulated against top-down EV production forecasts across the analysis window.
Segmentation dimensions modeled include product type, technology tier, end-user category, and vehicle application across the projection horizon. CAGRs derived from fitted growth curves applied to technology substitution rates and regulatory compliance deadlines. Forecast inputs incorporated ECE R48 implementation timelines, LED laser cost convergence trajectories, and fleet aging patterns for replacement demand estimation.
Decision-makers should treat outputs as directional under base assumptions of sustained EV penetration and regulatory harmonization; material deviation in semiconductor packaging capacity or trade policy would warrant model refresh. Specific risk factors include photonics engineering labor scarcity, divergence between NHTSA and ECE beam pattern requirements, and thermal management material cost volatility. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Circadian Lighting Market
Lighting
Global Lamps Market
Lighting
Industrial Lighting Market
Lighting
Saudi Arabia Smart Lighting Market
Lighting
Smart Lights Market
Lighting
Display Light Control Film Market
Lighting
Human Centric Lighting Market
Lighting
Hazardous Location LED Lighting Market
Lighting
Asia-Pacific Lighting Control Market
Lighting
LED Eye Protection Lamp Market
Lighting
Street and Roadway Lighting Market
Lighting
High Bay Lighting Market
Lighting
Industrial LiDAR Integrated Lighting Market
Lighting
Germany Indoor LED Lighting Market
Lighting
Lighting As a Service (Laas) Market
Lighting
Solar Spotlights Market