
 Saudi Arabia Smart Lighting Market | 2026-2036
Saudi Arabia Smart Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Smart Lighting Market Intelligence
Project finance tied to energy performance contracting is fragmenting the competitive landscape for smart lighting deployment in Saudi Arabia. Philips Saudi Lighting Company leverages its established local manufacturing footprint to sustain cost advantages across large municipal tenders. Osram/Ledvance differentiates through specialized IoT-enabled control systems that anchor premium positioning in commercial segments. Al Fanar Company Ltd competes on backward integration into electrical infrastructure, allowing bundled project bids that reduce client procurement complexity.
Saudi Arabia smart lighting encompasses networked luminaires with embedded sensors, wireless communication modules, and centralized management platforms that enable remote dimming, occupancy response, and energy analytics; systems typically operate on 220-230V AC supply with power factors exceeding 0.9 and communicate via mesh protocols such as Zigbee or Bluetooth Low Energy. LED fixtures dominate installed volume due to declining chip costs and SASO efficiency mandates, while IoT connectivity represents the fastest-expanding technology layer as building management systems integrate lighting with HVAC and security networks. The municipal end-user segment leads absolute spend driven by nationwide street retrofit programs, though commercial applications in hospitality and retail yield higher per-fixture margins.
SASO technical regulations mandate minimum luminous efficacy and electromagnetic compatibility for all imported lighting products, while the Saudi Energy Efficiency Center enforces consumption labeling that filters low-performance imports from distribution channels. NEOM's regulatory sandbox permits experimental deployment of powerline communication and Li-Fi variants outside standard certification paths, creating early-adoption corridors for technology suppliers. Stakeholders must monitor how SFDA product safety reviews and evolving cybersecurity standards for connected infrastructure reshape vendor qualification requirements and project commissioning timelines.
Market Dynamics
Municipal street retrofit mandates under Saudi Vision 2030 are compressing procurement timelines and forcing vendor consolidation around turnkey energy performance contracting models.
Growth Catalysts
- NEOM regulatory sandbox:Experimental corridors permit Li-Fi and powerline communication deployments outside standard SASO certification paths, accelerating technology validation cycles.
- SASO efficacy mandates:Minimum luminous efficacy requirements filter low-performance imports, creating protected channels for compliant domestic and regional manufacturers.
- King Abdullah Financial District:Premium commercial clusters demand IoT-integrated lighting systems that anchor building management convergence with HVAC and security networks.
Market Restraints
- LED chip cost volatility:Input price swings in semiconductor substrates compress margin buffers for fixture assemblers lacking captive wafer supply.
- Import concentration risk:Heavy reliance on East Asian module suppliers exposes projects to shipping lane disruptions and extended lead times.
- Cybersecurity compliance friction:Evolving SFDA connected infrastructure standards delay product registration and extend commissioning timelines for networked systems.
Strategic Opportunities
- Jeddah hospitality corridor:Underpenetrated luxury hotel and retail segments yield per-fixture margins significantly above municipal street lighting benchmarks.
- Energy performance contracting:Guaranteed savings models reduce upfront capital barriers for municipal buyers and lock in long-term service revenue streams.
- Li-Fi convergence:Integration of visible light communication with existing LED infrastructure opens data transmission applications in secure government and financial facilities.
Industry Challenges
- Mesh network commissioning:Zigbee and Bluetooth Low Energy interoperability gaps between vendor platforms inflate deployment labor costs and troubleshooting cycles.
- Retrofit electrical compatibility:Legacy 220-230V infrastructure in aging Riyadh districts requires custom driver configurations that fragment product standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Smart Lighting Market |
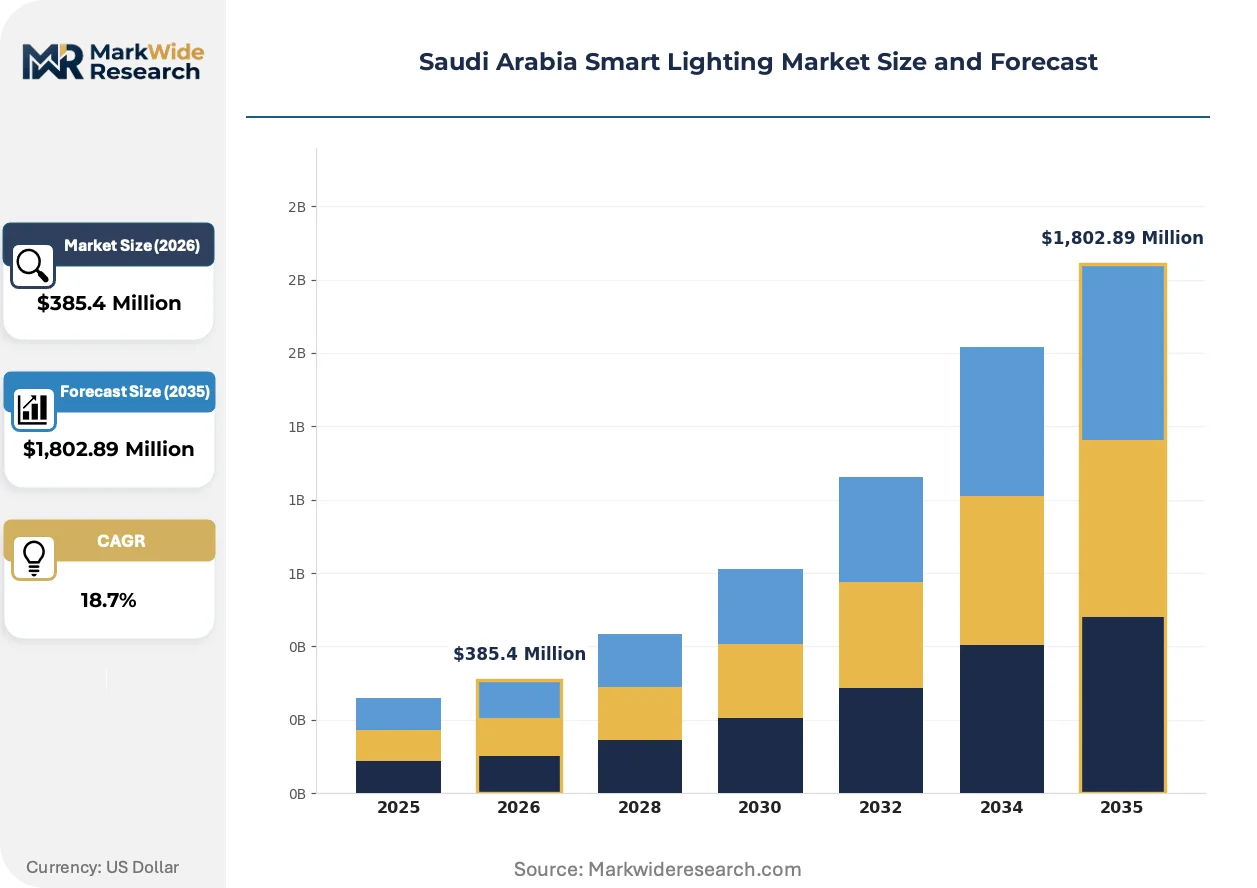
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,802.89 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, OLED, Smart Bulbs, Fixtures Technology: IoT, Bluetooth, Zigbee, Powerline Communication End User: Commercial, Residential, Industrial, Municipal Application: Street Lighting, Architectural Lighting, Indoor Lighting, Outdoor Lighting |
| Companies Covered | Zumtobel Lighting Saudi Arabia, National Lighting Company, Philips Saudi Lighting Company, Cinmar Lighting Systems, Al Fanar Company Ltd, Osram/Ledvance, Al Nasser Group, Huda Lighting, Cooper Lighting (Eaton), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Smart Lighting Market Strategic Shifts & Innovations
Connected infrastructure layers are overtaking luminaire hardware as the primary value capture mechanism, shifting competitive advantage toward software-integrated platform providers.
Li-Fi transmission modules embedded within high-frequency LED drivers are rendering obsolete conventional RF-based building communication backbones in secure government facilities. Defense and financial sector buyers in Riyadh are piloting these systems for electromagnetic-shielded environments where Wi-Fi penetration faces restrictions. The technology is rendering obsolete legacy copper Ethernet runs in new construction, compressing structured cabling contract values while expanding fixture-level electronics margins.
SASO electromagnetic compatibility testing protocols now mandate conducted emissions screening for all imported connected lighting products, extending certification timelines by four to eight weeks for first-time market entrants. Domestic manufacturers with established testing relationships capture accelerated approval pathways that foreign competitors cannot replicate. Commercial segment procurement teams are pre-qualifying vendors based on existing SASO registration portfolios, excluding speculative bidders from large district tenders.
Energy service companies are capturing municipal retrofit contracts through guaranteed savings structures that transfer performance risk from public agencies to private operators. Riyadh and Jeddah street lighting authorities now specify ten-year maintenance and energy outcome commitments rather than discrete fixture purchases. This model concentrates vendor selection around balance-sheet capacity and metering infrastructure ownership, marginalizing pure hardware suppliers without project finance capabilities.
Saudi Arabia Smart Lighting Market Segmentation
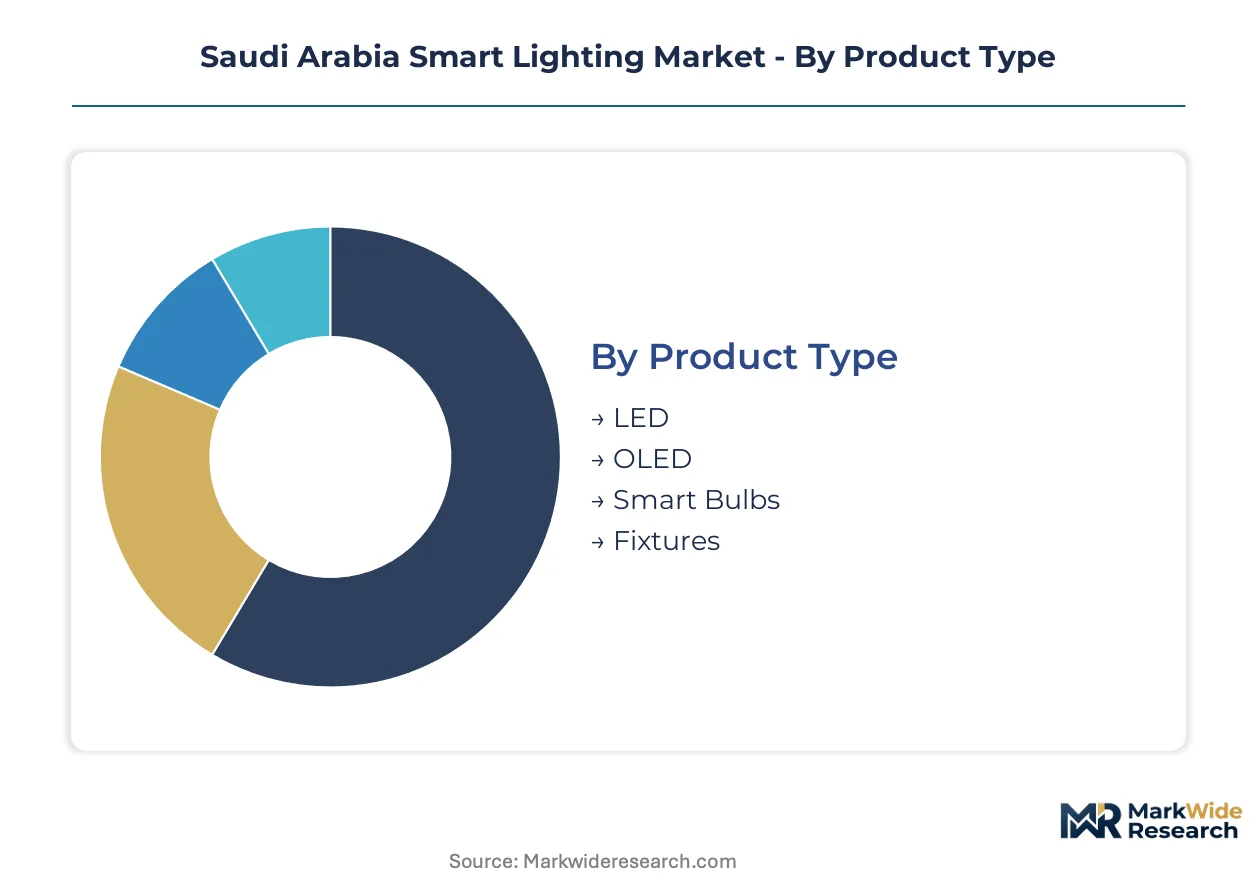
Smart lighting segmentation in Saudi Arabia reflects the tension between mature LED hardware and emerging connectivity layers. Procurement patterns diverge sharply across municipal retrofit programs, NEOM experimental corridors, and commercial building management convergence.
Product Type:
Mature LED fixtures dominate installed volume while emerging OLED and smart bulb categories capture premium positioning in controlled environments.
- LED:Solid-state semiconductor devices converting electrical current to visible light with luminous efficacy exceeding 100 lumens per watt. Municipal street retrofit programs across Riyadh and Jeddah concentrate demand as SASO mandates phase out legacy sodium vapor installations.
- Smart Bulbs:Retrofit-compatible lamps integrating wireless communication modules and dimmable drivers within standard form factors. Hospitality procurement in the Jeddah corridor favors these for rapid guest room upgrades without fixture replacement.
- OLED:Organic electroluminescent panels delivering uniform surface illumination without point-source glare. NEOM's architectural lighting specifications pilot these for facade integration where thermal management constraints limit LED density.
- Fixtures:Luminaire housings integrating heat sinks, optics, and mounting hardware as unified assemblies. King Abdullah Financial District tenders specify these for new construction where building management system convergence requires embedded sensor mounting points.
LED retains volume leadership; smart bulbs hold the steepest expansion curve.
Technology:
Cost tiers separate proprietary mesh protocols from emerging powerline alternatives that leverage existing electrical infrastructure.
- IoT:Cloud-connected management platforms aggregating sensor data across distributed luminaire networks. Commercial building operators in Riyadh concentrate deployment where HVAC and security system integration justifies centralized analytics investment.
- Zigbee:Mesh networking protocol operating in the 2.4 GHz band with self-healing topology and sub-50ms latency. Municipal street lighting authorities favor this for wide-area coverage where cellular backhaul costs prove prohibitive.
- Bluetooth:Low-energy beacon architecture enabling proximity-based control without dedicated gateway infrastructure. Retail environments in Jeddah shopping districts deploy these for location-aware customer experience applications.
- Powerline Communication:Data transmission modulated over existing 220-230V AC wiring eliminating separate control cable runs. NEOM's regulatory sandbox permits experimental deployment where electromagnetic compatibility with SASO standards remains under validation.
Zigbee retains volume leadership; powerline communication holds the steepest expansion curve.
End User:
Customer type segmentation reveals divergent procurement sophistication across public agencies and private facility operators.
- Municipal:City and regional authorities managing street, park, and public building illumination. Riyadh Municipality's energy performance contracting mandates concentrate demand around ten-year service agreements rather than discrete fixture purchases.
- Commercial:Office, retail, and hospitality facility operators prioritizing occupant experience and operational efficiency. King Abdullah Financial District developments anchor demand for IoT-integrated systems with real-time energy analytics.
- Residential:Individual homeowners and multi-unit property managers adopting retrofit-compatible solutions. Jeddah's upscale villa compounds represent concentrated demand for voice-activated and app-controlled installations.
- Industrial:Manufacturing, warehousing, and logistics facilities requiring high-bay illumination with motion response. Eastern Province petrochemical complexes specify hazardous-location rated fixtures with vibration-resistant mounting.
Municipal retains volume leadership; commercial holds the steepest expansion curve.
Application:
Geography within Saudi Arabia shapes application demand as urban retrofit priorities diverge from greenfield development patterns.
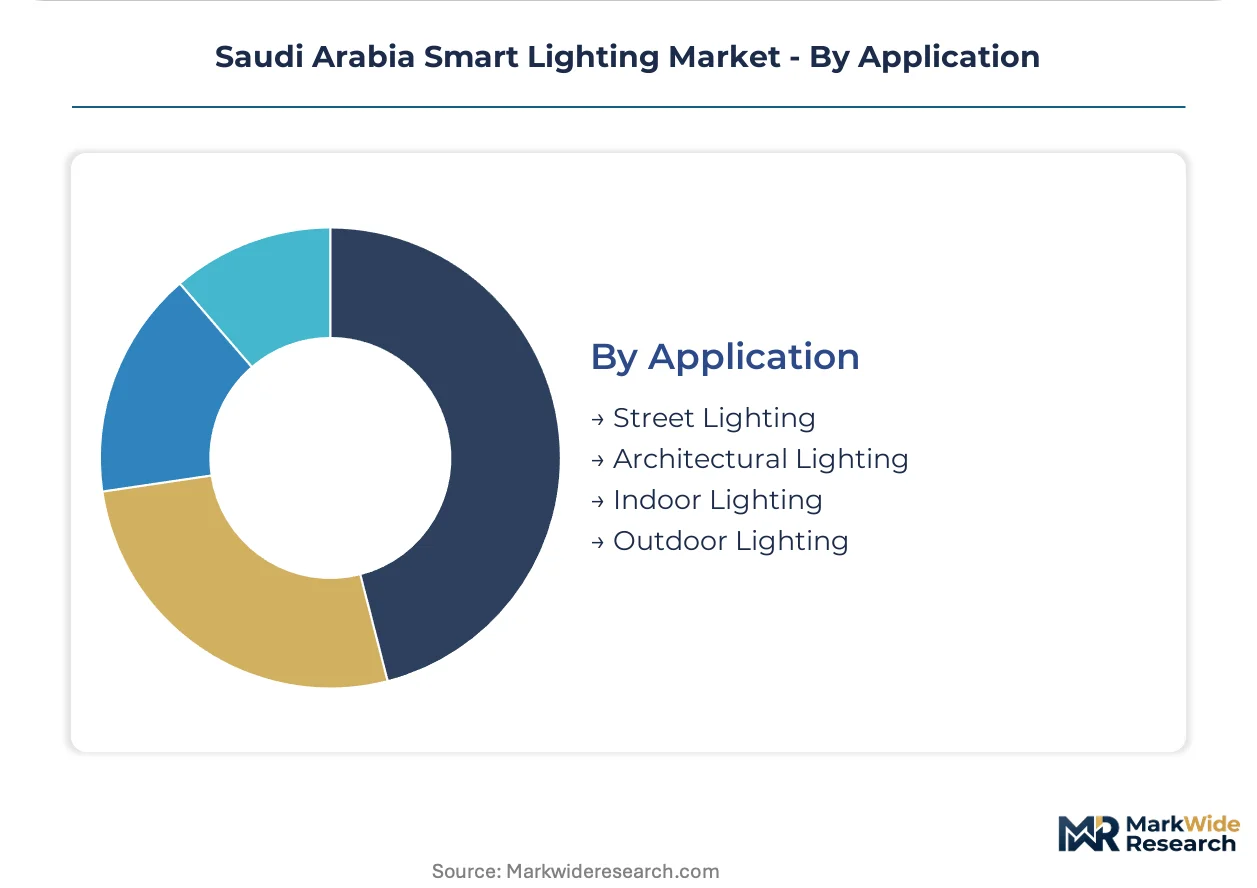
- Street Lighting:Roadway and intersection illumination with photocell dimming and remote fault monitoring. Nationwide retrofit programs under Saudi Vision 2030 concentrate deployment in Riyadh and Jeddah arterial corridors.
- Indoor Lighting:Office, hospitality, and retail interior illumination with occupancy sensing and daylight harvesting. NEOM's The Line development specifies these for subterranean environments where natural light penetration is architecturally constrained.
- Architectural Lighting:Facade, monument, and landscape accent illumination emphasizing aesthetic control and color rendering. Diriyah Gate development tenders drive demand for tunable white and RGBW systems.
- Outdoor Lighting:Parking, perimeter, and recreational area illumination with weather-sealed enclosures. Red Sea Project coastal installations specify corrosion-resistant housings for salt-air exposure.
Street lighting retains volume leadership; indoor lighting holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's smart lighting sector operates as a net import market with fixture assembly and control system integration concentrated in domestic free zones. The kingdom's regulatory environment prioritizes SASO-certified local production while experimental deployments in special economic zones test pre-certification technologies.
Riyadh
Municipal street retrofit programs anchor demand as the Riyadh Municipality accelerates energy performance contracting mandates. SASO efficacy standards filter non-compliant imports, protecting domestic manufacturers with established testing relationships. The King Abdullah Financial District drives premium commercial deployment of IoT-integrated building management systems.
Eastern Province
Petrochemical complexes and industrial logistics hubs generate specialized demand for hazardous-location rated fixtures with vibration-resistant mounting. The Saudi Energy Efficiency Center enforces consumption labeling that redirects procurement toward high-luminous-efficacy products. Dammam and Jubail industrial cities concentrate retrofit activity in warehousing and high-bay illumination segments.
Western Region
Jeddah's hospitality corridor yields per-fixture margins significantly above municipal benchmarks as luxury hotel operators prioritize rapid guest room upgrades. The Red Sea Project coastal installations specify corrosion-resistant housings engineered for salt-air exposure. Makkah's religious infrastructure maintains steady demand for architectural lighting with tunable white and RGBW control systems.
NEOM Northwest
The regulatory sandbox permits experimental Li-Fi and powerline communication deployments outside standard SASO certification paths. The Line development specifies indoor lighting for subterranean environments where natural light penetration faces architectural constraints. NEOM's pilot programs accelerate technology validation cycles for pre-commercial connected infrastructure layers.
Saudi Arabia Smart Lighting Market Key Industry Players
On the supply side, the industry is consolidating around turnkey energy performance contracting models that transfer operational risk from municipal buyers to private operators. Three strategic archetypes dominate: established multinational lighting groups with local manufacturing footprints, regional electrical infrastructure conglomerates with backward integration capabilities, and specialized IoT control system providers. Competitive moves center on balance-sheet capacity for long-term service agreements and metering infrastructure ownership.
Within the multinational tier, Philips Saudi Lighting Company and Osram/Ledvance exemplify scale-driven positioning, while Al Fanar Company Ltd anchors the regional infrastructure-integrated segment. These entities represent divergent paths to market access—one through captive manufacturing and the other through bundled electrical project capabilities. Their positioning reflects how vendor selection increasingly concentrates around project finance capacity rather than discrete hardware specifications.
| Leading Market Players |
|---|
| Zumtobel Lighting Saudi Arabia |
| National Lighting Company |
| Philips Saudi Lighting Company |
| Cinmar Lighting Systems |
| Al Fanar Company Ltd |
| Osram/Ledvance |
| Al Nasser Group |
| Huda Lighting |
| Cooper Lighting (Eaton) |
| Others |
Cost & Logistics Intelligence
Overcapacity in East Asian LED chip fabrication is compressing margin buffers for Saudi fixture assemblers and forcing pricing discipline across import-dependent supply tiers. This utilization dynamic concentrates bargaining power with module suppliers while pressuring local vendors to absorb cost volatility or cede municipal tender participation.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with differentiation driven by SASO certification tier and after-sales service bundling. Municipal procurement teams exhibit highest price sensitivity due to ten-year energy performance contracting mandates, while NEOM experimental corridor buyers accept premium positioning for pre-certified Li-Fi systems. Cost compression in the standard tier is intensifying because LED driver import concentration exposes assemblers to semiconductor substrate volatility.
Supply Chain Analysis
Extended payment terms from East Asian module suppliers now stretch to 120 days for Saudi distributors lacking supply-chain finance facilities. Manufacturing concentration rests on China, South Korea, and Taiwan for LED chips, with Malaysia and Vietnam contributing driver assembly capacity. Single-source vulnerability runs through narrow wafer supply channels, while distribution feeds through Riyadh-based electrical wholesalers serving municipal and commercial contractor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against powerline communication and Li-Fi variants that could displace Zigbee dominance in municipal retrofits. Incumbents must fortify positioning before experimental NEOM deployments scale to national standards.
For Market Incumbents: Insulate municipal revenue streams by securing ten-year energy performance contracting mandates before competitors build project finance capacity. Prioritize backward integration into LED driver assembly to reduce exposure to East Asian semiconductor volatility. Lock in SASO certification relationships that accelerate approval timelines for first-time entrants. For New Entrants and Emerging Players: Jeddah's hospitality corridor offers underpenetrated white-space where luxury hotel operators prioritize rapid guest room upgrades over municipal procurement complexity. Target voice-activated smart bulb retrofits in upscale villa compounds as a beachhead for residential expansion. Deploy app-controlled installation partnerships with local electrical contractors to bypass established distributor relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among energy service companies owning metering infrastructure and long-term maintenance obligations. Platform providers with IoT control software command superior valuation multiples against pure hardware assemblers. Monitor NEOM regulatory sandbox outcomes as the inflection signal for which pre-certification technologies achieve national SASO adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Energy Performance Contracting Mandate | Locks municipal buyers into ten-year service agreements that transfer operational risk to private operators. |
| SASO Certification Acceleration | Domestic manufacturers with established testing relationships capture approval pathways foreign competitors cannot replicate. |
| Li-Fi Pilot Deployment | NEOM's regulatory sandbox permits experimental visible light communication outside standard certification timelines. |
| Backward Integration into Drivers | Captive LED driver assembly reduces semiconductor substrate exposure and protects margin buffers. |
| Hospitality Channel Partnership | Jeddah luxury hotel operators yield per-fixture margins significantly above municipal street lighting benchmarks. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with municipal procurement officers, electrical contractors, hotel facility managers, and energy service company executives; and secondary validation through SASO technical regulation filings, Saudi Energy Efficiency Center consumption databases, customs import records, and NEOM development tender disclosures. Bottom-up fixture shipment estimates triangulated against top-down energy performance contracting value flows.
Forecast inputs span product type, technology protocol, end-user segment, and application geography across the projection horizon. Segmentation dimensions modeled include connectivity layer maturity, building management system integration depth, and regional regulatory cluster. CAGRs derive from fitted growth curves calibrated to municipal retrofit acceleration timelines and commercial IoT adoption patterns, with LED chip cost trajectories and SASO mandate enforcement schedules as key variable inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese module suppliers or accelerated Li-Fi standardization would shift outcomes. Macroeconomic deviation in oil revenues, regulatory tightening on cybersecurity compliance, or breakthrough solid-state lighting alternatives would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Explosion Proof Lighting Market
Lighting
Indicator Lights Market
Lighting
North America Outdoor Lighting Market
Lighting
Global Flame Proof Lighting Market
Lighting
Solar Lights Market
Lighting
Solid State Lighting System Market
Lighting
Lighting Market
Lighting
EV Lighting Market
Lighting
Art and Museum Lighting Market
Lighting
Ambient Lighting Market
Lighting
Industrial Lighting Lifecycle Services Market
Lighting
Lighting As a Service (Laas) Market
Lighting
Miniature Bulbs Market
Lighting
Asia-Pacific Lighting Control Market
Lighting
South America Outdoor LED Lighting Market
Lighting
Ring Lights Market