
 Ring Lights Market | 2026-2036
Ring Lights Market Size, Share, and Industry Trends Forecast 2026-2036
Ring Lights Market Outlook
Subscription-based equipment leasing and asset-light studio buildouts are reshaping competitive dynamics in the ring lights space. Neewer leverages its manufacturing scale to dominate entry-to-mid tier SKUs across Amazon and direct-to-consumer channels. Logitech anchors the premium segment through its integration with streaming peripherals and software ecosystems. Godox sustains professional photography loyalty via high-CRI LED arrays and modular accessory compatibility.
Ring lights are circular lighting fixtures, typically 12 to 26 inches in diameter, employing LED, fluorescent, halogen, or incandescent sources arranged around a hollow center to produce uniform, shadow-minimizing illumination for close-subject imaging. Their primary commercial purpose centers on portrait photography, video production, makeup application, and digital content creation where even facial lighting eliminates harsh shadows. LED ring lights now lead product type segmentation due to thermal efficiency, dimmability, and color temperature adjustability, while halogen and incandescent variants occupy shrinking legacy niches. USB-powered models represent the fastest-growing power source category, driven by mobile creator workflows and laptop-tethered streaming setups where portability outweighs output intensity.
The EU Ecodesign Directive and California Title 20 impose minimum luminous efficacy requirements that filter non-compliant halogen and incandescent ring lights from respective markets, compressing legacy SKU viability. The FCC regulates electromagnetic interference from dimmable LED drivers and wireless control modules sold in the United States, adding compliance cost layers for cross-border suppliers. Stakeholders must monitor how battery-powered USB segments evolve under evolving lithium-ion transport regulations from IATA and national aviation authorities, as creator mobility demands clash with tightening cargo restrictions.
Market Dynamics
The ring lights market contends with a fundamental tension between creator economy demand for portable, USB-powered solutions and professional studio requirements for high-CRI, modular systems with robust thermal management.
Growth Catalysts
- EU Ecodesign Directive:Minimum luminous efficacy mandates are accelerating LED ring light adoption by removing halogen and incandescent alternatives from European distribution channels.
- Content creation studios:Independent streamers and production houses now drive the fastest-expanding buyer segment, prioritizing color-accurate, dimmable fixtures for multi-platform output.
- USB power architecture:Laptop-tethered streaming workflows and mobile creator setups are displacing AC-dependent models, expanding addressable use cases beyond traditional studio environments.
Market Restraints
- LED driver component concentration:Dimmable driver manufacturing clusters heavily in East Asian supply bases, exposing brands to single-source vulnerability and extended lead times.
- California Title 20 compliance costs:Separate testing and certification requirements for the state's efficacy standards fragment SKU planning and inflate per-unit regulatory overhead.
- Smartphone computational photography:Advanced night-mode algorithms and AI-enhanced low-light capture are reducing dependency on external lighting among casual content creators.
Strategic Opportunities
- Subscription equipment leasing:Asset-light studio buildouts in the United States are creating recurring revenue pools for vendors willing to shift from transactional hardware sales to managed service models.
- Battery-powered USB segments:Evolving lithium-ion transport regulations from IATA present first-mover advantages for brands that pre-certify portable power systems against emerging cargo restrictions.
- High-CRI modular arrays:Professional photography loyalty remains sticky for vendors offering Godox-compatible accessory ecosystems and standardized mounting interfaces.
Industry Challenges
- FCC electromagnetic interference certification:Dimmable LED drivers and wireless control modules face extended testing timelines that compress product launch windows for cross-border suppliers.
- Color science talent scarcity:The specialized knowledge required for CRI optimization and multi-source color mixing sits concentrated among legacy photography lighting engineers, constraining product development velocity.
- Legacy halogen inventory stranding:EU and California regulatory phase-outs are forcing distributors to absorb write-downs on non-compliant stock while managing channel conflict with discounted clearance pricing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ring Lights Market |
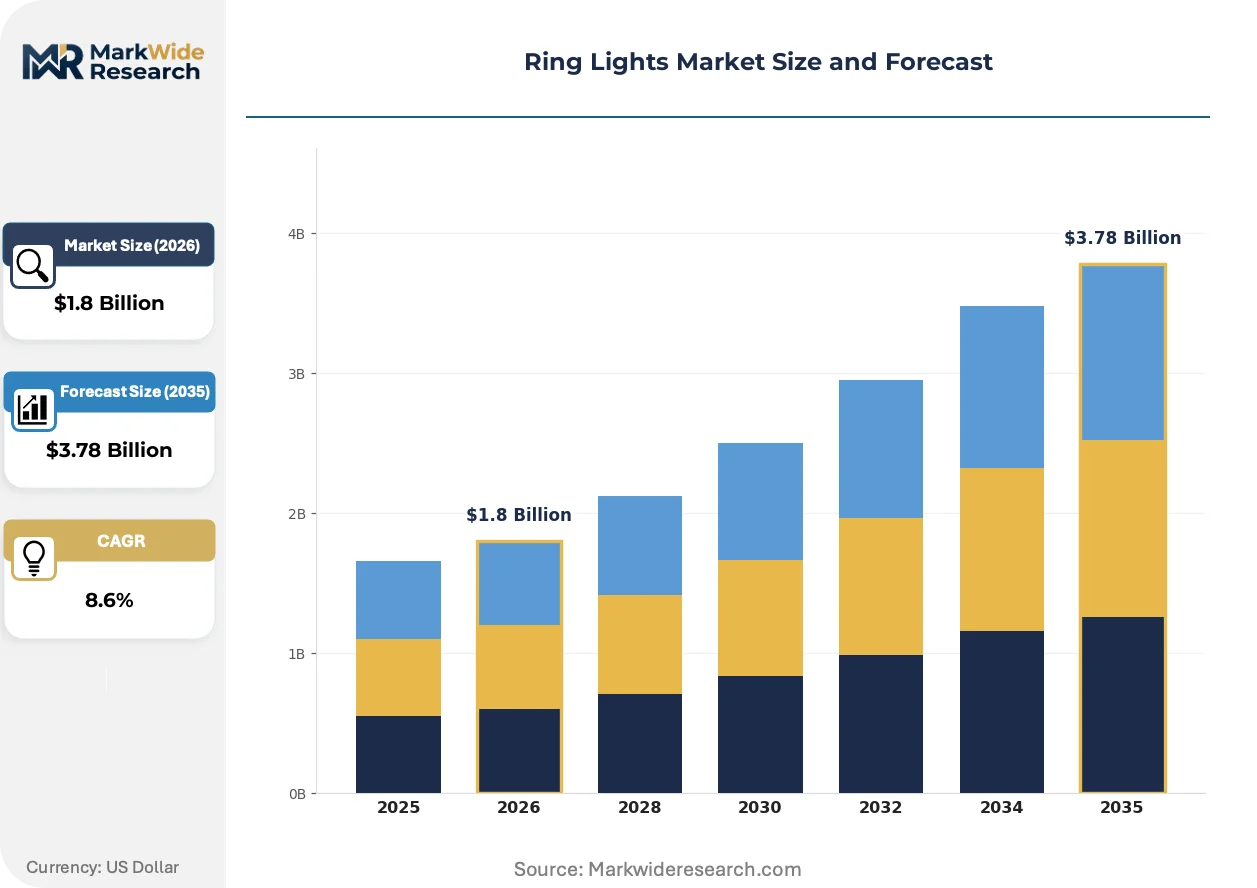
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.78 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Fluorescent, Halogen, Incandescent Application: Photography, Video Production, Makeup, Content Creation Size: 12 inch, 18 inch, 20 inch, 26 inch Power Source: Battery, AC, USB, Solar |
| Companies Covered | Elgato, Sensyne, Neewer, Logitech, Razer, UBeesize, Godox, Emart, Lume Cube, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ring Lights Market Strategic Shifts
Active innovation in ring lights centers on collapsing the performance gap between studio-grade output and pocketable form factors, while regulatory pressure and creator workflow fragmentation reshape competitive priorities.
Bi-color LED arrays with independent warm and cool diode channels are collapsing the traditional divide between fixed-color-temperature studio fixtures and adjustable field lighting. Mobile-first creators operating from co-working spaces and hotel rooms now demand CRI 95+ output from battery-powered units weighing under 500 grams. This compression is eroding the premium positioning of AC-powered studio exclusives and forcing incumbent brands to reengineer thermal dissipation around constrained form factors.
California Title 20 and the EU Ecodesign Directive are imposing parallel efficacy minimums that filter non-compliant SKUs from two of the largest addressable markets. Manufacturers must now maintain separate component bills and testing documentation for regulatory subsets, compressing margin structures on entry-tier products. The LED driver supply base is consolidating certification capabilities in-house to preserve cross-border market access.
Leasing and short-term rental channels are displacing outright equipment purchase among emerging creators with irregular project flows. London, Los Angeles, and Berlin production hubs now host specialized subscription services bundling ring lights with camera bodies and audio kits. This shift is fragmenting traditional retail volume concentration and forcing manufacturers to develop asset-tracking and refurbishment capabilities previously foreign to consumer electronics supply chains.
Ring Lights Market Segmentation
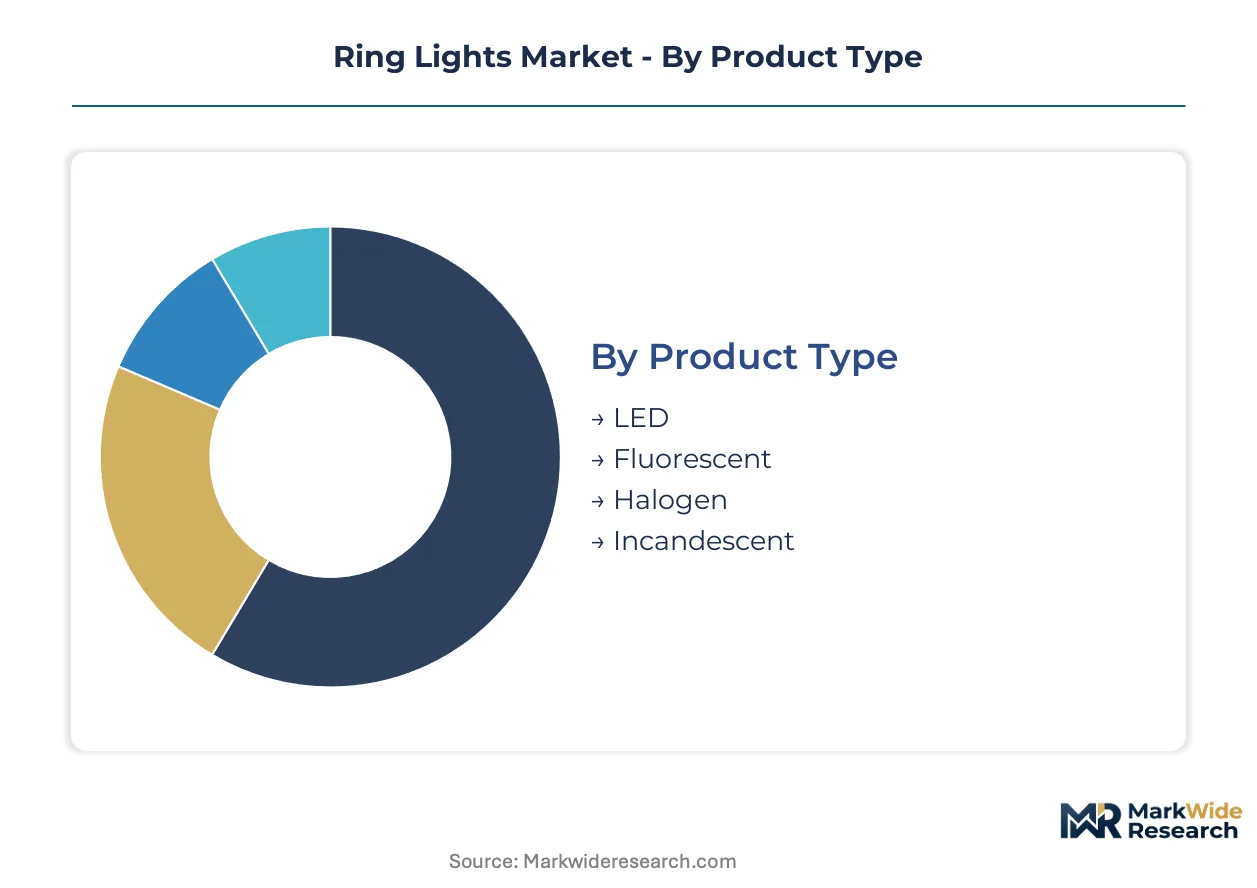
Ring light segmentation reflects divergent creator workflows and regulatory pressures reshaping product development. Each dimension captures distinct trade-offs between portability, output quality, and compliance burden that vendors must navigate.
Product Type:
Creator workflows span from mobile phone attachments to studio-grade rigs, demanding fundamentally different light source technologies.
- LED:Semiconductor diode arrays deliver dimmable output with adjustable color temperature and minimal thermal footprint. Content creation studios in the United States prioritize LED units for multi-hour streaming sessions where heat management and CRI 95+ accuracy prove essential.
- Fluorescent:Gas-discharge tubes produce soft, diffused illumination through phosphor coatings. Legacy photography rental houses in Germany and France retain fluorescent inventory for budget-conscious portrait clients, though replacement lamp scarcity accelerates phase-out.
- Halogen:Tungsten-halogen filaments generate high-CRI output with significant heat dissipation requirements. EU Ecodesign Directive efficacy minimums have removed halogen ring lights from European distribution channels entirely.
- Incandescent:Resistive wire filaments produce warm color temperature through thermal radiation. California Title 20 compliance costs and inventory stranding have collapsed commercial viability outside specialty theatrical applications.
The dominant share belongs to LED, while USB-compatible LED variants are climbing the fastest as laptop-tethered streaming proliferates.
Application:
End-use fragmentation drives specification divergence across color accuracy, mounting flexibility, and power autonomy requirements.
- Photography:Studio and location portrait work demands high-CRI output with standardized color temperature for post-production consistency. Professional photographers in Los Angeles and New York prioritize Godox-compatible mounting systems and modular accessory ecosystems.
- Video Production:Multi-camera interview setups and independent filmmaking require flicker-free dimming and DMX control integration. Production houses in London and Berlin specify 18-inch and 26-inch diameters for subject distance flexibility.
- Makeup:Cosmetic application depends on accurate skin tone rendering under daylight-matching conditions. Salon chains in South Korea and Japan specify bi-color LED arrays with independent warm and cool channels for client consultation accuracy.
- Content Creation:Independent streamers and short-form video producers prioritize USB-powered portability over output intensity. Mobile creators operating from co-working spaces and hotel rooms drive demand for sub-500-gram battery units.
Content creation commands the fastest-expanding application segment, though photography retains the highest average selling prices.
Size:
Physical diameter determines subject distance range, catchlight geometry, and transportability trade-offs that segment buyer profiles.
- 12 inch:Compact ring lights suit smartphone-mounted vlogging and makeup mirror integration. Mobile-first creators in India and Brazil favor 12-inch USB models for luggage-constrained travel workflows.
- 18 inch:Mid-diameter units balance portability with sufficient subject distance for seated streaming setups. Independent YouTube producers across Germany and the United Kingdom treat 18-inch as the default studio investment tier.
- 20 inch:Slightly expanded aperture extends comfortable working distance for standing subject framing. Commercial portrait studios in France specify 20-inch units for headshot sessions requiring subject mobility.
- 26 inch:Maximum diameter delivers the softest shadow transition and largest catchlight for cinematic close-ups. High-end production facilities in Los Angeles and New York deploy 26-inch arrays for broadcast interview lighting.
Eighteen-inch fixtures hold the volume leadership position, while 12-inch variants are gaining share fastest through mobile creator adoption.
Power Source:
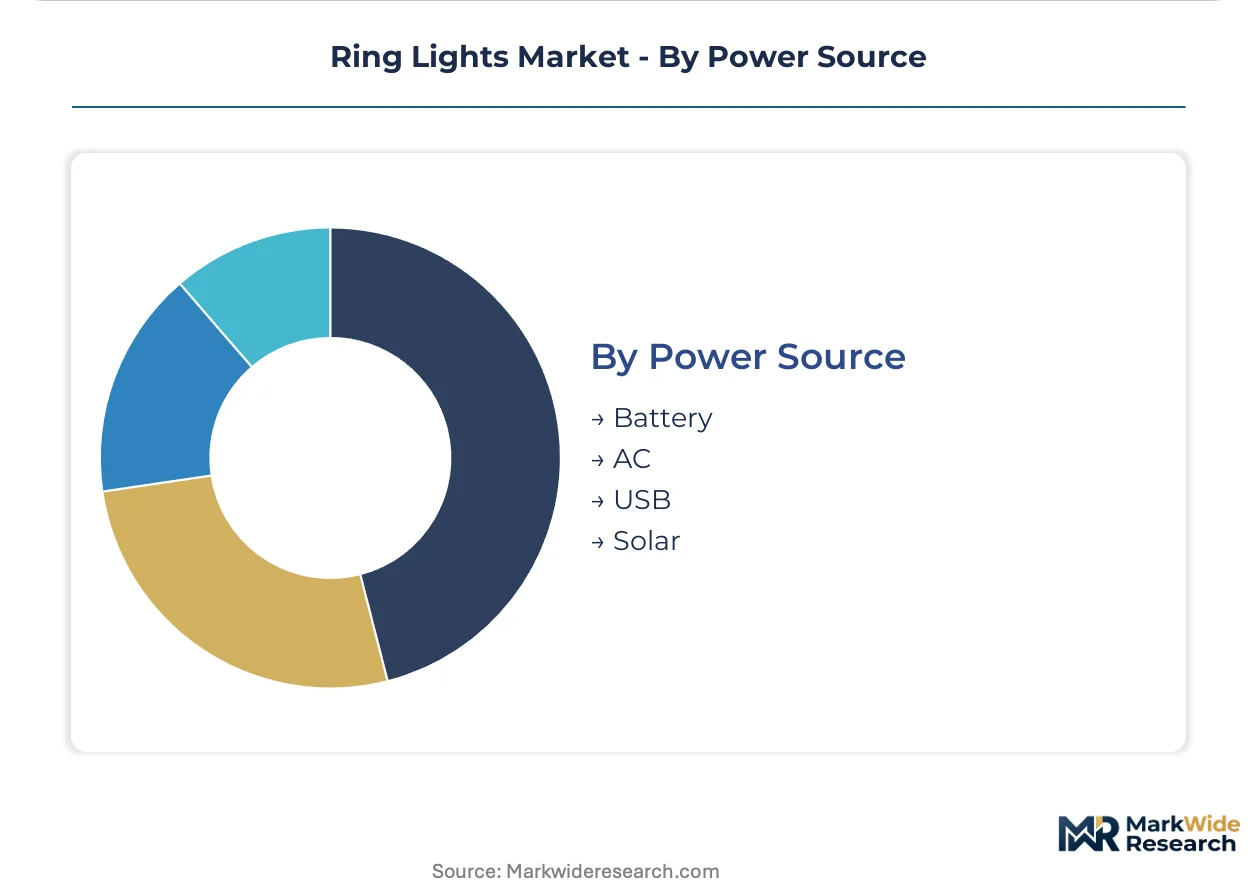
Energy architecture determines use case mobility, output ceiling, and regulatory exposure across transport and grid efficiency regimes.
- Battery:Lithium-ion cell packs enable location shooting without grid access. IATA cargo restrictions on lithium-ion transport complicate cross-border fulfillment for brands serving creator economies in Australia and Canada.
- AC:Mains-powered units deliver maximum sustained output for permanent studio installations. Professional photography studios in Japan and South Korea prefer AC architecture for thermal stability during extended sessions.
- USB:Bus-powered operation from laptops and power banks supports laptop-tethered streaming workflows. Mobile creators in the United States and United Kingdom are displacing AC-dependent models with USB-powered 12-inch and 18-inch variants.
- Solar:Photovoltaic charging integration targets off-grid content production and sustainability marketing claims. Expedition documentary crews operating in remote Australian and Kenyan locations pilot solar-hybrid prototypes.
AC-powered systems retain the dominant installed base, though USB architectures are expanding most quickly through streaming workflow adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Net import dependence in ring lights concentrates among creator economies lacking domestic LED driver manufacturing, while export surplus positions cluster in East Asian electronics assembly corridors. Trade flows now track regulatory divergence between EU efficacy mandates and US creator infrastructure buildouts.
United States
Independent streamers and content production houses in Los Angeles and New York drive premium ring light procurement for multi-platform output. The FCC regulates electromagnetic interference from dimmable LED drivers and wireless control modules, adding compliance cost layers for cross-border suppliers. E-commerce fulfillment density in California and Texas supports rapid inventory turnover for USB-powered mobile creator units.
Germany
Legacy photography rental houses in Berlin and Munich retain fluorescent inventory for budget-conscious portrait clients despite replacement lamp scarcity. The EU Ecodesign Directive imposes minimum luminous efficacy requirements that filter non-compliant halogen and incandescent ring lights from European distribution channels. Professional studios in Hamburg specify Godox-compatible mounting systems for modular accessory ecosystems.
China
LED driver manufacturing clusters heavily in Shenzhen and Dongguan supply bases, exposing brands to single-source vulnerability and extended lead times. The country's national electronics standards regulator oversees GB standards compliance for domestic and export-bound lighting products. Component concentration in the Pearl River Delta shapes global availability timelines for dimmable driver architectures.
United Kingdom
Independent YouTube producers across London and Manchester treat 18-inch ring lights as the default studio investment tier for seated streaming setups. Post-Brexit customs procedures complicate EU component sourcing for domestic assembly operations. Co-working space proliferation in Bristol and Edinburgh accelerates demand for sub-500-gram battery-powered USB units.
South Korea
Salon chains in Seoul specify bi-color LED arrays with independent warm and cool channels for client consultation accuracy in cosmetic application. The country's national electronics regulator enforces safety certification for lithium-ion battery packs in portable lighting equipment. Professional photography studios in Busan prefer AC architecture for thermal stability during extended portrait sessions.
Ring Lights Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in driver and LED array supply. The vendor base organizes around three tiers: manufacturing-scale Amazon-native brands, streaming-peripheral ecosystem anchors, and professional photography loyalty incumbents. Competitive moves concentrate on SKU fragmentation across power architectures and subscription equipment leasing pivots. Strategic partnerships between lighting OEMs and camera accessory distributors reshape channel access.
Within the manufacturing-scale tier, Neewer and UBeesize exemplify Amazon-native positioning across entry-to-mid tier SKUs. Godox anchors professional photography loyalty through high-CRI LED arrays and modular accessory compatibility. Logitech occupies the premium segment through integration with streaming peripherals and software ecosystems.
| Leading Market Players |
|---|
| Elgato |
| Sensyne |
| Neewer |
| Logitech |
| Razer |
| UBeesize |
| Godox |
| Emart |
| Lume Cube |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on Shenzhen and Dongguan LED driver manufacturing clusters determines both pricing tier spreads and supply chain shape, compressing margins on entry-tier SKUs while amplifying premium capture for brands with captive component sourcing.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Content creation studios in Los Angeles and New York absorb premium positioning for CRI 95+ certification and Godox-compatible mounting ecosystems, while Amazon-native brands compete on volume scale in the USB-powered economy tier. Price differentiation rests on thermal management sophistication and FCC pre-certification status. Cost compression in the standard tier is intensifying because California Title 20 compliance requires separate testing documentation. Independent streamers exhibit the highest price sensitivity, whereas professional photography studios show minimal elasticity for modular accessory compatibility.
Supply Chain Analysis
Contract manufacturing concentration sits with Foxconn, Luxshare Precision, and specialized LED assembly houses in the Pearl River Delta. Component sourcing draws from China for dimmable drivers, South Korea for high-efficacy LED dies, and Japan for optical diffusers. Raw material dependencies include aluminum heat sinks, lithium-ion cells for battery segments, and copper magnet wire for driver inductors. Single-source vulnerability in East Asian driver manufacturing exposes brands to extended lead times when IATA cargo restrictions tighten. Distribution runs through Amazon marketplace fulfillment centers, direct-to-consumer channels, and B&H Photo specialty retail for professional tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription equipment leasing represents a service-attach opportunity expanding faster than hardware transactional sales, with Los Angeles and Berlin production hubs now hosting specialized rental services bundling ring lights with camera bodies and audio kits.
For Market Incumbents: Insulate professional photography loyalty by deepening Godox-compatible accessory ecosystems and pre-certifying portable power systems against emerging IATA lithium-ion cargo restrictions. Acquire color science talent from legacy photography lighting engineers to accelerate CRI optimization velocity. Vertical integration into LED driver manufacturing preserves cross-border market access as regulatory testing timelines compress launch windows. For New Entrants and Emerging Players: Mid-market content creation studios in the United Kingdom and Germany represent the most penetrable entry point, where irregular project flows favor subscription models over capital expenditure. Battery-powered USB segments under 500 grams targeting mobile creators in co-working spaces offer white-space positioning against AC-dependent incumbents. A direct-to-consumer launch via TikTok Shop and creator affiliate programs bypasses established Amazon-native saturation. For Investors and Strategic Acquirers: The market sits at a regulatory-consolidation phase that favors vertically integrated component specialists with captive driver manufacturing and multi-certification capabilities. Long-term viability across the analysis window hinges on subscription infrastructure and refurbishment capabilities previously foreign to consumer electronics supply chains. Monitor EU Ecodesign Directive enforcement intensity and California Title 20 expansion to adjacent states as inflection indicators for legacy SKU obsolescence acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Equipment Leasing | Asset-light studio buildouts in Los Angeles create recurring revenue pools beyond transactional hardware sales. |
| LED Driver Backward Integration | In-house production of dimmable architectures preserves cross-border market access against FCC certification delays. |
| Battery Pre-Certification Program | IATA lithium-ion cargo compliance locks in first-mover advantage for portable creator workflows in Australia and Canada. |
| Godox Ecosystem Expansion | Modular accessory compatibility deepens professional photography loyalty in Hamburg and New York studio markets. |
| Direct-to-Consumer Platform Launch | TikTok Shop and creator affiliate channels bypass Amazon-native saturation among mobile-first Gen Z creators. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of SEC filings, Amazon marketplace transaction data, FCC equipment authorization databases, and EU Ecodesign Directive compliance registries. Primary interviews incorporated product managers at lighting OEMs, procurement leads at content creation studios, regulatory affairs specialists at cross-border suppliers, and category buyers at B&H Photo and Adorama. Bottom-up unit economics modeling triangulated against top-down market sizing from customs records and e-commerce fulfillment density metrics.
Forecast inputs span product type segmentation by LED, fluorescent, halogen, and incandescent architectures; power source differentiation across battery, AC, USB, and solar configurations; and application splits between photography, video production, makeup, and content creation. CAGRs were derived from regression analysis against creator economy infrastructure investment, regulatory phase-out timelines for legacy sources, and laptop-tethered streaming adoption curves. Industry-specific inputs include EU Ecodesign Directive enforcement velocity and California Title 20 expansion probability.
Practitioners should monitor IATA lithium-ion transport regulation evolution, smartphone computational photography advancement, and LED driver supply base consolidation for early signals of forecast revision. Quarterly review of FCC certification backlog duration and EU customs seizure rates for non-compliant legacy inventory is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Dimmer and Color Tunable Market
Lighting
High Bay Lighting Market
Lighting
Fluorescent Lighting Market
Lighting
Smart Lighting Market
Lighting
Industrial LiDAR Integrated Lighting Market
Lighting
Directional Luminaire Market
Lighting
US Indoor LED Lighting Market
Lighting
Hazardous Location LED Lighting Market
Lighting
Solar Column Headlight Market
Lighting
LED Eye Protection Lamp Market
Lighting
Gesture Control Light Market
Lighting
Global Lighting Control System Market
Lighting
Plasma Lighting Market
Lighting
Global Machine Vision Lighting Market
Lighting
Asia-Pacific Lighting Control Market
Lighting
Wireless Lighting Market