
 Ocular Drug Delivery Technology Market | 2026-2036
Ocular Drug Delivery Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Ocular Drug Delivery Technology Market Intelligence
The adoption of biodegradable polymers like poly-lactic-co-glycolic acid (PLGA) in place of non-degradable materials such as silicone is restructuring the economics of intravitreal implants. Ocular Therapeutix, Inc. specializes in hydrogel-based therapies for sustained release. Alimera Sciences, Inc. leverages its non-erodible implant technology for chronic retinal diseases. AbbVie Inc. competes through its broad portfolio of ophthalmic pharmaceuticals requiring advanced delivery mechanisms.
Ocular drug delivery technology comprises advanced formulations and devices designed to transport therapeutics to specific targets within the eye. These systems are engineered to bypass physiological barriers and maintain drug concentration, often utilizing particle sizes in the nanometer range. While topical eye drops remain a mature product category, technology segments like nanoparticles and hydrogels show significant momentum. Growth is most pronounced in applications for chronic conditions such as age-related macular degeneration and diabetic retinopathy, where sustained release is critical.
Market access is governed by stringent regulatory frameworks, including the U.S. FDA's requirements for new drug applications and the EMA's marketing authorisation process in Europe. In Japan, the PMDA imposes its own rigorous standards for safety and efficacy. These agencies' approval timelines directly influence development costs. Stakeholder success hinges on navigating the complex patent landscape and securing reimbursement for novel, high-cost delivery systems.
Market Dynamics
The fundamental dynamic shaping the ocular drug delivery market is the epidemiological transition toward chronic, age-related eye diseases. This shift from acute care necessitates sustained-release technologies that can maintain therapeutic drug levels over months, reducing treatment burden for conditions like glaucoma and diabetic retinopathy.
Growth Catalysts
- Advanced Formulations:The development of biodegradable polymers like PLGA and novel hydrogels enables the creation of long-acting implants and injectables, directly addressing the clinical need for reduced dosing frequency in chronic retinal diseases.
- Aging Demographics:A rising prevalence of age-related macular degeneration and glaucoma, particularly in developed nations like the United States and Japan, creates a large and growing patient population requiring advanced ophthalmic therapies.
- Regulatory Pathways for Innovation:Clear, albeit stringent, regulatory frameworks from agencies like the U.S. FDA provide a defined path to market for novel delivery systems that demonstrate significant improvements in efficacy or patient compliance.
Market Restraints
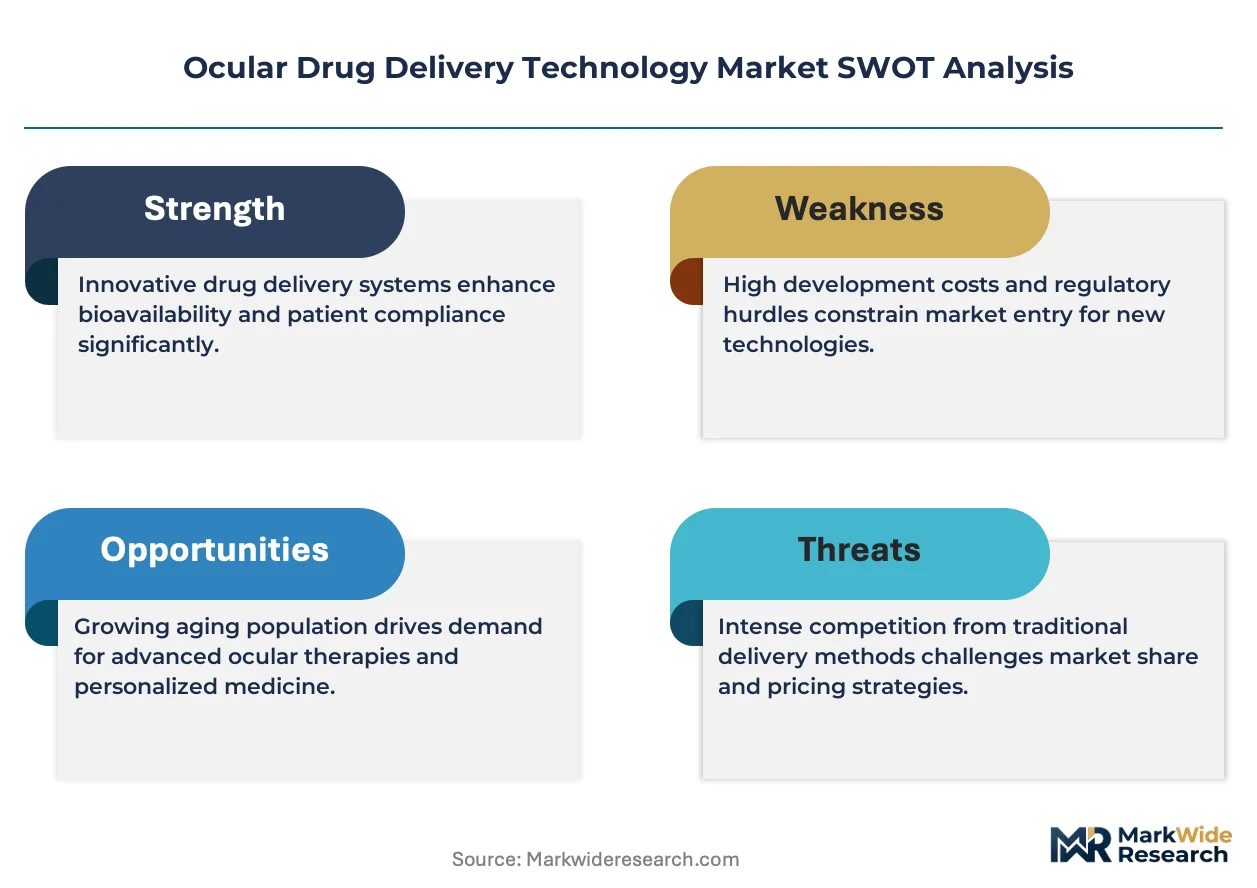
- High Development Costs:The research, development, and manufacturing of complex delivery systems, such as nanoparticle suspensions and biodegradable implants, involve substantial capital investment and specialized expertise, creating high barriers to entry.
- Physiological Barriers:The eye's natural protective mechanisms, including the blood-retinal barrier and tear film clearance, present formidable technical challenges to achieving effective drug concentration at posterior target sites.
- Stringent Regulatory Scrutiny:Lengthy and costly clinical trial requirements mandated by regulatory bodies like the European Medicines Agency (EMA) and Japan's PMDA can significantly delay product launches and increase overall development expenses.
Strategic Opportunities
- Expansion in Emerging Economies:Untapped markets in certain Asia-Pacific and Latin American countries, where healthcare infrastructure is improving, offer significant growth potential for more accessible and cost-effective drug delivery technologies.
- Gene Therapy Delivery:The rise of gene therapies for inherited retinal diseases creates a demand for new delivery vectors, including advanced viral and non-viral nanoparticle systems capable of targeted cell transfection within the retina.
- Smart Ocular Implants:The convergence of micro-electro-mechanical systems (MEMS) with drug delivery technology opens possibilities for intelligent implants that can monitor intraocular pressure and dispense medication on demand.
Industry Challenges
- Complex Patent Landscape:Navigating the dense and often overlapping intellectual property rights surrounding sustained-release platforms and hydrogel chemistry presents a significant operational hurdle, increasing the risk of litigation.
- Reimbursement Hurdles:Securing adequate reimbursement from public and private payers for premium-priced, technologically advanced delivery systems remains a critical challenge that can limit patient access and commercial uptake.
- Manufacturing Scalability:Achieving consistent, sterile, and large-scale production of formulations with components in the nanometer range is technically demanding and requires substantial investment in specialized manufacturing facilities and quality control processes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ocular Drug Delivery Technology Market |
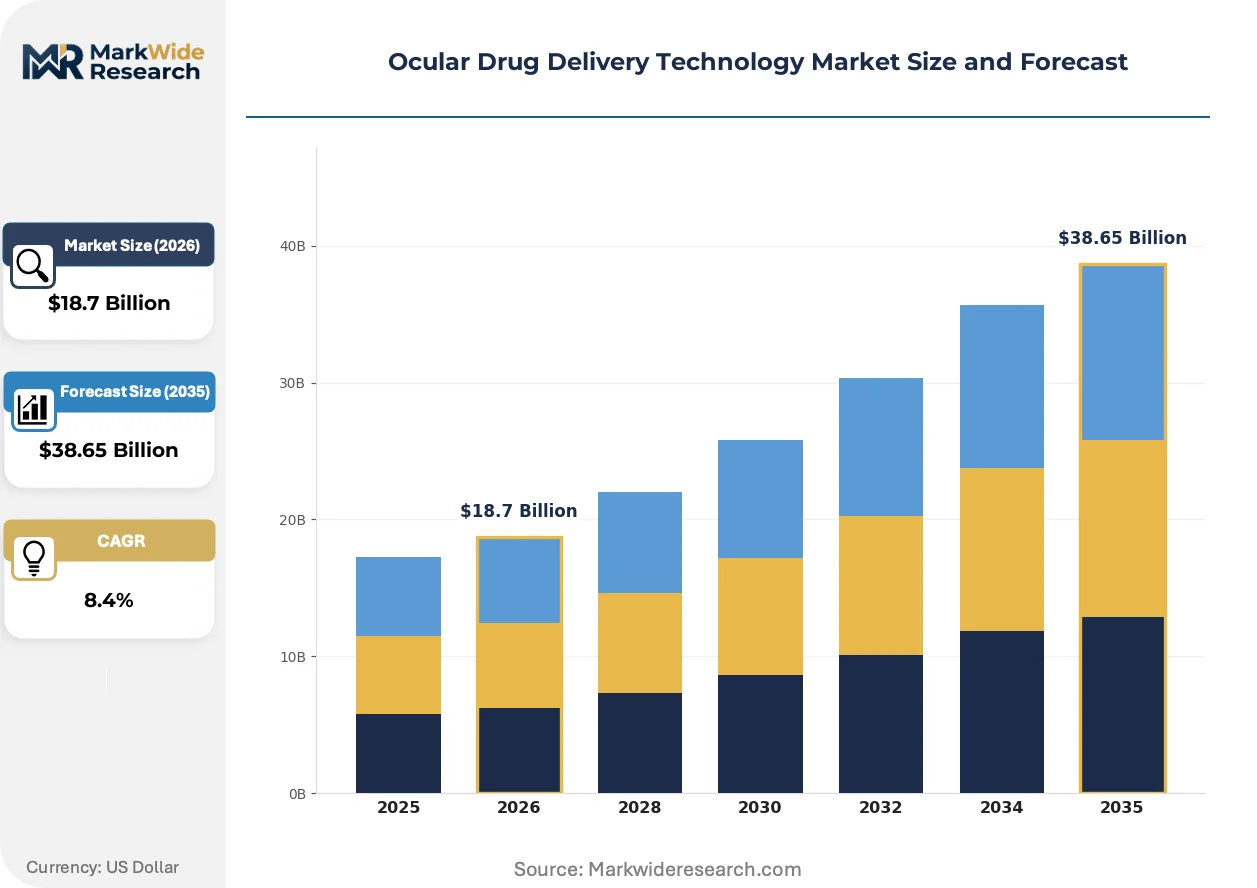
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Eye Drops, Ointments, Injectable Solutions, Intravitreal Implants, Microneedles Technology: Nanoparticles, Liposomes, Hydrogels, Contact Lens-Based Systems, Microemulsions Application: Glaucoma Management, Diabetic Retinopathy, Age-Related Macular Degeneration, Dry Eye Disease, Uveitis Treatment End User: Ophthalmic Clinics, Specialty Pharmacies, Research Institutes, Eye Hospitals, Ambulatory Surgical Centers |
| Companies Covered | Ocular Therapeutix, Inc., Alimera Sciences, Inc., Allergan plc, Bausch Health Companies Inc., Santen Pharmaceutical Co., Ltd., Clearside Biomedical, Inc., EyeGate Pharmaceuticals, Inc., Novartis AG, AbbVie Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ocular Drug Delivery Technology Market Strategic Shifts & Innovations
Precision and patient-centricity are becoming the central themes in technology development, moving the industry beyond conventional topical solutions. Innovations focus on minimizing treatment burden and improving therapeutic targeting to specific ocular tissues, reflecting a deeper understanding of disease pathology.
Microneedle arrays designed for transscleral application provide a minimally invasive method for delivering therapeutics to the posterior segment of the eye. Biopharmaceutical firms developing biologics for retinal conditions are actively exploring this approach in clinical development. This technology is integrating drug delivery with a physical device, offering a potential alternative to intravitreal injections administered by specialists in a clinical setting.
The European Medicines Agency (EMA) is increasingly emphasizing patient-reported outcomes and quality-of-life data within its marketing authorisation process for new ophthalmic treatments. This regulatory pressure incentivizes the development of delivery systems that demonstrably reduce treatment frequency and patient discomfort. Sustained-release technologies, which directly address this patient-centric mandate, are consequently gaining favor in regulatory submissions across Europe.
A discernible shift in care delivery is underway, with treatment administration moving from large hospital settings to smaller, specialized retina clinics. This decentralization of care disrupts established distribution models geared toward bulk hospital purchasing, creating an advantage for suppliers with agile logistics. This trend is most prominent in the United States, where networks of private ophthalmology practices are expanding their capacity to manage chronic eye diseases.
Ocular Drug Delivery Technology Market Segmentation
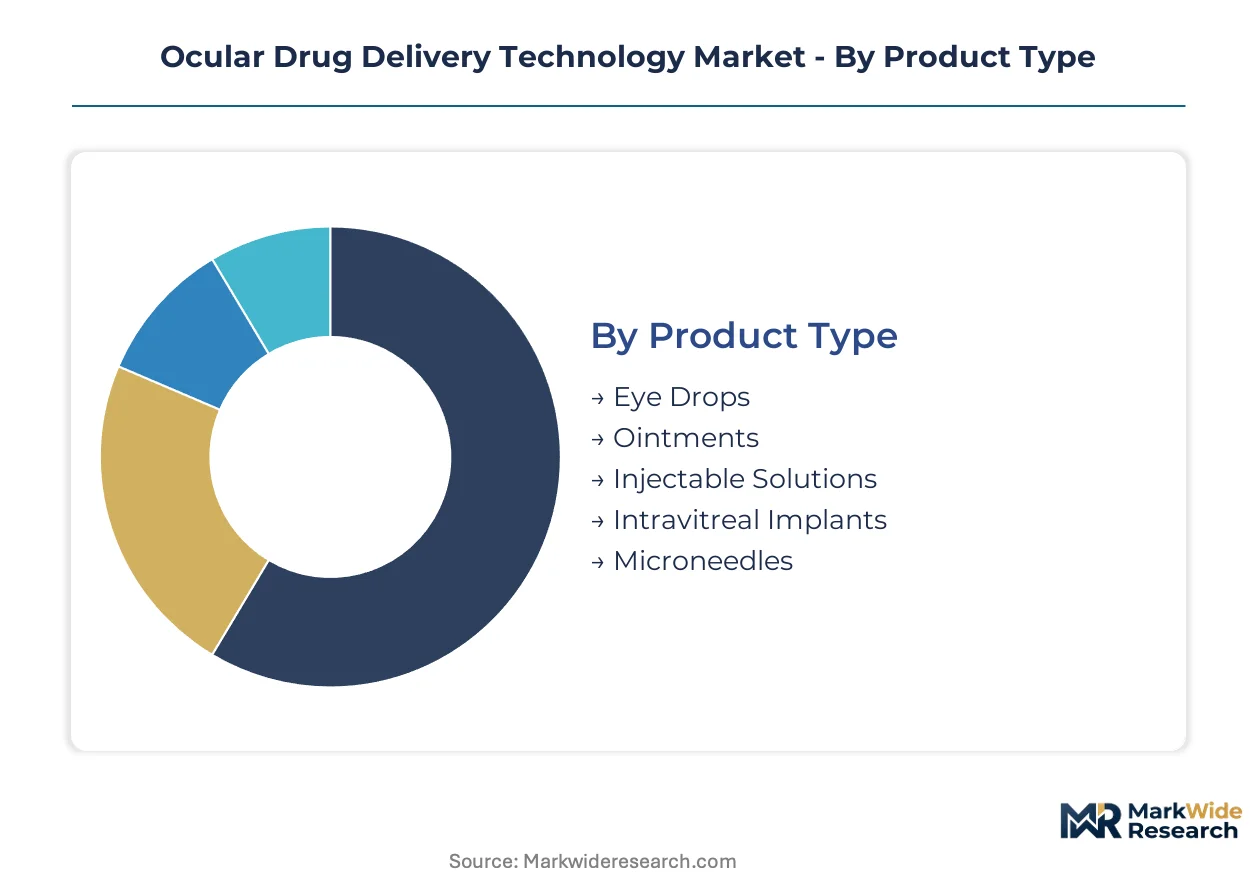
The ocular drug delivery technology market is strategically segmented to reflect the diverse methods of drug administration and the specific therapeutic needs of patients. Understanding these distinctions is crucial for manufacturers to tailor product development and market entry strategies effectively. This segmentation highlights the varying technical complexities and clinical applications across the industry.
Product Type:
Purchasing decisions in this category are primarily differentiated by the required administration route and the desired duration of therapeutic effect.
- Intravitreal Implants:These advanced systems are designed for sustained drug release directly into the vitreous humor, often utilizing biodegradable polymers like PLGA to reduce treatment frequency for chronic conditions. Demand concentrates in applications requiring long-term therapeutic levels, particularly for retinal diseases in the United States.
- Injectable Solutions:Formulations delivered via injection bypass ocular barriers, providing high drug concentrations at target sites within the eye, often employing specialized carriers for extended duration. These solutions are critical for conditions where rapid onset or precise dosing is necessary, especially in specialized retina clinics.
- Eye Drops:Topical eye drops represent a mature product category, offering non-invasive administration for anterior segment conditions.
- Ointments:These viscous formulations provide extended contact time on the ocular surface compared to drops, improving drug absorption for certain conditions.
- Microneedles:Microneedle arrays offer a minimally invasive transscleral application route, delivering therapeutics to the posterior segment of the eye.
Eye Drops leads volumes today; Intravitreal Implants is gaining share fastest.
Technology:
The maturity level of a technology often dictates its current adoption rate and future growth trajectory within the ocular drug delivery market.
- Hydrogels:These biocompatible polymer networks swell in water, enabling sustained release of therapeutic agents over extended periods, with Ocular Therapeutix, Inc. specializing in this area. Growth in hydrogel applications is pronounced in chronic conditions requiring consistent drug levels, particularly in Europe.
- Nanoparticles:Systems utilizing particle sizes in the nanometer range facilitate targeted drug delivery by bypassing physiological barriers and enhancing cellular uptake within ocular tissues. Demand for nanoparticles is accelerating with the rise of gene therapies for inherited retinal diseases.
- Liposomes:Lipid-based vesicles encapsulate drugs, enhancing solubility and extending residence time within the eye, particularly for hydrophobic compounds.
- Contact Lens-Based Systems:Specialized contact lenses are engineered to release medication continuously, offering a convenient, non-invasive option for sustained topical delivery.
- Microemulsions:These thermodynamically stable isotropic mixtures of oil, water, and surfactant enhance drug penetration and bioavailability for ophthalmic formulations.
The market shows a clear preference for Hydrogels due to their sustained-release capabilities.
Application:
Patient demographics and disease chronicity are the primary factors influencing the selection of appropriate drug delivery applications.
- Age-Related Macular Degeneration:This chronic condition, prevalent in aging populations, necessitates sustained-release technologies to maintain therapeutic drug levels and reduce treatment burden. The United States and Japan represent significant markets for new treatments.
- Diabetic Retinopathy:A leading cause of blindness, this chronic condition requires advanced delivery systems capable of sustained action to manage retinal damage and prevent vision loss. Demand is high for solutions reducing frequent injections.
- Glaucoma Management:This application requires consistent intraocular pressure control, driving demand for sustained-release formulations that improve patient compliance.
- Dry Eye Disease:Treatments focus on symptom relief and ocular surface health, often through advanced topical formulations with extended residence time.
- Uveitis Treatment:Managing ocular inflammation in uveitis often involves targeted delivery to the posterior segment, requiring potent anti-inflammatory agents.
Demand for Glaucoma Management remains high, while Age-Related Macular Degeneration is experiencing rapid expansion.
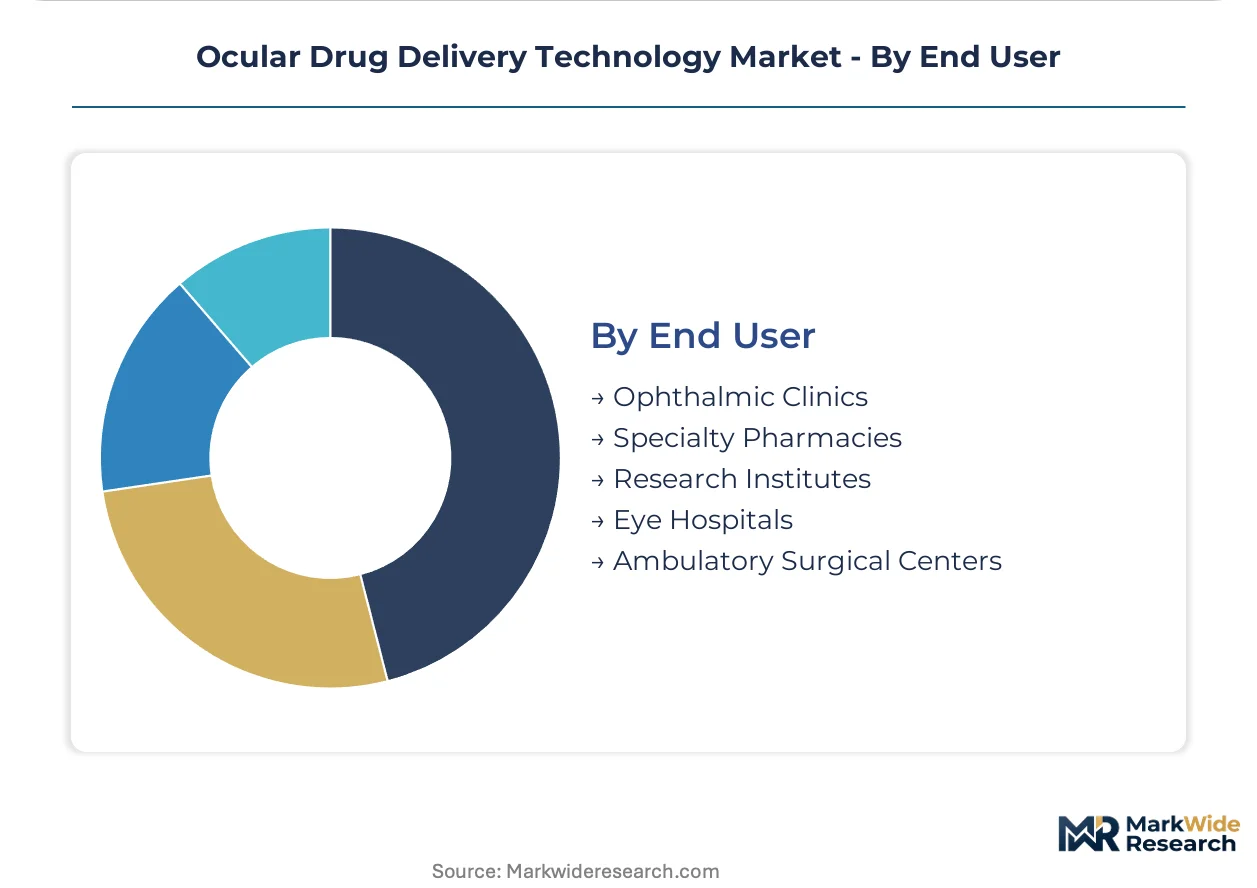
End User:
The operational scale and specialized service delivery models define the procurement patterns across different end-user segments.
- Ophthalmic Clinics:These specialized outpatient facilities are increasingly administering advanced ocular therapies, reflecting a decentralization of care delivery from larger hospitals. The trend is prominent in the United States, where private practices are expanding.
- Eye Hospitals:Large eye hospitals serve as primary centers for complex ophthalmic surgeries and treatments, maintaining significant purchasing power for a broad range of drug delivery systems. These institutions often handle high patient volumes and specialized cases.
- Specialty Pharmacies:These pharmacies manage and dispense high-cost, complex ophthalmic medications, often providing patient education and support services.
- Research Institutes:Academic and private research centers drive innovation in drug delivery, procuring advanced materials and systems for preclinical and clinical studies.
- Ambulatory Surgical Centers:Facilities performing outpatient eye surgeries require efficient and sterile drug delivery systems for pre-operative and post-operative care.
The shift towards Ophthalmic Clinics reflects evolving healthcare delivery models in developed nations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States biopharmaceutical research hubs drive innovation in ocular drug delivery technology, particularly for chronic eye diseases. This region benefits from substantial funding and an aging demographic, creating consistent demand for advanced ophthalmic solutions. Regulatory frameworks from agencies like the U.S. FDA guide market entry and product development for novel delivery systems.
United States
Aging demographics and significant biopharmaceutical research funding propel demand for sustained-release formulations in the United States. The U.S. FDA's stringent requirements for new drug applications shape product development pathways. The Boston-Cambridge innovation ecosystem pioneers novel delivery systems and hydrogel-based therapies for various ocular conditions.
Japan
An aging demographic and a high prevalence of age-related eye diseases generate substantial demand for advanced ophthalmic therapies in Japan. The PMDA imposes rigorous standards for safety and efficacy, influencing product design and clinical trials. Tokyo's pharmaceutical research centers actively develop advanced ophthalmic formulations and microneedle technologies.
Germany
Germany's strong healthcare infrastructure and focus on chronic conditions drive demand for sophisticated ocular drug delivery solutions. The European Medicines Agency (EMA) marketing authorisation process for ophthalmic treatments influences market access. Munich's biotech cluster advances biodegradable polymers and innovative implant designs for sustained drug release.
China
A large patient population and improving healthcare infrastructure contribute to the expanding market for ocular drug delivery technologies in China. The NMPA approval processes for new medical devices and drugs govern market introduction. Shanghai's biopharmaceutical industry parks attract increasing investment in local research and development for ocular therapeutics.
India
Untapped markets and improving access to specialized healthcare services create growth potential for ocular drug delivery technologies in India. CDSCO regulations for drug and medical device approvals guide local manufacturing and distribution. Hyderabad's Genome Valley fosters the development of cost-effective drug delivery solutions tailored for regional needs.
Ocular Drug Delivery Technology Market Key Industry Players
Global majors compete with regional champions across technological innovation and market access strategies within the ocular drug delivery market. The market structure exhibits a tiered consolidation, with large pharmaceutical companies alongside specialized firms and emerging biotech innovators. Strategic partnerships for technology licensing and portfolio diversification into advanced delivery mechanisms represent dominant competitive moves.
Specialists in advanced ocular delivery platforms include Ocular Therapeutix, Inc., which exemplifies hydrogel-based sustained release therapies. Alimera Sciences, Inc. represents non-erodible implant technology for chronic retinal diseases. AbbVie Inc. occupies a position among broad pharmaceutical companies with diverse ophthalmic portfolios requiring advanced delivery mechanisms.
| Leading Market Players |
|---|
| Ocular Therapeutix, Inc. |
| Alimera Sciences, Inc. |
| Allergan plc |
| Bausch Health Companies Inc. |
| Santen Pharmaceutical Co., Ltd. |
| Clearside Biomedical, Inc. |
| EyeGate Pharmaceuticals, Inc. |
| Novartis AG |
| AbbVie Inc. |
| Others |
Cost & Logistics Intelligence
Stringent regulatory frameworks from the U.S. FDA and EMA mandate high quality and compliance for ocular drug delivery systems. This regulatory pressure shapes supply chain choices and influences premium pricing for novel therapies.
Pricing Analysis
Input costs for specialized materials like biodegradable polymers and advanced hydrogels are frequently passed through to the final price of ocular drug delivery systems. Value-based pricing dominates for innovative therapies, reflecting clinical benefits and reduced treatment frequency. Price differentiation is driven by regulatory approval status and manufacturing complexity. Pricing pressure stems from reimbursement hurdles for novel, high-cost delivery systems, making ophthalmic clinics price-sensitive for standard products, while research institutes prioritize advanced solutions.
Supply Chain Analysis
Logistics and freight costs are significant for ocular drug delivery, particularly for temperature-sensitive biologics and high-value sterile implants requiring specialized transport. Supply concentration centers on the United States for advanced R&D and Germany for specialized component manufacturing. The industry relies on biocompatible polymers and sterile packaging, creating single-source vulnerability for specialized APIs or MEMS components. Distribution runs through direct-to-clinic models for complex therapies and specialty pharmacies for high-cost medications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ocular drug delivery market functions as a regulatory compounder, with stringent frameworks driving continuous innovation. The European Medicines Agency's (EMA) increasing emphasis on patient-reported outcomes directly incentivizes sustained-release technologies.
For Market Incumbents:
Anchor existing product lines with continuous formulation improvements to maintain market share against emerging technologies. Incumbents should strategically acquire specialized firms in gene therapy delivery or smart implant technology to counter disruptive entrants. Invest in manufacturing scalability for nanometer-range formulations to meet future demand. Secure robust intellectual property around novel sustained-release platforms.
For New Entrants and Emerging Players:
Microneedle arrays for transscleral application offer a technology-first wedge into the posterior segment delivery market. New entrants should target specific niche applications like gene therapy delivery for inherited retinal diseases, which demands novel nanoparticle systems. Untapped markets in certain Asia-Pacific countries present white-space growth opportunities. Partnering with specialized retina clinics can facilitate rapid market penetration by emphasizing patient compliance and reduced treatment burden.
For Investors and Strategic Acquirers:
Asymmetric upside sits with specialized biotech firms advancing next-generation sustained-release platforms for chronic retinal diseases. The market shows favorable long-term viability, driven by aging demographics and the epidemiological shift towards chronic eye conditions. Acquisition targets should possess robust patent portfolios in hydrogel chemistry or nanoparticle systems. A key signal to watch is successful Phase 3 clinical trial readouts for novel intravitreal implants demonstrating significantly reduced treatment frequency.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerate development of sustained-release implants for chronic conditions. |
| Regulatory Approval Pathway | Streamline U.S. FDA and EMA submissions for novel delivery systems. |
| Manufacturing Scale-Up | Invest in facilities for large-scale production of nanometer-range formulations. |
| Strategic Partnership | Collaborate with gene therapy developers for advanced delivery vectors. |
| Pipeline Diversification | Expand product offerings into smart ocular implants or microneedle technologies. |
Research Approach
Direct dialogue with drug development executives, regulatory affairs leads, and ophthalmologists provided qualitative insights into market dynamics. This primary research was rigorously validated against secondary sources, including U.S. FDA filings, EMA submissions, and ClinicalTrials.gov. The approach involved both bottom-up and top-down triangulation to ensure data accuracy and consistency.
A bottom-up analysis established market sizing for various product types and technologies, with top-down validation ensuring overall consistency. The analytical framework modeled segmentation across product type, technology, application, and end user over the projection horizon. Compound annual growth rates were derived from historical data and projected market drivers, including age-related macular degeneration prevalence and R&D pipeline progress.
The model holds under current regulatory landscapes and established reimbursement policies; deviation in healthcare funding or unexpected therapeutic breakthroughs would shift projections. Forecasts reflect assumptions regarding technological development trajectories and disease prevalence. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Europe Exosome Research Products Market
Biomedical Technology
Lipid Transfer Proteins Market
Biomedical Technology
Europe Serine Proteases Market
Biomedical Technology
Liquid Biopsy Market
Biomedical Technology
Neuro Immunoassay Market
Biomedical Technology
Global Primary Cell Culture Market
Biomedical Technology
Protein Expression Technology Market
Biomedical Technology
Fluoro Enzymatic Assays Market
Biomedical Technology
Handheld DNA Reader Market
Biomedical Technology
Global Synthetic Biosensors Market
Biomedical Technology
Cell Tracing and Tracking Test Market
Biomedical Technology
Ligases Enzyme Market
Biomedical Technology
Cell Proliferation Assay Market
Biomedical Technology
Exonucleases Market
Biomedical Technology
Custom Nucleic Acid Market
Biomedical Technology
DNA Forensics Market