
 Ontogenetic Market | 2026-2036
Ontogenetic Market Size, Share, and Industry Trends Forecast 2026-2036
Ontogenetic Market Analytics
Academic institutes are reorganizing procurement priorities toward high-throughput ontogenetic platforms, displacing traditional single-lab fabrication models. Evonik Industries AG anchors European supply chains for specialized cell culture media formulations. NVIDIA Corporation leverages GPU-accelerated computational models to simulate embryonic developmental trajectories. Judges Scientific Plc sustains instrumentation dominance through precision microscopy systems tailored to live-cell ontogenetic observation.
Ontogenetics encompasses the study of developmental processes from fertilization through organogenesis, employing time-lapse imaging, lineage tracing, and molecular profiling to map cell fate decisions across germ layer specification. CRISPR-mediated reporter insertion enables real-time tracking of transcription factor expression with single-cell resolution. Stem cell products command premium positioning due to donor scarcity and GMP compliance burdens, while differentiated cell lines mature into volume-driven commodities. Gene editing applications capture expanding margin pools as pharmaceutical sponsors outsource lineage-validation studies to contract research providers.
FDA's CBER division enforces donor eligibility and tissue safety standards under 21 CFR Part 1271, constraining raw material sourcing for embryonic cell products. REACH registration requirements in Europe impose substance characterization obligations on culture media chemistries, elevating compliance costs for exporters. ISO 10993 biocompatibility protocols govern device-contact applications in tissue engineering, filtering market access for non-validated suppliers. Stakeholders must monitor emerging FDA guidance on gene-edited cell therapies, as draft policies will determine whether autologous ontogenetic products require IND pathways or qualify for streamlined 361 HCT/P exemptions.
Market Dynamics
Academic procurement of high-throughput stem cell platforms is displacing traditional single-laboratory fabrication, concentrating purchasing power among institutional buyers who demand validated, GMP-compliant systems for developmental biology curricula.
Growth Catalysts
- NIH funding concentration:Sustained federal research allocations in the United States create concentrated demand for embryonic and induced pluripotent stem cell systems, with grant mechanisms favoring multi-investigator platform grants over individual R01 awards.
- CRISPR lineage tracing:FDA guidance on gene-edited cell therapies accelerates protocol standardization, reducing validation timelines for contract research providers conducting lineage-validation studies for pharmaceutical sponsors.
- GPU-accelerated simulation:Computational modeling of embryonic developmental trajectories enables in silico screening of teratogenic compounds, compressing preclinical timelines for developmental toxicology assessments.
Market Restraints
- Donor scarcity economics:Embryonic stem cell products face raw material constraints under 21 CFR Part 1271 donor eligibility requirements, elevating unit costs relative to induced pluripotent alternatives.
- REACH compliance burdens:European substance characterization obligations for culture media chemistries impose registration costs on exporters, filtering market access for non-validated suppliers.
- Technical standardization gaps:Absence of harmonized ISO 10993 biocompatibility protocols for device-contact ontogenetic applications creates validation bottlenecks in tissue engineering segments.
Strategic Opportunities
- Autologous therapy pathways:Emerging FDA draft guidance on 361 HCT/P exemptions for gene-edited ontogenetic products may streamline regulatory entry, reducing IND pathway requirements for certain autologous applications.
- Organoid contract manufacturing:Pharmaceutical outsourcing of lineage-validation studies to specialized CROs creates margin expansion in high-complexity gene editing services.
- Live-cell microscopy integration:Precision instrumentation tailored to time-lapse ontogenetic observation enables new service revenue streams in longitudinal developmental tracking.
Industry Challenges
- Cross-functional talent scarcity:Computational developmental biology requires rare hybrid expertise in embryology, bioinformatics, and CRISPR engineering, constraining platform scaling for academic spinouts.
- GMP facility capex intensity:ISO 14644 cleanroom infrastructure for stem cell manufacturing demands capital commitments that exclude mid-scale entrants from embryonic product segments.
- Intellectual property fragmentation:CRISPR licensing complexity across Broad Institute, UC Berkeley, and commercial tool providers creates transaction friction in gene-edited lineage tracing product development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ontogenetic Market |
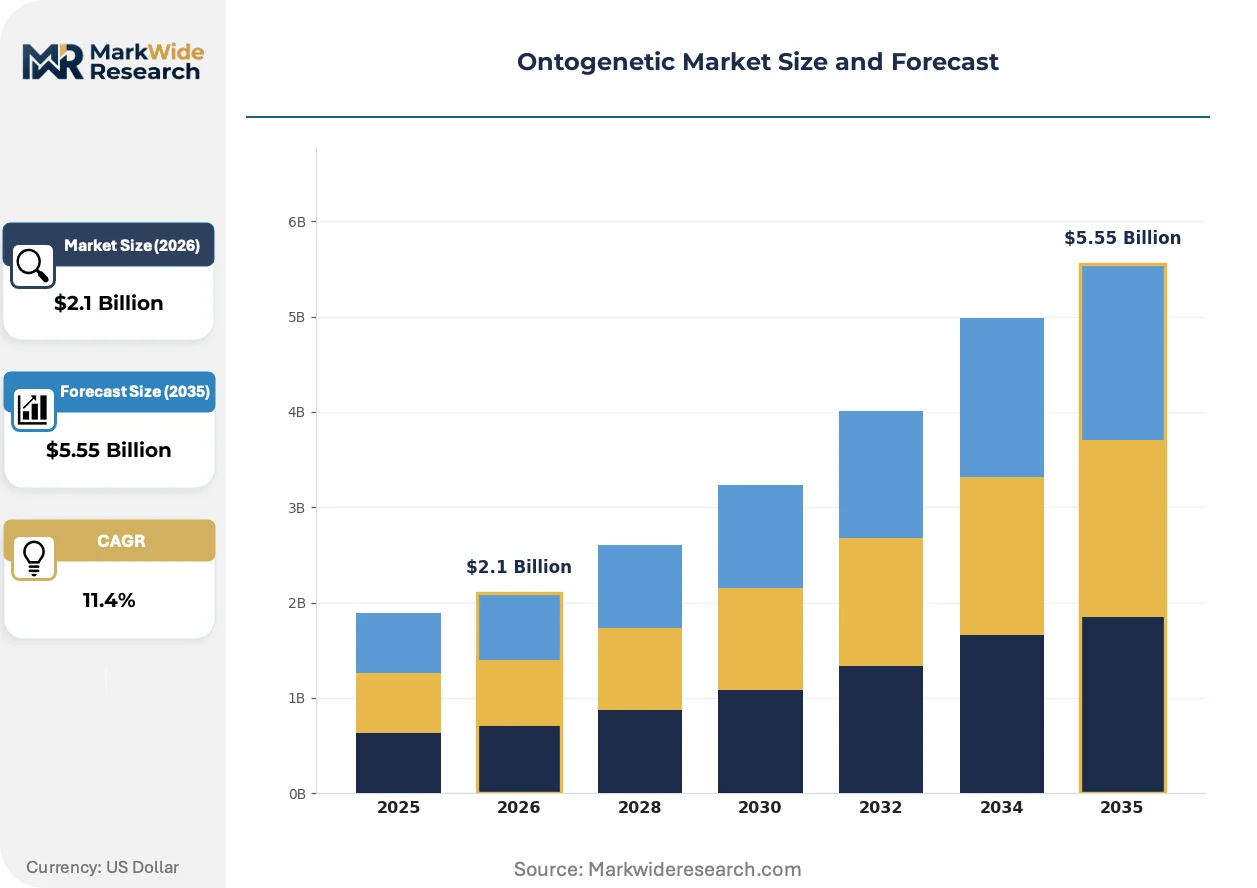
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $5.55 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Embryonic Cells, Stem Cells, Differentiated Cells, Induced Pluripotent Stem Cells Application: Regenerative Medicine, Drug Discovery, Tissue Engineering, Genetic Research End User: Biopharmaceutical Companies, Research Institutions, Clinical Laboratories, Academic Institutes Technology: Cell Culture, Gene Editing, CRISPR, Bioprocessing |
| Companies Covered | EMS Handels Gesellschaft mbH, Ontogeny Inc, Judges Scientific Plc, Evonik Industries AG, Symbiotic Devices, Thorlabs Inc, Natus Medical Incorporated, NVIDIA Corporation, ANT Neuro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ontogenetic Market Evolving Landscape
Time-resolved molecular profiling is compressing developmental biology from static endpoint assays into continuous observation systems, with instrumentation and computational layers converging around single-cell resolution workflows.
Microfluidic organoid culture platforms are miniaturizing embryonic developmental models from macro-scale tissue explants to chip-based systems. Pharmaceutical toxicology groups now adopt these systems at 18-month replacement cycles for teratogenicity screening. This miniaturization is compressing compound testing timelines from weeks to days while reducing donor tissue requirements by orders of magnitude.
EMA's evolving guidance on genetically modified cell-based medicinal products is forcing harmonization between centralized marketing authorization procedures and national tissue establishment oversight. European developers face dual compliance tracks for CRISPR-edited ontogenetic therapies. The induced pluripotent stem cell segment responds by segregating R&D and GMP manufacturing across jurisdictional boundaries to manage regulatory fragmentation.
Consolidated institutional procurement now dominates stem cell platform acquisition, with shared core facilities displacing individual laboratory purchases. Academic medical centers and research institutes aggregate demand through multi-year framework agreements with preferred suppliers. This concentration is most visible in the United States, where NIH-funded institutions leverage volume commitments to extract validation data packages and training services from vendors.
Ontogenetic Market Segmentation
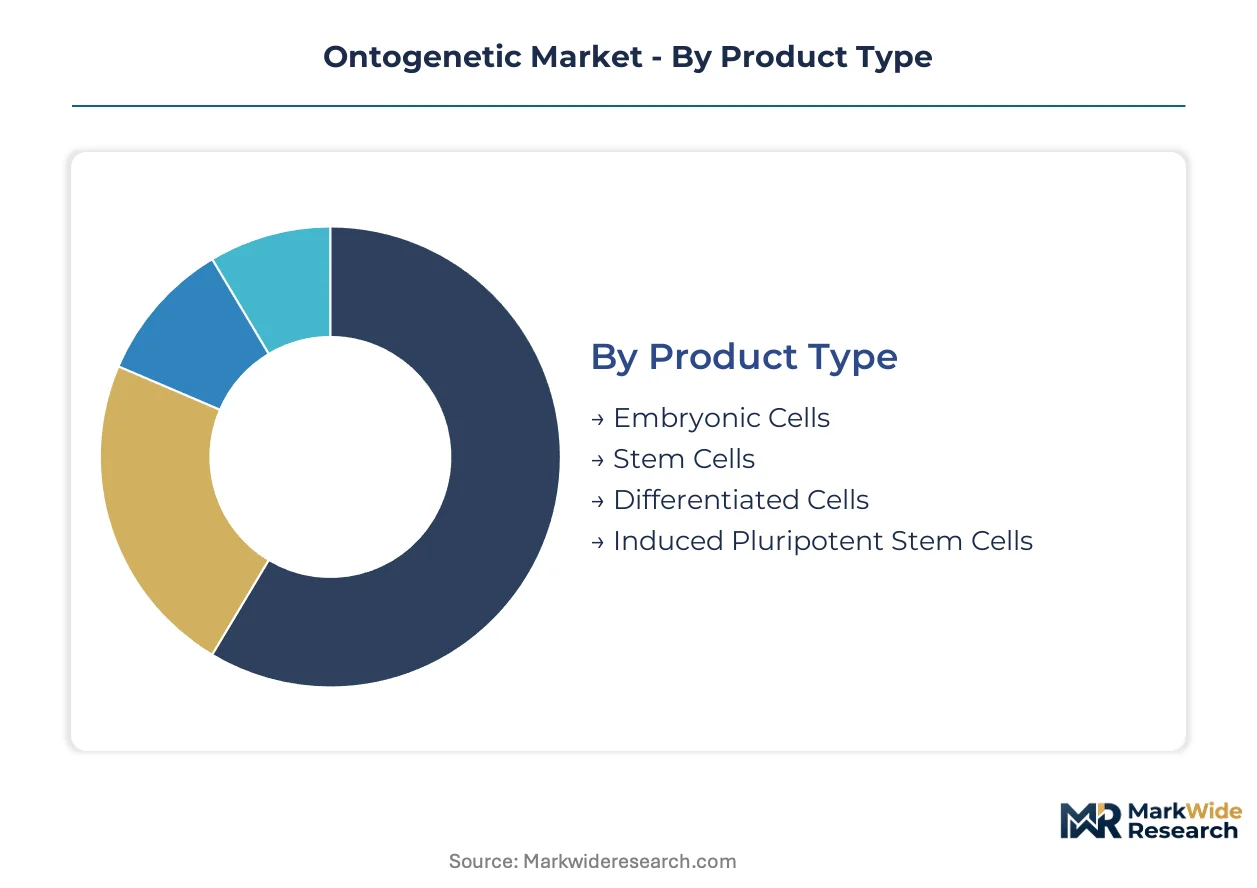
Ontogenetic market segmentation reflects divergent supply chain configurations across cell sourcing modalities and end-use applications. Procurement patterns vary sharply between GMP-compliant therapeutic products and research-grade reagents, creating distinct commercial ecosystems within each category.
Product Type:
Geographic concentration differs markedly across cell sourcing modalities, with embryonic products facing export restrictions under national tissue establishment laws while induced pluripotent alternatives circulate through global distribution networks.
- Embryonic Cells:Primary isolates from blastocyst-stage embryos retain pluripotency benchmarks exceeding reprogrammed alternatives. Procurement concentrates in jurisdictions with permissive oversight frameworks, particularly the United States where NIH funding sustains domestic repository networks and CBER donor eligibility rules constrain import alternatives.
- Induced Pluripotent Stem Cells:Somatic reprogramming eliminates donor tissue dependencies and enables patient-matched autologous sourcing. Japanese and South Korean manufacturing clusters lead commercial supply, leveraging METI and MFDS regulatory pathways that differentiate these products from embryonic equivalents.
- Stem Cells:Umbilical cord and bone marrow derivatives serve hematopoietic reconstruction with established clinical reimbursement codes.
- Differentiated Cells:Lineage-committed populations including cardiomyocytes and hepatocytes command premium positioning in toxicology screening contracts.
Embryonic cells hold the largest share; momentum sits with induced pluripotent stem cells.
Application:
Cost tier stratification separates capital-intensive therapeutic manufacturing from consumable-driven research applications, with tissue engineering occupying the highest per-unit value position.
- Tissue Engineering:Scaffold-integrated cellular constructs for organ replacement require ISO 10993 biocompatibility validation and GMP manufacturing infrastructure. German and Swiss medical device clusters absorb disproportionate volume through TÜV and Swissmedic notified body pathways.
- Drug Discovery:High-throughput screening platforms utilizing patient-derived organoids compress preclinical timelines. Contract research providers in Massachusetts and Cambridge UK capture outsourcing demand from pharmaceutical sponsors seeking teratogenicity data packages.
- Regenerative Medicine:Cell-based therapies face IND pathway requirements in the United States and centralized EMA marketing authorization in Europe.
- Genetic Research:CRISPR-mediated lineage tracing supports fundamental developmental biology with lower regulatory burden than therapeutic applications.
Drug discovery commands the greatest procurement volume; tissue engineering exhibits the steepest expansion trajectory.
End User:
Customer type determines specification intensity, with biopharmaceutical sponsors demanding extensive validation documentation unavailable to academic purchasers.
- Biopharmaceutical Companies:Sponsors outsource lineage-validation studies to contract research organizations with FDA master file access. Multi-year framework agreements predominate, with preferred supplier status contingent on audit-ready quality systems and intellectual property firewalls.
- Academic Institutes:Shared core facilities aggregate demand across multiple investigator laboratories, extracting training services and validation data packages through volume commitments. California and Massachusetts research clusters lead procurement concentration.
- Research Institutions:Government laboratories and independent research organizations operate under public procurement rules with extended tender cycles.
- Clinical Laboratories:Diagnostic applications require CLIA certification in the United States and ISO 15189 accreditation in Europe.
Biopharmaceutical companies represent the dominant revenue source; academic institutes are gaining share fastest through consolidated procurement.
Technology:
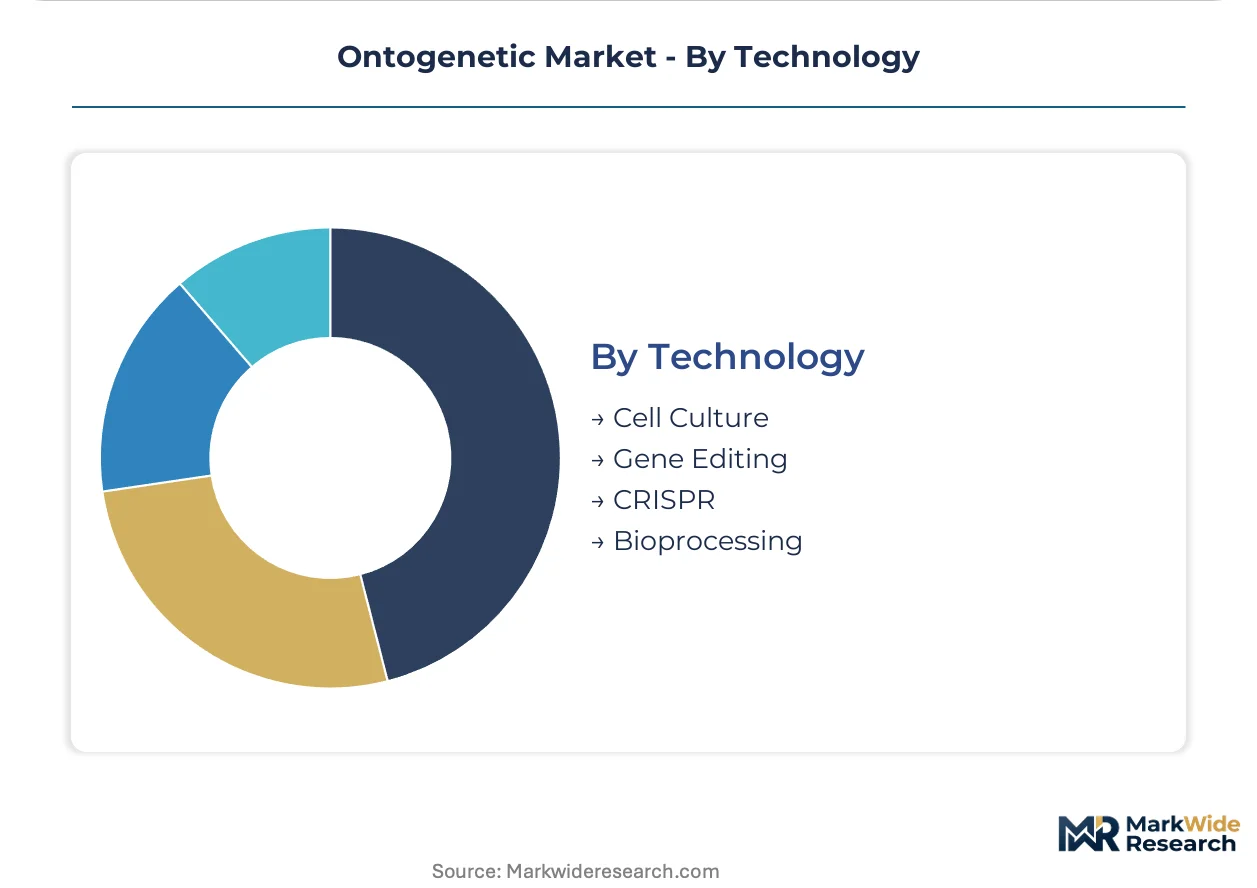
Supply concentration clusters around instrumentation vendors with integrated workflow portfolios versus specialized reagent providers serving modular research environments.
- Gene Editing:CRISPR-mediated reporter insertion and base editing enable real-time transcription factor tracking with single-cell resolution. Licensing complexity across Broad Institute, UC Berkeley, and commercial tool providers creates transaction friction in product development.
- Cell Culture:Specialized media formulations from European chemical suppliers anchor supply chains, with REACH registration requirements elevating compliance costs for exporters.
- CRISPR:Guide RNA design and delivery optimization services support lineage tracing protocol standardization under emerging FDA guidance.
- Bioprocessing:Scalable manufacturing platforms for clinical-grade cell products require ISO 14644 cleanroom infrastructure and automated closed-system operation.
Cell culture retains the broadest installed base; gene editing demonstrates the most rapid capability expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized cell culture media supply chains concentrate in European chemical manufacturing clusters, while CRISPR-based lineage tracing protocol development gravitates toward NIH-funded research corridors in the United States.
United States
NIH multi-investigator platform grants and CBER donor eligibility rules under 21 CFR Part 1271 concentrate embryonic stem cell procurement in federally funded institutions. Massachusetts and California research clusters absorb disproportionate volume through shared core facility models that extract validation data packages from preferred vendors.
Germany
TÜV and Swissmedic notified body pathways for ISO 10993 biocompatibility validation anchor tissue engineering demand in German medical device clusters. REACH substance characterization obligations elevate compliance costs for culture media exporters, filtering market access for non-validated chemical suppliers.
Japan
METI regulatory pathways differentiate induced pluripotent stem cells from embryonic equivalents, enabling patient-matched autologous sourcing without donor tissue constraints. Commercial manufacturing clusters in the Kanto region leverage MFDS-aligned quality systems to serve Asia-Pacific pharmaceutical outsourcing contracts.
United Kingdom
Cambridge contract research providers capture lineage-validation study demand from pharmaceutical sponsors seeking teratogenicity data packages. Academic medical centers aggregate procurement through multi-year framework agreements that prioritize GMP-compliant systems over research-grade alternatives.
South Korea
MFDS regulatory differentiation of reprogrammed cell products enables global distribution networks unconstrained by national tissue establishment laws. Manufacturing clusters near Seoul supply differentiated cardiomyocyte and hepatocyte lines to toxicology screening contracts in North American and European markets.
Ontogenetic Market Competitive Landscape
Concentration sits with diversified chemical conglomerates and precision instrumentation specialists rather than pure-play cell therapy developers. The vendor base separates into three tiers: European chemical suppliers anchoring media formulation supply chains, GPU-accelerated computational platform providers enabling in silico developmental modeling, and microscopy instrumentation houses serving live-cell observation workflows. Dominant competitive moves include strategic partnerships between reagent suppliers and pharmaceutical sponsors for lineage-validation outsourcing, plus capacity expansion in ISO 14644 cleanroom infrastructure for clinical-grade manufacturing.
Among diversified chemical conglomerates, Evonik Industries AG occupies a position exemplifying European supply chain anchoring for specialized formulations. Precision instrumentation specialists include Judges Scientific Plc, representing microscopy systems tailored to longitudinal developmental tracking, and NVIDIA Corporation, sitting within the computational simulation tier through GPU-accelerated embryonic trajectory modeling. These three anchors span the critical supply chain nodes from raw material chemistry through observational hardware to predictive software layers.
| Leading Market Players |
|---|
| EMS Handels Gesellschaft mbH |
| Ontogeny Inc |
| Judges Scientific Plc |
| Evonik Industries AG |
| Symbiotic Devices |
| Thorlabs Inc |
| Natus Medical Incorporated |
| NVIDIA Corporation |
| ANT Neuro |
| Others |
Value Network & Pricing Analysis
21 CFR Part 1271 donor eligibility requirements simultaneously gate supply qualification for embryonic stem cell products and enforce sharp price differentiation between GMP-compliant therapeutic tiers and research-grade alternatives. CBER oversight creates a dual-track market where validated suppliers command substantial premiums over non-certified competitors.
Pricing Analysis
FDA's 21 CFR Part 1271 dictates the pricing tier structure across embryonic and induced pluripotent stem cell segments, separating premium GMP-certified products from standard research-grade alternatives. Price differentiation rests on ISO 10993 biocompatibility validation status and REACH registration completeness for culture media formulations. Cost compression in research-grade consumables is intensifying because academic core facilities aggregate procurement through multi-year framework agreements. Biopharmaceutical sponsors demonstrate the lowest price sensitivity due to IND pathway requirements, while academic institutes extract maximum concessions through volume commitments.
Supply Chain Analysis
Container availability constraints on trans-Pacific trade lanes elevate inbound logistics costs for European culture media suppliers serving United States research clusters. Raw material concentration centers on Germany and Switzerland for specialized chemical formulations, with South Korean and Japanese manufacturing clusters dominating induced pluripotent stem cell production. Supply chains draw from blastocyst-stage embryo repositories, recombinant protein growth factors, and ISO 14644-compliant cleanroom infrastructure components. Single-source vulnerability characterizes CRISPR reagent licensing, where Broad Institute and UC Berkeley patent thickets create transaction friction. Distribution runs through institutional procurement officers at academic medical centers rather than individual laboratory purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ontogenetic market fragmentation creates multiple entry niches as consolidated academic procurement displaces single-laboratory fabrication models. Demand-side concentration among NIH-funded institutions generates specialized service gaps that agile entrants can exploit.
For Market Incumbents: Fortify GMP facility networks against emerging autologous therapy competitors by expanding ISO 14644 cleanroom capacity in Massachusetts and California research corridors. Defend against CRISPR licensing fragmentation by securing preferred supplier status through multi-year framework agreements with academic core facilities. Backward integration into specialized media formulation chemistry reduces exposure to REACH compliance cost escalation.
For New Entrants and Emerging Players: Organoid contract manufacturing services represent the most penetrable white-space segment, as pharmaceutical sponsors outsource lineage-validation studies to avoid in-house GMP infrastructure investments. Target academic spinouts lacking computational developmental biology expertise by offering integrated GPU-accelerated simulation platforms bundled with stem cell products. A service-first go-to-market angle emphasizing training and validation data packages differentiates against incumbent hardware vendors.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed contract research organizations possessing FDA master file access but limited bioprocessing scale. Long-term viability hinges on regulatory pathway clarity for gene-edited autologous products over the next decade. Watch for draft FDA guidance on 361 HCT/P exemptions as the critical inflection signal determining whether IND pathway requirements expand or contract for CRISPR-edited ontogenetic therapies.
| Strategic Initiative | Industry Significance |
|---|---|
| GMP Manufacturing Scale-Up | ISO 14644 cleanroom expansion in California and Massachusetts clusters captures NIH-funded academic procurement concentration. |
| CRISPR Licensing Agreement | Patent access from Broad Institute or UC Berkeley clears transaction friction for lineage-tracing product development pipelines. |
| Organoid Contract Manufacturing Partnership | Pharmaceutical outsourcing of teratogenicity screening compresses preclinical timelines while generating recurring revenue streams. |
| GPU-Accelerated Platform Integration | NVIDIA partnership enables in silico developmental modeling that differentiates hardware offerings against traditional microscopy vendors. |
| REACH-Compliant Media Formulation Backward Integration | European chemical manufacturing captive supply reduces export compliance burdens and secures raw material cost stability. |
Research Methodology
Initial hypotheses were tested against primary input from stem cell platform procurement officers, GMP facility operations directors, CRISPR protocol development scientists, and pharmaceutical outsourcing managers, then refined through secondary validation against FDA 510(k) filings, NIH RePORTER grant databases, EMA centralized marketing authorization procedures, and ISO 10993 biocompatibility test registries. Bottom-up demand modeling from individual academic medical center procurement records was triangulated against top-down supply-side capacity assessments from European chemical manufacturers and Asian cell banking facilities.
Variance decomposition across the projection horizon isolates volume drivers from price effects within each segmentation dimension: cell sourcing modality, application area, end-user type, and technology layer. CAGRs were derived from segment-level growth rate convergence analysis incorporating induced pluripotent stem cell reprogramming efficiency improvements, microfluidic organoid adoption cycles in toxicology screening, and evolving FDA guidance timelines for gene-edited cell therapy pathways.
Material uncertainties — regulatory pathway revisions for autologous ontogenetic products, CRISPR patent landscape litigation outcomes, and NIH funding allocation shifts — sit outside the modeled envelope. Forecasts reflect documented assumptions about protocol standardization velocity and institutional procurement consolidation trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Oligonucleotide Synthesis Market
Biomedical Technology
Structural Biology and Molecular Modeling Techniques Market
Biomedical Technology
Global Cell Dissociation Market
Biomedical Technology
Global Cell Counting Market
Biomedical Technology
Multiplex Biomarker Imaging Market
Biomedical Technology
Subcutaneous Biologics Market
Biomedical Technology
Bioadhesive Microspheres Market
Biomedical Technology
Global Stem Cell Assay Market
Biomedical Technology
Glycomics Market
Biomedical Technology
Cell Cycle Analysis Market
Biomedical Technology
Digital Biology Market
Biomedical Technology
Global Biological Stains Market
Biomedical Technology
High-End Cellomics Market
Biomedical Technology
3D Cell Culture Market
Biomedical Technology
DNA Synthesis Market
Biomedical Technology
Global Biosimulation Market