
 US Liquid Biopsy Market | 2026-2036
US Liquid Biopsy Market Size, Share, and Industry Trends Forecast 2026-2036
US Liquid Biopsy Market Insights
Consolidation among large hospital systems and integrated delivery networks is repositioning purchasing power toward centralized laboratory procurement. Guardant Health Inc. anchors its position through comprehensive genomic profiling services tied to major cancer centers. Foundation Medicine Inc. differentiates via FDA-approved companion diagnostic platforms that span multiple tumor types. Thermo Fisher Scientific Inc. leverages its scale in sequencing instrumentation to supply both clinical and research workflows.
Liquid biopsy analyzes circulating biomarkers—primarily cell-free DNA, circulating tumor cells, and exosomes—isolated from peripheral blood samples using specialized collection tubes and density-gradient or immunomagnetic separation protocols, enabling non-invasive cancer detection and molecular monitoring. Cell-free DNA dominates current clinical volume due to established analytical validity in tracking minimal residual disease and treatment response. Next-generation sequencing competes with digital droplet PCR for analytical sensitivity, while microfluidics platforms gain traction in point-of-care configurations where rapid turnaround matters.
FDA oversight of in vitro diagnostics and companion test approvals, combined with CMS national coverage determinations for circulating tumor DNA in solid tumors, shape reimbursement access and clinical adoption thresholds. State laboratory licensing requirements under CLIA and CAP accreditation standards further constrain which facilities can offer high-complexity molecular testing. Stakeholders must track evolving FDA guidance on analytical validation standards for multi-cancer early detection assays as the agency weighs benefit-risk frameworks for screening applications.
Market Dynamics
FDA breakthrough device designations and CMS national coverage determinations for circulating tumor DNA assays are compressing the validation-to-reimbursement cycle, forcing laboratories to build companion diagnostic infrastructure ahead of full clinical utility data.
Growth Catalysts
- Oncology department expansion:Major hospital networks in California, Massachusetts, and Texas are embedding liquid biopsy protocols into routine cancer care workflows, creating institutional demand pull.
- CLIA high-complexity laboratory licensing:CAP accreditation standards validate analytical performance, enabling accredited facilities to bill Medicare for ctDNA testing services.
- Minimal residual disease tracking:Cell-free DNA analytical validity in post-treatment monitoring is displacing invasive tissue biopsies for recurrence surveillance.
Market Restraints
- Sequencing reagent cost volatility:Proprietary consumable lock-in from dominant platform vendors constrains laboratory margin flexibility.
- Multi-cancer early detection validation gaps:FDA benefit-risk frameworks for screening applications remain unresolved, delaying assay commercialization timelines.
- Digital PCR substitution threat:Lower-cost digital droplet PCR platforms compete for mutation detection applications where single-gene sensitivity suffices.
Strategic Opportunities
- Point-of-care microfluidics:Rapid turnaround configurations target community oncology practices outside academic medical center catchments.
- Integrated delivery network procurement centralization:Hospital system consolidation creates volume aggregation opportunities for comprehensive genomic profiling contracts.
- Exosome isolation technology convergence:Combining immunomagnetic separation with next-generation sequencing opens proteomic-mutational co-detection applications.
Industry Challenges
- Bioinformatics pipeline validation:Variant calling algorithm standardization across CLIA laboratories lacks inter-laboratory proficiency testing mandates.
- Pre-analytical sample integrity:Specialized collection tube supply chain dependencies create specimen quality variability risks during transport.
- EHR integration complexity:Molecular results reporting into legacy electronic health record systems requires custom interface development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Liquid Biopsy Market |
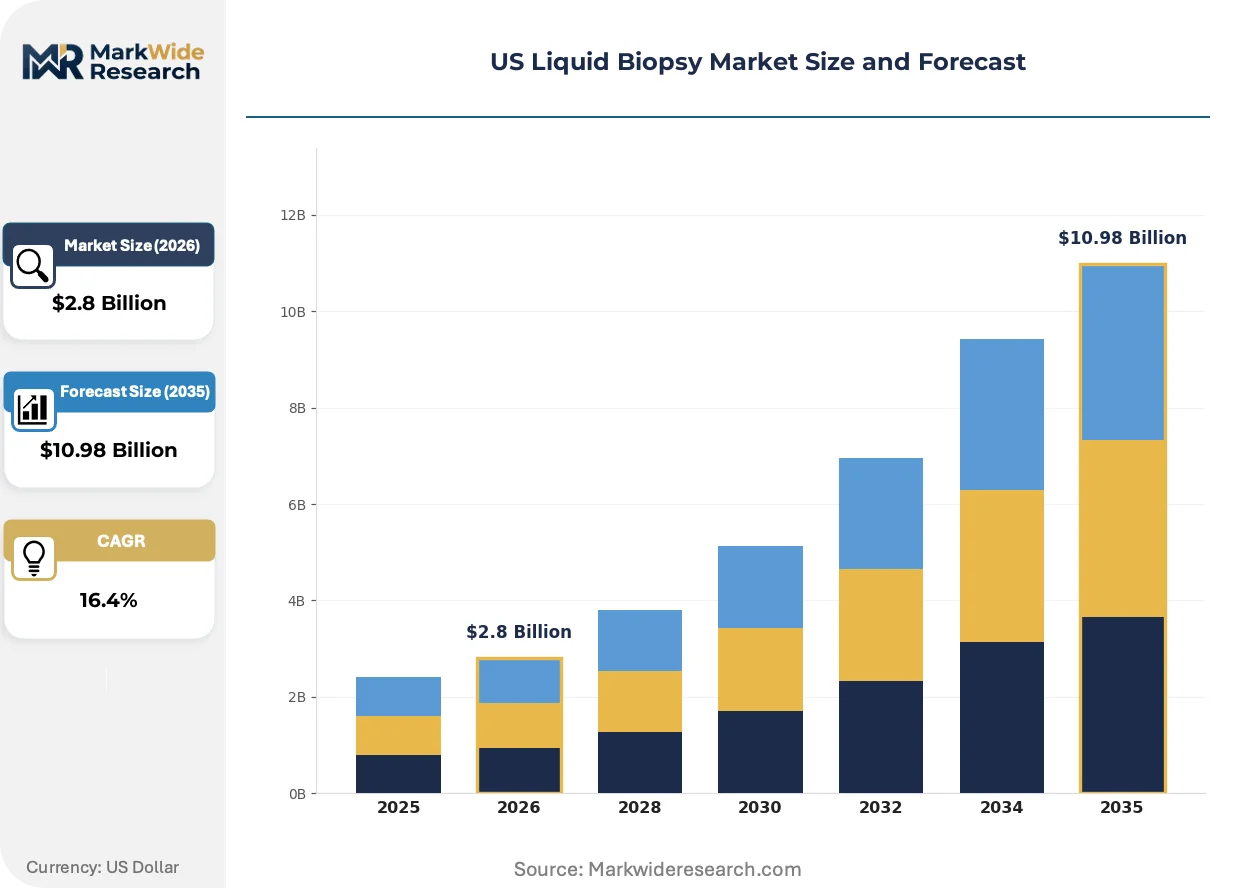
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $10.98 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Circulating Tumor Cells, Cell-Free DNA, Exosomes, Circulating RNA Technology: Next-Generation Sequencing, PCR, Microfluidics, Digital Droplet PCR Application: Cancer Diagnosis, Treatment Monitoring, Prognosis, Recurrence Prediction End User: Hospitals, Academic Research, Diagnostic Laboratories, Pharmaceutical Companies |
| Companies Covered | Guardant Health Inc., Foundation Medicine Inc., Natera Inc., Illumina Inc., Thermo Fisher Scientific Inc., F. Hoffmann-La Roche AG, QIAGEN N.V., Exact Sciences Corporation, Myriad Genetics Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Liquid Biopsy Market Trends and Innovations
Next-generation sequencing instrumentation and regulatory science are converging to compress assay development timelines while expanding reimbursable indications beyond late-stage cancer monitoring.
Cell-free DNA multi-cancer early detection is consolidating the screening landscape. Academic medical centers in Texas and Massachusetts are piloting population-scale protocols ahead of FDA screening indication approvals. The technology is consolidating vendor competition around end-to-end platform ecosystems rather than discrete test menus.
CMS national coverage determinations for circulating tumor DNA in solid tumors are reshaping laboratory reimbursement access. The policy creates immediate volume eligibility for Medicare beneficiaries while pressuring commercial payers toward parity. Community oncology practices in California are restructuring prior authorization workflows to capture this expanded access.
Hospital system procurement centralization is displacing decentralized laboratory purchasing. Integrated delivery networks in Massachusetts and Texas are consolidating molecular testing contracts under single-source comprehensive genomic profiling agreements. This concentration is most visible in precision medicine hubs where academic medical center influence shapes vendor selection criteria.
US Liquid Biopsy Market Segmentation
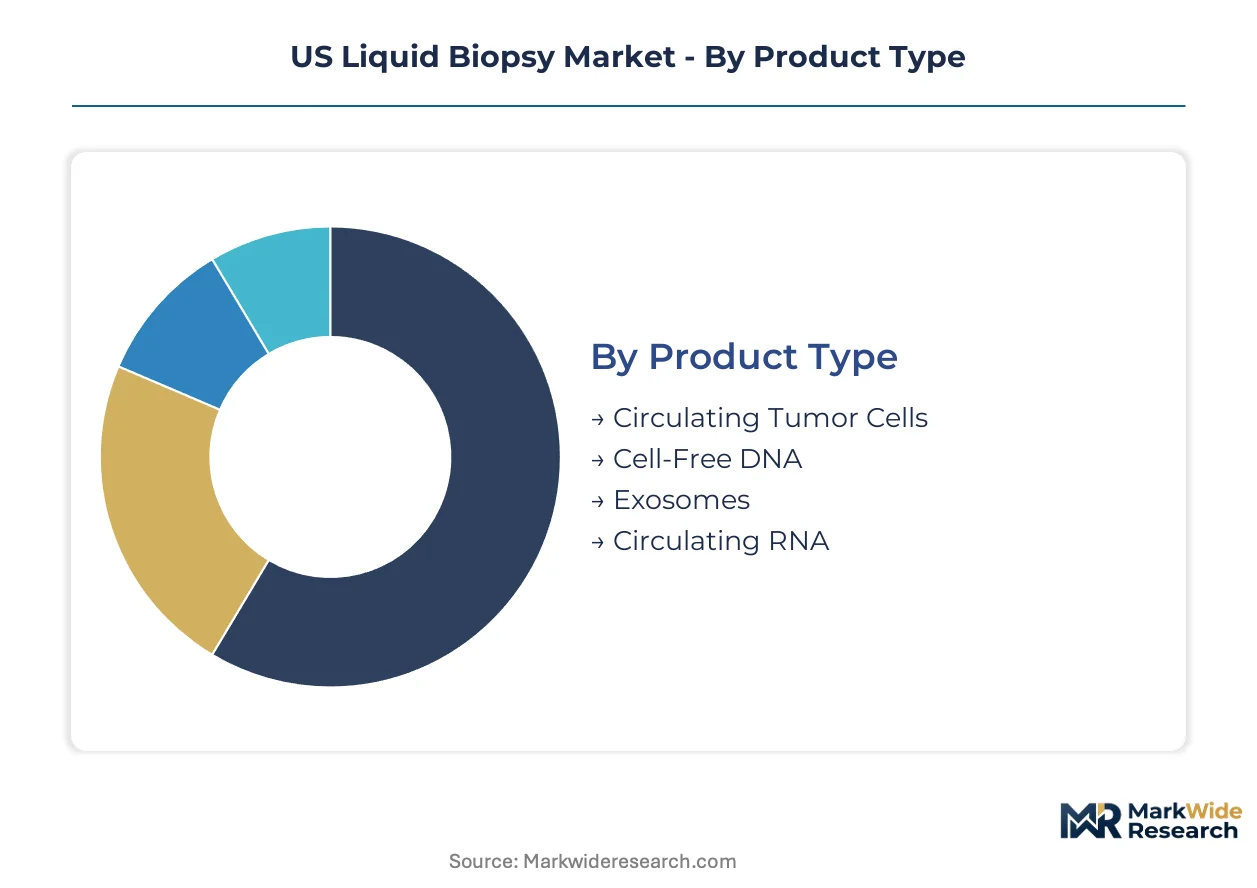
Liquid biopsy segmentation reveals how technology maturity, reimbursement pathways, and clinical workflow integration create divergent commercial trajectories across biomarker classes and analytical platforms. Understanding these divisions exposes where procurement power concentrates and which configurations face substitution threats.
Product Type:
Biomarker selection differentiates laboratories by analytical validity depth and Medicare billing eligibility.
- Cell-Free DNA:Fragmented tumor-derived nucleic acids in plasma enable minimal residual disease tracking with established CLIA validation protocols. Major cancer centers in California and Massachusetts prioritize ctDNA for post-treatment surveillance, displacing invasive tissue biopsies where sensitivity thresholds meet clinical utility requirements.
- Circulating Tumor Cells:Intact viable tumor cells isolated through immunomagnetic separation provide functional characterization beyond genotyping. Academic medical centers in Texas leverage CTC enumeration for drug response prediction, though technical complexity constrains community laboratory adoption.
- Exosomes:Membrane-bound extracellular vesicles carry proteomic and nucleic acid cargo for multi-omic co-detection.
- Circulating RNA:Transcriptomic signatures in blood reflect real-time gene expression dynamics with shorter half-lives than DNA.
Cell-free DNA leads volumes today; exosome isolation is gaining share fastest.
Technology:
Platform economics separate high-throughput reference laboratories from point-of-care configurations.
- Next-Generation Sequencing:Massively parallel sequencing of circulating nucleic acids delivers comprehensive genomic profiling across multiple alteration classes simultaneously. Foundation Medicine and Guardant Health anchor comprehensive genomic profiling contracts with integrated delivery networks, though reagent cost volatility pressures laboratory margins.
- Digital Droplet PCR:Partitioned amplification achieves single-molecule sensitivity for known hotspot mutations at lower per-sample cost. Community oncology practices in Texas adopt ddPCR for single-gene monitoring where NGS breadth exceeds clinical necessity.
- PCR:Conventional amplification remains cost-effective for high-volume, single-target applications with established primer designs.
- Microfluidics:Lab-on-chip architectures enable rapid turnaround in decentralized settings outside academic medical center catchments.
NGS commands the premium contract tier; microfluidics platforms are expanding most quickly into community settings.
Application:
Clinical use case determines reimbursement pathway and regulatory scrutiny intensity.
- Treatment Monitoring:Serial ctDNA quantification tracks therapeutic response and emergent resistance mechanisms in real time. CMS national coverage determinations for circulating tumor DNA in solid tumors created immediate Medicare eligibility, restructuring prior authorization workflows at hospital networks in California.
- Cancer Diagnosis:Initial malignancy detection through blood-based biomarker profiling requires higher analytical specificity to avoid false-positive cascades. FDA benefit-risk frameworks for multi-cancer early detection screening applications remain unresolved, delaying commercialization timelines for asymptomatic population testing.
- Prognosis:Baseline biomarker levels stratify patient risk categories to guide intensity of therapeutic intervention.
- Recurrence Prediction:Post-treatment surveillance protocols identify molecular relapse before radiographic evidence appears.
Treatment monitoring anchors current reimbursement; cancer diagnosis shows the steepest expansion trajectory pending screening indication approvals.
End User:
Procurement centralization across integrated delivery networks reconfigures vendor access patterns.
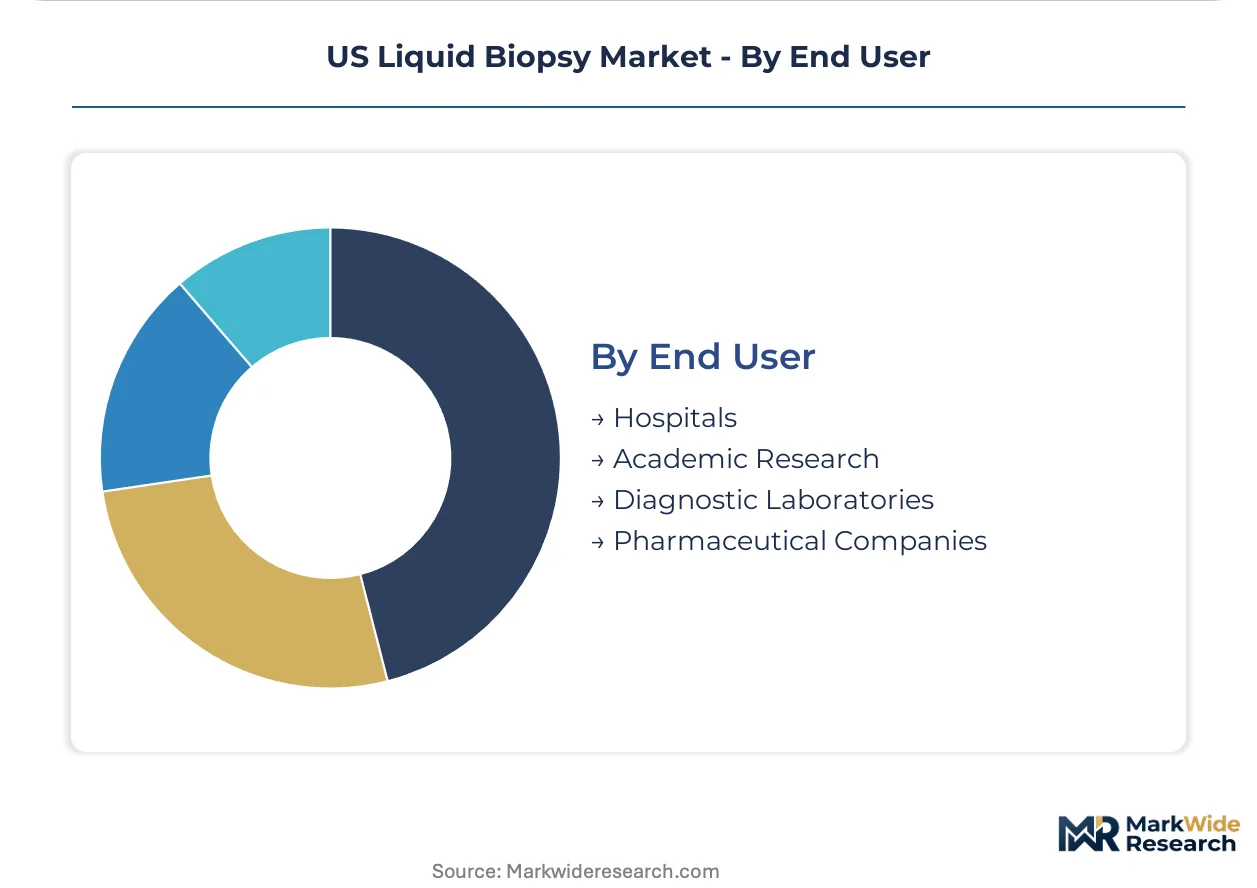
- Hospitals:Oncology departments at major hospital networks in Massachusetts and Texas embed liquid biopsy protocols into routine care workflows, creating institutional demand pull through standardized order sets and EHR-integrated result reporting.
- Diagnostic Laboratories:CLIA high-complexity facilities with CAP accreditation bill Medicare directly for ctDNA testing services, competing with hospital outreach laboratories for comprehensive genomic profiling contracts.
- Academic Research:University-affiliated medical centers pilot population-scale protocols ahead of FDA screening indication approvals.
- Pharmaceutical Companies:Drug developers utilize circulating biomarkers for patient stratification and companion diagnostic co-development.
Hospital systems lead procurement volumes today; diagnostic laboratories are climbing the fastest as centralized laboratory contracts displace decentralized purchasing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Massachusetts concentrates precision medicine infrastructure more densely than Texas, yet both states anchor distinct commercialization pathways for circulating tumor DNA assays. California's biotech corridor generates disproportionate early adoption volume for multi-cancer early detection pilots.
California
Academic medical centers in San Francisco and San Diego drive institutional demand for comprehensive genomic profiling services. FDA breakthrough device designations for circulating tumor DNA tests accelerate clinical validation timelines at Stanford and UCSF. The Bay Area biotech corridor clusters sequencing instrumentation vendors and specialized collection tube manufacturers within a fifty-mile radius.
Massachusetts
Harvard-affiliated hospital networks embed liquid biopsy protocols into standardized oncology order sets. CMS national coverage determinations for ctDNA testing enable immediate Medicare billing at Dana-Farber and Mass General Brigham. The Cambridge-Boston corridor concentrates companion diagnostic co-development activity between pharmaceutical developers and CLIA-accredited laboratories.
Texas
MD Anderson Cancer Center pilots population-scale minimal residual disease surveillance protocols for post-treatment monitoring. State laboratory licensing under CLIA high-complexity standards validates analytical performance for community laboratory expansion. The Houston medical center district anchors the Southwest's largest concentration of CAP-accredited molecular testing facilities.
New York
Memorial Sloan Kettering and NYU Langone compete for integrated delivery network procurement contracts across the Northeast corridor. New York State Department of Health laboratory permitting requirements constrain which facilities may offer circulating tumor cell enumeration services. The New York City metro area attracts venture financing for microfluidics platform development targeting point-of-care configurations.
Illinois
Northwestern Medicine and University of Chicago Medicine consolidate molecular testing contracts under single-source comprehensive genomic profiling agreements. Illinois state Medicaid reimbursement policies for liquid biopsy lag Medicare national coverage determinations, creating access disparities. The Chicago metro serves as a distribution hub for specialized blood collection tube supply chains serving Midwestern hospital networks.
US Liquid Biopsy Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across instrumentation, consumables, and testing services. Thermo Fisher Scientific and Illumina anchor the diversified tier through sequencing platform ecosystems, while Guardant Health and Foundation Medicine occupy specialized testing service positions. Three archetypes define competitive positioning: platform-integrated conglomerates, comprehensive genomic profiling laboratories, and point-of-care microfluidics developers. M&A activity concentrates on companion diagnostic infrastructure, while strategic partnerships target EHR integration capabilities.
Among pure-play testing specialists, Guardant Health Inc., Foundation Medicine Inc., and Natera Inc. exemplify the comprehensive genomic profiling archetype. Guardant Health anchors its position through major cancer center relationships. Foundation Medicine represents the FDA-approved companion diagnostic platform model spanning multiple tumor types. Natera Inc. occupies a distinct position in minimal residual disease surveillance applications. These three companies illustrate how testing service specialization creates procurement leverage against diversified instrumentation vendors in consolidated hospital system purchasing environments.
| Leading Market Players |
|---|
| Guardant Health Inc. |
| Foundation Medicine Inc. |
| Natera Inc. |
| Illumina Inc. |
| Thermo Fisher Scientific Inc. |
| F. Hoffmann-La Roche AG |
| QIAGEN N.V. |
| Exact Sciences Corporation |
| Myriad Genetics Inc. |
| Others |
Pricing and Supply Chain Analysis
Sequencing reagent price indices cascade through the liquid biopsy supply chain into three-tier pricing structures across premium, standard, and economy levels. California and Massachusetts academic medical centers absorb premium comprehensive genomic profiling rates, while Texas community laboratories gravitate toward lower-cost digital droplet PCR configurations.
Pricing Analysis
Capacity additions in Texas and California are reshaping price floors for cell-free DNA testing services. The dominant pricing model operates on per-sample transactional billing with volume-tiered discounts for integrated delivery network contracts. Price differentiation hinges on CAP accreditation status and FDA companion diagnostic approval tier, with Medicare-reimbursed hospital laboratories commanding premium positioning. Pricing pressure stems from digital PCR substitution in single-gene monitoring applications, squeezing margins for mid-tier NGS providers. Community oncology practices in Texas exhibit highest price sensitivity, while Harvard-affiliated hospital networks in Massachusetts demonstrate lowest sensitivity due to bundled EHR-integrated contracts.
Supply Chain Analysis
Direct-to-hospital laboratory channels handle high-complexity molecular testing demand from integrated delivery networks. Geographic supply concentration centers on the United States for CLIA-accredited reference laboratories, with specialized collection tube manufacturing clustered in California and Illinois. Raw material dependencies include proprietary sequencing reagents from Illumina and Thermo Fisher Scientific, immunomagnetic separation beads, and stabilized blood collection media. Supply chain risk manifests as single-source vulnerability for NGS platform consumables, constraining laboratory margin flexibility. Distribution runs through regional laboratory service agreements with hospital system procurement centralization displacing decentralized purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
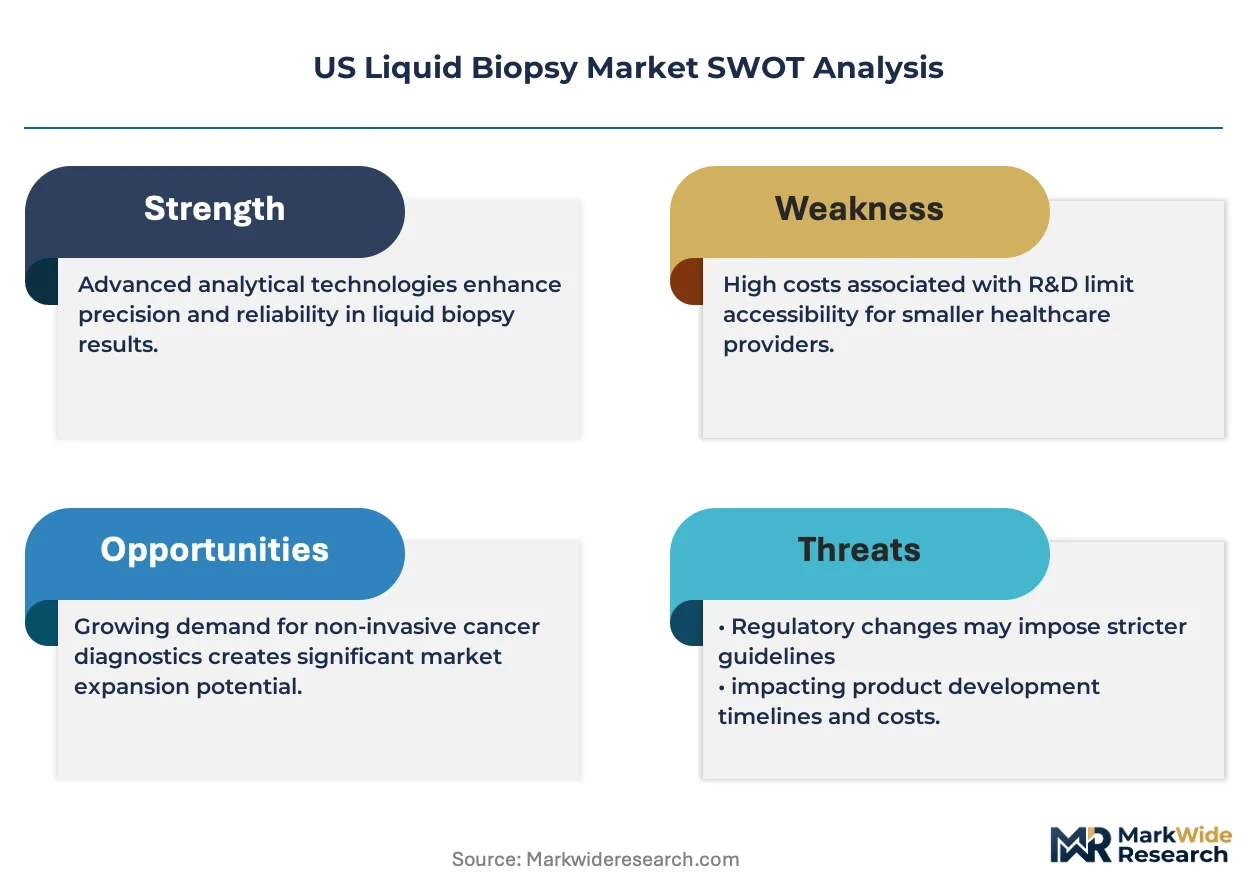
The US liquid biopsy market represents a late-cycle quality story where demand is gravitating toward FDA-approved companion diagnostic platforms with demonstrated analytical validity in minimal residual disease tracking.
For Market Incumbents: Anchor comprehensive genomic profiling contracts through EHR integration investments that lock in hospital system procurement centralization. Defend against digital PCR substitution by expanding mutation panel breadth beyond single-gene sensitivity thresholds. Prioritize CAP accreditation maintenance and FDA breakthrough device designation pursuit to sustain Medicare reimbursement access. Build companion diagnostic infrastructure ahead of multi-cancer early detection screening approvals to capture population-scale protocol pilots.
For New Entrants and Emerging Players: Telehealth-integrated direct-to-consumer channels offer lower customer acquisition costs for asymptomatic screening applications outside academic medical center catchments. Target community oncology practices in Texas and Illinois where prior authorization workflow restructuring creates access gaps. Pursue point-of-care microfluidics development for rapid turnaround configurations in decentralized settings. Emphasize exosome isolation technology convergence for proteomic-mutational co-detection differentiation.
For Investors and Strategic Acquirers: Asymmetric upside sits with CLIA-accredited laboratories possessing FDA-approved companion diagnostic platforms across multiple tumor types. Long-term viability over the projection horizon favors testing service specialists with integrated delivery network contract concentration over pure instrumentation vendors. Acquisition target archetype: mid-scale comprehensive genomic profiling laboratories with Massachusetts or Texas hospital system relationships. Monitor CMS national coverage determination expansions beyond solid tumors as inflection indicator for screening application commercialization timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerates clinical validation timelines at Stanford and MD Anderson Cancer Center. |
| CMS National Coverage Determination Expansion | Creates immediate Medicare eligibility for circulating tumor DNA testing services. |
| Hospital System Partnership | Mass General Brigham and Dana-Farber embed liquid biopsy into standardized order sets. |
| Software Companion Development | Enables EHR-integrated result reporting for comprehensive genomic profiling contracts. |
| Reimbursement Strategy | Prior authorization workflow restructuring captures expanded CMS access in California. |
Research Methodology
Direct dialogue with oncology department heads, CLIA laboratory directors, hospital procurement managers, and payer access specialists informed primary intelligence gathering. Secondary validation drew from FDA 510(k) filings, CMS national coverage determination documents, CAP proficiency testing records, and hospital GPO contract databases. Bottom-up testing volume estimates triangulated against top-down market sizing from sequencing instrumentation shipment data and Medicare billing code utilization.
Bottom-up modeling aggregated procedure volumes by biomarker class, technology platform, and end-user segment across the analysis window. Segmentation dimensions included cell-free DNA versus circulating tumor cell versus exosome biomarker type, NGS versus digital PCR versus microfluidics technology, and hospital versus diagnostic laboratory versus academic research end use. CAGRs derived from logistic diffusion curves fitted to reimbursement policy adoption timelines and companion diagnostic approval trajectories. Forecast inputs incorporated CLIA laboratory licensing expansion rates and FDA analytical validation guidance evolution.
The model assumes a particular technology adoption path; alternative pathways for multi-cancer early detection screening would alter the outlook if FDA benefit-risk frameworks resolve favorably ahead of base case assumptions. Forecasts reflect documented assumptions regarding CMS coverage expansion sequencing and integrated delivery network procurement centralization velocity. Regulatory delays in multi-cancer early detection validation or sequencing reagent supply disruptions would necessitate forecast revision. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Orthobiological Products Market
Biomedical Technology
Global Biomarker Technologies Market
Biomedical Technology
Global Transcriptomics Market
Biomedical Technology
Europe Transfection Technologies Market
Biomedical Technology
Brain Biomarkers Market
Biomedical Technology
Strand Displacement Amplicon (SDA) Market
Biomedical Technology
Live Cell Analysis System Market
Biomedical Technology
Human Reproductive Technologies Market
Biomedical Technology
Global Nicotinamide Adenine Dinucleotide (NAD) Market
Biomedical Technology
Cell Cryopreservation Market
Biomedical Technology
In-Vitro Transcription Templates Market
Biomedical Technology
Vaccine Technology Market
Biomedical Technology
Ocular Drug Delivery Technology Market
Biomedical Technology
Proteomics Market
Biomedical Technology
Rare Biomarkers Specimen Collection and Stabilization Market
Biomedical Technology
Custom Nucleic Acid Market