
 Video Projector Market | 2026-2036
Video Projector Market Size, Share, and Industry Trends Forecast 2026-2036
Video Projector Market Analysis
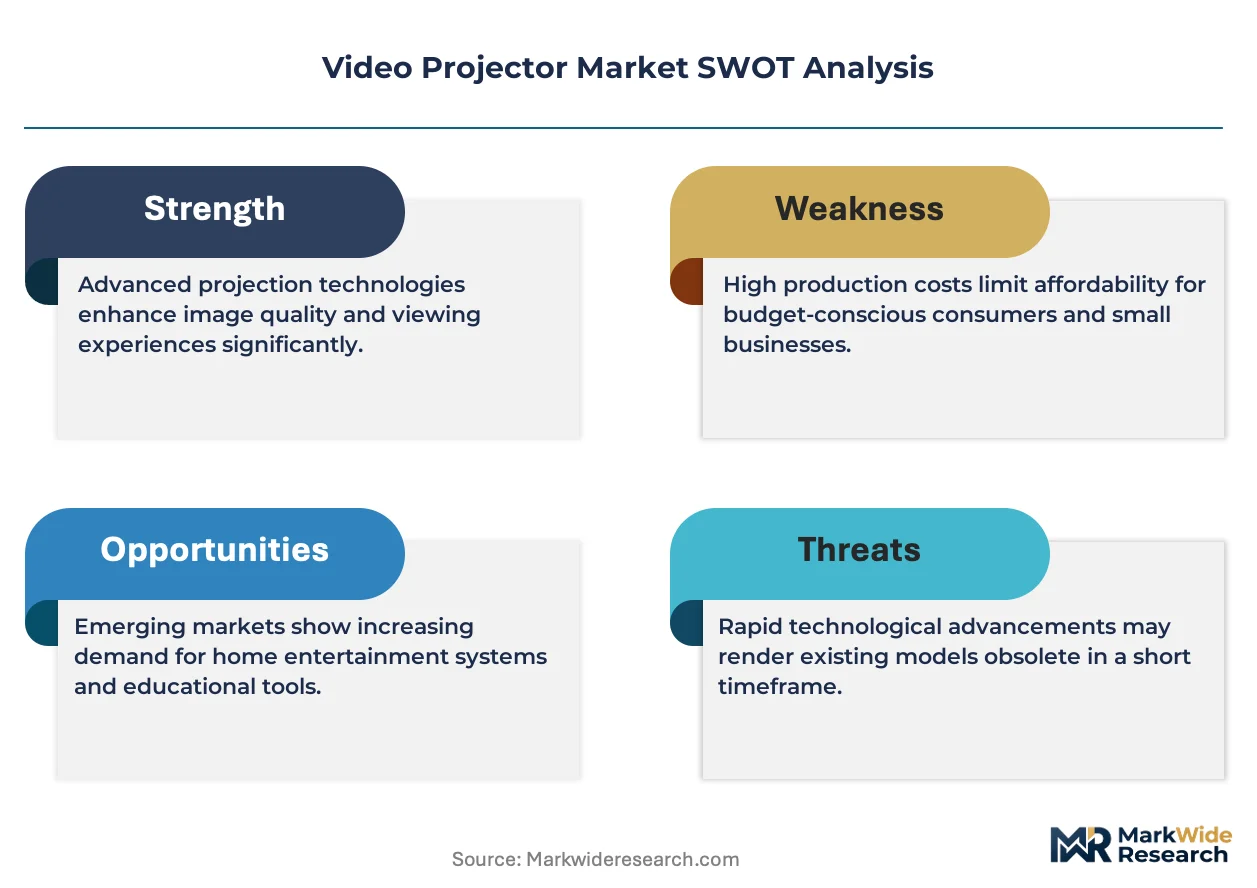
4K resolution specification tiers is bifurcating the video projector landscape into premium home cinema and mass-market portable camps. Epson leverages its in-house 3LCD manufacturing to sustain dominance in institutional and corporate channels. XGIMI specializes in compact LED-based systems that anchor its position in China's direct-to-consumer marketplace. Hisense competes through laser TV convergence products that blur the boundary between traditional projectors and flat-panel displays.
A video projector is an optoelectronic display device that modulates light through digital micromirror, liquid crystal, or liquid crystal on silicon engines to project enlarged images onto external surfaces, typically operating between 2,000 and 6,000 lumens for commercial applications and serving cinema, presentation, and immersive visualization purposes. Home Theater Projectors command the highest margin pools in residential channels where ambient light control permits premium pricing. Short Throw Projectors leads in spatially constrained corporate and education deployments where throw distances under 0.5 meters prove essential. Portable Projectors represents the fastest-growing structural category as lithium-ion power integration and autofocus algorithms reduce setup friction for mobile users.
FCC certification requirements in the United States and CE marking obligations under EU electromagnetic compatibility directives constrain market access for uncertified optical engines and radio-equipped smart projectors. RoHS substance restrictions and REACH chemical registration protocols in Europe compel manufacturers to reformulate solder compositions and eliminate restricted flame retardants from PCB assemblies. Stakeholders must monitor how emerging energy efficiency labeling schemes and right-to-repair mandates reshape product design priorities and after-service economics.
Market Dynamics
Laser phosphor technology is compressing replacement cycles across corporate and institutional installations while simultaneously eroding the installed base of mercury lamp architectures that sustained aftermarket revenue pools for two decades.
Growth Catalysts
- Hybrid work infrastructure mandates:Corporate real estate teams in the United States and Western Europe are refreshing conference room hardware to support synchronous collaboration platforms.
- REACH substance restrictions:European chemical registration protocols are accelerating mercury lamp phase-outs by compelling manufacturers to redesign optical engine assemblies around solid-state illumination.
- Outdoor cinema revival:Municipal parks departments and hospitality operators are deploying weatherized projection systems for experiential programming.
Market Restraints
- Laser diode supply concentration:High-brightness blue and red laser emitters rely on specialized foundry capacity concentrated in East Asian manufacturing clusters.
- Substitution by flat-panel displays:MicroLED and large-format LCD walls are capturing fixed-installation corporate briefing rooms where throw distance constraints previously favored projectors.
- FCC certification timelines:Radio-equipped smart projectors face extended electromagnetic compatibility review periods that delay product launches in the United States.
Strategic Opportunities
- India education digitization:State-level smart classroom initiatives are creating procurement pipelines for short-throw and interactive projection systems in government schools.
- Laser-LED hybrid convergence:Combining phosphor-converted blue laser with discrete red LED emitters enables wider color gamut at reduced thermal loads.
- Direct-to-consumer streaming integration:Built-in content platforms are opening subscription revenue streams for hardware manufacturers beyond initial equipment sales.
Industry Challenges
- Optical engineering talent scarcity:Compound lens design and thermal management expertise resides in aging workforces at Japanese and German precision optics houses.
- Legacy AV integration complexity:Enterprise IT departments struggle to bridge HDMI-CEC, HDBaseT, and network-controlled projection systems within unified device management frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Video Projector Market |
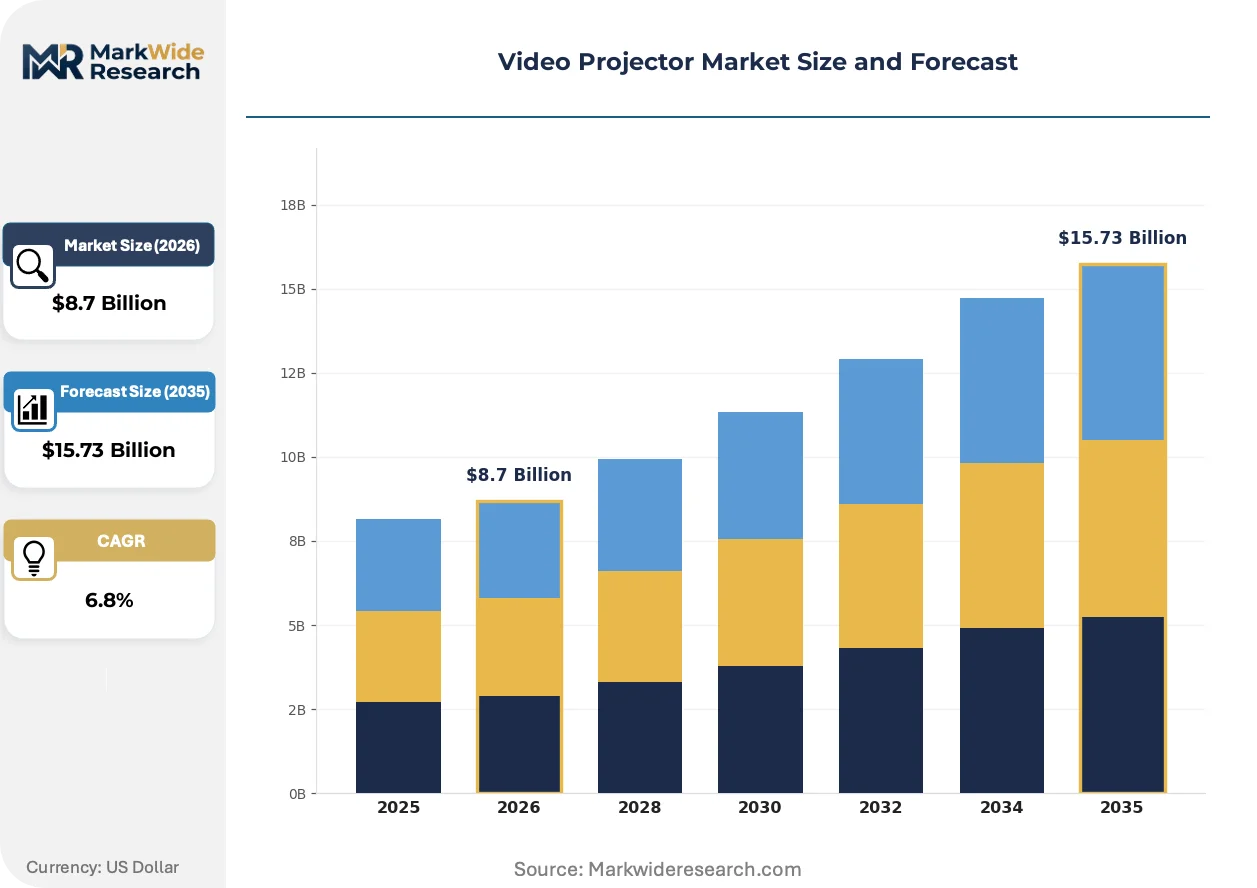
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Projectors, Short Throw Projectors, Home Theater Projectors, Business Projectors Technology: DLP, LCD, LCoS, LED End User: Education, Corporate, Entertainment, Government Application: Presentation, Home Cinema, Digital Signage, Live Events |
| Companies Covered | JMGO, Dangbei, Hisense, Epson, BenQ, XGIMI, NexiGo, TCL, AWOL Vision, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Video Projector Market Emerging Trajectories
Display engine architectures are fragmenting across three simultaneous vectors: solid-state illumination maturation, computational imaging integration, and power electronics densification. These shifts are compressing form factors while expanding addressable use cases.
Micro-LED backlighting is miniaturizing portable projection platforms by eliminating thermal management hardware previously required for high-lumen output. Chinese consumer electronics brands are adopting these engines for battery-powered units targeting camping and outdoor entertainment segments. The technology is miniaturizing chassis volumes by forty percent relative to comparable lamp-based predecessors.
EU F-Gas Regulation restrictions on hydrofluorocarbon refrigerants are forcing manufacturers to redesign thermal management systems in high-brightness installation projectors. Liquid cooling loops and phase-change materials are displacing conventional vapor compression cooling in premium cinema and large-venue applications. European rental and staging houses face accelerated equipment refresh obligations as service intervals compress under tighter leakage monitoring mandates.
Corporate procurement teams are consolidating AV equipment purchasing through managed workplace services contracts rather than discrete capital expenditure approvals. Facilities management platforms are bundling projection hardware with unified communications subscriptions and predictive maintenance telemetry. This shift is most pronounced in United States healthcare and financial services verticals where IT governance frameworks prioritize standardized endpoint security over departmental autonomy.
Video Projector Market Segmentation
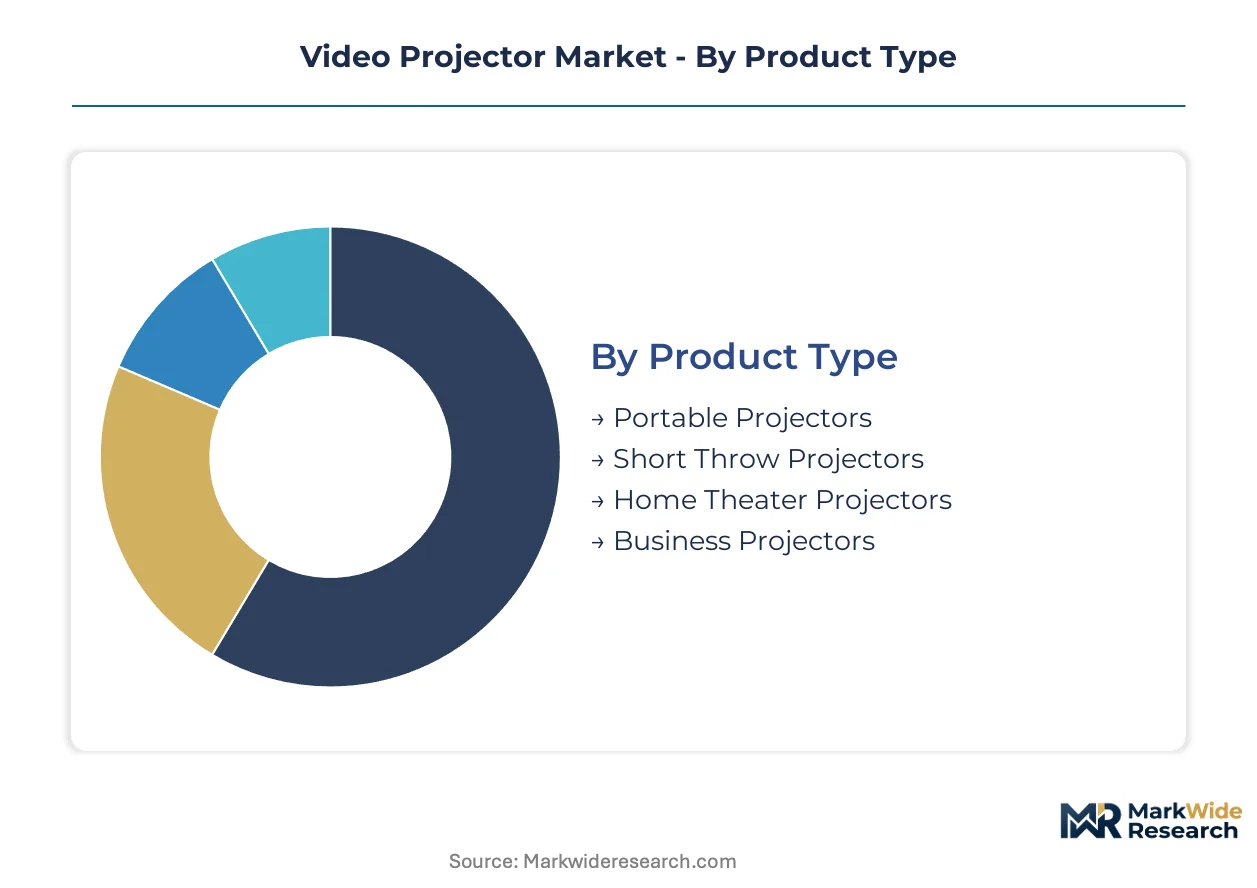
Video projector segmentation reveals divergent supply chain configurations across product architectures. Geographic concentration of manufacturing clusters and end-use demand centers shapes competitive positioning within each category.
Product Type:
Portable Projectors and Short Throw Projectors anchor export-led manufacturing from Chinese OEMs, while Home Theater and Business Projectors sustain domestic assembly in Japan and Germany for premium channels.
- Portable Projectors:Battery-powered LED engines with autofocus and keystone correction enable outdoor and mobile deployment. Demand concentrates in China's direct-to-consumer marketplace where camping culture and compact living spaces drive unit volumes. Lithium-ion integration and streaming OS bundling compress replacement cycles.
- Short Throw Projectors:Ultra-short throw optics (under 0.5 meters) project 100-inch images from wall-proximate placement. Corporate and education procurement in the United States and Western Europe favors these for spatially constrained conference rooms and smart classrooms. Laser phosphor illumination dominates this tier.
- Home Theater Projectors:4K resolution and high dynamic range specifications target dedicated cinema rooms with controlled ambient light.
- Business Projectors:3,000-5,000 lumen output balances brightness and portability for enterprise fleet deployment.
Business Projectors hold the largest share; momentum sits with Portable Projectors.
Technology:
Cost tier stratification separates premium LCoS and laser DLP installations from mass-market LCD and LED alternatives serving price-sensitive procurement channels.
- DLP:Digital micromirror devices from Texas Instruments enable high-contrast, maintenance-free operation in compact chassis. Texas Instruments' chipset supply constraints affect availability for mid-tier manufacturers. Single-chip color wheel architectures dominate portable and business segments.
- LCD:3LCD and 1LCD configurations from Epson and Sony sustain institutional procurement through color brightness advantages and lower rainbow artifacts. Epson's in-house panel manufacturing in Japan and the Philippines insulates supply from foundry bottlenecks affecting DLP.
- LCoS:Liquid crystal on silicon delivers native 4K resolution without pixel shifting for premium home cinema.
- LED:Solid-state RGB illumination eliminates color wheels and mercury lamps in entry-level portable units.
LCD holds the largest share; momentum sits with LED.
End User:
Volume concentration varies sharply by customer type, with Corporate and Education sustaining hardware refresh cycles while Entertainment and Government operate on extended procurement timelines.
- Corporate:Hybrid work infrastructure mandates in the United States drive conference room refresh spending through managed workplace services contracts. Facilities management platforms bundle projection hardware with unified communications subscriptions and predictive maintenance telemetry.
- Education:State-level smart classroom initiatives in India create procurement pipelines for interactive short-throw systems. Government schools prioritize total cost of ownership over upfront acquisition cost.
- Entertainment:Cinema exhibitors and live event operators deploy high-lumen laser installations for premium experiential programming.
- Government:Defense and public safety applications require ruggedized, secure, and TAA-compliant supply chains.
Corporate holds the largest share; momentum sits with Education.
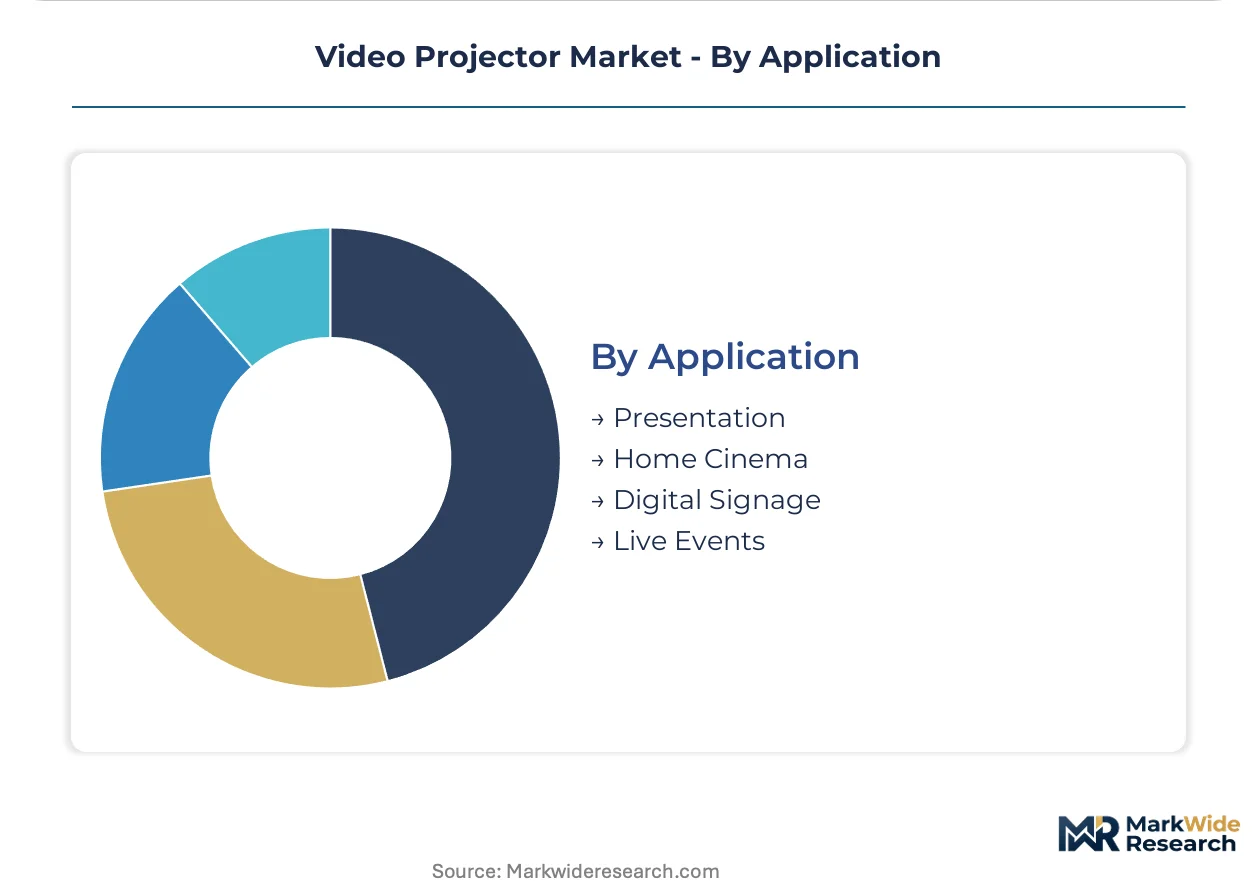
Application:
Application segmentation tracks divergent margin structures, with Home Cinema and Live Events commanding premium pricing against commoditized Presentation and Digital Signage volumes.
- Presentation:Corporate briefing room and classroom use cases prioritize brightness, connectivity, and fleet manageability over color accuracy. FCC certification timelines for radio-equipped smart projectors delay product launches in the United States.
- Home Cinema:Dedicated theater rooms with controlled lighting enable premium pricing for 4K HDR and laser illumination. Ambient light rejecting screens and integrated soundbars expand addressable residential markets.
- Digital Signage:Retail and hospitality deployments favor high-brightness, long-duty-cycle operation for static content display.
- Live Events:Rental and staging houses in Europe face accelerated refresh obligations under EU F-Gas Regulation leakage monitoring mandates for liquid-cooled high-brightness units.
Presentation holds the largest share; momentum sits with Home Cinema.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-led manufacturing from Chinese OEMs supplies portable and short-throw units worldwide, while Japan and Germany retain domestic assembly for premium institutional channels. Import dependency for high-brightness laser diodes shapes procurement strategies across major economies.
United States
Corporate hybrid-work infrastructure mandates drive conference room hardware refresh cycles through managed workplace services contracts. FCC certification timelines for radio-equipped smart projectors extend product launch schedules. Dallas and Austin tech corridors host AV integration firms bundling projection systems with unified communications platforms.
China
Domestic brands capture volume leadership in Asia-Pacific consumer channels through compact LED-based portable systems. MIIT certification requirements and GB standards regulate electromagnetic compatibility for optical engines. Shenzhen and Dongguan manufacturing clusters concentrate lithium-ion integration and streaming OS development for battery-powered camping units.
Germany
Institutional procurement favors 3LCD and laser phosphor installations for education and corporate verticals. REACH substance restrictions and RoHS compliance accelerate mercury lamp phase-outs in optical engine redesigns. Munich and Stuttgart precision optics houses maintain compound lens design expertise for premium cinema applications.
Japan
In-house LCD panel manufacturing insulates supply chains from foundry bottlenecks affecting alternative display technologies. METI energy efficiency labeling schemes reshape product design priorities for commercial installations. Nagoya and Osaka industrial corridors sustain thermal management engineering talent for high-brightness installation projectors.
India
State-level smart classroom initiatives generate procurement pipelines for interactive short-throw projection systems in government schools. BIS certification requirements constrain market access for uncertified optical engines. Bangalore and Hyderabad technology hubs host system integrators deploying fleet-managed projection hardware under education digitization programs.
Video Projector Market Vendor Landscape
Listed leaders compete with private specialists across capital access and R&D scale. The vendor base stratifies into three tiers: diversified electronics conglomerates with captive display engine manufacturing, pure-play projection specialists focused on niche illumination technologies, and direct-to-consumer brands leveraging e-commerce channel control. Consolidation pressures intensify as laser phosphor technology standardization erodes differentiation. Dominant competitive moves include backward integration into optical engine production and strategic partnerships with streaming platform operators.
Within the diversified electronics tier, Hisense and TCL exemplify convergence strategies that blur boundaries between traditional projectors and flat-panel displays. Epson anchors the institutional-specialist position through in-house 3LCD manufacturing. XGIMI occupies a position within the direct-to-consumer archetype, representing Chinese brands that dominate compact LED-based portable segments through e-commerce channel control and lithium-ion power integration.
| Leading Market Players |
|---|
| JMGO |
| Dangbei |
| Hisense |
| Epson |
| BenQ |
| XGIMI |
| NexiGo |
| TCL |
| AWOL Vision |
| Others |
Supply Flow & Price Mechanics
FCC certification timelines in the United States gate both supply qualification and price differentiation simultaneously, as radio-equipped smart projectors face extended electromagnetic compatibility review periods that compress margins for uncertified entrants while allowing certified incumbents to command premium positioning in corporate procurement channels.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in the video projector market. Price differentiation rests on certification grade and volume scale, with CE-marked laser phosphor installations commanding substantial premiums over uncertified lamp-based alternatives. Cost compression in entry-level portable segments is intensifying because Chinese direct-to-consumer brands are flooding e-commerce channels with lithium-integrated LED units. Education procurement teams in India exhibit highest price sensitivity, while cinema exhibitors in Europe demonstrate lowest sensitivity due to total cost of ownership calculations over extended duty cycles.
Supply Chain Analysis
Strategic stockpiling of high-brightness laser diodes characterizes procurement behavior among premium installation manufacturers, contrasting with just-in-time inventory practices in mass-market portable assembly. Supply concentrates in China for lithium-ion integration and streaming OS development, in Japan for 3LCD panel manufacturing, and in Germany for precision compound lens fabrication. Raw material dependencies include Texas Instruments DLP chipsets, phosphor-converted blue laser emitters, and rare-earth phosphors. Single-source vulnerability around specialized foundry capacity for red and blue laser emitters constrains output flexibility. Distribution runs through AV integration firms bundling hardware with unified communications subscriptions in United States corporate verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Switching costs embedded in legacy AV infrastructure create defensive moats for established players, as enterprise IT departments struggle to bridge HDMI-CEC, HDBaseT, and network-controlled projection systems within unified device management frameworks.
For Market Incumbents: Shield installed base revenue by deepening backward integration into optical engine production and accelerating laser phosphor refresh cycles before mercury lamp phase-outs complete. Flat-panel display convergence from Hisense and TCL threatens premium positioning; certification investment in FCC and REACH compliance preserves access to United States and European corporate procurement channels. Channel control through managed workplace services contracts locks out price-competitive challengers. For New Entrants and Emerging Players: Lead with battery-powered portable segments in India's education digitization pipeline, where state-level smart classroom initiatives prioritize total cost of ownership over brand heritage. Camping culture and compact living spaces in China's direct-to-consumer marketplace offer additional white-space penetration. Streaming OS bundling as the go-to-market angle opens recurring subscription revenue streams beyond hardware margins. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across LED-based portable manufacturing as Shenzhen and Dongguan clusters achieve scale efficiencies in lithium-ion integration. Long-term viability favors acquisition targets with captive optical engine production and streaming platform partnerships. The signal to monitor is FCC certification backlog duration, as extended timelines indicate regulatory friction that advantages incumbents with established compliance infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Optical Engine Production | Epson's in-house 3LCD manufacturing insulates supply from Texas Instruments foundry bottlenecks affecting DLP competitors. |
| Streaming Platform Partnership | XGIMI's built-in content platforms generate subscription revenue beyond initial equipment sales in China's e-commerce channels. |
| Laser Phosphor Technology Migration | REACH substance restrictions accelerate mercury lamp phase-outs and compress replacement cycles across European institutional installations. |
| Short-Throw Product Line Expansion | Ultra-short throw optics under 0.5 meters capture spatially constrained corporate and education deployments in the United States. |
| Direct-to-Consumer Channel Control | Chinese brands bypass AV integrator margins through e-commerce dominance in camping and outdoor entertainment segments. |
Methodological Framework
Initial hypotheses were tested against primary input from AV integration specialists, corporate facilities managers, education procurement officers, and precision optics engineers and refined through secondary validation against SEC filings of listed electronics conglomerates, MIIT certification databases, EU F-Gas Regulation compliance records, and customs trade data for optical engine imports. Bottom-up unit economics from manufacturing clusters in Shenzhen and Dongguan were triangulated against top-down demand projections from managed workplace services contracts.
Variance decomposition across the projection horizon isolates volume drivers by product type, technology architecture, end-user vertical, and application use case. CAGRs were derived from segment-level growth trajectory modeling incorporating hybrid work infrastructure mandates, REACH-driven lamp phase-out schedules, and India education digitization procurement pipelines. Industry-specific forecast inputs include Texas Instruments DLP chipset availability constraints and EU F-Gas leakage monitoring mandates for liquid-cooled high-brightness units.
The analysis sits within stated boundaries; outcomes outside sustained corporate hybrid work adoption or accelerated mercury lamp regulatory phase-outs would require recalibration. Forecasts reflect documented assumptions about laser diode foundry capacity expansion and streaming platform licensing economics. Revision becomes warranted when FCC certification timeline volatility or India BIS enforcement intensity crosses thresholds that alter market access economics for uncertified optical engines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Global Touchable Holographic Display Market
Display Technologies
Global Ultra Wide Temperature TFT Display Market
Display Technologies
Global Ferro Liquid Display Market
Display Technologies
Global Display Market
Display Technologies
Foldable Display Market
Display Technologies
Global Projector Market
Display Technologies
Computer Monitor Market
Display Technologies
3D Display Module Market
Display Technologies
Global 4K Display Resolution Market
Display Technologies
Global Display Panel Market
Display Technologies
4K Drawing Tablet with Screen Market
Display Technologies
Global Next Generation Display Market
Display Technologies
Plasma Display Module Market
Display Technologies
Interferometric Modulator Display Market
Display Technologies
OLED Laptops Market
Display Technologies
Global Display Controllers Market