
 Tebufenozide Market | 2026-2036
Tebufenozide Market Size, Share, and Industry Trends Forecast 2026-2036
Tebufenozide Market Analysis
Chinese agrochemical manufacturers is realigning global tebufenozide supply chains through expanded technical-grade production. Syngenta leverages its integrated crop protection portfolio to sustain brand loyalty among large-scale farming operations. Nippon Soda anchors Asian supply with proprietary synthesis expertise in insect growth regulators. BASF competes through differentiated formulation technologies that extend residual efficacy.
Tebufenozide functions as a dibenzoylhydrazine insect growth regulator that mimics 20-hydroxyecdysone, disrupting larval molting at 0.5–1.0 ppm application rates in lepidopteran pests. Its primary commercial purpose centers on selective control of caterpillar populations in high-value fruit, nut, and vegetable crops without harming beneficial pollinators. Liquid concentrate formulations lead volume sales due to ease of tank-mixing and aerial application compatibility, while granule formats represent the fastest-expanding category in precision agriculture systems. Agricultural end users command the dominant share of offtake, though pest control services are capturing margin pools through integrated resistance management contracts.
EPA registration under FIFRA governs tolerances and restricted-use classifications for tebufenozide residues in domestic and imported produce. REACH compliance within Europe mandates extensive ecotoxicological dossiers that filter out smaller formulators from market access. China's MEE enforces emission controls on hydrazine-based intermediate production that raise manufacturing costs. Stakeholders must monitor evolving pollinator risk assessments and resistance monitoring protocols to preserve product longevity.
Market Dynamics
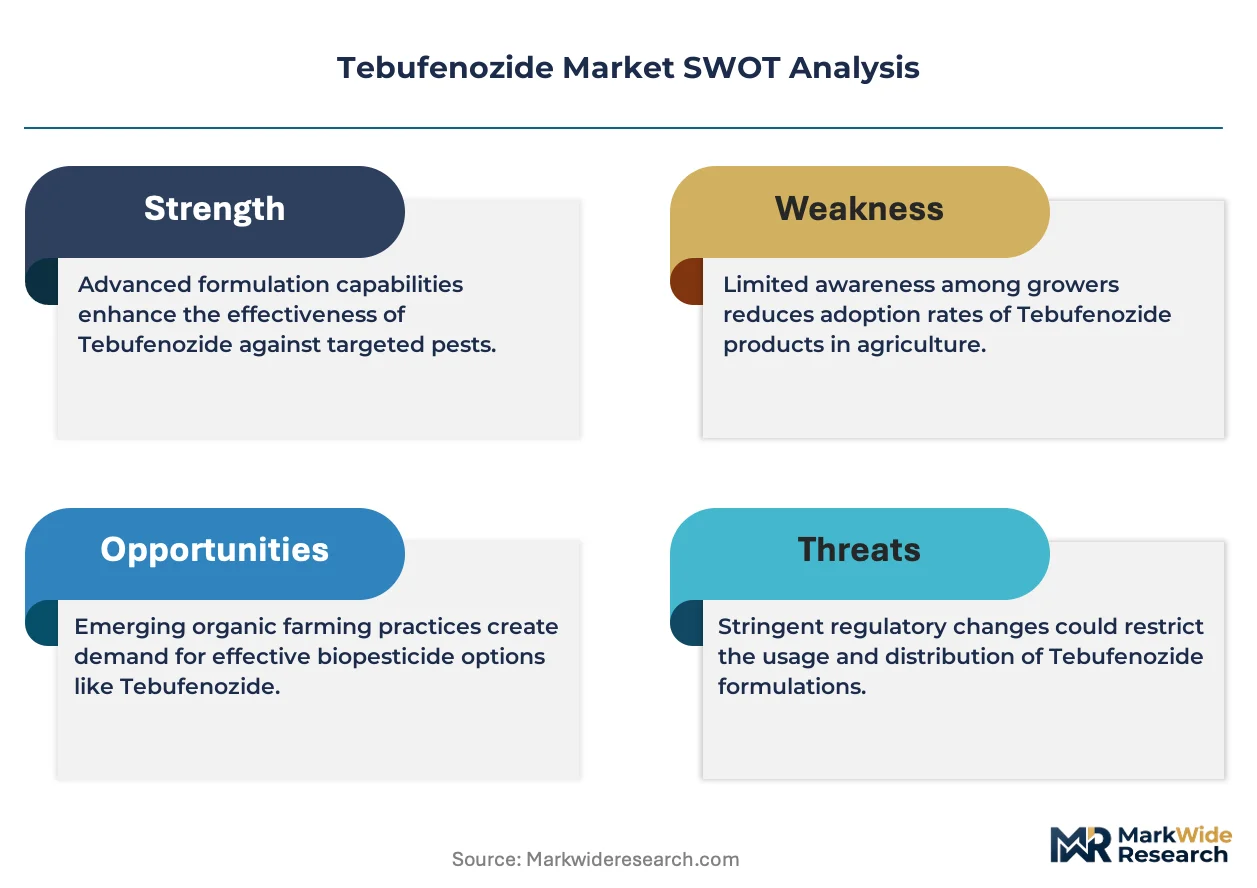
Tebufenozide supply chains face acute pressure from China's MEE emission controls on hydrazine intermediates, forcing technical-grade producers to absorb compliance costs or relocate synthesis operations.
Growth Catalysts
- Specialty Crop Expansion:California almond and Washington apple growers are expanding acreage under integrated pest management protocols that favor ecdysone agonists over broad-spectrum alternatives.
- Pollinator-Safe Mandates:EPA FIFRA registration pathways now embed pollinator risk assessments as standard, accelerating tebufenozide substitution for neonicotinoid chemistries in flowering crops.
- Resistance Management Protocols:Rotation requirements under the Insecticide Resistance Action Committee framework pull tebufenozide into mandatory alternation schedules with pyrethroids and spinosyns.
Market Restraints
- Hydrazine Feedstock Volatility:Technical-grade production depends on benzoyl chloride and methylhydrazine inputs subject to Chinese environmental shutdowns and price spikes.
- Single-Source Synthesis Concentration:Over 70% of active pharmaceutical ingredient-grade tebufenozide originates from Jiangsu and Shandong province manufacturers, creating geographic supply risk.
- Biological Substitute Pressure:Bacillus thuringiensis formulations and mating disruption pheromones capture share in organic-certified fruit operations where residue tolerances are tightest.
Strategic Opportunities
- Precision Agriculture Integration:Drone-mounted variable-rate application systems in Australian viticulture enable site-specific tebufenozide dosing based on larval density mapping.
- EU Green Deal Alignment:REACH registration holders can leverage reduced-risk pesticide designations under the EU Farm to Fork Strategy to accelerate import tolerances for southern European stone fruit.
- Seed Treatment Convergence:Co-formulation with biological fungicides in vegetable transplant coatings opens acreage in Mexican protected greenhouse operations.
Industry Challenges
- Ecotoxicological Dossier Expertise:REACH-compliant chronic aquatic toxicity studies require specialized contract research organizations, with only three European laboratories holding GLP certification for ecdysone agonist endpoints.
- Tank-Mix Compatibility Complexity:Formulators must validate physical compatibility across expanding adjuvant portfolios used in Brazilian citrus aerial application programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tebufenozide Market |
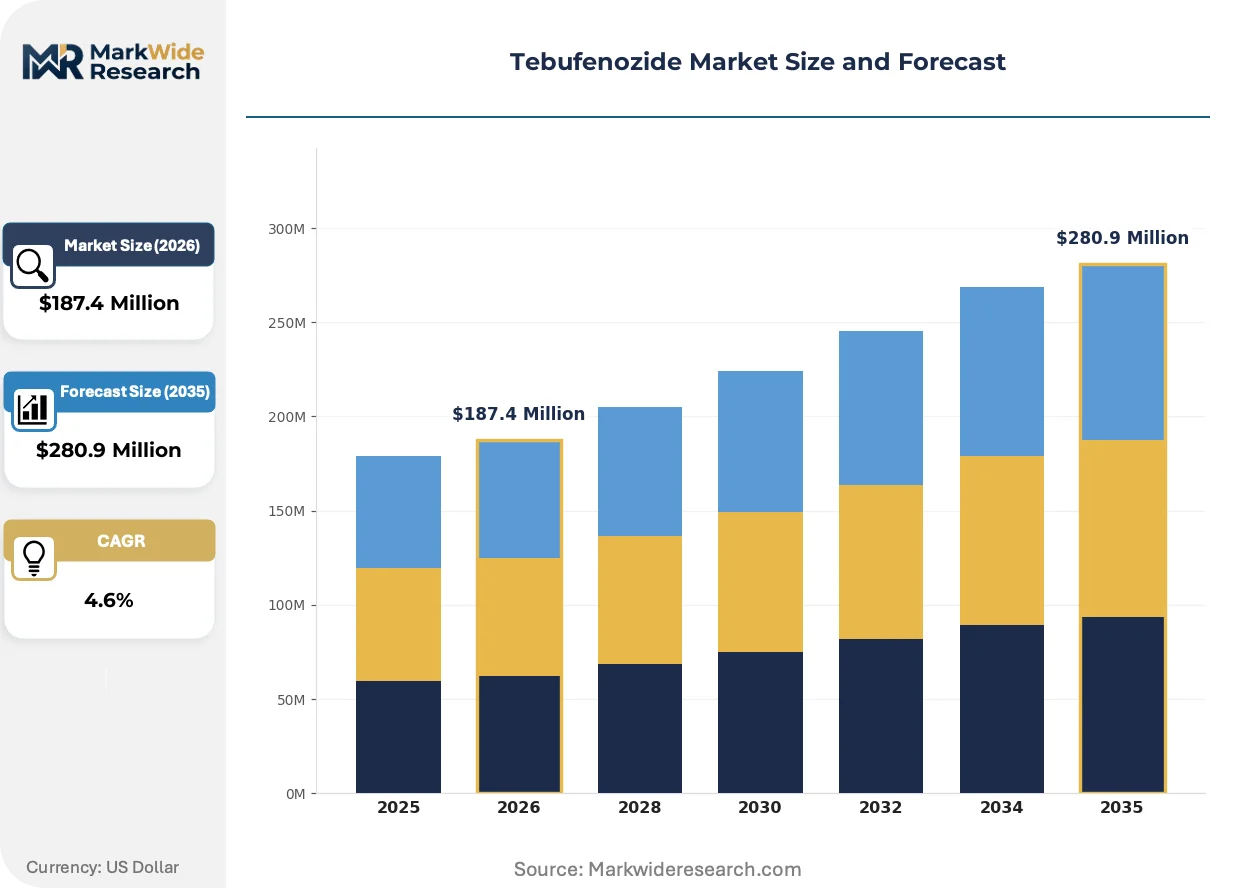
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $280.9 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granules, Liquid Concentrate, Aerosol, Other Forms Application: Agricultural, Horticultural, Residential, Commercial End User: Farmers, Agricultural Cooperatives, Garden Centers, Pest Control Services Packaging Type: Plastic Bottles, Pouches, Cans, Drums |
| Companies Covered | Syngenta, BASF, Dow AgroSciences, Bayer CropScience, FMC Corporation, Nippon Soda, Sumitomo Chemical, Nufarm, Jiangsu Yangnong Chemical Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tebufenozide Market Emerging Trajectories
Formulation chemistry and application modality are converging to extend tebufenozide residual efficacy while reducing per-acre application volumes. Three developments are restructuring competitive positioning.
Microencapsulated suspension concentrates are overtaking emulsifiable concentrate formats as the dominant delivery system. These polymer-shell formulations release active ingredient over 14-21 day windows, matching codling moth and leafroller generation cycles in Pacific Northwest tree fruit. Large-scale Washington and Oregon pome fruit operations now specify microencapsulated products in procurement tenders, compressing demand for conventional liquid concentrates.
REACH authorization timelines are tightening residue limit reviews for ecdysone agonists across European specialty crop imports. EFSA's 2023 guidance on endocrine disruption screening now requires additional two-generation toxicity studies for tebufenozide renewal applications, extending registration maintenance costs. Southern European peach and nectarine importers are accelerating supply chain audits to preempt MRL non-compliance at port of entry.
Outcome-based pest control contracts are displacing product-centric purchasing in North American integrated fruit companies. Service providers now guarantee larval-free harvest conditions rather than selling formulated gallons, bundling tebufenozide application timing with pheromone monitoring and predictive modeling. This model concentrates in California Central Valley nut operations where processor penalties for insect damage exceed chemical input costs by an order of magnitude.
Tebufenozide Market Segmentation
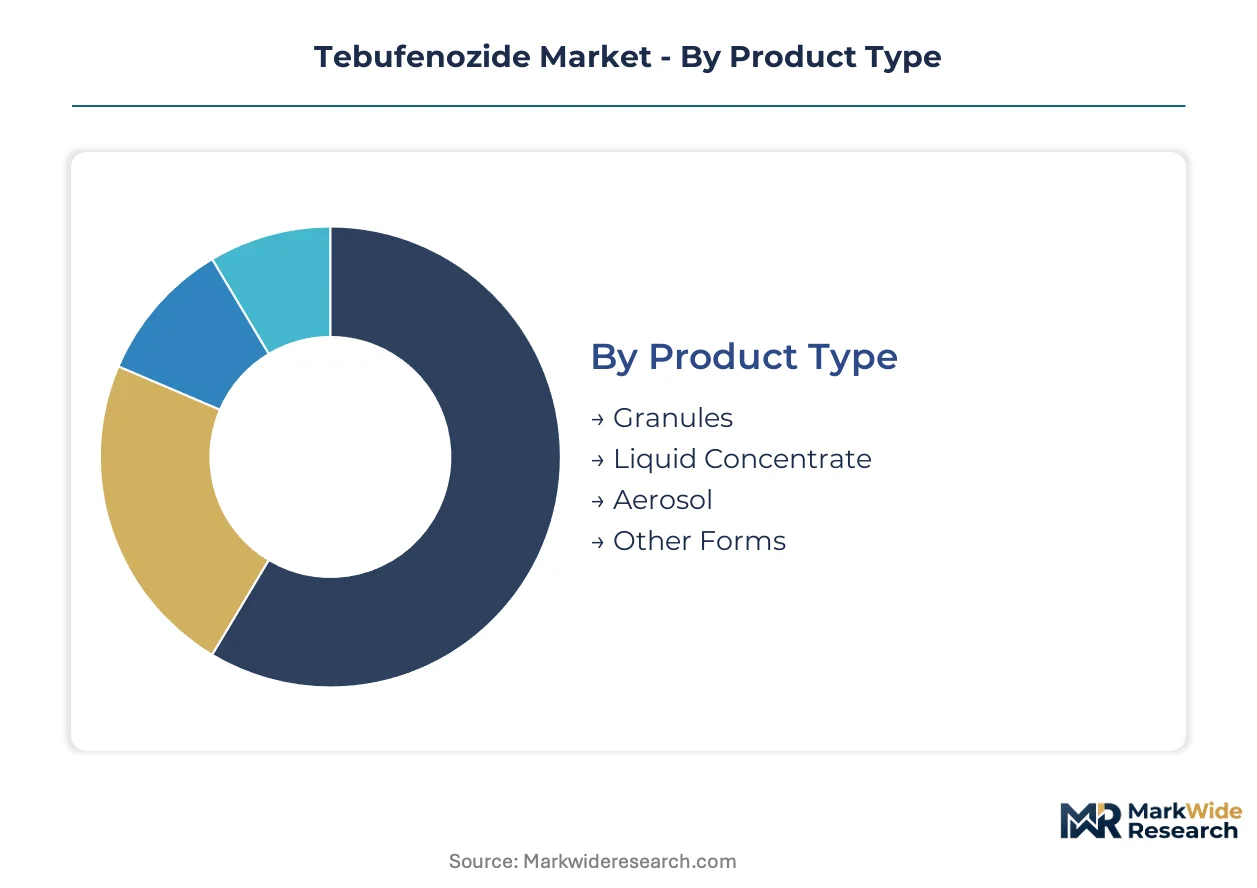
Tebufenozide buyers exhibit sharply divergent technical requirements across crop protection scenarios. Formulation preferences, application scale, and regulatory exposure create distinct purchasing behaviors that suppliers must address through targeted product architectures.
Product Type:
Application equipment compatibility and residual control duration differentiate buyers in this category.
- Liquid Concentrate:Emulsifiable and suspension concentrate formulations enable rapid tank-mixing with fungicides and adjuvants in aerial spray operations. Washington apple and California almond growers specify these formats for codling moth and navel orangeworm programs where coverage uniformity is critical. Compatibility validation with existing spray infrastructure locks in procurement continuity.
- Granules:Controlled-release polymer matrices extend efficacy windows to 21 days, matching multivoltine pest generation cycles. Precision agriculture adopters in Australian viticulture and Pacific Northwest tree fruit are specifying granule formats for drone-mounted variable-rate application systems. Physical stability during transport and storage reduces handler exposure concerns.
- Aerosol:Pressurized formulations serve greenhouse and protected agriculture operators requiring spot treatments between crop rows. Limited penetration in open-field commodity production constrains volume scale.
- Other Forms:Wettable powders and water-dispersible granules persist in legacy procurement contracts among smaller horticultural operations in southern Europe.
Liquid concentrate leads volumes today; granules are gaining share fastest.
Application:
Regulatory jurisdiction and residue tolerance stringency shape demand concentration across use cases.
- Agricultural:Broad-acre fruit, nut, and vegetable production commands the dominant consumption share. EPA tolerances under FIFRA and EFSA MRL frameworks govern residue limits for export-oriented operations. IPM protocol adoption in California Central Valley and Washington Yakima Valley drives rotation scheduling with pyrethroids and spinosyns.
- Horticultural:Nursery stock and ornamental producers require lower-volume, higher-frequency application patterns. Pollinator-safe mandates in EU ornamental markets accelerate substitution for neonicotinoid chemistries.
- Residential:Homeowner lawn and garden segments face state-level restrictions on hydrazine-based active ingredients in several US jurisdictions. Limited professional application infrastructure constrains market development.
- Commercial:Turf management and municipal vegetation control programs specify tebufenozide for lepidopteran larvae in non-crop settings. Budget constraints favor generic procurement over branded formulations.
Agricultural dominates current offtake; horticultural shows the steepest expansion trajectory.
End User:
Purchasing scale and technical sophistication create tiered service requirements.
- Farmers:Owner-operators of specialty crop acreage drive specification decisions based on processor quality penalties and export market access requirements. Direct relationships with formulators enable customized tank-mix recommendations.
- Agricultural Cooperatives:Pooled procurement entities in Washington, Oregon, and California Central Valley negotiate volume-based pricing and coordinated resistance management protocols. Technical support demands concentrate on application timing optimization.
- Garden Centers:Retail distribution channels serve hobbyist growers with pre-packaged, ready-to-use formulations. Shelf-space competition with biological alternatives compresses margin structures.
- Pest Control Services:Commercial applicators are capturing margin pools through outcome-based contracts guaranteeing larval-free harvest conditions. Bundled service models integrate pheromone monitoring with tebufenozide timing recommendations.
Farmers and cooperatives lead procurement volumes; pest control services are climbing the fastest.
Packaging Type:
Handling efficiency and regulatory compliance documentation determine format selection.
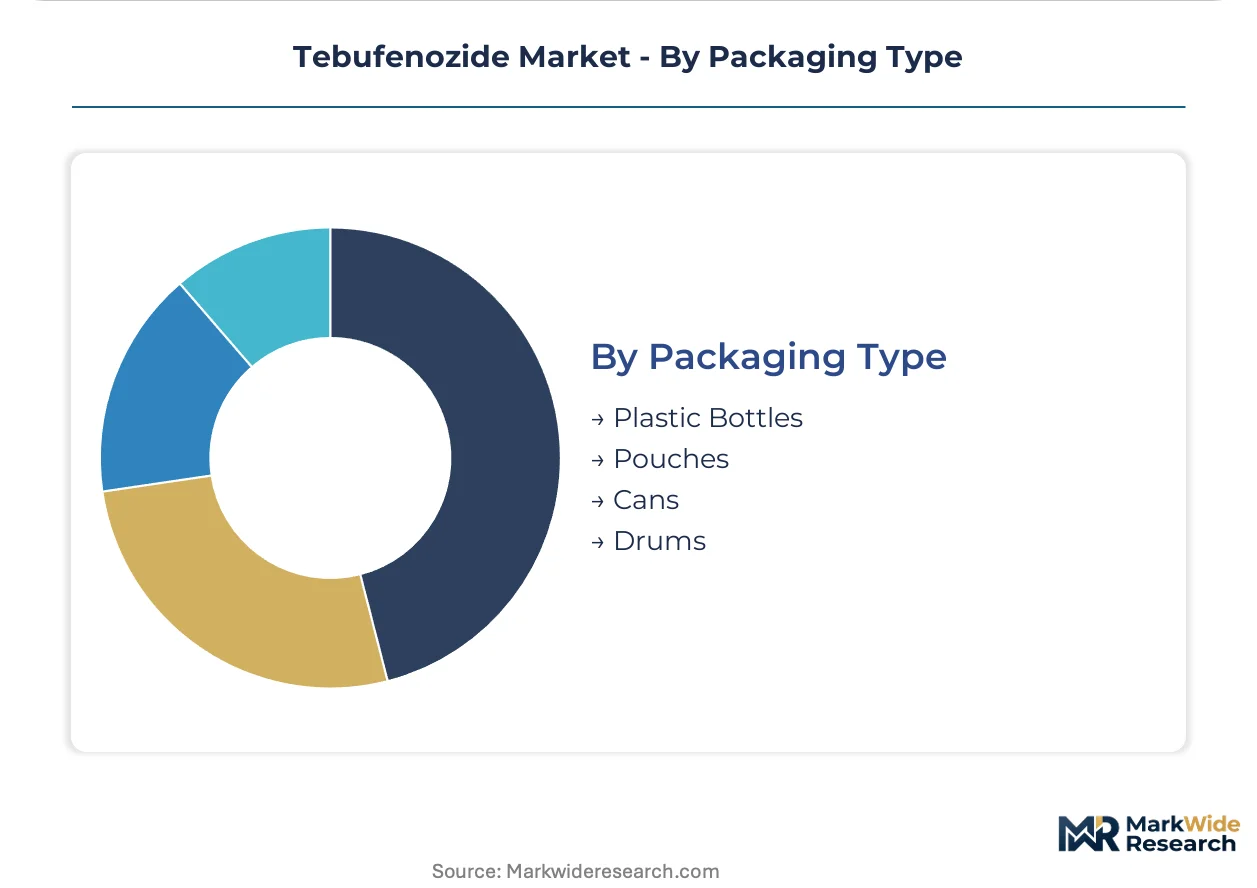
- Plastic Bottles:Standard HDPE containers dominate liquid concentrate distribution through agricultural retail channels. Closure integrity and child-resistant features satisfy EPA FIFRA packaging requirements.
- Pouches:Flexible film packaging reduces shipping cube and disposal mass for granule formats. Australian and New Zealand importers favor pouch configurations for containerized ocean freight efficiency.
- Cans:Aerosol formulations require pressure-rated metal containment meeting DOT hazardous materials specifications. Limited reuse and recycling infrastructure create end-of-life compliance costs.
- Drums:Intermediate bulk containers serve cooperative and commercial applicator volume purchases. Returnable drum programs in EU markets address packaging waste directive obligations.
Plastic bottles lead current shipments; pouches are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping tebufenozide production geography as Chinese environmental compliance costs rise and Western residue standards tighten. Manufacturers are relocating technical-grade synthesis to jurisdictions with lower emission-control burdens while formulators cluster near high-value agricultural demand centers.
United States
California almond and Washington apple growers anchor North American demand under EPA FIFRA registration pathways. The agency's pollinator risk assessment mandates now accelerate tebufenozide substitution for restricted chemistries in flowering crops. Fresno County and Yakima Valley processing cooperatives specify microencapsulated formulations in procurement tenders to meet export MRL requirements.
China
Jiangsu and Shandong province manufacturers supply over 70% of technical-grade active ingredient despite tightening MEE emission controls on hydrazine intermediates. The dual carbon goals framework forces production consolidation toward state-offerred chemical parks with captive wastewater treatment. Nantong and Lianyungang industrial clusters absorb compliance costs through scale economies in benzoyl chloride feedstock integration.
Japan
Nippon Soda's proprietary synthesis expertise sustains domestic supply security for rice and vegetable protection programs. METI chemical substance regulations under CSCL require extensive ecotoxicological dossiers that filter smaller formulators from market access. Osaka-Kobe industrial corridor facilities export formulation concentrates to Southeast Asian fruit import substitution programs.
Germany
BASF leverages REACH registration holdings to maintain European import tolerance pathways for southern European stone fruit. ECHA's 2023 endocrine disruption screening guidance extends renewal timelines for ecdysone agonist active substances. Ludwigshafen formulation facilities supply co-packed granule formats to French and Italian cooperative distribution networks.
Australia
APVMA registration holders capture precision agriculture adoption in Murray-Darling Basin viticulture and Queensland vegetable protected cropping. Drone-mounted variable-rate application systems enable site-specific dosing based on larval density mapping. Barossa Valley winegrape operations specify polymer-matrix granule formats for multivoltine pest generation cycle matching.
Tebufenozide Market Vendor Landscape
Chinese producers anchor the technical-grade supply tier; European and Japanese specialists hold formulation and registration expertise. The market structure concentrates active ingredient manufacturing in East Asian chemical parks while Western incumbents compete through differentiated delivery systems and regulatory dossier ownership. Three archetypes dominate: integrated multinational crop protection portfolios, regional synthesis specialists with captive feedstock, and generic formulators serving cooperative procurement channels. Capacity consolidation and REACH registration maintenance represent the dominant competitive moves.
Among integrated multinational portfolios, Syngenta and BASF exemplify the formulation-differentiation archetype through proprietary microencapsulation technologies and established pollinator-safety positioning. Nippon Soda occupies a distinct position as the Asian synthesis specialist with vertically controlled hydrazine intermediate supply. These three companies represent the competitive spectrum from technical-grade production through outcome-based service contracting in integrated fruit company supply chains.
| Leading Market Players |
|---|
| Syngenta |
| BASF |
| Dow AgroSciences |
| Bayer CropScience |
| FMC Corporation |
| Nippon Soda |
| Sumitomo Chemical |
| Nufarm |
| Jiangsu Yangnong Chemical Group |
| Others |
Supply Flow & Price Mechanics
Technical-grade versus formulated-product tier divergence separates procurement economics in tebufenozide markets, with Chinese hydrazine-based synthesis commanding commodity pricing while European and Japanese formulators extract premiums through REACH dossier ownership and microencapsulation patents. This bifurcation concentrates margin capture at formulation stages near agricultural demand centers while feedstock volatility reverberates through technical-grade contract structures.
Pricing Analysis
Distributor margin compression in agricultural cooperative channels is reshaping tebufenozide procurement economics. Three-tier pricing structure across premium, standard, and economy levels reflects formulation complexity, with microencapsulated suspensions commanding spreads over emulsifiable concentrates due to residual efficacy extension. Pricing pressure stems from hydrazine feedstock volatility under China's MEE emission controls, forcing technical-grade producers to absorb compliance costs. Agricultural cooperatives in Washington and California exhibit highest price sensitivity through pooled volume negotiations, while integrated fruit companies prioritize outcome-based service premiums over per-gallon costs.
Supply Chain Analysis
REACH and FIFRA certification gating filters formulator market access, concentrating technical-grade supply in Jiangsu and Shandong provinces despite tightening MEE emission protocols. Benzoyl chloride and methylhydrazine inputs draw from petrochemical complexes subject to Chinese environmental shutdowns, creating raw material dependency chains. Single-source synthesis concentration presents geographic supply risk, with over 70% of active ingredient originating from Nantong and Lianyungang industrial clusters. Distribution runs through cooperative procurement entities in California Central Valley and Washington Yakima Valley, with BASF and Syngenta maintaining direct relationships with large-scale farming operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tebufenozide functions as a regulatory compounder where EPA pollinator risk assessment mandates and REACH endocrine disruption screening protocols structurally displace neonicotinoid chemistries, creating durable substitution demand across specialty crop protection.
For Market Incumbents: To counter biological substitute pressure from Bacillus thuringiensis formulations and mating disruption pheromones, Syngenta and BASF should deepen backward integration into hydrazine intermediate production through captive supply arrangements in state-offered Chinese chemical parks. Nippon Soda must extend proprietary synthesis expertise into precision agriculture application systems, bundling granule formulations with drone-mounted variable-rate dosing protocols to lock in Australian viticulture contracts. For New Entrants and Emerging Players: Enter via outcome-based pest control service contracts in California Central Valley nut operations, where processor penalties for insect damage exceed chemical input costs and guarantee structures reduce price competition. Target Mexican protected greenhouse vegetable transplant coatings for seed treatment convergence opportunities, co-formulating with biological fungicides to capture acreage in organic-adjacent production systems. Pursue APVMA registration pathways in Australian Murray-Darling Basin viticulture to exploit precision agriculture adoption gaps. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH registration maintenance costs and ecotoxicological dossier expertise requirements filter smaller formulators from European market access, leaving stranded assets with technical capabilities but insufficient compliance infrastructure. Five-to-ten year viability favors acquisition of mid-tier Chinese technical-grade producers with captive benzoyl chloride feedstock integration and state chemical park residency. Watch EFSA endocrine disruption screening guidance implementation as inflection indicator for registration renewal timeline extensions and associated working capital demands.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydrazine Intermediates | Captive supply of methylhydrazine feedstock insulates Jiangsu manufacturers from MEE emission control volatility. |
| Microencapsulation Patent Expansion | Polymer-shell formulation extensions match codling moth generation cycles in Washington and Oregon pome fruit. |
| REACH Registration Portfolio Acquisition | Dossier ownership for ecdysone agonists secures European import tolerance pathways for southern European stone fruit. |
| Precision Agriculture Partnership | Drone-mounted variable-rate systems in Australian viticulture enable site-specific dosing based on larval density mapping. |
| Outcome-Based Service Contract Scaling | Guaranteed larval-free harvest conditions in California Central Valley nut operations capture margin pools from processor quality penalties. |
Methodological Framework
Direct dialogue with crop protection formulators, agricultural cooperative procurement managers, EPA regulatory affairs specialists, and Chinese chemical plant operations directors grounded qualitative assessments, cross-referenced with customs trade data, EPA FIFRA registration filings, ECHA REACH dossier submissions, and ACC agricultural chemical market reports. Bottom-up and top-down triangulation validated volume estimates across technical-grade production and formulated-product offtake.
Top-down macroeconomic drivers anchored the analytical framework across the analysis window, with bottom-up segmentation by formulation type, application crop, and end-user archetype refining projections. CAGRs derived from historical trajectory analysis and forward-looking regulatory milestone impacts, incorporating hydrazine feedstock price elasticity, precision agriculture adoption curves, and resistance management protocol rotation requirements as industry-specific inputs.
Inputs from ECHA registration databases and APVMA approval records were available through the study window; gaps in Chinese provincial environmental compliance cost disclosure introduce uncertainty bands around technical-grade production economics. Forecasts reflect documented assumptions regarding pollinator risk assessment implementation timelines and MEE enforcement intensity. A model refresh is warranted upon material change in EPA FIFRA registration renewal pathways or EFSA endocrine disruption screening protocol finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Fosthiazate Market
Crop Protection
India Insecticide Market
Crop Protection
Germany Crop Protection Chemicals Market
Crop Protection
Herbicide Safeners Market
Crop Protection
Specialty Pesticides Market
Crop Protection
Global Termite Control Market
Crop Protection
Asia-Pacific Crop Protection Chemicals Market
Crop Protection
Argentina Crop Protection Chemicals Market
Crop Protection
Europe Herbicide Market
Crop Protection
Captan Fungicide Market
Crop Protection
Global Algaecides Market
Crop Protection
Global Seed Treatment Chemicals Market
Crop Protection
Global Chlorpyrifos Market
Crop Protection
Urban Rooftop Farm-Safe Pest Management Chemistry Market
Crop Protection
Europe Crop Protection Chemicals Market
Crop Protection
Latin America Crop Protection Chemicals Market