
 Nutraceutical Packaging Market | 2026-2036
Nutraceutical Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Nutraceutical Packaging Market Analysis
E-commerce fulfillment channels for nutraceuticals is narrowing as direct-to-consumer subscription models reshape order profiles and unit economics. Amcor plc leverages its global film and laminate portfolio to serve high-barrier pouch requirements for probiotic brands. Berry Global anchors North American blow-molded bottle capacity for vitamin and supplement producers. Gerresheimer AG specializes in glass primary packaging for liquid nutraceuticals where oxygen and light sensitivity demands inert material solutions.
Nutraceutical packaging encompasses primary and secondary containment systems engineered to preserve bioactive compound stability, moisture sensitivity, and shelf-life integrity through specified barrier properties, desiccant integration, and child-resistant functionality. These systems employ multilayer coextrusion, thermoforming, or blow-fill-seal processes to achieve oxygen transmission rates below 0.1 cc per square meter per day for oxidation-prone ingredients. Plastic bottles dominate current volume across pharmacy and supermarket channels due to cost efficiency and design flexibility, while pouches represent the fastest-expanding format as single-serve and on-the-go consumption patterns gain traction among online retailers. Glass commands premium positioning in clean-label and organic segments where perceived purity supports margin pools, though its weight and fragility constrain broader adoption.
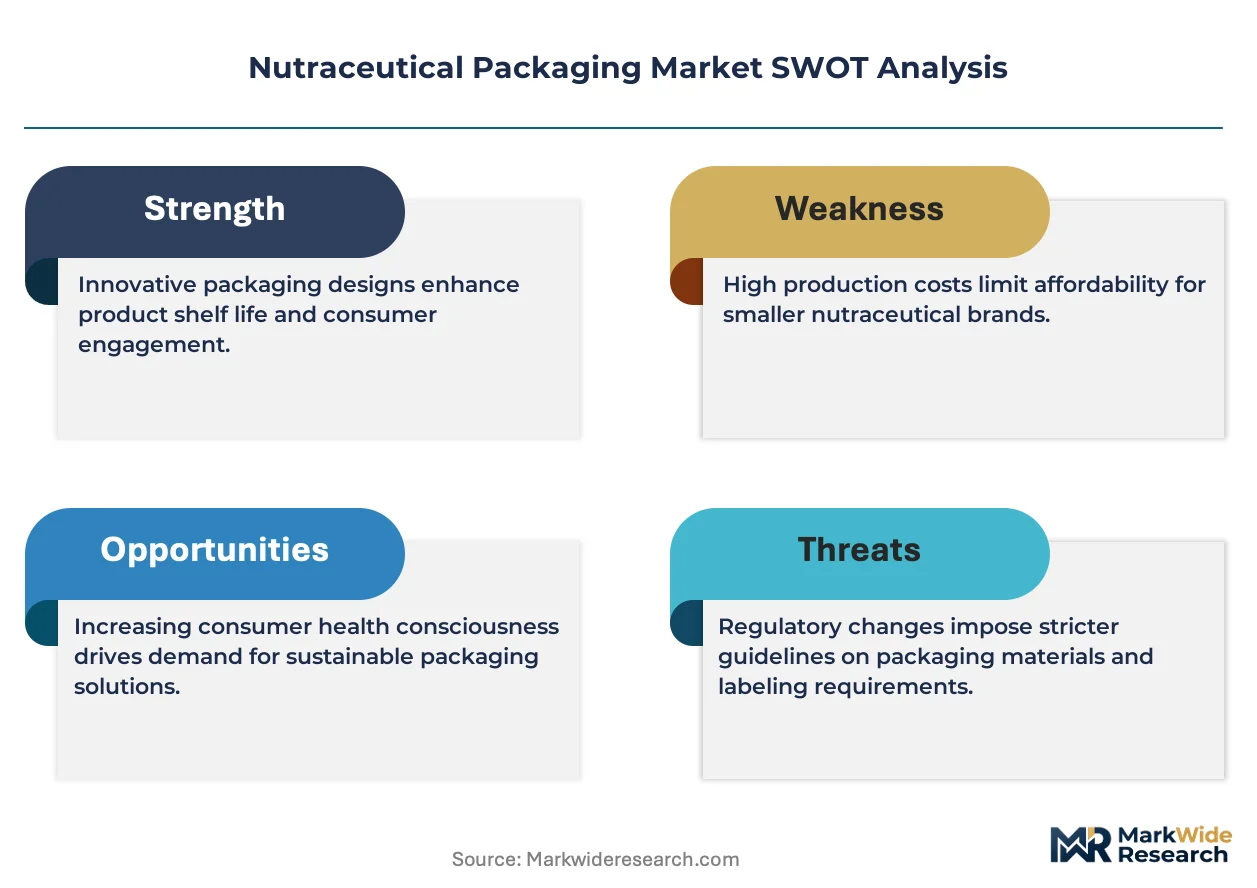
FDA regulations on dietary supplement labeling and cGMP compliance mandate lot traceability, tamper-evident features, and accurate ingredient declarations that directly shape packaging specification requirements. EFSA health claim authorization processes in Europe influence front-of-pack communication design and substantiation documentation that brands must integrate into label architectures. The EU Green Deal's packaging waste directives and emerging state-level extended producer responsibility frameworks in the US are forcing material recyclability assessments and lightweighting investments across the supplier base. Stakeholders must monitor evolving compostability certifications and chemical recycling infrastructure buildouts to align portfolio roadmaps with shifting compliance horizons.
Market Dynamics
The EU Green Deal and F-Gas Regulation are compressing material transition timelines across European nutraceutical supply chains, forcing converters to requalify barrier films and desiccant systems ahead of statutory deadlines. Contract manufacturers in Germany are accelerating specification changes to maintain pharmacy channel access.
Growth Catalysts
- Sports Nutrition Expansion:Athlete-targeted brands are demanding single-serve pouch formats that preserve hygroscopic powder stability through moisture barrier coextrusion. This format shift is pulling film lamination capacity toward high-barrier structures.
- REACH Chemical Restrictions:European substance authorization processes are eliminating legacy plasticizers from primary packaging, creating replacement demand for bio-based barrier polymers that maintain oxygen transmission performance below oxidation thresholds for probiotics.
- Direct-to-Consumer Subscription Models:Recurring shipment economics favor lightweight, shippable pouch configurations over rigid bottles. E-commerce fulfillment centers are specifying unit-dose compliance packs that reduce dimensional weight charges.
Market Restraints
- Resin Supply Concentration:Ethylene vinyl alcohol copolymer supply clusters in Northeast Asia, exposing European converters to freight volatility and extended lead times for oxygen barrier layers critical to omega-3 oil stability.
- Glass Weight Penalty:Premium clean-label positioning incurs 8-12x mass versus polymer alternatives, constraining direct-to-consumer shipping economics and limiting organic segment scalability.
- Extended Producer Responsibility Fees:Germany's Verpackungsgesetz imposes per-kilogram fees on non-recyclable multilayer structures, eroding margin pools for conventional pouch formats that dominate probiotic sachets.
Strategic Opportunities
- Chemical Recycling Infrastructure:Pyrolysis capacity buildouts in the Netherlands and Belgium are creating offtake pathways for contaminated multilayer nutraceutical packaging that mechanical sorting cannot process.
- Child-Resistant Compliance Packs:Melatonin and CBD gummy brands require CPSC-certified unit-dose blisters that integrate senior-friendly opening torque with poison-prevention functionality.
- Compostable Certification Alignment:TÜV Austria's OK Compost HOME standard is enabling shelf-stable powder formats in home-compostable films that satisfy organic retailer procurement mandates.
Industry Challenges
- Desiccant Integration Complexity:Embedding silica gel canisters into high-speed form-fill-seal lines without compromising seal integrity requires tooling retrofits that extend qualification timelines.
- Migration Testing Backlogs:FDA Type III drug master file submissions for novel coextruded structures face 18-24 month review queues, delaying market entry for next-generation barrier solutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nutraceutical Packaging Market |
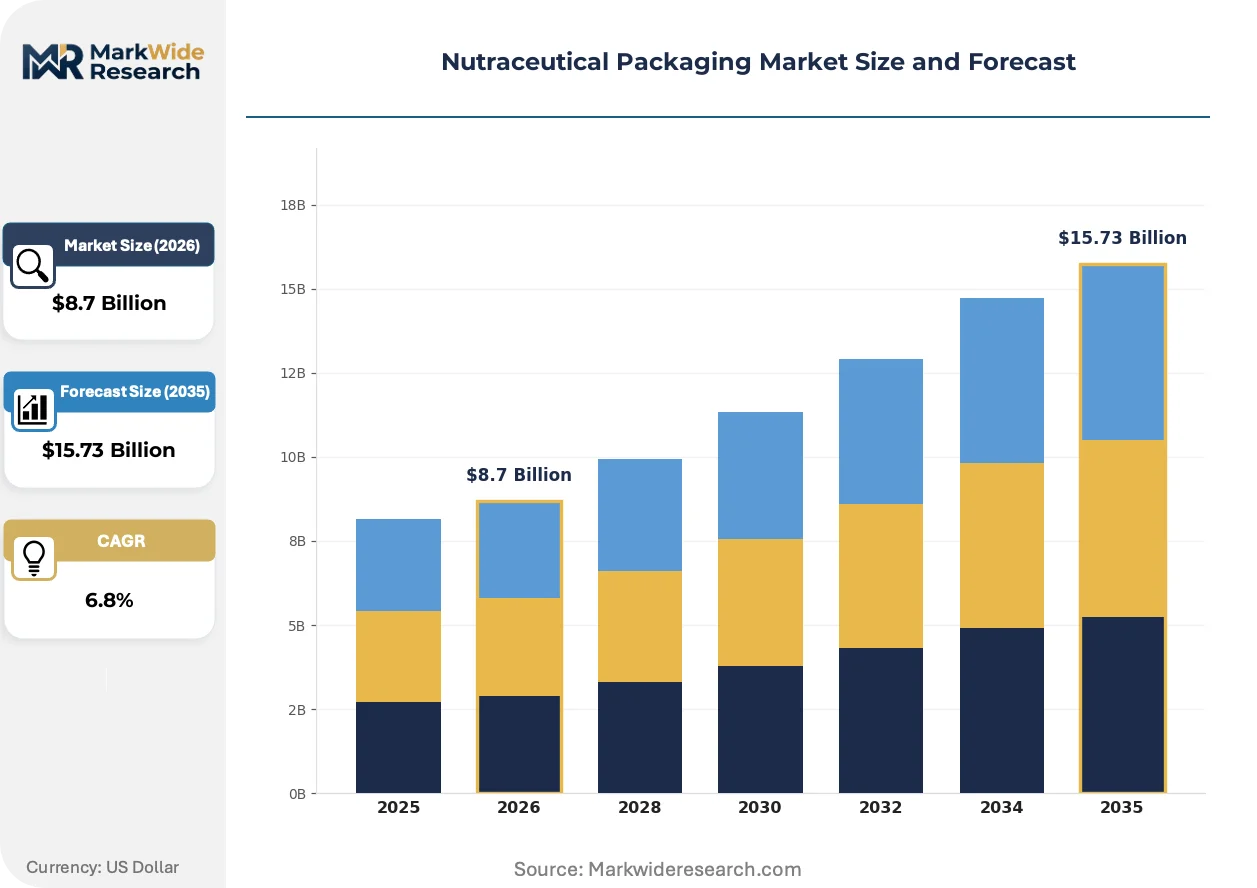
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Bottles, Pouches, Blisters, Tubs Material: Plastic, Glass, Metal, Paperboard End User: Pharmacies, Health Food Stores, Online Retailers, Supermarkets Closure Type: Screw Caps, Snap Caps, Foil Seals, zippers |
| Companies Covered | Amcor plc, Berry Global, Gerresheimer AG, Graham Packaging, TricorBraun LLC, ProAmpac, Glenroy, Inc., WestRock Company, Huhtamaki Oyj, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nutraceutical Packaging Market Emerging Trajectories
Active and intelligent packaging systems are migrating from pharmaceutical applications into nutraceutical formats, driven by shelf-life extension requirements for temperature-sensitive bioactives. Material science advances are collapsing the performance gap between conventional and sustainable barrier structures.
Mono-material polyethylene pouches with plasma-enhanced barrier coatings are rendering obsolete conventional multilayer polyester-aluminum-PE laminates that dominate probiotic stick-pack formats. European contract packagers are piloting these structures for pharmacy-channel melatonin powders. The technology is rendering obsolete legacy specification lock-ins that have constrained converter innovation for two decades.
The EU F-Gas Regulation's phase-down of hydrofluorocarbon blowing agents is forcing rigid bottle producers to adopt hydrocarbon or CO2-based foam core technologies for vitamin tablet containers. German converters are absorbing capital costs for extrusion blow molding line conversions. Liquid nutraceutical categories requiring thermal insulation during distribution are most affected, with brands reformulating around ambient-stable matrices to avoid cold-chain dependency.
Subscription fulfillment economics are compressing order cycles from quarterly bulk purchases to monthly personalized assortments. Direct-to-consumer vitamin brands are specifying unit-dose blister cards that integrate lot traceability QR codes for regulatory compliance. This pattern is most visible in US West Coast logistics clusters serving wellness-focused demographic cohorts.
Nutraceutical Packaging Market Segmentation
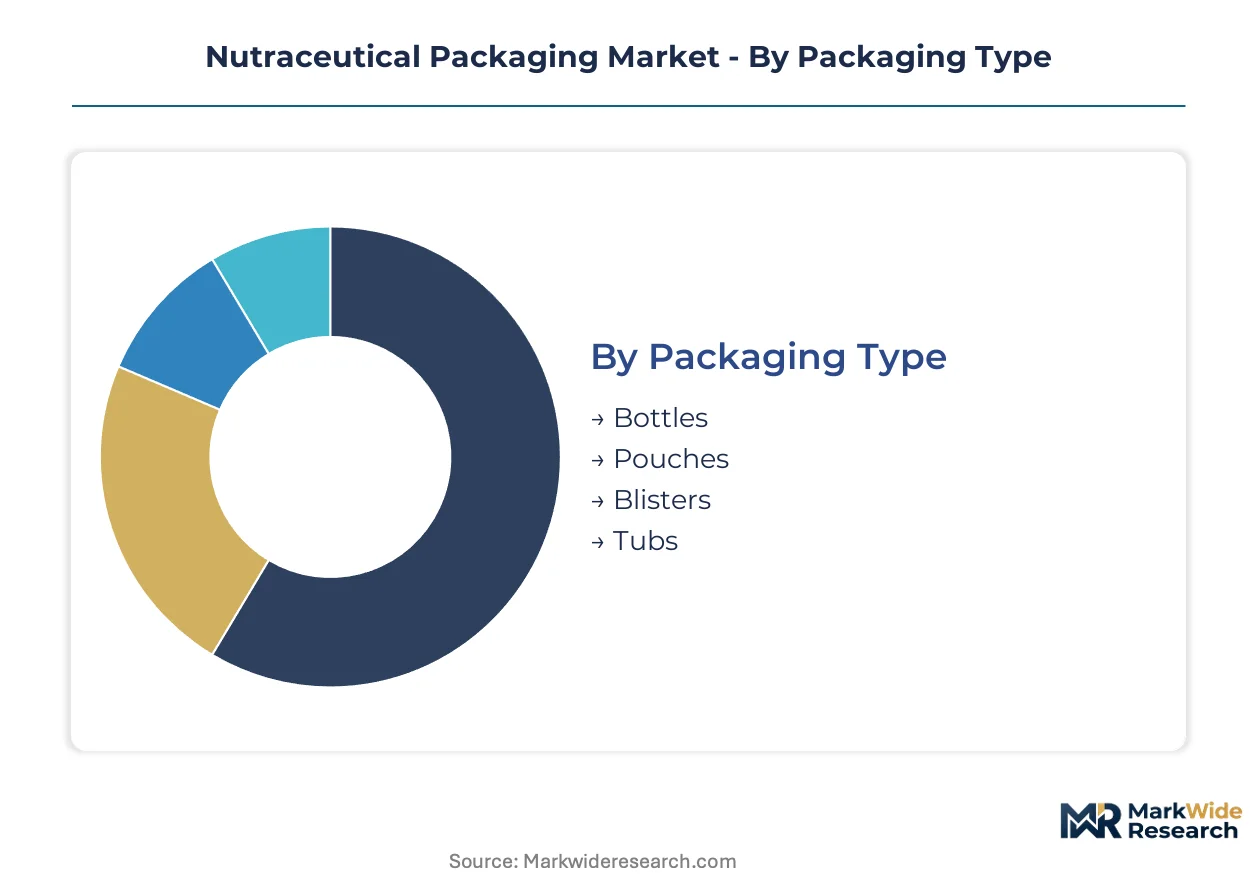
Nutraceutical packaging segmentation reflects divergent stability requirements across dosage forms and distribution channels. Material selection and format geometry directly determine barrier performance, child-resistance compliance, and e-commerce shippability.
Packaging Type:
Mature formats dominate pharmacy and mass retail channels, while emerging configurations capture direct-to-consumer growth vectors.
- Bottles:Blow-molded HDPE and PET containers with desiccant closures protect moisture-sensitive tablets and capsules. Pharmacy chains in Germany specify bottles for prescription supplement fulfillment due to established cGMP handling protocols.
- Pouches:High-barrier multilayer laminates with oxygen transmission rates below 0.1 cc per square meter per day preserve probiotic powder potency. Single-serve stick packs are displacing bulk jars in sports nutrition subscription boxes.
- Blisters:Thermoformed PVC or aluminum lidding films enable unit-dose compliance tracking for melatonin and CBD gummies.
- Tubs:Wide-mouth polypropylene containers accommodate scoop-dosed protein powders and meal replacement blends.
Bottles retain volume leadership; pouches hold the steepest expansion curve.
Material:
Cost tiers stratify across premium purity positioning and functional barrier economics.
- Plastic:Multilayer coextrusion and barrier coatings dominate probiotic and omega-3 applications. EVOH and nylon interlayers achieve shelf-life extension for oxidation-prone ingredients at unit costs below glass alternatives.
- Glass:Amber and cobalt blue borosilicate vials command organic and clean-label segments where perceived chemical inertness justifies shipping cost premiums. German organic retailers mandate glass for liquid tonic positioning.
- Metal:Aluminum canisters and tubes provide absolute light and oxygen barriers for effervescent tablets and topical nutraceuticals.
- Paperboard:Recyclable cartons and folding boxes serve secondary packaging for subscription box presentation and retail shelf differentiation.
Plastic commands unit volume; glass captures margin concentration in premium channels.
End User:
Customer type determines order profile economics and regulatory documentation intensity.
- Pharmacies:German Apotheken require tamper-evident seals, Braille labeling, and batch traceability systems for reimbursed supplement categories. Contract manufacturers maintain dedicated filling lines for pharmacy channel compliance.
- Health Food Stores:Independent retailers in the Netherlands and Belgium prioritize compostable packaging certifications and front-of-pack sustainability claims.
- Online Retailers:Amazon and direct-to-consumer vitamin brands specify lightweight, shippable formats that minimize dimensional weight charges.
- Supermarkets:Mass merchandisers drive high-volume, standard-specification bottles for private-label vitamin programs.
Pharmacies anchor specification complexity; online retailers are expanding most quickly.
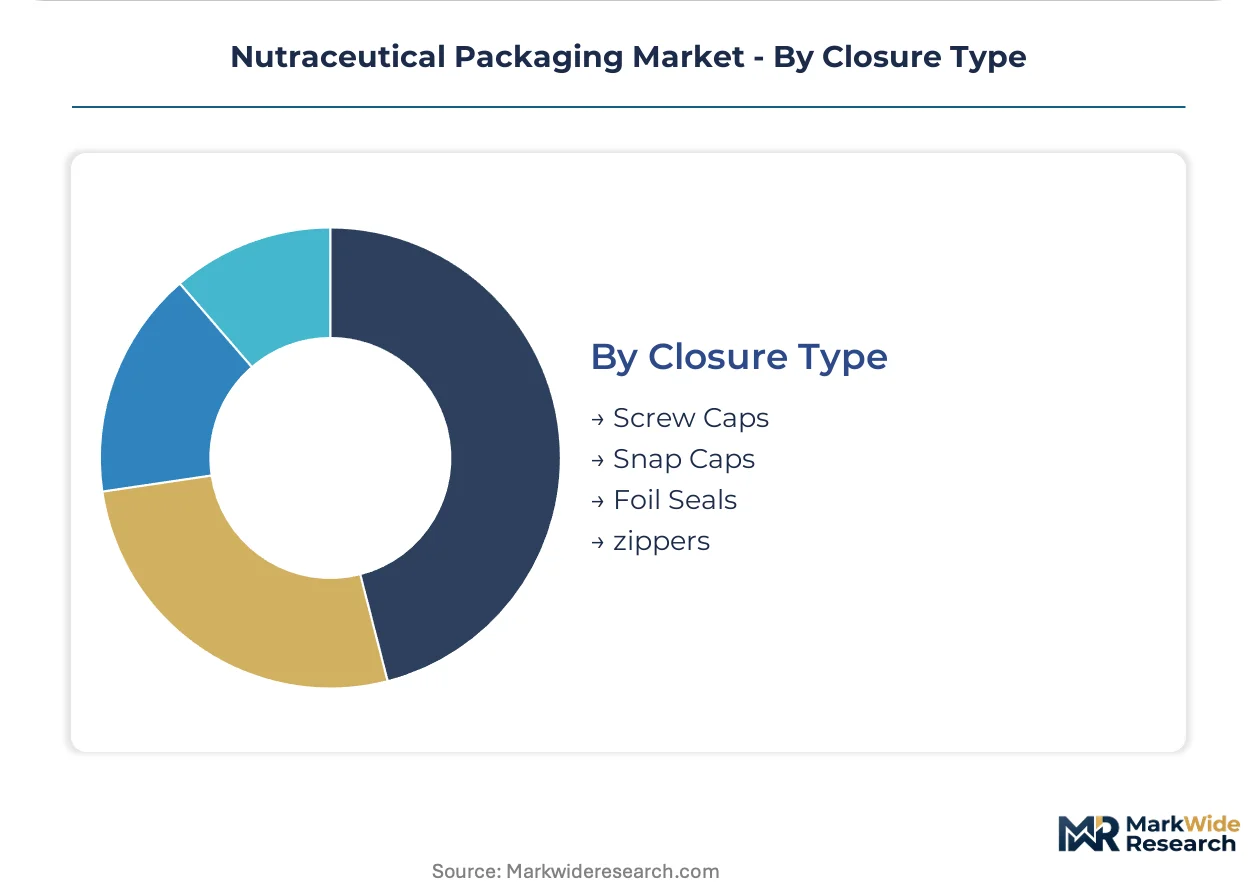
Closure Type:
Application requirements differentiate child-resistance mandates from convenience-oriented opening torque.
- Screw Caps:Continuous thread HDPE closures with induction foil liners dominate tablet bottles. German Verpackungsgesetz compliance drives mono-material cap designs for mechanical recyclability.
- Snap Caps:Hinged dispensing closures enable single-handed powder scooping for sports nutrition tubs.
- Foil Seals:Heat-induction aluminum membranes provide tamper evidence and oxygen barriers for probiotic jars.
- Zippers:Press-to-close profiles in multilayer pouches support resealable powder and gummy formats.
Screw caps retain installed base dominance; zippers gain share in pouch format conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA dietary supplement labeling mandates and cGMP compliance requirements anchor North American specification standards, while Germany's Verpackungsgesetz and the EU Green Deal compress material transition timelines across European supply chains. Regional demand patterns diverge sharply between pharmacy-channel compliance requirements and direct-to-consumer subscription economics.
Germany
Contract manufacturers serving Apotheken channels are accelerating barrier film requalification ahead of EU F-Gas Regulation deadlines. The Verpackungsgesetz imposes escalating per-kilogram fees on non-recyclable multilayer structures, eroding margin pools for conventional probiotic sachets. Industrial clusters in North Rhine-Westphalia and Bavaria host dedicated filling lines for pharmacy-compliant supplement packaging.
United States
West Coast logistics clusters serving wellness-focused demographic cohorts are specifying unit-dose blister cards with lot traceability QR codes for regulatory compliance. FDA Type III drug master file submissions for novel coextruded structures face extended review queues, delaying next-generation barrier solutions. Pacific Northwest contract packagers are piloting mono-material polyethylene pouches with plasma-enhanced barrier coatings.
Netherlands
Pyrolysis capacity buildouts in Rotterdam and Antwerp are creating offtake pathways for contaminated multilayer nutraceutical packaging that mechanical sorting cannot process. REACH chemical restrictions are eliminating legacy plasticizers from primary packaging, generating replacement demand for bio-based barrier polymers. Dutch independent retailers prioritize TÜV Austria OK Compost HOME certifications for organic supplement lines.
China
Domestic brands are reformulating around ambient-stable matrices to avoid cold-chain dependency as thermal insulation requirements tighten. NMPA alignment with international stability testing protocols is elevating barrier performance specifications for imported supplement packaging. Yangtze River Delta converters are absorbing capital costs for extrusion blow molding line conversions to hydrocarbon-based foam core technologies.
India
FSSAI health claim substantiation requirements are influencing front-of-pack communication design for ayurvedic supplement brands. CDSCO stability testing mandates for probiotic formulations are driving oxygen transmission rate specifications below 0.1 cc per square meter per day. Maharashtra-based contract manufacturers are scaling high-barrier pouch capacity for single-serve powder formats.
Nutraceutical Packaging Market Vendor Landscape
Diversified packaging conglomerates and specialized primary containment specialists split the market across format-specific capability tiers. Consolidation pressure concentrates among blow-molded bottle producers serving high-volume pharmacy channels, while pouch format innovation attracts mid-scale film lamination specialists. Three archetypes dominate: integrated multiformat converters with global film portfolios, regional blow-molding specialists anchoring North American vitamin supply chains, and glass primary packaging experts serving liquid nutraceutical stability requirements. Competitive moves center on chemical recycling infrastructure partnerships and mono-material barrier technology licensing.
Within the integrated multiformat tier, Amcor plc and Berry Global exemplify scale-driven positions spanning rigid and flexible formats. Gerresheimer AG occupies a specialized niche in glass primary containment for oxygen-sensitive liquid applications. These three entities represent divergent strategic postures: global film portfolio leverage, regional blow-molded capacity anchoring, and premium inert material specialization respectively.
| Leading Market Players |
|---|
| Amcor plc |
| Berry Global |
| Gerresheimer AG |
| Graham Packaging |
| TricorBraun LLC |
| ProAmpac |
| Glenroy, Inc. |
| WestRock Company |
| Huhtamaki Oyj |
| Others |
Supply Flow & Price Mechanics
Ethylene vinyl alcohol copolymer production clusters in Northeast Asia tether European converters to freight volatility and extended lead times, compressing margin pools for oxygen barrier layers that omega-3 oil stability demands. This upstream concentration forces downstream buyers into long-term offtake negotiations or specification downgrades that compromise shelf-life claims.
Pricing Analysis
Geographic price spreads between German pharmacy-channel specifications and Asian mass-market alternatives exceed three-to-one multiples. Three-tier pricing structure across premium pharmacy-grade, standard retail, and economy private-label levels stratifies the market. Cost compression in economy tiers is intensifying because India's FSSAI-mandated stability testing is elevating minimum barrier specifications. Subscription vitamin brands exhibit lowest price sensitivity; supermarket private-label programs anchor the most elastic demand.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates converter risk assessments as REACH chemical restrictions eliminate legacy plasticizer options. Supply concentrates in Germany for pharmacy-compliant filling capacity, China for EVOH resin and blow-molded bottle machinery, and the Netherlands for pyrolysis chemical recycling infrastructure. Raw material dependencies include EVOH oxygen barrier resins, hydrocarbon-based foam core blowing agents, and plasma-enhanced coating precursors. Single-source vulnerability in Northeast Asian EVOH supply is forcing qualification of secondary resin grades. Distribution runs through contract manufacturing networks anchored in North Rhine-Westphalia industrial clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nutraceutical packaging market sits at a high-growth inflection as EU F-Gas Regulation deadlines force material transitions ahead of converter requalification cycles. Mono-material barrier technologies are disrupting two decades of multilayer specification lock-ins.
For Market Incumbents: Harden barrier film portfolios against REACH-authorized bio-based polymer substitution by securing backward integration into chemical recycling offtake agreements in the Netherlands and Belgium. Lock in pharmacy-channel specification control through dedicated filling line investments in Bavaria before contract manufacturers consolidate access. Child-resistant compliance pack certification represents the priority defensive moat as melatonin and CBD gummy brands multiply. For New Entrants and Emerging Players: Establish a beachhead in home-compostable pouch formats certified to TÜV Austria OK Compost HOME standards, where organic retailer procurement mandates outstrip qualified supplier capacity. Target Dutch and Belgian independent health food stores with front-of-pack sustainability claims that command shelf placement premiums. Lead with chemical recycling feedstock partnerships that solve the multilayer waste liability constraining incumbent margin structures. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed contract manufacturing platforms in Germany that have consolidated Apotheken-channel filling capacity but lack film lamination capabilities. Five-to-ten-year viability hinges on mono-material barrier technology licensing positions rather than legacy multilayer equipment depreciation schedules. The signal to watch is FDA Type III drug master file submission volumes for novel coextruded structures, which indicate next-generation barrier solution pipeline depth.| Strategic Initiative | Industry Significance |
|---|---|
| Chemical Recycling Infrastructure Partnership | Pyrolysis capacity in Rotterdam creates offtake pathways for contaminated multilayer packaging that mechanical sorting cannot process. |
| Mono-Material Barrier Technology Licensing | Plasma-enhanced polyethylene coatings from Pacific Northwest pilot programs are rendering legacy polyester-aluminum-PE laminates obsolete. |
| Child-Resistant Compliance Pack Certification | CPSC-certified unit-dose blisters integrate senior-friendly opening torque with poison-prevention functionality for melatonin and CBD gummies. |
| Pharmacy-Channel Filling Line Expansion | Dedicated lines in North Rhine-Westphalia and Bavaria secure Apotheken access ahead of EU Green Deal packaging waste directive enforcement. |
| Home-Compostable Certification Alignment | TÜV Austria OK Compost HOME standard enables shelf-stable powder formats that satisfy organic retailer procurement mandates in the Netherlands. |
Methodological Framework
Cross-validation between primary interviews with packaging procurement managers at vitamin brands, contract manufacturing operations directors, and regulatory affairs specialists anchors the qualitative findings against secondary validation from FDA Type III drug master file submissions, EFSA health claim authorization databases, and EU Green Deal implementation tracking. Bottom-up triangulation of converter capacity announcements and top-down demand modeling from subscription vitamin shipment data establish volume boundaries. Customs records for EVOH resin imports and TÜV Austria certification registries provide secondary cross-checks.
Calibration against historical barrier film adoption curves and pharmacy-channel specification change timelines shapes the analytical framework across the analysis window. Segmentation dimensions modeled include packaging format, material substrate, end-user channel, and closure type. CAGRs derive from regression analysis of converter capital expenditure cycles and regulatory deadline clustering. Forecast inputs incorporate REACH substance authorization timelines and NMPA stability testing protocol alignment trajectories for Chinese market entry.
Stress conditions across EVOH resin supply disruption, EU F-Gas Regulation acceleration, and subscription model churn rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding chemical recycling infrastructure buildout pace and mono-material barrier coating yield rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Pharmacy Repackaging Systems Market
Pharmaceutical Packaging
Europe Pharmaceutical Packaging Market
Pharmaceutical Packaging
Single Dose Dispensers Market
Pharmaceutical Packaging
Clinical Trial Packaging Market
Pharmaceutical Packaging
Pharmaceutical HDPE Bottle Market
Pharmaceutical Packaging
Europe Pharmaceutical Blister Packaging Market
Pharmaceutical Packaging
Europe Glass Prefilled Syringes and Glass Vials Packaging Equipment Market
Pharmaceutical Packaging
Pharmaceutical Unit Dose Packaging Market
Pharmaceutical Packaging
China Pharmaceutical Packaging Market
Pharmaceutical Packaging
Parenteral Drugs Packaging Market
Pharmaceutical Packaging
Asia-Pacific Pharmaceutical Vials Market
Pharmaceutical Packaging
Pharmaceutical Vials Market
Pharmaceutical Packaging
Oral Dose Packaging Market
Pharmaceutical Packaging
Pharmaceutical Ampoules Market
Pharmaceutical Packaging
Latin America Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Smart Pharmaceutical Packaging Market