
 Infectious Disease Treatments Market | 2026-2036
Infectious Disease Treatments Market Size, Share, and Industry Trends Forecast 2026-2036
Infectious Disease Treatments Market Outlook
Indian API manufacturers is recalibrating output toward finished-dose infectious disease formulations. Pfizer Inc. leverages its vertical integration across penicillin-class supply chains to secure raw material access. Gilead Sciences, Inc. anchors its position through sustained R&D intensity in antiviral platforms. Merck & Co., Inc. differentiates via manufacturing scale in vaccine-adjuvant combinations for emerging pathogen preparedness.
Infectious disease treatments comprise pharmacological agents engineered to inhibit, neutralize, or eliminate pathogenic microorganisms including bacteria, viruses, fungi, and parasites, typically formulated with defined bioavailability parameters and stability profiles for targeted tissue distribution. These therapies serve to reduce morbidity, interrupt transmission chains, and prevent resistance amplification in clinical and public health settings. Antibacterials command mature margin pools amid stewardship-driven narrowing of empirical prescribing, while antivirals represent the fastest-expanding category due to RNA-targeting platform advances. Injectable delivery modes dominate hospital settings for acute infections, though oral formulations for outpatient resistant tuberculosis management are gaining structural share in resource-limited health systems.
The FDA's Qualified Infectious Disease Product program and EMA's PRIME designation pathway accelerate development timelines for novel mechanism therapies against resistant pathogens. WHO prequalification standards shape procurement eligibility for low-income country buyers, directly filtering market access for generic manufacturers. Stakeholders must monitor resistance surveillance data and regulatory exclusivity cliff timing to align pipeline investments with evolving standard-of-care protocols.
Market Dynamics
Antimicrobial resistance surveillance networks are compressing empirical prescribing windows and forcing therapeutic substitution protocols in acute care settings worldwide.
Growth Catalysts
- FDA Qualified Infectious Disease Product incentives:Extended exclusivity periods accelerate novel mechanism investments against resistant Gram-negative pathogens.
- Hospital antimicrobial stewardship mandates:Institutional protocols in tertiary care centers drive rapid diagnostic-guided therapy selection.
- India's pharmaceutical PLI scheme:Domestic manufacturing incentives expand API-to-finished-dose capacity for tuberculosis and HIV therapeutics.
Market Restraints
- API supply concentration:Penicillin and cephalosporin intermediate production clusters in specific Asian manufacturing zones create single-source vulnerability.
- Clinical trial cost inflation:Patient recruitment for resistant pathogen studies requires expanded site networks in Eastern Europe and Latin America.
- Generic substitution pressure:Off-patent fluoroquinolones and macrolides erode branded pricing power in outpatient infectious disease management.
Strategic Opportunities
- Sub-Saharan Africa public procurement:WHO prequalification pathways open volume contracts for pediatric antiretroviral fixed-dose combinations.
- Long-acting injectable platforms:Depot formulations for HIV pre-exposure prophylaxis reduce adherence failure in mobile populations.
- EMA PRIME designation acceleration:Priority medicines status compresses review timelines for bacteriophage therapy candidates.
Industry Challenges
- Microbiology talent scarcity:Specialized clinical trial investigators for multidrug-resistant organism studies remain concentrated in academic medical centers.
- Regulatory divergence:Discordant resistance breakpoint standards between FDA and EMA complicate unified clinical development strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infectious Disease Treatments Market |
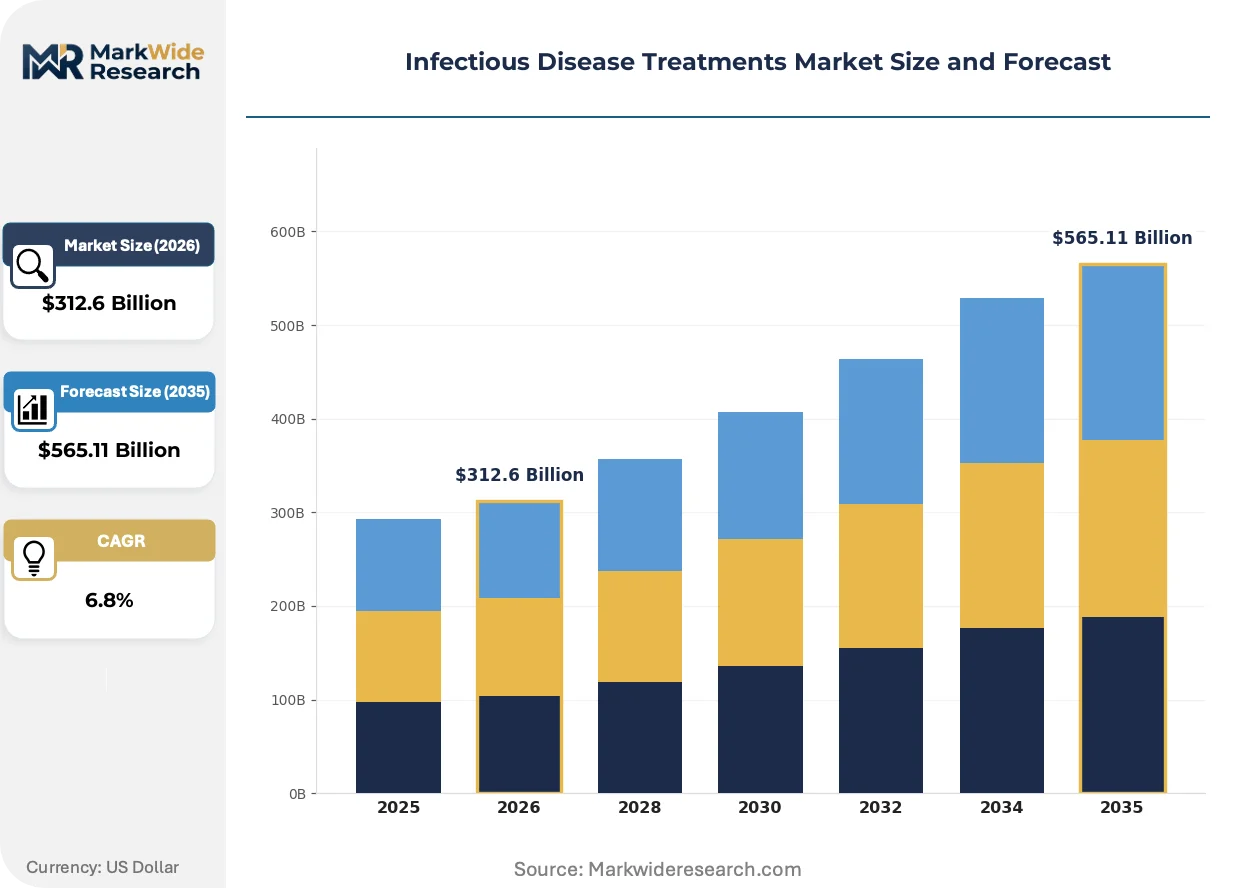
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $565.11 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibacterials, Antivirals, Antifungals, Antiparasitics Delivery Mode: Injectable, Oral, Topical, Inhalation End User: Hospitals, Clinics, Home Care, Research Laboratories Therapy Area: HIV, Tuberculosis, Malaria, Hepatitis |
| Companies Covered | Pfizer Inc., Gilead Sciences, Inc., Merck & Co., Inc., F. Hoffmann-La Roche Ltd, Novartis AG, GlaxoSmithKline plc, Sanofi S.A., AstraZeneca plc, AbbVie Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infectious Disease Treatments Market Strategic Shifts
RNA-targeting platforms and rapid diagnostic integration are compressing therapeutic development cycles and reshaping how prescribers match agents to pathogen profiles.
mRNA vaccine manufacturing infrastructure is consolidating infectious disease R&D pipelines. Pharmaceutical developers repurposed pandemic-era lipid nanoparticle capacity toward seasonal influenza and cytomegalovirus candidates. Hospital procurement committees now prioritize suppliers with demonstrated nucleic acid platform adaptability.
EMA's PRIME designation pathway is compressing development timelines for antibacterial therapies addressing unmet resistance threats. Sponsors receive accelerated scientific advice and priority review status. Small and mid-cap developers leverage this framework to secure early hospital formulary commitment before Phase III completion.
Diagnostic-guided stewardship protocols are displacing empirical broad-spectrum prescribing in tertiary care. Rapid PCR-based resistance detection cuts time-to-appropriate therapy from days to hours. German and Dutch hospital networks lead adoption, with procurement contracts now bundling assay platforms with restricted antibiotic access rights.
Infectious Disease Treatments Market Segmentation
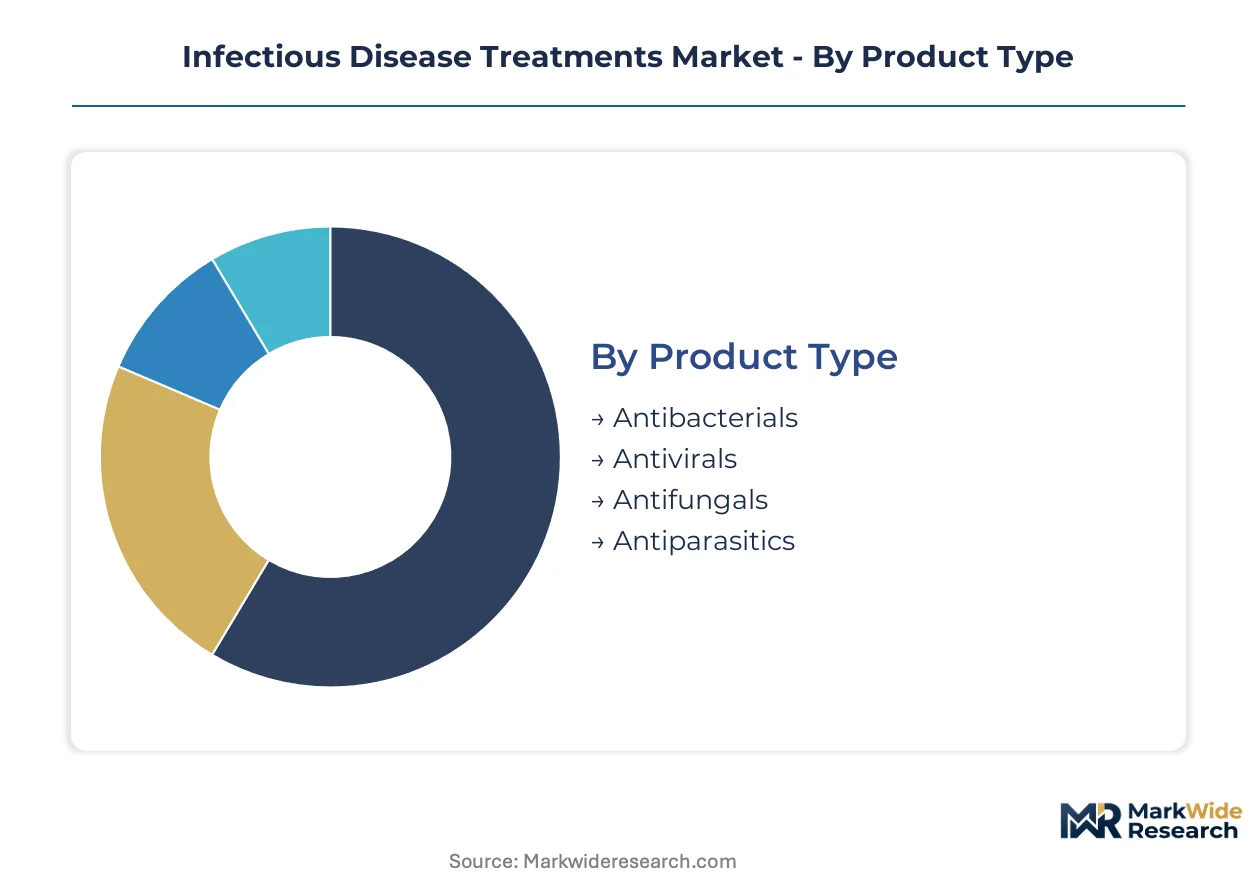
Segmentation in infectious disease treatments determines procurement pathways, regulatory requirements, and reimbursement eligibility. Hospital formularies classify products by delivery mode and resistance profile, while national immunization programs filter access by therapy area and end-user setting.
Product Type:
Certification burdens diverge sharply: antibacterials face FDA Qualified Infectious Disease Product and EMA PRIME scrutiny for novel mechanisms, while antivirals navigate accelerated pathways for RNA-targeting platforms. Antifungals and antiparasitics typically follow standard review timelines with WHO prequalification for tropical disease indications.
- Antibacterials:Beta-lactam, macrolide, and fluoroquinolone formulations dominate empirical prescribing in tertiary care. Stewardship mandates in German and Dutch hospital networks compress usage windows, favoring rapid diagnostic-guided narrow-spectrum agents over broad-spectrum coverage.
- Antivirals:Nucleoside analogs and protease inhibitors target HIV, hepatitis, and emerging RNA pathogens. India's PLI scheme expands domestic API-to-finished-dose capacity for tenofovir and dolutegravir combinations, reducing import dependency for government immunization programs.
- Antifungals:Azole and echinocandin classes address candidiasis and aspergillosis in immunocompromised patients.
- Antiparasitics:Artemisinin-based combination therapies and anthelmintics serve malaria and neglected tropical disease protocols.
Leading the category by volume: antibacterials. Expanding most quickly: antivirals.
Delivery Mode:
Cost tiers separate acute hospital administration from outpatient chronic management, with injectable platforms commanding premium pricing for intensive care applications.
- Injectable:Intravenous and intramuscular formulations deliver rapid bioavailability for sepsis, meningitis, and surgical prophylaxis. Hospital procurement committees in the US and Germany bundle depot antiretroviral access with adherence monitoring contracts for HIV pre-exposure prophylaxis.
- Oral:Fixed-dose combinations for tuberculosis and HIV enable directly observed therapy in resource-limited settings. India's domestic manufacturing scale drives cost compression for government tenders.
- Topical:Creams and ointments address localized fungal and bacterial skin infections in outpatient dermatology.
- Inhalation:Nebulized antivirals and antifungals target respiratory tract colonization in cystic fibrosis and transplant populations.
Dominant by revenue: injectable. Gaining share fastest: oral formulations for resistant tuberculosis management.
End User:
Application requirements shape product specifications: hospitals demand multidose vials and cold-chain stability, while home care prioritizes patient-administered oral regimens with minimal monitoring.
- Hospitals:Tertiary care centers deploy rapid diagnostic-guided therapy selection under antimicrobial stewardship mandates. FDA and EMA resistance breakpoint standards directly filter formulary access for novel Gram-negative agents.
- Clinics:Outpatient infusion centers administer long-acting injectable antiretrovirals and parenteral antibiotics.
- Home Care:Self-administered oral antivirals for HIV and hepatitis C reduce facility burden. WHO prequalification enables procurement for community-based treatment programs in Sub-Saharan Africa.
- Research Laboratories:Reference centers conduct resistance surveillance and clinical trial site networks for multidrug-resistant organism studies.
Highest volume concentration: hospitals. Steepest expansion trajectory: home care.
Therapy Area:
Geographic disease burden determines manufacturing allocation and regulatory priority: HIV and tuberculosis drive volume in low-income country tenders, while hepatitis commands premium pricing in insured markets.
- HIV:Combination antiretroviral therapy requires sustained manufacturing scale for tenofovir, emtricitabine, and integrase inhibitor platforms. India's API producers supply pediatric fixed-dose combinations meeting WHO prequalification standards for public procurement.
- Tuberculosis:First-line and multidrug-resistant regimens demand six-to-twenty-four month adherence protocols. Bedaquiline and delamanid access expands through EMA compassionate use and national TB program tenders in high-burden countries.
- Malaria:Artemisinin-based combination therapies face resistance surveillance requirements in Sub-Saharan Africa and Southeast Asia.
- Hepatitis:Direct-acting antivirals for hepatitis C achieve sustained virologic response in twelve-week courses, with pricing tiered by national income classification.
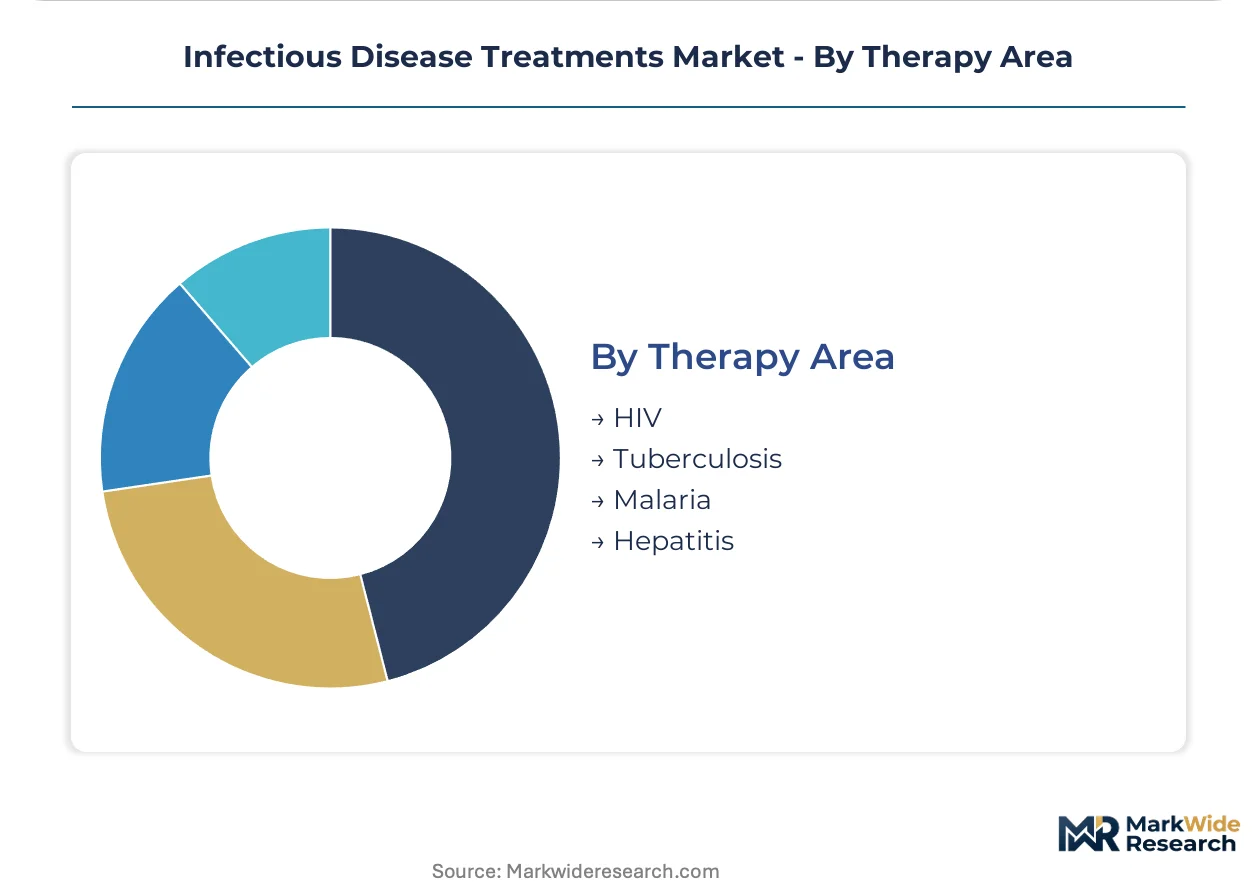
Largest addressable population: HIV. Climbing the fastest: hepatitis C direct-acting antiviral uptake in middle-income markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Penicillin and cephalosporin intermediate production clusters in specific Asian manufacturing zones anchor regional supply chains. Hospital procurement of novel antiviral therapies concentrates in markets with tightened antimicrobial resistance stewardship requirements. Demand scaling is fastest where domestic pharmaceutical manufacturing capacity and government immunization programs intersect.
United States
FDA Qualified Infectious Disease Product incentives drive hospital formulary adoption of novel Gram-negative agents. The FDA's extended exclusivity periods accelerate investments in resistant pathogen therapies. Boston and San Francisco biotech clusters host rapid diagnostic-guided therapy developers integrating PCR-based resistance detection.
Germany
EMA PRIME designation pathways compress review timelines for bacteriophage therapy candidates. German hospital networks lead European adoption of diagnostic-guided stewardship protocols bundling assay platforms with restricted antibiotic access. The Rhine-Ruhr industrial corridor concentrates tertiary care centers deploying rapid time-to-appropriate therapy systems.
India
Domestic API-to-finished-dose capacity expansion targets tuberculosis and HIV therapeutics under the PLI scheme. CDSCO regulatory harmonization with WHO prequalification standards shapes procurement eligibility for government immunization programs. Hyderabad and Ahmedabad pharmaceutical clusters scale tenofovir and dolutegravir combination output for pediatric fixed-dose tenders.
Switzerland
Swissmedic priority review frameworks attract developers of emerging pathogen preparedness vaccines. Basel anchors vaccine-adjuvant combination manufacturing scale for international procurement. The country's precision medicine infrastructure supports clinical trial site networks for multidrug-resistant organism studies.
Brazil
ANVISA regulatory pathways filter market access for generic manufacturers targeting outpatient infectious disease management. São Paulo and Rio de Janeiro hospital networks deploy empirical broad-spectrum prescribing compression protocols. The country's national immunization program tenders drive volume contracts for antiretroviral fixed-dose combinations.
Infectious Disease Treatments Market Competitive Environment
Global majors compete with regional champions across manufacturing scale and regulatory exclusivity positioning. The vendor base stratifies into three tiers: vertically integrated penicillin-class suppliers, RNA-targeting platform specialists, and generic finished-dose formulators serving public procurement. Dominant competitive moves include backward integration into API supply and strategic partnerships for long-acting injectable platform access.
Within the vertically integrated tier, Pfizer Inc. and Gilead Sciences, Inc. occupy positions securing raw material access and sustained R&D intensity respectively. Merck & Co., Inc. anchors the vaccine-adjuvant manufacturing scale archetype for emerging pathogen preparedness. These three exemplify how regulatory exclusivity timing and resistance surveillance data alignment determine pipeline investment prioritization.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Gilead Sciences, Inc. |
| Merck & Co., Inc. |
| F. Hoffmann-La Roche Ltd |
| Novartis AG |
| GlaxoSmithKline plc |
| Sanofi S.A. |
| AstraZeneca plc |
| AbbVie Inc. |
| Others |
Value Chain & Pricing Dynamics
Penicillin-class intermediate costs cascade from concentrated Asian manufacturing zones through three distinct pricing tiers: premium novel Gram-negative agents with FDA Qualified Infectious Disease Product exclusivity, standard stewardship-compliant formulations, and economy generic antibiotics under tender pressure. API-to-finished-dose conversion economics in India compress mid-tier margins while hospital procurement committees in Germany and the United States bundle rapid diagnostic platforms with restricted antibiotic access rights.
Pricing Analysis
Warranty and service bundling separates premium novel mechanism therapies from unbundled commodity generics. Three-tier pricing structure across premium, standard, and economy levels reflects FDA QIDP certification status, volume scale, and geographic delivery cost. Cost compression in the economy tier intensifies because Indian PLI scheme output floods government tender markets. Public procurement programs in Sub-Saharan Africa exhibit highest price sensitivity; hospital formulary committees in tertiary US centers demonstrate lowest sensitivity due to bundled diagnostic access.
Supply Chain Analysis
Specialized microbiology talent availability in Hyderabad, Basel, and Boston anchors API synthesis and clinical trial site networks. Active pharmaceutical ingredient production draws from penicillin and cephalosporin intermediate clusters in India and China, with finished-dose formulation capacity expanding in Ahmedabad and São Paulo. Single-source vulnerability in beta-lactam intermediate supply creates structural risk. Distribution runs through hospital procurement committees, government immunization program tenders, and outpatient pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA Qualified Infectious Disease Product exclusivity periods erect a cost-of-compliance barrier that rewards sustained R&D investment while filtering out capital-constrained challengers. This regulatory moat deepens as antimicrobial resistance surveillance networks tighten empirical prescribing windows worldwide.
For Market Incumbents: To counter generic substitution pressure in fluoroquinolone and macrolide categories, secure backward integration into penicillin-class API supply and expand manufacturing scale in vaccine-adjuvant combinations for emerging pathogen preparedness. CDSCO harmonization with WHO prequalification standards in India offers channel control leverage for pediatric fixed-dose combination tenders. For New Entrants and Emerging Players: The price-point gap between premium novel Gram-negative agents and economy generic antibiotics opens white-space in oral formulations for multidrug-resistant tuberculosis management. Target Sub-Saharan Africa public procurement through WHO prequalification pathways. Pursue EMA PRIME designation acceleration for bacteriophage therapy candidates as the fastest regulatory entry mechanism. For Investors and Strategic Acquirers: EMA PRIME designation grants for bacteriophage candidates are the leading indicator that novel mechanism platforms will secure early hospital formulary commitment before Phase III completion. Long-term viability across the analysis window favors developers with demonstrated nucleic acid platform adaptability. RNA-targeting specialists with depot formulation capabilities represent priority acquisition archetypes. Watch FDA resistance breakpoint standard revisions as the trigger for therapeutic substitution protocol shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates Phase III completion for resistant Gram-negative candidates under FDA QIDP incentives. |
| Regulatory Approval Pathway | EMA PRIME designation compresses review timelines for priority antibacterial therapies. |
| Manufacturing Scale-Up | Indian PLI scheme subsidies expand tenofovir and dolutegravir output for government tenders. |
| Pipeline Diversification | Long-acting injectable platforms for HIV pre-exposure prophylaxis reduce adherence failure rates. |
| Strategic Partnership | Hospital network bundling of rapid PCR diagnostics with restricted antibiotic access secures formulary position. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists combined with FDA filings, EMA submissions, ClinicalTrials.gov entries, and formulary databases. Bottom-up patient population modeling and top-down pharmaceutical expenditure tracking were triangulated for consistency.
Granularity-level modeling operated at the intersection of product type, delivery mode, end-user setting, therapy area, and regional regulatory cluster. Volume and value outputs were derived through patient-flow analysis, treatment protocol adherence assumptions, and procurement tender tracking across the projection horizon. CAGRs were calculated from segmented baseline estimates and projected standard-of-care protocol shifts. Resistance surveillance network data and exclusivity cliff timing served as key forecast inputs.
Inputs from FDA, EMA, and WHO sources were available through the study window; gaps in real-time resistance surveillance introduce uncertainty bands around novel mechanism adoption curves. Forecasts reflect documented assumptions regarding regulatory pathway durations, procurement cycle timing, and stewardship mandate enforcement intensity. Pipeline advancement delays, API supply disruptions, or divergence in FDA-EMA resistance breakpoint standards warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infectious Disease
Retropharyngeal Abscess Market
Infectious Disease
Communicable Diseases Treatment Market
Infectious Disease
Point-Of-Care Infectious Disease Testing Market
Infectious Disease
Chikungunya Fever Market
Infectious Disease
Mycobacterium Infections Treatment Market
Infectious Disease
Global Acute Bacterial Skin and Skin Structure Infection (ABSSSI) Market
Infectious Disease
Infectious Disease Diagnostics Market
Infectious Disease
Efavirenz Market
Infectious Disease
Coxsackievirus Infections Treatment Market
Infectious Disease
Toxoplasmosis Infection Treatment Market
Infectious Disease
Arthropod Borne Viral Infections Market
Infectious Disease
APAC Infectious Disease Diagnosis & Treatment Market
Infectious Disease
Measles Market
Infectious Disease
Viral Hemorrhagic Fever Market
Infectious Disease
Virology Market
Infectious Disease
Italy Infectious Disease in-Vitro Diagnostics Market