
 HDPE Corrugated Pipe Market | 2026-2036
HDPE Corrugated Pipe Market Size, Share, and Industry Trends Forecast 2026-2036
HDPE Corrugated Pipe Market Insights
Market Context
Skilled polymer welding technicians is reorganizing capacity expansion timelines across HDPE corrugated pipe manufacturing. Advanced Drainage Systems leverages vertical integration from resin to installation to control project margins in North American stormwater contracts. JM Eagle sustains manufacturing scale advantages through continuous extrusion operations across multiple US production facilities. Wavin anchors European demand through specialized drainage solutions tailored to municipal infrastructure standards.
Technical Definition and Segment Structure
HDPE corrugated pipe consists of high-density polyethylene formed into ribbed or annular profiles with hollow sections, manufactured through extrusion or spiral winding processes to achieve ring stiffness ratings between SN2 and SN8 for buried applications. Double wall configurations command the strongest margin pools due to superior crush resistance in deep-burial municipal projects, while single wall variants dominate agricultural drainage where cost sensitivity prevails. Infrastructure end users generate the most stable procurement volumes through multi-year public works programs, whereas mining applications show the fastest specification shift toward smooth interior variants that reduce friction losses in slurry transport.
Regulatory Environment
ASTM F667 and AASHTO M252 govern dimensional and performance standards for corrugated polyethylene pipe in US transportation and drainage applications, while EPA stormwater regulations under the Clean Water Act mandate retention and infiltration systems that specify HDPE components. India's BIS certification requirements for plastic piping create compliance barriers that favor established domestic manufacturers over imports. Stakeholders must monitor evolving state-level procurement rules that increasingly embed lifecycle cost criteria rather than upfront material pricing alone.
Market Dynamics
China's MEE dual carbon goals are forcing concrete-to-polymer substitution in stormwater infrastructure, compressing specification timelines and redrawing competitive positioning across municipal procurement channels.
Growth Catalysts
- EPA Clean Water Act mandates:Retention and infiltration system requirements specify HDPE components for stormwater management, locking in material demand across US transportation projects.
- Jal Jeevan Mission procurement:Rural sanitation drives in India's northern states concentrate demand for corrugated drainage systems in agricultural and village infrastructure.
- Double-wall extrusion advances:Improved ring stiffness ratings enable deeper burial applications, expanding addressable project scope in municipal drainage.
Market Restraints
- Resin price volatility:Ethylene feedstock fluctuations compress margin predictability for extrusion-dependent manufacturers.
- Skilled polymer welder scarcity:Certified technician shortages in North America delay installation capacity and project handoffs.
- Concrete substitution inertia:Municipal engineers in legacy infrastructure markets retain specification bias toward traditional materials despite lifecycle cost disadvantages.
Strategic Opportunities
- Smooth-interior mining applications:Slurry transport specifications favor reduced-friction variants, opening specification shifts in extraction operations.
- India BIS certification barriers:Compliance complexity favors established domestic manufacturers over import competition in government tenders.
- Lifecycle cost procurement rules:State-level public works programs embed total-ownership metrics that reward polymer durability over upfront concrete pricing.
Industry Challenges
- ASTM F667 certification timelines:Dimensional and performance testing protocols create multi-month approval delays for new product variants.
- Continuous extrusion capex intensity:Scale-efficient manufacturing requires substantial capital deployment for multi-facility operations.
- Legacy system integration:Retrofit projects face compatibility friction when connecting corrugated polymer to existing concrete or clay infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HDPE Corrugated Pipe Market |
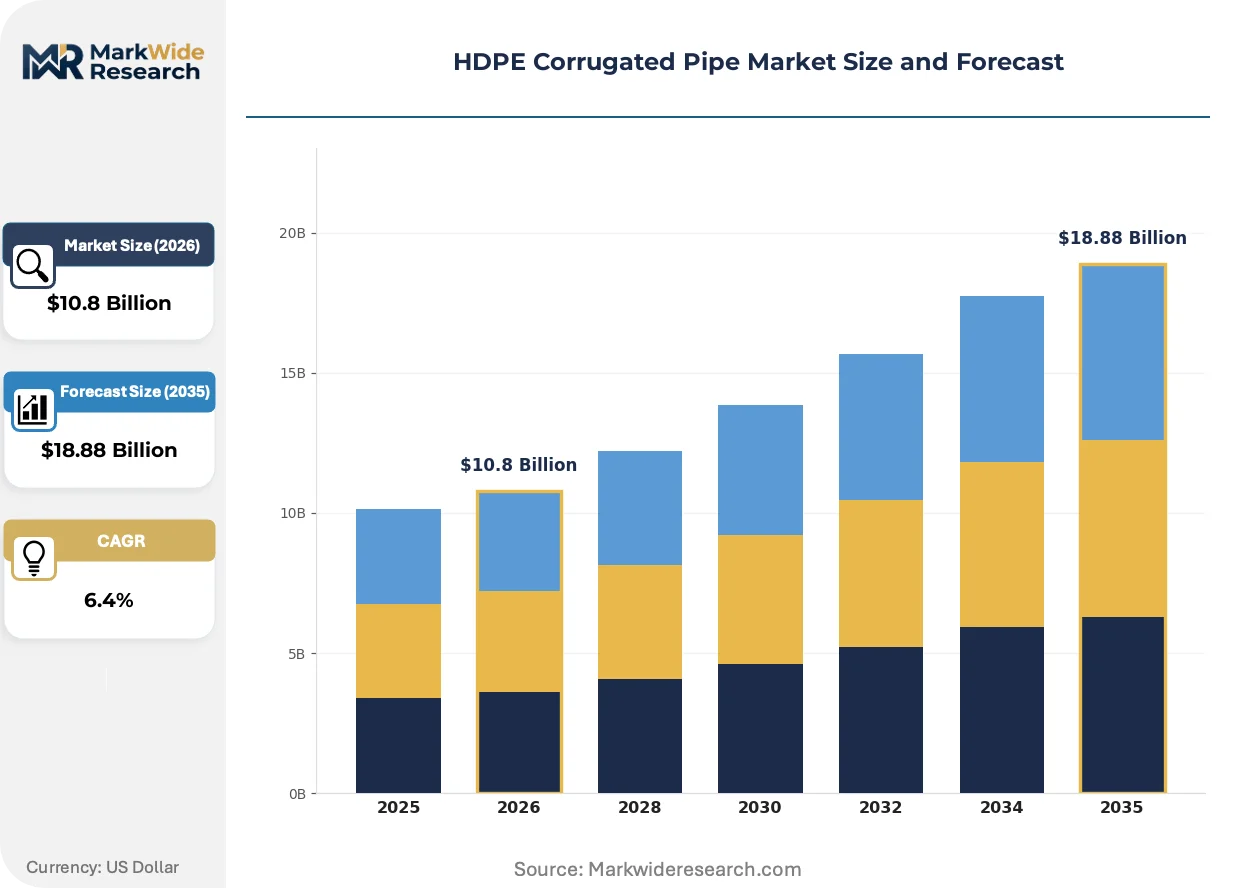
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $18.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Wall, Double Wall, Spiral Pipe, Smooth Interior Application: Drainage, Sewage, Electrical Conduit, Telecom End User: Construction, Agriculture, Mining, Infrastructure Distribution Channel: Direct Sales, Wholesalers, Online Retail, Distributors |
| Companies Covered | Advanced Drainage Systems, Wavin, JM Eagle, Chevron Phillips Chemical Company, WL Plastics, Supreme Industries, Polypipe Group, Uponor, KWH Pipe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HDPE Corrugated Pipe Market Trends and Innovations
Manufacturing precision and material formulation are compressing product differentiation windows, forcing suppliers to anchor value in installation support and specification engineering rather than commodity pipe alone.
Co-extrusion barrier technology is miniaturizing multilayer wall structures without sacrificing ring stiffness, enabling lighter transport and faster field handling. Municipal contractors in the United States specify these profiles for trenchless installation methods. Equipment suppliers report order backlogs for co-extrusion lines stretching eighteen months.
China's MEE dual carbon implementation timeline is accelerating concrete displacement mandates in provincial stormwater tenders. Municipal design bureaus face binding emissions targets that penalize high-carbon materials. Polymer system suppliers report specification wins in tier-two and tier-three city procurement.
Engineering firms bundle material supply with hydraulic modeling and installation supervision, unbundling the traditional product-only sale. US municipal clients favor single-source accountability for drainage performance outcomes. This service-layer attachment is compressing pure-manufacturer margins while rewarding vertically capable suppliers.
HDPE Corrugated Pipe Market Segmentation
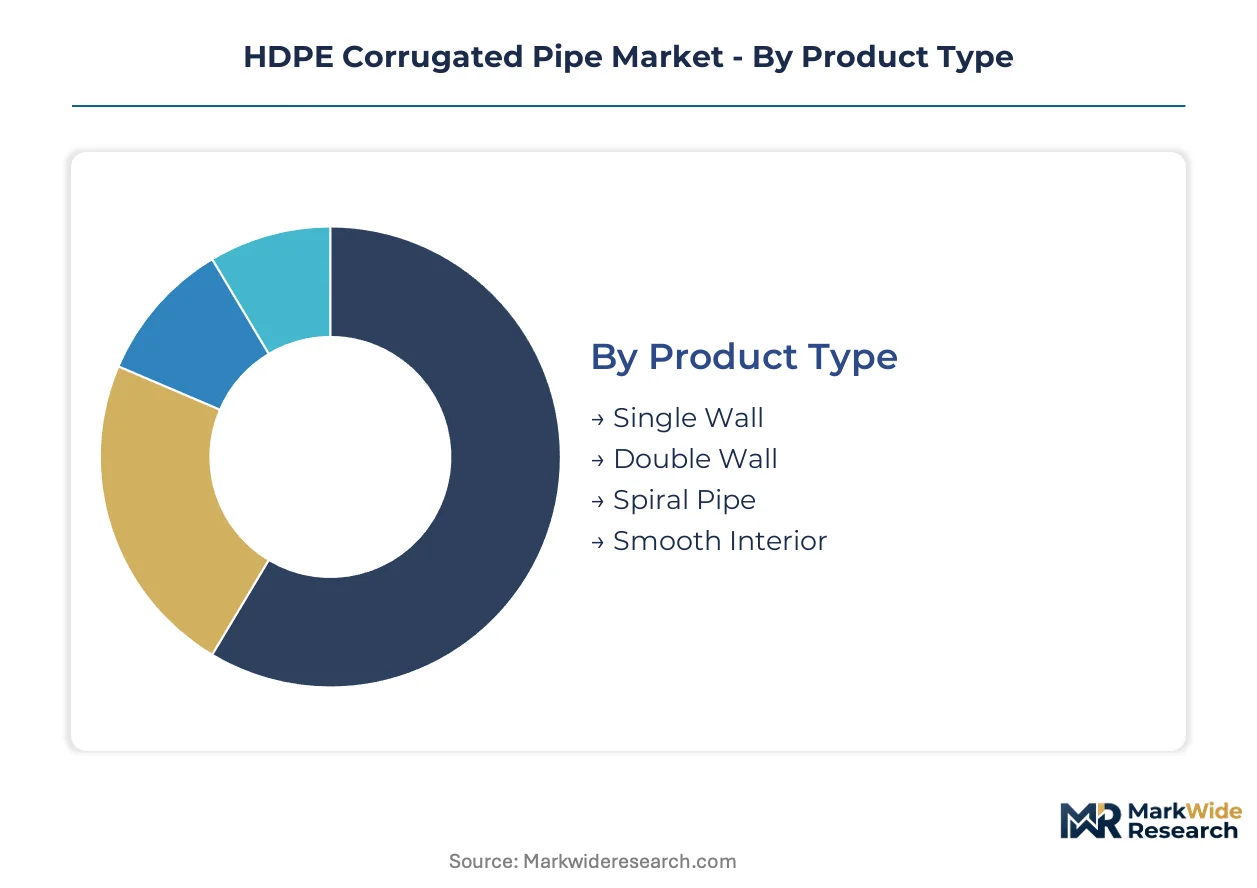
HDPE corrugated pipe procurement flows through distinct channel architectures that reshape competitive positioning. Product specifications vary sharply by burial depth and load-bearing requirements, while end-user categories determine margin durability through contract structure and volume predictability.
Product Type:
Double-wall configurations move primarily through direct sales channels for municipal contracts, while single-wall variants flow through distributor networks serving agricultural and residential contractors. Spiral pipe and smooth-interior grades occupy specialized procurement channels tied to engineering specifications.
- Double Wall:Co-extruded profiles with corrugated exterior and smooth interior achieve SN4 to SN8 ring stiffness ratings. Municipal drainage projects in the United States specify these for deep-burial applications where crush resistance determines material selection. China's provincial stormwater tenders under MEE dual carbon mandates are accelerating displacement of reinforced concrete.
- Single Wall:Annular-corrugated profiles manufactured through continuous extrusion deliver cost-optimized drainage for shallow burial. Agricultural drainage contractors in India's northern states procure these through Jal Jeevan Mission rural sanitation programs where upfront cost sensitivity dominates specification.
- Spiral Pipe:Helically wound profiles with integrated bell-and-spigot joints accommodate large-diameter civil engineering projects.
- Smooth Interior:Reduced-friction bores engineered for slurry transport and high-velocity flow applications.
Single Wall dominates installed base. Double Wall is where expansion concentrates.
Application:
Drainage and sewage applications generate recurring public works procurement through multi-year infrastructure programs. Electrical conduit and telecom segments follow distinct specification pathways tied to utility engineering standards rather than civil works criteria.
- Drainage:Stormwater retention and infiltration systems specified under EPA Clean Water Act mandates require HDPE components for permeability and installation speed. State transportation departments embed lifecycle cost criteria that favor polymer durability over concrete in roadside culvert replacement.
- Sewage:Gravity sewer lines and force mains demand corrosion-resistant profiles for aggressive effluent environments. India's BIS certification requirements create compliance barriers that concentrate government tender awards among established domestic manufacturers.
- Electrical Conduit:Encased ducting for underground power distribution with dielectric insulation properties.
- Telecom:Protective casing for fiber-optic cable burial in rights-of-way.
Drainage commands the largest project volumes. Sewage is climbing the fastest on replacement-driven specification.
End User:
Infrastructure and construction end users anchor volume through specification engineering relationships, while agriculture and mining follow price-competitive procurement with shorter contract cycles.
- Infrastructure:Municipal agencies and transportation authorities procure through formal bidding processes with multi-year delivery schedules. China's tier-two and tier-three cities are redrawing competitive positioning as MEE emissions targets penalize high-carbon concrete systems in provincial tenders.
- Construction:Residential and commercial developers source through distributor networks with just-in-time delivery requirements. Skilled polymer welder scarcity in North America compresses installation capacity and extends project handoff timelines.
- Agriculture:Farm drainage and irrigation systems prioritize cost-per-foot metrics over engineered specifications.
- Mining:Slurry transport operations specify smooth-interior variants to reduce friction losses and pumping energy.
Infrastructure dominates installed base. Mining is where specification expansion concentrates.
Distribution Channel:
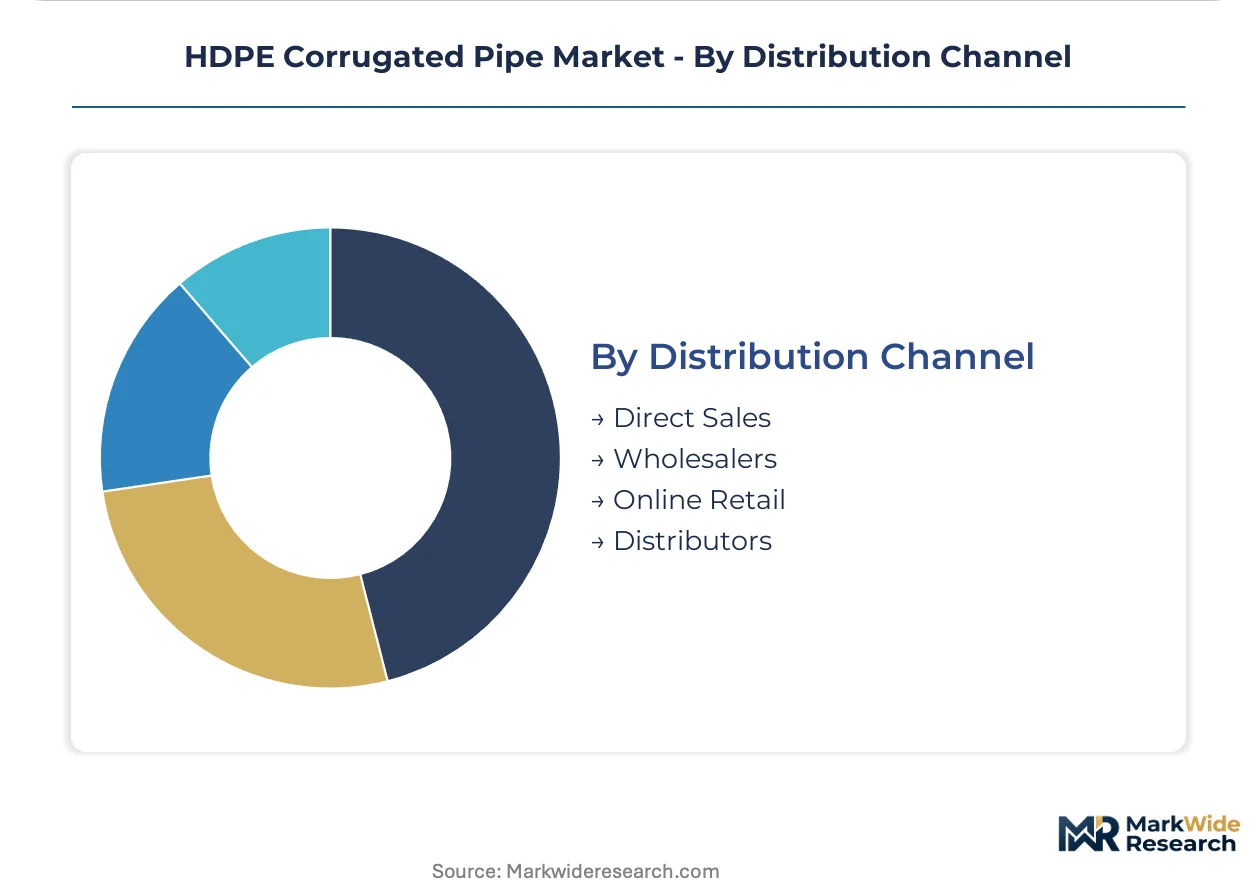
Channel selection correlates with project scale and specification complexity. Direct sales capture engineered municipal contracts, while wholesaler and distributor networks serve fragmented agricultural and residential demand.
- Direct Sales:Manufacturer-to-contractor relationships for large-diameter municipal projects requiring hydraulic modeling and installation supervision. Advanced Drainage Systems leverages vertical integration from resin to installation to control project margins.
- Wholesalers:Regional inventory positions serving mid-scale contractors with standard dimension ratios and ring stiffness ratings. JM Eagle sustains manufacturing scale advantages through continuous extrusion operations feeding these channels.
- Distributors:Local stocking points for small-diameter agricultural and residential drainage with rapid fulfillment requirements.
- Online Retail:Emerging channel for standardized fittings and repair components with documented specifications.
Direct Sales dominates engineered project value. Distributors capture the broadest transaction volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA stormwater regulations and China's MEE dual carbon mandates are redrawing procurement geography for HDPE corrugated pipe systems. Municipal infrastructure spending concentrates in North American and Asian markets where regulatory pressure accelerates polymer substitution.
United States
Municipal drainage contractors in the United States specify double-wall configurations for deep-burial transportation projects. State transportation departments embed lifecycle cost criteria under EPA Clean Water Act implementation that favor polymer durability over concrete culvert replacement. Advanced Drainage Systems leverages vertical integration from resin to installation to capture stormwater contract margins across the Midwest and Southeast.
China
Provincial stormwater tenders in tier-two and tier-three cities are accelerating concrete displacement under MEE dual carbon enforcement timelines. Municipal design bureaus face binding emissions targets that penalize high-carbon materials in procurement scoring. Manufacturing clusters in the Yangtze River Delta and Pearl River Delta are scaling co-extrusion capacity to serve provincial infrastructure budgets.
India
Rural sanitation procurement under Jal Jeevan Mission concentrates demand in northern states for agricultural and village drainage systems. BIS certification requirements for plastic piping create compliance barriers that favor established domestic manufacturers over import competition. Industrial corridors in Gujarat and Maharashtra anchor production capacity for government tender fulfillment.
Germany
Municipal engineering standards in Germany specify ring stiffness ratings for buried drainage applications that reward material durability. EU Green Deal implementation pressures local authorities to reduce embodied carbon in infrastructure procurement. Engineering clusters in North Rhine-Westphalia and Bavaria anchor specification engineering relationships with municipal clients.
Canada
Transportation authorities in Ontario and British Columbia specify HDPE components for roadside culvert replacement programs. Provincial procurement rules increasingly embed total-ownership metrics that reward polymer performance over upfront material pricing. Installation capacity constraints in the Prairie Provinces compress project handoff timelines for municipal contractors.
HDPE Corrugated Pipe Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the HDPE corrugated pipe market. Vertically integrated resin-to-installation operators capture engineered municipal contracts through specification control, while scale-focused extruders dominate agricultural and residential channels through distributor networks. The competitive terrain separates into three archetypes: full-service infrastructure specialists, continuous-extrusion scale manufacturers, and regional fabrication specialists. Dominant competitive moves include backward integration into resin supply and geographic expansion through co-extrusion line deployment.
Among North American infrastructure specialists, Advanced Drainage Systems and JM Eagle exemplify contrasting scale strategies. Advanced Drainage Systems occupies a position as a vertically integrated operator controlling project margins from material supply through installation supervision. JM Eagle represents the continuous-extrusion scale archetype sustaining manufacturing advantages across multiple production facilities. European demand anchors through Wavin, which sits within the specialized drainage solutions tier serving municipal infrastructure standards.
| Leading Market Players |
|---|
| Advanced Drainage Systems |
| Wavin |
| JM Eagle |
| Chevron Phillips Chemical Company |
| WL Plastics |
| Supreme Industries |
| Polypipe Group |
| Uponor |
| KWH Pipe |
| Others |
Pricing and Supply Chain Analysis
Project-based municipal contracts lock in multi-year resin supply commitments and stabilize margin visibility for extrusion-dependent manufacturers facing ethylene feedstock fluctuations. China's MEE dual carbon procurement scoring and India's Jal Jeevan Mission tender structures embed lifecycle cost criteria that compress pure-commodity pricing power while rewarding installation-service bundling.
Pricing Analysis
Price spreads between North American and Asian HDPE corrugated pipe markets reflect freight differentials and regional resin cost structures rather than specification gaps. Contract-based long-term offtake dominates municipal infrastructure procurement, with price differentiation anchored in ring stiffness certification tiers and installation supervision depth. Pricing pressure stems from concrete substitution inertia among legacy municipal engineers, though state-level lifecycle cost rules in the United States soften buyer price sensitivity for infrastructure end users compared to agricultural contractors.
Supply Chain Analysis
Gulf Coast ethylene production and Yangtze River Delta resin processing constitute critical chokepoints for global HDPE corrugated pipe manufacturing. Supply concentration in the United States, China, and Germany feeds continuous extrusion operations that draw from ethylene feedstock, co-extrusion equipment, and certified polymer welding technician pools. Single-source vulnerability runs through specialized co-extrusion line manufacturers facing eighteen-month order backlogs. Distribution runs through direct sales for engineered municipal contracts and wholesaler networks for fragmented agricultural demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
HDPE corrugated pipe incumbents must defend against concrete substitution campaigns backed by legacy municipal engineer relationships and upfront cost bias in public procurement scoring.
For Market Incumbents: Compound specification control through captive resin supply and installation supervision bundling that concrete competitors cannot replicate. Secure ASTM F667 certification pipelines for co-extruded variants before provincial tender deadlines in China. Deepen backward integration into ethylene feedstock to buffer margin compression from resin price volatility. For New Entrants and Emerging Players: Differentiate on smooth-interior mining applications where slurry transport specifications favor reduced-friction engineering over commodity drainage profiles. Target India's BIS-certified domestic manufacturing tier where compliance barriers shield from import competition. Lead with hydraulic modeling services that unbundle pure-product sales and anchor municipal client relationships. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated resin-to-installation operators with proven specification engineering relationships in tier-two Chinese cities and Midwest US transportation departments. Five-to-ten year viability hinges on co-extrusion technology leadership and provincial emissions mandate enforcement velocity. Watch for MEE dual carbon procurement scoring adoption rates as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Captive ethylene sourcing insulates margin predictability from Gulf Coast feedstock volatility. |
| Co-Extrusion Capacity Expansion | Additional production lines in Yangtze River Delta clusters capture China's provincial stormwater tender acceleration. |
| Installation Supervision Bundling | Engineering service layers compress pure-manufacturer margins while locking municipal client retention. |
| BIS Certification Investment | Compliance positioning secures Jal Jeevan Mission government tender awards against import competition. |
| Smooth-Interior Product Line Development | Reduced-friction variants penetrate mining slurry transport specifications with faster specification velocity. |
Research Methodology
Initial hypotheses were tested against primary input from municipal procurement officers, polymer welding technicians, co-extrusion equipment suppliers, and stormwater engineering consultants and refined through secondary validation. Trade data from USITC and China's General Administration of Customs, ASTM and AASHTO standards documentation, and provincial tender databases in Hebei and Guangdong anchored supply-side triangulation. Bottom-up project pipeline assessments and top-down resin consumption models converged on volume estimates.
Variance decomposition across ring stiffness tiers, end-use applications, and regional regulatory clusters structured the analytical framework. CAGRs derived from installed base replacement cycles and new infrastructure budget trajectories modeled demand elasticity to MEE dual carbon enforcement and EPA Clean Water Act implementation. Ethylene feedstock cost curves and co-extrusion line deployment schedules fed capacity-expansion assumptions.
The analysis sits within stated boundaries; outcomes outside sustained provincial emissions mandate enforcement in China and state-level lifecycle cost procurement adoption in the United States would require recalibration. Forecasts reflect documented assumptions regarding concrete substitution velocity and skilled technician availability. Practitioners should keep alternative scenarios live as MEE procurement scoring rules and ASTM certification timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
GCC CPVC Pipes Market
Pipes and Tubes
Gas Pipe Fittings Market
Pipes and Tubes
Global Tracer Wires Market
Pipes and Tubes
Plastic Pipes and Fittings Market
Pipes and Tubes
FRP Pipes and Tanks Market
Pipes and Tubes
Global Polyethylene Pipes and Fittings Market
Pipes and Tubes
Glass Reinforced Plastic (GRP) Piping Market
Pipes and Tubes
Saudi Arabia PVC Pipes Market
Pipes and Tubes
Plastic Pipe Jointing and Welding Market
Pipes and Tubes
Global Flexible Pipes Market
Pipes and Tubes
GCC Polyethylene (PE) Pipes Market
Pipes and Tubes
Glass Reinforced Epoxy (GRE) Pipes Market
Pipes and Tubes
Kuwait PVC Pipes Market
Pipes and Tubes
Global Titanium Tube Market
Pipes and Tubes
Hot Dip Galvanized Steel Pipe Market
Pipes and Tubes
North America Hydraulic Fluid Connectors Market