
 India Process Piping Market | 2026-2036
India Process Piping Market Size, Share, and Industry Trends Forecast 2026-2036
India Process Piping Market Insights
Aftermarket service revenue is narrowing the margin gap with new pipe fabrication as plant operators extend asset life cycles. DEE Piping Systems leverages its coastal fabrication yards to anchor large-diameter contracts for oil terminals. Apollo Pipes Limited competes aggressively in PVC process lines for chemical handling applications. Electrosteel Castings Limited sustains its foundry-to-finish vertical model across ductile iron pressure piping.
Process piping encompasses welded and seamless conduit systems engineered to transport fluids, gases, and slurries under defined pressure-temperature ratings, typically fabricated from carbon steel, stainless steel, or thermoplastic compounds with wall schedules ranging from SCH 10 to SCH 160. These networks form the circulatory backbone of refineries, water treatment plants, and pharmaceutical sterile processing facilities, where leak integrity and corrosion resistance determine operational uptime. Stainless steel piping for chemical processing applications commands premium margins due to Mo-bearing grades and orbital welding requirements, while carbon steel remains the volume anchor across oil and gas gathering networks. PVC process piping for water treatment infrastructure is gaining specification share as municipalities prioritize corrosion-free conveyance and reduced cathodic protection burdens.
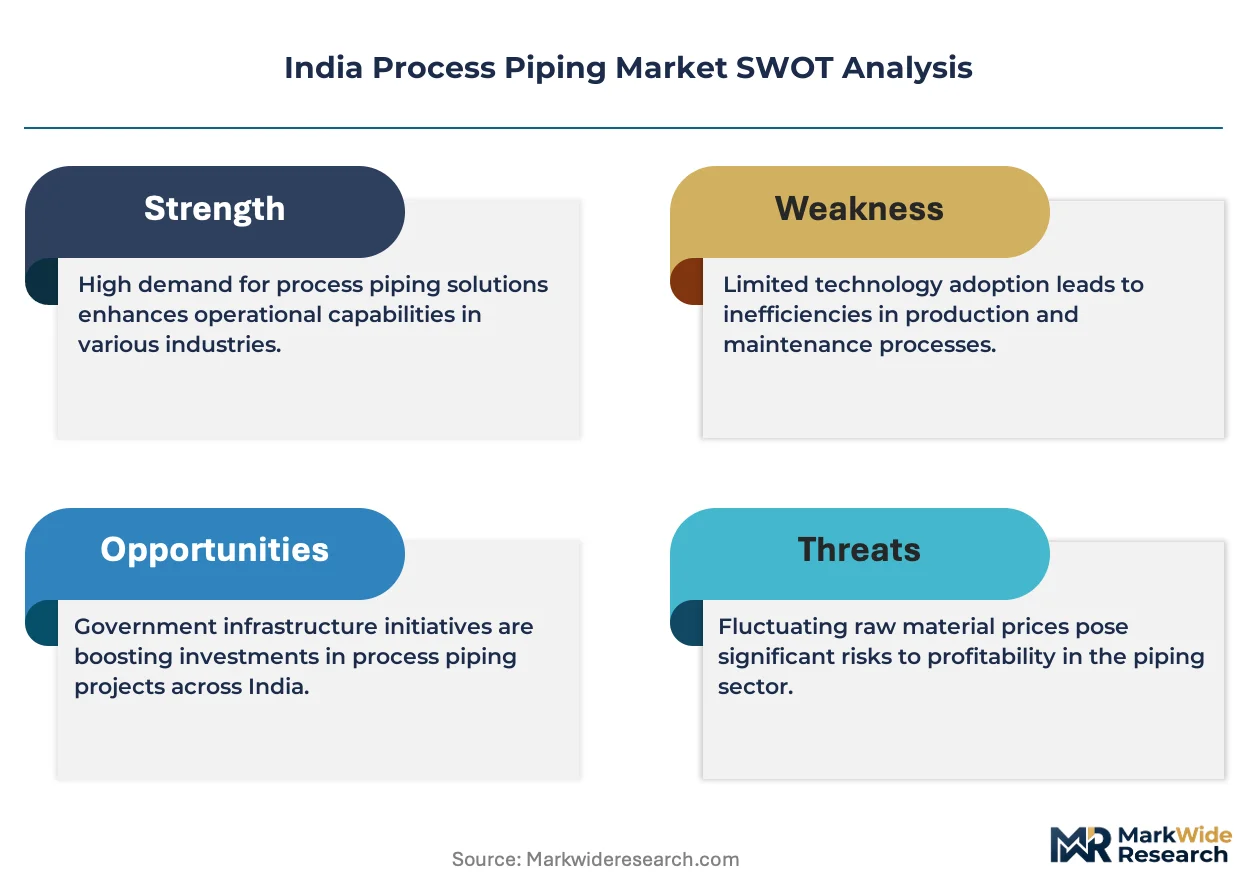
BIS pressure equipment standards, CEA thermal power regulations, and the Petroleum and Natural Gas Regulatory Board pipeline safety codes collectively mandate material traceability, hydrostatic testing protocols, and welder qualification records for all process piping installations. These compliance layers elevate entry barriers for unorganized fabricators while creating specification pull for BIS-certified mills and approved welding contractors. Stakeholders must monitor evolving PLI scheme disbursements for specialty steel production, as domestic alloy availability will determine whether import dependence for critical grades narrows or persists through the forecast horizon.
Market Dynamics
Refinery capacity expansions by Indian Oil and Reliance Industries are pulling high-pressure alloy piping systems into the installed base faster than domestic mills can qualify new heats, creating a structural tension between project timelines and BIS certification throughput.
Growth Catalysts
- CEA thermal power regulations:Mandated efficiency upgrades are forcing supercritical boiler retrofits that require P91 and P92 chrome-moly piping grades, opening specification windows for specialized fabricators.
- Dahej petrochemical cluster:Greenfield investments in Gujarat's chemical corridor are concentrating demand for corrosion-resistant stainless systems in a single geography with logistics advantages.
- Orbital welding automation:Reduced welder-hour requirements on high-purity process lines are compressing project schedules and expanding addressable contract volume for qualified contractors.
Market Restraints
- Specialty steel import dependence:Domestic mills lack consistent production capability for duplex and super-duplex grades, forcing project owners to absorb currency volatility and extended lead times from European and Japanese suppliers.
- BIS certification bottlenecks:Pressure equipment material approvals average 14-18 months, delaying commercialization of newly developed domestic alloy formulations and preserving import reliance.
- Thermoplastic substitution in water handling:PVC and CPVC systems are capturing specification share in municipal and light chemical applications where pressure-temperature ratings permit non-metallic solutions.
Strategic Opportunities
- Andhra Pradesh pharma corridor:Sterile processing facility expansions in Visakhapatnam create demand for electropolished 316L tubing with orbital weld documentation that domestic fabricators are only beginning to address.
- PLI scheme for specialty steel:Disbursement acceleration would incentivize domestic mill investment in nickel-alloy production, narrowing the import gap for critical chemical service grades.
- Digital twin integration:Convergence of piping stress analysis software with IoT sensor networks enables predictive maintenance contracts that extend fabricator relationships beyond installation.
Industry Challenges
- Orbital welder certification scarcity:The Petroleum and Natural Gas Regulatory Board's qualification requirements for high-pressure hydrogen service exceed current training pipeline output, constraining project execution capacity.
- Material traceability system integration:Fabricators must reconcile BIS mill test certificates with end-user ERP platforms, creating documentation friction that delays final acceptance and payment release.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Process Piping Market |
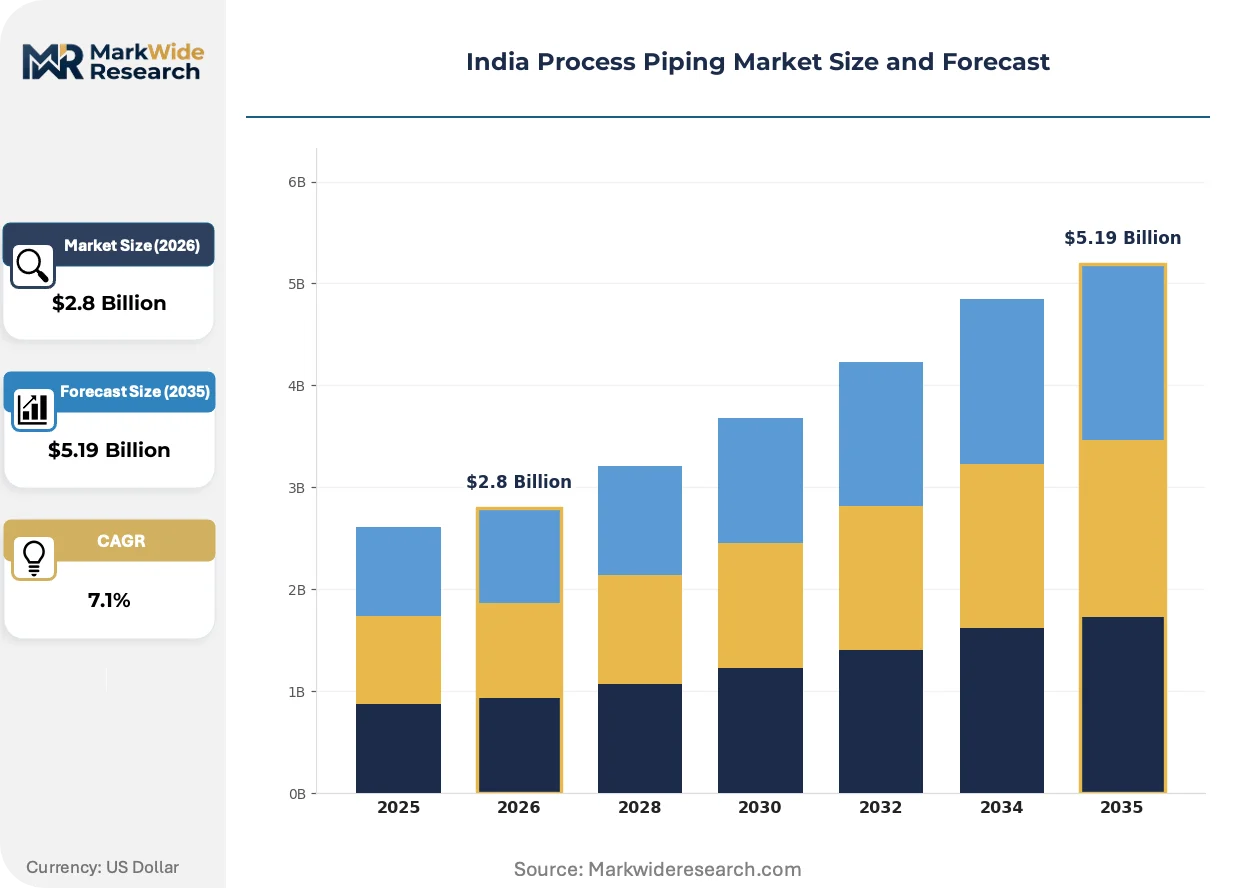
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.19 Billion |
| CAGR (2026 – 2036) | 7.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbon Steel, Stainless Steel, Alloy Steel, PVC Application: Oil & Gas, Water Treatment, Chemical Processing, Food & Beverage End User: Energy, Manufacturing, Construction, Pharmaceutical Installation: Onshore, Offshore, Industrial, Commercial |
| Companies Covered | Apollo Pipes Limited, Prince Pipes and Fittings Limited, Finolex Industries Limited, DEE Piping Systems, Jindal SAW Ltd., Supreme Industries Private Limited, ASTRAL Limited, Electrosteel Castings Limited, Ashirvad Pipes Private Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Process Piping Market Trends and Innovations
Automation in welding and inspection protocols is compressing quality assurance cycles while raising the technical floor for market participation, favoring fabricators with capital reserves over labor-dependent competitors.
Automated orbital TIG welding systems with real-time seam tracking are rendering obsolete manual root-pass procedures on high-purity pharmaceutical and semiconductor piping. Reliance Industries and Sun Pharma have specified automated weld documentation for new greenfield projects, eliminating small fabricators lacking robotic capital from premium bid pools. This technology compression is bifurcating the contractor base between automated specialists and commodity carbon-steel job shops.
BIS pressure equipment standards are tightening material documentation requirements for hydrogen service applications, forcing fabricators to upgrade metallurgical testing capabilities. The 2024 amendments mandate Charpy V-notch testing at sub-zero temperatures for specific alloy grades, adding cost and timeline pressure to project quotations. Gujarat-based fabricators are responding fastest due to concentration of hydrogen pipeline pilot projects in the Hazira industrial zone.
Engineering-procurement-construction firms are unbundling piping installation from lump-sum contracts, creating direct procurement relationships between end-users and specialized fabricators. This channel restructuring eliminates margin stacking but transfers project management burden to owner organizations with limited piping technical staff. The shift is most visible in refinery maintenance turnarounds where Indian Oil has piloted direct fabrication contracting for critical path spool replacement.
India Process Piping Market Segmentation
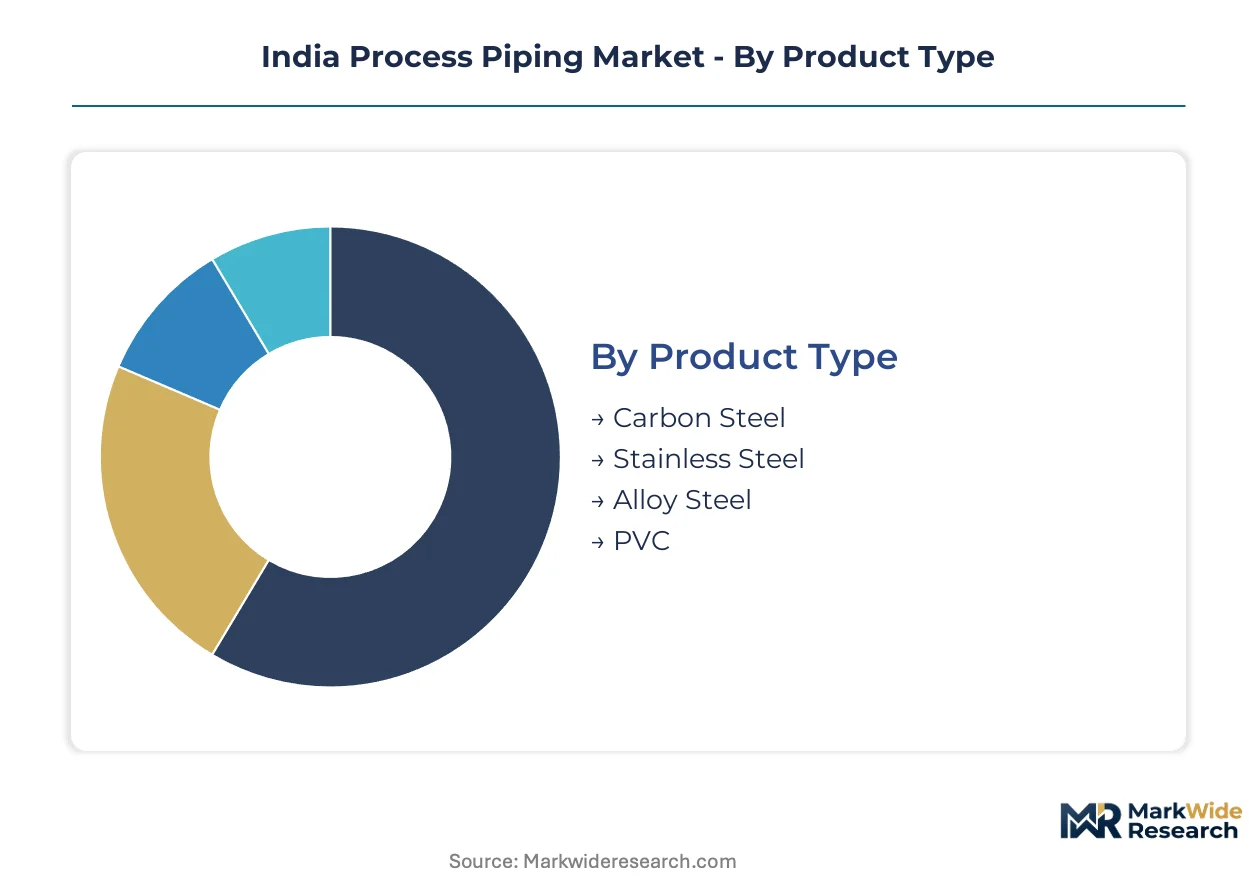
Process piping procurement cycles vary dramatically by material grade and end-use criticality, with refinery turnarounds demanding 18-month alloy qualification timelines while municipal PVC contracts close in weeks. Understanding these velocity differentials helps suppliers align inventory and certification investments with actual revenue conversion speed.
Product Type:
Carbon steel turns over fastest in standard refinery maintenance cycles, while super-duplex stainless grades sit in 14-month BIS certification queues before first commercial deployment.
- Carbon Steel:SCH 40 through SCH 160 wall schedules dominate gathering networks and boiler feed systems. Indian Oil's Paradip expansion is pulling 24-inch line pipe in volumes that strain domestic mill rolling capacity. This grade dominates installed base.
- Stainless Steel:304L and 316L austenitic grades with orbital weld documentation serve pharmaceutical sterile processing and chemical corrosion duty. Dahej cluster specifications for chloride-bearing service are accelerating specification of Mo-bearing grades. This is where expansion concentrates.
- Alloy Steel:P91 and P92 chrome-moly grades withstand supercritical boiler conditions above 565°C.
- PVC:Corrosion-free thermoplastic systems capture municipal water treatment specifications where pressure ratings permit non-metallic solutions.
Carbon steel dominates installed base. Stainless steel is where expansion concentrates.
Application:
Water treatment contracts award on shortest procurement cycles, while chemical processing qualifications stretch across multi-year validation protocols.
- Oil & Gas:High-pressure gathering systems and refinery process units demand full BIS pressure equipment compliance with hydrostatic testing documentation. Reliance Industries' Jamnagar complex specifications are tightening welder qualification requirements for hydrogen service. This grade dominates installed base.
- Water Treatment:Municipal distribution networks and desalination plants specify PVC and ductile iron for corrosion resistance. Gujarat's Narmada pipeline Phase II is standardizing on cement-lined ductile iron for trunk mains. This is where expansion concentrates.
- Chemical Processing:Acid service and caustic handling require duplex stainless or specialty alloy selections.
- Food & Beverage:3A sanitary standards and electropolished 316L tubing serve dairy and brewery process lines.
Oil & Gas commands the largest contract values. Water Treatment offers the steepest expansion trajectory for non-metallic substitution.
End User:
Energy sector procurement operates on decade-long asset life cycles, while pharmaceutical facility upgrades turn over on 3-5 year validation windows.
- Energy:Thermal power supercritical retrofits and refinery capacity additions specify P91, P92, and high-pressure carbon steel systems. CEA regulations are mandating efficiency upgrades that open specification windows for specialized fabricators. This segment dominates installed base.
- Manufacturing:Process plant utilities and compressed air systems specify standard carbon steel schedules with lower documentation burdens. Hazira industrial zone expansions are concentrating demand for medium-pressure fabricated spools. This is where expansion concentrates.
- Construction:Building services and HVAC hydronics specify lighter wall schedules with faster installation cycles.
- Pharmaceutical:Sterile processing demands electropolished tubing with full orbital weld documentation and material traceability.
Energy anchors volume demand. Pharmaceutical offers the fastest-climbing margin tier for qualified fabricators.
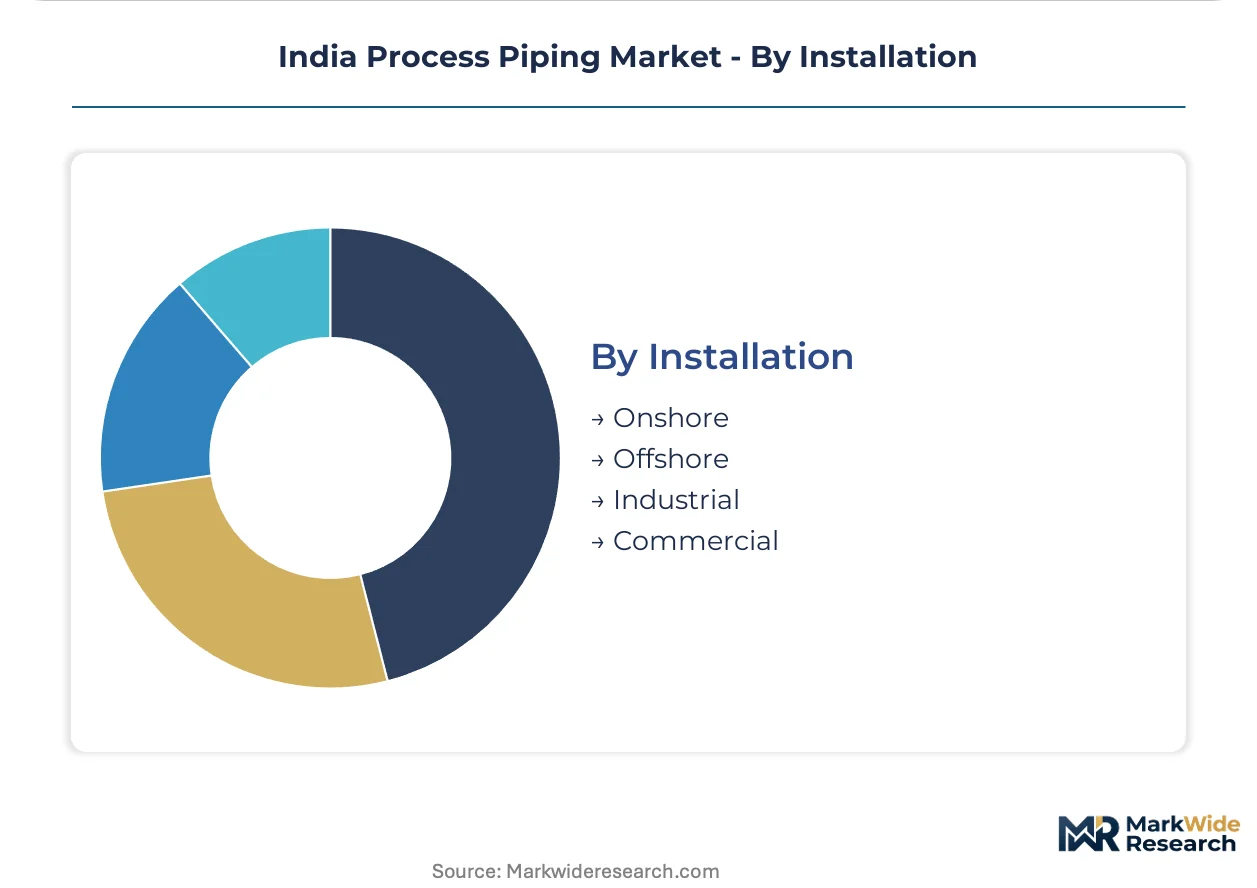
Installation:
Onshore fabrication yards deliver on compressed schedules, while offshore platform piping demands marine-grade coatings and extended corrosion allowances.
- Onshore:Coastal fabrication yards in Gujarat and Andhra Pradesh anchor large-diameter contracts for terminals and refineries. DEE Piping Systems' Dahej facility is capturing oil terminal spool packages through logistics proximity. This segment dominates installed base.
- Industrial:Plant-integrated process units require field welding with preheat and post-weld heat treatment protocols. BIS certification mandates for pressure-bearing equipment are accelerating material upgrades across domestic fabricators. This is where expansion concentrates.
- Offshore:Platform process piping demands splash zone coatings and cathodic protection integration.
- Commercial:Building services specify lighter schedules with reduced pressure-temperature ratings.
Onshore commands the majority of fabrication hours. Industrial plant retrofits are expanding most quickly as asset life extension programs accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gujarat consumes process piping differently than other Indian states, prioritizing high-pressure alloy systems for petrochemical service over the PVC and ductile iron networks that dominate municipal procurement elsewhere.
Gujarat
Dahej and Hazira industrial clusters anchor the nation's densest concentration of refinery and chemical processing capacity. BIS pressure equipment certification mandates accelerate material upgrades among fabricators serving Reliance Industries and Indian Oil expansions. Dahej petrochemical corridor greenfield investments concentrate demand for corrosion-resistant stainless systems within a single logistics-advantaged geography.
Maharashtra
Mumbai-Pune industrial belt sustains legacy chemical processing infrastructure requiring scheduled turnaround spool replacements. CEA thermal power regulations force supercritical boiler retrofits at coastal generation stations, opening specification windows for P91 and P92 chrome-moly piping grades. Thane-Belapur manufacturing zone fabricators capture medium-pressure carbon steel contracts for process plant utilities.
Andhra Pradesh
Visakhapatnam pharmaceutical corridor expansions create demand for electropolished 316L tubing with orbital weld documentation. CD sterile processing facility standards mandate material traceability protocols that domestic fabricators are only beginning to address. Vizag SEZ sterile processing investments pull premium-grade stainless systems away from standard chemical service specifications.
Tamil Nadu
Manali-Ennore petrochemical complex maintenance cycles sustain steady demand for refinery-grade carbon steel spools. State pollution control board enforcement tightens leak detection requirements for aging process units, accelerating replacement schedules. Chennai port logistics advantage positions local fabricators for coastal terminal piping packages.
Haryana
Manesar-Bawal automotive supplier parks generate ancillary demand for compressed air and utility piping systems. PLI scheme disbursements for specialty steel production incentivize mill investment in nickel-alloy capability that would narrow import dependence for regional fabricators. Gurgaon industrial corridor specifications trend toward lighter wall schedules with reduced documentation burdens.
India Process Piping Market Competitive Landscape
Capability concentration sits with specialized alloy fabricators holding BIS pressure equipment approvals; scale advantage sits with diversified pipe manufacturers serving high-volume municipal and agricultural segments. The market structures around three tiers: integrated steel mills with captive piping divisions, independent fabricators with coastal yard advantages, and polymer specialists dominating thermoplastic specifications. Consolidation pressure runs through qualified welder scarcity and orbital welding automation requirements that favor capital-intensive operators.
Among listed players, DEE Piping Systems represents the coastal fabrication archetype with Dahej yard positioning, while Apollo Pipes Limited and Electrosteel Castings Limited exemplify divergent material specialization strategies across polymer and ferrous categories. Apollo Pipes occupies a position in PVC process line competition for chemical handling applications. Electrosteel Castings anchors the foundry-to-finish vertical model across ductile iron pressure piping. These three names illustrate how capability boundaries segment competitive terrain between thermoplastic substitution threats and alloy-grade premium capture.
| Leading Market Players |
|---|
| Apollo Pipes Limited |
| Prince Pipes and Fittings Limited |
| Finolex Industries Limited |
| DEE Piping Systems |
| Jindal SAW Ltd. |
| Supreme Industries Private Limited |
| ASTRAL Limited |
| Electrosteel Castings Limited |
| Ashirvad Pipes Private Limited |
| Others |
Pricing and Supply Chain Analysis
European and Japanese specialty steel mills anchor upstream supply for critical alloy grades, concentrating margin capture in high-pressure hydrogen service segments where BIS certification bottlenecks preserve import dependence. Project owners absorb currency volatility and extended lead times, while domestic fabricators compete on standard carbon steel specifications where pricing power remains fragmented.
Pricing Analysis
Long-term offtake contracts dominate high-pressure alloy procurement for refinery expansions, insulating Reliance Industries and Indian Oil from spot volatility in nickel-alloy markets. Price differentiation hinges on BIS certification tier and orbital weld documentation grade, with automated weld protocols commanding premium positioning over manual procedures. Cost compression in standard carbon steel spools is intensifying because domestic mill overcapacity strains rolling schedules. Municipal water treatment buyers exhibit highest price sensitivity, while pharmaceutical sterile processing operators prioritize material traceability over unit cost.
Supply Chain Analysis
Contract manufacturing concentration sits with Jindal SAW and DEE Piping Systems for large-diameter coastal fabrication, supplemented by regional job shops for field welding services. Geographic supply draws from Japan, Germany, and Sweden for super-duplex and P92 grades, while domestic mills feed standard carbon and austenitic stainless demand. Raw material sourcing rests on nickel ore imports, chrome-moly billet availability, and PVC resin from petrochemical corridors. Single-source vulnerability persists for hydrogen-qualified orbital welding equipment. Distribution runs through engineering-procurement-construction firms unbundling direct procurement relationships to specialized fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket service revenue layers including predictive maintenance contracts and digital twin integration are expanding faster than new pipe fabrication hardware, creating recurring revenue pools that extend fabricator relationships beyond installation cycles.
For Market Incumbents: Build certification moats through accelerated BIS pressure equipment approvals and captive orbital welder training pipelines. Deepen backward integration into coastal fabrication yard capacity to capture Dahej and Hazira terminal contracts. Defend against thermoplastic substitution in municipal water handling by bundling electropolished stainless systems with lifecycle service agreements. For New Entrants and Emerging Players: Pursue Andhra Pradesh pharmaceutical corridor opportunities where electropolished 316L tubing demand outpaces qualified domestic supply. Target Visakhapatnam sterile processing facility expansions as the most penetrable geography given documentation capability gaps. Establish go-to-market positioning through orbital welding automation partnerships that compress project schedules for CD-standard validations. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed coastal fabrication specialists holding Dahej logistics positioning and BIS pressure equipment approvals. Five-to-ten year viability hinges on PLI scheme acceleration for domestic nickel-alloy production narrowing import dependence. Monitor BIS certification throughput timelines as the inflection signal determining whether project owners shift procurement to qualified domestic mills or preserve European supplier relationships.| Strategic Initiative | Industry Significance |
|---|---|
| Orbital Welding Automation Investment | Reliance Industries specifications eliminate manual-weld competitors from premium bid pools. |
| Backward Integration into Coastal Fabrication | DEE Piping Systems anchors oil terminal spool packages through logistics proximity. |
| BIS Certification Acceleration | Domestic mill qualification timelines determine import substitution feasibility for critical grades. |
| Digital Twin Platform Development | Predictive maintenance contracts extend fabricator relationships beyond installation completion. |
| Pharmaceutical Corridor Expansion | Visakhapatnam sterile processing investments pull premium stainless from standard chemical service. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with plant engineers, EPC procurement leads, BIS certification officers, and aftermarket service directors; and secondary validation through Petroleum and Natural Gas Regulatory Board pipeline safety codes, CEA thermal power regulation filings, customs import data for specialty steel grades, and PLI scheme disbursement records. Bottom-up project pipeline aggregation triangulated against top-down industrial capacity assessments.
Forecast inputs considered material grade segmentation, end-use criticality tiers, installation type velocity differentials, and regional cluster concentration patterns across the projection horizon. CAGRs derived from weighted capacity expansion schedules, BIS certification throughput assumptions, and substitution elasticity between metallic and thermoplastic systems. Industry-specific inputs included refinery turnaround cycles, supercritical boiler retrofit mandates, and pharmaceutical facility validation windows.
Macroeconomic conditions sit as an overlay; deviation in rupee-dollar exchange rates, nickel price volatility, or infrastructure disbursement timing would shift the trajectory. Forecasts reflect documented assumptions on domestic mill qualification timelines and PLI incentive acceleration. Quarterly review of BIS certification queue lengths, specialty steel import volumes, and orbital welder training pipeline output is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Thermoplastic Pipe Market
Pipes and Tubes
Gas Fittings and Components Market
Pipes and Tubes
Saudi Arabia PVC Pipes Market
Pipes and Tubes
Hydrogen Tube Skids Market
Pipes and Tubes
Chlorinated Polyvinyl Chloride (Cpvc) Pipes Market
Pipes and Tubes
FEP Tubing Products Market
Pipes and Tubes
Weld Overlay Process Clad Pipes Market
Pipes and Tubes
Glass Reinforced Epoxy (GRE) Pipes Market
Pipes and Tubes
Multibore Tubes Market
Pipes and Tubes
Bahrain PVC Pipes Market
Pipes and Tubes
Galvanized Steel Tubes Market
Pipes and Tubes
Pipeline Processing and Pipeline Services Market
Pipes and Tubes
Pipe and Tube Cutters Market
Pipes and Tubes
Plastic Pipe Market
Pipes and Tubes
Aluminium Tubes for OPC Drum Market
Pipes and Tubes
Global Copper Pipes and Tubes Market