
 Global Flexible Pipes Market | 2026-2036
Global Flexible Pipes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Flexible Pipes Market Analysis
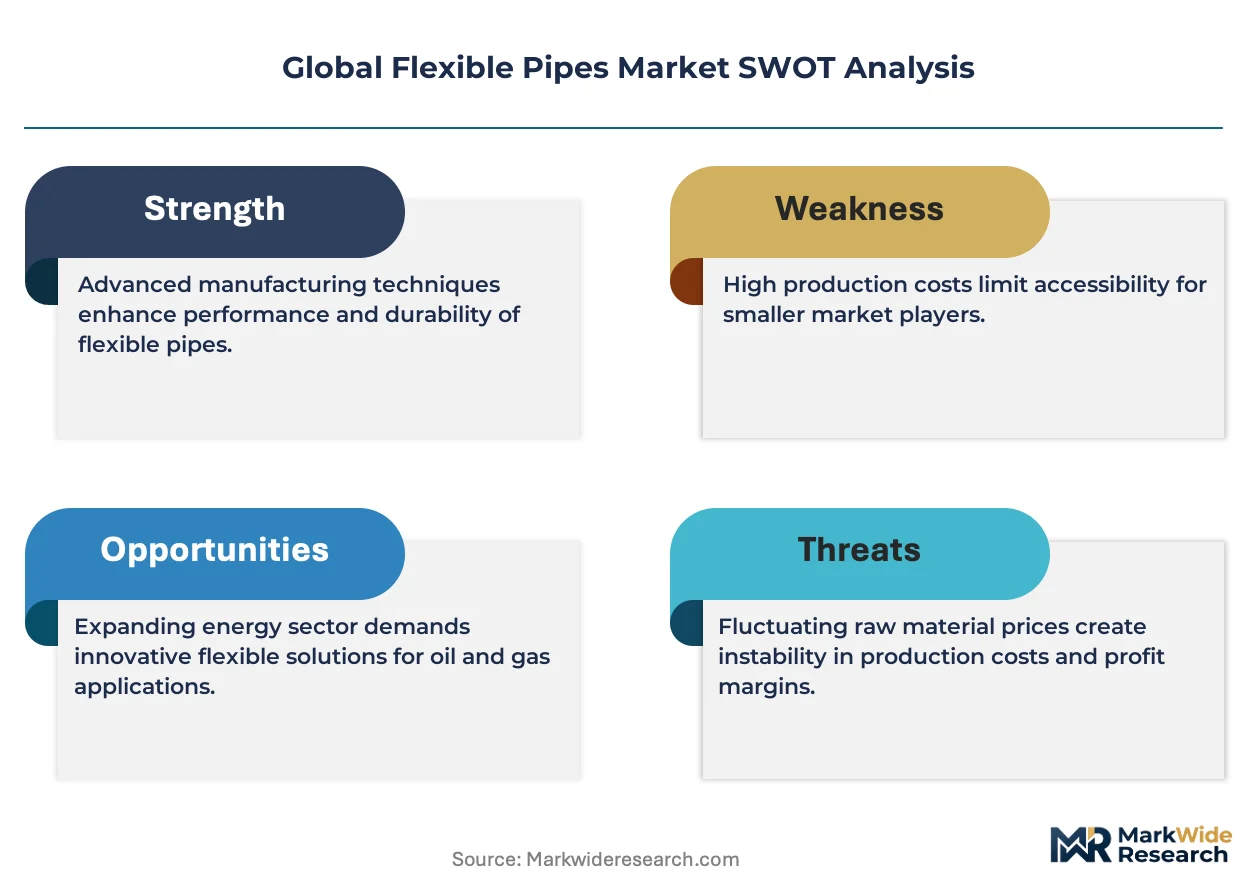
Advanced polymer matrix engineering is reshaping flexible pipe construction, replacing traditional steel carcass designs with thermoplastic composite pressure barriers that withstand corrosive sour gas environments. TechnipFMC plc leverages integrated subsea engineering capabilities to dominate turnkey umbilical and riser contracts. Baker Hughes sustains technology leadership through proprietary dynamic bend stiffener designs. Saipem S.p.A. anchors Mediterranean project execution with shallow-water installation expertise.
Flexible pipes are multi-layered conduits comprising polymer barriers, steel armor wires, and anti-wear tapes engineered to transport hydrocarbons, chemicals, and water under combined pressure, tension, and bending loads in dynamic offshore service. HDPE product types command structural volume in water management and mining distribution networks where abrasion resistance and joint flexibility reduce installation labor. Subsea installation methods concentrate margin pools as deeper water ratings require specialized reel-lay vessels and tensioner technology. Fluid transfer applications lead offshore segments, while wastewater handling drives above-ground municipal adoption.
API 17J standards govern United States flexible pipe qualification, mandating cyclic fatigue testing and collapse resistance verification before subsea deployment. Brazil's national petroleum regulator enforces local content requirements that shape supplier selection for pre-salt flexible riser packages. ECHA REACH restrictions on phthalate plasticizers are forcing PVC formulation changes across European water management contracts. Stakeholders must monitor how polymer feedstock volatility and evolving subsea tieback architectures alter procurement specifications for next-generation dynamic risers.
Market Dynamics
Deepwater field economics are compressing riser replacement cycles as subsea tieback architectures demand higher fatigue-resistant polymer barriers that withstand sour gas corrosion at extreme pressures.
Growth Catalysts
- Brazil Pre-Salt Developments:Petrobras continues commissioning floating production facilities with integrated flexible flowline systems, sustaining demand for high-pressure dynamic risers rated beyond 300 bar.
- REACH Material Certification:ECHA restrictions on phthalate plasticizers are accelerating PVC formulation innovations that improve chemical resistance in water management applications.
- API 17J Qualification Mandates:Cyclic fatigue testing requirements in the United States are filtering out marginal suppliers and concentrating procurement among certified manufacturers with proven collapse resistance verification.
Market Restraints
- Steel Armor Wire Volatility:High-tensile steel wire rod prices fluctuate with scrap metal markets, compressing margin predictability for armor layer fabricators.
- Reel-Lay Vessel Scarcity:Deepwater installation capacity concentrates among North Sea and Gulf of Mexico vessel operators, creating bottlenecks for pre-salt project scheduling.
- HDPE Substitution Pressure:Rigid spoolable composite pipes are capturing shallow-water tieback applications previously served by unbonded flexible pipes.
Strategic Opportunities
- West Africa Brownfield Revitalization:Aging FPSO fleets in Angolan and Nigerian waters require riser replacement programs that favor turnkey flexible pipe contractors with local installation partnerships.
- Carbon Capture Injection Lines:Thermoplastic composite pressure barriers are penetrating CO2 transport applications where corrosion resistance exceeds steel carcass capabilities.
- EU Green Deal Funding:Circular economy incentives for recyclable polymer matrices are opening procurement channels for bio-based barrier materials in North Sea decommissioning projects.
Industry Challenges
- Polymer Matrix Engineering Talent:Finite element modeling expertise for multi-layer stress analysis remains scarce among pipe manufacturers expanding thermoplastic composite capabilities.
- Dynamic Bend Stiffener Integration:Vessel-based installation of bend limiters at extreme water depths demands precision tensioner coordination that extends offshore campaign durations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Flexible Pipes Market |
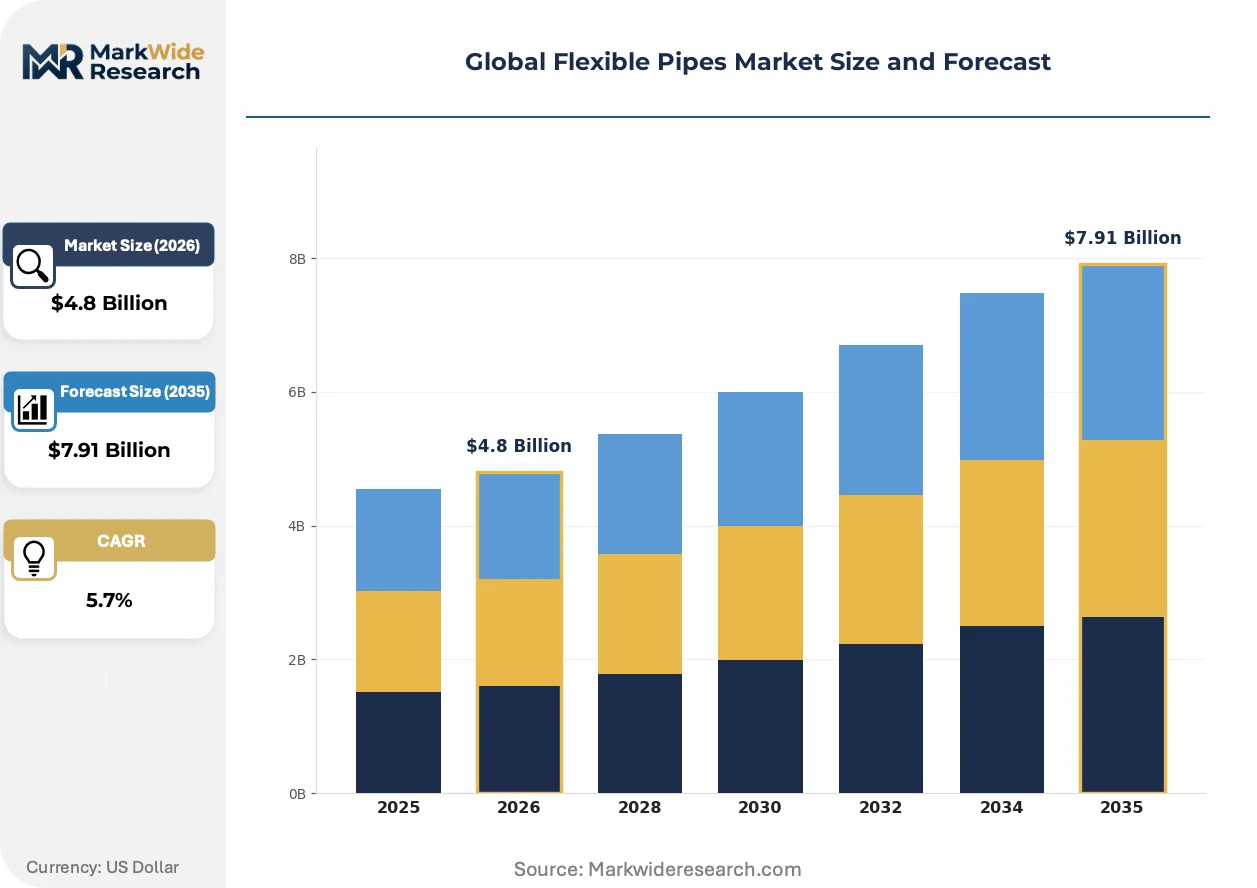
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PVC, Polyurethane, HDPE, PVDF End User: Oil & Gas, Water Management, Chemicals, Mining Installation Method: Buried, Above Ground, Floating, Subsea Application: Fluid Transfer, Wastewater, Offshore, Industrial |
| Companies Covered | Prysmian Group, Schlumberger Limited, TechnipFMC plc, Strohm B.V., Saipem S.p.A., NOV Inc., Shawcor Ltd, Magma Global Ltd, Baker Hughes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Flexible Pipes Market Emerging Trajectories
Thermoplastic composite pressure barriers are displacing conventional metallurgy across sour gas applications, while regulatory tightening on polymer feedstocks and vessel specialization requirements reshape competitive capabilities.
Reinforced thermoplastic pipe (RTP) technology with glass fiber or carbon fiber pressure vessels is rendering obsolete traditional steel carcass designs in corrosive offshore environments. Norwegian operators are specifying RTP for marginal field tiebacks where weight reduction accelerates installation timelines. The shift is compressing demand for corrosion-resistant alloy metallurgy in dynamic riser construction.
ECHA REACH restrictions on phthalate plasticizers are forcing formulation changes across European water management contracts. Pipe fabricators are qualifying alternative plasticizer chemistries that maintain flexibility ratings under low-temperature service conditions. Municipal procurement specifications in Germany and France now require third-party certification of non-phthalate barrier compounds.
Integrated service contracting is consolidating procurement decisions among supermajors with captive engineering capabilities. Turnkey umbilical and riser packages are displacing component-level sourcing for pre-salt developments in Brazil. This concentration is visible in Petrobras tender structures that favor single-source accountability for design, fabrication, and offshore installation.
Global Flexible Pipes Market Segmentation
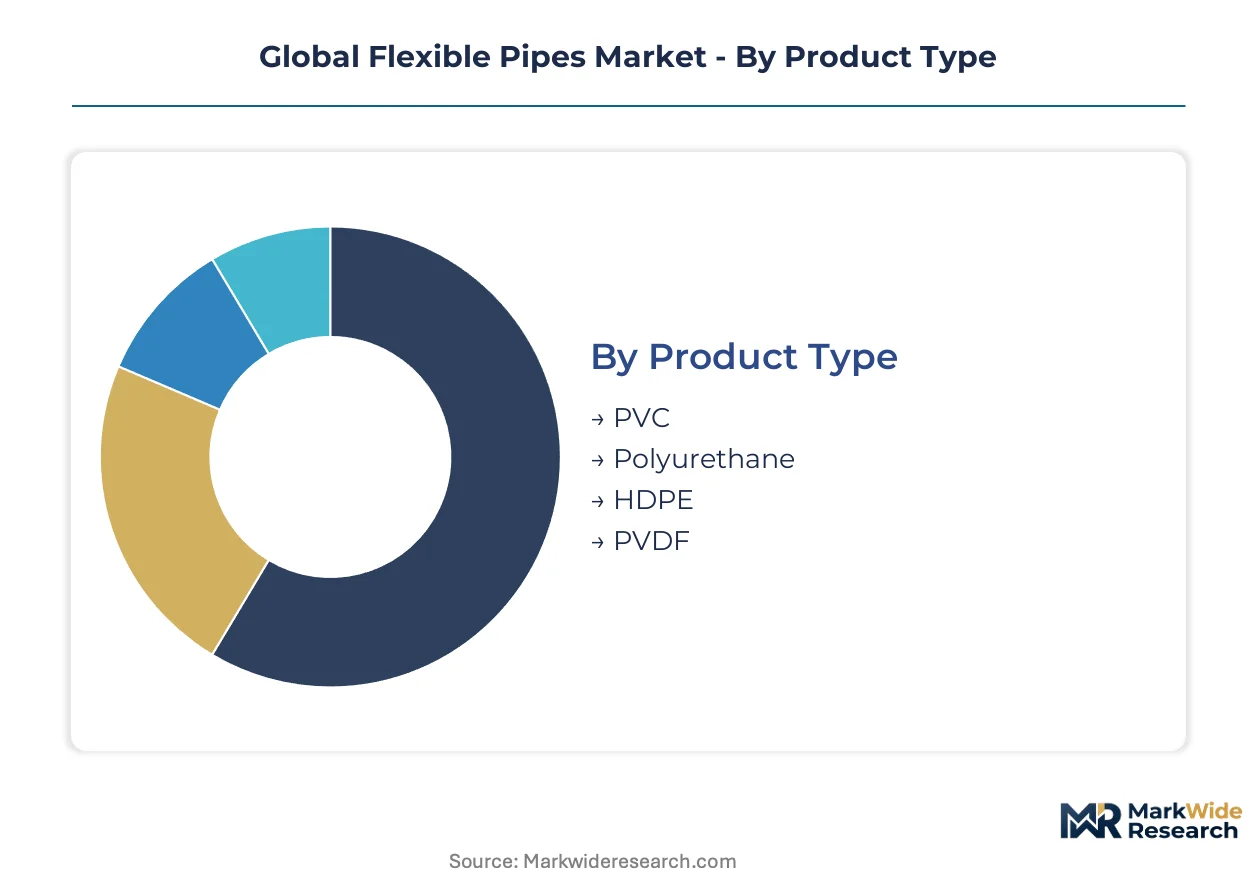
Flexible pipe segmentation reflects divergent material science requirements across corrosive hydrocarbon transport, municipal infrastructure, and dynamic subsea service. Each dimension captures distinct procurement specifications, installation protocols, and regulatory compliance burdens that reshape supplier capabilities.
Product Type:
Material selection spans rigid thermoplastics for structural water networks to elastomeric barriers engineered for dynamic fatigue resistance in offshore hydrocarbon service.
- HDPE:High-density polyethylene dominates mining slurry transport and municipal water distribution where abrasion resistance and thermal fusion jointing reduce field labor. Demand concentrates in Australia's iron ore corridors and Chilean copper belt operations where HDPE's flexibility accommodates ground movement without mechanical couplings.
- Polyurethane:Elastomeric thermoset matrices form dynamic riser pressure barriers that withstand cyclic bending and sour gas permeation at extreme depths. Brazil's pre-salt operators specify polyurethane load-bearing layers for flexible flowlines rated beyond 300 bar operating pressure.
- PVC:Rigid thermoplastic formulations serve gravity-fed wastewater and irrigation networks where cost efficiency outweighs pressure rating requirements.
- PVDF:Fluoropolymer barriers deliver chemical inertness for aggressive acid transfer in semiconductor fabrication and specialty chemical processing.
The dominant share belongs to HDPE, while polyurethane is closing the gap fastest as deepwater field economics accelerate thermoplastic composite adoption.
End User:
Customer procurement patterns diverge between capital-intensive offshore project cycles and recurring municipal maintenance budgets.
- Oil & Gas:Offshore operators commission integrated flexible riser and flowline packages through multi-year fabrication contracts tied to floating production facility schedules. Subsea tieback architectures in Brazil, West Africa, and the Gulf of Mexico drive specification for dynamic pressure barriers with 25-year fatigue life.
- Water Management:Municipal utilities and mining operators prioritize HDPE distribution networks with fusion-welded joints that eliminate leakage points. German and French procurement specifications now mandate ECHA REACH-compliant plasticizer formulations for potable water contact barriers.
- Chemicals:Process industries specify fluoropolymer-lined flexible conduits for sulfuric acid and caustic transfer where metallic corrosion would accelerate maintenance cycles.
- Mining:Slurry transport applications favor thick-walled HDPE and polyurethane hoses that withstand abrasive ore particle impingement in remote extraction sites.
Oil & Gas commands the largest contract values, though water management delivers the steadiest replacement demand across fragmented municipal procurement channels.
Installation Method:
Deployment physics dictate radically different engineering specifications from trench burial to dynamic subsea tensioning.
- Subsea:Reel-lay vessels deploy continuous flexible pipe from horizontal spools through tensioners that manage plastic deformation limits. Deepwater ratings require specialized marine assets concentrated among North Sea and Gulf of Mexico contractors, creating scheduling bottlenecks for pre-salt developments.
- Buried:Trench installation for municipal water and gas distribution demands crush-resistant HDPE formulations with standardized dimension ratios that withstand soil loading and ground settlement.
- Above Ground:Exposed routing in industrial facilities and temporary mining installations prioritizes UV-stabilized jackets and mechanical protection layers against impact damage.
- Floating:Surface-mounted configurations for oil spill containment and temporary water transfer utilize buoyant hose assemblies with integrated flotation collars.
Subsea installation captures the highest margins per meter, while buried deployment represents the largest cumulative length across infrastructure replacement cycles.
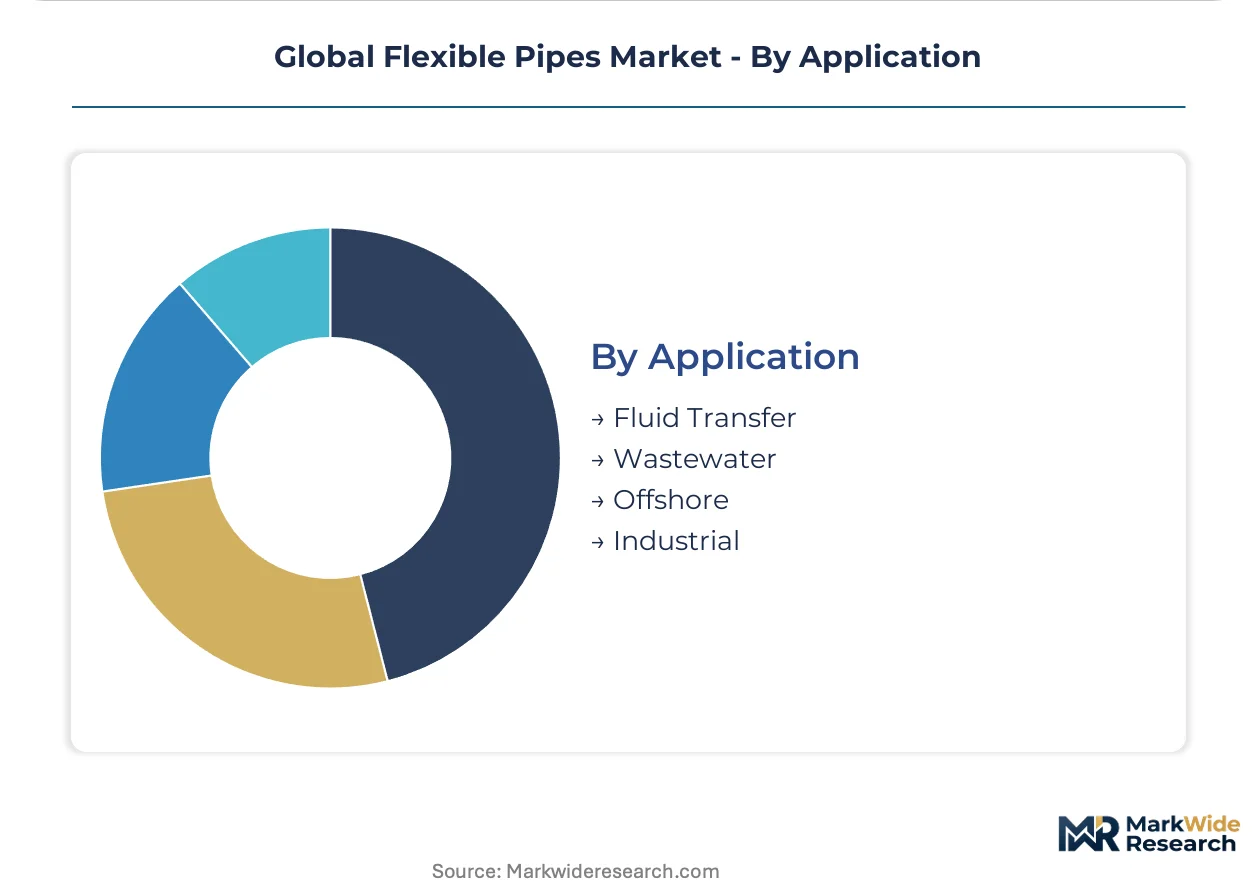
Application:
Functional requirements range from passive containment to active pressure containment under combined mechanical loads.
- Fluid Transfer:Hydrocarbon production flowlines and chemical injection lines demand multi-layer pressure barriers with steel armor wire reinforcement. API 17J qualification mandates cyclic fatigue testing before subsea deployment in United States waters.
- Wastewater:Gravity and low-pressure sewage networks utilize corrugated HDPE and PVC profiles that accommodate soil movement and root intrusion resistance.
- Offshore:Dynamic riser service combines tension, pressure, and bending loads that exceed static flowline specifications, requiring specialized bend stiffener integration at vessel connection points.
- Industrial:Process plant utility distribution employs flexible metal hoses and thermoplastic conduits for steam, compressed air, and hydraulic service within confined equipment layouts.
Fluid transfer generates the highest revenue concentration, with offshore applications expanding most quickly as field developments migrate into deeper water and harsher corrosive environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil exports flexible riser systems to West African offshore operators, creating a trade corridor that concentrates deepwater installation expertise across the South Atlantic. This flow pattern shapes regional procurement strategies as pre-salt engineering capabilities transfer to Angolan and Nigerian brownfield projects.
Brazil
Petrobras commissions floating production facilities with integrated flexible flowline systems rated beyond 300 bar operating pressure. ANP local content requirements mandate domestic fabrication quotas for pre-salt riser packages. The Rio de Janeiro industrial cluster hosts specialized reel-lay vessel operators serving Campos and Santos basin developments.
United States
Gulf of Mexico operators deploy dynamic risers for subsea tieback architectures in ultra-deepwater fields. API 17J qualification mandates cyclic fatigue testing and collapse resistance verification before offshore deployment. Houston anchors the engineering design ecosystem, with fabrication yards concentrated in Louisiana serving shelf and deepwater installations.
Norway
North Sea decommissioning projects and marginal field tiebacks drive specification for thermoplastic composite pressure barriers. ECHA REACH restrictions on phthalate plasticizers accelerate formulation changes in water management applications. Stavanger and Bergen host integrated subsea engineering centers developing RTP technology for sour gas environments.
China
Domestic offshore operators expand flexible pipe procurement for South China Sea deepwater gas developments. MIIT standards govern thermoplastic composite qualification for corrosive hydrocarbon transport. The Tianjin and Qingdao port clusters support manufacturing scale-up for regional supply chain localization.
United Kingdom
North Sea basin maturity sustains riser replacement cycles and brownfield infrastructure upgrades. HSE offshore safety regulations enforce dynamic bend stiffener integration standards at vessel connection points. Aberdeen maintains subsea engineering concentration despite production decline, with specialist firms pivoting to decommissioning and carbon capture injection line applications.
Global Flexible Pipes Market Vendor Landscape
Channel-controlling players compete with product-specialist players across segmented procurement channels. The market exhibits tiered consolidation with turnkey contractors capturing integrated subsea packages while component fabricators serve municipal and industrial replacement demand. Three archetypes dominate: integrated engineering-procurement-construction firms, specialized flexible pipe manufacturers, and diversified energy service conglomerates. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms address reel-lay vessel scarcity and polymer matrix engineering talent gaps.
Among integrated subsea contractors, TechnipFMC plc and Saipem S.p.A. exemplify the turnkey archetype with bundled umbilical and riser accountability. Baker Hughes occupies a position representing diversified energy service scale, leveraging proprietary dynamic bend stiffener designs across multiple offshore basins. These three anchors illustrate how competitive positioning stratifies between project-integrated capability and technology-specific specialization.
| Leading Market Players |
|---|
| Prysmian Group |
| Schlumberger Limited |
| TechnipFMC plc |
| Strohm B.V. |
| Saipem S.p.A. |
| NOV Inc. |
| Shawcor Ltd |
| Magma Global Ltd |
| Baker Hughes |
| Others |
Supply Flow & Price Mechanics
Steel armor wire volatility determines both margin compression in standard-tier products and supply chain regionalization toward scrap-adjacent manufacturing clusters in Turkey and India. This commodity exposure compresses pricing spreads between API 17J-certified premium risers and unbonded flowlines for shallow-water tiebacks.
Pricing Analysis
Technology-generation pricing gaps separate thermoplastic composite pressure barriers from conventional steel carcass designs, with RTP commanding project-based premiums for sour gas service. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with API 17J qualification and ECHA REACH compliance as threshold tiers. Cost compression in standard HDPE water management products is intensifying because of HDPE substitution pressure from rigid spoolable composites. Municipal procurement teams exhibit highest price sensitivity, while Petrobras-style supermajors prioritize single-source accountability over unit economics.
Supply Chain Analysis
Tariff exposure between China and the United States dominates raw material procurement risk for polymer feedstock converters serving North American offshore operators. High-tensile steel wire rod supply concentrates in China, South Korea, and Turkey, while polymer matrix engineering talent clusters in Norway, Brazil, and the United Kingdom. The supply chain draws from specialized reel-lay vessel operators concentrated in the North Sea and Gulf of Mexico, creating single-source vulnerability for deepwater installation campaigns. Distribution runs through integrated engineering-procurement-construction firms that bundle fabrication with offshore installation accountability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among supermajors with captive engineering capabilities, fragmenting procurement decisions away from component-level sourcing toward turnkey accountability structures.
For Market Incumbents: Entrench API 17J certification leadership through cyclic fatigue testing infrastructure investments that filter marginal competitors from pre-salt tender pools. Backward integration into polymer matrix compounding secures formulation control against ECHA REACH plasticizer restrictions. Priority lever: captive reel-lay vessel partnerships addressing scheduling bottlenecks in Brazil and West Africa. For New Entrants and Emerging Players: Establish a beachhead in carbon capture injection line applications where thermoplastic composite corrosion resistance exceeds incumbent steel carcass capabilities. Municipal water management in Germany and France presents penetrable white space through non-phthalate barrier certification. Go-to-market angle: third-party REACH compliance documentation bundled with fusion-welding field service. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors RTP-specialist fabricators with finite element modeling capabilities over legacy steel carcass manufacturers. Long-term viability hinges on polymer matrix engineering talent acquisition and reel-lay vessel access. Signal to watch: Petrobras tender structures shifting from component sourcing to integrated umbilical and riser packages.| Strategic Initiative | Industry Significance |
|---|---|
| Polymer Matrix R&D Partnership | Accelerates thermoplastic composite qualification for sour gas depths beyond 300 bar. |
| Reel-Lay Vessel Joint Venture | Secures installation capacity for pre-salt and West Africa brownfield campaigns. |
| ECHA REACH Compliance Certification | Unlocks German and French municipal water procurement channels. |
| Carbon Capture Line Qualification | Positions RTP technology for CO2 transport corrosion resistance. |
| Local Content Fabrication Facility | Satisfies ANP domestic quotas for Brazilian pre-salt riser packages. |
Methodological Framework
Operator-level perspectives from subsea project engineers, polymer R&D directors, reel-lay vessel operators, and municipal procurement managers anchored the qualitative base. Primary interviews with flexible pipe fabricators and offshore installation contractors combined with secondary validation from API 17J qualification records, ANP local content filings, and ECHA REACH substance restriction updates. Bottom-up segmentation modeling triangulated against top-down energy service company revenue disclosures.
Scenario-bracketing framed demand projections across the analysis window, with segmentation dimensions spanning product type, installation method, end-use industry, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles and greenfield project sanctioning timelines. Forecast inputs incorporated FPSO orderbook visibility and polymer feedstock price band assumptions.
Stress conditions across steel scrap volatility, reel-lay vessel day-rate spikes, and REACH plasticizer restriction enforcement were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about subsea tieback architecture evolution and thermoplastic composite adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Pneumatic Fittings Market
Pipes and Tubes
PVC Pipes Market
Pipes and Tubes
Global Polyolefin Pipes Market
Pipes and Tubes
Coiled Tubing Manufacturing Market
Pipes and Tubes
Global PEX (Cross-Linked Polyethylene) Market
Pipes and Tubes
OCTG Pipe Market
Pipes and Tubes
Saudi Arabia Copper Pipes and Tubes Market
Pipes and Tubes
FRP Pipes and Tanks Market
Pipes and Tubes
GCC CPVC Pipes Market
Pipes and Tubes
North America PVC Pipes Market
Pipes and Tubes
Glass Reinforced Epoxy (GRE) Pipes Market
Pipes and Tubes
India PVC Pipes Market
Pipes and Tubes
Galvanized Iron Pipes Market
Pipes and Tubes
United States Copper Pipes and Tubes Market
Pipes and Tubes
Global Polypropylene Pipes Market
Pipes and Tubes
Global Copper Pipes and Tubes Market