
 Stand Alone Cloud Storage Market | 2026-2036
Stand Alone Cloud Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Stand Alone Cloud Storage Market Analysis
Platform licensing revenue is reconfiguring margin pools away from raw infrastructure resale toward value-added orchestration layers. Amazon Web Services leverages its hyperscale footprint to sustain pricing power in object storage tiers. Microsoft Azure anchors enterprise trust through deep integration with productivity suites. Google Cloud Platform differentiates on analytics-ready storage architectures that reduce downstream compute costs.
Stand alone cloud storage denotes dedicated, off-premises data repositories provisioned independently of bundled compute or application services, typically accessed via RESTful APIs or NFS/SMB protocols with durability guarantees exceeding eleven nines. Its primary purpose is to decouple persistent data from volatile compute workloads, enabling cost-optimized retention and geographic redundancy. Public cloud deployment captures the dominant share of new capacity additions, while hybrid configurations attract organizations balancing latency-sensitive operations against compliance-bound archives. Backup solutions within the solution-type dimension command mature, high-volume contracts, whereas archiving solutions generate superior margins through infrequent-access pricing mechanics and long-term retention lock-in.
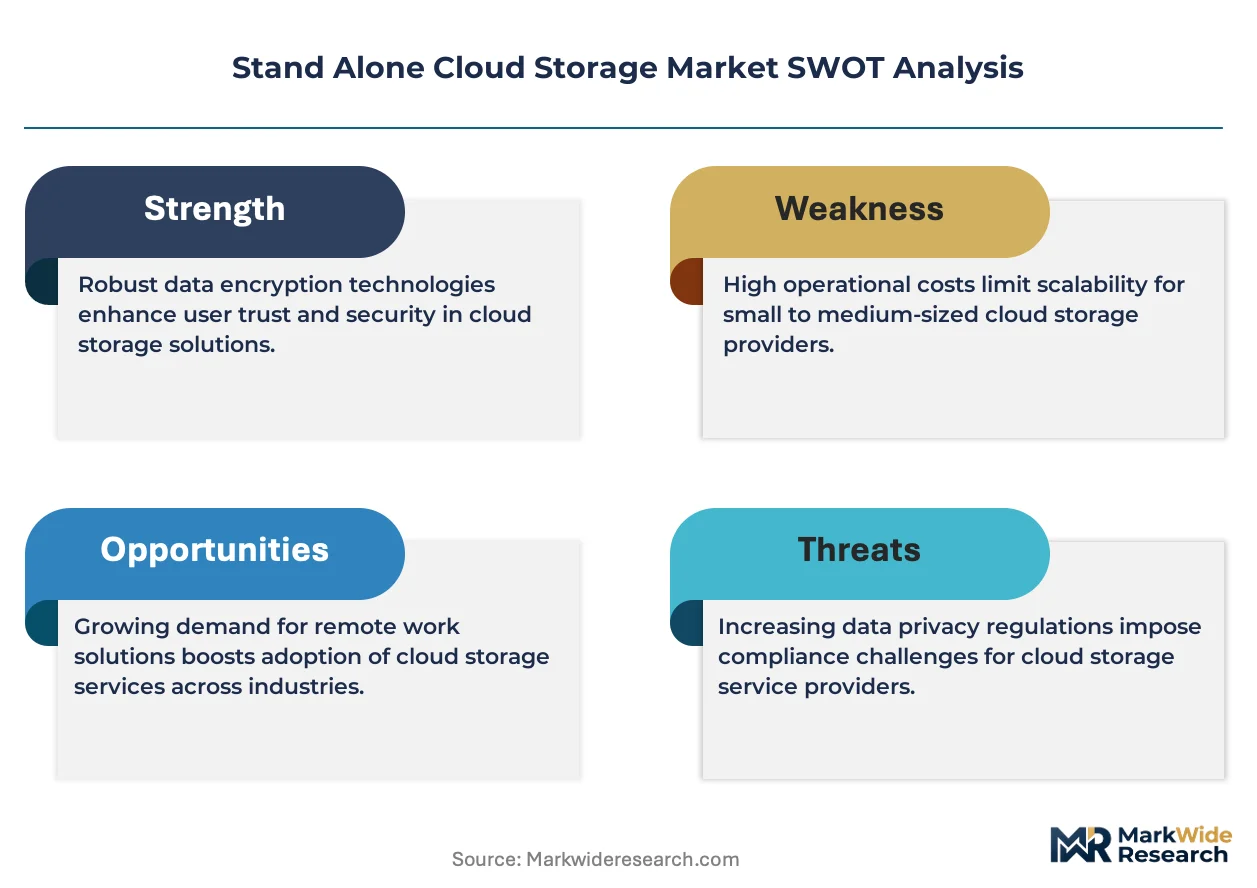
FDA guidelines for electronic records in life sciences, GDPR data-localization mandates enforced by EU member regulators, and India's DPDP Act administered by the Data Protection Board collectively shape product roadmaps and geographic deployment choices. Compliance with these frameworks determines market access for providers and procurement eligibility for buyers. Stakeholders must monitor evolving data-sovereignty rulings and cross-border transfer mechanisms to anticipate infrastructure localization requirements and contract restructuring needs.
Market Dynamics
Data sovereignty mandates are forcing infrastructure localization decisions across the storage stack. Providers must replicate capacity in-country to satisfy residency requirements, fragmenting previously centralized architectures.
Growth Catalysts
- GDPR enforcement:European regulators are levying substantial penalties for cross-border transfer violations. Enterprises are procuring EU-zone object storage to eliminate jurisdictional exposure.
- Life sciences digitization:FDA 21 CFR Part 11 compliance for electronic records is mandating immutable audit trails. Pharmaceutical manufacturers are contracting dedicated archival tiers with WORM capabilities.
- Hyperscale capex concentration:Amazon, Microsoft, and Google are deploying region-specific availability zones. Their infrastructure investment is pulling enterprise procurement toward certified local facilities.
Market Restraints
- Egress fee lock-in:Hyperscale providers charge punitive rates for data retrieval. Customers face switching costs that entrench incumbent relationships.
- Silicon supply concentration:NAND fabrication concentrates in Taiwan and South Korea. Geopolitical friction threatens flash-based tier availability.
- Latency physics:Edge computing requirements collide with centralized cold storage economics. Real-time applications cannot tolerate round-trip delays to distant regions.
Strategic Opportunities
- India's DPDP Act implementation:The Data Protection Board is finalizing localization rules. First-mover providers can anchor Mumbai and Hyderabad facilities ahead of enforcement.
- AI training data lakes:Generative model builders require petabyte-scale repositories with high-throughput access. This segment demands new performance-optimized tiers distinct from traditional backup.
- FinOps tooling integration:Cloud cost management platforms are embedding storage optimization modules. Channel partnerships with FinOps vendors unlock mid-market penetration.
Industry Challenges
- Multi-cloud orchestration expertise:Kubernetes-native storage abstraction requires scarce platform engineering talent. Enterprises struggle to hire engineers fluent in CSI drivers and cross-cluster replication.
- Legacy tape migration:Financial services and media archives retain decades of LTO cartridges. Extracting readable data without corruption demands specialized restoration services.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stand Alone Cloud Storage Market |
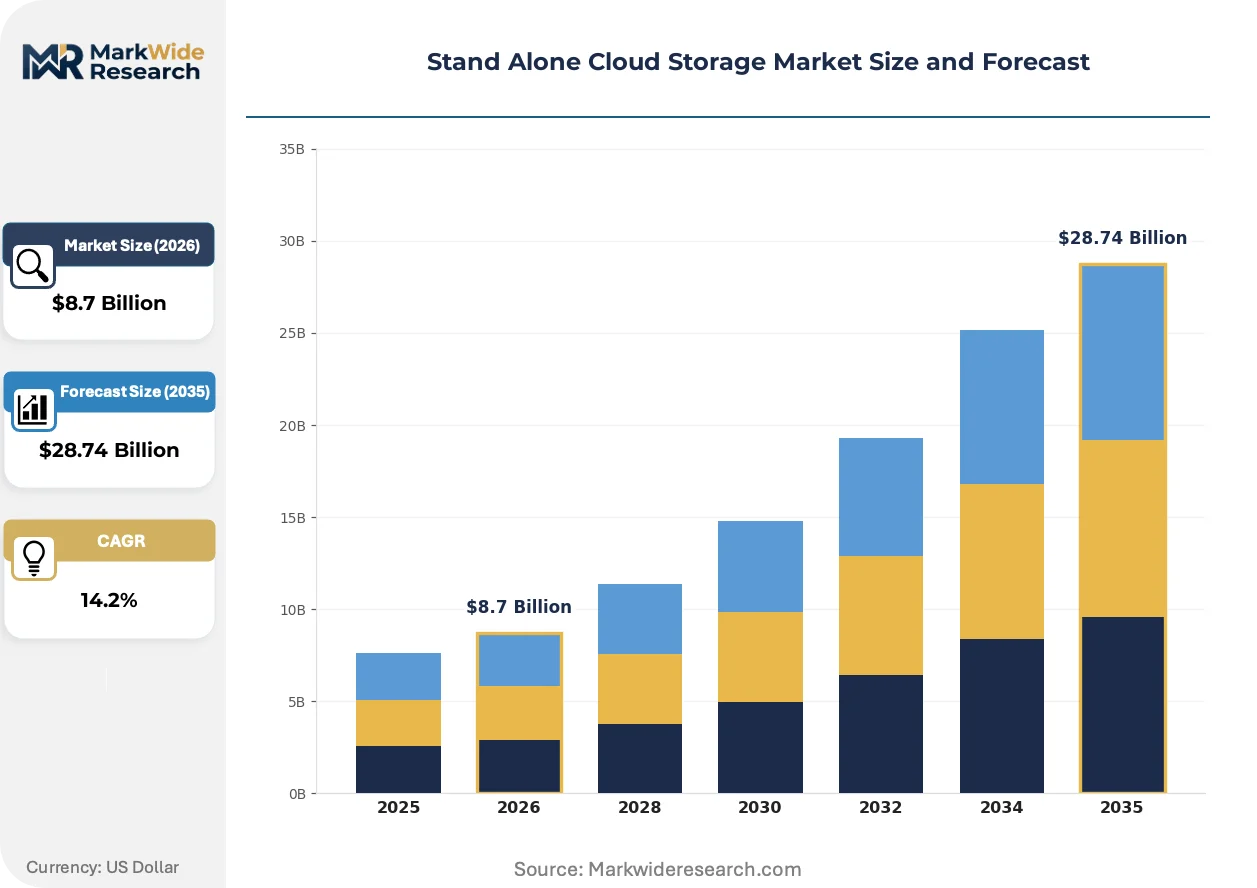
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Solution Type: Backup Solutions, Archiving Solutions, File Sharing Solutions, Synchronization Solutions End User: Small Businesses, Enterprises, Individual Users, Non-Profits Service Model: IaaS, PaaS, SaaS, Managed Services |
| Companies Covered | Amazon Web Services (AWS), Microsoft Azure, Google Cloud Platform, Alibaba Cloud, Oracle Cloud Infrastructure, IBM Cloud, Tencent Cloud, Dropbox, NetApp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stand Alone Cloud Storage Market Emerging Trajectories
Storage architectures are bifurcating between performance-optimized hot tiers and compliance-bound cold repositories. This divergence is reshaping vendor R&D priorities and buyer procurement playbooks.
Immutable object storage is migrating from ransomware recovery insurance to primary compliance infrastructure. Healthcare systems and municipal governments are adopting write-once-read-many buckets as default for sensitive records. This shift is compressing demand for traditional backup software licenses while expanding raw capacity contracts.
Europe's CSRD sustainability disclosure rules are mandating carbon accounting for data center operations. Storage providers must now report embodied emissions from hardware manufacturing and operational power draw. Financial services and multinational manufacturers are prioritizing providers with verified renewable energy matching in EU availability zones.
Consumption-based billing is displacing reserved capacity contracts in mid-market procurement. Buyers are negotiating pay-per-gigabyte arrangements with automatic tiering policies. This pattern is most visible among North American SaaS vendors optimizing cash flow against unpredictable growth trajectories.
Stand Alone Cloud Storage Market Segmentation
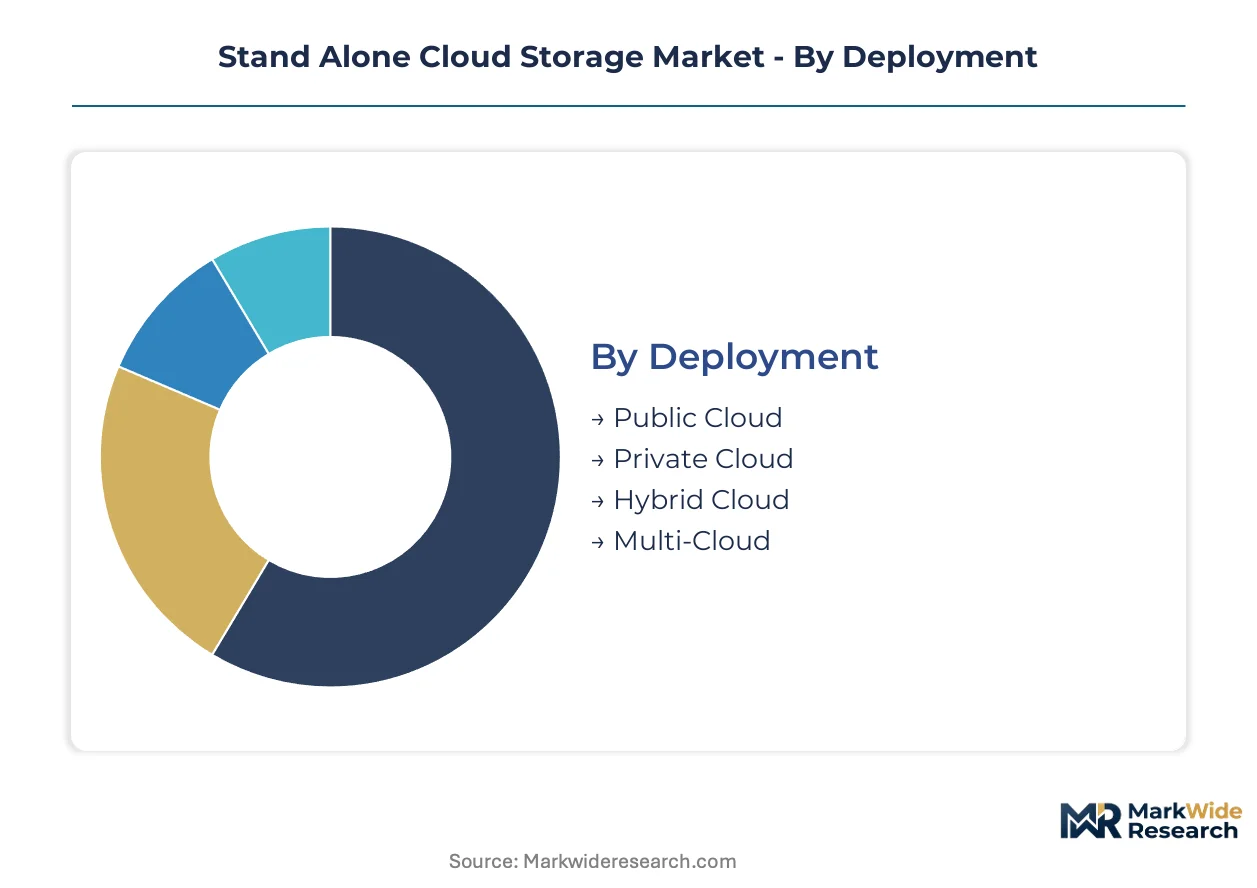
Segmentation in stand alone cloud storage reveals divergent procurement rhythms and margin structures across deployment modes and service tiers. Buyers optimize for sovereignty, latency, or cost depending on workload criticality and regulatory exposure.
Deployment:
Public cloud configurations turn over fastest as enterprises cycle through hyperscale providers, while private cloud deployments lock in capital for multi-year depreciation cycles.
- Public Cloud:Shared infrastructure pools provisioned via API with eleven-nines durability guarantees. Demand concentrates among SaaS vendors in the United States seeking elastic scaling without upfront capex.
- Private Cloud:Dedicated hardware and software stacks deployed on-premises or in single-tenant colocation facilities. Financial services firms in Germany favor this model for GDPR-mandated data residency.
- Hybrid Cloud:Policy-driven orchestration spanning on-premises and off-premises tiers. Healthcare systems use hybrid architectures to keep patient records local while archiving imaging to remote cold storage.
- Multi-Cloud:Abstraction layers distributing workloads across two or more hyperscale providers. Enterprises pursuing vendor diversification and egress fee arbitrage are expanding multi-cloud procurement.
Public cloud dominates installed base. Multi-cloud is where expansion concentrates.
Solution Type:
Backup solutions command the highest transaction velocity with annual contract renewals, while archiving solutions generate decade-long retention lock-in with minimal churn.
- Backup Solutions:Point-in-time recovery systems with incremental snapshot scheduling and cross-region replication. Ransomware resilience mandates are accelerating enterprise procurement in Japan's manufacturing sector.
- Archiving Solutions:Immutable object storage with WORM compliance and legal-hold capabilities. Pharmaceutical manufacturers under FDA 21 CFR Part 11 are contracting petabyte-scale archival tiers.
- File Sharing Solutions:Sync-and-share platforms with granular access controls and mobile endpoint support. Distributed professional services firms are standardizing on enterprise file sharing for client collaboration.
- Synchronization Solutions:Continuous replication engines maintaining consistency across edge and core repositories. Media production houses with globally dispersed editing teams are driving synchronization demand.
Backup solutions anchor recurring revenue. Archiving solutions yield the steepest expansion trajectory as compliance mandates tighten.
End User:
Enterprises negotiate three-year enterprise license agreements with volume commitments, while small businesses purchase monthly subscriptions with no minimums.
- Small Businesses:Sub-100 employee organizations procuring consumption-based storage without dedicated IT staff. India's DPDP Act compliance deadlines are prompting small business migration from consumer-grade to business-tier storage.
- Enterprises:Fortune 500 and equivalent organizations with petabyte-scale requirements and procurement committees. Life sciences digitization under FDA guidelines is expanding enterprise archival spending.
- Individual Users:Consumer and prosumer accounts with gigabyte-tier needs and credit-card billing. Photo and video backup remains the primary use case for individual subscriptions.
- Non-Profits:Mission-driven organizations with constrained budgets and grant-funded technology initiatives. Educational institutions and humanitarian NGOs qualify for donated or discounted storage programs.
Enterprises dominate installed base. Small businesses are where expansion concentrates.
Service Model:
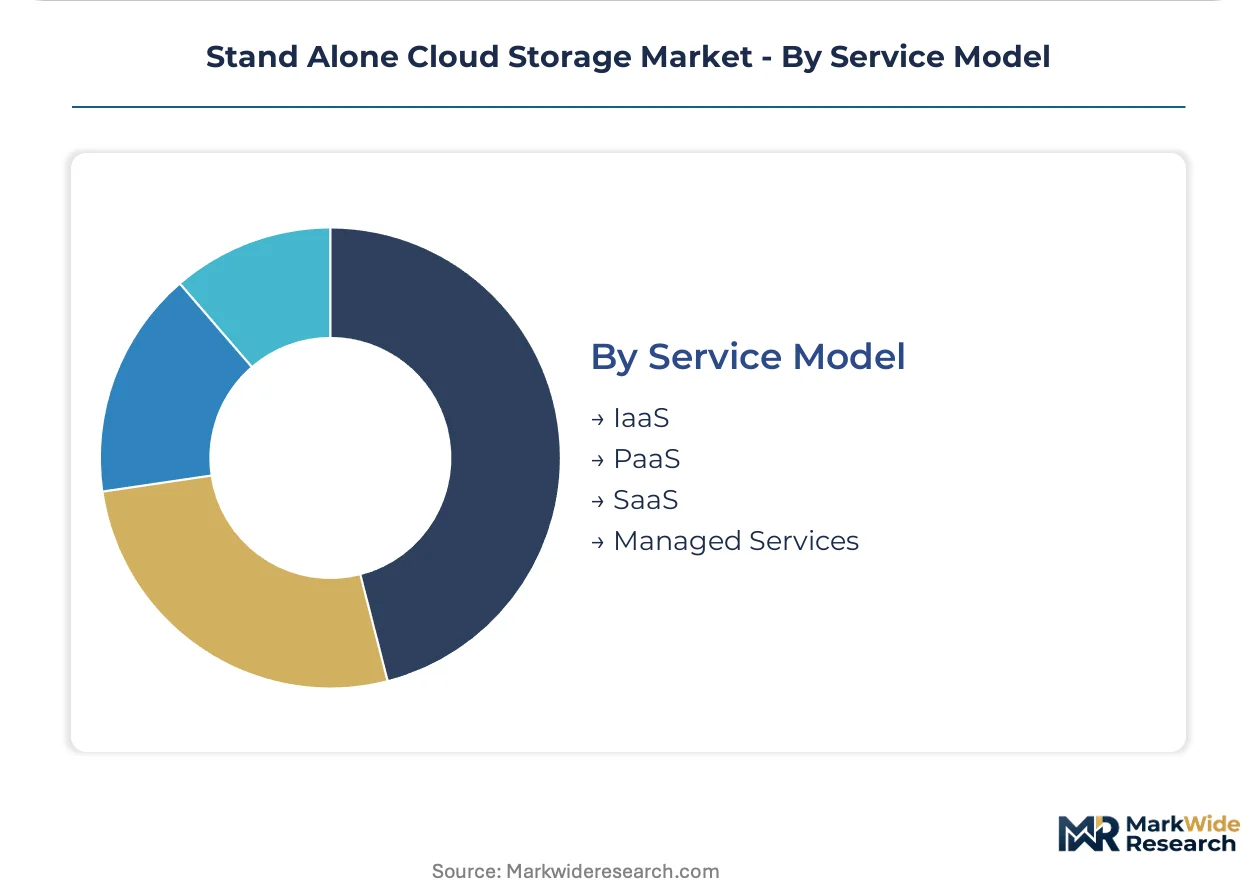
IaaS contracts refresh annually as infrastructure teams rebalance hyperscale commitments, while managed services engagements span five-year outsourcing terms.
- IaaS:Raw compute and storage resources exposed through RESTful APIs and command-line interfaces. Cloud-native application developers in the United States prefer IaaS for maximum architectural control.
- PaaS:Developer-centric environments bundling runtime, middleware, and data services. AI training data lake builders are selecting PaaS storage for integrated pipeline tooling.
- SaaS:Fully managed applications with embedded storage opaque to end users. Productivity suite integration is pulling enterprise procurement toward SaaS-embedded storage tiers.
- Managed Services:Outsourced infrastructure operations with SLAs governing availability, recovery time, and compliance attestation. Regulated industries lacking internal platform expertise are expanding managed services adoption.
IaaS dominates installed base. Managed services are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. United States enterprises prioritize elastic scaling and FinOps integration, while European and Asian buyers anchor procurement decisions on data sovereignty mandates and local regulatory compliance.
United States
Hyperscale operators anchor infrastructure investment in Virginia and Oregon data center clusters. FDA guidelines for electronic records in life sciences drive archival tier procurement from pharmaceutical manufacturers. Enterprise procurement committees in the New York metro area channel petabyte-scale contracts toward certified facilities with renewable energy matching.
Germany
Financial services firms favor private cloud deployments for GDPR-mandated data residency in Frankfurt and Munich facilities. The country's national data protection regulator enforces strict cross-border transfer limitations. Industrial manufacturers in Baden-Württemberg are migrating decades of LTO tape archives to immutable object storage with WORM capabilities.
India
The Data Protection Board is finalizing localization rules under the DPDP Act, prompting first-mover facility construction in Mumbai and Hyderabad. Small businesses with sub-100 employee counts are migrating from consumer-grade to business-tier storage ahead of compliance deadlines. Enterprise procurement in Bangalore's technology corridor concentrates on hybrid architectures balancing latency-sensitive operations against compliance-bound archives.
Japan
Ransomware resilience mandates from METI are accelerating enterprise backup procurement in the manufacturing sector. Pharmaceutical manufacturers under PMDA oversight contract petabyte-scale archival tiers with immutable audit trails. The Kanto region around Tokyo anchors hyperscale availability zone investment, pulling enterprise procurement toward certified local facilities.
United Kingdom
Professional services firms in London standardize on enterprise file sharing solutions for client collaboration. The Information Commissioner's Office enforces GDPR-aligned data localization requirements for sensitive records. Media production houses with globally dispersed editing teams in the Southeast drive demand for continuous synchronization engines.
Stand Alone Cloud Storage Market Vendor Landscape
Capability concentration sits with one tier; scale advantage sits with another. The market structures around three hyperscale operators commanding infrastructure investment and a fragmented tier of specialists competing on compliance certification and vertical expertise. Strategic archetypes include sovereignty-focused regional providers, analytics-optimized platform builders, and tape-to-cloud migration specialists. Dominant competitive moves encompass geographic expansion into mandated localization zones and portfolio diversification toward FinOps-integrated consumption models.
Among hyperscale operators, Amazon Web Services, Microsoft Azure, and Google Cloud Platform exemplify the scale-driven archetype, each anchoring distinct competitive positioning through deep integration with adjacent service ecosystems. These entities occupy positions where infrastructure capex concentration creates gravitational pull on enterprise procurement decisions, particularly in regulated industries requiring certified facility attestation.
| Leading Market Players |
|---|
| Amazon Web Services (AWS) |
| Microsoft Azure |
| Google Cloud Platform |
| Alibaba Cloud |
| Oracle Cloud Infrastructure |
| IBM Cloud |
| Tencent Cloud |
| Dropbox |
| NetApp |
| Others |
Supply Flow & Price Mechanics
Overcapacity in hyperscale availability zones across Virginia and Oregon is compressing spot pricing for object storage tiers while forcing long-term contract renegotiations. This utilization dynamic simultaneously erodes margin buffers for flash-based tier suppliers and accelerates procurement consolidation among enterprise buyers seeking committed-use discounts.
Pricing Analysis
Long-term offtake agreements with three-year volume commitments dominate enterprise procurement, though consumption-based billing gains traction among mid-market SaaS vendors with unpredictable growth trajectories. Pricing stratifies across hot, warm, and cold tiers differentiated by latency guarantees and durability SLAs. Cost compression in archive tiers is intensifying because hyperscale providers are absorbing margin erosion to lock in decade-long retention contracts. Small businesses with sub-100 employee counts exhibit the highest price sensitivity, while pharmaceutical manufacturers under FDA compliance mandates show minimal elasticity for WORM-certified archival tiers.
Supply Chain Analysis
Extended payment terms from hyperscale operators to NAND fabrication facilities in Taiwan and South Korea are restructuring working capital requirements across the storage stack. Hardware manufacturing concentrates in Taiwan, South Korea, and China, with final assembly gravitating toward Malaysia and Mexico. Flash memory supply draws from concentrated wafer fabrication capacity, enterprise-grade hard disk production, and specialized controller chip design. Single-source vulnerability in advanced NAND lithography equipment creates geopolitical exposure. Distribution runs through direct hyperscale API provisioning, channel partner resale, and managed services outsourcing arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform engineering talent scarcity is constraining enterprise adoption of multi-cloud orchestration, creating asymmetric advantage for providers with pre-integrated abstraction layers. Kubernetes-native storage expertise gaps limit buyer ability to execute vendor diversification strategies.
For Market Incumbents: Harden data sovereignty compliance certification across EU, India, and Japan regulatory zones to preempt regional specialist encroachment. Expand Mumbai and Hyderabad facility footprints ahead of DPDP Act enforcement deadlines. Deepen vertical integration into renewable energy procurement to satisfy CSRD carbon disclosure mandates from European financial services buyers. For New Entrants and Emerging Players: India's small business segment migrating from consumer-grade to business-tier storage ahead of DPDP compliance deadlines represents the most penetrable entry point. AI training data lake builders requiring petabyte-scale repositories with high-throughput access constitute a second white-space target. Partner with FinOps tooling vendors to embed storage optimization modules and unlock mid-market channel penetration. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across AI-optimized storage tiers as hyperscale capex concentrates in GPU-adjacent data center clusters. Acquisition targets should demonstrate proven WORM compliance certification and established relationships with pharmaceutical or life sciences procurement committees. Monitor hyperscale availability zone expansion announcements as early signals of regional market share redistribution.| Strategic Initiative | Industry Significance |
|---|---|
| Geographic Expansion into Mandated Localization Zones | EU, India, and Japan data sovereignty enforcement requires in-country facility certification for market access. |
| FinOps-Integrated Consumption Model Development | Channel partnerships with cloud cost management platforms unlock mid-market procurement committee engagement. |
| Immutable Object Storage Platform Launch | FDA 21 CFR Part 11 and ransomware resilience mandates are compressing traditional backup software demand. |
| Renewable Energy Procurement Certification | CSRD sustainability disclosure rules now mandate carbon accounting for EU availability zone operations. |
| Tape-to-Cloud Migration Service Acquisition | Financial services and media archives retain decades of LTO cartridges requiring specialized restoration expertise. |
Methodological Framework
A standing panel of cloud infrastructure architects, enterprise procurement officers, FinOps practitioners, and channel partner executives provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from hyperscaler capex disclosures, SEC 10-K infrastructure investment filings, and EU regulatory enforcement databases. Bottom-up capacity deployment tracking and top-down enterprise spending surveys were triangulated to anchor market sizing.
Scenario-bracketing around data sovereignty enforcement timelines and AI training data lake demand inflection points shaped the analytical framework. Segmentation dimensions modeled include deployment architecture, solution type, end-user scale tier, and service model complexity across the projection horizon. CAGRs were derived from elasticity-adjusted capacity expansion curves and compliance-driven procurement acceleration patterns. Hyperscale availability zone announcement pipelines and DPDP Act implementation phases served as industry-specific forecast inputs.
Practitioners should monitor regulatory enforcement intensity, NAND supply concentration events, and hyperscale pricing tier restructuring for early signals of forecast deviation. The analysis reflects assumptions regarding sustained enterprise cloud migration, continued data sovereignty legislative tightening, and stable geopolitical conditions for semiconductor supply chains. Macroeconomic contraction, trade restriction escalation, or breakthrough edge storage economics would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Storage Solutions
Scale-Out NAS Market
Storage Solutions
Belgium Data Center Storage Market
Storage Solutions
UK Data Center Storage Market
Storage Solutions
Automated Storage and Retrieval Systems in Laboratories Market
Storage Solutions
Cloud Native Storage Market
Storage Solutions
New Zealand Data Center Storage Market
Storage Solutions
Network Attached Storage (NAS) Market
Storage Solutions
Cloud Storage Market
Storage Solutions
Mexico Data Center Storage Market
Storage Solutions
Switzerland Data Center Storage Market
Storage Solutions
Automated Storage and Retrieval System (AS & RS) Market
Storage Solutions
Enterprise File Sync and Share Platform Market
Storage Solutions
Nigeria Data Center Storage Market
Storage Solutions
Consumer Cloud Storage Services Market
Storage Solutions
Consumer Network Attached Storage Market
Storage Solutions
Data Backup and Recovery Market