
 Global Cloud Storage Software Market | 2026-2036
Global Cloud Storage Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cloud Storage Software Market Foresight
Healthcare provider adoption of cloud-based medical imaging archives is consolidating as the fastest-rising end-use vertical, displacing traditional tape-backup dominance in hospital IT budgets. Amazon Web Services sustains technology leadership in object storage throughput for genomic datasets, while Microsoft Azure dominates enterprise hybrid deployments through its extensive private fiber backbone. Google Cloud differentiates on analytics-integrated storage layers that reduce query latency for real-time clinical decision support.
Cloud storage software denotes distributed data persistence platforms that abstract physical storage infrastructure across geographically dispersed server clusters, typically guaranteeing durability through erasure coding with n+2 or n+3 redundancy schemes and automatic failover below 15-second recovery point objectives. The primary commercial purpose centers on replacing capital-intensive on-premises storage area networks with operational-expense models that scale elastically with data volume. Hybrid cloud deployment captures the largest margin pool as enterprises retain sensitive workloads on private infrastructure while bursting analytics to public tiers. Backup and recovery solutions lead solution type revenue, though disaster recovery segments accelerate fastest as ransomware resilience becomes a board-level priority.
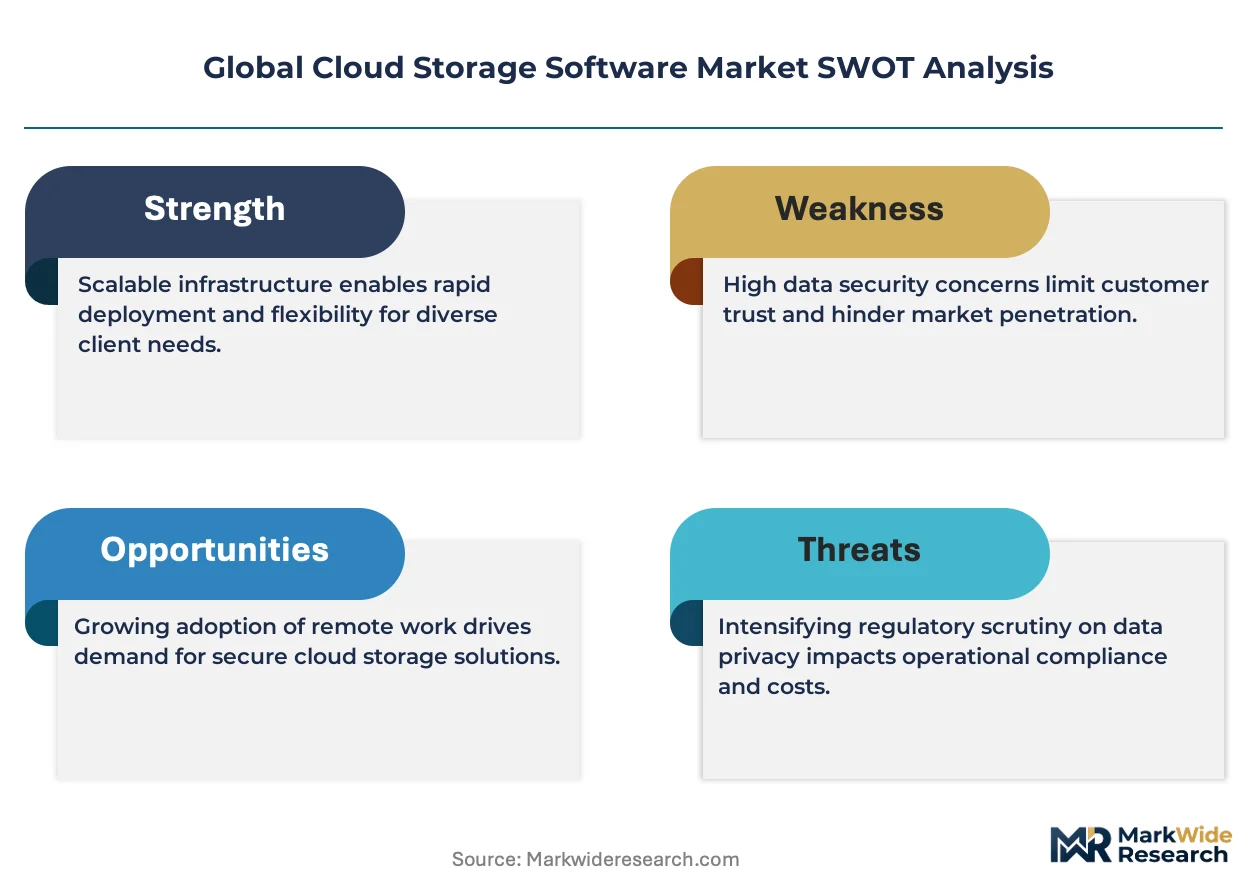
FDA 21 CFR Part 11 guidelines shape healthcare cloud procurement by mandating audit trails and electronic signature integrity for clinical data repositories. EMA's GxP data integrity requirements and the EU AI Act's training data provenance rules compound compliance complexity for pharmaceutical cloud migrations. GDPR Article 44 cross-border transfer mechanisms further constrain architecture choices for multinational deployments. Stakeholders must weigh sovereign cloud certifications against interoperability costs when selecting regional deployment partners.
Market Dynamics
Healthcare providers migrating petabyte-scale medical imaging archives from tape libraries to cloud object storage are compressing procurement cycles and consolidating vendor relationships around platforms that satisfy FDA 21 CFR Part 11 audit requirements.
Growth Catalysts
- Regulatory Compliance Mandates:The EU AI Act's training data provenance rules and GDPR Article 44 cross-border transfer mechanisms are forcing pharmaceutical and healthcare enterprises to adopt sovereign-certified cloud architectures that embed automated compliance tooling.
- Genomic Data Explosion:Precision medicine initiatives at research hospitals and biobanks are generating exabyte-scale genomic datasets that exceed on-premises storage economics, driving demand for erasure-coded object storage with sub-15-second RPO guarantees.
- Industrial Mittelstand Migration:Germany's mid-sized manufacturers are abandoning legacy SAN infrastructure for operational-expense cloud models that eliminate capital-intensive refresh cycles and enable elastic bursting for IoT analytics workloads.
Market Restraints
- Data Residency Fragmentation:Divergent national data sovereignty laws across France, Germany, and Saudi Arabia are compelling vendors to maintain redundant in-country infrastructure, elevating operational costs and complicating unified management plane architectures.
- Encryption Key Escrow Risks:Healthcare and financial services buyers in Switzerland and the UAE are resisting multi-tenant cloud models where encryption key control remains vendor-dependent, slowing public cloud adoption for regulated workloads.
- Legacy Tape Archive Inertia:Hospital IT departments with decades of LTO tape investment and established retrieval workflows face high organizational friction migrating to cloud-native archival tiers despite superior total cost of ownership.
Strategic Opportunities
- Edge-to-Core Federated Storage:Converging 5G network slicing with distributed cloud storage nodes enables real-time medical imaging preprocessing at hospital edge locations before central cloud archival, opening new service revenue streams for telecom-cloud partnerships.
- Carbon-Aware Storage Tiers:The EU Green Deal's embodied carbon disclosure requirements and CSRD reporting mandates are creating preference for storage providers offering granular carbon intensity metrics and renewable-energy-matched availability zones.
- India's Healthcare Digitization:The country's Ayushman Bharat digital health mission and PLI scheme for data center infrastructure are catalyzing demand for compliant medical record clouds among private hospital chains and diagnostic networks.
Industry Challenges
- Multi-Cloud Orchestration Talent Scarcity:Enterprise storage architects with demonstrated expertise in Kubernetes-native data services, cross-cloud replication policies, and FinOps cost optimization command premium compensation that mid-market buyers struggle to afford.
- Ransomware Recovery Validation:Immutable backup architectures and air-gapped recovery workflows require continuous purple-team testing that strains security operations capacity, with many organizations discovering coverage gaps only during actual incidents.
- Interoperability Certification Delays:EHR vendors and PACS providers maintain proprietary data formats that complicate cloud migration, with DICOM standard extensions and HL7 FHIR mapping projects extending integration timelines by quarters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cloud Storage Software Market |
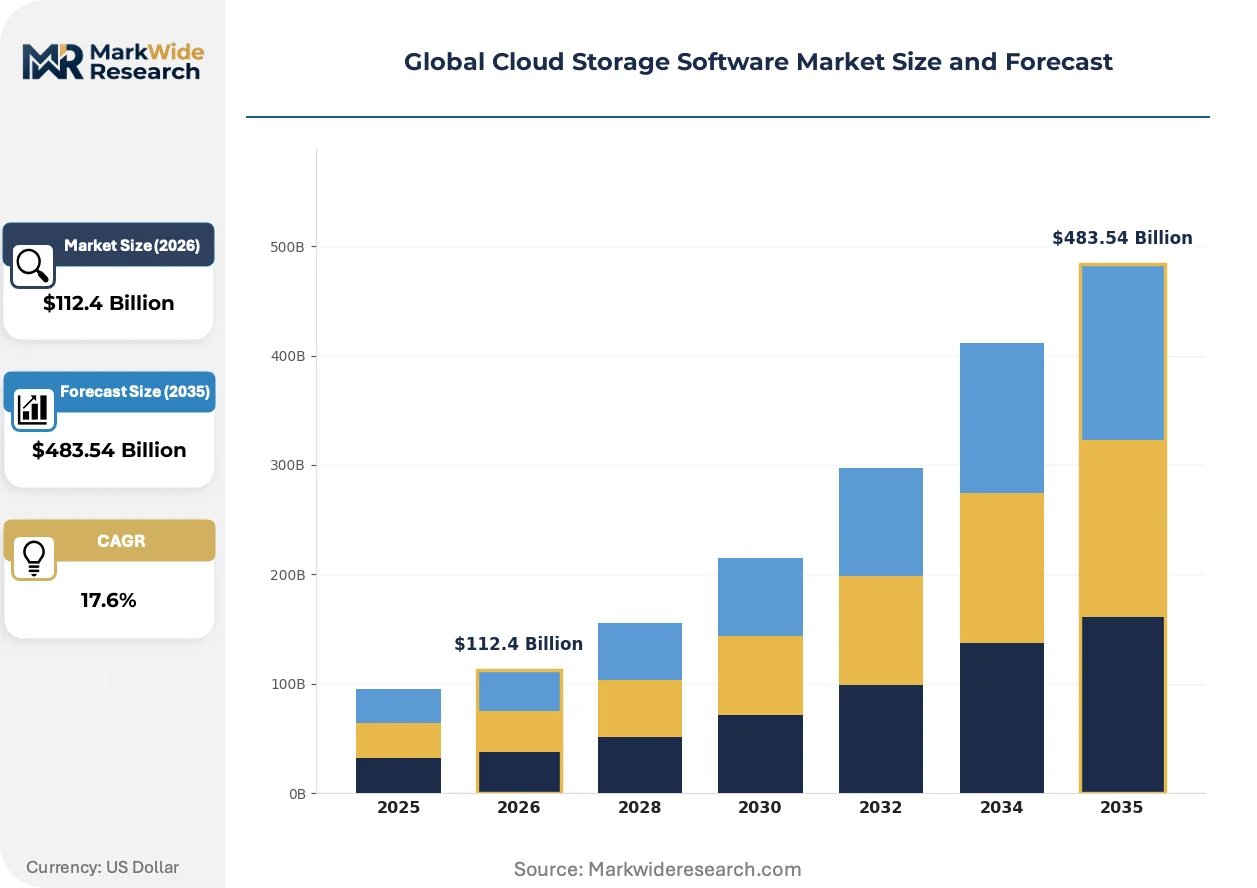
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $483.54 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Solution Type: Backup & Recovery, Archiving, File Sharing, Disaster Recovery, Collaboration Tools Use Case: Data Management, Compliance & Security, Content Delivery, Application Hosting, Analytics End User: IT Services, Telecommunication Providers, Financial Services Firms, Media & Entertainment Studios, Education Institutions |
| Companies Covered | Amazon Web Services, Microsoft Azure, Google Cloud, Alibaba Cloud, Oracle Cloud Infrastructure, IBM Cloud, Dropbox, Dell Technologies, Hewlett Packard Enterprise, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cloud Storage Software Market Shifts & Advancements
Software-defined storage controllers are absorbing functions previously resident in dedicated hardware appliances, collapsing the distinction between primary and secondary storage tiers while embedding AI-driven data placement optimization.
Intelligent tiering engines with machine learning-based access pattern prediction are integrating predictive caching algorithms that automatically promote cold medical imaging studies to hot tiers ahead of scheduled oncology tumor board reviews. Hospital radiology departments at academic medical centers are deploying these capabilities to eliminate retrieval latency for comparative diagnostic reads. This compression of storage economics is enabling institutions to retain full-fidelity imaging indefinitely rather than destructive compression.
The EU AI Act's risk-based classification system for AI-enabled clinical decision support is mandating training data lineage documentation that extends backward through storage infrastructure audit trails. Pharmaceutical sponsors conducting decentralized clinical trials must now demonstrate immutable provenance for every dataset feeding algorithmic endpoints. Contract research organizations are responding by procuring storage platforms with embedded blockchain-anchored timestamping and cryptographic verification.
Consumption-based billing models with granular per-gigabyte, per-operation, and per-egress pricing are displacing capacity-commitment contracts among mid-market healthcare providers that experienced dramatic utilization volatility during pandemic-era telehealth expansion. Value-added resellers and managed service providers are capturing margin by aggregating demand across independent physician practices and negotiating enterprise-tier discounts unavailable to individual buyers. This channel consolidation is most advanced in the United States, where private equity-backed dental and ophthalmology roll-ups are standardizing on single cloud storage backbones across acquired practices.
Global Cloud Storage Software Market Segmentation
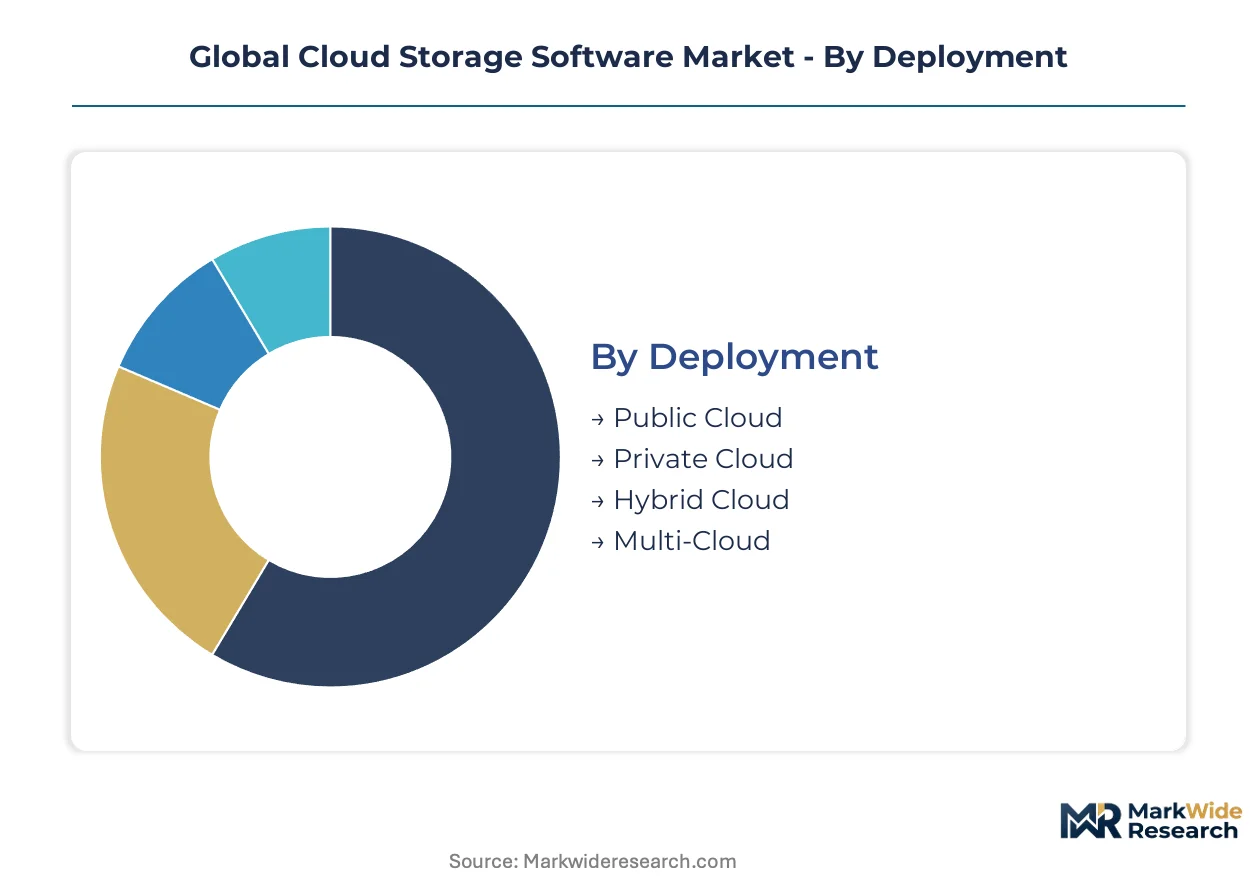
Cloud storage software procurement patterns diverge sharply across deployment architectures and solution types, with enterprise buyers prioritizing compliance certifications over raw performance metrics. Understanding segment-level upgrade cycles reveals where vendor consolidation and margin expansion concentrate.
Deployment:
Legacy infrastructure refresh cycles are accelerating as on-premises storage area networks reach end-of-life, forcing enterprises to evaluate operational-expense models against capital-intensive replacement.
- Public Cloud:Multi-tenant object storage platforms deliver elastic scalability through erasure-coded redundancy across geographically distributed availability zones. Healthcare providers in Germany favor sovereign-certified public tiers for medical imaging archives subject to GDPR Article 44 transfer restrictions.
- Private Cloud:Dedicated infrastructure deployments retain sensitive workloads on-premises while virtualizing storage controllers through software-defined architectures. Swiss financial institutions mandate private cloud for encryption key escrow control under national banking secrecy frameworks.
- Hybrid Cloud:Unified management planes orchestrate data placement across on-premises and public tiers based on access frequency and compliance classification. Industrial manufacturers in the Mittelstand segment leverage hybrid bursting for IoT analytics during production peaks.
- Multi-Cloud:Abstraction layers prevent vendor lock-in by enabling workload portability across competing hyperscaler platforms. Enterprise architects deploy multi-cloud strategies to satisfy divergent regional data residency requirements without redundant infrastructure investment.
Hybrid Cloud sits at the top of the volume ranking, with Multi-Cloud climbing the fastest as procurement teams diversify supplier risk.
Solution Type:
Cost tier differentiation separates commodity backup offerings from premium disaster recovery suites that command annual recurring revenue multiples.
- Backup & Recovery:Scheduled snapshot replication with immutable versioning protects against ransomware encryption attacks through air-gapped recovery points. Hospital IT departments prioritize backup solutions with FDA 21 CFR Part 11 audit trail compatibility for clinical data repositories.
- Archiving:Cold tier storage with retrieval latency measured in minutes to hours replaces legacy LTO tape libraries for long-term data retention. Pharmaceutical sponsors conducting decentralized clinical trials deploy archiving with blockchain-anchored provenance to satisfy EU AI Act training data lineage mandates.
- File Sharing:Synchronized collaboration workspaces with granular permission controls and real-time conflict resolution. Media production studios in Los Angeles and Mumbai leverage high-throughput file sharing for distributed post-production workflows.
- Disaster Recovery:Automated failover orchestration with sub-15-minute recovery time objectives and continuous data protection replication. Financial services firms in Singapore and Dubai mandate disaster recovery certification for regulatory operational resilience frameworks.
- Collaboration Tools:Integrated document editing, version control, and workflow automation within unified storage namespaces. Education institutions deploying learning management systems require collaboration tools with FERPA-compliant access logging.
Backup & Recovery leads absolute revenue contribution, while Disaster Recovery expands most quickly as board-level ransomware resilience elevates procurement priority.
Use Case:
Application-specific storage configurations concentrate demand around analytics-integrated layers that reduce query latency for real-time decision support.
- Data Management:Unified metadata catalogs with automated classification, lifecycle policies, and cross-platform search indexing. Research hospitals managing exabyte-scale genomic datasets deploy data management with intelligent tiering based on access pattern prediction.
- Compliance & Security:Immutable audit logs, encryption key management, and automated regulatory reporting for multi-jurisdictional deployments. Contract research organizations require compliance tooling that embeds EMA GxP data integrity verification.
- Content Delivery:Globally distributed edge caching with origin shielding and dynamic image optimization for low-latency media streaming. Over-the-top video platforms in India and Brazil leverage content delivery storage to serve subscriber growth without infrastructure provisioning delays.
- Application Hosting:Container-native persistent volumes with snapshot consistency for stateful microservices orchestration. Telecommunication providers deploying 5G network functions virtualization rely on application hosting storage for sub-millisecond latency guarantees.
- Analytics:Query-optimized columnar formats with predicate pushdown and vectorized execution for business intelligence workloads. Retail chains in Japan and South Korea integrate analytics storage with point-of-sale transaction streams for real-time inventory optimization.
Data Management commands the largest installed base, with Analytics gaining share fastest as machine learning pipelines proliferate across enterprise data estates.
End User:
Customer type determines pricing architecture, with regulated industries accepting premium tiers for sovereign certification and audit documentation.
- IT Services:Managed service providers aggregate demand across mid-market clients to negotiate enterprise-tier volume discounts unavailable to individual buyers. MSPs in the United States standardize on single cloud storage backbones across private equity-backed practice roll-ups.
- Telecommunication Providers:Edge-to-core federated architectures converging 5G network slicing with distributed storage nodes for real-time preprocessing. European telecom operators partner with hyperscalers to deploy hospital-edge imaging nodes before central cloud archival.
- Financial Services Firms:Immutable ledger storage with cryptographic verification for trade reconstruction and regulatory examination readiness. Swiss and UAE banking regulators resist multi-tenant models where encryption key control remains vendor-dependent.
- Media & Entertainment Studios:High-throughput object storage for uncompressed 4K/8K video workflows with frame-accurate editing over wide-area networks. Production facilities in London and Vancouver require storage with granular carbon intensity metrics under EU Green Deal disclosure mandates.
- Education Institutions:Cost-optimized archival tiers for research dataset preservation with federated identity integration for multi-institutional collaboration. Indian universities participating in the Ayushman Bharat digital health mission procure compliant medical record clouds for teaching hospital networks.
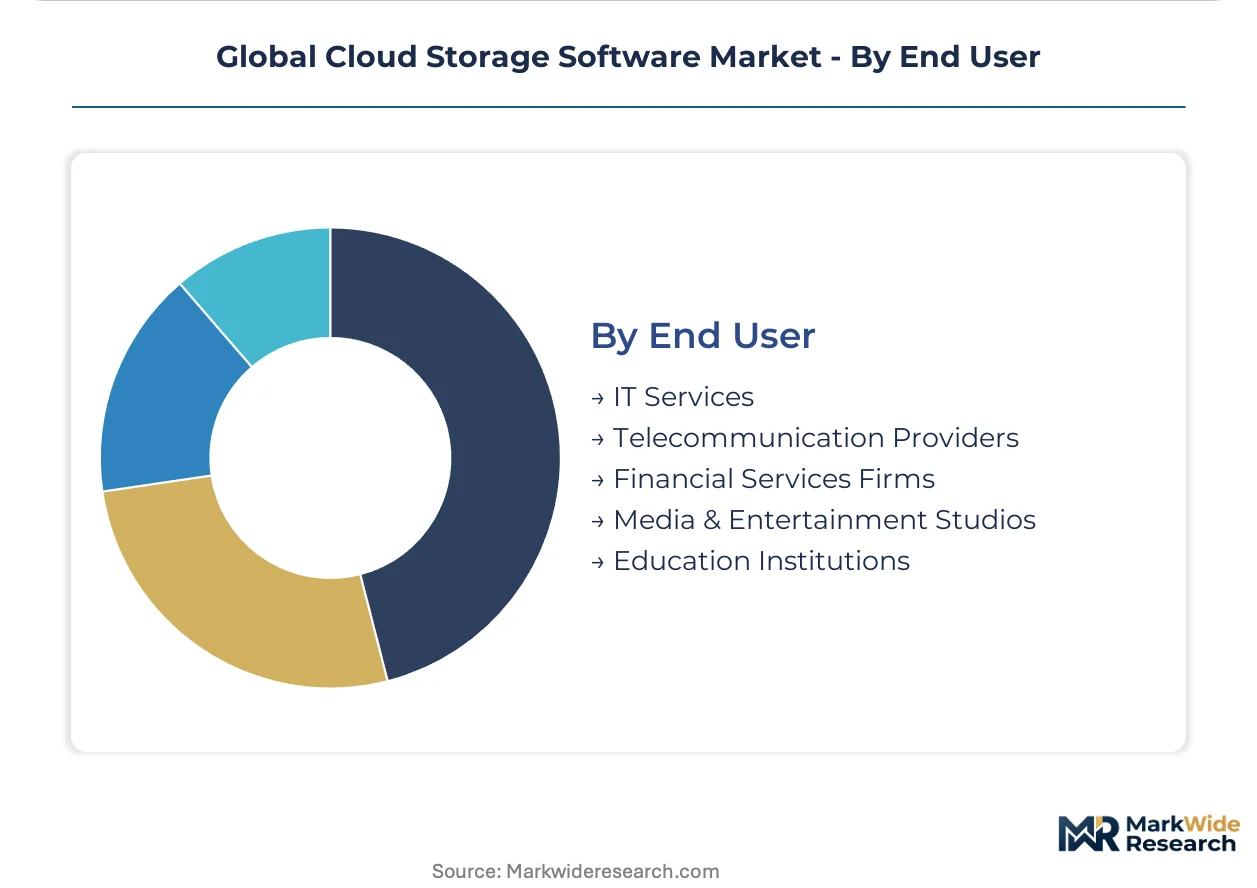
IT Services represents the deepest vertical penetration, with Telecommunication Providers expanding most rapidly as network-edge storage nodes proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial Mittelstand concentration anchors the most acute migration activity, with sovereign cloud procurement reshaping vendor selection criteria across automotive, pharmaceutical, and precision manufacturing clusters.
United States
Healthcare providers in Boston and the Research Triangle compress procurement cycles around FDA 21 CFR Part 11-compliant platforms for genomic datasets and medical imaging archives. Private equity-backed dental and ophthalmology roll-ups standardize on single cloud storage backbones across acquired practices, consolidating channel demand through managed service providers.
Germany
Industrial manufacturers in Baden-Württemberg and Bavaria abandon legacy SAN infrastructure for operational-expense models under GDPR Article 44 transfer restrictions. The EU AI Act's training data provenance rules compel pharmaceutical sponsors in Frankfurt-Rhine-Main to procure storage with embedded blockchain-anchored timestamping for decentralized clinical trials.
China
Domestic cloud operators capture biobank and precision medicine workloads as dual carbon goals and data localization requirements reshape procurement. Research hospitals in Shanghai and Beijing generate exabyte-scale genomic datasets that exceed on-premises economics, driving demand for erasure-coded object storage with sub-15-second RPO guarantees.
India
The Ayushman Bharat digital health mission and PLI scheme for data center infrastructure catalyze compliant medical record cloud adoption among private hospital chains in Maharashtra and Karnataka. Diagnostic networks in Delhi-NCR and Telangana deploy sovereign-certified tiers to satisfy emerging data residency frameworks for cross-border research collaboration.
Switzerland
Financial institutions in Zurich and Geneva mandate private cloud deployments for encryption key escrow control under national banking secrecy frameworks. Healthcare buyers resist multi-tenant models where key control remains vendor-dependent, slowing public cloud adoption for regulated workloads despite superior total cost of ownership economics.
Global Cloud Storage Software Market Competitive Landscape
Strategic partnerships dominate the current landscape as hyperscalers embed compliance tooling and sovereign certifications to capture regulated verticals. The vendor base concentrates around three technology archetypes: hyperscale public cloud operators with dedicated healthcare and financial services lanes, legacy infrastructure vendors pivoting to software-defined storage controllers, and regional sovereign cloud specialists. Portfolio diversification and geographic expansion through local partnership networks constitute the primary competitive moves, with M&A activity concentrated in edge-to-core orchestration and FinOps optimization capabilities.
Within the hyperscale tier, Amazon Web Services, Microsoft Azure, and Google Cloud occupy positions defined by throughput specialization, hybrid deployment dominance, and analytics-integrated storage layers respectively. Each anchors distinct procurement preferences: AWS captures genomic dataset workloads through object storage performance, Azure secures enterprise hybrid deployments via private fiber backbone extension, and Google Cloud targets real-time clinical decision support through query-optimized architectures. Regional specialists including Alibaba Cloud and Oracle Cloud Infrastructure exemplify sovereign certification strategies that satisfy data residency fragmentation across divergent national frameworks.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Azure |
| Google Cloud |
| Alibaba Cloud |
| Oracle Cloud Infrastructure |
| IBM Cloud |
| Dropbox |
| Dell Technologies |
| Hewlett Packard Enterprise |
| Others |
Supply & Pricing Matrix
Data center energy costs in Germany feed directly into sovereign cloud pricing premiums, with Mittelstand manufacturers absorbing elevated operational-expense rates to satisfy GDPR Article 44 residency mandates while Indian buyers access carbon-intensive but tariff-shielded domestic infrastructure under PLI scheme subsidies.
Pricing Analysis
Distributor margins on sovereign-certified tiers compress as hyperscalers deploy direct enterprise sales teams. Subscription SaaS-tiered models dominate, with price differentiation driven by FDA 21 CFR Part 11 certification grade and volume commit scale. Pricing pressure intensifies in backup and recovery segments as ransomware resilience commoditizes air-gapped architectures. Mid-market healthcare providers exhibit highest price sensitivity, while Swiss financial institutions accept premium tiers for encryption key escrow control.
Supply Chain Analysis
Server hardware supply rests on Taiwanese ODMs, South Korean memory fabricators, and Chinese rare earth processors for magnetic storage substrates. Hyperscaler capex cycles draw from semiconductor foundry output, precision cooling systems, and renewable energy PPAs. Single-source vulnerability concentrates in advanced node GPU supply for AI-integrated storage tiers. Distribution runs through direct hyperscaler contracts and managed service provider aggregators serving mid-market buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sovereign cloud procurement in Germany commands 40-60% pricing premiums over standard public tiers, creating arbitrage incentive for vendors to replicate certification infrastructure in India where PLI scheme subsidies offset compliance buildout costs.
For Market Incumbents: Deploy sovereign certification leverage to defend against emerging regional specialists capturing Mittelstand workloads. Backward integration into edge hardware manufacturing secures 5G network slicing partnerships with European telecom operators. Channel control through managed service provider exclusivity agreements locks in private equity-backed healthcare roll-ups before competitors replicate FDA-compliant audit tooling. For New Entrants and Emerging Players: Direct-to-OEM digital routes bypass hyperscaler-dominated procurement committees. India's Ayushman Bharat digitization presents the most penetrable white-space, with compliant medical record clouds for diagnostic networks lacking sovereign-certified alternatives. Go-to-market through system integrators bundling storage with hospital information system deployments accelerates reference customer acquisition. For Investors and Strategic Acquirers: Consolidation pressure builds where multi-cloud orchestration talent scarcity fragments mid-market service delivery. Long-term viability favors platforms embedding automated compliance tooling for EU AI Act training data provenance. Acquisition targets include edge-to-core orchestration specialists and FinOps optimization SaaS vendors. Watch hyperscaler capex allocation shifts toward sovereign infrastructure as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | GDPR Article 44 compliance unlocks German Mittelstand procurement budgets previously blocked. |
| Edge-to-Core Partnership | 5G network slicing with telecom operators enables real-time medical imaging preprocessing at hospital locations. |
| FinOps Capability Acquisition | Cost optimization tooling addresses mid-market buyer talent scarcity and margin compression. |
| Blockchain-Anchored Provenance | EU AI Act training data lineage mandates drive pharmaceutical sponsor platform switching. |
| Carbon-Aware Tier Development | CSRD disclosure requirements create preference for renewable-energy-matched availability zones. |
Research Methodology
Bottom-up healthcare provider and industrial manufacturer modeling reconciled against top-down hyperscaler capex tracking forms the analytical core. Primary interviews with hospital IT directors, pharmaceutical data management leads, Mittelstand operations managers, and sovereign cloud procurement officers combined with secondary validation from SEC filings, EMA GxP guidance documents, GDPR Article 44 regulatory texts, and hyperscaler infrastructure expansion disclosures. Cross-referencing deployment architecture adoption rates against solution type revenue reporting enables triangulation.
Input-output matrices map data volume growth drivers through segmentation dimensions including deployment model, organization size, vertical compliance intensity, and regional regulatory framework. CAGRs derive from curve-fitting historical adoption patterns against projected infrastructure buildout across the analysis window. Forecast inputs incorporate genomic dataset generation rates at research hospitals and IoT sensor deployment trajectories in industrial manufacturing clusters.
The model assumes a particular technology adoption path; alternative pathways for quantum-resistant encryption would alter the outlook for long-term archival tier security positioning. Forecasts reflect assumptions regarding sovereign certification harmonization across EU member states. Material deviation in GDPR enforcement intensity or hyperscaler data center permitting timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Storage Solutions
Nigeria Data Center Storage Market
Storage Solutions
Global Server Storage Area Network Market
Storage Solutions
Virtual Machine Backup and Recovery Market
Storage Solutions
Austria Data Center Storage Market
Storage Solutions
Hard Disk Market
Storage Solutions
Storage Software Market
Storage Solutions
Copy Data Management Software Market
Storage Solutions
Global Enterprise File Sharing and Synchronization (EFSS) Market
Storage Solutions
Netherlands Data Center Storage Market
Storage Solutions
Saudi Arabia Data Center Storage Market
Storage Solutions
United Arab Emirates Data Center Storage Market
Storage Solutions
South Africa Data Center Storage Market
Storage Solutions
India Data Center Storage Market
Storage Solutions
Spain Data Center Storage Market
Storage Solutions
Switzerland Data Center Storage Market
Storage Solutions
Sweden Data Center Storage Market