
 Cloud Engineering Market | 2026-2036
Cloud Engineering Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Engineering Market Intelligence
The replacement of monolithic, on-premise IT infrastructure with distributed, microservices-based architectures is shifting the fundamental economics of software development and deployment. Amazon Web Services dominates the underlying infrastructure layer, providing the foundational tools for this transition. Service providers like Accenture and ScienceSoft then specialize in architecting and managing these complex cloud environments for enterprise clients. These firms compete on the basis of certified expertise and industry-specific solution frameworks.
Cloud engineering encompasses the design, implementation, and management of applications and systems on cloud computing platforms. It involves applying engineering principles to orchestrate services like compute, storage, and networking using automation and code-based infrastructure management. While Infrastructure as a Service (IaaS) forms the foundational revenue base, Platform as a Service (PaaS) and Function as a Service (FaaS) are showing higher growth rates. The adoption of technology stacks built on containers and serverless computing is accelerating the move towards multi-cloud and hybrid cloud deployment models.
Data sovereignty and privacy regulations, including Europe's GDPR and the US HIPAA, dictate cloud architecture choices, particularly in healthcare and finance. Concurrently, standards from bodies like the ISO, such as ISO/IEC 27017 for cloud security, establish benchmarks for service provider credibility and enterprise procurement. Navigating the patchwork of national data localization laws while optimizing for cost and performance remains the central strategic challenge for enterprise cloud architects.
Market Dynamics
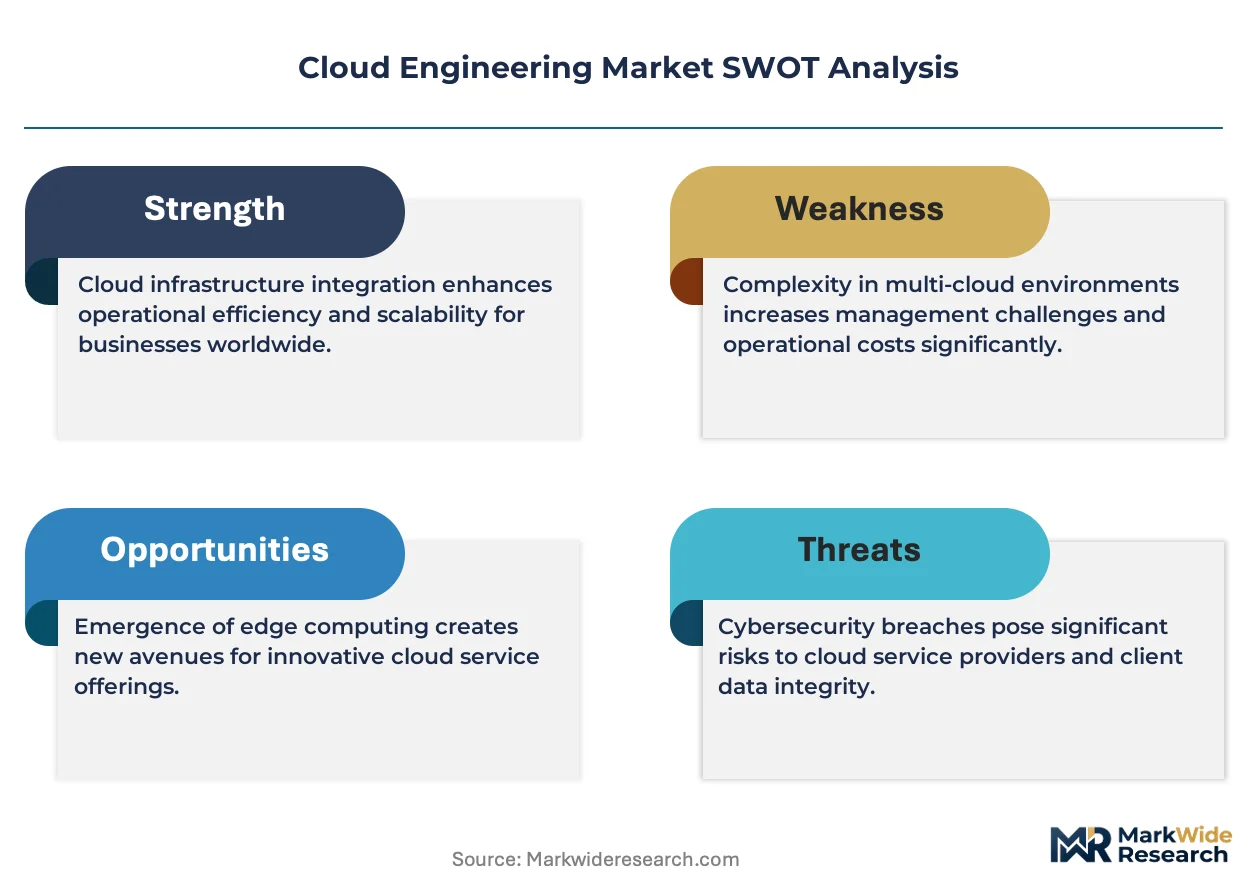
The proliferation of national data sovereignty laws, exemplified by Europe's GDPR and India's data localization rules, is the central force shaping cloud architecture. This regulatory pressure compels enterprises to adopt complex multi-cloud and hybrid strategies for compliance.
Growth Catalysts
- Regulatory Mandates:The EU AI Act requires governable AI systems, necessitating cloud engineering for data lineage, monitoring, and compliance reporting.
- BFSI Sector Adoption:Financial institutions are migrating core platforms to the cloud for scalability and security, driving demand for specialized FinOps engineering.
- Container Orchestration:Platforms like Kubernetes accelerate the move from monolithic architectures to portable microservices across different cloud providers.
Market Restraints
- Cost Unpredictability:Opaque data egress fees from major providers create significant financial risk and budget volatility for multi-cloud strategies.
- Technical Complexity:Managing security and interoperability across disparate cloud platforms introduces complexity that exceeds the skills of many IT teams.
- Data Localization Laws:National data residency rules in geographies like India and China complicate global application architecture and increase overhead.
Strategic Opportunities
- Edge Computing Integration:Combining cloud with edge computing opens new markets for low-latency applications in manufacturing and autonomous systems.
- Specialized AI Platforms:Building managed cloud platforms for training and deploying large language models addresses a high-value market need.
- Green Cloud Solutions:Offering services for carbon footprint optimization helps enterprises meet sustainability goals under mandates like the EU's CSRD.
Industry Challenges
- Talent Scarcity:A shortage of engineers with certified expertise in multi-cloud architecture and cybersecurity constrains project timelines and enterprise adoption.
- Legacy System Integration:Connecting modern cloud applications with aging on-premise systems within hybrid models creates significant technical and security hurdles.
- Compliance Burden:Maintaining continuous compliance with standards like ISO/IEC 27017 across multiple cloud environments is a resource-intensive task.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Engineering Market |
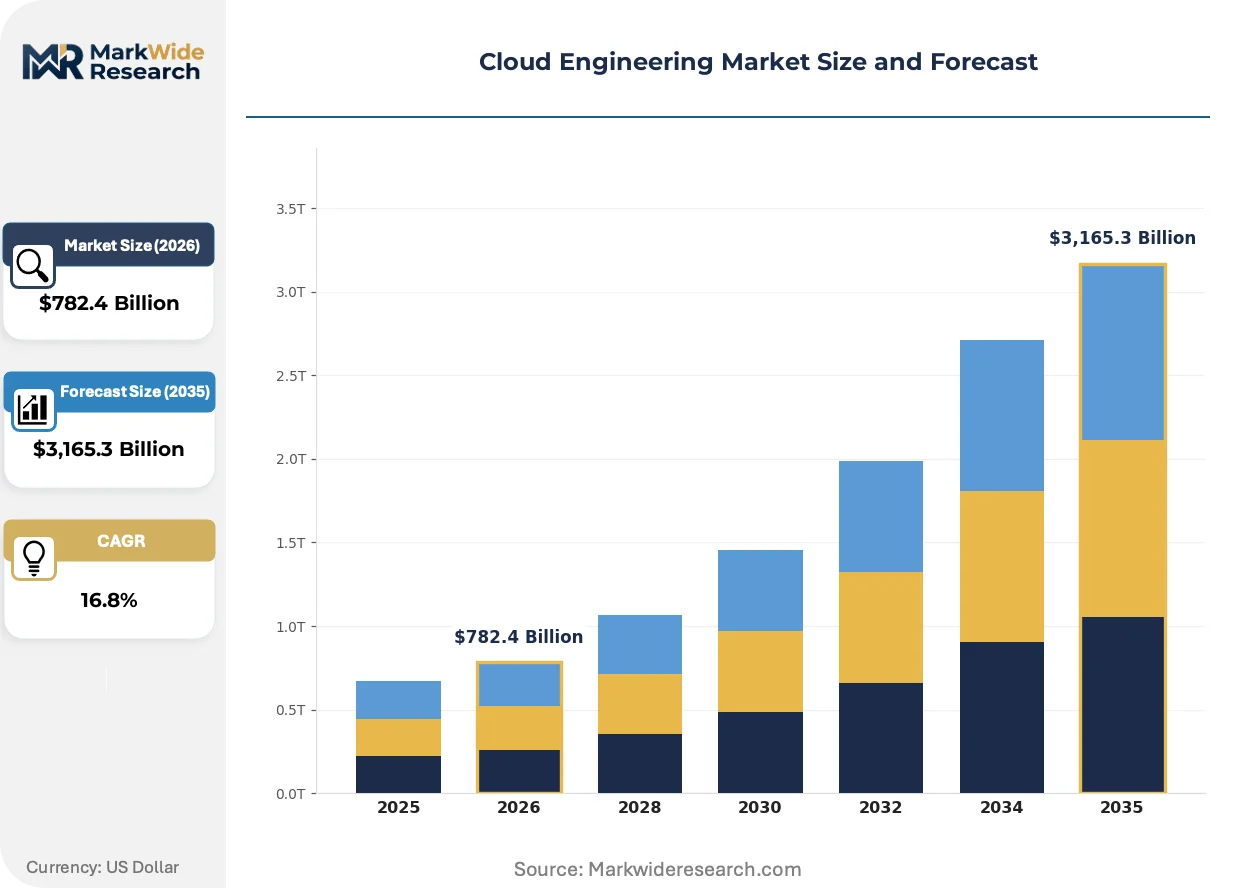
| Market Size in 2026 | $782.4 Billion |
| Market Size in 2035 | $3,165.3 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Type: Infrastructure as a Service, Platform as a Service, Software as a Service, Function as a Service End User Sector: Healthcare, Retail, BFSI, Education Technology Stack: Microservices, Containers, Serverless Computing, DevOps |
| Companies Covered | Amazon Web Services, Accenture, ScienceSoft, DataArt, Radixweb, Closeloop Technologies, Instinctools, Jade Global, Spellbind, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Engineering Market Strategic Shifts & Innovations
Automation and abstraction are fundamentally altering cloud engineering practices, shifting focus from manual infrastructure configuration to policy-driven orchestration. This evolution enables greater scale and developer autonomy but also introduces new layers of complexity.
Serverless computing, or Function as a Service (FaaS), provides event-driven compute without the need to manage underlying servers. Enterprises in retail and media are rapidly adopting this model for its cost efficiency and scalability. The technology is expanding into the domain of core business logic, replacing traditional microservices for certain back-end workloads.
The European Union's AI Act imposes stringent requirements for the governance and transparency of artificial intelligence systems. Its implementation is forcing cloud engineers to design and build auditable data pipelines and model lifecycle management tools. Sectors like finance and healthcare in Germany and France are particularly affected, prioritizing architectures that support explainability and risk assessment.
Enterprise buying behavior is moving away from single-vendor cloud strategies toward deliberate multi-cloud and hybrid-cloud deployments. This shift prioritizes workload portability and avoids vendor lock-in, disrupting the dominance of a single provider for all services. The pattern is most visible in large financial services and technology companies across the United States and Europe.
Cloud Engineering Market Segmentation
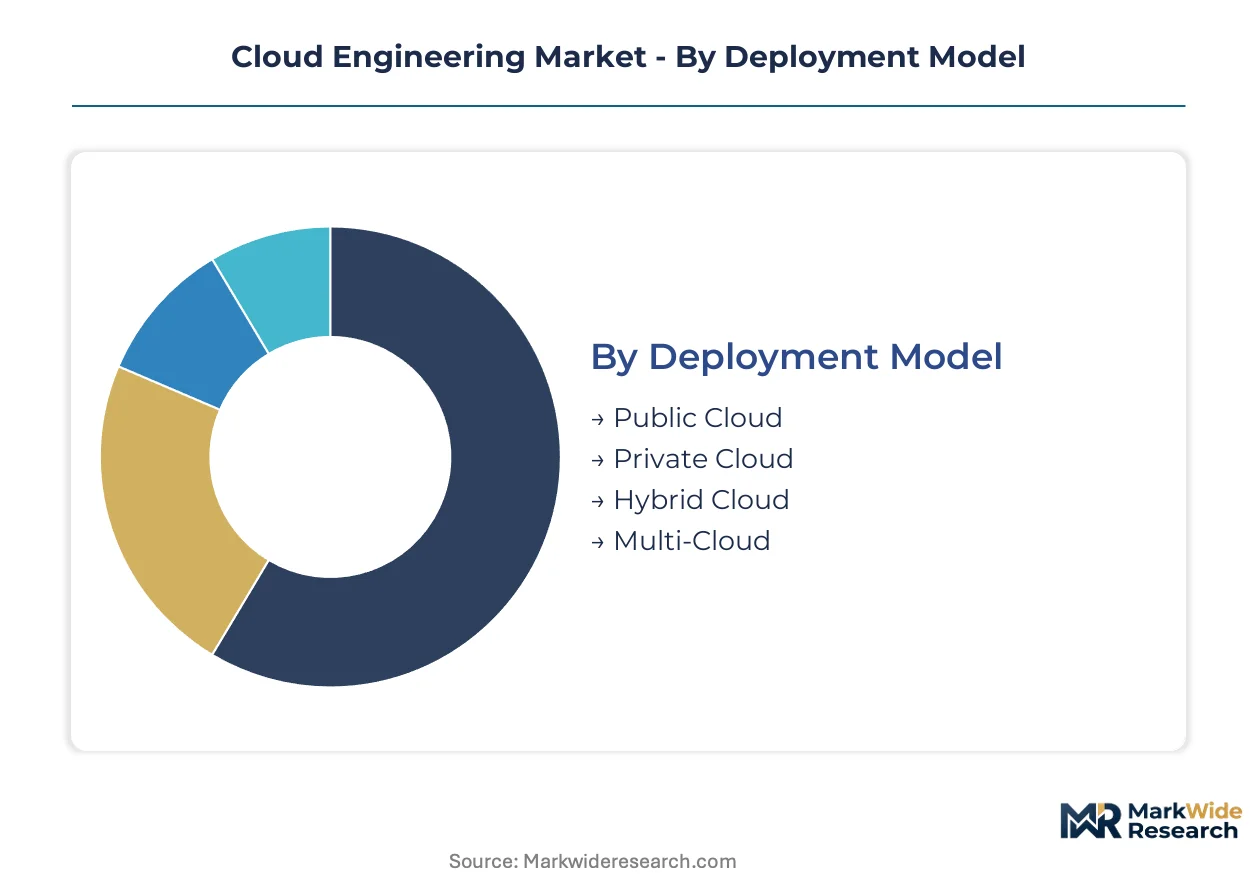
The cloud engineering market categorizes solutions based on deployment architectures, service delivery models, end-user industry applications, and underlying technology components. Understanding these segments clarifies how enterprises consume and implement cloud strategies, influencing vendor specialization and market demand patterns.
Deployment Model:
The technology axis for cloud deployment defines how infrastructure resources are provisioned and managed across various environments.
- Public Cloud:This model delivers computing services over the public internet, making resources like servers and storage available to multiple customers on demand. Financial institutions in the United States often leverage public cloud for non-sensitive workloads due to its scalability and cost-efficiency.
- Hybrid Cloud:Hybrid cloud integrates on-premise infrastructure with public cloud services, allowing data and applications to move between environments. German enterprises adopt hybrid strategies for compliance with national data sovereignty laws while retaining flexibility for burst capacity.
- Private Cloud:Private cloud resources are used exclusively by a single organization, either on-premises or hosted by a third party. This model offers enhanced security and control, favored by government agencies and highly regulated sectors for sensitive data.
- Multi-Cloud:Multi-cloud involves using multiple public cloud services from different providers, often to avoid vendor lock-in and optimize for specific workloads. Technology companies in India utilize multi-cloud to distribute risk and leverage best-of-breed services from various providers.
Public Cloud leads on scale; Hybrid Cloud leads on momentum.
Service Type:
The value proposition for cloud services dictates the level of abstraction and management responsibilities undertaken by the provider versus the consumer.
- Infrastructure as a Service (IaaS):IaaS provides virtualized computing resources over the internet, including virtual machines, storage, and networking. Enterprises use IaaS as the foundational layer for migrating existing applications and building new ones, forming a significant revenue base.
- Function as a Service (FaaS):FaaS, or serverless computing, allows developers to execute code in response to events without managing underlying servers. Retail and media sectors in Europe adopt FaaS for its event-driven scalability and cost-efficiency, particularly for intermittent workloads.
- Platform as a Service (PaaS):PaaS offers a complete development and deployment environment in the cloud, including operating systems, programming language execution environments, and databases. Developers leverage PaaS for rapid application development and deployment, abstracting away infrastructure concerns.
- Software as a Service (SaaS):SaaS delivers ready-to-use applications over the internet on a subscription basis, managed entirely by the vendor. Business users widely adopt SaaS for various functions, requiring minimal technical overhead from the client side.
Adoption of Infrastructure as a Service reflects widespread operational needs; Function as a Service demonstrates rapid expansion.
End User Sector:
Industry-specific requirements drive distinct cloud engineering demands, influencing architecture choices and compliance frameworks.
- BFSI:The Banking, Financial Services, and Insurance sector requires highly secure, scalable, and compliant cloud platforms for core banking systems and transaction processing. Financial institutions in the United States prioritize FinOps engineering to manage cloud costs and ensure regulatory adherence.
- Healthcare:Healthcare organizations demand cloud solutions that meet stringent data privacy regulations like HIPAA in the US and GDPR in Europe. Cloud engineering in this sector focuses on secure data storage, interoperability, and analytics for patient records and research.
- Retail:Retail enterprises utilize cloud engineering for e-commerce platforms, supply chain optimization, and personalized customer experiences. Scalability for seasonal demand and rapid deployment of new features are critical for retail cloud initiatives.
- Education:The education sector leverages cloud services for e-learning platforms, student information systems, and research computing. Cloud engineering supports remote learning environments and collaborative research projects for universities globally.
Investment in BFSI focuses on security; Healthcare prioritizes compliance.
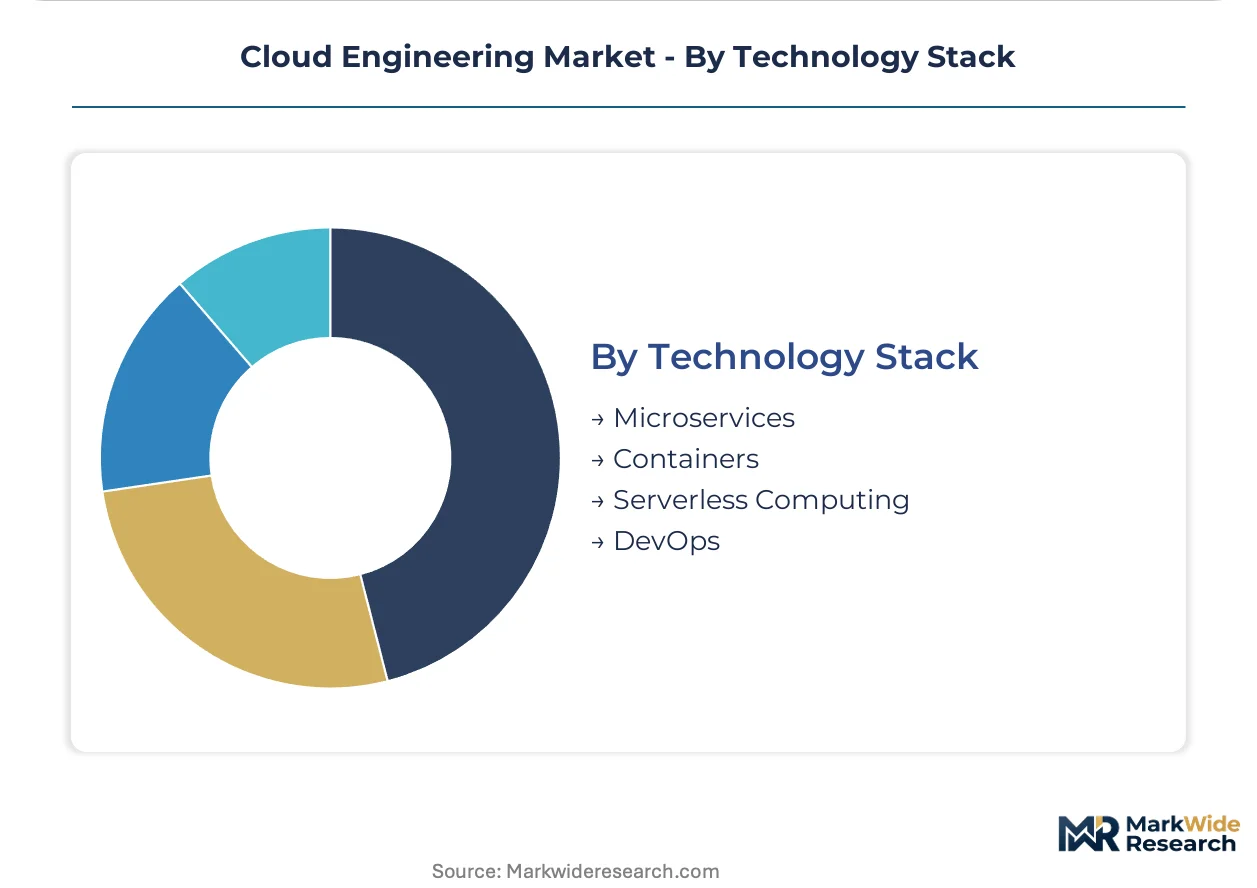
Technology Stack:
The architectural approach to cloud-native development defines the tools and methodologies used to build and operate applications.
- Microservices:Microservices architecture structures an application as a collection of loosely coupled, independently deployable services. This approach enhances agility and scalability for complex enterprise applications, particularly in technology firms.
- Containers:Containers package applications and their dependencies into portable, isolated units, enabling consistent deployment across various environments. Platforms like Kubernetes accelerate the adoption of containers for managing microservices across multi-cloud setups in Germany.
- Serverless Computing:Serverless computing abstracts away server management, allowing developers to focus solely on writing code that executes on demand. Enterprises adopt serverless for event-driven applications and backend functions, optimizing resource utilization.
- DevOps:DevOps integrates software development and IT operations to shorten the systems development life cycle and provide continuous delivery with high software quality. This methodology improves collaboration and automation in cloud engineering projects across industries.
Efficiency gains define Containers; developer autonomy drives Serverless Computing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States' technology centers anchor significant cloud engineering demand, driven by robust digital transformation and regulatory compliance requirements. Regional strategies prioritize secure, scalable cloud architectures to manage diverse enterprise workloads.
United States
Financial institutions and healthcare providers in the United States drive significant cloud engineering demand for secure, compliant platforms. HIPAA and SEC regulations necessitate advanced cloud security and data governance frameworks. Silicon Valley and major financial hubs like New York City see concentrated activity in FinOps engineering and multi-cloud adoption.
Germany
German enterprises heavily adopt hybrid cloud strategies to comply with national data sovereignty laws and the EU AI Act. The country's strong industrial base demands cloud engineering for edge computing integration in manufacturing. Munich and Berlin serve as key centers for cloud solution development and deployment in the automotive and industrial sectors.
India
India's rapidly expanding digital economy fuels demand for multi-cloud and serverless architectures to avoid vendor lock-in. Data localization rules compel complex cloud deployments for many enterprises. Bengaluru and Hyderabad are major technology hubs where cloud engineering firms specialize in scalable solutions for e-commerce and financial services.
United Kingdom
The United Kingdom's financial services and public sector accelerate cloud adoption, requiring robust cloud engineering for data resilience and regulatory adherence. GDPR compliance influences cloud architecture choices for data processing and storage across industries. London remains a critical hub for FinTech cloud innovation and specialized cybersecurity services.
Japan
Japanese enterprises increasingly leverage cloud engineering for digital transformation initiatives, focusing on operational efficiency and disaster recovery solutions. METI guidelines encourage cloud adoption while emphasizing data security and system reliability. Tokyo and Osaka lead in cloud infrastructure development, particularly for manufacturing and retail sectors.
Cloud Engineering Market Key Industry Players
Portfolio diversification dominates the current landscape as cloud engineering service providers expand their offerings to include specialized AI platforms and green cloud solutions. The market exhibits a tiered structure, with global consultancies competing alongside niche cloud-native specialists. Strategic partnerships and technology licensing represent other significant competitive moves.
Within the global consulting tier, Accenture exemplifies comprehensive cloud transformation services, catering to large enterprise clients across diverse industries. Amazon Web Services anchors the infrastructure layer, providing foundational cloud services that enable numerous engineering firms. ScienceSoft represents a specialized archetype, focusing on custom cloud development and digital product engineering for specific client needs.
| Leading Market Players |
|---|
| Amazon Web Services |
| Accenture |
| ScienceSoft |
| DataArt |
| Radixweb |
| Closeloop Technologies |
| Instinctools |
| Jade Global |
| Spellbind |
| Others |
Cost & Logistics Intelligence
The EU AI Act's stringent compliance requirements compel enterprises to invest in auditable cloud architectures, directly influencing how service providers structure their offerings and associated pricing models.
Pricing Analysis
Opaque data egress fees from major cloud providers directly impact service delivery costs, which are then passed through to enterprise clients. The dominant pricing model remains project-based for custom cloud engineering solutions, alongside subscription-based tiers for managed services. Price differentiation drivers include certified expertise in specific cloud platforms and the level of customization required for complex hybrid or multi-cloud environments. Pricing pressure stems from client demand for cost predictability and optimized FinOps solutions. Large financial institutions are less price-sensitive due to compliance mandates, while smaller enterprises seek more cost-efficient, standardized offerings.
Supply Chain Analysis
Single-source vulnerability sits with hyperscale cloud providers like Amazon Web Services, which form the foundational infrastructure layer for most cloud engineering services. Geographic supply concentration for cloud infrastructure centers on the United States and Ireland, with growing investments in India. Raw material dependencies include specialized server components and high-bandwidth networking equipment. A structural supply chain risk is the potential for significant outages or security breaches within a dominant provider. Distribution runs through a global network of specialized cloud engineering firms and IT consultancies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cloud engineering market is transitioning into a late-cycle quality story, driven by enterprise demand for highly secure, governable, and optimized cloud environments. This shift prioritizes premium specifications for compliance and performance.
For Market Incumbents: Deepen certified expertise in multi-cloud security and FinOps engineering to counter emerging specialized threats. Expand solution frameworks for complex hybrid cloud environments, particularly in regulated sectors like BFSI and healthcare. Invest in AI-driven automation tools to improve operational efficiency and manage cost unpredictability from hyperscalers. This proactive approach mitigates margin pressure from commoditized basic cloud services.
For New Entrants and Emerging Players: The EU AI Act in Europe opens a window for specialized AI governance platforms, focusing on auditable data pipelines and model lifecycle management. Target underserved regional markets in developing economies with localized compliance expertise and cost-effective serverless solutions. A go-to-market angle involves offering pre-configured, industry-specific compliance templates for faster time-to-value in sectors like manufacturing.
For Investors and Strategic Acquirers: Asymmetric upside sits with niche cloud engineering firms possessing deep expertise in specific regulatory frameworks or cutting-edge technologies like edge computing. Focus on companies demonstrating strong recurring revenue from managed services and proprietary automation IP over the long term. The signal to watch for inflection is widespread enterprise adoption of green cloud solutions driven by CSRD mandates.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop AI Governance Platforms | Addresses stringent EU AI Act compliance requirements for enterprise AI systems. |
| Expand FinOps Engineering Services | Helps enterprises optimize cloud spending and manage cost unpredictability across platforms. |
| Invest in Edge Computing Integration | Unlocks new low-latency application markets in manufacturing and autonomous systems. |
| Obtain Multi-Cloud Security Certifications | Enhances credibility and addresses complex security challenges across disparate cloud environments. |
| Offer Green Cloud Optimization Tools | Assists enterprises in meeting sustainability goals and reducing their carbon footprint. |
Research Approach
Direct dialogue with CTOs, cloud architects, IT procurement officers, and compliance specialists provided qualitative grounding for the analysis. This primary research was rigorously validated against secondary sources, including SEC filings from major cloud providers, industry consortium reports, and regulatory body publications like those from the EU. The data was then triangulated using both bottom-up market sizing and top-down revenue analysis.
Market projections were generated through a robust quantitative model, segmenting the cloud engineering landscape by deployment model, service type, end-user sector, and technology stack. Compound annual growth rates were derived from historical trends and projected adoption patterns across the analysis window. Key inputs included enterprise IT spending forecasts and regional regulatory compliance timelines.
Revisions become necessary when significant shifts in regulatory landscapes or unforeseen technological disruptions materialize. Forecasts reflect assumptions regarding macro-economic stability and continued digital transformation initiatives. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Technology
Global Cloud Systems Management Market
Cloud Technology
Cloud Data Quality Radar Market
Cloud Technology
Global Health Cloud Market
Cloud Technology
Cloud Managed Services Market
Cloud Technology
Telecom Cloud Orchestration Market
Cloud Technology
Cloud Ceilometer Market
Cloud Technology
Cloud Information Technology Service Management (ITSM) Market
Cloud Technology
Global Cloud-Based PLM Market
Cloud Technology
Private Cloud Services Market
Cloud Technology
Cloud Native Technologies Market
Cloud Technology
Cloud Workflow Market
Cloud Technology
Global Cloud Monitoring Market
Cloud Technology
Global Cloud Discovery Market
Cloud Technology
Cloud Digital Video Recording (DVR) Market
Cloud Technology
Cloud Monitoring System Market
Cloud Technology
Top 10 Cloud Technologies Market