
 Bacteriostatic Water for Injection Market | 2026-2036
Bacteriostatic Water for Injection Market Size, Share, and Industry Trends Forecast 2026-2036
Bacteriostatic Water for Injection Market Analysis
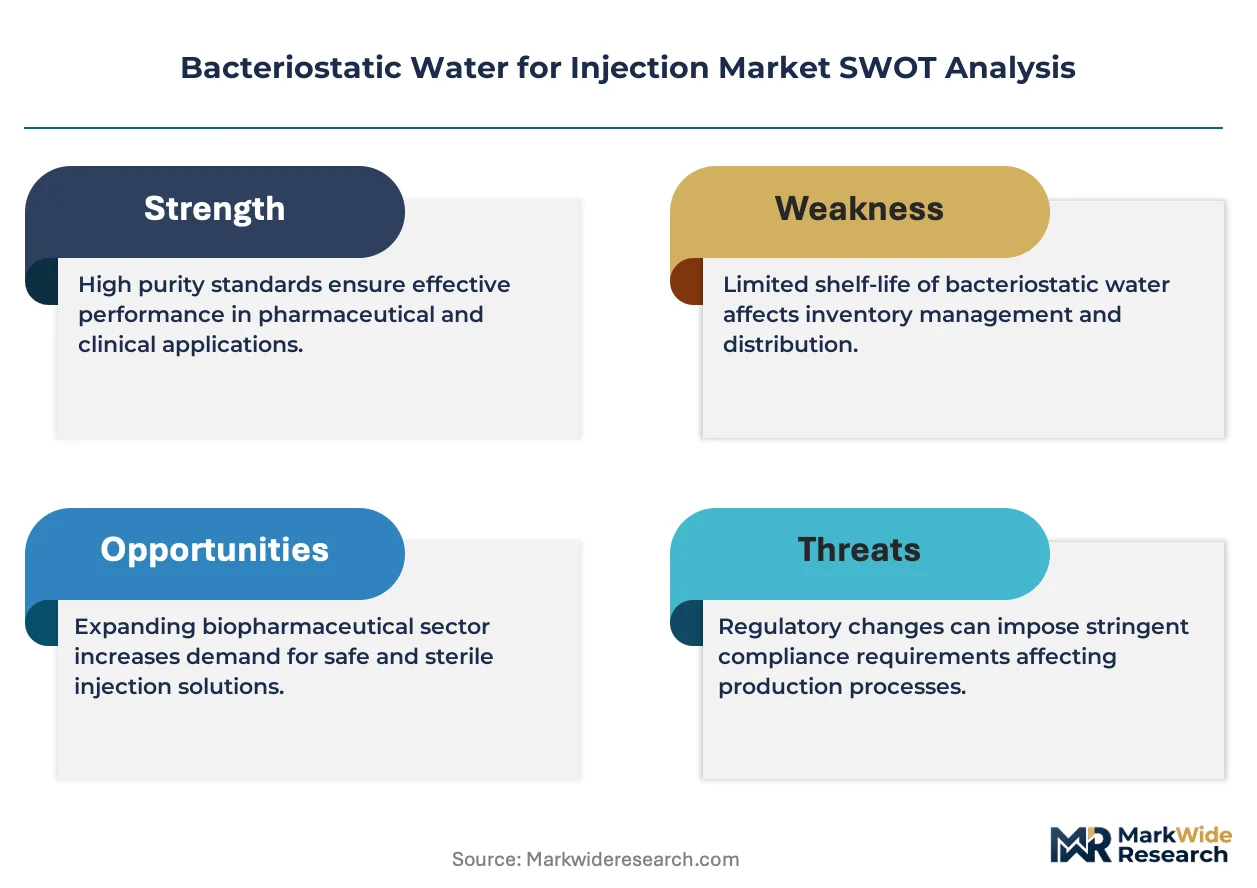
Modular packaging configurations is shifting how hospitals and compounding pharmacies procure sterile diluents, with buyers favoring multi-dose vial bundles over single-unit purchases to reduce per-dose handling costs. Pfizer leverages its hospital channel infrastructure to sustain contracted supply relationships with large health systems. Baxter International anchors its position through integrated delivery of parenteral solutions and companion diluent products. Hikma Pharmaceuticals competes on cost-efficient manufacturing scale across North American and European distribution networks.
Bacteriostatic Water for Injection is sterile water containing benzyl alcohol as a bacteriostatic preservative, typically supplied in concentrations of 0.9% benzyl alcohol to permit repeated withdrawals while inhibiting microbial growth; it serves as a diluent for drugs administered via intramuscular, intravenous, or subcutaneous injection. Multi-dose vials dominate volume throughput due to their compatibility with high-frequency hospital pharmacy operations, while single-use vials command premium positioning in specialty biologics reconstitution where contamination risk carries elevated liability. The pharmaceutical application segment leads absolute consumption, though laboratory use exhibits the fastest structural expansion as cell therapy manufacturing scales demand GMP-grade sterile water for media preparation.
FDA Current Good Manufacturing Practice regulations and USP Chapter 797 sterile compounding standards shape product formulation, labeling, and expiry dating across the United States market, with batch release testing requirements directly influencing manufacturer cost structures and capacity planning. The EPA monitors benzyl alcohol discharge thresholds from production facilities, while ISO 13485 quality management certifications govern supplier qualification for medical device and pharmaceutical OEM partnerships. Stakeholders must monitor evolving USP Chapter 795 and 797 revision timelines to anticipate reformulation investments and packaging redesign obligations.
Market Dynamics
Hospital pharmacy consolidation is compressing supplier relationships into fewer, larger contracts, forcing manufacturers to reconfigure packaging formats and delivery logistics around centralized procurement mandates rather than decentralized purchasing patterns.
Growth Catalysts
- USP Chapter 797 Revisions:The FDA-backed sterile compounding standards are tightening beyond-use dating protocols, compelling hospitals to source GMP-certified bacteriostatic water with extended stability claims to reduce waste and recompounding frequency.
- Cell Therapy Manufacturing Scale-Up:Laboratory applications for GMP-grade sterile diluents are accelerating as biotech firms expand autologous and allogeneic cell therapy production, creating parallel demand streams outside traditional pharmaceutical reconstitution.
- Multi-Dose Vial Economics:Hospital pharmacies are adopting bundled multi-dose configurations to minimize per-dose handling labor and reduce contamination incidents during high-volume sterile preparation workflows.
Market Restraints
- Benzyl Alcohol Input Volatility:Fluctuations in pharmaceutical-grade benzyl alcohol supply, concentrated among specialty chemical producers in Germany and China, inject cost unpredictability into preservative formulation budgets.
- Single-Source API Dependencies:Sterile water for injection relies on captive membrane filtration and distillation capacity held by a limited set of parenteral solution manufacturers, creating geographic concentration risk in the United States and Western Europe.
- Substitution by Preservative-Free Alternatives:Single-use vials with immediate-use dating are displacing bacteriostatic formats in liability-sensitive biologics reconstitution, particularly for monoclonal antibody therapies where benzyl alcohol compatibility remains restricted.
Strategic Opportunities
- 503B Compounding Pharmacy Expansion:Outsourced sterile compounding facilities in the United States are purchasing bulk diluent volumes under FDA registration pathways, opening a channel distinct from traditional hospital pharmacy procurement.
- Prefilled Syringe Integration:Convergence between ready-to-use diluent containers and automated reconstitution devices is creating demand for customized fill volumes and Luer-lock compatible presentations in ambulatory infusion centers.
- EMA Regulatory Harmonization:The European Medicines Agency's alignment of sterile water monographs with USP standards is reducing dual-registration burdens, enabling streamlined cross-Atlantic supply for multinational health systems.
Industry Challenges
- Aseptic Processing Workforce Scarcity:FDA-inspected sterile manufacturing facilities face recruitment gaps for qualified aseptic operators and quality assurance personnel, extending batch release timelines and constraining capacity expansion.
- ISO 13485 Certification Burden:Medical device OEM partnerships require quality management system audits that add six-to-twelve-month supplier qualification periods, delaying revenue recognition for new contract wins.
- Legacy ERP Integration Friction:Hospital systems running on-premises inventory management platforms struggle to synchronize electronic ordering with manufacturer EDI systems, generating manual reconciliation overhead and stockout risks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bacteriostatic Water for Injection Market |
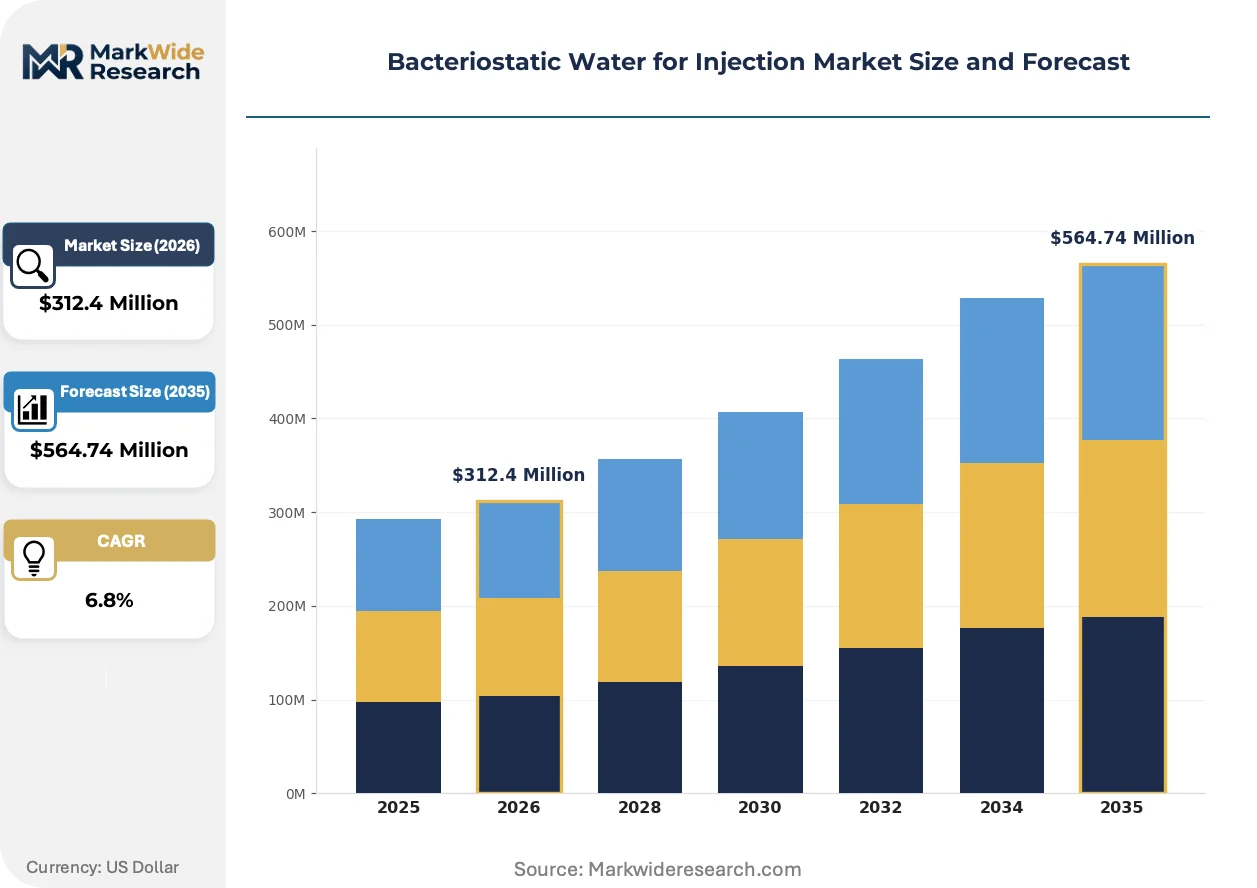
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Use Vials, Multi-Dose Vials, Ampoules, Cartridges Application: Pharmaceuticals, Vaccines, Injectable Solutions, Laboratory Use End User: Hospitals, Clinics, Research Labs, Pharmaceutical Companies Packaging Type: Glass Bottles, Plastic Bottles, Blister Packs, Pouches |
| Companies Covered | Pfizer, Hikma Pharmaceuticals, Baxter International, Novartis, Viatris, B. Braun Melsungen, Teva Pharmaceutical, Steris, Fresenius Kabi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bacteriostatic Water for Injection Market Emerging Trajectories
Packaging automation and regulatory data transparency are restructuring how sterile diluents move from manufacturing through compounding operations, with implications for traceability systems and supplier qualification protocols.
Closed-system transfer devices (CSTDs) are consolidating compatibility requirements for bacteriostatic water vials in hazardous drug compounding. Oncology pharmacies at major academic medical centers are adopting CSTD-integrated vial access systems at accelerated pace. This technology is consolidating vendor selection criteria around mechanical interface standardization rather than standalone vial specifications.
The FDA's Drug Supply Chain Security Act (DSCSA) serialization mandates are tightening unit-level traceability requirements for prescription drug products, including diluent components of combination therapies. Manufacturers must now embed unique product identifiers at the vial level, increasing labeling complexity and verification infrastructure costs. Hospital pharmacies in the United States are responding by consolidating purchases with suppliers offering pre-serialized configurations.
Consolidated service agreements are replacing transactional purchasing for sterile water products. Large health systems are negotiating multi-year contracts bundling diluents with parenteral nutrition and irrigation solutions, displacing spot-market procurement. This pattern is most visible in the United States, where hospital merger activity has concentrated buying power among ten to fifteen national systems controlling substantial pharmacy spend.
Bacteriostatic Water for Injection Market Segmentation
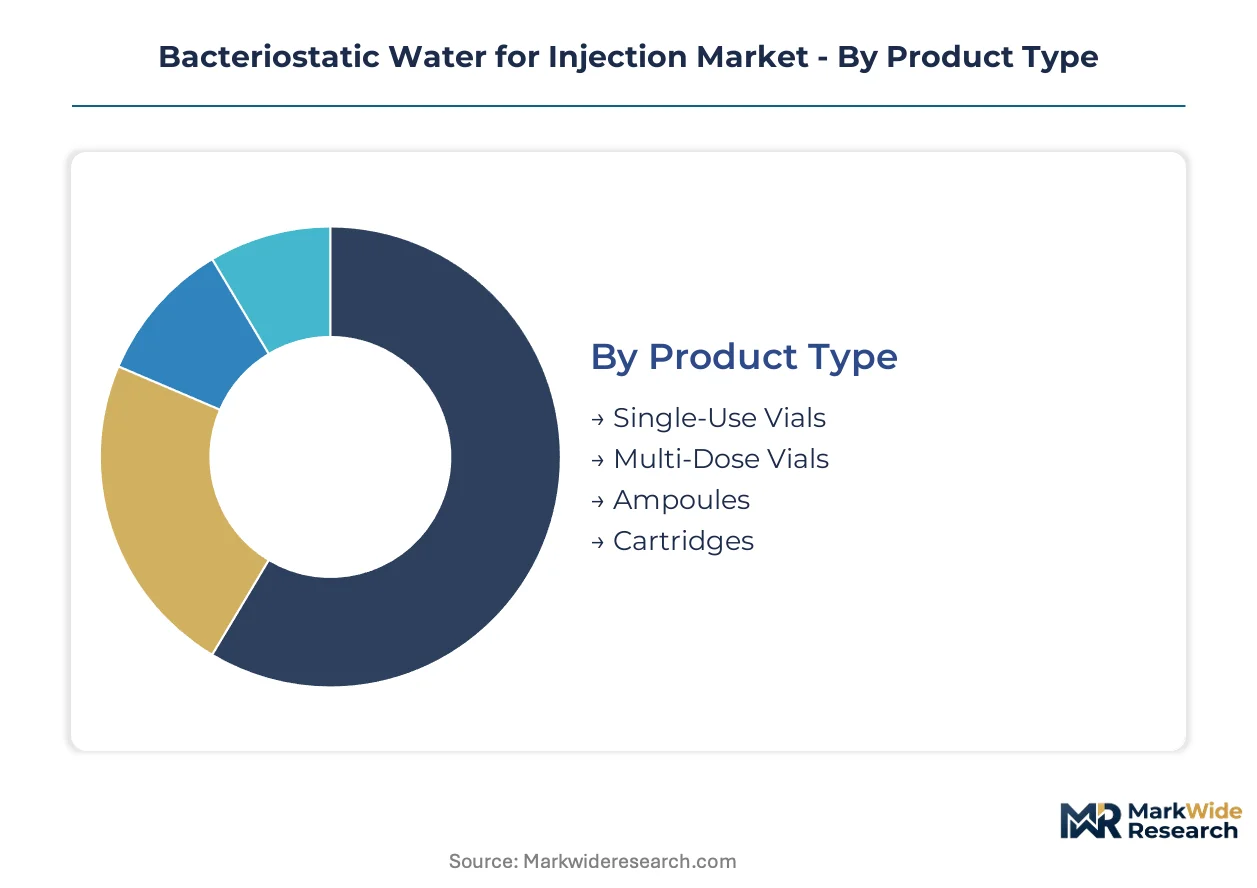
Segmentation in bacteriostatic water for injection reveals how packaging format, application intensity, and procurement channel interact to determine pricing power and supplier stickiness. Manufacturers configure production lines around specific container-closure systems, creating switching costs that lock in customer relationships across multi-year contracts.
Product Type:
Customization versus standardization tension runs deepest in container format selection, where multi-dose configurations demand specialized benzyl alcohol preservation engineering while single-use formats prioritize terminal sterilization simplicity.
- Multi-Dose Vials:These containers incorporate 0.9% benzyl alcohol to permit repeated needle penetrations over 28-day dating periods without microbial contamination. Hospital pharmacies in the United States concentrate procurement here, driven by USP Chapter 797 compliance costs that penalize frequent vial opening and discarding.
- Single-Use Vials:Preservative-free presentations with immediate-use dating dominate biologics reconstitution where benzyl alcohol exhibits drug compatibility restrictions. Specialty infusion centers and oncology clinics specify these formats for monoclonal antibody therapies.
- Ampoules:Snap-open glass containers serve emergency medicine and field deployment scenarios requiring absolute tamper evidence without rubber closure systems.
- Cartridges:Pen-injector compatible formats integrate with automated reconstitution devices in ambulatory care settings.
Most installed capacity flows through Multi-Dose Vials. Expansion is steepest in Single-Use Vials.
Application:
Volume concentration versus margin extraction varies sharply across therapeutic categories, with pharmaceutical manufacturing commanding bulk tonnage while laboratory applications extract premium pricing for GMP-grade certification.
- Pharmaceuticals:Drug reconstitution for intramuscular, intravenous, and subcutaneous injection constitutes the foundational demand base. Contract manufacturers and branded drug sponsors specify lot-matched diluent certificates to satisfy FDA batch release requirements.
- Laboratory Use:Cell therapy manufacturing and media preparation demand GMP-grade sterile water with extended endotoxin documentation. Biotech firms in Boston and San Diego clusters are scaling autologous production, creating parallel demand outside traditional pharmaceutical channels.
- Vaccines:Lyophilized vaccine reconstitution requires preservative-compatible diluents with demonstrated stability across cold chain distribution.
- Injectable Solutions:Parenteral nutrition and hydration therapy compounding utilizes bacteriostatic water as a base diluent in hospital pharmacy cleanrooms.
Pharmaceuticals absorb the majority of production volume. Laboratory Use is gaining share fastest.
End User:
Procurement sophistication and regulatory burden intensity diverge across customer types, with hospital systems leveraging consolidated purchasing power against fragmented clinic demand.
- Hospitals:Centralized pharmacy operations at academic medical centers and integrated delivery networks negotiate multi-year contracts bundling diluents with parenteral solutions. These buyers impose electronic data interchange requirements and DSCSA serialization compliance on suppliers.
- Pharmaceutical Companies:Drug sponsors source lot-matched diluents with customized fill volumes and specialized closure systems for clinical trial materials and commercial manufacturing.
- Clinics:Ambulatory infusion centers and specialty practices purchase through distributor channels with higher per-unit costs but lower minimum order quantities.
- Research Labs:Cell therapy developers and contract research organizations specify GMP-grade materials with extensive documentation packages for regulatory submission support.
Hospital procurement channels handle the largest throughput. Pharmaceutical company direct sourcing is climbing the fastest.
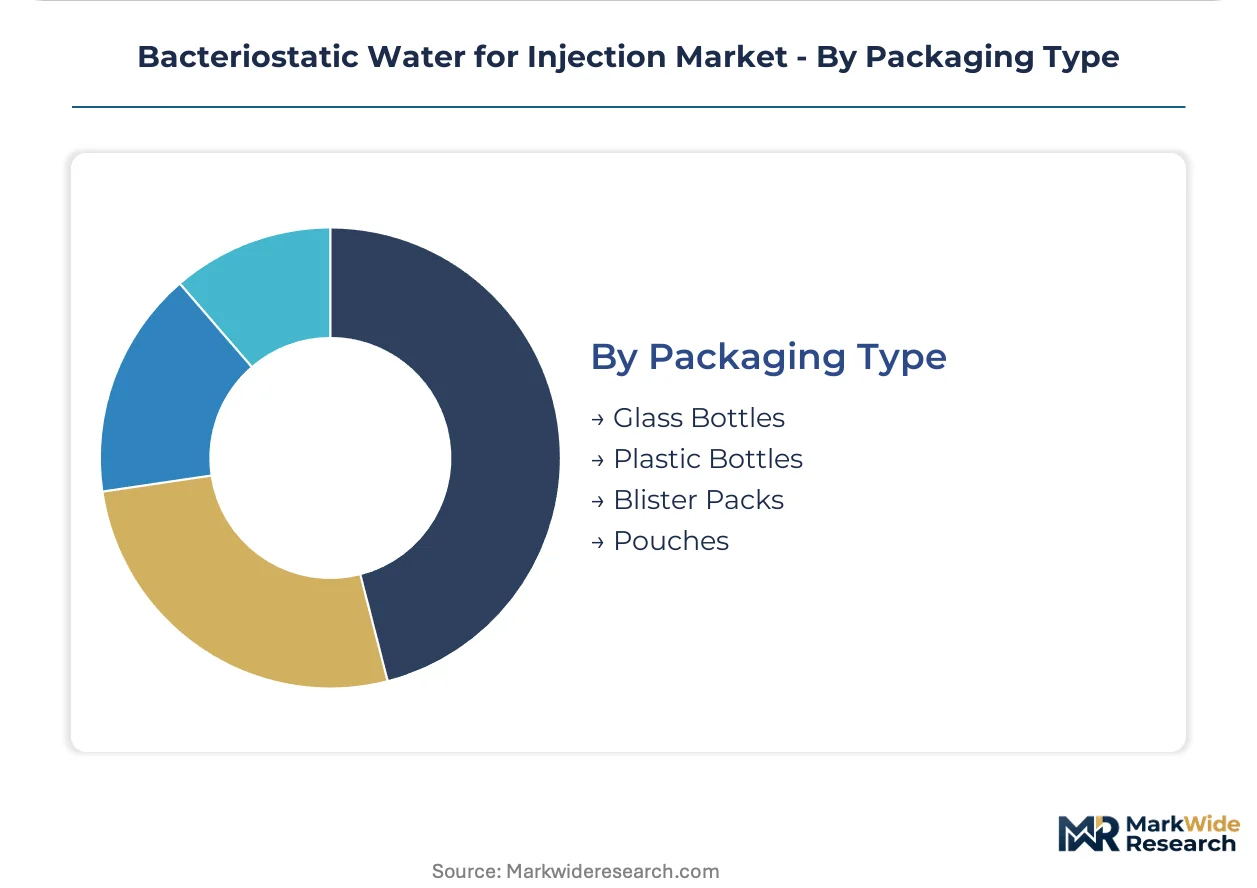
Packaging Type:
Material selection tradeoffs between chemical inertness, breakage resistance, and sustainability credentials shape supplier qualification protocols and geographic manufacturing placement.
- Glass Bottles:Borosilicate and treated soda-lime glass dominate parenteral applications requiring inert contact surfaces and visible particulate inspection. European manufacturers favor this format for compatibility with established filling lines.
- Plastic Bottles:Cyclic olefin polymer and polypropylene presentations reduce shipping weight and breakage risk in distribution to remote clinics and military medical units.
- Blister Packs:Unit-dose presentations support automated dispensing systems in high-volume hospital pharmacies.
- Pouches:Flexible containment systems serve bulk compounding operations and 503B outsourcing facilities with reduced storage footprint requirements.
Glass Bottles retain the majority of installed filling capacity. Plastic Bottles are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The bacteriostatic water for injection industry traces its commercial origins to mid-20th century pharmaceutical manufacturing clusters in the United States and Germany, where parenteral solution technology first achieved industrial scale. Today production capacity distributes across North American, European, and Asia-Pacific manufacturing bases serving distinct regulatory environments.
United States
Hospital consolidation and 503B compounding pharmacy expansion drive procurement volume concentration. FDA USP Chapter 797 revisions mandate extended beyond-use dating protocols that favor GMP-certified suppliers. The Boston-Cambridge biotech corridor anchors cell therapy manufacturing demand for GMP-grade sterile diluents.
Germany
Specialty chemical production of pharmaceutical-grade benzyl alcohol supplies preservative inputs across European formulation networks. EMA sterile water monograph harmonization with USP standards reduces dual-registration burdens for exporters. The Rhine-Main manufacturing belt concentrates aseptic filling capacity serving hospital and laboratory segments.
China
Domestic parenteral solution manufacturing scales to serve hospital pharmacy modernization programs. NMPA GMP certification requirements for sterile water products tighten batch release documentation standards. The Yangtze River Delta cluster hosts membrane filtration and distillation capacity expansion for regional supply security.
India
Contract manufacturing organizations scale sterile diluent production for export to regulated markets. CDSCO alignment with ICH Q7 guidelines shapes active pharmaceutical ingredient and excipient quality management systems. The Hyderabad-Visakhapatnam pharmaceutical corridor builds aseptic processing workforce pipelines for sterile manufacturing expansion.
Japan
Aging demographics sustain hospital pharmacy demand for multi-dose vial configurations in chronic disease management. PMDA GMP ministerial ordinances enforce terminal sterilization validation for parenteral preparations. The Kansai region maintains legacy filling line infrastructure serving domestic and select Asia-Pacific export markets.
Bacteriostatic Water for Injection Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification tier and customer relationship depth. Hospital pharmacy consolidation compresses supplier counts into fewer contracted relationships per health system. Three archetypes populate the competitive map: integrated parenteral solution conglomerates, sterile manufacturing specialists, and regional generic injectable players. Dominant competitive moves include multi-year service agreement bundling and 503B outsourcing channel cultivation.
Within the integrated conglomerate tier, Pfizer and Baxter International occupy positions anchored by hospital channel infrastructure and companion product portfolios. Hikma Pharmaceuticals exemplifies the cost-efficient manufacturing scale archetype across North American distribution networks. These three entities represent the structural poles around which competitive positioning organizes—contracted supply relationships, integrated delivery systems, and manufacturing scale efficiency.
| Leading Market Players |
|---|
| Pfizer |
| Hikma Pharmaceuticals |
| Baxter International |
| Novartis |
| Viatris |
| B. Braun Melsungen |
| Teva Pharmaceutical |
| Steris |
| Fresenius Kabi |
| Others |
Supply Flow & Price Mechanics
Membrane filtration capacity expansion across the United States and Germany is simultaneously lowering per-unit production costs and concentrating supply relationships among three dominant parenteral solution manufacturers. This technological transition rewards health systems with scale procurement power while squeezing margin flexibility for mid-tier competitors lacking captive distillation assets.
Pricing Analysis
Contract-based long-term offtake agreements dominate hospital pharmacy procurement, with pricing stratifying across GMP-certification grade, volume scale, and DSCSA serialization readiness. Cost compression in standard-grade multi-dose vials is intensifying because 503B outsourcing facilities are capturing volume with leaner compliance overhead. Research laboratories exhibit the lowest price sensitivity due to GMP-documentation requirements, while ambulatory clinics face the highest sensitivity given distributor markups on small-lot orders.
Supply Chain Analysis
Pharmaceutical-grade benzyl alcohol supply rests on specialty chemical producers in Germany and China, with sterile water for injection production anchored in the United States, Germany, and India. Captive membrane filtration systems, borosilicate glass vials, and rubber closure components constitute critical input dependencies. Single-source API vulnerability concentrates risk around parenteral solution manufacturers with limited geographic redundancy. Distribution runs through integrated health system procurement portals and 503B compounding pharmacy bulk channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through GMP-certification tier upgrading as cell therapy manufacturers pay premiums for extended endotoxin documentation. Centralized hospital procurement creates volume concentration that rewards suppliers with serialization-ready infrastructure.
For Market Incumbents: Deepen backward integration into benzyl alcohol supply through captive relationships with German specialty chemical producers. Expand aseptic filling capacity in the Boston-Cambridge corridor to capture cell therapy manufacturing demand. ISO 13485 certification investments defend position against emerging sterile manufacturing specialists seeking medical device OEM partnerships. For New Entrants and Emerging Players: Launch via 503B outsourcing facility bulk supply agreements, bypassing entrenched hospital GPO contracts. Target the laboratory use segment with GMP-grade documentation packages for autologous cell therapy producers. A prefilled syringe compatibility strategy unlocks ambulatory infusion center demand outside consolidated health system procurement. For Investors and Strategic Acquirers: Valuations sit cheapest among regional generic injectable players lacking USP Chapter 797 serialization infrastructure. Long-term viability favors suppliers with dual FDA-EMA registration pathways and captive membrane filtration assets. The signal to watch is NMPA GMP certification acceleration in China's Yangtze River Delta cluster as a proxy for Asia-Pacific supply security.| Strategic Initiative | Industry Significance |
|---|---|
| USP Chapter 797 Compliance Investment | Extended beyond-use dating claims reduce hospital pharmacy recompounding waste and strengthen contracted supply relationships. |
| 503B Outsourcing Channel Cultivation | Bulk diluent volumes through FDA-registered compounding facilities open procurement pathways outside traditional hospital GPO structures. |
| Prefilled Syringe Integration | Luer-lock compatible presentations align with automated reconstitution devices in ambulatory infusion centers. |
| EMA Regulatory Harmonization | Alignment of sterile water monographs with USP standards enables streamlined cross-Atlantic supply for multinational health systems. |
| Closed-System Transfer Device Compatibility | CSTD-integrated vial access systems consolidate vendor selection criteria around mechanical interface standardization in oncology compounding. |
Methodological Framework
Coverage spans the United States, Germany, China, and India, with primary inputs from each region's manufacturing clusters. Hospital pharmacy directors, 503B compounding facility operators, cell therapy manufacturing executives, and GMP compliance officers provided qualitative grounding. Secondary validation drew from FDA 483 inspection observations, EMA sterile water monograph revisions, USP Chapter 797 draft guidance, and hospital procurement database extracts. Bottom-up volume modeling triangulated against top-down pharmaceutical production capacity assessments.
Segmentation granularity operated at packaging format, application intensity, and end-user procurement channel levels across the projection horizon. Treatment line differentiation, GMP-certification tier, and regional regulatory cluster density shaped analytical framework construction. CAGRs derived from installed base attrition rates and capacity expansion pipelines, with cell therapy manufacturing scale-up and hospital consolidation velocity as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under benzyl alcohol supply disruption or accelerated USP Chapter 797 revision implementation. Forecasts reflect assumptions regarding aseptic processing workforce availability and DSCSA serialization infrastructure deployment. NMPA certification timelines, EMA-USP harmonization progress, and 503B facility registration growth constitute the small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Digital Pharmaceutical Supply Chain Management Market
Pharmaceuticals
Global Human Growth Hormone (HGH) Market
Pharmaceuticals
Lithuania Pharmaceutical Market
Pharmaceuticals
Global Self-Administered Drugs Market
Pharmaceuticals
Angiopoietin Inhibitors Therapeutic Market
Pharmaceuticals
Controlled Substance Market
Pharmaceuticals
PAP and Paracetamol Market
Pharmaceuticals
Small Volume Parenteral Market
Pharmaceuticals
Hydroxypropyl Methylcellulose (HPMC) Capsules Market
Pharmaceuticals
Antiplatelet Market
Pharmaceuticals
Oral Anti-Diabetic Drugs Market
Pharmaceuticals
Complex Injectable Market
Pharmaceuticals
Global Osteoporosis Drugs Market
Pharmaceuticals
Powder-Filled Hard Gelatin Capsules Market
Pharmaceuticals
Norway Pharmaceutical Market
Pharmaceuticals
Asia-Pacific Meglitinide Market