
 Gemcitabine HCL Market | 2026-2036
Gemcitabine HCL Market Size, Share, and Industry Trends Forecast 2026-2036
Gemcitabine HCL Market Analysis
Hospital group purchasing organizations is reconfiguring how generic oncology injectables reach end users in the Gemcitabine HCL space. Eli Lilly and Company anchors originator positioning through its established lyophilized formulation legacy. Dr. Reddy's Laboratories Ltd. leverages Indian manufacturing scale to compete in regulated export markets. Fresenius Kabi sustains European hospital contract strength through integrated parenteral production networks.
Gemcitabine HCL is a nucleoside analog chemotherapeutic agent, typically formulated as a hydrochloride salt with specified purity grades for intravenous administration, functioning as a DNA synthesis inhibitor in cancer treatment protocols. Injectable formulations dominate commercial volume due to oncology's reliance on controlled-dose parenteral delivery in hospital settings. Lyophilized powder presentations command attention from procurement teams seeking extended shelf stability and cold-chain flexibility. Hospital end users represent the core demand node, absorbing the majority of institutional purchasing power for pancreatic, breast, and lung cancer regimens.
FDA enforces current good manufacturing practice standards for sterile injectable oncology generics, while EMA's MDR framework tightens traceability for critical-dose cancer therapies. India's CDSCO aligns with WHO prequalification benchmarks to accelerate domestic facility approvals for export-oriented production. Stakeholders must monitor evolving bioequivalence study requirements for complex parenteral generics as regulators narrow acceptable therapeutic equivalence windows.
Market Dynamics
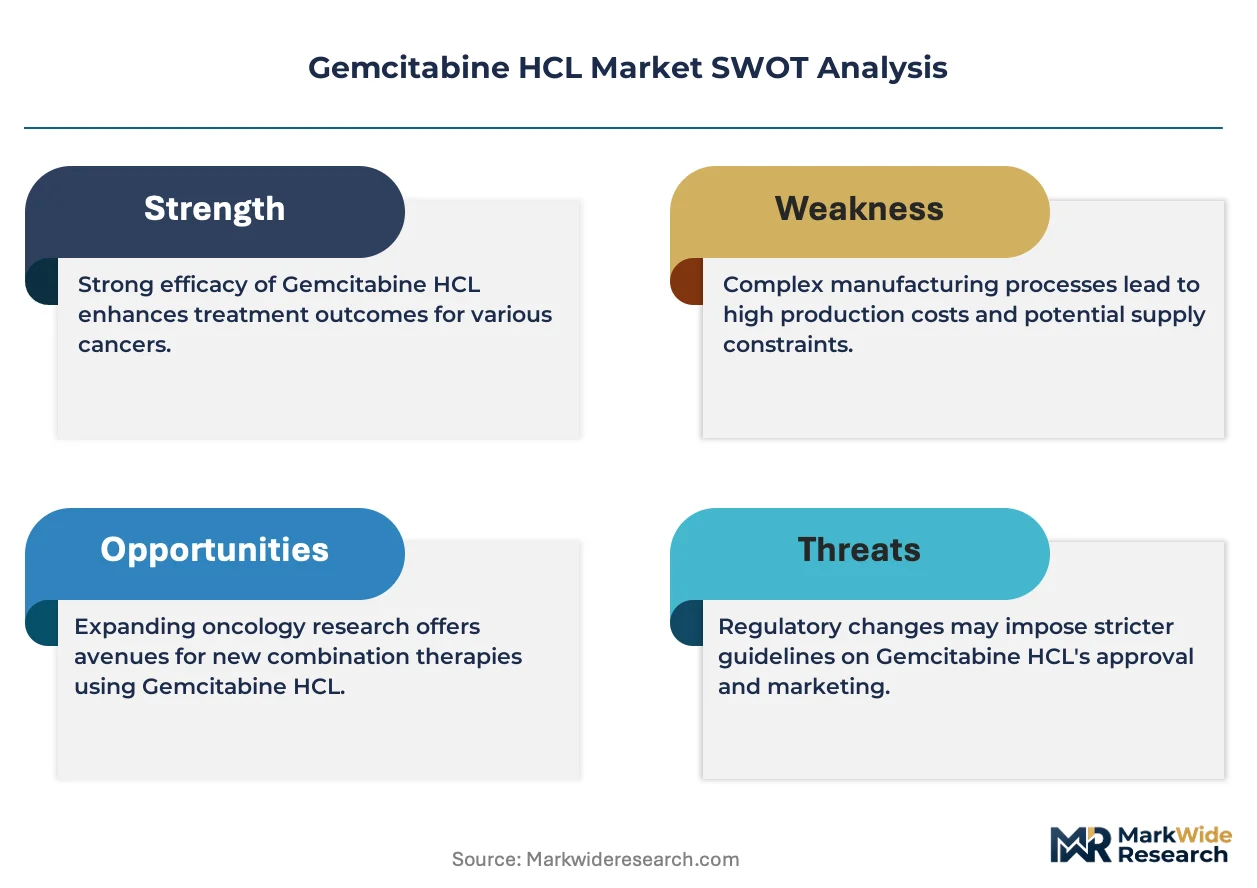
Hospital procurement centralization through group purchasing organizations is compressing margins for generic oncology injectables while tightening bioequivalence requirements from FDA and EMA force manufacturing upgrades across the supply base.
Growth Catalysts
- FDA cGMP Enforcement:Stricter sterile injectable standards are filtering out subscale manufacturers and consolidating volume among compliant facilities.
- India CDSCO Alignment:WHO prequalification benchmarks are accelerating domestic facility approvals for export-oriented gemcitabine production.
- Lyophilized Formulation Demand:Extended shelf stability requirements from hospital pharmacy directors are shifting procurement toward powder presentations.
Market Restraints
- API Concentration Risk:Active pharmaceutical ingredient supply concentrates among Chinese manufacturers, creating single-source vulnerability.
- Cold-Chain Cost Structure:Temperature-controlled distribution requirements add logistics overhead that erodes generic margin structures.
- EMA MDR Traceability:Medical Device Regulation serialization mandates impose compliance costs disproportionate to unit economics.
Strategic Opportunities
- Brazil ANVISA Pathway:Latin American regulatory harmonization opens access to underpenetrated oncology markets.
- Continuous Manufacturing:Process analytical technology integration with real-time release testing compresses batch cycle times.
- Direct Hospital Contracting:Bypassing wholesale distribution through integrated delivery network agreements captures margin.
Industry Challenges
- Sterile Manufacturing Talent Gap:Aseptic processing expertise scarcity constrains capacity expansion timelines.
- Bioequivalence Study Complexity:Narrow therapeutic equivalence windows for parenteral generics extend clinical development duration.
- Legacy System Integration:Serialization track-and-trace requirements conflict with established enterprise resource planning infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gemcitabine HCL Market |
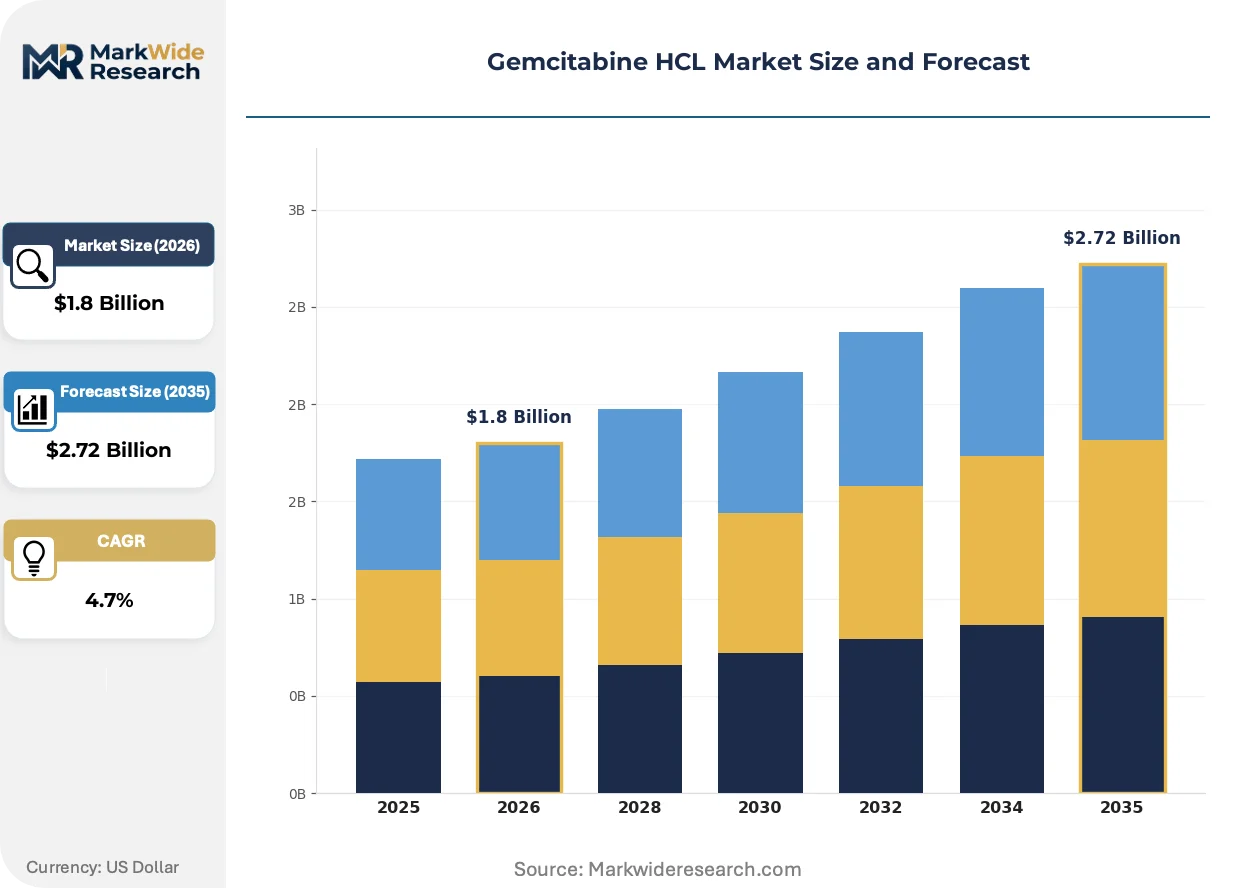
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
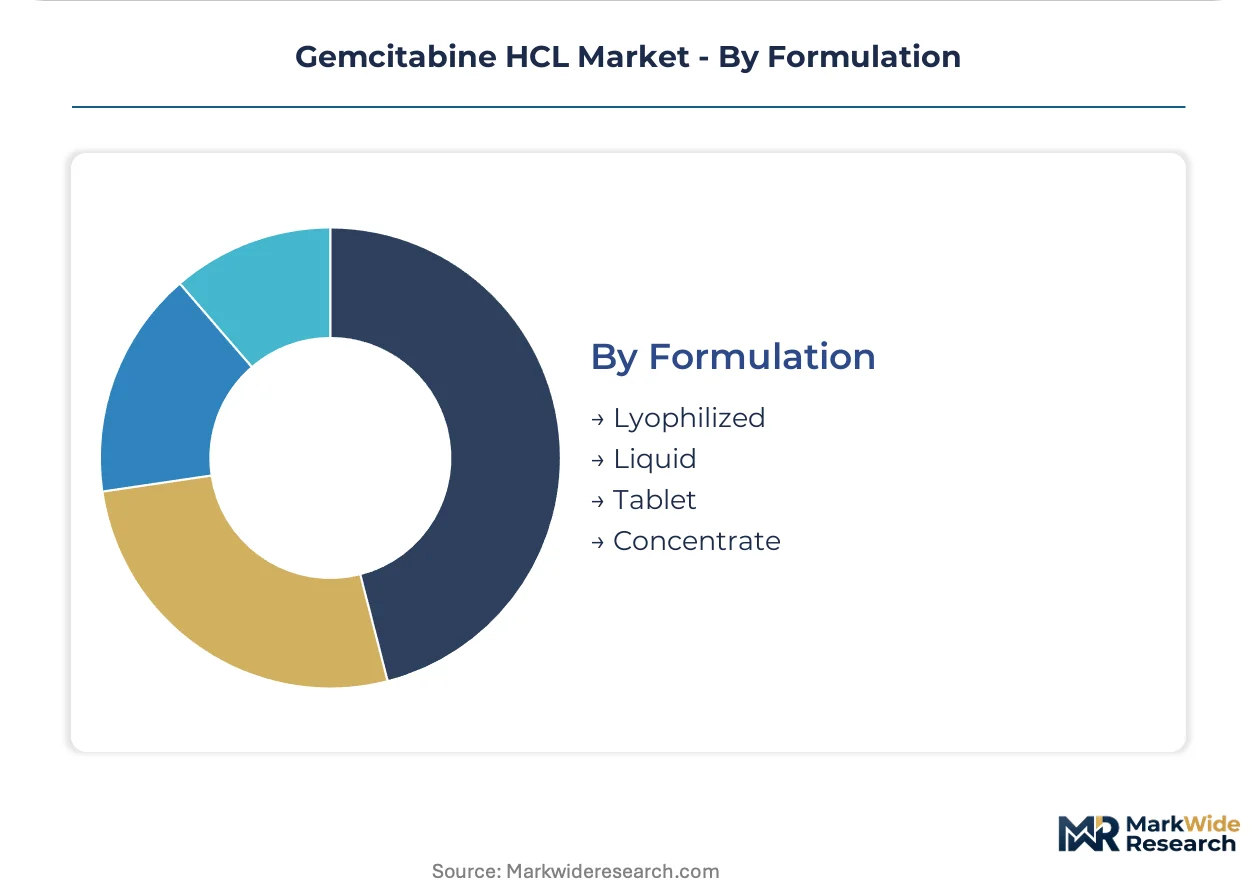
| Segmentation | Product Type: Injectable, Oral, Solution, Powder End User: Hospitals, Clinics, Research Institutes, Pharmacies Application: Oncology, Blood Disorders, Autoimmune Diseases, Metabolic Disorders Formulation: Lyophilized, Liquid, Tablet, Concentrate |
| Companies Covered | Dr. Reddy's Laboratories Ltd., Sun Pharmaceutical Industries Ltd., Fresenius Kabi, Pfizer Inc., Teva Pharmaceutical Industries Ltd., Accord Healthcare, Eli Lilly and Company, Mylan N.V., Apotex Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gemcitabine HCL Market Emerging Trajectories
Formulation science and regulatory science are converging to reshape how generic oncology injectables achieve commercial viability. Manufacturing process innovation now determines competitive position as much as regulatory approval.
Ready-to-use liquid formulations are hybridizing with advanced aseptic fill-finish technology to reduce compounding error risk in hospital settings. Oncology pharmacy directors at academic medical centers are adopting these presentations for high-volume regimens. The shift is hybridizing competitive dynamics by rewarding fill-finish capabilities over API synthesis scale.
EMA's Medical Device Regulation is tightening unique device identification requirements for combination products containing gemcitabine. Manufacturers must now integrate serialization at the primary container level. European hospital procurement teams are favoring suppliers with established MDR technical documentation.
Consolidated contracting through group purchasing organizations is compressing supplier rosters to three-to-five approved vendors per therapeutic class. Integrated delivery networks are unbundling clinical pharmacy services from drug acquisition. The United States exhibits the most pronounced concentration, with three national GPOs controlling procurement for two-thirds of acute care beds.
Gemcitabine HCL Market Segmentation
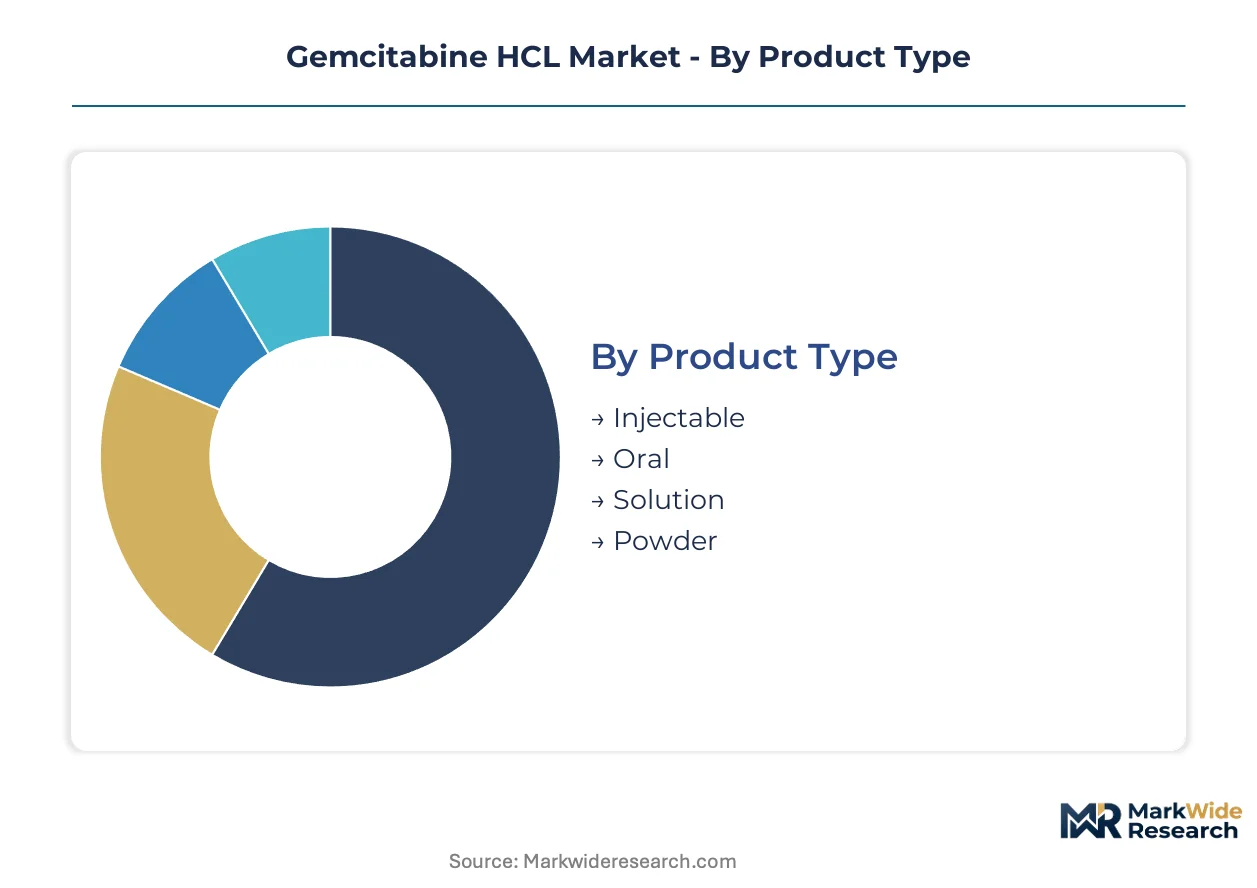
Gemcitabine HCL procurement patterns diverge sharply across formulation types and care settings, with hospital pharmacy directors prioritizing stability profiles while research institutes drive spot demand for investigational lots. Understanding these segment dynamics reveals where manufacturing investments concentrate and where margin compression hits hardest.
Product Type:
Injectable presentations turn inventory fastest due to protocol-driven consumption in oncology wards, while oral formulations sit longer as second-line alternatives with narrower prescriber acceptance.
- Injectable:Hydrochloride salt formulations for intravenous infusion dominate institutional purchasing, with hospital GPOs in the United States and India consolidating procurement around FDA and CDSCO-compliant sterile fill-finish capacity. Cold-chain requirements constrain supplier eligibility to manufacturers with validated distribution networks.
- Oral:Capsule and tablet presentations serve outpatient maintenance protocols where parenteral administration proves impractical. Bioavailability challenges limit uptake to specific pancreatic and breast cancer regimens prescribed by academic medical centers.
- Solution:Ready-to-use liquid formulations reduce compounding error risk but carry shorter shelf lives that strain pharmacy inventory management.
- Powder:Bulk active pharmaceutical ingredient purchases support institutional compounding operations and research-scale synthesis.
Injectable presentations anchor the volume base while oral formulations gain share at the steepest rate as outpatient cancer care expands.
End User:
Cost tier stratification separates high-volume contract purchasers from price-sensitive spot buyers, with integrated delivery networks extracting steepest discounts through committed volume.
- Hospitals:Academic medical centers and community hospital systems absorb the majority of gemcitabine volume through standardized chemotherapy protocols for pancreatic, lung, and breast malignancies. Group purchasing organization membership determines formulary access and pricing tier.
- Clinics:Outpatient oncology infusion centers favor ready-to-use presentations that minimize pharmacy labor overhead and compounding liability exposure.
- Research Institutes:Investigational drug supply for clinical trials demands small-batch flexibility and documentation rigor that specialized CMOs provide.
- Pharmacies:Retail and specialty pharmacy channels handle limited oral formulation dispensing for maintenance therapy patients.
Hospitals command the dominant procurement position while clinics expand their share most rapidly as site-of-care migration accelerates.
Application:
Application-based demand concentrates where prescriber familiarity and protocol reimbursement align, with oncology generating predictable recurring orders against sporadic purchases for rare disease indications.
- Oncology:Pancreatic ductal adenocarcinoma and non-small cell lung cancer represent the anchor indications, with gemcitabine-cisplatin and gemcitabine-paclitaxel combinations entrenched in NCCN guidelines. Hospital pharmacy directors stock these regimens as first-line standards.
- Blood Disorders:Off-label use in myelodysplastic syndromes and relapsed acute myeloid leukemia creates niche demand from academic hematology programs.
- Autoimmune Diseases:Investigational applications in systemic lupus and vasculitis generate sporadic investigator-initiated trial demand.
- Metabolic Disorders:Preclinical exploration in metabolic modulation produces minimal commercial volume.
Oncology applications generate the foundational revenue stream while blood disorder indications show the most rapid expansion in investigator-sponsored trials.
Formulation:
Supply concentration among lyophilized specialists creates procurement bottlenecks, while liquid formulation entrants compete on convenience despite shorter dating.
- Lyophilized:Freeze-dried powder presentations deliver extended stability and cold-chain flexibility that hospital pharmacy directors prioritize for inventory security. Eli Lilly's legacy formulation established the stability benchmark that generics must match.
- Liquid:Ready-to-use solutions eliminate reconstitution steps but require tighter temperature control and carry shorter expiry dates that challenge distribution economics.
- Tablet:Oral solid dosage forms occupy a narrow niche where bioequivalence to parenteral therapy has been demonstrated for specific protocols.
- Concentrate:High-potency solutions for dilution support institutional compounding and research applications requiring dose customization.
Lyophilized formulations maintain volume dominance while liquid presentations capture the fastest share gains among outpatient infusion centers prioritizing workflow efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA enforcement of current good manufacturing practice standards for sterile injectable oncology drugs anchors procurement patterns in the United States, while CDSCO and EMA frameworks shape parallel compliance architectures in India and Europe.
United States
Hospital group purchasing organizations consolidate procurement for pancreatic and lung cancer protocols across academic medical centers and community systems. FDA bioequivalence standards for generic parenteral oncology drugs tighten acceptable therapeutic equivalence windows. New Jersey and Indiana host concentrated sterile fill-finish capacity serving national distribution networks.
India
Domestic chemotherapy access programs and export-oriented production scale simultaneously. CDSCO alignment with WHO prequalification benchmarks accelerates facility approvals for regulated markets. Hyderabad and Ahmedabad clusters specialize in API synthesis and lyophilized formulation manufacturing for European and North American contracts.
Germany
EMA Medical Device Regulation serialization mandates drive technical documentation investments for combination products. Hospital pharmacy directors prioritize suppliers with established unique device identification compliance. Baden-Württemberg and Bavaria maintain integrated parenteral production networks serving continental procurement.
China
NMPA oversight of nucleoside analog manufacturing concentrates API supply among specialized chemical producers. Domestic oncology protocol expansion absorbs growing gemcitabine volumes for pancreatic and non-small cell lung cancer indications. Jiangsu and Zhejiang provinces dominate hydrochloride salt synthesis capacity.
Brazil
ANVISA regulatory harmonization opens procurement pathways for imported generic oncology injectables as national cancer plan coverage expands. Hospital oncology wards in São Paulo and Rio de Janeiro anchor institutional demand. Local distributors navigate cold-chain infrastructure gaps to serve interior state markets.
Gemcitabine HCL Market Vendor Landscape
Originator legacy holders and scaled generic manufacturers split the market between premium-priced lyophilized formulations and cost-optimized alternatives. Three strategic archetypes dominate: integrated pharmaceutical conglomerates with hospital contract depth, Indian export specialists leveraging manufacturing scale, and European parenteral-focused operators with fill-finish expertise. Competitive moves concentrate on M&A for sterile manufacturing capacity and strategic partnerships for distribution network access.
Within the export-specialist tier, Dr. Reddy's Laboratories Ltd. and Sun Pharmaceutical Industries Ltd. exemplify Indian manufacturing scale competing in regulated markets. Fresenius Kabi occupies a position among European parenteral operators with integrated production networks. Eli Lilly and Company anchors the originator archetype through established lyophilized formulation heritage.
| Leading Market Players |
|---|
| Dr. Reddy's Laboratories Ltd. |
| Sun Pharmaceutical Industries Ltd. |
| Fresenius Kabi |
| Pfizer Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Accord Healthcare |
| Eli Lilly and Company |
| Mylan N.V. |
| Apotex Inc. |
| Others |
Supply Flow & Price Mechanics
Shanghai-Frankfurt pharmaceutical freight corridors absorb cold-chain premiums that compound API concentration effects in Jiangsu province, compressing margin structures for Indian lyophilized formulators while rewarding European fill-finish operators with MDR-compliant documentation packages. Hospital GPOs in the United States extract volume discounts that force supplier consolidation toward CDSCO-validated export houses with WHO prequalification status.
Pricing Analysis
The customization-premium spread separates standard lyophilized vials from patient-specific dosing protocols configured for academic medical center trials. Contract-based long-term offtake dominates institutional procurement, with price differentiation driven by FDA bioequivalence certification tier and cold-chain delivery reliability. Cost compression in the standard injectable tier intensifies as Chinese API producers expand hydrochloride salt capacity. Community hospital systems exhibit highest price sensitivity; research institutes tolerate premium positioning for investigational lot flexibility.
Supply Chain Analysis
Export-control regimes limiting nucleoside analog technology transfer constrain API synthesis capacity expansion outside established chemical corridors. Supply concentrates in China for hydrochloride salt production, India for lyophilized formulation, and Germany for aseptic fill-finish. Raw material dependencies include cytidine precursors, specialized fermentation media, and pharmaceutical-grade hydrochloric acid. Single-source vulnerability pervades the Jiangsu-Zhejiang API cluster. Distribution runs through hospital GPO consolidated contracts with regional cold-chain logistics partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aseptic processing expertise scarcity constrains capacity expansion timelines across sterile oncology injectable manufacturing, creating asymmetric returns for facilities with validated EU-GMP and FDA cGMP compliance. The capability gap widens as EMA MDR serialization mandates layer technical documentation requirements onto traditional pharmaceutical competencies.
For Market Incumbents: Build regulatory moat through simultaneous FDA cGMP and EMA MDR technical documentation investments that filter subscale competitors. Eli Lilly's lyophilized formulation heritage demonstrates how originator positioning sustains premium tier access. Defensive consolidation moves center on acquiring Indian CDSCO-compliant facilities with WHO prequalification momentum. Capacity addition in Hyderabad-Ahmedabad clusters captures export-oriented production scale.
For New Entrants and Emerging Players: Build out continuous manufacturing capabilities with process analytical technology integration to compress batch cycle times against legacy fill-finish operators. Brazil ANVISA regulatory harmonization presents the most penetrable geography as national cancer plan coverage expands. Outpatient oncology infusion centers offer white-space access through ready-to-use liquid formulation workflows. Go-to-market angle: direct hospital contracting bypassing wholesale distribution layers.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified pharmaceutical conglomerates with underutilized sterile injectable capacity and incomplete regulatory documentation packages. Long-term viability favors assets with demonstrated EMA MDR unique device identification compliance and established European hospital pharmacy director relationships. Acquisition target archetype: mid-scale European parenteral operators with integrated production networks. Signal to watch: CDSCO acceleration of WHO prequalification-aligned facility approvals indicating export capacity inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO-WHO Prequalification Alignment | Accelerates Indian facility approvals for regulated export markets in Europe and North America. |
| Continuous Manufacturing Adoption | Process analytical technology integration compresses gemcitabine batch cycle times against legacy methods. |
| Direct Hospital GPO Contracting | Bypassing wholesale distribution captures margin in United States academic medical center procurement. |
| EMA MDR Technical Documentation | Unique device identification compliance determines European hospital pharmacy formulary access. |
| Lyophilized Formulation Capacity Expansion | Extended shelf stability presentations command procurement preference from hospital inventory managers. |
Methodological Framework
Operator-level perspectives from sterile manufacturing plant managers, hospital pharmacy directors, regulatory affairs leads at export-oriented Indian firms, and oncology GPO contracts managers anchored the qualitative base. Primary interviews combined with secondary validation from FDA 483 inspection observations, EMA MDR technical documentation databases, CDSCO facility approval records, and hospital procurement database extracts. Bottom-up volume estimates from formulation-specific production capacity and top-down demand triangulation from cancer protocol incidence rates converged on segment-level outputs.
Scenario-bracketing framed low-case assumptions around API supply disruption in Chinese chemical corridors and high-case assumptions around accelerated outpatient infusion center expansion. Segmentation dimensions modeled include formulation type, end-user channel, application indication, and regional regulatory cluster. CAGRs derived from protocol-driven consumption elasticity and manufacturing capacity expansion trajectories. Forecast inputs incorporated pancreatic and non-small cell lung cancer guideline evolution and sterile fill-finish talent pipeline constraints.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese API producers toward downstream formulation integration would shift outcomes. Material shifts in FDA bioequivalence study requirements for complex parenteral generics or EMA MDR enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
US Pharmaceutical Warehousing Market
Pharmaceuticals
Global Immunosuppressant Drugs Market
Pharmaceuticals
Psychedelic Drugs Market
Pharmaceuticals
Respiratory Virus Infection Drug Market
Pharmaceuticals
Non-Sterile Liquids/Suspensions Market
Pharmaceuticals
Europe FMD Vaccine Market
Pharmaceuticals
Global Treatment-Resistant Depression Market
Pharmaceuticals
Tapentadol Market
Pharmaceuticals
Fibroblast Activation Protein Inhibitors Market
Pharmaceuticals
Global Shingles Vaccine Market
Pharmaceuticals
Male Hypogonadism Market
Pharmaceuticals
Canine Dilated Cardiomyopathy Drugs Market
Pharmaceuticals
Cefazedone Sodium Market
Pharmaceuticals
Enteric Empty Capsules Sales Market
Pharmaceuticals
Global Fluorouracil (5FU) Market
Pharmaceuticals
Compounding Chemotherapy Market