
 Artificial Intelligence in Drug Screening Market | 2026-2036
Artificial Intelligence in Drug Screening Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Intelligence in Drug Screening Market Analysis
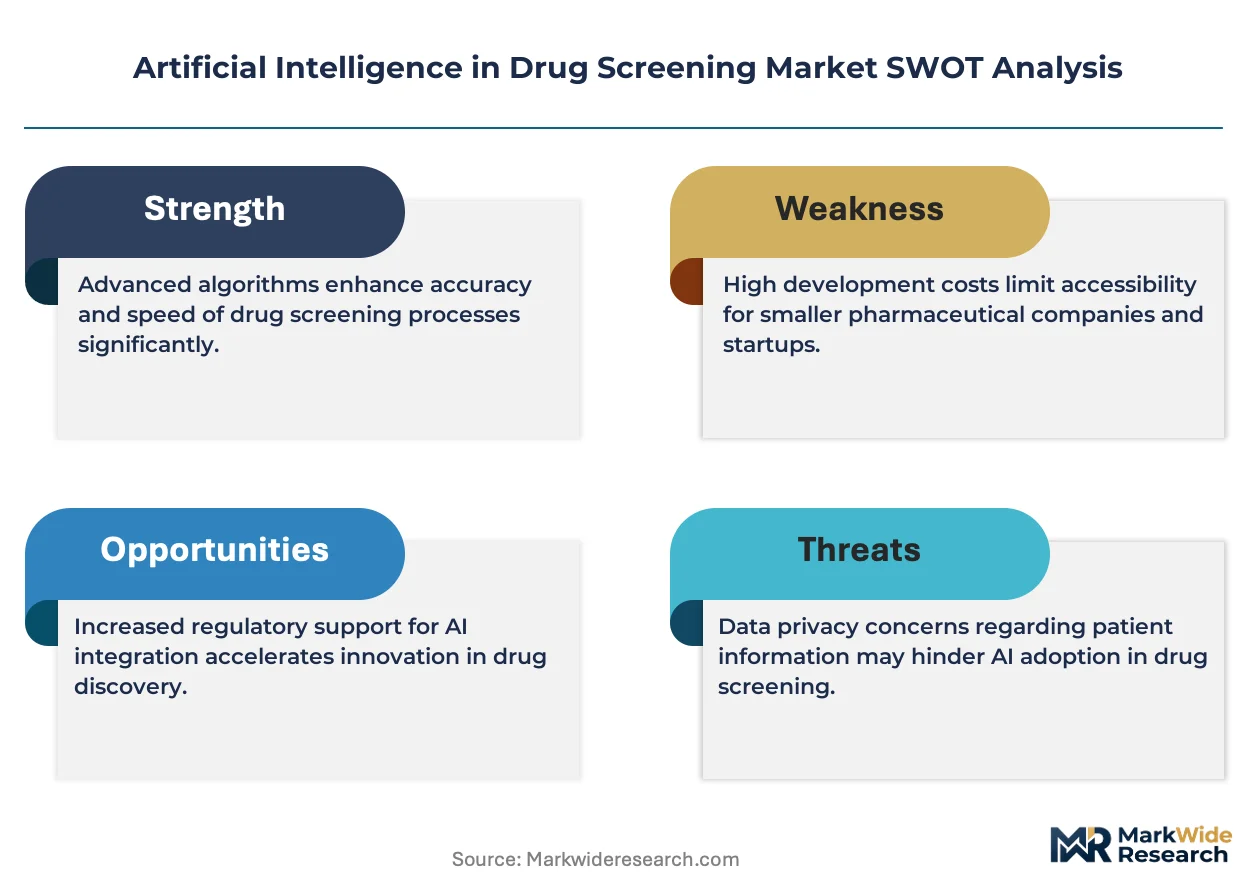
The gap between premium AI drug screening platforms and commodity prediction tools is consolidating around access to proprietary training data and regulatory-grade validation pipelines. NVIDIA Corporation leverages its GPU infrastructure to anchor high-throughput molecular simulation workloads for contract research organizations. Exscientia sustains differentiation through end-to-end autonomous chemistry capabilities that compress design-make-test cycles. Recursion Pharmaceuticals competes by integrating its own biological data generation with machine learning, creating a closed-loop discovery engine that rivals open-architecture alternatives.
Artificial intelligence in drug screening encompasses computational systems that predict molecular activity, toxicity, and pharmacokinetic behavior using multi-omic datasets, chemical structure representations, and phenotypic imaging data with throughput exceeding 10^6 compounds per virtual screening campaign. These systems primarily serve to replace or augment wet-laboratory assays during lead identification and safety profiling stages, reducing cost and timeline exposure before IND-enabling studies. Deep learning architectures now dominate structural biology applications where protein-ligand binding affinity prediction demands complex feature extraction from crystallographic and cryo-EM inputs. Cloud-based delivery models represent the fastest-expanding deployment category as pharmaceutical companies outsource computational infrastructure to manage burst workloads during candidate optimization sprints. Toxicology screening within the application layer remains the most mature segment, with established validation frameworks that ease regulatory acceptance compared to emerging biomarker discovery use cases.
FDA guidance on AI-enabled medical product development, alongside EMA's qualification opinion pathways for novel methodologies, shapes investment priorities by demanding reproducible algorithm performance across diverse patient populations. ISO 13485 quality management expectations and HIPAA data governance requirements further constrain how screening platforms handle clinical trial records and proprietary compound libraries. Stakeholders must monitor evolving precedents for regulatory acceptance of purely in-silico safety signals as primary evidence for first-in-human dosing decisions.
Market Dynamics
The central structural force reshaping artificial intelligence in drug screening is the FDA's evolving stance on in-silico evidence for IND submissions, which is compressing validation timelines and forcing platform providers to build regulatory-grade audit trails before commercial deployment.
Growth Catalysts
- NIH computational biology funding:Sustained federal investment in the United States accelerates academic-industry partnerships for training data generation and benchmark development.
- Deep learning architectures:Transformer-based protein structure prediction from AlphaFold derivatives enables high-throughput target validation that reduces wet-laboratory dependency.
- EMA qualification opinion pathways:European regulatory clarity on novel methodology acceptance creates precedents that reduce submission risk for AI-enabled toxicology packages.
Market Restraints
- GPU supply concentration:NVIDIA's dominance in training infrastructure creates cost volatility and procurement bottlenecks for mid-scale biotechnology firms.
- HIPAA data governance:United States privacy requirements constrain cross-institutional dataset pooling, fragmenting training corpora and limiting model generalizability.
- Proprietary compound library access:Pharmaceutical incumbents restrict external platform access to historical screening data, starving open-architecture competitors of negative-result training examples.
Strategic Opportunities
- Japan's PMDA regulatory sandbox:Accelerated approval pathways for computational biomarkers create first-mover advantages for toxicology prediction platforms.
- Cloud-native deployment models:Burst-compute arrangements for candidate optimization sprints displace capital-intensive on-premise infrastructure.
- Multi-omic data fusion:Integration of transcriptomic, proteomic, and phenotypic imaging inputs enables indication expansion beyond traditional small-molecule screening.
Industry Challenges
- Computational biology talent scarcity:Shortage of professionals bridging machine learning and molecular pharmacology constrains platform development velocity.
- ISO 13485 certification timelines:Quality management system implementation for medical device-classified screening tools delays commercial launch by 18-24 months.
- Legacy LIMS integration:Pharmaceutical IT environments require expensive middleware development to connect AI platforms with existing compound management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Intelligence in Drug Screening Market |
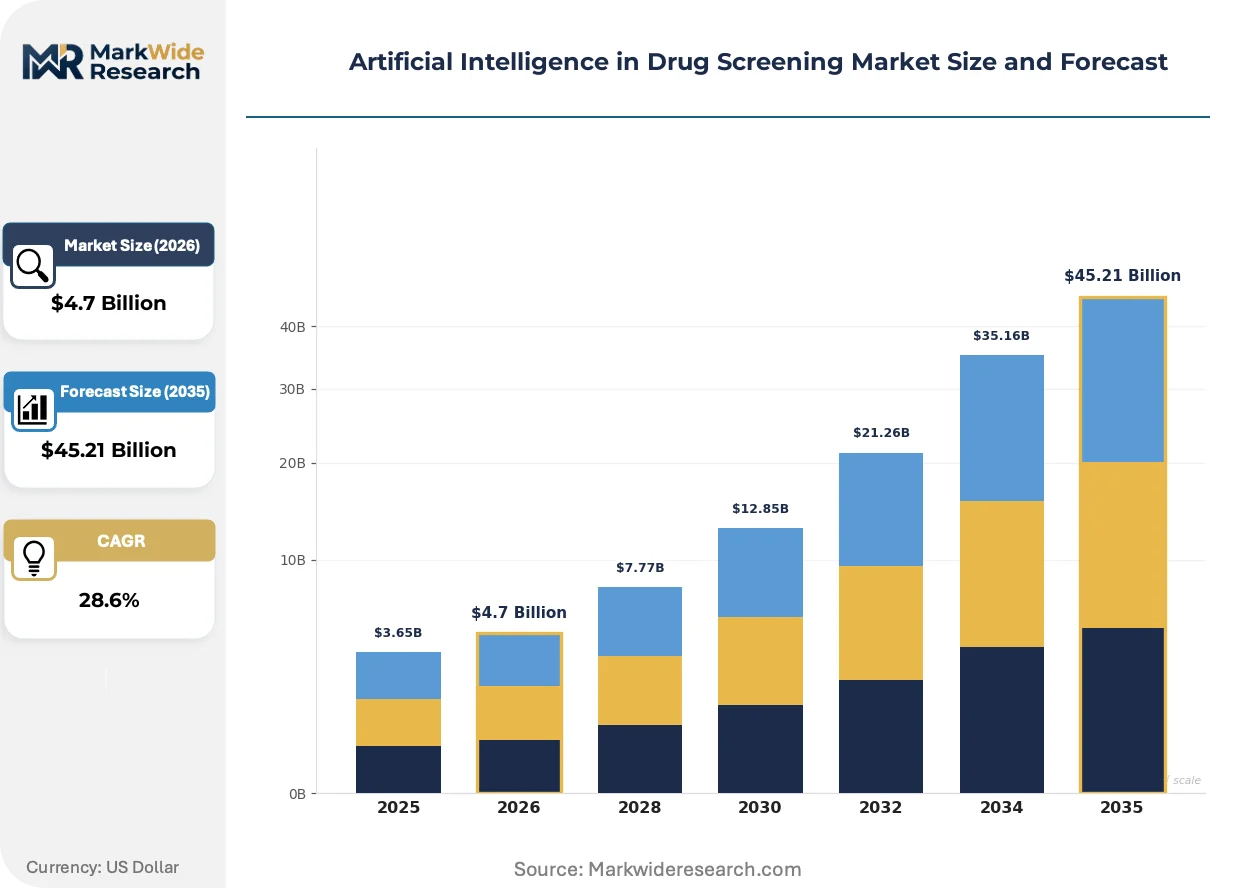
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $45.21 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
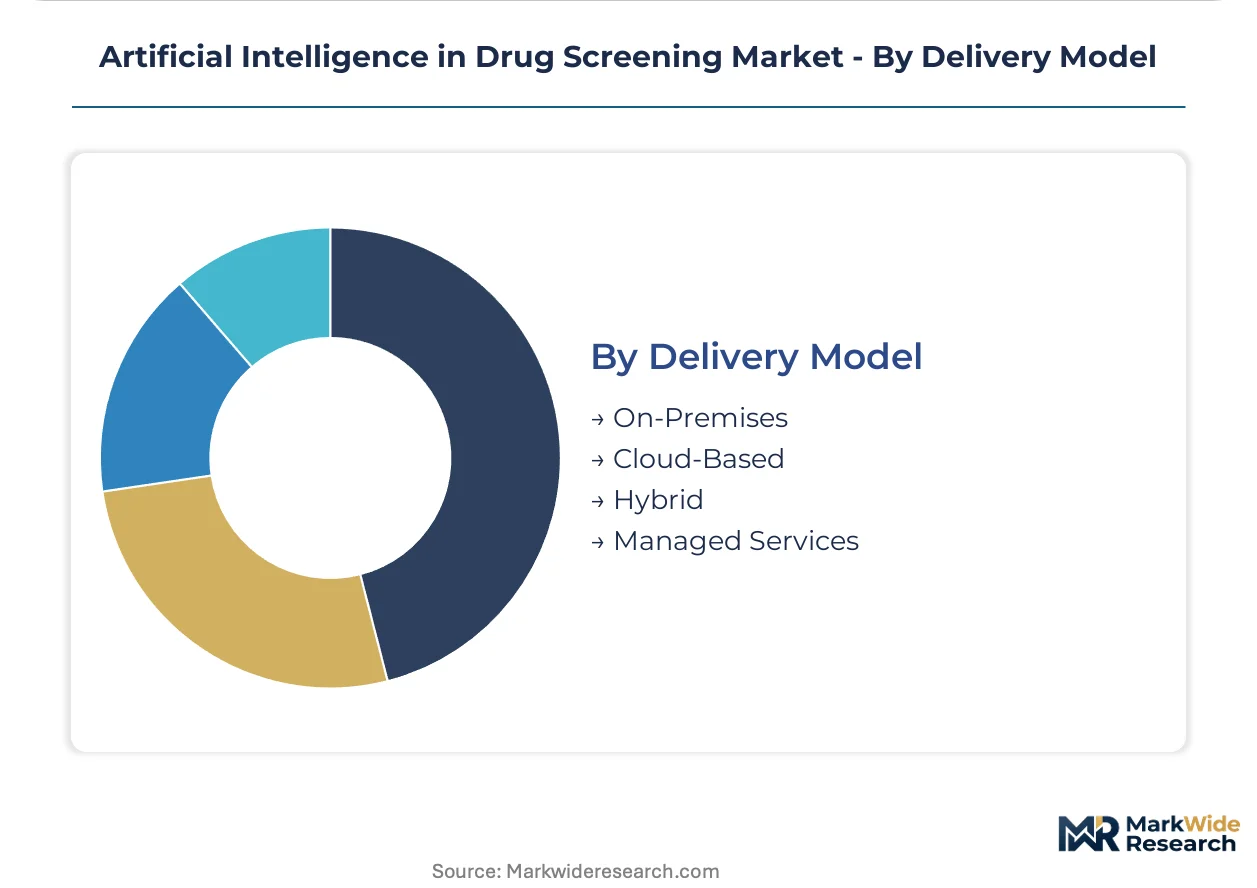
| Segmentation | Technology: Machine Learning, Deep Learning, Natural Language Processing, Computer Vision Application: Polypharmacology, Toxicology, Biomarker Discovery, Drug Repurposing End User: Pharmaceutical Companies, Contract Research Organizations, Academic Institutions, Biotechnology Firms Delivery Model: On-Premises, Cloud-Based, Hybrid, Managed Services |
| Companies Covered | NVIDIA Corporation, Exscientia, Insilico Medicine, Recursion Pharmaceuticals, Schrödinger, Atomwise, BenevolentAI, Isomorphic Labs, Insitro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Intelligence in Drug Screening Market Emerging Trajectories
Active diffusion of foundation models trained on protein structure databases is compressing the frontier between structural biology and predictive toxicology, forcing incumbent platforms to rearchitect around generative rather than discriminative learning paradigms.
Foundation models for molecular property prediction are consolidating competitive advantage around proprietary fine-tuning datasets rather than base architecture innovation. Mid-cap biotechnology firms are adopting these pre-trained weights through API access to avoid capital-intensive infrastructure buildouts. This consolidation is compressing the viable vendor set to those controlling either unique biological data generation capabilities or hyperscale compute reserves.
EMA's draft reflection paper on AI in medicinal product development is forcing toxicology screening providers to document algorithm performance across diverse patient populations before submission acceptance. The industrial consequence is mandatory investment in demographic stratification testing that was previously optional. Contract research organizations serving European pharmaceutical clients are most affected, accelerating partnerships with academic medical centers for retrospective validation cohorts.
Pharmaceutical procurement teams are unbundling computational screening from full-service discovery contracts, creating spot-market purchasing for burst-workload campaigns. This disintermediation pressures platform providers to offer transparent per-compound pricing rather than enterprise subscription models. The shift is most visible in United States biotechnology clusters where venture-backed firms prioritize operational flexibility over long-term vendor commitments.
Artificial Intelligence in Drug Screening Market Segmentation
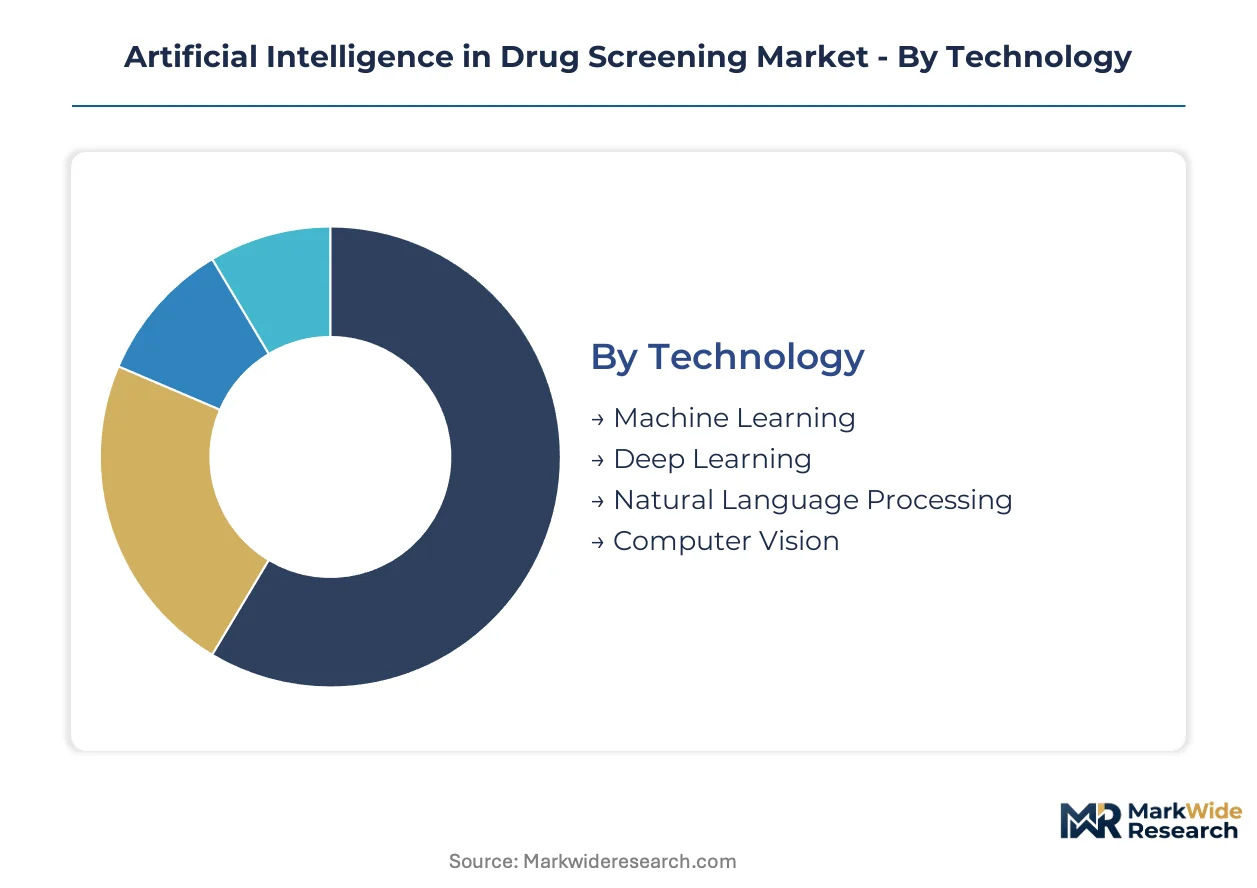
Segmentation in AI drug screening reveals how computational infrastructure, regulatory requirements, and end-user sophistication create divergent purchasing patterns across the value chain. Platform providers must architect modular offerings that span cloud-native biotech startups and compliance-heavy pharmaceutical incumbents simultaneously.
Technology:
Upgrade cycles in screening technology accelerate where legacy statistical methods face displacement by transformer architectures trained on protein structure databases.
- Deep Learning:Neural architectures extract hierarchical features from molecular graphs and cryo-EM density maps, enabling binding affinity predictions that reduce crystallography bottlenecks. Pharmaceutical companies in the United States prioritize these tools for kinome-wide target validation campaigns where wet-laboratory throughput limits progress.
- Machine Learning:Random forest and gradient-boosted models persist in production toxicology pipelines where interpretability requirements outweigh accuracy gains. Contract research organizations favor these established methods for regulatory submissions where algorithmic transparency eases FDA review.
- Natural Language Processing:Extracts structured relationships from patent corpora and clinical trial registries to identify repurposing candidates.
- Computer Vision:Quantifies phenotypic changes in high-content imaging assays for morphological profiling at scale.
Volume placements concentrate in Machine Learning; the faster expansion belongs to Deep Learning.
Application:
Application selection tracks the maturity of validation frameworks, with toxicology maintaining deployment leads while biomarker discovery builds evidence bases for regulatory acceptance.
- Toxicology:In-silico safety profiling predicts hepatotoxicity, cardiotoxicity, and genotoxicity endpoints using structural alerts and pathway models. United States biotechnology firms deploy these tools to compress IND-enabling study timelines where animal testing costs dominate preclinical budgets.
- Biomarker Discovery:Multi-omic integration identifies pharmacodynamic signatures that stratify patient responder populations. Academic medical centers in Germany and the United Kingdom drive demand through EMA qualification opinion pathways that validate computational biomarker submissions.
- Polypharmacology:Maps off-target interactions that explain adverse event mechanisms and identify combination opportunities.
- Drug Repurposing:Matches approved compounds to new indications through mechanistic pathway overlap and real-world evidence mining.
Revenue concentration favors Toxicology; Biomarker Discovery climbs the fastest as qualification pathways mature.
End User:
End-user segmentation reflects capital intensity gradients, with pharmaceutical incumbents funding platform builds while smaller entities rent computational capacity.
- Pharmaceutical Companies:Internal AI groups develop proprietary screening pipelines integrated with legacy compound management systems. These organizations in Switzerland and the United States maintain captive infrastructure to protect structural data assets from third-party exposure.
- Biotechnology Firms:Venture-backed developers outsource computational screening to manage burn rates during candidate optimization sprints. Clusters in Cambridge, Massachusetts and South San Francisco concentrate demand for burst-compute arrangements that replace capital-intensive server deployments.
- Contract Research Organizations:Provide validated screening services to sponsors lacking internal computational biology capabilities.
- Academic Institutions:Generate training datasets and benchmark algorithms through NIH-funded consortia.
Procurement volume centers on Pharmaceutical Companies; Biotechnology Firms are gaining share fastest through cloud-native purchasing models.
Delivery Model:
Delivery architecture selection hinges on data residency requirements and workload predictability, with hybrid configurations emerging where sensitive compound libraries coexist with elastic compute needs.
- Cloud-Based:API-accessible screening platforms eliminate infrastructure capital expenditure and enable per-compound pricing. Mid-cap biotechnology firms in the United Kingdom and the Netherlands prefer these arrangements for candidate optimization campaigns with variable throughput demands.
- On-Premises:Air-gapped deployments satisfy HIPAA and trade secret protections for proprietary structural databases. Large pharmaceutical organizations in Japan and the United States mandate these configurations for early-discovery stages where compound identity requires restricted access.
- Hybrid:Combines local data storage with cloud burst capacity for large-scale virtual screening campaigns.
- Managed Services:Outsourced platform operation with dedicated support for regulatory documentation and validation maintenance.
Deployment volume concentrates in Cloud-Based; Hybrid configurations show the steepest expansion trajectory as data governance tools mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston and Cambridge anchor the densest concentration of AI drug screening deployment, where NIH-funded academic medical centers and venture-backed biotechnology firms cluster within a ten-mile radius of Kendall Square.
United States
Federal computational biology funding through the National Institutes of Health accelerates training data generation for machine learning models. FDA guidance on AI-enabled medical product development establishes validation requirements that shape platform design. The Boston-Cambridge corridor concentrates demand from biotechnology firms seeking burst-compute arrangements for candidate optimization.
United Kingdom
Academic medical centers in London and Cambridge drive biomarker discovery applications through partnerships with EMA qualification pathways. The Medicines and Healthcare products Regulatory Agency coordinates with European counterparts on algorithm performance standards. The Golden Triangle biotech cluster generates multi-omic datasets that fuel proprietary model fine-tuning.
Germany
Pharmaceutical incumbents in Frankfurt and Munich maintain captive AI infrastructure integrated with legacy compound management systems. The Federal Institute for Drugs and Medical Devices enforces ISO 13485 quality management expectations for screening tools. The Heidelberg-Mannheim region concentrates contract research organizations serving European toxicology validation requirements.
Switzerland
Large pharmaceutical organizations in Basel mandate air-gapped deployments to protect proprietary structural databases from third-party exposure. Swissmedic coordinates with EMA on qualification opinions for computational biomarkers. The Basel biotech corridor anchors internal AI group development for kinome-wide target validation.
Japan
Mid-cap biotechnology firms in Tokyo and Osaka adopt cloud-native screening platforms to manage variable throughput demands. The Pharmaceuticals and Medical Devices Agency operates regulatory sandboxes for accelerated approval of computational toxicology tools. The Kanto region concentrates demand for API-accessible molecular simulation workloads.
Artificial Intelligence in Drug Screening Market Vendor Landscape
Premium-margin players sit above commodity-margin players across proprietary data access and regulatory-grade validation capabilities. The vendor base stratifies into three tiers: hyperscale compute providers, autonomous chemistry platforms, and biological data generators. Strategic differentiation concentrates on end-to-end integration versus modular API delivery. M&A activity targets training data assets and regulatory documentation capabilities.
Within the autonomous chemistry tier, Exscientia and Schrödinger exemplify platform providers compressing design-make-test cycles through integrated computational infrastructure. NVIDIA Corporation anchors the hyperscale compute vector with GPU infrastructure for high-throughput molecular simulation. Recursion Pharmaceuticals occupies a position in the biological data generator archetype through closed-loop discovery engines that rival open-architecture alternatives.
| Leading Market Players |
|---|
| NVIDIA Corporation |
| Exscientia |
| Insilico Medicine |
| Recursion Pharmaceuticals |
| Schrödinger |
| Atomwise |
| BenevolentAI |
| Isomorphic Labs |
| Insitro |
| Others |
Supply Flow & Price Mechanics
FDA guidance on AI-enabled medical product development gates qualified supply access for regulatory-grade screening platforms, restricting premium-tier pricing to vendors with validated audit trails and documented algorithm performance across diverse patient populations. Pharmaceutical procurement teams leverage this compliance threshold to compress pricing for commodity prediction tools while sustaining premium arrangements with end-to-end autonomous chemistry providers.
Pricing Analysis
Value-based pricing anchored to IND submission success rates and timeline compression outcomes dominates contract structures for AI drug screening platforms. Three-tier pricing structure across regulatory-validated, benchmark-tested, and open-source tiers reflects differentiation by FDA submission support depth and proprietary training data access. Pricing pressure stems from GPU infrastructure cost volatility and mid-cap biotechnology firms adopting API-accessible burst-compute models over enterprise subscriptions. Contract research organizations exhibit highest price sensitivity due to margin compression in fee-for-service toxicology validation; pharmaceutical incumbents prioritize outcome guarantees over unit cost.
Supply Chain Analysis
Direct-to-pharmaceutical channels handle hyperscale buyer demand for integrated discovery platforms, while API-mediated distribution serves venture-backed biotechnology firms with variable throughput requirements. GPU manufacturing concentrates in Taiwan, South Korea, and the United States, with NVIDIA infrastructure anchoring training workloads for molecular simulation. The supply chain draws from specialized semiconductor foundries, cryo-EM equipment manufacturers, and cloud hyperscaler data centers. Single-source vulnerability in advanced GPU procurement creates bottleneck risk for mid-scale platform providers. Distribution runs through specialized contract research organization networks and direct enterprise sales teams serving Basel and Boston-Cambridge pharmaceutical clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Transformer-based protein structure prediction is displacing legacy statistical methods in toxicology screening, compressing competitive timelines for platform providers and forcing architectural reinvestment across the vendor base.
For Market Incumbents: Deepen proprietary biological data generation capabilities to differentiate against foundation model API commoditization. Secure ISO 13485 certification ahead of EMA qualification opinion pathway expansion to defend regulatory-grade pricing tiers. Incumbent platforms face substitution threat from generative chemistry startups with lower infrastructure overhead.
For New Entrants and Emerging Players: Begin with Japan's PMDA regulatory sandbox for computational toxicology tools, where accelerated approval pathways reduce validation capital requirements. Target mid-cap biotechnology firms in the United Kingdom and Netherlands seeking cloud-native burst-compute arrangements without long-term vendor commitments. A per-compound transparent pricing model displaces entrenched subscription relationships in venture-backed clusters.
For Investors and Strategic Acquirers: EMA draft reflection paper finalization is the leading indicator that demographic stratification testing mandates will consolidate viable vendors to those with academic medical center partnerships. Long-term viability favors closed-loop discovery engines integrating captive data generation with machine learning over open-architecture alternatives. Acquisition targets should demonstrate proprietary fine-tuning datasets rather than base architecture innovation.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory-Grade Validation Pipeline Investment | FDA submission-ready audit trails differentiate premium platforms from commodity prediction tools. |
| Academic Medical Center Partnership | Retrospective validation cohorts satisfy EMA demographic stratification requirements for toxicology screening. |
| GPU Infrastructure Reservation Agreement | Secured compute capacity insulates against NVIDIA supply concentration and procurement bottlenecks. |
| Cloud-Native API Platform Launch | Per-compound pricing models capture venture-backed biotechnology firm demand for operational flexibility. |
| Multi-Omic Data Fusion Capability | Integration of transcriptomic and phenotypic imaging inputs expands addressable market beyond small-molecule screening. |
Methodological Framework
Multi-period observation of NIH computational biology funding allocations, FDA guidance document releases, and EMA qualification opinion precedents anchored the trend analysis, supplemented by interviews with drug development executives, regulatory affairs leads at pharmaceutical sponsors, platform engineers at contract research organizations, and formulary access specialists. Secondary validation drew from FDA filings, EMA reflection papers, ClinicalTrials.gov registry entries, and hyperscaler capex disclosures. Bottom-up segmentation modeling triangulated against top-down market sizing from federal funding trajectories and biotechnology venture deployment patterns.
Segment-weighting across technology archetype, application maturity, end-user capital intensity, and delivery model governance requirements structured the analytical framework. Deployment model transitions and regulatory acceptance timelines were modeled throughout the forecast period. CAGRs derived from trajectory fitting to historical adoption curves in adjacent computational biology markets, adjusted for AI-specific validation pathway maturation. Forecast inputs included NIH appropriations projections, GPU infrastructure capacity expansion announcements, and EMA qualification opinion issuance rates.
Underlying measurement precision varies by segment; toxicology screening applications carry tighter precision than emerging biomarker discovery use cases due to established validation frameworks. Forecasts reflect assumptions regarding FDA guidance finalization timing and EMA methodological qualification pathway expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
United Kingdom (UK) Diabetes Drugs Market
Pharmaceuticals
Global Epilepsy Drug Market
Pharmaceuticals
Computer-Aided Drug Discovery Market
Pharmaceuticals
Middle-East and Africa Sodium-Dependent Glucose Co-Transporter 2 Inhibitors Market
Pharmaceuticals
Global Divalproex Sodium Market
Pharmaceuticals
Pharmacy and Drug Store Franchises Market
Pharmaceuticals
Traumatic Brain Injury Drugs Market
Pharmaceuticals
Metoprolol Tartrate Market
Pharmaceuticals
Unfractionated Heparin Market
Pharmaceuticals
Empty Capsules Market
Pharmaceuticals
Cough Syrup Market
Pharmaceuticals
Dyslipidemia Therapeutics Market
Pharmaceuticals
Clozapine Market
Pharmaceuticals
Canada Pharmaceutical Market
Pharmaceuticals
Asia-Pacific Sodium-Dependent Glucose Cotransporter 2 (SGLT-2) Market
Pharmaceuticals
Antiplatelet Drugs Market