
 Processed Fruit Bases Market | 2026-2036
Processed Fruit Bases Market Size, Share, and Industry Trends Forecast 2026-2036
Processed Fruit Bases Market Analytics
Apple puree is broadening its substitution footprint across bakery and confectionery applications as formulators reduce refined sugar content. Döhler Group leverages integrated fruit sourcing networks across Central Europe to secure year-round raw material continuity. AGRANA Beteiligungs AG anchors its position through captive sugar-reduction R&D facilities in Austria. Del Monte Foods Inc. competes on tropical fruit specialization, controlling pineapple and mango puree supply chains from plantation to processing.
Processed fruit bases comprise stabilized fruit preparations—typically 18-32°Brix concentrates, aseptic purees, or individually quick-frozen (IQF) segments—manufactured through enzymatic treatment, evaporation, and pasteurization for downstream food and beverage integration. The primary commercial purpose centers on delivering consistent flavor, color, and functional viscosity to manufacturers lacking fresh fruit handling infrastructure. Puree and concentrate categories dominate value capture, with puree commanding premium positioning in infant nutrition and dairy applications while concentrate volumes expand fastest in carbonated and still beverage production. Frozen segments sustain margin pools through cold-chain-dependent foodservice channels where texture integrity commands specification premiums.
FDA food safety modernization rules and USDA organic certification requirements shape North American product standards, while EFSA purity specifications and EU Green Deal farm-to-fork targets constrain formulation chemistry and carbon intensity across European supply bases. These regulatory layers elevate compliance costs for non-integrated processors while creating technical barriers that favor operators with in-house analytical and reformulation capabilities. Stakeholders must monitor evolving maximum residue limits for crop protection chemicals and assess backward integration into varietal breeding programs to secure long-term specification compliance.
Market Dynamics
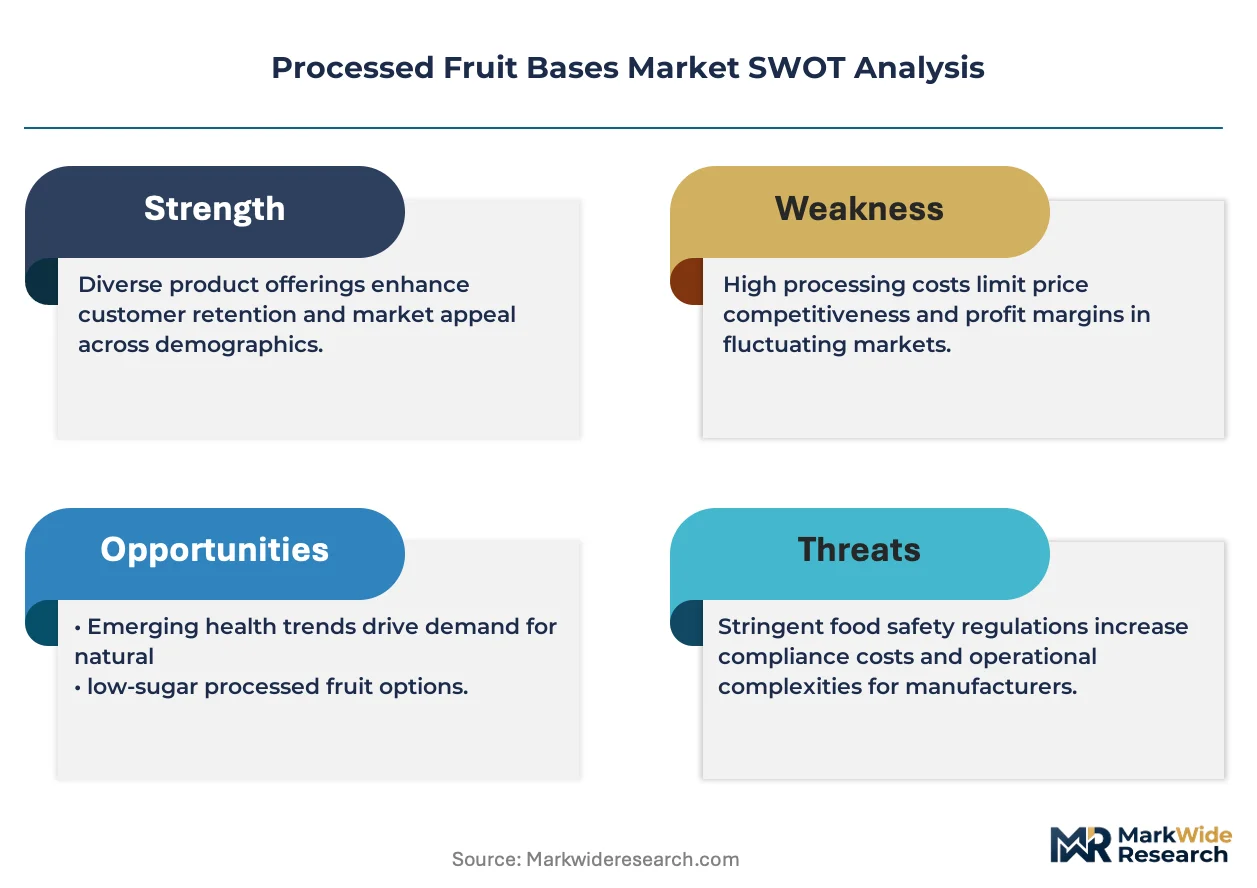
EU Green Deal farm-to-fork mandates are compressing processor margins while simultaneously advantaging operators with captive extraction technology and varietal breeding programs.
Growth Catalysts
- Clean-label beverage formulation:Carbonated and still drink manufacturers are expanding procurement of aseptic purees to replace artificial flavor systems, pulling concentrate volumes through 2035.
- USDA organic certification pipeline:Infant nutrition brands in North America are locking multi-year contracts for certified organic apple and pear purees, creating specification premiums that sustain margin pools.
- Germany's industrial bakery clusters:Customized puree blend demand concentrates in Bavaria and Baden-Württemberg, where automated portioning systems require viscosity-calibrated fruit bases at scale.
Market Restraints
- Water-stressed sourcing zones:Concentrated pineapple cultivation in Costa Rica and Thailand faces irrigation quota tightening, elevating raw material volatility for tropical puree processors.
- EFSA maximum residue limit compression:Tighter crop protection chemical thresholds are disqualifying conventional orchards from EU supply chains, shrinking qualified supplier bases.
- Fresh fruit substitution elasticity:Quick-service chains with in-house peeling infrastructure can pivot to whole fruit during puree price spikes, capping pricing power in foodservice channels.
Strategic Opportunities
- Reduced-water extraction technology:Membrane filtration and osmotic concentration systems are opening facility locations in water-scarce regions previously excluded from processing economics.
- India's organized retail expansion:Modern trade format growth in Mumbai, Delhi, and Bangalore is creating cold-chain demand for IQF fruit segments in premium dessert applications.
- EU Green Deal carbon accounting:Processors with verified low-intensity supply chains can access preferential procurement terms from sustainability-mandated multinational food manufacturers.
Industry Challenges
- Enzymatic process engineering talent:Shortage of specialists in pectinase optimization and thermal profile control is extending commissioning timelines for new aseptic lines.
- Multi-certification stacking:Simultaneous pursuit of organic, kosher, halal, and BRC accreditation creates audit complexity and documentation overhead that smaller processors struggle to absorb.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Processed Fruit Bases Market |
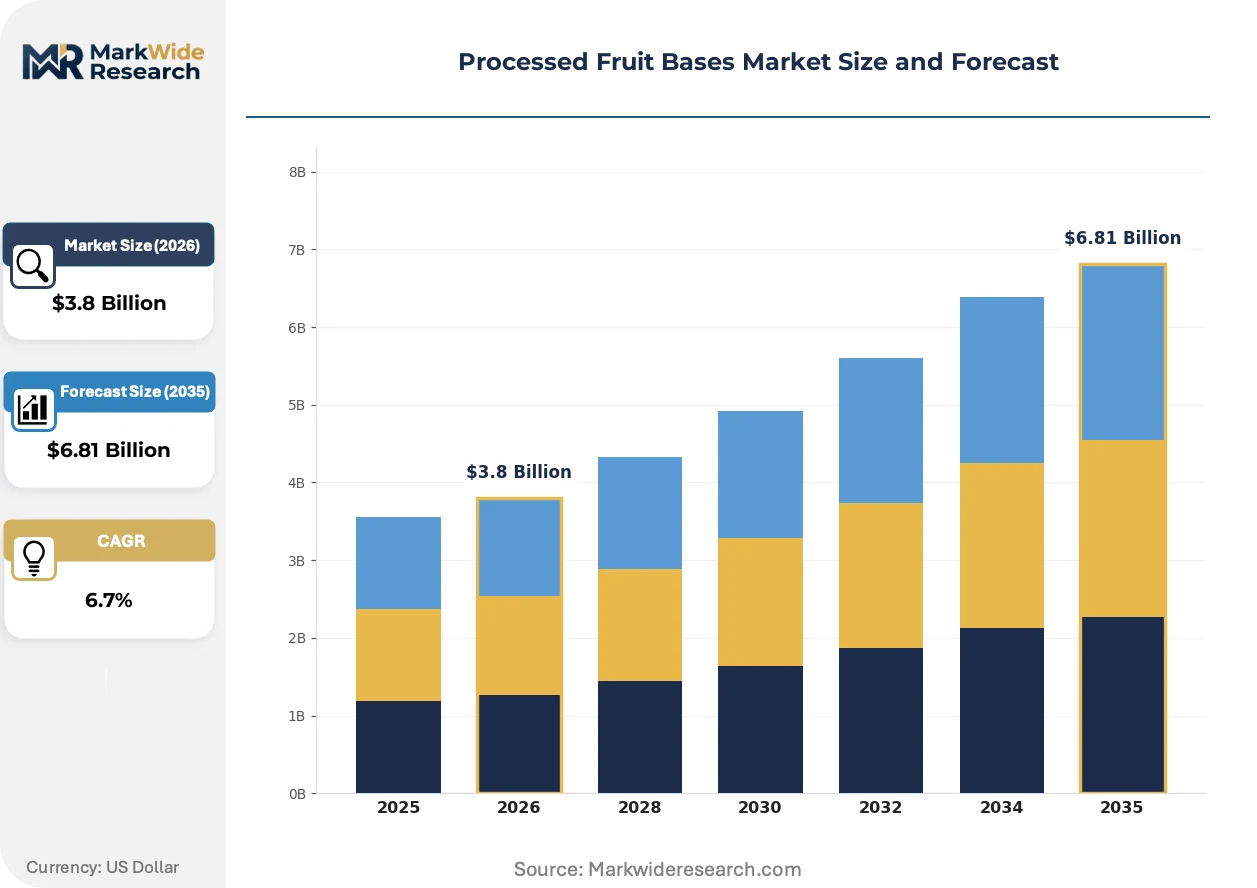
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Puree, Concentrate, Dried, Frozen End Use: Beverages, Bakery, Confectionery, Dairy Packaging Type: Glass Jar, Plastic Container, Sachet, Bulk Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Others |
| Companies Covered | Dole Food Company Inc., Nestlé S.A., AGRANA Beteiligungs AG, Conagra Brands Inc., Archer Daniels Midland Company, Döhler Group, Ingredion Incorporated, Del Monte Foods Inc., The Kraft Heinz Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Processed Fruit Bases Market Evolving Landscape
Extraction technology advances and regulatory carbon accounting are rewriting operational economics across the processed fruit base supply chain.
Membrane filtration systems are replacing conventional evaporators in concentrate production, cutting thermal energy consumption by half. Beverage manufacturers in Germany and the Netherlands are qualifying these outputs for clean-label claims. This technology is rewriting facility location logic, permitting profitable operations in regions previously excluded by water or energy constraints.
EU Green Deal corporate sustainability reporting requirements now mandate Scope 3 agricultural emissions disclosure. Processors must document orchard-to-warehouse carbon intensity or face exclusion from multinational procurement lists. French and Italian dairy cooperatives are most exposed, accelerating backward integration into varietal breeding to secure low-carbon raw material pipelines.
Direct contracting between processors and organized retail bakery chains is displacing traditional ingredient distributor intermediation in Western Europe. Buyers in Spain and Portugal now specify Brix, pH, and viscosity tolerances in annual tenders rather than accepting standard catalog grades. This channel compression is most visible in the premium dessert segment, where texture integrity commands specification premiums that justify bypassing wholesale layers.
Processed Fruit Bases Market Segmentation
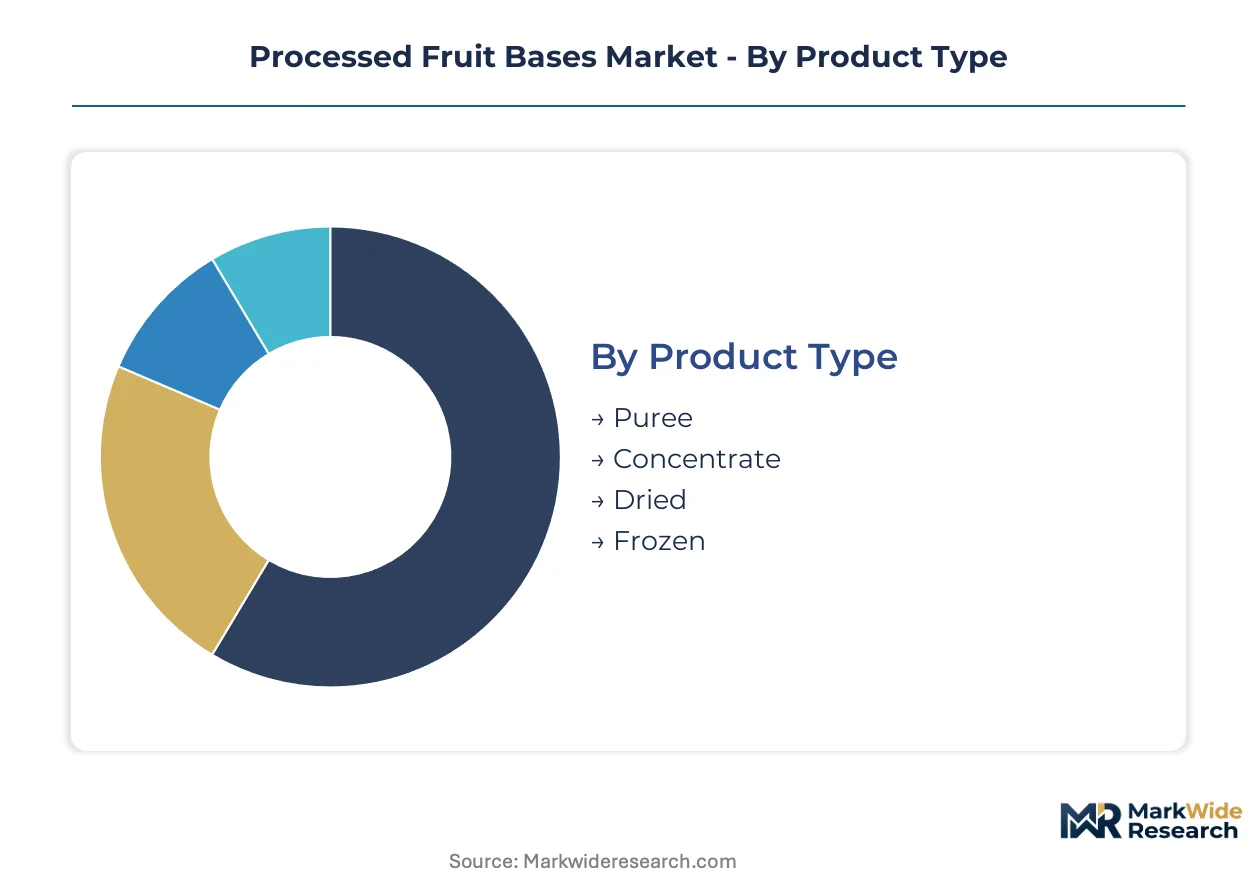
Segmentation in processed fruit bases reveals distinct specification requirements across downstream applications. Beverage manufacturers prioritize Brix consistency and aseptic stability, while bakery and dairy channels demand viscosity-calibrated purees with precise enzymatic treatment profiles. Understanding these divergent technical thresholds enables processors to align production assets with margin-optimized demand pools.
Product Type:
Purchase volume and shelf-life requirements dictate format selection, with cold-chain availability and formulation flexibility driving the trade-off between concentrate economy and puree premium positioning.
- Puree:Aseptic fruit purees at 18-24°Brix deliver intact fiber matrices and controlled viscosity for infant nutrition and dairy applications. German industrial bakery clusters source customized apple and pear purees with enzymatically modified pectin profiles for automated depositing systems. Specification premiums sustain margins where viscosity tolerances tighten to ±5% batch-to-batch variance.
- Concentrate:Evaporated or membrane-concentrated bases at 28-32°Brix minimize transport costs and enable dilution flexibility at point-of-use. Carbonated beverage manufacturers in the Netherlands and Germany are expanding procurement of these formats for clean-label flavor systems, pulling volumes through reformulation cycles that displace artificial alternatives.
- Dried:Low-moisture fruit powders and flakes extend shelf stability for confectionery inclusions and dry mix applications where water activity constraints apply.
- Frozen:IQF segments and frozen purees preserve texture integrity for premium dessert and foodservice channels dependent on cold-chain infrastructure.
Puree leads on scale through dairy and infant nutrition contract volumes; concentrate leads on momentum through beverage clean-label reformulation.
End Use:
Application-specific rheology and microbial specifications fragment demand, with each channel imposing distinct certification and processing constraints.
- Beverages:Still and carbonated drink manufacturers require clarified concentrates with low pulp content and stable color metrics across shelf life. EU Green Deal carbon accounting mandates now favor processors with verified low-intensity supply chains, reshaping procurement qualification in France and Italy.
- Bakery:Industrial scale operations in Bavaria and Baden-Württemberg demand viscosity-calibrated purees compatible with automated portioning and depositing equipment. Sugar-reduction trends are accelerating substitution of refined sweeteners with apple puree extending across croissant, muffin, and filled pastry applications.
- Confectionery:Fruit inclusions and centers require controlled water activity and texture stability through thermal processing cycles.
- Dairy:Yogurt and dessert applications prioritize aseptic purees with neutral pH drift and minimal syneresis risk through fermentation.
Beverage applications lead on scale through concentrate volumes; bakery leads on momentum through sugar-reduction substitution elasticity.
Packaging Type:
Volume scale and contamination risk tolerance determine format economics, with foodservice and industrial channels favoring unit cost minimization over retail presentation.
- Bulk:Aseptic bag-in-drum and tanker formats serve industrial manufacturers with dedicated receiving infrastructure and rapid throughput requirements. German dairy cooperatives and beverage bottlers in the Netherlands specify these formats for annual contract volumes where handling efficiency outweighs packaging premiums.
- Glass Jar:Premium retail positioning for organic and specialty purees leverages transparency and chemical inertness for shelf-stable distribution.
- Plastic Container:Polypropylene and PET formats balance cost and convenience for mainstream retail and foodservice portioning.
- Sachet:Single-serve flexible packaging serves hospitality and institutional channels requiring portion control and minimal waste.
Bulk packaging leads on scale through industrial procurement concentration; glass jar leads on momentum through organic certification premiums.
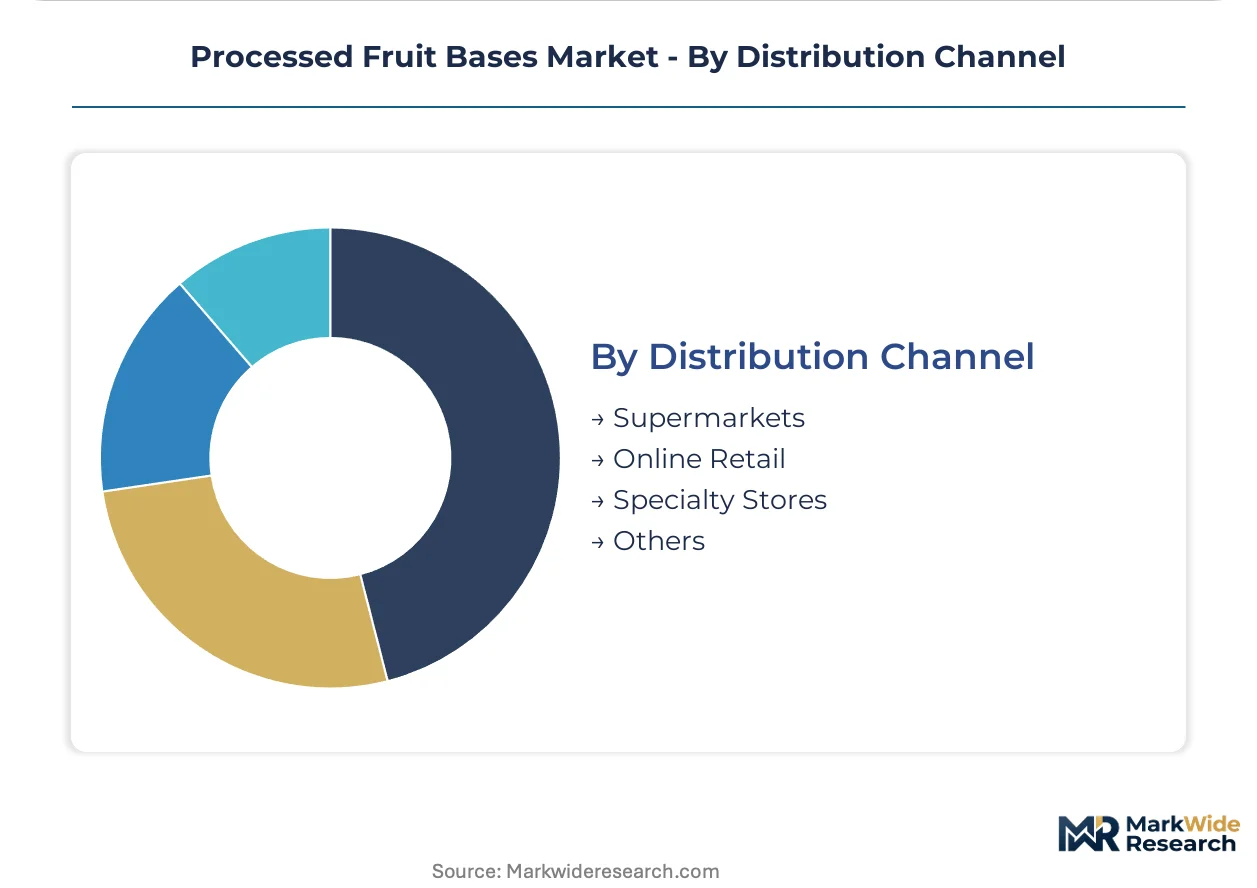
Distribution Channel:
Channel selection reflects buyer scale and specification complexity, with direct contracting displacing wholesale intermediation where technical parameters require annual calibration.
- Specialty Stores:Organic and gourmet retailers in Spain and Portugal specify Brix, pH, and viscosity tolerances in direct annual tenders, bypassing traditional ingredient distributors. This channel compression is most visible in premium dessert segments where texture integrity commands specification premiums that justify procurement overhead.
- Supermarkets:Organized retail chains in India—expanding through Mumbai, Delhi, and Bangalore—are creating cold-chain demand for IQF segments in premium dessert applications as modern trade format penetration deepens.
- Online Retail:E-commerce platforms serve small-batch manufacturers and regional processors with fragmented demand and limited storage infrastructure.
- Others:Foodservice distributors and institutional procurement networks complete channel coverage for hospitality and catering applications.
Supermarkets lead on scale through modern trade expansion; specialty stores lead on momentum through direct contracting and specification premium capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial bakery clusters in Bavaria and Baden-Württemberg anchor European demand for viscosity-calibrated fruit purees, while regulatory pressure from the EU Green Deal reshapes procurement qualification across the continent.
Germany
Automated portioning systems in Bavarian croissant and muffin plants pull customized apple and pear purees with enzymatically modified pectin profiles. The EU Green Deal's farm-to-fork mandates compress processor margins while favoring operators with captive extraction technology. Ingredient distributors in Baden-Württemberg face displacement as industrial buyers issue direct annual tenders specifying Brix and viscosity tolerances.
United States
Infant nutrition brands in California and New York Metro lock multi-year contracts for certified organic apple and pear purees, creating specification premiums that sustain margin pools. FDA food safety modernization rules and USDA organic certification requirements shape product standards and elevate compliance costs. Beverage manufacturers in the Pacific Northwest expand procurement of aseptic purees to replace artificial flavor systems in clean-label reformulations.
Netherlands
Carbonated and still drink manufacturers in Rotterdam and Amsterdam accelerate concentrate volumes through reformulation cycles that displace artificial alternatives. EFSA purity specifications constrain formulation chemistry across European supply bases. Membrane filtration adoption permits profitable processing operations in water-scarce regions previously excluded by conventional evaporator economics.
India
Modern trade format expansion in Mumbai, Delhi, and Bangalore creates cold-chain demand for IQF fruit segments in premium dessert applications. FSSAI regulations govern food safety standards while organized retail growth deepens specification complexity. Processors target Maharashtra and Karnataka for facility locations that serve quick-service chains with backward integration into varietal breeding programs.
France
Dairy cooperatives in Île-de-France and Auvergne-Rhône-Alpes accelerate backward integration into varietal breeding to secure low-carbon raw material pipelines under EU Green Deal corporate sustainability reporting. EFSA maximum residue limit compression disqualifies conventional orchards from supply chains, shrinking qualified supplier bases. Paris-based dessert manufacturers specify texture-calibrated purees in direct procurement contracts that bypass wholesale intermediation.
Processed Fruit Bases Market Competitive Landscape
Capacity expansion dominates the current landscape as processors install membrane filtration and osmotic concentration systems to access water-scarce regions and qualify for EU Green Deal carbon accounting preferences. The vendor base stratifies across three tiers: multinational ingredient conglomerates with integrated fruit sourcing networks, mid-scale regional processors with specialized puree capabilities, and commodity concentrate traders dependent on spot market arbitrage. Strategic partnerships and portfolio diversification represent the dominant competitive moves, with operators seeking multi-certification stacking to capture organic, kosher, and halal specification premiums.
Within the multinational conglomerate tier, Döhler Group and AGRANA Beteiligungs AG exemplify operators with integrated Central European fruit sourcing networks and captive R&D infrastructure. Del Monte Foods Inc. occupies a position among tropical fruit specialists controlling plantation-to-processing supply chains for pineapple and mango purees. These three entities represent distinct archetypes: the diversified ingredient platform, the regional processing anchor with sugar-reduction capabilities, and the vertical tropical commodity controller.
| Leading Market Players |
|---|
| Dole Food Company Inc. |
| Nestlé S.A. |
| AGRANA Beteiligungs AG |
| Conagra Brands Inc. |
| Archer Daniels Midland Company |
| Döhler Group |
| Ingredion Incorporated |
| Del Monte Foods Inc. |
| The Kraft Heinz Company |
| Others |
Value Network & Pricing Analysis
EU Green Deal farm-to-fork mandates are forcing beverage manufacturers to source from processors with verified low-carbon supply chains, compressing margins for conventional operators while creating specification premiums for certified suppliers. This regulatory pressure reshapes procurement economics as buyers absorb higher input costs to maintain multinational supply eligibility.
Pricing Analysis
Input-cost pass-through from raw fruit procurement dominates pricing dynamics, with irrigation quota tightening in Costa Rica and Thailand elevating tropical puree volatility. Three-tier pricing structure across premium, standard, and economy levels separates organic-certified purees for infant nutrition from conventional concentrates for beverage applications. Price differentiation hinges on certification stacking and viscosity calibration precision. Pricing pressure stems from EFSA maximum residue limit compression disqualifying conventional orchards. Quick-service chains with in-house peeling infrastructure exhibit highest price sensitivity, while dairy cooperatives in France and Germany demonstrate lowest elasticity due to formulation lock-in.
Supply Chain Analysis
Apple and pear supply rests on Central European orchard networks in Germany, Poland, and Austria, while pineapple and mango sourcing draws from plantation zones in Costa Rica, Thailand, and the Philippines. Raw material dependencies center on varietal breeding programs, pectinase enzyme supply, and aseptic packaging film. Single-source vulnerability concentrates in tropical puree processors lacking diversified geography coverage. Distribution runs through direct annual tenders from industrial bakery clusters and beverage manufacturers, displacing traditional ingredient distributor intermediation in Western Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's Scope 3 agricultural emissions disclosure mandate compounds processor economics, creating sustained demand for carbon-accounted fruit bases as multinational manufacturers face procurement exclusion risks.
For Market Incumbents: Deploy membrane filtration technology adoption to access water-scarce regions and qualify for EU Green Deal carbon accounting preferences. Incumbents must defend against emerging regional processors by securing captive varietal breeding programs that lock low-carbon raw material pipelines. Capacity addition in Maharashtra and Karnataka serves quick-service chain demand while building backward integration moats. For New Entrants and Emerging Players: Organized retail bakery chains in Spain and Portugal represent the most penetrable channel partner type, as direct contracting displaces wholesale intermediation. New entrants should target IQF fruit segments for India's modern trade expansion in Mumbai, Delhi, and Bangalore. A go-to-market angle centered on texture-calibrated puree specifications for automated portioning systems bypasses established distributor relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale regional processors possessing specialized puree capabilities and multi-certification stacking infrastructure. Long-term viability favors operators with demonstrated enzymatic process engineering talent and captive R&D facilities. The signal to watch is accelerated direct contracting velocity between processors and sustainability-mandated multinational food manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Adoption | Reduces thermal energy consumption by half, qualifying outputs for EU Green Deal procurement preferences. |
| Backward Integration into Varietal Breeding | Secures low-carbon raw material pipelines under EFSA maximum residue limit compression. |
| Multi-Certification Stacking | Captures organic, kosher, and halal specification premiums that sustain margin pools. |
| Direct Annual Tendering | Bypasses wholesale intermediation with industrial bakery clusters in Bavaria and Baden-Württemberg. |
| Cold-Chain Infrastructure Expansion | Enables IQF segment penetration into India's modern trade formats in Mumbai and Delhi. |
Research Methodology
Multiple input streams — processor procurement managers, beverage formulation directors, dairy cooperative technical leads, and retail bakery chain buyers — were reconciled against secondary validation from EU Green Deal regulatory filings, FSSAI safety standards, and customs trade records. Primary interviews with enzymatic process engineers and aseptic line operators informed operational constraint assessments. Bottom-up volume modeling across puree, concentrate, dried, and frozen formats triangulated with top-down value aggregation.
Data-stream reconciliation anchored forecasts across product type, end-use application, packaging format, and distribution channel dimensions. CAGRs were derived through segment-level growth rate reconciliation against macroeconomic drivers. Industry-specific forecast inputs incorporated EU Green Deal carbon accounting adoption curves and membrane filtration technology penetration rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to irrigation quota enforcement in tropical sourcing zones and EFSA maximum residue limit threshold revisions. Forecasts reflect assumptions around clean-label reformulation velocity and organized retail expansion pace. A small set of named triggers — EU Green Deal procurement exclusion enforcement, FSSAI cold-chain mandate expansion, and enzymatic process engineering talent availability — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
South America Soup Market
Processed Foods
Low-Fat Desserts to Buy Market
Processed Foods
Fermented Foods Market
Processed Foods
Tomato Puree Market
Processed Foods
Chocolate Filling Market
Processed Foods
Dairy Desserts Market
Processed Foods
United States Fresh Noodles Market
Processed Foods
Asia-Pacific Soup Market
Processed Foods
Processed Eucheuma Seaweed Market
Processed Foods
United States Ice Cream Market
Processed Foods
Sugar-Free Ice Cream Market
Processed Foods
Processed Meat Market
Processed Foods
Fat Free Food Market
Processed Foods
India Spray Dried Food Market
Processed Foods
Mashed Potatoes Market
Processed Foods
Processed Vegetable Market