
 Global Orthopedic Imaging Equipment Market | 2026-2036
Global Orthopedic Imaging Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Orthopedic Imaging Equipment Market Foresight
The EU Medical Device Regulation is realigning the cost-of-entry calculus for orthopedic imaging manufacturers seeking CE marking access across Europe. Siemens Healthineers leverages its established regulatory affairs infrastructure to sustain faster conformity assessment timelines than smaller rivals. GE HealthCare anchors its competitive position through backward integration into detector manufacturing, while Philips Healthcare differentiates via its integrated diagnostic workflow software that spans imaging modalities.
Orthopedic imaging equipment encompasses diagnostic systems engineered to visualize musculoskeletal structures through ionizing radiation, magnetic fields, or acoustic waves, with spatial resolution thresholds typically ranging from sub-millimeter for CT bone detail to sub-millimeter isotropic for MRI soft-tissue contrast. These systems serve the primary commercial purpose of enabling pre-operative planning, fracture classification, implant positioning verification, and post-surgical monitoring across hospital and outpatient settings. Digital radiography occupies the largest installed base among product types due to its lower capital footprint and faster exam throughput, while portable imaging represents the fastest-expanding technology segment as point-of-care musculoskeletal assessment migrates beyond traditional radiology departments. MRI scanners command the deepest margin pools in joint assessment applications, where cartilage and ligament visualization requirements justify premium pricing.
The FDA governs device clearance through the 510(k) pathway and radiation safety performance standards, while the EU MDR imposes stricter clinical evidence requirements and post-market surveillance obligations that extend compliance costs across the product lifecycle. Japan's PMDA maintains distinct pharmaceutical and medical device agency protocols that create additional localization burdens for foreign manufacturers. Stakeholders must monitor how divergent regulatory timelines across these three jurisdictions reshape competitive access and prioritization of R&D spending.
Market Dynamics
The EU Medical Device Regulation's stricter clinical evidence requirements are forcing orthopedic imaging manufacturers to restructure their conformity assessment timelines and post-market surveillance systems, compressing competitive access for smaller players while rewarding established regulatory affairs infrastructure.
Growth Catalysts
- Ambulatory surgical center expansion:Rising procedural volumes in outpatient settings across the United States and Germany are redirecting capital budgets toward portable imaging platforms and digital radiography systems with faster exam throughput.
- FDA radiation dose optimization protocols:The agency's renewed enforcement emphasis on ALARA principles is accelerating replacement cycles for aging fixed radiography units with dose-efficient digital detectors.
- Japan's aging demographic density:Concentrated elderly populations in Tokyo and Osaka corridors are sustaining hospital infrastructure renewal demand for MRI scanners with superior soft-tissue contrast for joint assessment.
Market Restraints
- Detector component supply concentration:Backward integration into amorphous silicon flat-panel detector manufacturing remains concentrated among a limited set of East Asian substrate suppliers, creating input vulnerability.
- EU MDR compliance cost escalation:The regulation's extended clinical evidence requirements and notified body capacity constraints are stretching conformity assessment timelines to 18-24 months for new submissions.
- CT bone detail substitution pressure:Cone-beam CT systems in dental and extremity applications are capturing cases previously routed to conventional CT, compressing volume in certain hospital departments.
Strategic Opportunities
- India's underserved tier-2 hospital network:Domestic manufacturing incentives under the PLI scheme are creating localized production pathways for cost-optimized digital radiography units targeting 400+ district hospitals.
- AI-assisted diagnostic workflow integration:Automated fracture detection algorithms are converging with PACS architectures to reduce radiologist reading time and enable point-of-care decision support.
- Mobile C-arm penetration in Germany:Outpatient orthopedic clinics are adopting battery-powered fluoroscopy systems for intraoperative implant verification, bypassing traditional radiology department queues.
Industry Challenges
- Specialized service engineer scarcity:MRI superconducting magnet maintenance and helium management require technician certifications that outpace vocational training program output in multiple markets.
- Legacy PACS integration friction:New digital radiography installations face interoperability barriers with decade-old hospital information systems, extending deployment timelines and requiring costly middleware.
- CE marking documentation burden:EU MDR's expanded technical file requirements for clinical evaluation reports are consuming 40% more regulatory affairs capacity than predecessor directives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Orthopedic Imaging Equipment Market |
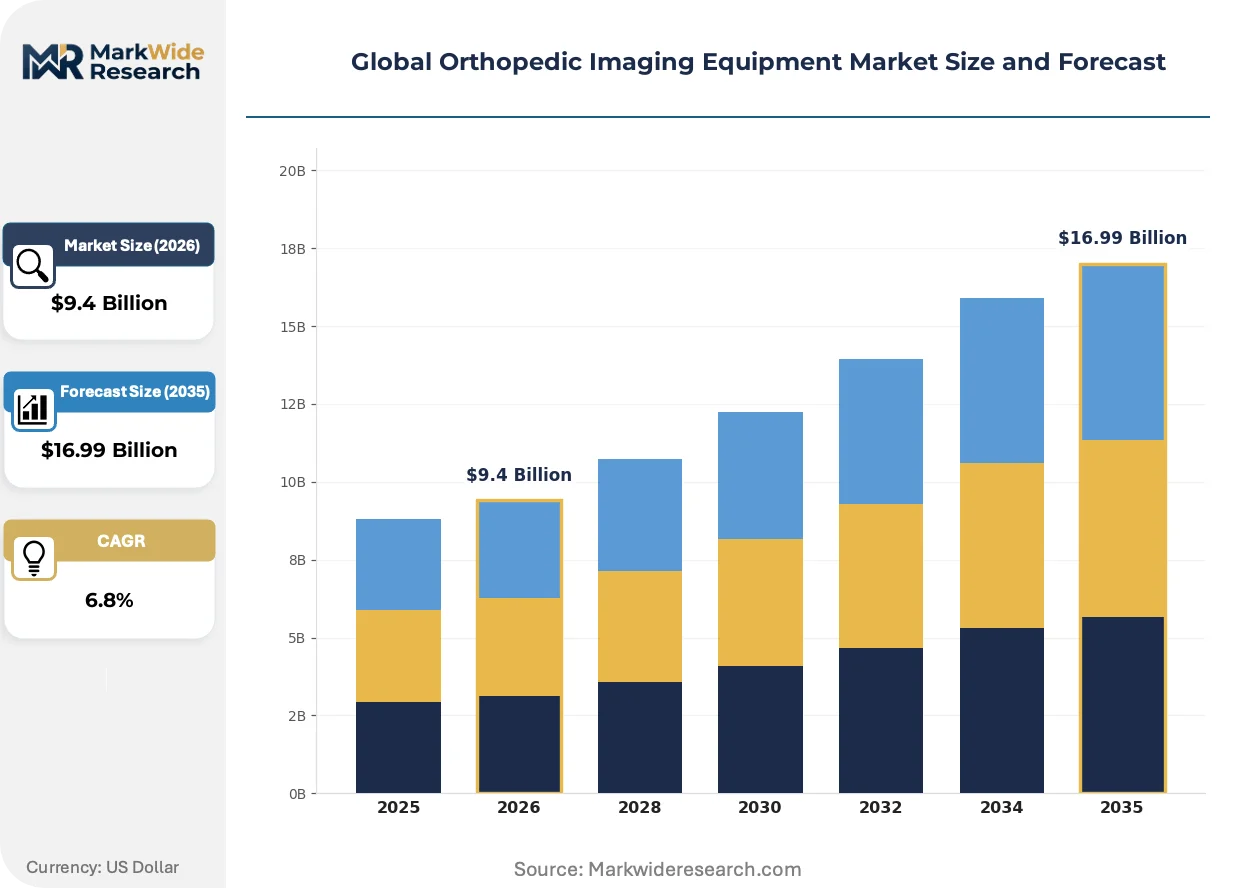
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $16.99 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-Ray Systems, MRI Scanners, CT Scanners, Ultrasound Devices, Fluoroscopy Machines Technology: Digital Radiography, Computed Tomography, Magnetic Resonance Imaging, 3D Imaging, Portable Imaging Application: Spine Imaging, Joint Assessment, Trauma Diagnosis, Bone Density Analysis, Soft Tissue Evaluation End User: Orthopedic Clinics, Diagnostic Centers, Rehabilitation Facilities, Research Institutes, Sports Medicine Centers |
| Companies Covered | Canon Medical Systems, Fujifilm Holdings, Siemens Healthineers, Ziehm Imaging, Orthoscan, GE HealthCare, Hologic, Medtronic, Philips Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Orthopedic Imaging Equipment Market Shifts & Advancements
Orthopedic imaging is experiencing simultaneous pressure from radiation dose reduction mandates, point-of-care decentralization, and software-defined diagnostic workflows that are compressing the traditional radiology department model.
Photon-counting CT detector technology is converging with orthopedic applications to deliver sub-millimeter bone detail at 40% lower radiation exposure than energy-integrating detectors. Academic medical centers in the United States and Germany are piloting these systems for complex fracture classification and post-surgical monitoring. The structural consequence is a narrowing performance gap between CT and MRI for cortical bone assessment, potentially reshaping modality selection protocols.
The EU AI Act's risk classification framework for medical device software is imposing conformity assessment obligations on diagnostic algorithms that were previously deployed under lighter touch oversight. Manufacturers must now maintain post-market performance monitoring systems and algorithm change control protocols. High-risk orthopedic applications including automated fracture detection and implant positioning verification face the steepest compliance ramps.
Subscription-based equipment access models are displacing outright capital purchase arrangements for mid-tier digital radiography systems in United States outpatient networks. Independent orthopedic groups are prioritizing per-scan pricing structures that bundle hardware, software, and maintenance into predictable operational expenditures. This shift is most visible in Texas and Florida metropolitan corridors where private equity-backed practice consolidation is standardizing procurement processes across multi-site networks.
Global Orthopedic Imaging Equipment Market Segmentation
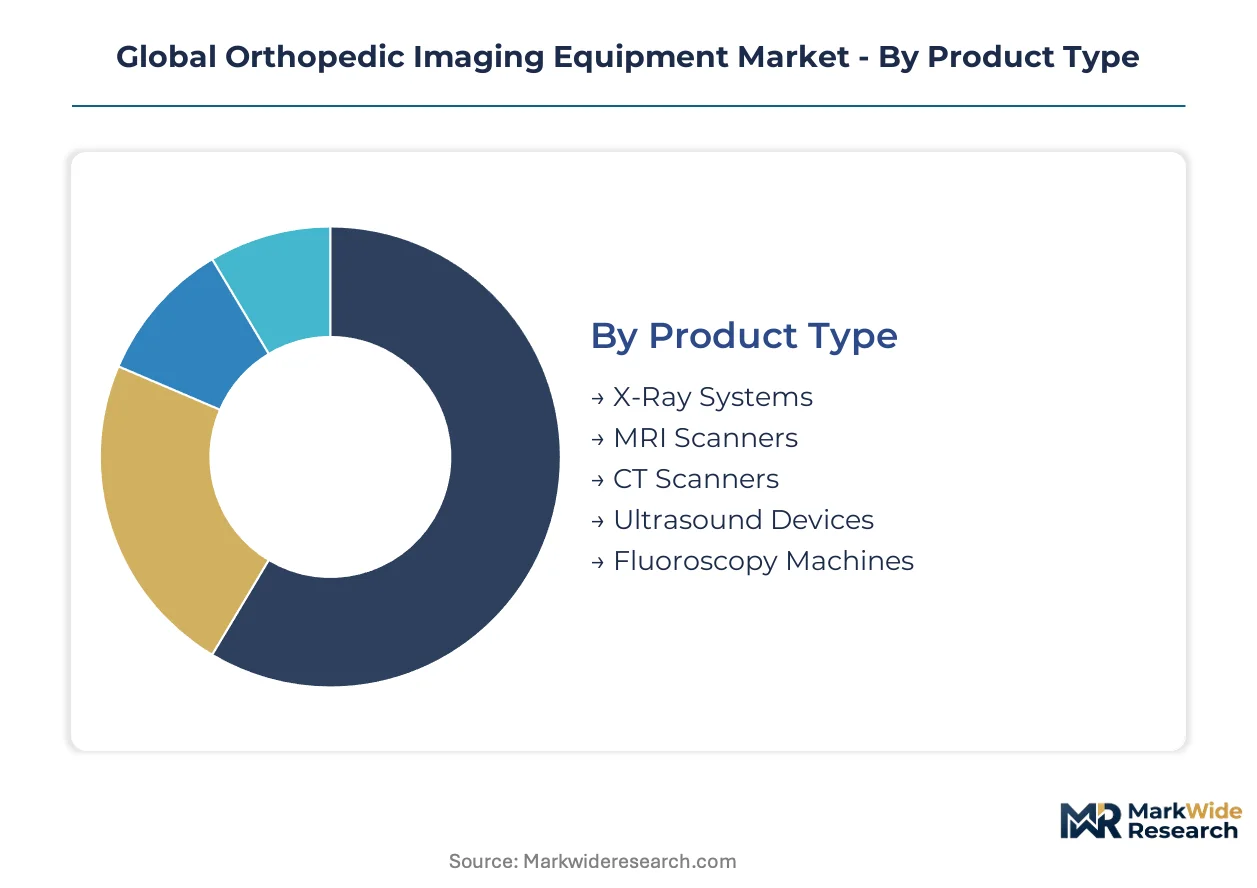
Orthopedic imaging equipment segments diverge sharply between high-throughput workhorse modalities and premium-margin specialized systems. Procurement patterns across hospitals, outpatient clinics, and ASCs fragment demand across four distinct taxonomies: product hardware, underlying technology, clinical application, and care setting.
Product Type:
X-Ray Systems anchor volume throughput across cost-sensitive installations, while MRI Scanners command the steepest pricing premiums in joint and soft-tissue applications.
- X-Ray Systems:Fixed and mobile radiography units utilizing tungsten-target tubes and amorphous silicon flat-panel detectors deliver sub-millimeter spatial resolution for fracture line visualization. Demand concentrates in United States ambulatory surgical centers where faster exam turnaround supports higher patient volumes. The FDA's ALARA dose optimization protocols are accelerating replacement of aging analog and CR systems with DR platforms.
- MRI Scanners:Superconducting 1.5T and 3T systems with dedicated extremity coils enable cartilage, meniscus, and ligament assessment without ionizing radiation. Japan's PMDA oversight of helium supply chain security shapes procurement timelines for magnet maintenance contracts in Tokyo and Osaka hospital clusters. Premium joint assessment applications justify 3-4x capital outlays versus radiography equivalents.
- CT Scanners:Multi-detector row systems with iterative reconstruction algorithms balance bone detail against radiation exposure in trauma settings.
- Ultrasound Devices:Linear and curvilinear transducers with musculoskeletal presets enable dynamic tendon and joint evaluation at point-of-care.
- Fluoroscopy Machines:Mobile C-arm configurations with flat-panel detectors support real-time implant positioning verification during orthopedic procedures.
Today's leader: X-Ray Systems. Tomorrow's challenger: MRI Scanners.
Technology:
Digital detector architectures are displacing analog acquisition across all product categories, while portable form factors capture the steepest expansion trajectory in outpatient migration.
- Digital Radiography:Direct-capture selenium and indirect-capture cesium iodide/amorphous silicon detector stacks eliminate chemical processing and enable immediate image availability. Germany's outpatient orthopedic clinics in Bavaria and North Rhine-Westphalia are standardizing on wireless DR panels for extremity imaging outside radiology department workflows.
- Portable Imaging:Battery-powered mobile X-ray and lightweight extremity MRI systems enable musculoskeletal assessment at bedside, in operating suites, or field-side. United States sports medicine networks in Texas and Florida metropolitan corridors are deploying these units to bypass traditional radiology queues and accelerate return-to-play decisions.
- Computed Tomography:Energy-integrating and emerging photon-counting detector arrays generate isotropic volumetric data for complex fracture classification.
- Magnetic Resonance Imaging:Superconducting and low-field permanent magnet architectures address varying site infrastructure and patient throughput requirements.
- 3D Imaging:Cone-beam CT and tomosynthesis reconstruction algorithms generate depth-resolved views from limited-angle acquisition sequences.
Fixed installations still dominate revenue; mobile platforms are gaining share fastest.
Application:
Joint assessment commands premium equipment allocation, while trauma diagnosis drives highest exam frequency across emergency and urgent care settings.
- Joint Assessment:MRI and weight-bearing CT protocols for knee, hip, and shoulder evaluation require specialized coils and positioning apparatus to visualize articular cartilage, labral structures, and subchondral bone. Japan's concentrated elderly populations in urban corridors sustain demand for high-field systems capable of detecting early osteoarthritic changes before surgical intervention.
- Trauma Diagnosis:Rapid radiography and CT protocols for fracture detection and classification prioritize throughput and radiation efficiency over soft-tissue contrast. United States Level I trauma centers balance speed requirements against dose reduction mandates in polytrauma patient cohorts.
- Spine Imaging:Long-length radiography and dedicated MRI sequences address scoliosis, degenerative disc disease, and post-surgical hardware assessment.
- Bone Density Analysis:Dual-energy X-ray absorptiometry systems quantify mineral content for osteoporosis screening and fracture risk stratification.
- Soft Tissue Evaluation:High-frequency ultrasound and specialized MRI sequences differentiate tendon, ligament, and muscle pathology.
Joint assessment maintains pricing power; trauma work commands installed base scale.
End User:
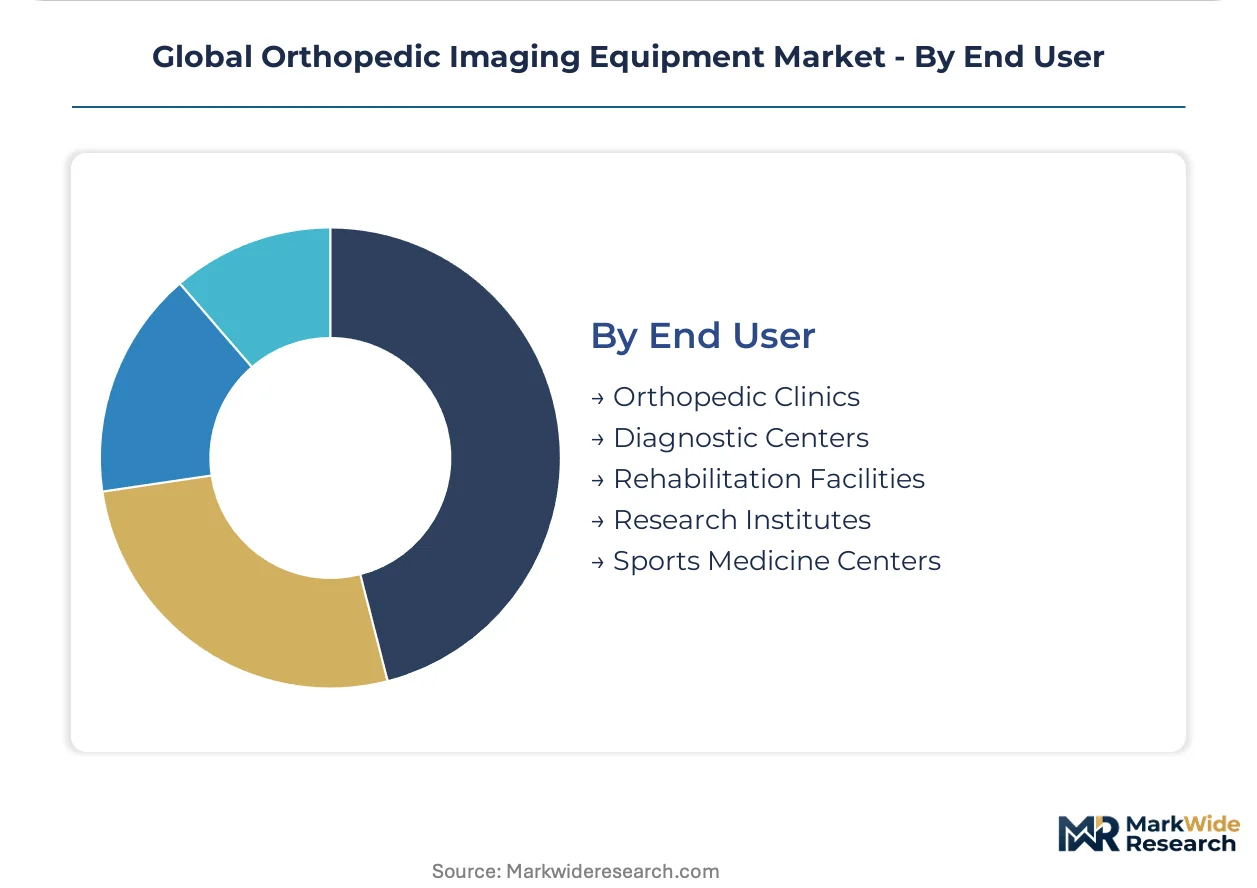
Diagnostic Centers aggregate highest equipment utilization rates, while Orthopedic Clinics are driving the decentralization shift toward point-of-care imaging.
- Orthopedic Clinics:Single and multi-specialty practices are acquiring compact radiography and extremity MRI systems to retain patient flow and revenue within practice walls. United States private equity-backed practice consolidation in Texas and Florida is standardizing equipment specifications across 10-20 site networks to enable centralized reading and quality assurance.
- Diagnostic Centers:Dedicated imaging facilities achieve equipment utilization rates of 12-16 hours daily through centralized scheduling and multi-referral-source aggregation. Germany's outpatient radiology networks leverage this scale to amortize premium CT and MRI capital across broader patient populations.
- Rehabilitation Facilities:Post-acute settings utilize ultrasound and portable radiography to monitor healing progression and guide therapeutic intervention.
- Research Institutes:Academic medical centers deploy preclinical and advanced clinical systems for biomarker development and surgical technique validation.
- Sports Medicine Centers:Dedicated athletic facilities prioritize rapid turnaround imaging for injury assessment and return-to-play clearance.
Diagnostic Centers hold volume concentration; Orthopedic Clinics are capturing the fastest expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized MRI service engineers and radiologic technologists concentrate in Germany, Japan, and the United States, anchoring the highest-value orthopedic imaging procurement corridors worldwide. These talent clusters sustain premium equipment utilization rates that outpace broader regional averages. Regulatory divergence across FDA, EU MDR, and PMDA jurisdictions reshapes manufacturer prioritization and compliance investment.
United States
Ambulatory surgical center expansion in Texas and Florida metropolitan corridors is redirecting capital budgets toward portable digital radiography platforms. The FDA's renewed ALARA dose optimization enforcement accelerates replacement cycles for aging fixed radiography units with dose-efficient detectors. Private equity-backed orthopedic practice consolidation in these states standardizes equipment specifications across 10-20 site networks.
Germany
Outpatient orthopedic clinics in Bavaria and North Rhine-Westphalia are standardizing on wireless DR panels for extremity imaging outside radiology department workflows. The EU MDR's stricter clinical evidence requirements and notified body capacity constraints stretch conformity assessment timelines to 18-24 months for new submissions. Mobile C-arm penetration in these regions enables intraoperative implant verification bypassing traditional radiology queues.
Japan
Concentrated elderly populations in Tokyo and Osaka corridors sustain hospital infrastructure renewal demand for MRI scanners with superior soft-tissue contrast for joint assessment. The PMDA maintains distinct pharmaceutical and medical device agency protocols that create additional localization burdens for foreign manufacturers. Helium supply chain security oversight shapes procurement timelines for superconducting magnet maintenance contracts in these urban clusters.
India
Domestic manufacturing incentives under the PLI scheme are creating localized production pathways for cost-optimized digital radiography units targeting 400+ district hospitals in tier-2 networks. The CDSCO's medical device regulatory framework is evolving toward greater harmonization with international standards while retaining country-specific clinical trial requirements. Maharashtra and Gujarat industrial corridors are capturing assembly investments from multinational manufacturers seeking tariff-advantaged supply positions.
United Kingdom
NHS procurement frameworks for imaging equipment are consolidating purchasing power across integrated care systems, favoring suppliers with established service networks. The Medicines and Healthcare products Regulatory Agency's post-Brexit regulatory autonomy maintains alignment with EU MDR technical standards while streamlining certain conformity assessment pathways. London and Southeast England academic medical centers are piloting photon-counting CT systems for complex fracture classification.
Global Orthopedic Imaging Equipment Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the orthopedic imaging equipment landscape, creating a tiered competitive structure. The market consolidates around established regulatory affairs infrastructure and captive detector manufacturing capabilities. Three archetypes dominate: full-modality conglomerates with backward integration into detector production, software-centric workflow integrators, and portable imaging specialists serving point-of-care decentralization. M&A activity concentrates on AI-assisted diagnostic algorithm developers, while geographic expansion targets India's PLI-advantaged manufacturing zones.
Among diversified imaging conglomerates, Siemens Healthineers and GE HealthCare exemplify the full-modality archetype with established regulatory affairs infrastructure sustaining faster conformity assessment timelines. Philips Healthcare occupies a position emphasizing integrated diagnostic workflow software across imaging modalities. Within the portable imaging specialist tier, Ziehm Imaging and Orthoscan represent focused players capturing ambulatory surgical center expansion demand through battery-powered fluoroscopy configurations.
| Leading Market Players |
|---|
| Canon Medical Systems |
| Fujifilm Holdings |
| Siemens Healthineers |
| Ziehm Imaging |
| Orthoscan |
| GE HealthCare |
| Hologic |
| Medtronic |
| Philips Healthcare |
| Others |
Supply & Pricing Matrix
Performance-tier divergence between photon-counting CT systems and conventional energy-integrating detectors manifests in both capital outlay stratification and captive supply chain configurations, with premium-tier manufacturers anchoring detector fabrication in-house while mid-market players source from East Asian substrate specialists.
Pricing Analysis
Bundled service contracts versus unbundled equipment-only procurement splits the orthopedic imaging market into divergent commercial models. Three-tier pricing structure across premium, standard, and economy levels reflects detector resolution specifications, FDA 510(k) pathway tier, and after-sales service bundling. Cost compression in economy-tier digital radiography intensifies because India's PLI-advantaged manufacturing is flooding tier-2 hospital networks with localized production. Ambulatory surgical centers exhibit highest price sensitivity, while academic medical centers in the United States and Germany demonstrate lowest sensitivity due to grant-funded procurement cycles.
Supply Chain Analysis
Dual-sourcing requirements for amorphous silicon flat-panel detectors are now standard among United States hospital purchasing committees, mandating qualification of at least two substrate suppliers to mitigate single-source vulnerability. Manufacturing concentrates in Japan, South Korea, and Taiwan for detector stack fabrication, while final system assembly feeds from Germany, the United States, and China. Helium supply for MRI superconducting magnets rests on Qatar, the United States, and Algeria extraction. Tariff exposure on Chinese-manufactured components is reshaping procurement timelines. Distribution runs through manufacturer-direct sales forces for premium systems and GPO-aggregated contracts for mid-tier installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The orthopedic imaging market reads as a late-cycle quality story, with demand shifting decisively toward photon-counting CT specifications and AI-integrated diagnostic workflows that command premium positioning.
For Market Incumbents: Extend regulatory affairs capacity to compress EU MDR conformity assessment timelines below competitor averages, and deepen backward integration into detector manufacturing to secure input supply against East Asian substrate concentration. Cone-beam CT substitution in extremity applications threatens conventional CT volume, making certification investment in photon-counting pathways the critical defensive lever. For New Entrants and Emerging Players: Begin with India's tier-2 district hospital network, where PLI scheme incentives and underserved radiology infrastructure create the most penetrable white space. Target cost-optimized digital radiography with wireless DR panels, leveraging domestic assembly partnerships to bypass tariff exposure on complete system imports. A software-first go-to-market angle—bundling AI-assisted fracture detection with hardware—differentiates against established capital-equipment incumbents. For Investors and Strategic Acquirers: Consolidation pressure builds where EU MDR compliance costs exceed 40% of regulatory affairs capacity for mid-cap specialists lacking diversified modality portfolios. Long-term viability favors full-modality conglomerates with captive detector supply and established notified body relationships. Algorithm developers with FDA-cleared orthopedic AI applications represent the priority acquisition archetype. The signal to watch is PMDA helium supply chain security rulings, which would reshape MRI maintenance contract economics and magnet procurement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence requirements compress competitive access for smaller manufacturers. |
| Hospital System Partnership | United States GPO contracts aggregate purchasing power across multi-site orthopedic networks. |
| Software Companion Development | AI-assisted fracture detection algorithms reduce radiologist reading time in PACS integration. |
| Backward Integration | Captive detector manufacturing secures supply against East Asian substrate concentration risk. |
| Reimbursement Strategy | CMS coding alignment for point-of-care imaging accelerates ASC capital budget allocation. |
Research Methodology
Multiple input streams — primary interviews with hospital purchasing committees, biomedical engineers, and GPO contracts managers; secondary validation against FDA 510(k) filings, EU MDR notified body registers, and hospital procurement databases — were reconciled through bottom-up equipment installation tracking and top-down manufacturer revenue triangulation.
Data-stream reconciliation across the projection horizon employed segmentation modeling by product hardware, underlying technology, clinical application, and care setting, with regional regulatory cluster as an additional dimension. CAGRs were derived from installed base replacement cycles and ambulatory surgical center expansion trajectories. Forecast inputs included PMDA helium supply chain security protocols and FDA ALARA enforcement intensity variations.
Several conditions sit outside the modeled scope, including abrupt EU MDR notified body capacity constraints beyond current 18-24 month timelines, and sudden PMDA localization requirements for foreign manufacturers. Forecasts reflect documented assumptions about ASC procedural volume trajectories and detector substrate supply stability. Deviation in FDA radiation dose optimization enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Portable Ultrasound Market
Medical Imaging
France Diagnostic Imaging Equipment Market
Medical Imaging
US Interventional Radiology Market
Medical Imaging
Cardiology PACS Market
Medical Imaging
South Korea Computed Tomography Market
Medical Imaging
Republic of Ireland (ROI) and Northern Ireland MRI and CT Scan Radiology Services Market
Medical Imaging
Medical X-Ray Films Market
Medical Imaging
Medical Image Exchange System Market
Medical Imaging
South Africa Diagnostic Imaging Equipment Market
Medical Imaging
Enterprise Medical Image Viewers Market
Medical Imaging
Japan Mammography Market
Medical Imaging
Global Digital Radiography Market
Medical Imaging
India Diagnostic Imaging Equipment Market
Medical Imaging
Italy Computed Tomography Market
Medical Imaging
US Gadolinium-Based Contrast Media Market
Medical Imaging
Mobile Tomography Market