
 South Africa Diagnostic Imaging Equipment Market | 2026-2036
South Africa Diagnostic Imaging Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Diagnostic Imaging Equipment Market Insights
CE marking equivalency requirements under the South African Health Products Regulatory Authority are pivoting the cost-of-entry calculus for multinational suppliers. GE Healthcare leverages its established Johannesburg service infrastructure to sustain aftermarket revenue streams. Siemens Healthineers anchors its position through direct technical training partnerships with tertiary institutions. Philips competes on digital integration platforms that connect imaging archives across provincial health networks.
Diagnostic imaging equipment encompasses electromagnetic radiation, acoustic wave, or magnetic field-based systems engineered to generate visual representations of internal anatomical structures for clinical diagnosis, with specifications typically spanning 1.5–3 Tesla field strength for MRI and 64–256 slice acquisition for CT platforms. X-ray and ultrasound modalities command the installed base due to lower capital requirements and broader point-of-care deployment, while MRI and CT scanner segments attract concentrated investment from oncology and neurology service lines where reimbursement differentials support longer payback periods. Digital technology is displacing analog architectures across public sector tenders, though hybrid configurations persist in resource-constrained settings where infrastructure reliability varies.
The South African Health Products Regulatory Authority enforces device registration aligned with ISO 13485 quality management systems, while the National Department of Health's Essential Equipment List shapes provincial procurement priorities and technology tiering. The country's national standards body, the South African Bureau of Standards, administers electrical safety and electromagnetic compatibility certifications that filter non-compliant imports from lower-cost manufacturing origins. Stakeholders must monitor NHI procurement centralization timelines and corresponding shifts in maintenance contract structures.
Market Dynamics
The National Health Insurance procurement centralization is restructuring South Africa's diagnostic imaging landscape by consolidating provincial purchasing authority under a single national framework, forcing equipment vendors to recalibrate service contract terms and technical support architectures.
Growth Catalysts
- Oncology service line expansion:Academic medical centers in Gauteng are investing in advanced MRI and CT platforms to support radiation therapy planning and tumor surveillance protocols.
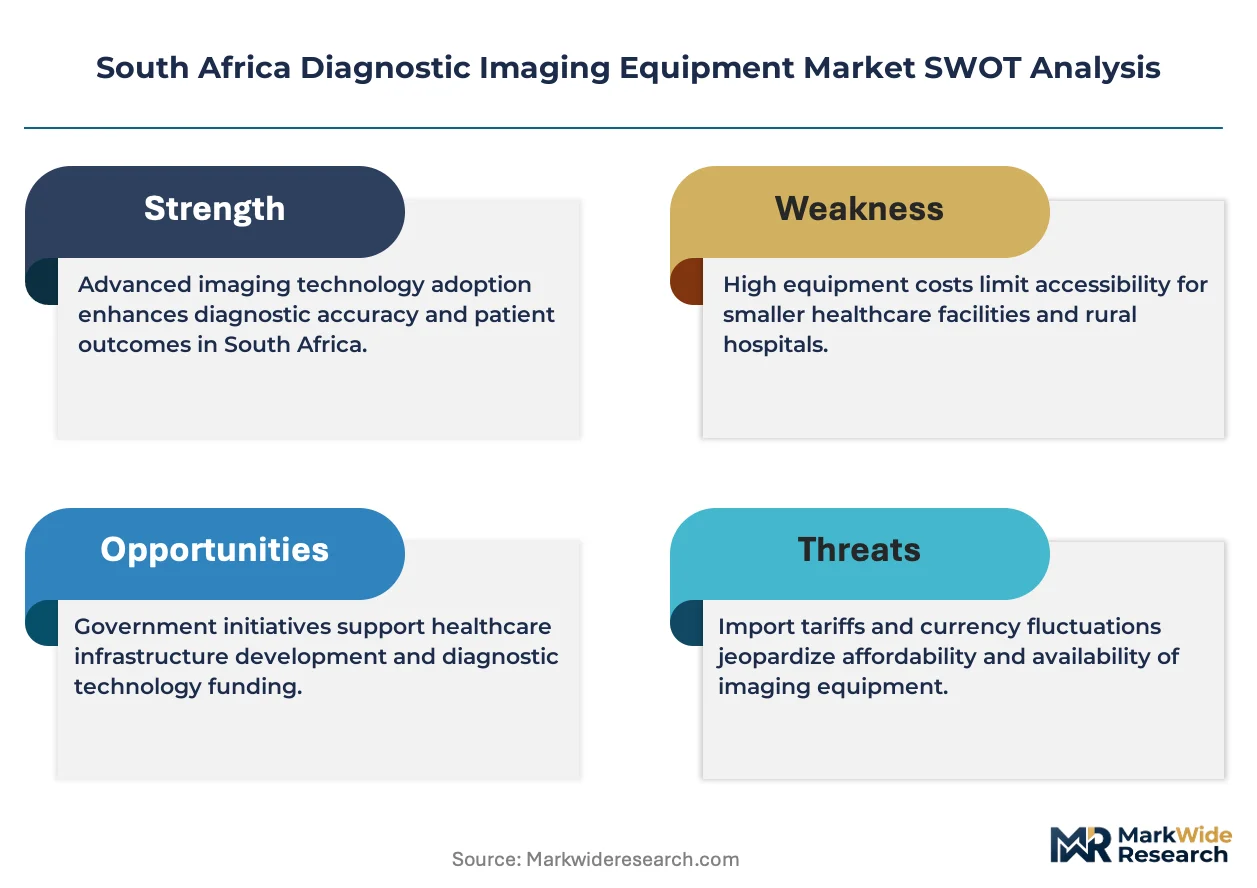
- South African Health Products Regulatory Authority licensing:Elevated compliance thresholds for imported modalities are filtering lower-tier competitors and creating protected market space for established suppliers with Johannesburg-based service infrastructure.
- Digital radiography conversion:Public sector tenders are mandating replacement of analog X-ray systems with detector-based architectures, driving systematic upgrade cycles across provincial hospital networks.
Market Restraints
- Capital intensity barriers:3 Tesla MRI and 256-slice CT platforms require foreign currency denominated procurement, exposing buyers to Rand volatility and extended depreciation schedules.
- Service infrastructure concentration:Technical support capabilities cluster in Johannesburg and Cape Town, creating maintenance access gaps for facilities in Limpopo and Eastern Cape provinces.
- Power grid reliability constraints:Voltage fluctuation in rural districts necessitates costly uninterruptible power supply systems, inflating total cost of ownership for digital imaging installations.
Strategic Opportunities
- Point-of-care ultrasound penetration:Emergency departments and rural clinics in KwaZulu-Natal represent underdeployed demand for compact, battery-operated acoustic imaging systems.
- Artificial intelligence integration:Convergence of deep learning algorithms with PACS archives is enabling automated lesion detection and workflow prioritization in tertiary radiology departments.
- Refurbished equipment channels:Certified pre-owned CT and MRI platforms from European decommissioning programs offer compliance-viable entry points for budget-constrained district hospitals.
Industry Challenges
- Biomedical engineering talent scarcity:Specialized training programs for magnetic resonance coil maintenance and CT detector calibration produce insufficient graduates to match installed base growth.
- Interoperability fragmentation:Legacy DICOM implementations from multiple vendor generations complicate enterprise-wide image archive consolidation under provincial health network mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Diagnostic Imaging Equipment Market |
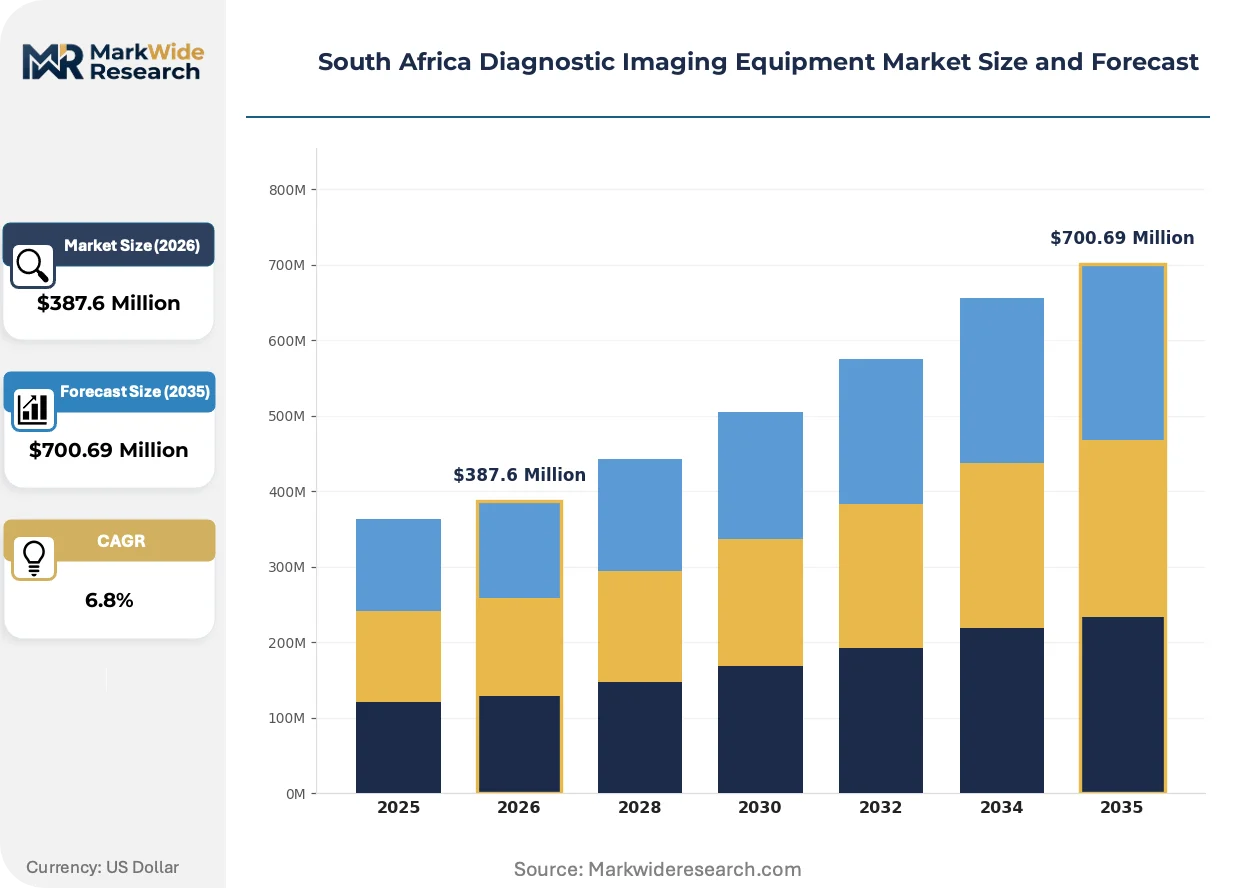
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-Ray, Ultrasound, MRI, CT Scanner End Use: Hospitals, Diagnostic Clinics, Research Labs, Outpatient Facilities Technology: Digital, Analog, Hybrid, Portable Application: Cardiology, Oncology, Orthopedics, Neurology |
| Companies Covered | GE Healthcare, Siemens Healthineers, Koninklijke Philips, Fujifilm Corporation, Carestream Health, Canon Medical Systems, Samsung Electronics, Hologic, Esaote, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Diagnostic Imaging Equipment Market Trends and Innovations
Artificial intelligence deployment is compressing radiologist interpretation cycles while cloud-based image distribution is collapsing geographic barriers between scanning sites and diagnostic expertise.
Vendor-neutral archive technology is unifying imaging data from heterogeneous modalities into single searchable repositories. Academic medical centers in Gauteng and Western Cape are piloting these platforms to enable multi-site tumor board consultations. This unification is eliminating proprietary silos that previously locked facilities into single-supplier upgrade pathways.
South African Health Products Regulatory Authority alignment with ISO 13485 quality management systems is extending device registration timelines for novel modalities. Manufacturers must demonstrate continuous post-market surveillance capabilities, elevating documentation burdens for first-time market entrants. Tertiary institutions with established clinical engineering departments are absorbing these compliance costs more readily than district hospitals.
Consolidated procurement under the National Health Insurance framework is compressing vendor negotiation cycles from multi-year provincial processes to centralized national tenders. Equipment suppliers are responding by pre-negotiating maintenance terms and spare parts availability commitments. This behavioral shift is most visible in Gauteng's academic medical center cluster, where purchasing authority has already migrated to national coordination units.
South Africa Diagnostic Imaging Equipment Market Segmentation
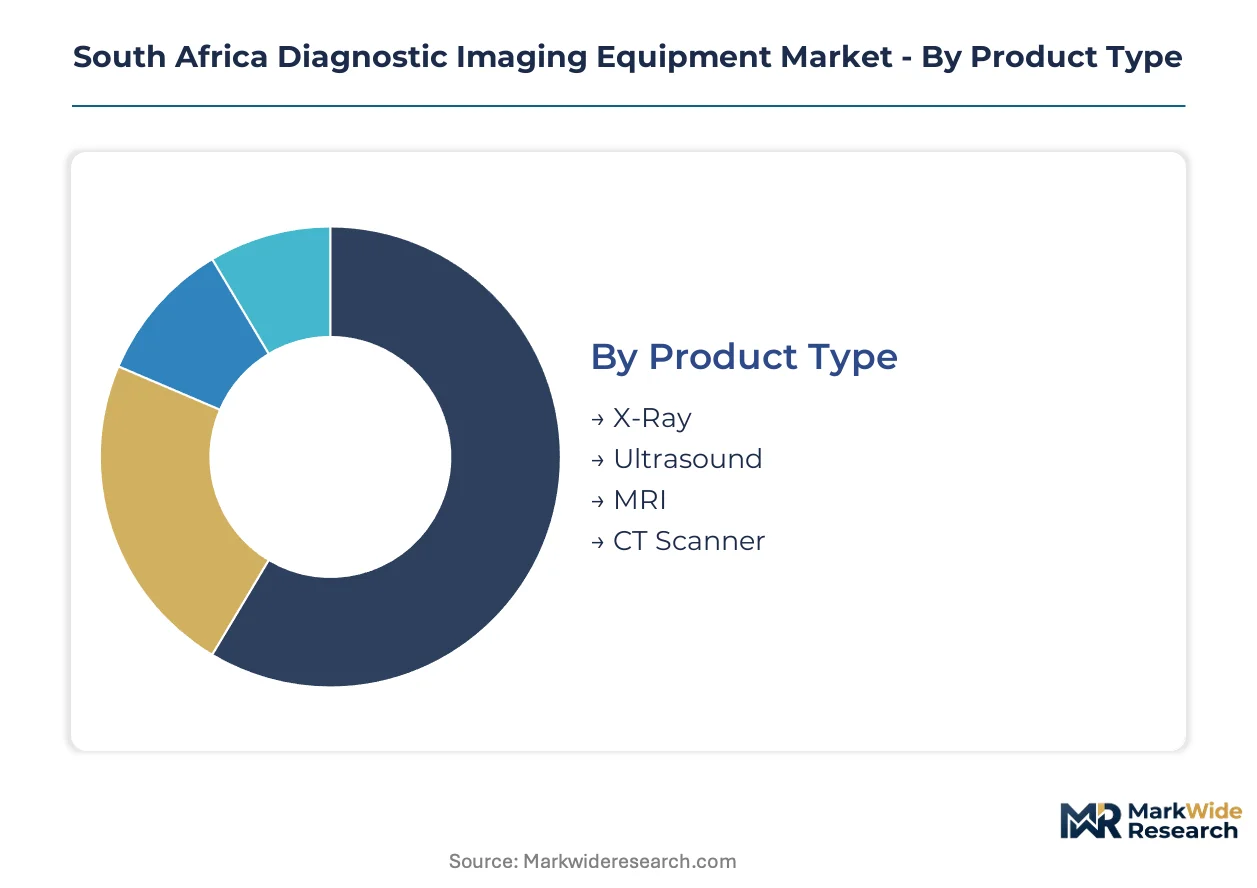
Diagnostic imaging equipment in South Africa fragments across procurement tiers, clinical settings, and infrastructure readiness levels. Each segmentation dimension reveals distinct buyer priorities that shape vendor positioning and service contract structures.
Product Type:
Capital intensity and reimbursement differentials separate buyers into distinct procurement tiers across public and private channels.
- X-Ray:Detector-based digital radiography systems dominate public sector tenders as the National Department of Health mandates analog replacement. District hospitals in Eastern Cape and Limpopo prioritize these platforms for their lower total cost of ownership and reduced power infrastructure demands.
- CT Scanner:64-slice to 256-slice acquisition platforms concentrate demand in Gauteng's academic medical centers where radiation therapy planning and trauma protocols require sub-millimeter spatial resolution. Rand volatility exposes buyers to extended depreciation schedules for imported systems.
- Ultrasound:Compact acoustic imaging systems serve point-of-care deployment in emergency departments and rural clinics.
- MRI:1.5–3 Tesla field strength platforms attract concentrated investment from oncology and neurology service lines.
X-Ray leads volumes today; CT Scanner is gaining share fastest.
End Use:
Procurement authority concentration under the National Health Insurance framework is collapsing previously fragmented buyer decision-making into centralized national tenders.
- Hospitals:Tertiary institutions in Gauteng and Western Cape anchor demand for advanced MRI and CT platforms with integrated PACS archives. These facilities absorb South African Health Products Regulatory Authority compliance costs through established clinical engineering departments.
- Diagnostic Clinics:Private imaging centers in Johannesburg and Cape Town compete on throughput metrics and radiologist availability. Digital radiography and ultrasound modalities dominate their capital allocation due to faster payback periods.
- Outpatient Facilities:Community health centers require compact, reliable platforms with minimal service infrastructure dependence.
- Research Labs:Academic institutions pilot vendor-neutral archive technology and AI-integrated interpretation workflows.
Hospitals lead volumes today; Diagnostic Clinics are expanding most quickly.
Technology:
Infrastructure reliability across South Africa's provinces creates a three-tier technology deployment pattern that vendors must navigate.
- Digital:Detector-based architectures with direct radiography panels and solid-state ultrasound transducers command public sector tenders. The Essential Equipment List prioritizes these platforms for their integration with provincial health network mandates.
- Hybrid:Configurations combining digital acquisition with analog backup systems persist in KwaZulu-Natal and rural districts where voltage fluctuation necessitates operational redundancy.
- Portable:Battery-operated ultrasound and X-ray units target emergency departments and mobile screening programs.
- Analog:Legacy film-based systems remain in limited deployment where digital conversion funding lags.
Digital leads volumes today; Portable is climbing the fastest.
Application:
Clinical service line expansion priorities within academic medical centers concentrate investment in specific diagnostic modalities.
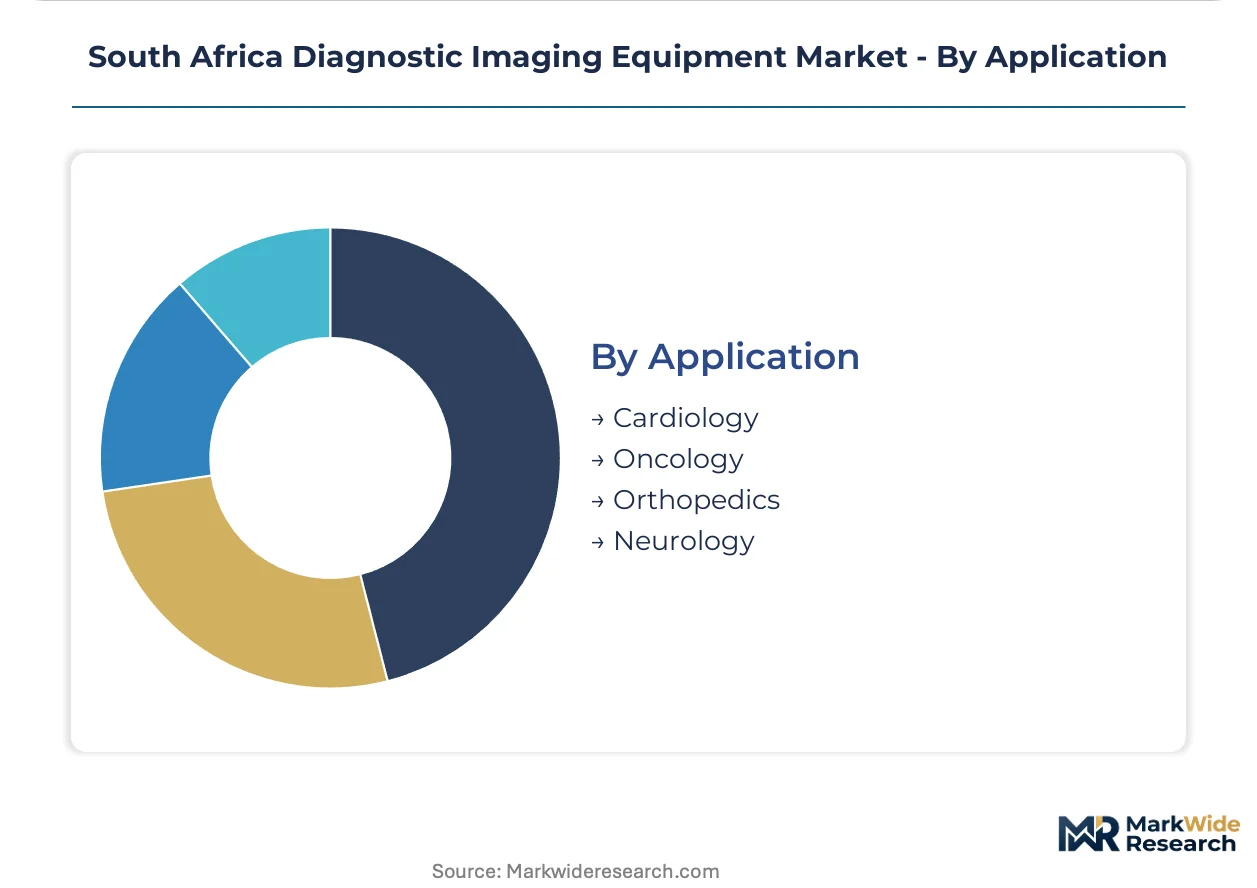
- Oncology:Tumor surveillance protocols and radiation therapy planning drive demand for 3 Tesla MRI and 256-slice CT platforms. Gauteng's academic medical center cluster anchors this segment with dedicated molecular imaging service lines.
- Cardiology:ECG-gated CT angiography and stress echocardiography systems concentrate in private hospital networks with interventional capabilities.
- Neurology:Functional MRI and diffusion tensor imaging protocols require specialized coil configurations and post-processing software.
- Orthopedics:Weight-bearing CT and musculoskeletal ultrasound serve sports medicine and trauma reconstruction programs.
Oncology leads volumes today; Cardiology is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic imaging equipment manufacturing traces its industrial lineage to post-war precision engineering clusters in Germany and the United States, where computed tomography and magnetic resonance platforms first achieved commercial scale during the 1970s and 1980s.
Gauteng Province
The academic medical center cluster in Johannesburg anchors procurement volumes for 3 Tesla MRI and 256-slice CT platforms. South African Health Products Regulatory Authority licensing requirements concentrate compliance expertise in this province. Charlotte Maxeke Johannesburg Academic Hospital and Steve Biko Academic Hospital drive adoption of AI-integrated PACS archives for multi-site tumor board consultations.
Western Cape
Tygerberg Hospital and Groote Schuur Hospital anchor tertiary demand for digital radiography conversion under National Health Insurance procurement timelines. The provincial health department's Essential Equipment List prioritization shapes technology tiering across district facilities. Cape Town's private diagnostic clinic density supports faster payback periods for ultrasound and X-ray modalities.
KwaZulu-Natal
Inkosi Albert Luthuli Central Hospital anchors oncology service line expansion with radiation therapy planning infrastructure. Point-of-care ultrasound penetration lags in rural clinics despite emergency department demand at Addington and King Edward VIII hospitals. Battery-operated portable imaging systems address power grid reliability constraints in uMgungundlovu and Ugu districts.
Eastern Cape
Nelson Mandela Academic Hospital in Mthatha anchors tertiary demand amid service infrastructure concentration gaps. District hospitals prioritize lower total cost of ownership platforms with reduced power infrastructure demands. The province's rural electrification variability sustains hybrid digital-analog configurations in OR Tambo and Alfred Nzo districts.
Limpopo
Polokwane Hospital anchors provincial demand while maintenance access gaps complicate advanced modality deployment. Voltage fluctuation in Vhembe and Mopani districts necessitates uninterruptible power supply investments. Refurbished equipment channels from European decommissioning programs offer compliance-viable entry points for budget-constrained facilities.
South Africa Diagnostic Imaging Equipment Market Competitive Landscape
The competitive structure tilts toward multinational conglomerates with established Johannesburg service infrastructure. Three to five global manufacturers command premium-tier positioning through direct technical training partnerships with tertiary institutions. Mid-tier Asian suppliers compete on detector-based digital radiography platforms for provincial hospital tenders. Dominant competitive moves include pre-negotiated maintenance terms under National Health Insurance centralized procurement and spare parts availability commitments spanning 10-15 year equipment lifecycles.
Among the multinational tier, GE Healthcare leverages its Johannesburg-based service infrastructure to sustain aftermarket revenue streams. Siemens Healthineers anchors its position through direct technical training partnerships with academic medical centers in Gauteng and Western Cape. Philips occupies a position emphasizing digital integration platforms that connect imaging archives across provincial health networks.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Koninklijke Philips |
| Fujifilm Corporation |
| Carestream Health |
| Canon Medical Systems |
| Samsung Electronics |
| Hologic |
| Esaote |
| Others |
Pricing and Supply Chain Analysis
Three-tier pricing stratification across premium, standard, and economy levels manifests in divergent supply chain configurations across South Africa's diagnostic imaging landscape. Premium-tier vendors bundle Johannesburg-based technical support and spare parts availability into long-term contracts, while standard and economy tiers source through refurbished equipment channels with fragmented aftermarket service networks.
Pricing Analysis
Bundled service contracts dominate premium-tier procurement from multinational suppliers with established Johannesburg infrastructure, while unbundled equipment-only pricing characterizes mid-tier Asian manufacturers competing on detector-based digital radiography. Price differentiation hinges on South African Health Products Regulatory Authority certification tier and geographic delivery cost to provinces outside Gauteng. Cost compression in the standard tier is intensifying because provincial hospitals increasingly evaluate total cost of ownership including uninterruptible power supply investments. District facilities in Eastern Cape and Limpopo exhibit highest price sensitivity, whereas academic medical centers in Gauteng prioritize uptime guarantees over capital expenditure minimization.
Supply Chain Analysis
Freight costs from Germany, the Netherlands, and China constitute a material share of landed equipment value for imported MRI and CT platforms. Manufacturing concentration in these jurisdictions creates dependency on specialized superconducting wire, rare earth magnets, and solid-state detector arrays. Single-source vulnerability for helium supply used in MRI magnet cooling exposes buyers to commodity price volatility. Distribution runs through Johannesburg-based warehousing with radiating logistics to Cape Town, Durban, and secondary provincial hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in aftermarket service bundling and refurbished equipment certification, as National Health Insurance procurement centralization compresses upfront equipment margins while elongating maintenance contract durations.
For Market Incumbents: Deploy pre-negotiated maintenance terms as the primary defensive lever against mid-tier Asian entrants undercutting on capital equipment pricing. Deepen spare parts inventory positioning in Cape Town to close service infrastructure gaps threatening Eastern Cape and Limpopo accounts. Anchor capacity in Johannesburg-based clinical engineering training partnerships to lock in tertiary institution loyalty against Siemens Healthineers and Philips. For New Entrants and Emerging Players: South African Health Products Regulatory Authority alignment with ISO 13485 quality management systems opens a window for refurbished equipment channels from European decommissioning programs. Target district hospitals in KwaZulu-Natal and Eastern Cape with certified pre-owned CT platforms offering compliance-viable total cost of ownership. Pursue direct technical training partnerships with biomedical engineering programs at Walter Sisulu University and University of KwaZulu-Natal to circumvent incumbent service infrastructure advantages. For Investors and Strategic Acquirers: Asymmetric upside sits with service infrastructure operators capable of consolidating fragmented aftermarket maintenance across provincial health networks. Long-term viability favors acquisition targets with established Johannesburg-based spare parts logistics and clinical engineering training capabilities. Watch National Health Insurance procurement centralization timelines as inflection indicator for maintenance contract structure shifts from provincial to national negotiation frameworks.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Locks in multi-site maintenance contracts under National Health Insurance centralized procurement timelines. |
| CE Marking Pathway | Accelerates South African Health Products Regulatory Authority device registration through established quality management equivalency. |
| Software Companion Development | Enables AI-integrated PACS archive differentiation for multi-site tumor board consultations in Gauteng academic centers. |
| Reimbursement Strategy | Aligns oncology service line expansion with National Department of Health Essential Equipment List prioritization. |
| Backward Integration into Refurbishment | Captures margin from European decommissioning programs serving budget-constrained Eastern Cape district hospitals. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital procurement managers, biomedical engineers, GPO contracts managers, and clinical radiologists with secondary validation against hospital procurement databases, South African Health Products Regulatory Authority device registration filings, and National Department of Health tender documentation. Bottom-up installed base modeling and top-down expenditure flow analysis were triangulated to anchor market sizing.
Comparable-period anchoring linked historical provincial procurement patterns to projected National Health Insurance centralization timelines across the analysis window. Segmentation dimensions modeled include product type, end-use setting, technology tier, and clinical application. CAGRs were derived from equipment replacement cycle analysis and public sector budget allocation trajectories, incorporating Rand volatility exposure and infrastructure readiness indices as industry-specific forecast inputs.
Revisions become necessary when National Health Insurance implementation timelines shift, South African Health Products Regulatory Authority licensing requirements tighten, or provincial electrification reliability diverges from baseline assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Industrial Radiography Market
Medical Imaging
Open Magnetic Resonance Imaging System Market
Medical Imaging
France Digital X-Ray Devices Market
Medical Imaging
X-Ray Film Market
Medical Imaging
Latin America Medical Imaging Software Market
Medical Imaging
Global Dental Panoramic Radiography Market
Medical Imaging
China Digital X-Ray Market
Medical Imaging
South America CT Market
Medical Imaging
Magnetoencephalography (MEG) Market
Medical Imaging
Diagnostic Imaging Markers Market
Medical Imaging
Gallium-68 Market
Medical Imaging
Asia-Pacific Digital Radiology Market
Medical Imaging
Global Spectral Computed Tomography (CT) Market
Medical Imaging
Europe Mobile Tomography Market
Medical Imaging
Fluoroscopy C-Arms Market
Medical Imaging
United Kingdom Magnetic Resonance Imaging Market