
 BRICS Oral Care Market | 2026-2036
BRICS Oral Care Market Size, Share, and Industry Trends Forecast 2026-2036
BRICS Oral Care Market Analysis
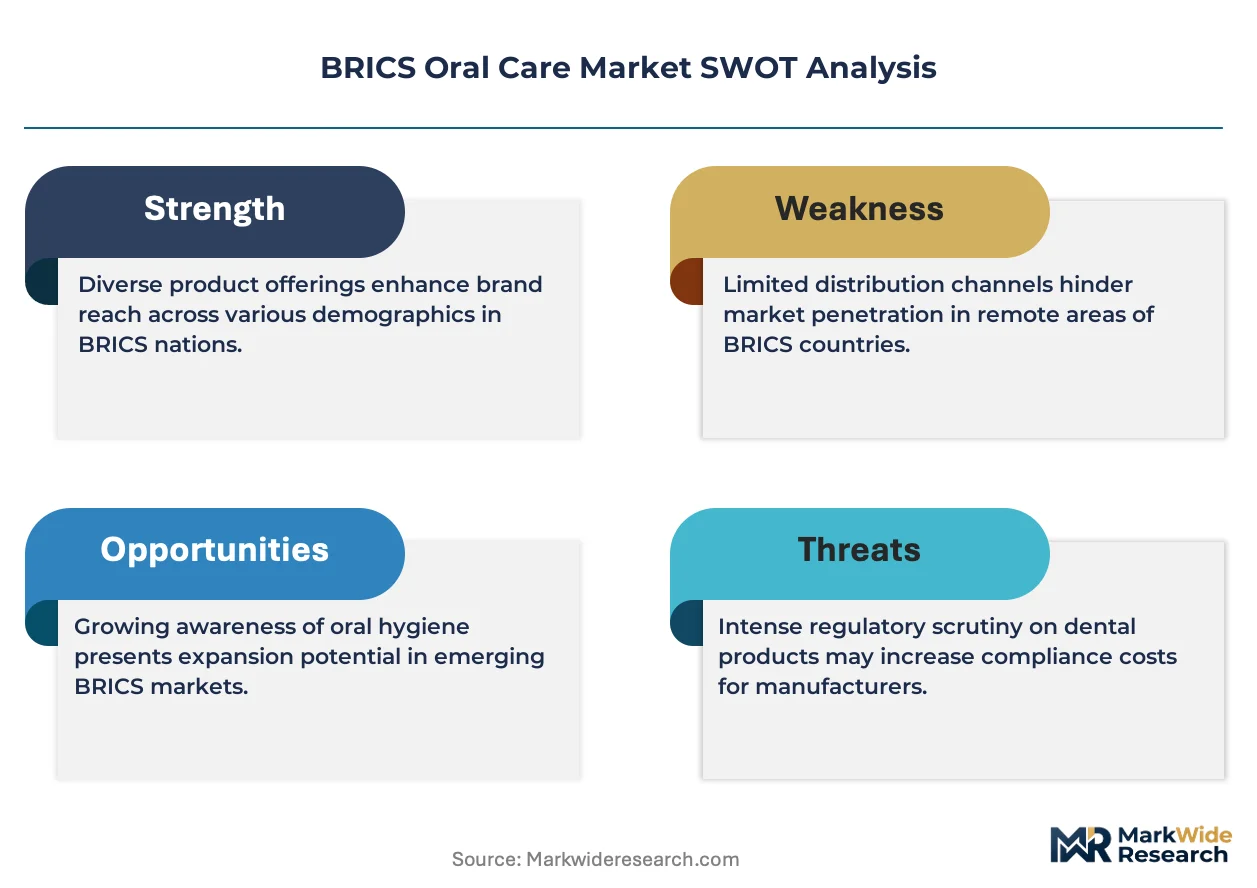
India's BIS certification requirements for oral hygiene products is consolidating quality benchmarks across domestic manufacturing. Colgate-Palmolive leverages its extensive distribution infrastructure to sustain shelf dominance in both urban and rural outlets. Hindustan Unilever anchors premium positioning through specialized Ayurveda-inspired formulations tailored to regional preferences. Procter & Gamble differentiates via technology leadership in electric oral care devices through its global innovation pipeline.
BRICS oral care encompasses toothpaste, mouthwash, dental floss, and whitening products formulated for preventive hygiene and aesthetic dental maintenance. These products typically incorporate fluoride compounds at 1000-1500 ppm, antibacterial agents such as cetylpyridinium chloride, and abrasive silica systems engineered for enamel-safe stain removal. Toothpaste dominates value generation across the BRICS bloc due to universal daily-use frequency and established brand loyalty. E-commerce represents the fastest-expanding distribution channel as platform logistics penetrate secondary cities and price comparison drives trial switching. Dental clinics emerge as a concentrated margin pool where professional-grade recommendations convert to premium product purchases.
China's SAMR enforces GB standards governing toothpaste ingredient safety and labeling claims, while India's BIS mandates product quality certification for domestic manufacture and import. Brazil's ANVISA regulates oral antiseptic classifications, creating compliance complexity for multinational mouthwash portfolios. Russia's technical regulations on cosmetic-hygiene products require state registration, extending market access timelines for new entrants. Stakeholders must monitor evolving national standards divergence versus harmonization pressures as BRICS trade frameworks deepen cross-border product circulation.
Market Dynamics
India's BIS quality mandates and China's GB standards for toothpaste ingredients are forcing formulation reformulations across multinational portfolios, compressing product development cycles while elevating compliance costs for market access.
Growth Catalysts
- Urban Tier-2/3 Penetration:Organized retail expansion in India's secondary cities accelerates branded oral care shelf presence among first-time category upgraders.
- BIS Certification Mandate:India's compulsory quality standards for oral hygiene products consolidate domestic manufacturing capabilities and filter substandard imports.
- Electric Device Adoption:Rechargeable sonic brushing systems gain traction among China's middle-class households seeking preventive dental maintenance solutions.
Market Restraints
- Fluoride Input Volatility:Sodium fluoride and sodium monofluorophosphate supply concentrates in Chinese chemical processing clusters, exposing margins to export duty fluctuations.
- State Registration Timelines:Russia's technical regulations on cosmetic-hygiene products require extended documentation periods, delaying new entrant commercialization by 12-18 months.
- Natural Substitute Preference:Charcoal-based and neem-derived traditional formulations in South African informal retail capture price-sensitive consumers outside branded channels.
Strategic Opportunities
- Brazil's ANVISA Reclassification:Regulatory clarity on oral antiseptic therapeutic claims creates pathway for premium mouthwash portfolio expansion with professional endorsement leverage.
- Dental Clinic Channel Development:Professional recommendation-driven dispensing in Brazil and China captures high-margin patient compliance purchases.
- Ayurveda-Inspired Positioning:Herbal-active formulations aligned with India's traditional medicine preferences unlock differentiated pricing in domestic and diaspora markets.
Industry Challenges
- Formulation Chemist Scarcity:Qualified professionals capable of bridging traditional herbal knowledge with modern fluoride stabilization protocols remain concentrated in Mumbai and Bangalore.
- Multi-Jurisdiction Labeling Complexity:Divergent GB standard claims in China versus BIS disclosure requirements in India force SKU proliferation and inventory segmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | BRICS Oral Care Market |
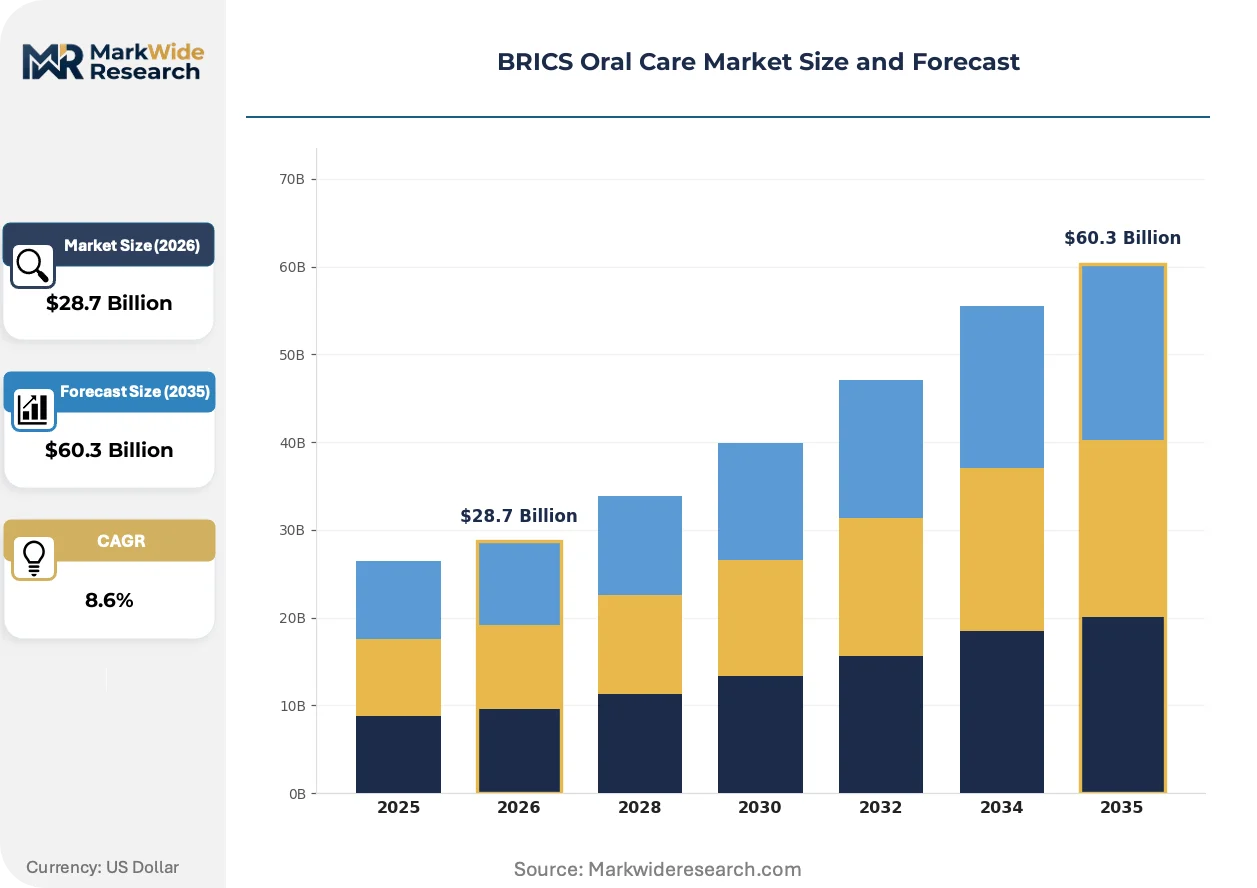
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $60.3 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Toothpaste, Mouthwash, Dental Floss, Whitening Products End User: Adults, Children, Seniors, Dental Clinics Distribution Channel: Retail Stores, E-commerce, Pharmacies, Supermarkets Price Tier: Premium, Mid-range, Economy, Budget |
| Companies Covered | Unilever, Hindustan Unilever, Colgate-Palmolive, Koninklijke Philips, Dabur India, Procter & Gamble, GlaxoSmithKline, Lion Corporation, Johnson & Johnson, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
BRICS Oral Care Market Emerging Trajectories
Smart connectivity and professional-channel integration are compressing the boundary between consumer oral care and clinical preventive dentistry across BRICS markets.
Enamel-safe abrasive silica systems with engineered particle size distribution is rewriting stain removal efficacy benchmarks. China's premium urban consumers adopt these formulations at three times the rate of standard calcium carbonate alternatives. The technology is rewriting competitive positioning by forcing legacy chalk-based manufacturers into accelerated R&D catch-up cycles.
China's SAMR enforcement of GB standards governing toothpaste ingredient safety and labeling claims tightens permissible therapeutic language. Multinational portfolios face reformulation costs or market withdrawal for non-compliant SKUs. Professional whitening lines and sensitivity-repair variants bear the heaviest compliance burden as clinical-adjacent claims attract regulatory scrutiny.
Subscription-based replenishment models displace traditional retail stocking patterns among Brazil's São Paulo and Rio de Janeiro metropolitan consumers. Platform algorithms curate personalized paste and rinse combinations based on dental scan data from partner clinic networks. This channel migration is most visible in China's tier-1 cities where platform logistics infrastructure enables same-day delivery of customized oral care kits.
BRICS Oral Care Market Segmentation
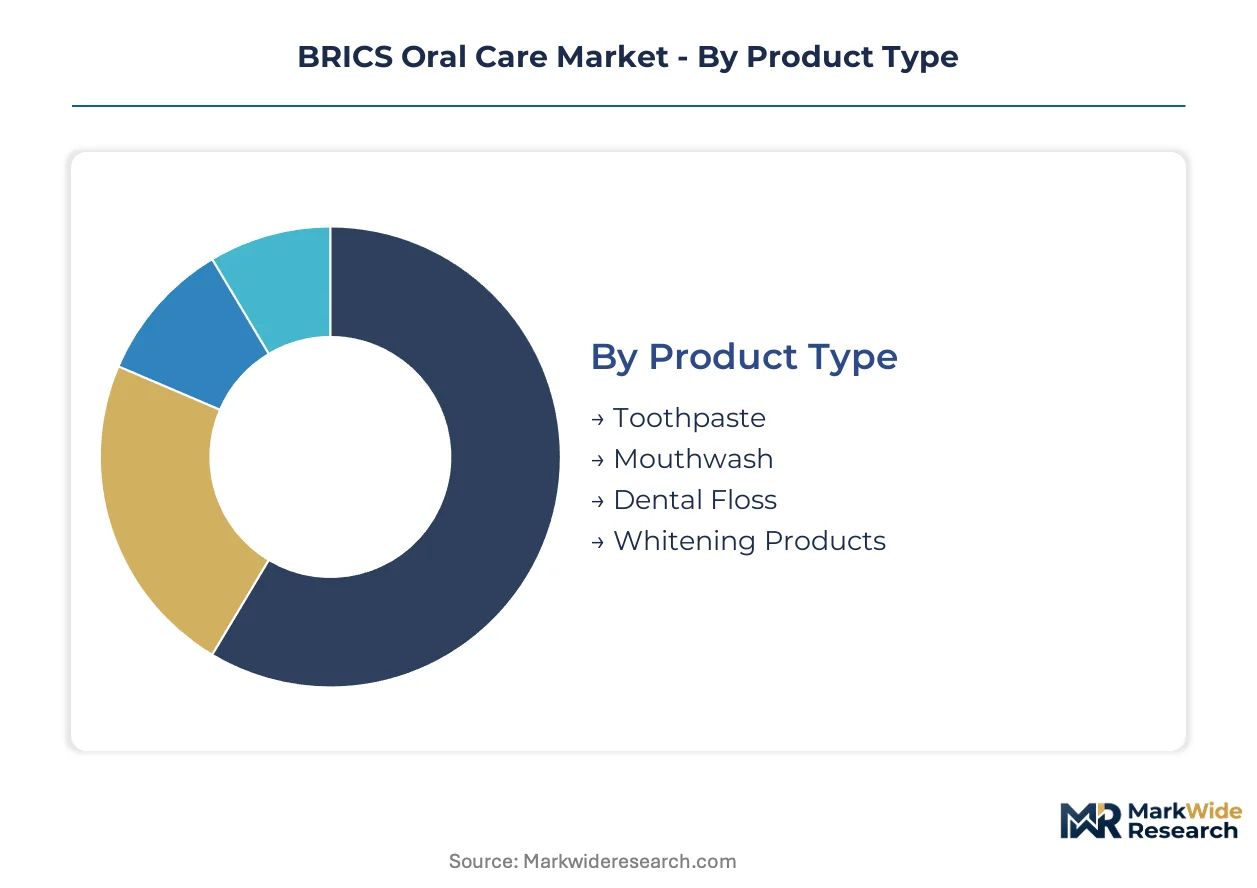
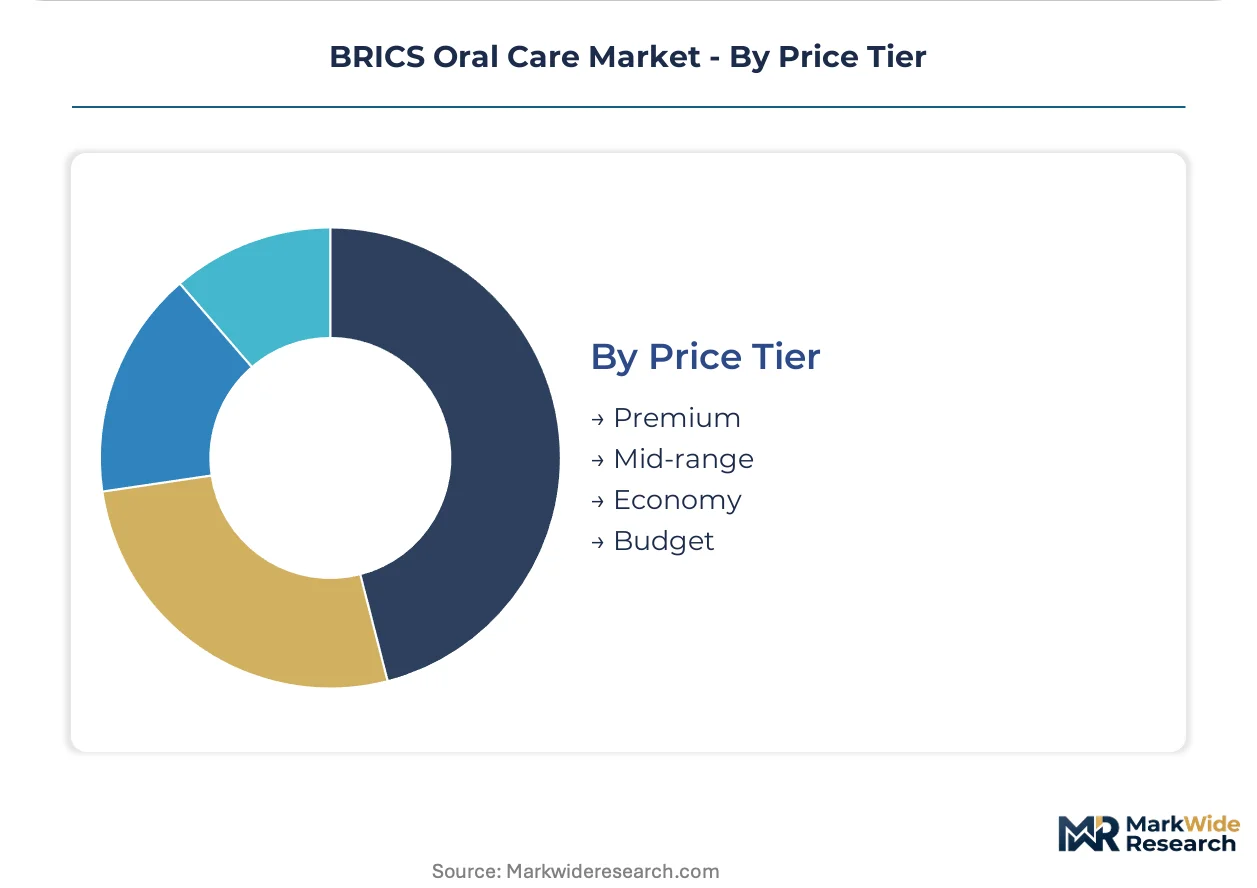
BRICS oral care segmentation reveals distinct consumption patterns across product categories, with formulation chemistry and channel access determining buyer conversion. Price tier stratification in India and Brazil creates parallel market structures where premium fluoride systems and economy herbal variants coexist without direct competition.
Product Type:
Formulation chemistry and daily-use frequency separate buyers into prevention-focused versus aesthetic-motivated segments.
- Toothpaste:Fluoride-stabilized pastes incorporating 1000-1500 ppm sodium fluoride or sodium monofluorophosphate dominate preventive routines. China's tier-1 cities concentrate demand for enamel-safe silica abrasives, while India's tier-2/3 expansion drives standard calcium carbonate volumes.
- Mouthwash:Cetylpyridinium chloride and essential oil formulations target interdental hygiene gaps left by mechanical cleaning. Brazil's ANVISA therapeutic claim reclassification is accelerating professional-channel dispensing in São Paulo dental clinics.
- Dental Floss:Waxed nylon and PTFE monofilament systems address interproximal plaque removal. South Africa's organized retail penetration lags other BRICS markets for this segment.
- Whitening Products:Peroxide-based gels and abrasive polishing systems target extrinsic stain removal. Regulatory scrutiny under China's GB standards restricts clinical-adjacent therapeutic positioning.
Toothpaste leads volumes today; whitening products are gaining share fastest.
End User:
Age-linked dental condition prevalence and recommendation authority shape product selection criteria across buyer groups.
- Adults:Working-age consumers with disposable income drive premium fluoride and sensitivity-repair adoption. India's urban middle-class expansion concentrates demand in 25-45 age brackets seeking preventive maintenance solutions.
- Children:Flavor-optimized low-fluoride formulations address early habit formation. China's one-child policy legacy elevates per-capita parental spending on pediatric oral care relative to other BRICS markets.
- Seniors:Xerostomia and periodontal condition management requirements drive specialized rinse and denture care demand. Russia's aging demographic profile concentrates this segment in Moscow and St. Petersburg.
- Dental Clinics:Professional recommendation authority converts patient compliance into high-margin dispensing. Brazil's clinic network expansion and China's tier-1 private dentistry growth accelerate this channel.
Adult end users anchor revenue today; dental clinics are expanding most quickly.
Distribution Channel:
Logistics infrastructure maturity and price transparency mechanisms determine channel preference by geography and tier.
- Retail Stores:Kirana networks and independent pharmacies sustain reach in India's rural hinterlands where platform penetration remains incomplete. Colgate-Palmolive and Hindustan Unilever leverage decades of distributor relationships for shelf dominance.
- E-commerce:Platform algorithms and subscription replenishment displace traditional stocking in China's tier-1 cities and Brazil's metropolitan cores. Same-day delivery infrastructure enables trial-size sampling that reduces switching costs.
- Pharmacies:Pharmacist endorsement credibility supports therapeutic-positioned mouthwash and sensitivity product sales. Russia's regulatory environment channels professional-grade formulations through this controlled access point.
- Supermarkets:Organized retail expansion in India's tier-2/3 cities accelerates branded oral care access among first-time category upgraders. Private label penetration remains limited by BIS certification requirements.
Retail stores maintain volume leadership today; e-commerce is climbing the fastest.
Price Tier:
Income stratification and certification grade separate buyers into parallel consumption bands with minimal cross-tier migration.
- Premium:Enamel-safe silica systems, electric device compatibility, and professional endorsement leverage command 3-4x economy pricing. China's SAMR-compliant therapeutic claims and India's BIS-certified manufacturing anchor this tier.
- Mid-range:Standard fluoride pastes with brand heritage positioning capture India's urban middle-class and Brazil's aspiring consumers. Ayurveda-inspired herbal-actives from Hindustan Unilever concentrate in this band.
- Economy:Calcium carbonate-based formulations with basic cavity prevention claims serve price-sensitive volume demand. South Africa's informal retail channels and Russia's regional cities sustain this tier.
- Budget:Unbranded or private label products with minimal fluoride content operate at margin-minimum price points. Quality variance risks under China's GB enforcement and India's BIS mandate are compressing this segment's legal market access.
Mid-range pricing holds volume dominance today; premium tier is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Modern oral care manufacturing traces its industrial lineage to mid-20th century multinational expansion into emerging markets, with BRICS nations subsequently developing distinct regulatory and consumption ecosystems that now shape regional competitive dynamics.
Brazil
Metropolitan São Paulo and Rio de Janeiro drive premium mouthwash adoption through dental clinic channel expansion. ANVISA's therapeutic claim reclassification for oral antiseptics creates regulatory clarity for professional-grade portfolio positioning. The Southeast industrial corridor concentrates formulation manufacturing serving Mercosur distribution networks.
Russia
Moscow and St. Petersburg concentrate senior-focused denture care and xerostomia management demand amid aging demographic profiles. State registration requirements for cosmetic-hygiene products under technical regulations extend new entrant market access timelines. The Central Federal District anchors import-dependent supply chains for fluoride active ingredients.
India
Tier-2 and tier-3 urban centers accelerate branded oral care penetration through organized retail expansion. BIS compulsory quality certification for oral hygiene products filters substandard domestic manufacture and imports. Mumbai and Bangalore concentrate scarce formulation chemistry talent bridging herbal knowledge with fluoride stabilization protocols.
China
Tier-1 cities adopt enamel-safe silica abrasive systems at multiples of standard calcium carbonate rates. SAMR enforcement of GB standards governing toothpaste ingredient safety and labeling claims tightens therapeutic claim permissibility. The Yangtze River Delta cluster dominates sodium fluoride and sodium monofluorophosphate chemical processing.
South Africa
Informal retail channels sustain charcoal-based and neem-derived traditional formulation demand among price-sensitive consumers. Quality variance risks under import standards compress budget-tier legal market access. Gauteng province concentrates organized retail distribution infrastructure serving secondary city expansion.
BRICS Oral Care Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification-grade and distribution-depth dimensions. The market structure consolidates around heritage multinationals with decades-long distributor relationships and domestic champions leveraging Ayurveda-inspired positioning. Three archetypes dominate: global FMCG conglomerates with full-category portfolios, regional herbal-specialist manufacturers, and technology-driven device specialists. Competitive moves concentrate on dental clinic channel development and e-commerce platform partnership formation.
Among global FMCG conglomerates, Colgate-Palmolive, Hindustan Unilever, and Procter & Gamble exemplify distinct strategic positioning archetypes. Colgate-Palmolive occupies the heritage-distribution anchor position leveraging extensive rural and urban shelf presence. Hindustan Unilever represents the regional-preference adaptation specialist through Ayurveda-inspired formulation development. Procter & Gamble sits within the technology-transfer tier importing electric device innovation through global pipeline access.
| Leading Market Players |
|---|
| Unilever |
| Hindustan Unilever |
| Colgate-Palmolive |
| Koninklijke Philips |
| Dabur India |
| Procter & Gamble |
| GlaxoSmithKline |
| Lion Corporation |
| Johnson & Johnson |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between BIS-certified and uncertified oral hygiene products drives parallel pricing and procurement configurations across BRICS markets. India's compulsory quality mandates and China's GB enforcement create tiered supply access where certified manufacturers command 3-4x pricing multiples over informal channels, while fluoride active ingredient sourcing concentrates in chemical processing clusters that amplify input cost volatility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates BRICS oral care, with enamel-safe silica abrasives and electric device compatibility anchoring premium positioning. Price differentiation rests on BIS certification grade and SAMR therapeutic claim compliance, with China's tier-1 urban buyers showing lowest price sensitivity. Cost compression in economy calcium carbonate tiers intensifies because of sodium fluoride supply concentration and export duty exposure.
Supply Chain Analysis
Single-source vulnerability sits with China's Yangtze River Delta cluster for sodium fluoride and sodium monofluorophosphate active ingredients. Raw material dependencies span fluoride compounds from Chinese chemical processors, silica abrasives from specialized mineral suppliers, and essential oils for mouthwash formulations. Tariff exposure on fluoride exports from China amplifies margin risk for Indian and Brazilian formulators. Distribution runs through organized retail expansion in India's tier-2/3 cities and platform logistics in China's metropolitan cores.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
BRICS oral care represents a late-cycle quality story as middle-class consumption shifts toward BIS-certified and SAMR-compliant premium formulations with professional endorsement leverage.
For Market Incumbents: Deploy dental clinic channel control to capture high-margin patient compliance purchases in São Paulo and tier-1 Chinese cities. Consolidate shelf presence through distributor relationship deepening in India's expanding organized retail footprint. Counter Ayurveda-inspired regional specialists by accelerating enamel-safe silica R&D catch-up cycles. For New Entrants and Emerging Players: The premium-economy price-point gap in South Africa's informal retail channels opens white-space entry for charcoal-based and neem-derived formulations with quality certification pathway development. Target Russia's senior-focused denture care segment where state registration timelines have filtered multinational competition. Pursue pharmacist endorsement credibility as the primary go-to-market angle for therapeutic-positioned mouthwash launches. For Investors and Strategic Acquirers: Consolidation pressure builds where formulation chemistry talent scarcity in Mumbai and Bangalore constrains domestic herbal-specialist scaling. Long-term viability favors acquiring regional Ayurveda-inspired manufacturers with BIS certification infrastructure and diaspora market access. Watch dental clinic dispensing volume trends in Brazil and China as the inflection signal for premium channel migration acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| BIS Certification Investment | Quality mandate compliance filters substandard competitors from India's domestic manufacture and import channels. |
| Dental Clinic Channel Expansion | Professional recommendation authority in São Paulo and tier-1 Chinese cities converts patient compliance to premium purchases. |
| Ayurveda-Inspired Brand Extension | Herbal-active formulations aligned with traditional medicine preferences unlock differentiated pricing in domestic and diaspora markets. |
| E-commerce Platform Partnership | Subscription replenishment algorithms displace traditional retail stocking in Brazil's metropolitan cores and China's tier-1 cities. |
| Enamel-Safe Silica R&D Scale-Up | Engineered particle size distribution systems rewrite stain removal efficacy benchmarks against legacy chalk-based competitors. |
Methodological Framework
Coverage spans Brazil, Russia, India, China, and South Africa, with primary inputs from each market's regulatory and commercial stakeholders. The analysis combines interviews with brand managers, category buyers at organized retailers, channel sales heads, and formulation chemistry specialists with secondary validation from BIS certification databases, ANVISA regulatory filings, SAMR GB standard enforcement records, and customs trade data. Bottom-up and top-down triangulation cross-validates volume estimates against retail audit patterns and production capacity disclosures.
Rate-of-change decomposition across the analysis window segments modeled dimensions by product type, end user age bracket, distribution channel logistics maturity, and price tier certification grade. CAGRs derive from trend extrapolation adjusted for regulatory enforcement intensity and middle-class consumption elasticity. Forecast inputs incorporate electric device adoption curves in China's tier-1 cities and organized retail penetration rates in India's secondary urban centers.
Caveats apply where BIS certification timeline acceleration or SAMR therapeutic claim reinterpretation could materially shift the outlook. Forecasts reflect assumptions about fluoride input price stability and dental clinic network expansion pacing. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oral Care
Chemotherapy-Induced Oral Mucositis Market
Oral Care
Kids Oral Care Products Market
Oral Care
Oral Antiseptics Market
Oral Care
Asia-Pacific Oral Care Market
Oral Care
Xerostomia Treatment Market
Oral Care
Ayurvedic Toothpaste Market
Oral Care
Baby Oral Care Market
Oral Care
Europe Oral Hygiene Market
Oral Care
Oral Thrush Treatment Market
Oral Care
Global Interdental Cleaning Products Market
Oral Care
Halitosis Treatment Market
Oral Care
Baby Teeth Care Products Market
Oral Care
Oral Thin Films Market
Oral Care
Mouthwash Market
Oral Care
Oral Health Ingredient Market
Oral Care
Mouth Sore Medicine Market