
 Oral Health Ingredient Market | 2026-2036
Oral Health Ingredient Market Size, Share, and Industry Trends Forecast 2026-2036
Oral Health Ingredient Market Analytics
Pharmaceutical-grade fluoride specifications are reorganizing procurement priorities across oral care supply chains. Procter & Gamble leverages its captive sodium fluoride production to secure formulation consistency across regional plants. Haleon anchors its ingredient strategy around clinically validated stannous fluoride complexes. Unilever competes through scaled natural extract sourcing in Southeast Asian supply corridors.
Oral health ingredients encompass functional actives, excipients, and delivery vehicles formulated for dental hygiene applications, with fluoride concentrations typically calibrated between 1,000 and 1,500 ppm for anticavity efficacy and abrasivity indices measured by radioactive dentin abrasion scores. These inputs serve consumer product manufacturers, compounding pharmacies, and dental professional channels seeking therapeutic or cosmetic oral outcomes. Fluoride-based actives retain the dominant value share, though natural extracts represent the fastest-expanding margin pool as clean-label preferences intensify across European and North American retail. Whitening strips as a product format command premium ingredient economics due to hydrogen peroxide stabilization requirements and film-forming polymer specifications.
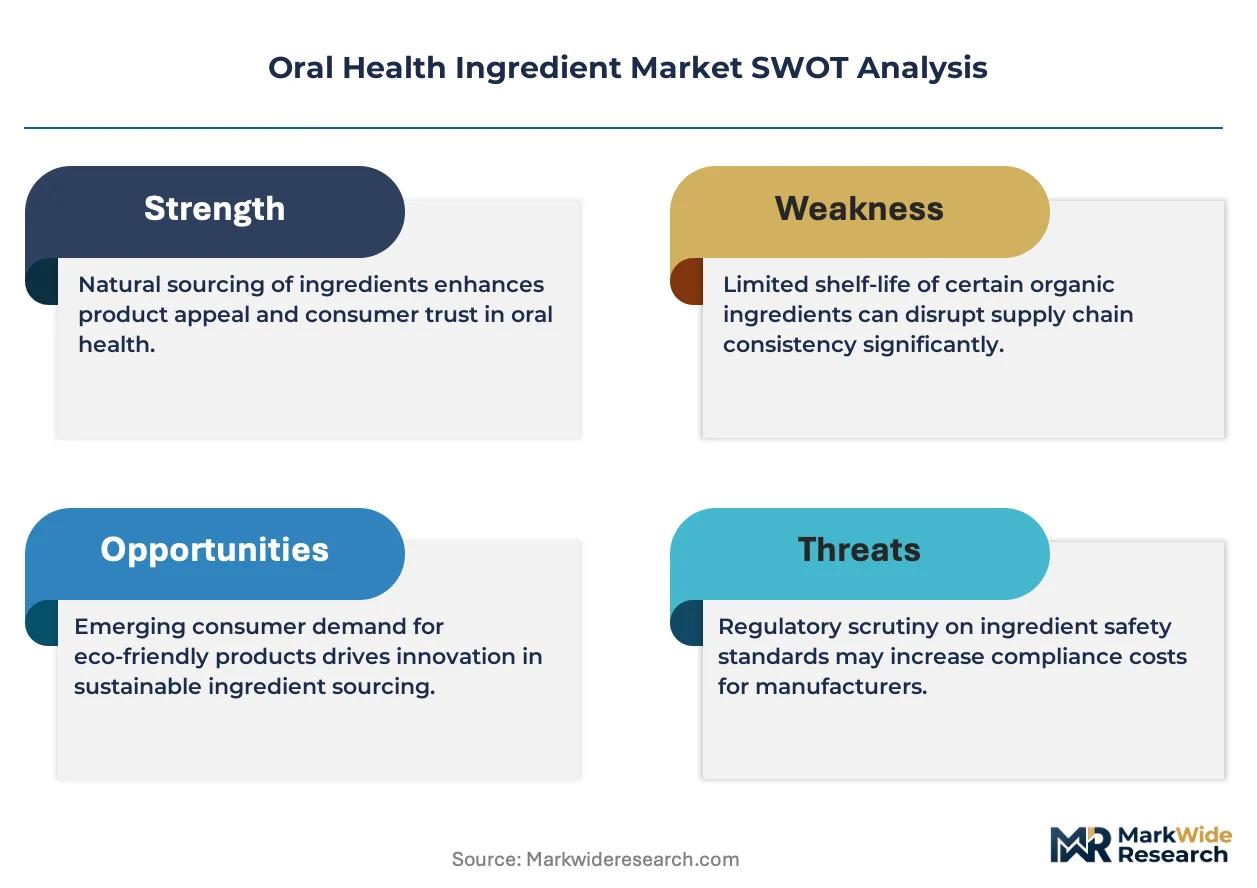
EPA oversees fluoride discharge limits from manufacturing facilities, while ECHA classifies certain antimicrobial quaternary compounds under REACH authorization procedures, constraining formulation flexibility for mouthwash producers. FDA monograph compliance for anticavity drug products mandates specific active concentrations and labeling claims, creating barrier-to-entry dynamics for new ingredient suppliers. Stakeholders must monitor evolving regulatory thresholds for peroxide-based whitening systems across multiple jurisdictions.
Market Dynamics
The European Union's REACH authorization procedures for antimicrobial quaternary compounds are forcing oral care formulators to redesign mouthwash actives and validate substitute chemistries, compressing product development timelines and elevating R&D expenditure across the supply base.
Growth Catalysts
- Specialty enamel repair formulations:Adult consumers in Germany and France are prioritizing preventive dental care, driving uptake of hydroxyapatite and calcium phosphate complexes in premium toothpaste channels.
- REACH-driven safety innovation:The EU's tightening safety assessments for cetylpyridinium chloride and chlorhexidine are accelerating investment in bio-based antimicrobial alternatives with cleaner toxicological profiles.
- Whitening strip stabilization:Hydrogen peroxide film-forming polymer specifications command premium ingredient economics as North American consumers shift toward at-home cosmetic dental treatments.
Market Restraints
- Fluoride supply concentration:Captive sodium fluoride production by integrated consumer goods manufacturers limits third-party supplier access to pharmaceutical-grade specifications.
- Peroxide regulatory fragmentation:Divergent concentration thresholds for whitening actives across FDA, Health Canada, and EU cosmetic regulations complicate cross-border formulation standardization.
- Abrasivity index calibration costs:Radioactive dentin abrasion testing requirements impose fixed compliance burdens on small-scale natural extract suppliers entering therapeutic claims markets.
Strategic Opportunities
- Southeast Asian natural extract corridors:Scaled sourcing of neem, miswak, and clove oil derivatives offers margin expansion for clean-label formulations targeting European retail buyers.
- Dental professional channel premiumization:Compounding pharmacies and clinician-directed sales in Germany present untapped volume for prescription-strength fluoride varnishes and remineralization pastes.
- Dual carbon alignment:China's NMPA green chemistry incentives and MIIT sustainable manufacturing standards create procurement advantages for suppliers with verified carbon footprint reductions.
Industry Challenges
- Toxicological assessor scarcity:REACH-compliant safety data sheet preparation and substance volume tracking require specialized regulatory chemistry expertise that mid-tier ingredient suppliers struggle to retain.
- Legacy fluoride specification integration:Reformulating established anticavity monograph products to incorporate novel delivery vehicles demands multi-year FDA pre-IND consultation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oral Health Ingredient Market |
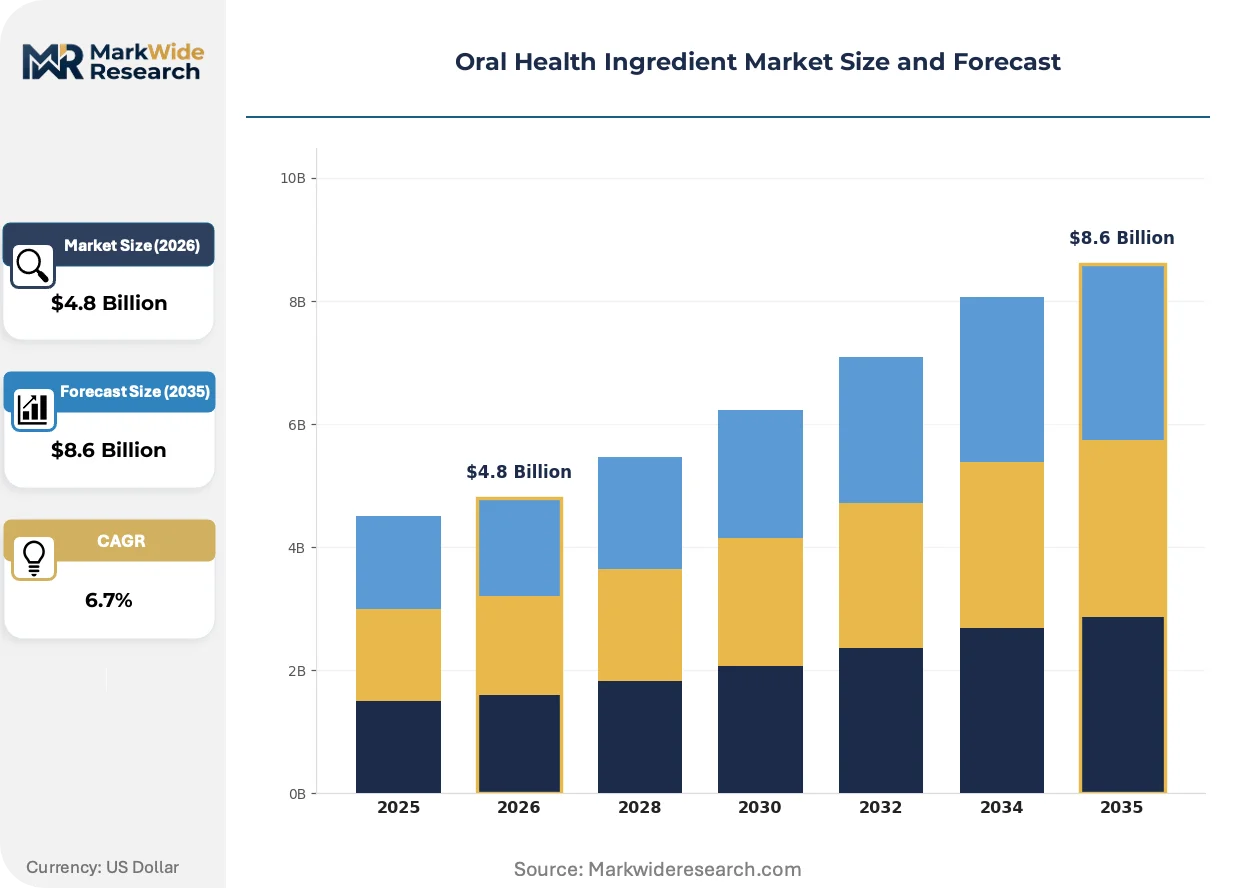
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Toothpaste, Mouthwash, Dental Floss, Whitening Strips Ingredient Type: Fluoride, Antimicrobials, Natural Extracts, Abrasives Formulation Type: Gel, Liquid, Paste, Powder End User: Adults, Children, Seniors, Professional Dentists |
| Companies Covered | Colgate-Palmolive Company, Procter & Gamble, Unilever, Johnson & Johnson, Haleon, Henkel, Church & Dwight, Koninklijke Philips, GlaxoSmithKline, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oral Health Ingredient Market Evolving Landscape
Formulation science is diverging along therapeutic efficacy and clean-label positioning axes, with ingredient suppliers pressured to validate clinical outcomes while eliminating synthetic preservatives and petroleum-derived carriers from oral care compositions.
Biomimetic mineralization technology is bifurcating competitive positioning in the enamel repair segment. Synthetic hydroxyapatite and casein phosphopeptide-amorphous calcium phosphate complexes are displacing conventional fluoride mono-therapy in premium adult formulations. German dental professional channels are adopting these actives at accelerated rates, compressing market space for commodity fluoride suppliers unable to demonstrate remineralization efficacy beyond basic caries prevention.
ECHA's 2024 updates to REACH authorization lists for quaternary ammonium compounds are reshaping antimicrobial mouthwash formulations. The industrial consequence is a forced migration toward phenolic alternatives and essential oil blends that lack equivalent clinical validation for gingivitis reduction. Mouthwash producers serving EU markets are responding by commissioning new randomized controlled trials to support substitute active claims, elevating development costs and extending time-to-market.
Clean-label procurement preferences are fragmenting buyer-supplier relationships in North American retail. Mass-market retailers are unbundling after-sales technical support from ingredient contracts, replacing dedicated formulation partnerships with spot purchasing of certified natural extracts. This pattern is most visible in the United States, where Sephora and Target clean beauty standards are cascading into oral care aisle resets, advantaging suppliers with third-party organic and non-GMO certifications over legacy chemical manufacturers.
Oral Health Ingredient Market Segmentation
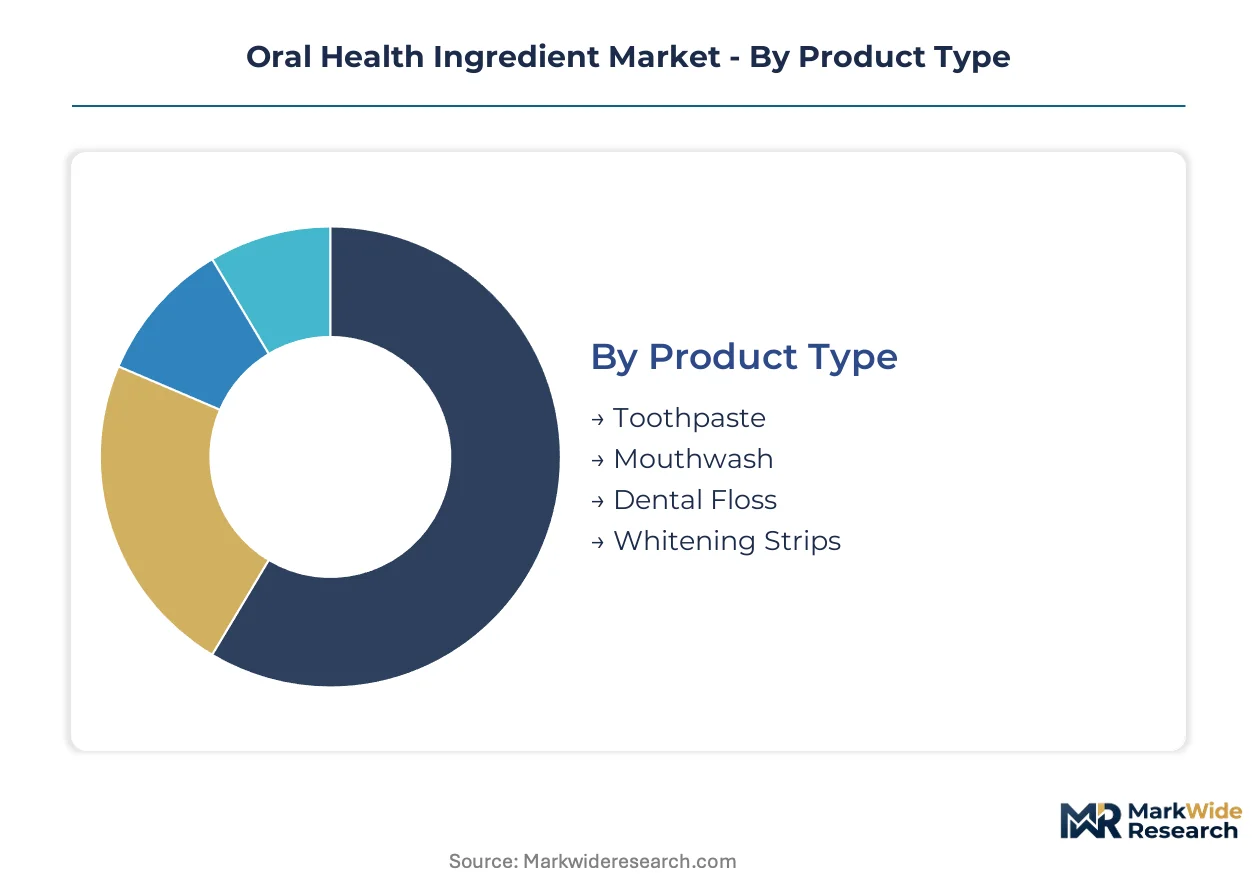
Ingredient suppliers must calibrate R&D portfolios against four intersecting dimensions—product format, active chemistry, physical state, and user population—each carrying distinct margin profiles and regulatory burdens. Misalignment between these segments and go-to-market capabilities erodes profitability in a market where formulation specifications are tightening under REACH and FDA oversight.
Product Type:
Premium ingredient economics concentrate in formats requiring specialized stabilization chemistry and film-forming polymer specifications.
- Toothpaste:Formulations incorporate fluoride concentrations calibrated between 1,000 and 1,500 ppm alongside abrasivity indices measured by radioactive dentin abrasion scores. Demand in Germany concentrates through dental professional channels seeking enamel repair variants with hydroxyapatite complexes.
- Mouthwash:Antimicrobial actives face forced substitution as ECHA REACH authorization procedures constrain cetylpyridinium chloride and chlorhexidine usage, elevating R&D expenditure for phenolic and essential oil alternatives lacking equivalent clinical validation.
- Dental Floss:Waxed and unwaxed polymer substrates incorporate flavoring agents and antimicrobial coatings, with procurement shifting toward bio-based wax alternatives under EU Green Deal sustainability pressures.
- Whitening Strips:Hydrogen peroxide stabilization requirements and film-forming polymer specifications command premium ingredient economics as North American consumers shift toward at-home cosmetic dental treatments.
The dominant share belongs to Toothpaste, while Whitening Strips is closing the gap fastest.
Ingredient Type:
Supply-side concentration and captive production arrangements determine third-party supplier access across active chemistry categories.
- Fluoride:Sodium fluoride and stannous fluoride complexes retain dominant value share, though pharmaceutical-grade specifications are increasingly captive to integrated consumer goods manufacturers limiting external procurement channels.
- Antimicrobials:Quaternary ammonium compounds face REACH authorization constraints while phenolic alternatives require fresh clinical validation investment, fragmenting competitive positioning among mouthwash formulators.
- Natural Extracts:Neem, miswak, and clove oil derivatives sourced through Southeast Asian supply corridors represent the steepest expansion trajectory as clean-label preferences intensify across European and North American retail resets.
- Abrasives:Hydrated silica and calcium carbonate specifications are calibrated against radioactive dentin abrasion testing protocols, with compliance costs disadvantaging small-scale suppliers entering therapeutic claims markets.
Fluoride maintains volume leadership, though Natural Extracts is expanding most quickly on margin contribution.
Formulation Type:
Physical state selection governs delivery vehicle engineering, stability testing protocols, and manufacturing equipment requirements.
- Gel:Transparent or translucent matrices require solubilization of actives and compatibility with synthetic or natural thickeners, with demand concentrating in cosmetic-oriented toothpaste and mouthwash applications.
- Liquid:Mouthwash and rinse formulations demand preservative systems and antimicrobial stability validation, with ECHA tightening safety assessments for synthetic preservatives under REACH frameworks.
- Paste:Semi-solid rheology enables suspension of abrasive particles and controlled release of fluoride actives, serving the largest volume segment across consumer and professional channels.
- Powder:Dry formulations offer preservative-free positioning and reduced shipping weights, appealing to sustainability-focused European retail buyers despite limited current market penetration.
Paste formulations dominate current volume, while Gel is gaining share fastest in premium positioning.
End User:
User population segmentation dictates regulatory pathway complexity, clinical validation requirements, and channel access strategies.
- Adults:Preventive dental care priorities drive uptake of enamel repair formulations with hydroxyapatite and calcium phosphate complexes in German and French premium channels.
- Children:Pediatric formulations require lower fluoride concentrations and flavor masking systems, with FDA monograph compliance mandating specific labeling claims that extend development timelines.
- Seniors:Dry mouth and gingivitis management needs concentrate demand for specialized moisturizing agents and antimicrobial systems in clinician-directed sales.
- Professional Dentists:Prescription-strength fluoride varnishes and remineralization pastes command premium economics through compounding pharmacy and dental professional channels in Germany.
Adults retain the largest addressable base, while Professional Dentists is climbing the fastest on per-unit value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German ingredient exports supply premium toothpaste formulators across France and the Netherlands, while Southeast Asian natural extract corridors feed clean-label demand in North American retail channels.
Germany
Dental professional channels in Bavaria and North Rhine-Westphalia drive uptake of hydroxyapatite and calcium phosphate complexes for enamel repair formulations. ECHA's REACH authorization procedures for antimicrobial quaternary compounds force mouthwash producers in Hamburg to redesign actives and validate substitute chemistries. The Frankfurt-Rhine-Main cluster concentrates compounding pharmacy procurement of prescription-strength fluoride varnishes.
United States
FDA monograph compliance for anticavity drug products mandates specific active concentrations and labeling claims that extend development timelines for new ingredient suppliers. EPA fluoride discharge limits from manufacturing facilities in New Jersey and Ohio constrain production expansion for third-party sodium fluoride suppliers. The Greater Boston area anchors clinical validation partnerships between ingredient developers and dental research institutions.
China
NMPA green chemistry incentives and MIIT sustainable manufacturing standards create procurement advantages for suppliers with verified carbon footprint reductions. The Yangtze River Delta concentrates hydrogen peroxide stabilization chemistry production for whitening strip film-forming polymers. Shanghai-based formulators are scaling natural extract sourcing partnerships with Southeast Asian supply corridors.
France
ANSM oversight of cosmetic and therapeutic oral care claims requires dual regulatory pathways for enamel repair products positioning between drug and cosmetic categories. The Île-de-France region houses headquarters of major consumer goods manufacturers driving premium ingredient specifications. Lyon-based toxicological consultancies serve REACH-compliant safety data sheet preparation for mid-tier ingredient suppliers.
India
CDSCO alignment with international pharmaceutical-grade fluoride specifications is reorganizing procurement priorities for domestic toothpaste manufacturers. Gujarat and Maharashtra host natural extract processing facilities supplying neem and clove oil derivatives to European clean-label buyers. The Delhi-NCR corridor concentrates regulatory chemistry expertise for substance volume tracking under India's evolving chemical safety frameworks.
Oral Health Ingredient Market Competitive Landscape
Listed leaders compete with private specialists across formulation consistency and captive supply security. The supplier base organizes around three tiers: integrated consumer goods manufacturers with in-house fluoride production, specialized pharmaceutical-grade chemical suppliers, and regional natural extract processors. Strategic moves concentrate on backward integration into sodium fluoride production and scaled sourcing agreements in Southeast Asian supply corridors.
Among integrated consumer goods manufacturers, Procter & Gamble, Haleon, and Unilever exemplify divergent ingredient strategies. Procter & Gamble anchors its position through captive sodium fluoride production securing formulation consistency across regional plants. Haleon occupies a position centered on clinically validated stannous fluoride complexes. Unilever represents the scale-driven archetype through natural extract sourcing in Southeast Asian supply corridors.
| Leading Market Players |
|---|
| Colgate-Palmolive Company |
| Procter & Gamble |
| Unilever |
| Johnson & Johnson |
| Haleon |
| Henkel |
| Church & Dwight |
| Koninklijke Philips |
| GlaxoSmithKline |
| Others |
Value Network & Pricing Analysis
Hydroxyapatite displacement of conventional fluoride mono-therapy in German premium channels is simultaneously shifting procurement geography toward Japanese mineral suppliers and compressing margins for commodity sodium fluoride producers locked into pharmaceutical-grade specifications.
Pricing Analysis
Technology-generation pricing gaps separate biomimetic mineralization actives from legacy fluoride complexes and emerging bio-based antimicrobials. Pricing stratifies across premium enamel repair formulations, standard anticavity actives, and economy-grade abrasives based on clinical validation depth and REACH compliance certification. Cost compression in commodity fluoride tiers is intensifying because captive production by integrated consumer goods manufacturers limits third-party supplier access. Professional dentist channels exhibit lowest price sensitivity due to prescription-strength reimbursement structures, while mass-market retailers demonstrate acute sensitivity to per-unit active costs.
Supply Chain Analysis
Strait of Malacca transit underwrites Southeast Asian natural extract corridors feeding European clean-label demand. Supply concentration centers on China for hydrogen peroxide stabilization chemistry, Germany for pharmaceutical-grade fluoride specifications, and India for neem and clove oil processing. Raw material dependencies encompass sodium fluoride precursors, film-forming polymers for whitening strips, and bio-based wax alternatives for dental floss substrates. Single-source vulnerability from ECHA REACH authorization restrictions on quaternary ammonium compounds elevates substitution risk for mouthwash formulators. Distribution runs through dental professional channels in Bavaria and North Rhine-Westphalia, compounding pharmacies in Frankfurt-Rhine-Main, and mass-market retail resets across North American clean beauty aisles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The oral health ingredient market sits at a cyclical recovery phase driven by post-pandemic preventive dental care prioritization among adult consumers in Germany and France.
For Market Incumbents: Shield formulation consistency advantages by deepening captive sodium fluoride production and securing multi-year supply agreements with Southeast Asian natural extract processors. ECHA's tightening REACH authorization timelines for antimicrobial quaternary compounds threaten established mouthwash actives, making backward integration into bio-based phenolic alternatives the priority defensive lever. For New Entrants and Emerging Players: Differentiate on clean-label certification depth to penetrate mass-market retail resets at Sephora and Target where third-party organic and non-GMO credentials outweigh legacy chemical manufacturer relationships. The most penetrable white space sits in prescription-strength fluoride varnishes for German compounding pharmacies, accessible through clinician-directed sales partnerships rather than commodity ingredient spot purchasing. For Investors and Strategic Acquirers: The market sits at an early-cycle phase that favors acquisition of specialized pharmaceutical-grade chemical suppliers with validated REACH compliance infrastructure. Long-term viability across the five-to-ten year window hinges on toxicological assessor retention and substance volume tracking capabilities. The signal to watch as inflection indicator is CDSCO alignment progress with international fluoride specifications in Indian domestic manufacturing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sodium Fluoride Production | Procter & Gamble's captive supply secures formulation consistency across regional plants. |
| REACH-Compliant Safety Data Sheet Investment | Lyon-based toxicological consultancies serve mid-tier suppliers facing ECHA authorization deadlines. |
| Scaled Natural Extract Sourcing Partnerships | Unilever's Southeast Asian corridor agreements feed European clean-label retail resets. |
| Clinical Validation Partnership with Dental Research Institutions | Greater Boston anchors biomimetic mineralization efficacy studies for enamel repair claims. |
| Dual Carbon Footprint Certification Program | China's NMPA green chemistry incentives create procurement advantages for verified carbon reduction. |
Research Methodology
Desk research of regulatory filing databases, customs trade records, and clinical trial registries preceded structured interviews with formulation scientists at consumer goods manufacturers, procurement leads at compounding pharmacies, regulatory affairs specialists, and dental professional channel distributors. Secondary validation drew from ECHA substance volume tracking data, FDA anticavity monograph documentation, EPA fluoride discharge compliance records, and Nielsen retail audit information across European and North American markets. Bottom-up ingredient demand modeling triangulated against top-down consumer product manufacturer procurement disclosures.
Variance decomposition across the projection horizon isolates volume drivers by product format, active chemistry tier, formulation state, and end-user population segment. The analytical framework models segmentation dimensions including therapeutic versus cosmetic positioning, pharmaceutical-grade versus technical-grade specifications, and dental professional versus retail channel access. CAGRs were derived from fitted growth curves benchmarked against historical fluoride adoption patterns and natural extract penetration trajectories. Industry-specific forecast inputs encompass REACH authorization timeline assumptions and NMPA green chemistry incentive uptake rates.
Material uncertainties — regulatory threshold revisions for peroxide-based whitening systems, ECHA substance authorization list updates, and CDSCO specification alignment delays — sit outside the modeled envelope. Forecasts reflect assumptions about continued clean-label preference intensification and sustained dental professional channel premiumization. Practitioners should keep alternative scenarios live as antimicrobial active substitution timelines and carbon footprint verification standards evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oral Care
Oral Irrigator Market
Oral Care
Kids Oral Care Products Market
Oral Care
Halitosis Treatment Market
Oral Care
Toothcare Market
Oral Care
Global Oral Hygiene Market
Oral Care
BRICS Oral Care Market
Oral Care
Global Oral Care/Oral Hygiene Market
Oral Care
Global Toothbrush and Toothpaste Market
Oral Care
Global Interdental Cleaning Products Market
Oral Care
Baby Oral Care Market
Oral Care
Global Halitosis Market
Oral Care
China Oral Care Market
Oral Care
Mouthwash Market
Oral Care
Oral Rinse Market
Oral Care
Xerostomia Treatment Market
Oral Care
Mouth Spray Market