
 Herbal Toothpaste Market | 2026-2036
Herbal Toothpaste Market Size, Share, and Industry Trends Forecast 2026-2036
Herbal Toothpaste Market Outlook
Premium fluoride-free certification is rotating from niche positioning to mainstream expectation in developed and emerging economies alike. Patanjali Ayurved Limited leverages its farm-to-tube supply chain to dominate India's traditional medicine retail channels. Colgate-Palmolive Company anchors its position through mass-market distribution density and dual-portfolio strategy spanning conventional and herbal lines. Dabur India Limited specializes in Ayurvedic heritage formulations that sustain brand loyalty across multi-generational households.
Herbal toothpaste denotes a dentifrice formulation incorporating plant-derived active ingredients such as neem, clove oil, or meswak extract as primary functional agents rather than synthetic compounds, manufactured through cold-processing or low-temperature extraction to preserve volatile phytochemical integrity. The product category serves consumers seeking oral hygiene efficacy without artificial preservatives, colors, or fluoride content. Organic and fluoride-free product types command margin premiums as supply chains invest in certified raw material sourcing and third-party validation. Sensitive teeth and gum care applications are expanding fastest as dental practitioners in Europe and North America recommend plant-based alternatives for patients with mucosal sensitivities or post-procedural recovery needs.
India's BIS and FSSAI frameworks mandate heavy metal limits and microbial purity standards for herbal oral care products, creating compliance barriers for unorganized manufacturers while validating premium positioning for certified brands. The EU's REACH regulation and Cosmetics Regulation impose disclosure requirements on botanical ingredient concentrations that shape export feasibility for Asian producers. Stakeholders must monitor evolving greenwashing litigation risks in North America and Europe where unsubstantiated natural claims face intensifying regulatory scrutiny and class-action exposure.
Market Dynamics
Millennial and Gen Z consumers in urban India are rejecting synthetic oral care formulations, forcing manufacturers to reconfigure supply chains around cold-processed botanical extraction and certified organic sourcing.
Growth Catalysts
- FSSAI purity benchmarks:India's tightening heavy metal and microbial standards for herbal cosmetics are elevating certified brands above unorganized competitors, consolidating shelf space in modern retail.
- Post-procedural recovery applications:Dental practitioners in Europe and North America are recommending plant-based alternatives for patients with mucosal sensitivities, expanding the clinical endorsement base beyond wellness positioning.
- Meswak and neem cold-processing:Low-temperature extraction methods preserve volatile phytochemical integrity, delivering functional efficacy claims that withstand regulatory scrutiny in export markets.
Market Restraints
- Certified organic raw material costs:Farm-to-tube traceability requirements inflate input expenses by 40-60% versus conventional dentifrice formulations, compressing margins for mid-tier producers.
- REACH disclosure burdens:The EU's botanical ingredient concentration reporting requirements create export friction for Asian manufacturers lacking in-house regulatory affairs capabilities.
- Fluoride-free efficacy skepticism:Dental associations in Germany and Japan continue questioning caries-prevention claims of non-fluoride formulations, limiting pharmacy channel penetration.
Strategic Opportunities
- Tier-two Indian cities:Underpenetrated urban corridors beyond Mumbai, Delhi, and Bangalore present whitespace for Ayurvedic heritage brands establishing modern trade presence before multinational saturation.
- Green chemistry convergence:Biodegradable packaging films derived from agricultural waste are converging with waterless toothpaste formats, enabling zero-waste product positioning in Scandinavian markets.
- BIS standard recognition:India's harmonization with ISO botanical quality frameworks creates regulatory tailwind for domestic manufacturers seeking Middle Eastern export approvals through mutual recognition protocols.
Industry Challenges
- Phytochemical standardization expertise:Shortage of analytical chemists capable of validating batch-to-batch active compound consistency slows new product development cycles.
- Greenwashing litigation exposure:Class-action risk in North American and European jurisdictions demands substantiation infrastructure for natural claims that many mid-cap producers lack.
- Cold-chain reconfiguration:Legacy distribution networks designed for shelf-stable synthetics require capital-intensive retrofitting to maintain volatile oil integrity through last-mile delivery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Herbal Toothpaste Market |
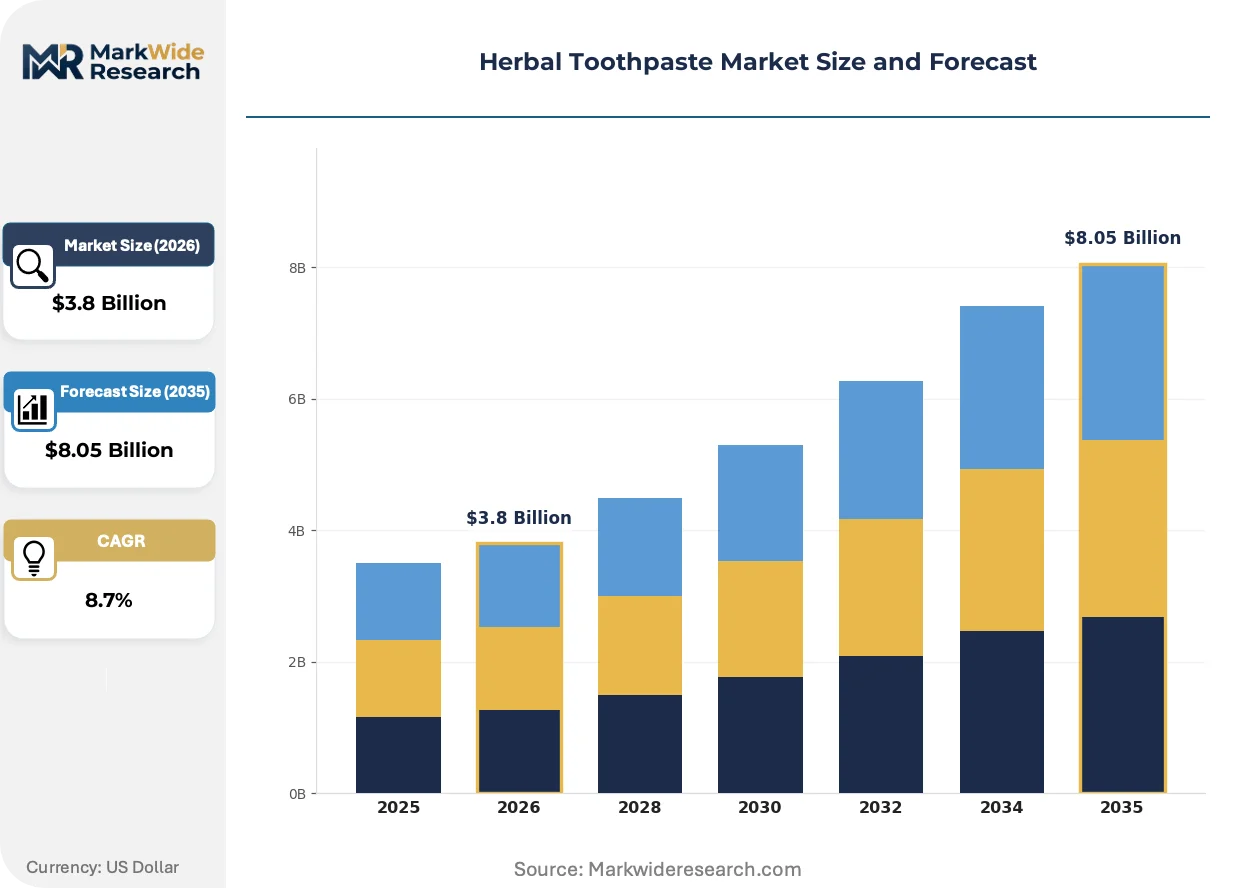
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
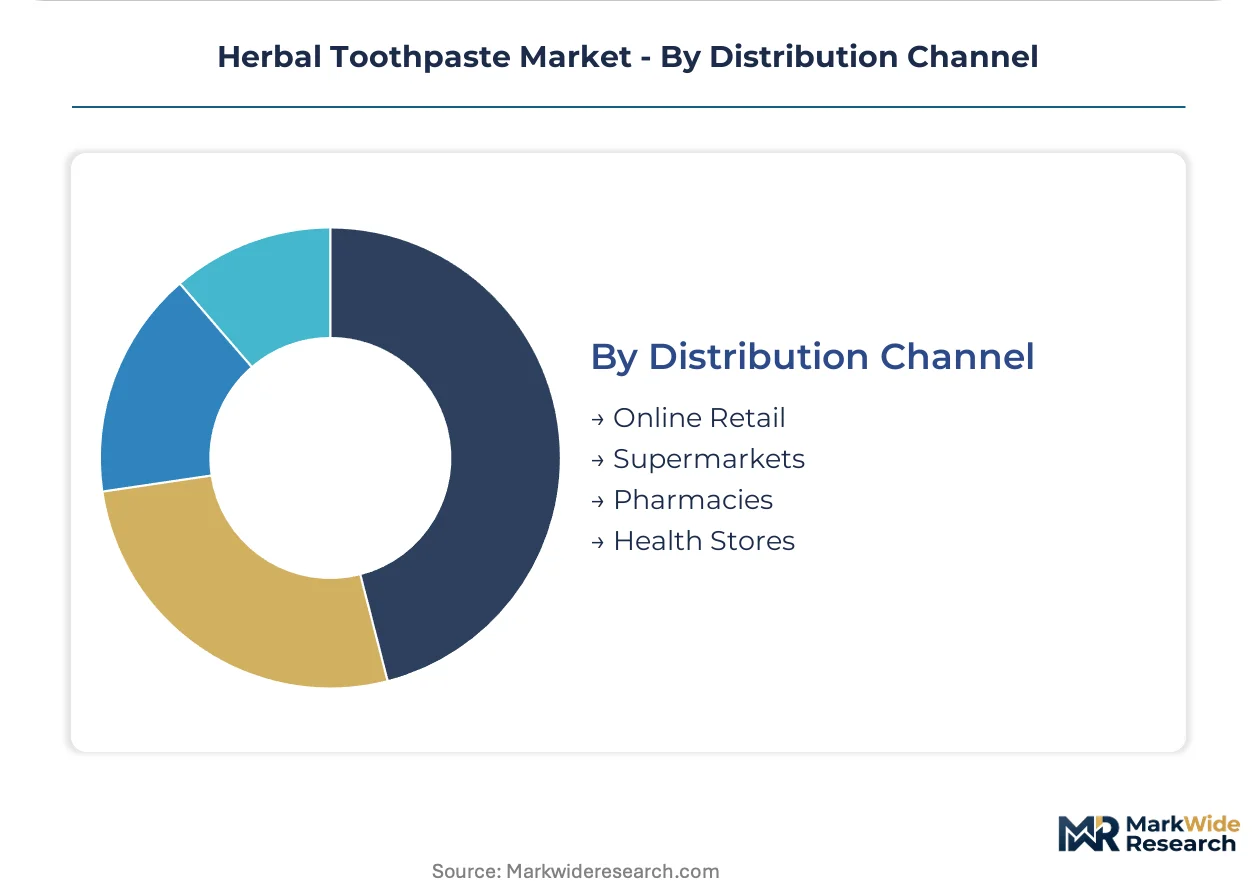
| Segmentation | Product Type: Natural, Organic, Fluoride-Free, Vegan Application: Daily Use, Sensitive Teeth, Whitening, Gum Care End User: Adults, Children, Seniors, Families Distribution Channel: Online Retail, Supermarkets, Pharmacies, Health Stores |
| Companies Covered | Patanjali Ayurved Limited, GlaxoSmithKline plc, Colgate-Palmolive Company, Rajni Herbals, Vicco, Dabur India Limited, Unilever PLC, HCP Wellness, The Himalaya Drug Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Herbal Toothpaste Market Strategic Shifts
Formulation science and regulatory disclosure requirements are converging to reshape competitive positioning, with technology-enabled transparency becoming the primary differentiation mechanism rather than ingredient storytelling alone.
Waterless toothpaste tablets incorporating lyophilized herbal actives are supplanting traditional tube formats in European zero-waste retail channels. Urban professionals in Amsterdam and Copenhagen are adopting these formats at pace, driven by airline carry-on convenience and bathroom aesthetic minimalism. The shift is compressing packaging cost structures while enabling direct-to-subscription revenue models that bypass conventional retail slotting fees.
REACH Article 33 disclosure mandates for botanical concentration thresholds are forcing reformulation of export-oriented product lines. Manufacturers serving EU markets must now quantify neem azadirachtin and clove eugenol percentages in public-facing documentation. Ayurvedic heritage brands with established laboratory infrastructure are responding faster than commodity suppliers, widening the compliance gap between certified and uncertified competitors.
Subscription-based replenishment cycles are disrupting pharmacy and supermarket stocking patterns for oral care. Indian metro consumers are migrating to quarterly delivery models curated by wellness platforms, replacing monthly impulse purchases. This behavioral pivot is most visible in Bangalore and Hyderabad, where direct-to-consumer brands capture recurring revenue through algorithmic personalization of herbal formulations matched to seasonal climate conditions.
Herbal Toothpaste Market Segmentation
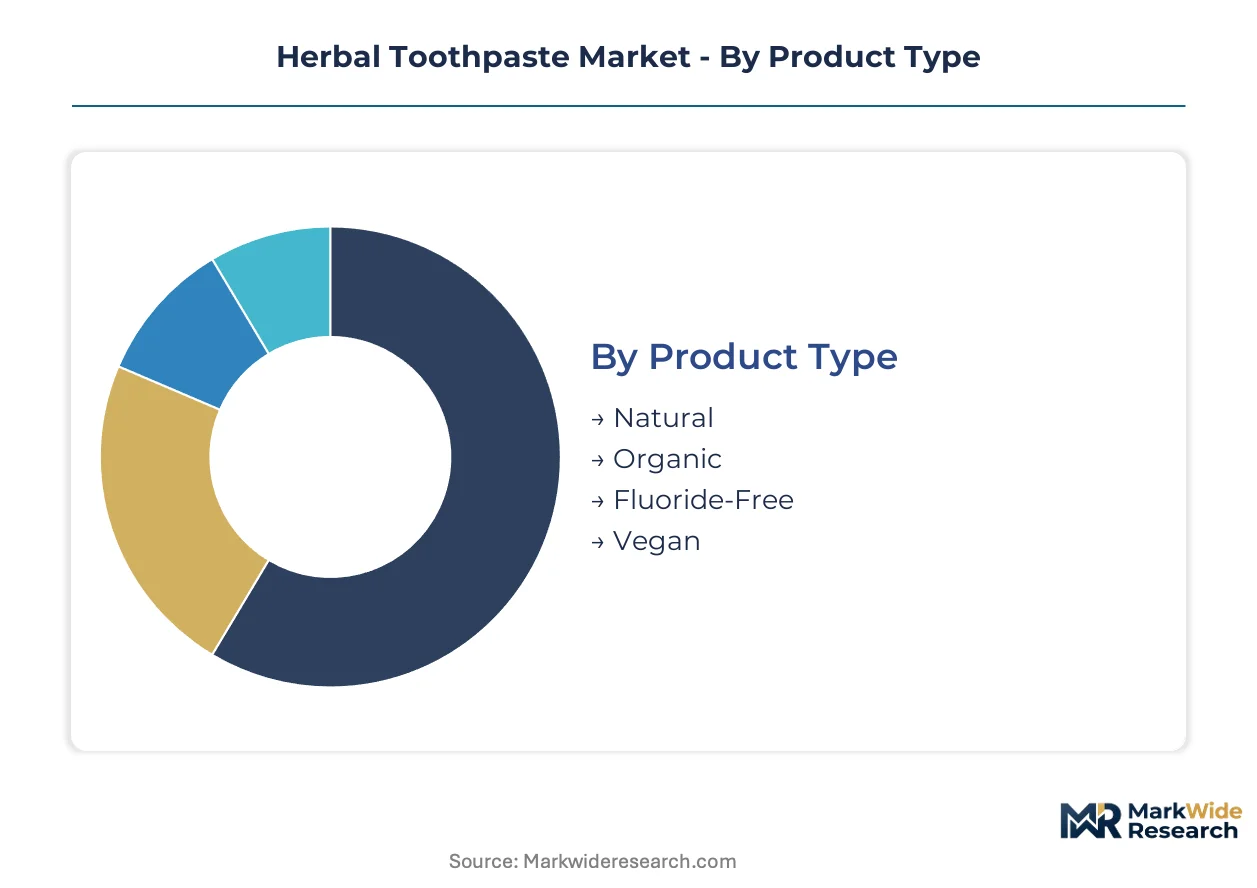
Herbal toothpaste manufacturers must navigate divergent substitution threats across product tiers, where synthetic alternatives compete aggressively on price while clinical endorsement gaps create vulnerability in pharmacy channels. Segmentation strategy determines whether brands capture premium positioning through certification depth or volume through mass-market accessibility.
Product Type:
Substitution pressure intensifies as consumers trade between certified organic premiums and loosely labeled natural variants that undercut on shelf price without comparable regulatory validation.
- Natural:Formulations leveraging plant-derived actives like neem or clove without third-party certification face erosion from private-label synthetics mimicking herbal positioning. Demand concentrates in India's tier-two cities where price sensitivity outstrips certification awareness.
- Organic:Cold-processed botanicals with USDA or India Organic certification command 40-60% input cost premiums that filter through to retail pricing. Urban professionals in Mumbai and Delhi sustain this tier through wellness platform subscriptions that prioritize traceability over convenience.
- Fluoride-Free:Positioning appeals to chemical-averse segments but encounters resistance from dental associations in Germany and Japan questioning caries-prevention efficacy.
- Vegan:Excludes all animal-derived ingredients including glycerin from conventional sources, aligning with Scandinavian zero-waste retail channels and Amsterdam's bathroom aesthetic minimalism trend.
Natural formulations retain volume leadership; Organic certification holds the steepest expansion curve.
Application:
Margin concentration follows clinical validation depth, with practitioner-recommended segments insulating against price-driven substitution.
- Daily Use:Standard maintenance formulations dominate unit volume but face commoditization as mass-market brands replicate herbal positioning without functional differentiation.
- Sensitive Teeth:Potassium nitrate-free alternatives incorporating meswak or chamomile extracts gain traction through European dental practitioner recommendations for post-procedural recovery. Demand clusters in Copenhagen and Amsterdam where mucosal sensitivity diagnoses drive prescription-adjacent purchases.
- Whitening:Charcoal and baking soda variants compete against peroxide-based synthetics on aesthetic outcomes rather than clinical metrics, limiting pharmacy channel penetration.
- Gum Care:Ayurvedic heritage formulations with astringent botanicals sustain multi-generational household loyalty across Bangalore and Hyderabad, where traditional medicine retail channels reinforce habitual repurchase.
Daily Use commands absolute volume; Sensitive Teeth applications are expanding most quickly through clinical endorsement networks.
End User:
Household purchasing authority determines whether formulations prioritize adult wellness positioning or child-safe compliance requirements.
- Adults:Individual purchasing decisions favor specialized applications matched to specific oral conditions, enabling premium pricing for targeted formulations.
- Children:Safety-focused guardians demand fluoride-free alternatives with mild flavor profiles, creating formulation constraints that limit botanical intensity. Regulatory scrutiny from India's FSSAI on pediatric oral care claims elevates compliance costs for this segment.
- Seniors:Gum recession and dry mouth conditions drive demand for moisturizing bases with aloe or licorice extracts, with uptake concentrated in Japan's aging demographic corridors.
- Families:Multi-user packaging formats prioritize cost efficiency over specialization, capturing volume through Bangalore supermarket chains and quarterly subscription bundles.
Families drive aggregate volume through consolidated purchasing; Seniors represent the most defensible margin tier through condition-specific requirements.
Distribution Channel:
Channel selection determines exposure to regulatory disclosure burdens versus convenience-driven impulse purchasing.
- Online Retail:Direct-to-consumer platforms bypass slotting fees while enabling algorithmic personalization of formulations to seasonal climate conditions. Bangalore and Hyderabad consumers migrate fastest to quarterly replenishment models curated by wellness platforms.
- Supermarkets:Mass-market density rewards brands with farm-to-tube traceability infrastructure that satisfies modern retail procurement standards. Patanjali Ayurved Limited dominates this channel through traditional medicine retail penetration.
- Pharmacies:Clinical credibility requirements restrict entry to brands with documented phytochemical standardization; EU REACH disclosure mandates on botanical concentrations create friction for uncertified competitors.
- Health Stores:Zero-waste positioning and waterless tablet formats gain traction in Scandinavian specialist retail, with lyophilized herbal actives compressing packaging cost structures.
Supermarkets sustain volume leadership through distribution density; Online Retail climbs the fastest as subscription models displace monthly impulse purchasing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows from Asian botanical processors face mounting compliance friction in European and North American import channels. India's trade surplus in herbal oral care depends on cold-chain integrity and phytochemical documentation that smaller producers struggle to maintain.
India
Millennial and Gen Z consumers in Mumbai, Delhi, and Bangalore are rejecting synthetic formulations, creating pull-through for farm-to-tube traceability systems. FSSAI purity benchmarks and BIS heavy metal limits are consolidating shelf space toward certified manufacturers. Production clusters in Gujarat and Maharashtra are retrofitting cold-processing infrastructure to preserve volatile oil integrity through last-mile distribution.
United States
Wellness platform subscriptions are displacing pharmacy impulse purchasing among urban professionals in New York and Los Angeles. FDA oversight of cosmetic oral care claims remains lighter than pharmaceutical dentifrice regulation, though FTC scrutiny of unsubstantiated natural positioning is intensifying. Direct-to-consumer brands in California are capturing recurring revenue through algorithmic personalization matched to regional climate conditions.
Germany
Dental association skepticism toward fluoride-free caries-prevention claims limits pharmacy channel penetration for plant-based alternatives. REACH Article 33 disclosure mandates on botanical concentration thresholds create documentation burdens for Asian exporters lacking in-house regulatory affairs. Berlin and Hamburg consumers are adopting waterless toothpaste tablets through zero-waste retail channels, compressing packaging cost structures.
Japan
Aging demographic corridors are driving demand for moisturizing bases with aloe and licorice extracts among seniors with dry mouth conditions. PMDA and METI frameworks for quasi-drug oral care claims require clinical substantiation that Ayurvedic heritage brands are investing to obtain. Osaka and Tokyo distribution networks are reconfiguring around subscription replenishment models that bypass conventional retail slotting fees.
Netherlands
Amsterdam's bathroom aesthetic minimalism trend is accelerating adoption of lyophilized herbal actives in tablet formats. ECHA alignment with REACH disclosure requirements shapes import feasibility for Asian producers seeking EU market access. Rotterdam logistics hubs are consolidating cold-chain capabilities for volatile phytochemical preservation through European distribution.
Herbal Toothpaste Market Competitive Environment
Concentration sits with Ayurvedic heritage specialists and multinational dual-portfolio strategists. The competitive terrain splits between farm-to-tube traceability leaders and mass-market distribution density players. Three archetypes dominate: traditional medicine retail channel specialists, modern trade mass-market anchors, and direct-to-consumer subscription platforms. Strategic moves center on cold-processing capacity expansion and regulatory certification depth.
Within the heritage Ayurvedic tier, Patanjali Ayurved Limited and Dabur India Limited exemplify farm-to-tube supply chain control. Colgate-Palmolive Company occupies a position spanning conventional and herbal portfolio lines through mass-market density. Among European multinationals, GlaxoSmithKline plc and Unilever PLC represent dual-market approaches balancing synthetic and botanical formulations. The Himalaya Drug Company anchors the mid-tier certification space. These entities illustrate competitive positioning around traceability infrastructure, regulatory compliance depth, and channel-specific distribution architecture rather than interchangeable product substitution.
| Leading Market Players |
|---|
| Patanjali Ayurved Limited |
| GlaxoSmithKline plc |
| Colgate-Palmolive Company |
| Rajni Herbals |
| Vicco |
| Dabur India Limited |
| Unilever PLC |
| HCP Wellness |
| The Himalaya Drug Company |
| Others |
Value Chain & Pricing Dynamics
India Organic and USDA certification tiers gate both raw material qualification and retail price positioning simultaneously, forcing manufacturers to absorb 40-60% input cost premiums to access urban professional segments in Mumbai and Delhi that prioritize traceability over convenience.
Pricing Analysis
Urban wellness platform subscribers anchor three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on certification depth and cold-processing validation, with organic-certified formulations commanding sustained premiums. Cost compression in the natural tier is intensifying because private-label synthetics mimic herbal positioning without regulatory burden. Tier-two city households exhibit highest price sensitivity, while Bangalore and Hyderabad professionals show lowest elasticity for subscription-curated formulations.
Supply Chain Analysis
India and Thailand anchor botanical raw material cultivation, with Gujarat and Maharashtra production clusters retrofitting cold-processing infrastructure. The supply chain draws from neem, meswak, and clove oil inputs whose volatile phytochemical integrity requires temperature-controlled logistics. Single-source vulnerability concentrates in farm-to-tube traceability systems where smallholder consolidation lags demand. Distribution runs through modern trade supermarkets and direct-to-consumer wellness platforms that bypass conventional slotting fees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face sustained substitution pressure from synthetic dentifrice brands replicating herbal aesthetic positioning without functional ingredient load, requiring defensive investment in certification depth and clinical validation infrastructure.
For Market Incumbents: Compound farm-to-tube traceability advantages by backward integration into captive organic cultivation in Gujarat and Maharashtra production corridors. Elevate FSSAI and BIS certification depth to create compliance moats against unorganized competitors. Cold-processing capacity expansion insulates volatile oil integrity through last-mile delivery, defending margin position against commodity suppliers lacking analytical standardization infrastructure.
For New Entrants and Emerging Players: Anchor in tier-two Indian cities beyond Mumbai, Delhi, and Bangalore where modern trade penetration remains underdeveloped and Ayurvedic heritage positioning resonates before multinational saturation. Target sensitive teeth and gum care applications where European dental practitioner endorsements create prescription-adjacent purchase authority. Launch through direct-to-consumer subscription models curated by wellness platforms to bypass supermarket slotting fee barriers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across cold-processing infrastructure and phytochemical laboratory standardization capabilities. Long-term viability favors acquisition targets with established BIS-ISO harmonization and Middle Eastern export approval pathways through mutual recognition protocols. The signal to monitor is REACH Article 33 disclosure compliance speed among Asian exporters, separating certified heritage brands from commodity suppliers facing EU market friction.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Processing Capacity Expansion | Preserves volatile phytochemical integrity for FSSAI purity benchmark compliance in Indian retail. |
| Organic Certification Investment | Unlocks 40-60% input cost recovery through urban professional subscription channels in Mumbai and Delhi. |
| Direct-to-Consumer Platform Launch | Bypasses supermarket slotting fees while enabling algorithmic personalization for Bangalore and Hyderabad consumers. |
| Waterless Tablet Format Introduction | Aligns with Amsterdam and Copenhagen zero-waste retail channels and bathroom aesthetic minimalism trends. |
| EU REACH Compliance Pathway | Enables export feasibility through botanical concentration disclosure infrastructure for neem azadirachtin and clove eugenol. |
Study Parameters
A standing panel of brand managers at heritage Ayurvedic houses, category buyers at modern trade retailers, cold-chain logistics operators, and phytochemical laboratory directors provided ongoing calibration. Primary interviews with supply chain planners and regulatory affairs specialists at FSSAI-notified bodies combined with secondary validation from BIS technical committee documentation, India Organic certification registries, EU ECHA REACH disclosure filings, and Nielsen retail audit data. Bottom-up volume modeling across product type, application, end user, and distribution channel segments triangulated against top-down macroeconomic drivers.
Consistency checks validated volume and value outputs against external benchmarks throughout the forecast period. The analytical framework modeled segmentation across product type, application, end user, and distribution channel dimensions plus regional regulatory cluster differentiation. CAGRs were derived from fitted growth curves incorporating cold-processing adoption rates, subscription platform penetration in Indian metros, and EU import compliance velocity for Asian exporters.
Underlying assumptions cover FSSAI purity benchmark enforcement intensity and EU REACH disclosure mandate adherence timelines, with deviation risk concentrated in greenwashing litigation exposure and phytochemical standardization expertise shortages. Recalibration cycles align with material shifts in regulatory disclosure requirements and cold-chain infrastructure investment patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oral Care
Us Oral Care Market
Oral Care
GCC Oral Hygiene Market
Oral Care
Kids Toothpaste Market
Oral Care
Global Toothbrush and Toothpaste Market
Oral Care
South America Oral Care Market
Oral Care
Mouthwash Market
Oral Care
Kids Oral Care Products Market
Oral Care
Baby Oral Care Market
Oral Care
Oral Thin Films Market
Oral Care
Middle East and Africa Oral Care Market
Oral Care
Children's Oral Care Market
Oral Care
North America Oral Care Market
Oral Care
LED Oral Care Kits Market
Oral Care
Dry Mouth Relief Market
Oral Care
Mouth Sore Medicine Market
Oral Care
Global Halitosis Market