
 Japan Oral Hygiene Market | 2026-2036
Japan Oral Hygiene Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Oral Hygiene Market Intelligence
Pharmacy distribution is tilting toward preventive care bundles in Japan's oral hygiene sector. Lion Corporation leverages its deep domestic manufacturing footprint to control shelf placement in drugstore chains. Kao Corporation anchors its position through sustained R&D investment in enzymatic formulations. Procter & Gamble competes by extending premium imports through select urban retail partnerships.
Oral hygiene encompasses products designed to maintain dental health through mechanical cleaning, chemical antimicrobial action, or therapeutic delivery of active agents such as fluoride at concentrations between 900 and 1,500 ppm. These formulations serve both cosmetic purposes and disease prevention, with particular emphasis on reducing periodontal disease incidence in aging populations. Toothpaste occupies the largest revenue pool among product types, though whitening variants command disproportionate margin premiums. The senior end-user segment shows the steepest trajectory as edentulism rates decline and implant maintenance protocols expand. Online retail channels capture growing transaction volume through subscription models for repeat-purchase items.
METI sets packaging reduction targets that manufacturers must incorporate into product redesign cycles. PMDA oversight of quasi-drug classifications determines which antibacterial claims receive regulatory clearance for market entry. JIS standards for toothbrush filament safety and dimensional consistency create baseline quality thresholds that both domestic and imported products must satisfy. Stakeholders should monitor how aging-clinic partnerships reshape professional-channel procurement patterns.
Market Dynamics
Japan's oral hygiene sector confronts a demographic inversion where elderly consumers now drive category innovation rather than trailing mainstream adoption. This structural pivot forces manufacturers to redesign product portfolios around implant maintenance, reduced manual dexterity, and pharmacy-based preventive care protocols.
Growth Catalysts
- Implant Maintenance Protocols:Dental clinics now prescribe specialized brushes and antimicrobial rinses for post-surgical care. This clinical channel creates recurring revenue streams distinct from retail.
- METI Packaging Mandates:Sustainability targets compel lightweight tube redesigns and refill formats. Compliance investments differentiate domestic manufacturers from import-dependent competitors.
- Enzymatic Formulation Advances:Biofilm-disrupting enzymes replace abrasive whitening agents in premium tiers. Kao Corporation's R&D pipeline accelerates clinical validation for these therapeutic claims.
Market Restraints
- Fluoride Import Dependency:Industrial-grade sodium fluoride concentrates arrive primarily from Chinese chemical processors. Geopolitical friction elevates input cost volatility beyond hedging capacity.
- Quasi-Drug Approval Bottlenecks:PMDA's antibacterial claim review timeline extends 18-24 months for novel actives. This regulatory friction delays revenue recognition for reformulated products.
- Substitution by Professional Cleaning:Ultrasonic scaling services at dental clinics reduce home-care intensity for affluent seniors. Perceived efficacy gaps compress premium toothpaste volume.
Strategic Opportunities
- Subscription Commerce Models:Online platforms capture repeat-purchase loyalty through auto-replenishment algorithms. Seniors in Greater Tokyo show highest retention for brush-head replacement cycles.
- Prefecture-Level Aging-Clinic Partnerships:Hokkaido and Kyushu regions lack pharmacy density but maintain robust dental clinic networks. Direct procurement contracts bypass fragmented retail.
- Biodegradable Filament Convergence:PLA-based brush fibers meet METI targets while differentiating against nylon imports. Material science partnerships with domestic polymer specialists reduce certification risk.
Industry Challenges
- Formulation Chemist Scarcity:Cosmetic science graduates prefer skincare sector compensation. Oral care R&D labs compete for enzymatic stability expertise against larger personal care divisions.
- Legacy Manufacturing Footprint Stranding:Lion Corporation's regional factories require retooling for tube-to-pouch format shifts. Capex allocation debates delay sustainability compliance timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Oral Hygiene Market |
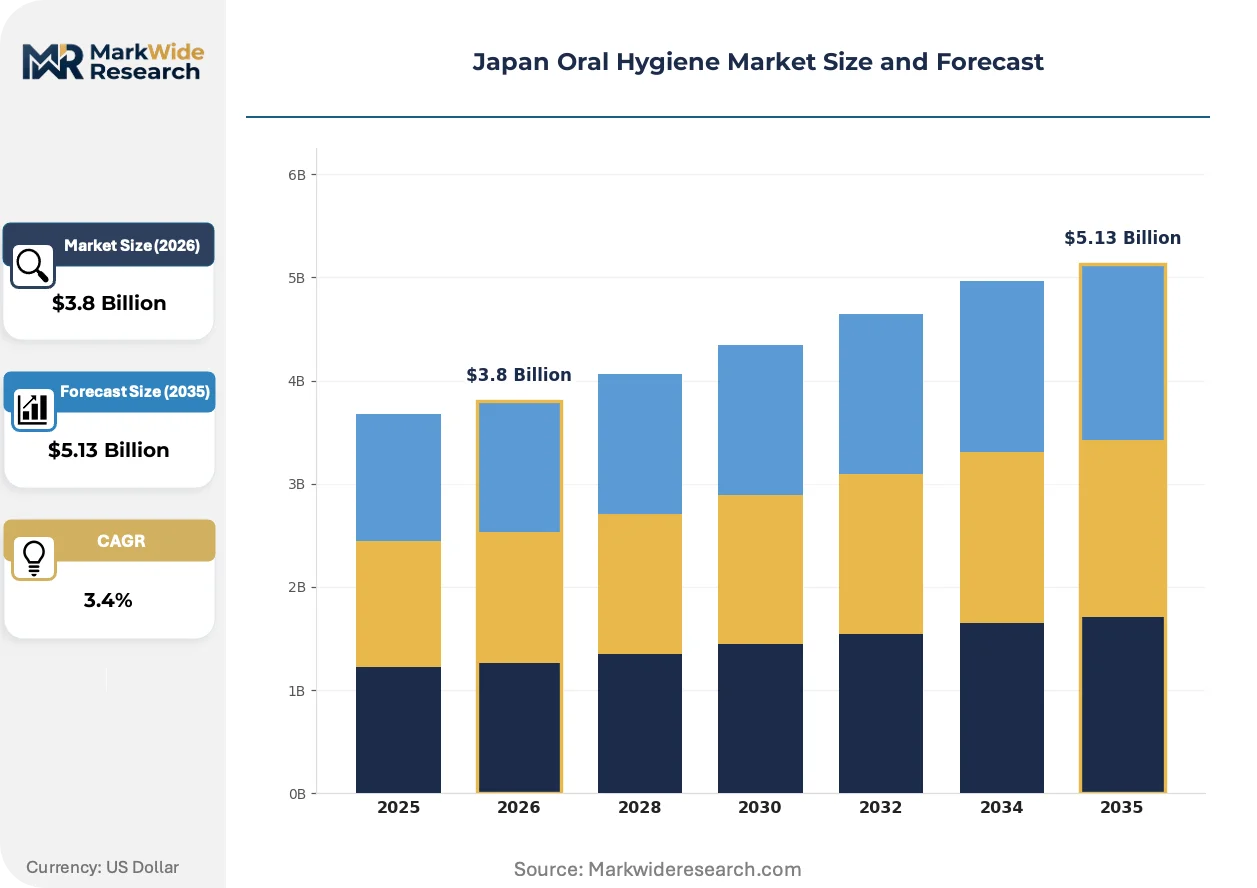
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.13 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Toothpaste, Mouthwash, Dental Floss, Chewing Gum End User: Adults, Children, Seniors, Professionals Distribution Channel: Online Retail, Supermarkets, Pharmacies, Convenience Stores Ingredient Type: Natural, Fluoride, Whitening, Antibacterial |
| Companies Covered | Lion Corporation, Kao Corporation, Procter & Gamble Company, Unilever PLC, GlaxoSmithKline plc, Colgate-Palmolive Company, Sunstar Suisse SA, Church & Dwight Co., Inc., Johnson & Johnson, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Oral Hygiene Market Strategic Shifts & Innovations
Connected devices and clinical validation protocols are displacing cosmetic marketing as the primary value driver in Japanese oral care. Manufacturers now compete on biometric feedback integration and professional endorsement depth.
Smart toothbrush systems is digitizing home care compliance through pressure sensors and brushing-duration analytics. Seniors in Osaka and Nagoya metropolitan areas adopt these devices fastest, driven by dental clinic recommendations. The technology is digitizing patient-dentist communication channels, enabling remote monitoring that reduces emergency intervention rates.
PMDA's 2023 quasi-drug classification revisions tightened evidentiary standards for antibacterial claims. Manufacturers must now submit microbiome safety data alongside efficacy documentation. Premium whitening tiers face reformulation costs as benzoyl peroxide concentrations fall under stricter scrutiny.
Pharmacy bundling now dominates preventive care procurement in Greater Tokyo. Retailers assemble toothpaste-floss-rinse combinations with loyalty-program discounts. Hokkaido's rural pharmacies resist this shift, maintaining single-item stocking patterns that fragment manufacturer trade investment efficiency.
Japan Oral Hygiene Market Segmentation
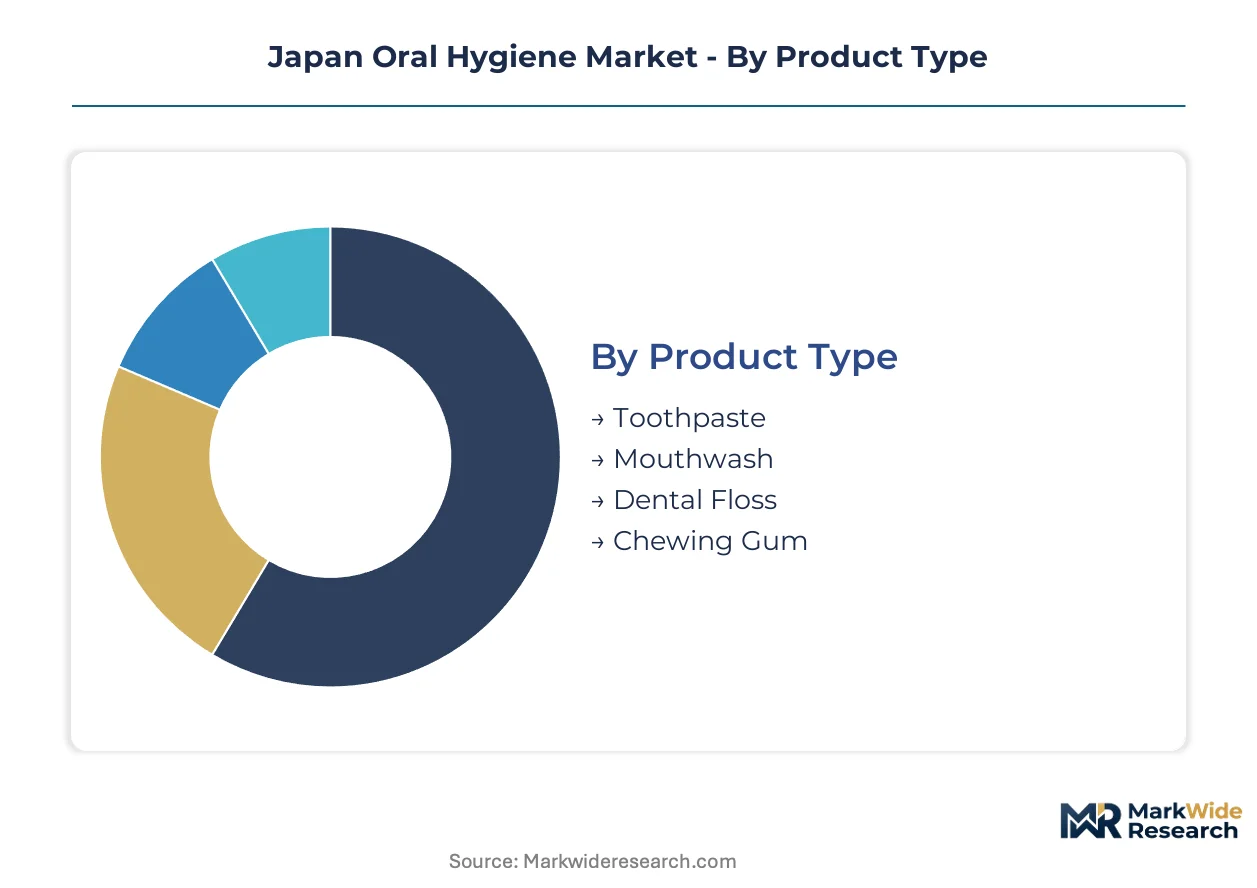
Japan's oral hygiene market fragments across four distinct dimensions that determine procurement patterns and margin structures. Product type and end-user segmentation drive formulation investments, while distribution channel and ingredient type govern regulatory compliance burdens and shelf placement economics.
Product Type:
Replacement cycles vary dramatically across this category, with consumables turning over weekly versus durable goods lasting months. Toothpaste commands the shortest repurchase interval and highest household penetration.
- Toothpaste:Fluoride concentrations between 900 and 1,500 ppm dominate therapeutic positioning. Greater Tokyo's pharmacy chains prioritize enzymatic formulations for aging consumers with implant maintenance protocols. METI packaging mandates accelerate lightweight tube redesigns that elevate manufacturing complexity.
- Mouthwash:Antimicrobial rinses carry quasi-drug classification under PMDA oversight, extending approval timelines. Dental clinics in Osaka and Nagoya prescribe these for post-surgical care, creating recurring clinical-channel revenue distinct from retail turnover.
- Dental Floss:Waxed and unwaxed variants serve manual dexterity limitations among senior users. Prefecture-level aging-clinic partnerships in Hokkaido bypass fragmented retail through direct procurement contracts.
- Chewing Gum:Xylitol-based formulations target inter-meal caries prevention in school-age populations. Convenience store distribution concentrates in urban corridors with commuter density.
Toothpaste dominates installed base. Mouthwash is where expansion concentrates.
End User:
Demographic targeting shapes formulation intensity and price positioning, with age-correlated dental conditions driving portfolio specialization.
- Adults:Standard preventive care regimens sustain volume throughput. Whitening variants command disproportionate margin premiums in Greater Tokyo's premium retail tiers.
- Children:Flavor-optimized low-fluoride formulations comply with pediatric safety thresholds. School-based distribution programs in Osaka prefecture create institutional procurement channels.
- Seniors:Edentulism decline and implant proliferation reshape demand toward specialized brushes and antimicrobial protocols. Subscription commerce models capture highest retention for brush-head replacement cycles in Tokyo metropolitan areas.
- Professionals:Dental hygienists and clinic staff influence patient compliance through recommendation authority. Continuing education partnerships in Nagoya strengthen brand loyalty among clinical intermediaries.
Adults dominate installed base. Seniors are climbing the fastest trajectory.
Distribution Channel:
Channel selection determines margin capture versus volume scale, with digital platforms eroding traditional pharmacy dominance in repeat-purchase categories.
- Online Retail:Auto-replenishment algorithms lock in subscription loyalty for consumables. Seniors in Greater Tokyo show highest platform retention for scheduled delivery cycles.
- Supermarkets:Mass-market SKUs compete on price transparency and promotional intensity. Standard fluoride formulations dominate shelf space in suburban locations.
- Pharmacies:Preventive care bundles now dominate procurement in Greater Tokyo. Loyalty-program discounts assemble toothpaste-floss-rinse combinations that fragment single-item trade investments.
- Convenience Stores:Impulse-oriented SKUs target commuter corridors with travel-size formats. Hokkaido's rural network resists bundling shifts, maintaining fragmented stocking patterns.
Pharmacies dominate installed base. Online retail is gaining share fastest.
Ingredient Type:
Regulatory classification intensity varies across this dimension, with therapeutic claims triggering extended PMDA review timelines.
- Natural:Plant-derived extracts appeal to sustainability-conscious segments. METI packaging convergence favors biodegradable material sourcing from domestic polymer specialists.
- Fluoride:Industrial-grade sodium fluoride concentrates arrive primarily from Chinese processors, elevating input cost volatility. Geopolitical friction constrains hedging capacity for domestic formulators.
- Whitening:Benzoyl peroxide concentrations face stricter PMDA scrutiny under 2023 quasi-drug revisions. Reformulation costs compress margin structures for premium tiers.
- Antibacterial:Microbiome safety data requirements now accompany efficacy documentation. Novel actives endure 18-24 month approval bottlenecks that delay revenue recognition.
Fluoride dominates installed base. Natural ingredients are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shinkansen high-speed rail network and Tokyo Bay port infrastructure anchor Japan's oral hygiene distribution architecture, enabling rapid replenishment cycles across the archipelago's dense metropolitan corridors.
Kanto/Tokyo
Greater Tokyo's pharmacy density drives preventive care bundle adoption among aging consumers. METI packaging mandates accelerate lightweight tube redesigns through domestic manufacturing clusters in Saitama and Chiba prefectures. Subscription commerce models capture highest retention for brush-head replacement cycles in the metropolitan area.
Kansai/Osaka
Dental clinic networks in Osaka and Kyoto prescribe antimicrobial rinses for implant maintenance protocols. PMDA quasi-drug oversight shapes formulation investments for clinical-channel products. Smart toothbrush adoption concentrates in Osaka's aging population, driven by dentist recommendations.
Chubu/Nagoya
Continuing education partnerships strengthen brand loyalty among dental hygienists in Aichi prefecture. Toyota Motor Corporation's industrial workforce sustains employer-sponsored dental benefit programs that drive premium product procurement. Manufacturing facilities in Gifu prefecture produce enzymatic formulations for regional distribution.
Kyushu
Rural pharmacy fragmentation forces direct procurement contracts between manufacturers and dental clinics in Fukuoka and Kumamoto. Aging-clinic partnerships bypass retail concentration gaps across the island. METI sustainability guidelines drive refill format trials in regional test markets.
Hokkaido
Low pharmacy density maintains single-item stocking patterns that resist Greater Tokyo's bundling trends. Sapporo's dental clinic networks serve as primary distribution nodes for specialized implant maintenance products. Cold-chain logistics constraints favor domestically manufactured formulations over temperature-sensitive imports.
Japan Oral Hygiene Market Key Industry Players
On the supply side, the industry is consolidating around domestic manufacturing footprints and clinical-channel partnerships. Three strategic archetypes dominate: integrated chemical-to-consumer conglomerates with enzymatic R&D pipelines, multinational FMCG giants leveraging import partnerships for premium tiers, and specialized oral care firms focused on professional endorsement channels. Competitive moves concentrate on pharmacy shelf placement negotiations and sustainability compliance certification.
Among domestic chemical conglomerates, Lion Corporation and Kao Corporation exemplify the integrated archetype through captive manufacturing and formulation science depth. Procter & Gamble Company anchors the multinational import strategy through selective urban retail partnerships. These three occupy distinct competitive positions without direct overlap in channel strategy or price positioning.
| Leading Market Players |
|---|
| Lion Corporation |
| Kao Corporation |
| Procter & Gamble Company |
| Unilever PLC |
| GlaxoSmithKline plc |
| Colgate-Palmolive Company |
| Sunstar Suisse SA |
| Church & Dwight Co., Inc. |
| Johnson & Johnson |
| Others |
Cost & Logistics Intelligence
Fluoride import dependency from Chinese chemical processors compresses margin structures across premium and economy tiers while forcing domestic manufacturers toward lightweight tube formats and refill systems. This single-source vulnerability for sodium fluoride concentrates simultaneously elevates input cost volatility and accelerates sustainability-driven packaging redesign investments.
Pricing Analysis
Volume-discount tiering structures stratify across premium enzymatic formulations, standard fluoride pastes, and economy private-label SKUs. Certification grade under PMDA quasi-drug classification and geographic delivery cost to rural prefectures drive price differentiation. Cost compression in standard tiers is intensifying because of Chinese feedstock volatility. Mass-market supermarket buyers show highest price sensitivity; dental clinic procurement committees exhibit lowest.
Supply Chain Analysis
Upstream feedstock for sodium fluoride concentrates draws primarily from Chinese chemical processors, with secondary sourcing from domestic polymer specialists for PLA-based filaments. Key inputs span industrial-grade fluoride, enzymatic active agents, and biodegradable brush fibers. Single-source vulnerability for fluoride creates tariff exposure and geopolitical risk. Distribution runs through pharmacy chains in Greater Tokyo, direct procurement contracts in Hokkaido, and subscription platforms for repeat consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's oral hygiene sector is entering a cyclical recovery phase as implant maintenance protocols expand clinical-channel recurring revenue beyond retail turnover volatility.
For Market Incumbents: Entrench pharmacy shelf placement through preventive care bundle exclusivity and accelerate METI-compliant lightweight tube manufacturing in Saitama-Chiba clusters. Vertical integration into domestic polymer sourcing for PLA filaments reduces certification risk against nylon import substitution. For New Entrants and Emerging Players: Hokkaido's rural pharmacy fragmentation offers direct procurement contracts with dental clinics as the most penetrable entry vector. Target subscription commerce models for brush-head replacement cycles in Greater Tokyo. Pursue prefecture-level aging-clinic partnerships bypassing retail concentration gaps. For Investors and Strategic Acquirers: The market sits at a premium-therapeutic expansion phase that favors enzymatic R&D specialists with clinical validation pipelines. Long-term viability hinges on PMDA quasi-drug approval capacity and METI sustainability compliance certification. Watch PMDA antibacterial claim review timelines as inflection indicator for revenue recognition velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Formulation R&D Investment | Kao Corporation's clinical validation pipeline accelerates therapeutic claim differentiation against abrasive whitening competitors. |
| Lightweight Tube Manufacturing Scale-Up | Lion Corporation's Saitama-Chiba retooling captures METI compliance leadership and pharmacy chain exclusivity. |
| Prefecture-Level Aging-Clinic Partnership | Hokkaido direct procurement contracts bypass fragmented rural retail and establish recurring clinical-channel revenue. |
| Subscription Commerce Platform Launch | Auto-replenishment algorithms lock in senior retention for brush-head replacement cycles across Greater Tokyo. |
| Biodegradable Filament Certification | PLA-based brush fibers meet METI targets while differentiating against temperature-sensitive nylon imports. |
Research Approach
The analysis maps toothpaste, mouthwash, dental floss, and chewing gum sub-sectors, each validated through formulation chemists, pharmacy category buyers, dental clinic procurement managers, and METI regulatory affairs specialists. Primary interviews with Lion Corporation and Kao Corporation R&D directors combined with secondary validation from PMDA quasi-drug filings, JIS toothbrush filament standards, and METI packaging guidelines. Bottom-up volume triangulation against top-down value estimates anchored the market sizing framework.
Assumptions held fluoride import dependency ratios and PMDA review timelines constant while varying senior population growth rates and subscription commerce penetration curves across the projection horizon. Segmentation dimensions modeled include product type, end-user demographic, distribution channel, and ingredient classification. CAGRs derived from historical pharmacy audit data and dental clinic procurement survey trends, with enzymatic formulation adoption curves and implant maintenance protocol expansion as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by multinational FMCG giants or domestic chemical conglomerates would shift outcomes. Quarterly review of PMDA quasi-drug approval velocities and METI packaging compliance certification rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oral Care
Herbal Toothpaste Market
Oral Care
LED Oral Care Kits Market
Oral Care
Global Oral Hygiene Market
Oral Care
South America Oral Care Market
Oral Care
Oral Hygiene Products Market
Oral Care
Children's Oral Care Market
Oral Care
Dry Mouth Relief Market
Oral Care
China Oral Care Market
Oral Care
Ayurvedic Toothpaste Market
Oral Care
Oral Irrigator Market
Oral Care
Kids Toothpaste Market
Oral Care
Middle East and Africa Oral Care Market
Oral Care
North America Oral Care Market
Oral Care
BRICS Oral Care Market
Oral Care
Global Oral Care Products Market
Oral Care
Baby Teeth Care Products Market