
 India Rice Seed Market | 2026-2036
India Rice Seed Market Size, Share, and Industry Trends Forecast 2026-2036
India Rice Seed Market Foresight
ICAR's mandatory Nucleus Seed Certification is reorganizing which breeders can commercialize new varieties. Kaveri Seeds leverages its in-house parental line development to sustain germplasm control across South India. Mahyco anchors the central Indian market through deep distribution into Maharashtra and Madhya Pradesh cooperatives. Nuziveedu Seeds competes on volume scale, extending its reach into eastern rice belts through wholesale channel density.
India rice seed comprises genetically improved propagules bred for specific agro-climatic zones, with hybrid varieties requiring controlled crossing between cytoplasmic male sterile lines and restorer parents to exploit heterosis for yield gains of 15-25% over open pollinated types. The product category splits into hybrid seeds, open pollinated varieties, basmati seeds, and aromatic seeds, with hybrid seeds commanding premium positioning due to recurring purchase cycles and proprietary parentals, while basmati seeds retain stable margin pools linked to export-parity pricing and Geographical Indication enforcement. End user demand flows through farmers, agricultural corporations, government agencies, and seed distributors, with government agencies driving volume through subsidized distribution schemes and farmers capturing the fastest growth shift toward branded hybrid replacements.
BIS seed standards, CDSCO biosafety protocols for transgenic trials, and state-level Seed Inspectorate enforcement collectively shape market access and product liability exposure for breeders operating across Indian territory. The Plant Variety Protection and Farmers' Rights Act creates dual pressure on royalty structures while enabling farmer-saved seed exemptions that constrain hybrid monetization. Stakeholders must monitor how the proposed Seed Bill amendments alter variety registration timelines and enforcement mechanisms across state agriculture departments.
Market Dynamics
ICAR's mandatory Nucleus Seed Certification is compressing commercialization timelines for new rice varieties while concentrating breeding authority among institutional players with certified infrastructure. This regulatory pivot is restructuring competitive access across India's rice seed value chain.
Growth Catalysts
- Subsidy-Driven Hybrid Conversion:State agriculture departments in Telangana and Andhra Pradesh are expanding subsidized distribution schemes that accelerate farmer replacement of open-pollinated varieties with certified hybrid seeds.
- Export-Parity Basmati Premiums:Geographical Indication enforcement for basmati cultivation in Punjab and Haryana is sustaining margin pools that attract breeding investment toward aromatic specialty lines.
- Kharif Sowing Intensification:Irrigated acreage expansion across the Godavari delta and Krishna basin is concentrating demand for high-yield hybrid varieties suited to controlled water regimes.
Market Restraints
- Parental Line Supply Concentration:Cytoplasmic male sterile germplasm development remains concentrated among a narrow base of institutional breeders with ICAR-linked research stations.
- Seed Replacement Rate Volatility:Farmer-saved seed exemptions under the Plant Variety Protection and Farmers' Rights Act constrain recurring revenue capture for proprietary hybrid developers.
- Biosafety Protocol Friction:CDSCO transgenic trial requirements impose extended field-evaluation timelines that delay biotech trait commercialization for stress-tolerant rice lines.
Strategic Opportunities
- Eastern Belt Channel Penetration:Wholesale distributor density remains underdeveloped in Odisha and West Bengal, creating whitespace for volume-scale players to establish procurement relationships with state seed corporations.
- Direct-to-Farmer Digital Platforms:Agri-tech marketplaces are emerging as alternative seed procurement channels that bypass traditional mandi-based distributor networks in Maharashtra and Madhya Pradesh.
- Climate-Adaptive Trait Development:BIS seed standards for drought and salinity tolerance are creating certification pathways that reward breeders with advanced molecular marker capabilities.
Industry Challenges
- Certification Timeline Compression:Variety registration requirements under the Seed Act are extending from multi-season DUS testing to mandatory Nucleus Seed Certification, straining breeder field-station capacity.
- Seed Inspectorate Enforcement Variability:State-level compliance intensity differs across Seed Inspectorate jurisdictions, creating liability exposure for national distributors operating across multiple agriculture departments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Rice Seed Market |
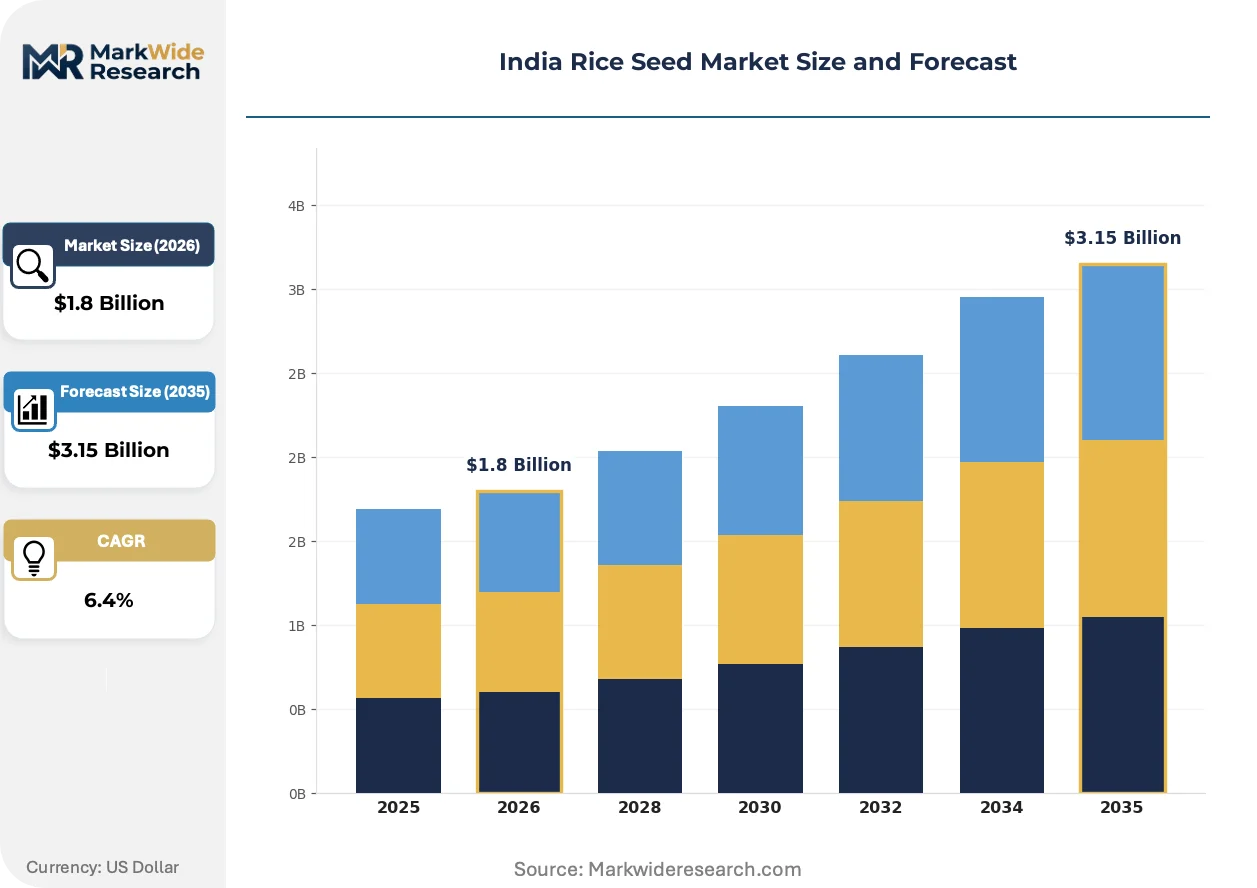
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hybrid Seeds, Open Pollinated Varieties, Basmati Seeds, Aromatic Seeds End User: Farmers, Agricultural Corporations, Government Agencies, Seed Distributors Packaging Type: Bags, Bulk Containers, Boxes, Retail Packs Distribution Channel: Retail Stores, E-Commerce, Wholesalers, Cooperative Societies |
| Companies Covered | Kaveri Seeds, Nuziveedu Seeds Ltd, Maharashtra Hybrid Seeds Co. (Mahyco), Rasi Seeds Private Limited, Advanta Seeds - UPL, Syngenta Group, Bayer AG, Corteva Agriscience, DCM Shriram Ltd (Bioseed), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Rice Seed Market Shifts & Advancements
Marker-assisted selection and genomic prediction tools are compressing breeding cycles while digital traceability platforms are reshaping how seed quality assurance flows from nucleus to certified commercial lots.
Genomic selection platforms incorporating genome-wide association studies are fragmenting traditional pedigree-based breeding programs. Progressive state seed corporations in Telangana and Karnataka are piloting these tools for accelerated line fixation. The technology is fragmenting germplasm control by enabling smaller breeding operations to compete on trait precision without multi-decade parental line accumulation.
BIS seed standards revision for minimum genetic purity thresholds is tightening enforcement protocols across state Seed Inspectorates. The regulation is elevating laboratory testing infrastructure requirements for all commercial seed lots. Small and mid-scale seed processors in eastern India are responding by consolidating testing contracts with centralized ICAR-accredited laboratories.
Farmer procurement behavior is rotating toward branded hybrid replacements with verifiable certification documentation. Traditional commission-based mandi intermediaries in Punjab and Haryana are losing volume to cooperative-direct and agri-retail channels. This shift is most visible among commercial rice farmers with above-ten-hectare holdings who prioritize traceable germplasm origin for export-linked basmati cultivation.
India Rice Seed Market Segmentation
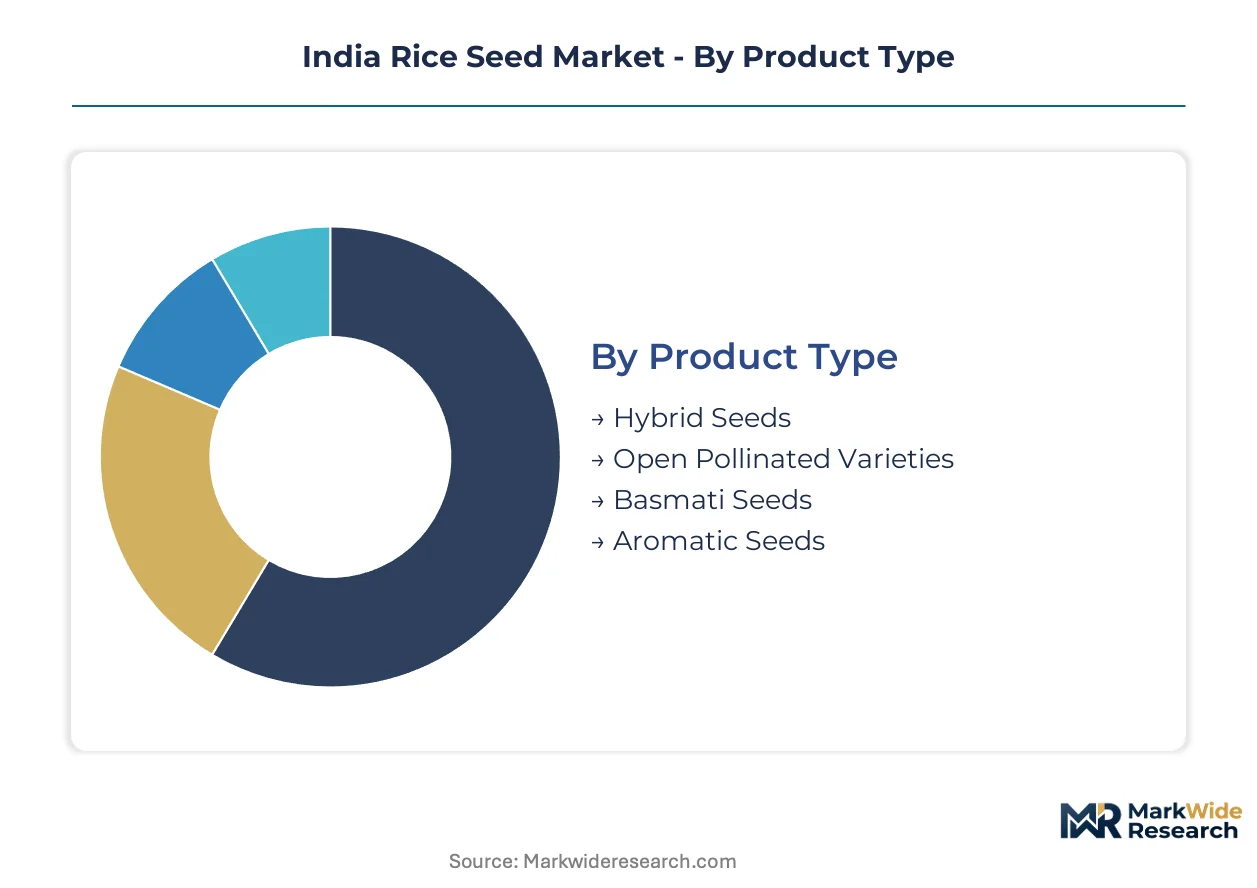
Segmentation in India's rice seed market reveals how regulatory pressure and procurement channel evolution are reshaping competitive access. Breeders must align product portfolios with specific farmer categories and state-level distribution infrastructures to capture recurring revenue streams.
Product Type:
Hybrid seeds face the most acute substitution threat from farmer-saved open-pollinated varieties, forcing proprietary breeders to defend germplasm control through certification-linked pricing.
- Hybrid Seeds:Genetically improved propagules bred through controlled crossing of cytoplasmic male sterile lines with restorer parents to exploit heterosis for yield advantages. Demand concentrates among commercial farmers in Telangana and Andhra Pradesh where subsidized distribution schemes accelerate replacement cycles, though parental line supply concentration limits new entrant participation.
- Open Pollinated Varieties:Self-fertile rice lines allowing farmer seed saving across generations without yield collapse. Procurement dominates in Odisha and West Bengal where smallholder economics favor saved-seed economics over recurring hybrid purchases, constraining proprietary breeder market access.
- Basmati Seeds:Aromatic long-grain varieties with Geographical Indication protection in Punjab and Haryana.
- Aromatic Seeds:Specialty fragrance lines including non-basmati regional types like Kalanamak and Gobindobhog.
Open pollinated varieties retain volume leadership across India's rice acreage; hybrid seeds hold the steepest expansion curve as state subsidy programs deepen penetration.
End User:
Customer type segmentation tracks how procurement authority is migrating from government intermediaries toward direct farmer decision-making with rising commercial holding sizes.
- Farmers:Individual cultivators ranging from marginal subsistence operators to commercial enterprises exceeding ten hectares. Above-ten-hectare operators in Punjab and Haryana increasingly demand traceable germplasm documentation for export-linked basmati cultivation, shifting procurement toward cooperative-direct and agri-retail channels.
- Government Agencies:State agriculture departments and seed corporations managing subsidized distribution schemes. Telangana and Andhra Pradesh departments drive the highest hybrid seed volumes through targeted kharif sowing programs, creating concentrated demand spikes that strain breeder production planning.
- Agricultural Corporations:Integrated farming enterprises and contract cultivation aggregators.
- Seed Distributors:Licensed mandi intermediaries and wholesale channel operators.
Government agencies retain volume leadership through subsidy program scale; farmers are climbing the fastest as procurement authority shifts toward direct branded purchases.
Packaging Type:
Packaging segmentation reflects cost tier differentiation between institutional bulk procurement and smallholder retail accessibility.
- Bulk Containers:Large-format packaging for state seed corporation procurement and agricultural corporation orders. Concentrated demand flows through Telangana and Andhra Pradesh state agriculture departments where kharif sowing intensification requires volume-scale logistics coordination.
- Bags:Standardized woven polypropylene units of 10-40kg for cooperative society distribution. Maharashtra and Madhya Pradesh cooperatives anchor central Indian demand through deep distribution networks into tier-2 mandi towns.
- Retail Packs:Small-unit packaging for individual farmer counter sales.
- Boxes:Rigid packaging for premium basmati and aromatic specialty lines.
Bags retain volume leadership through cooperative channel dominance; bulk containers are gaining share fastest as state procurement centralizes.
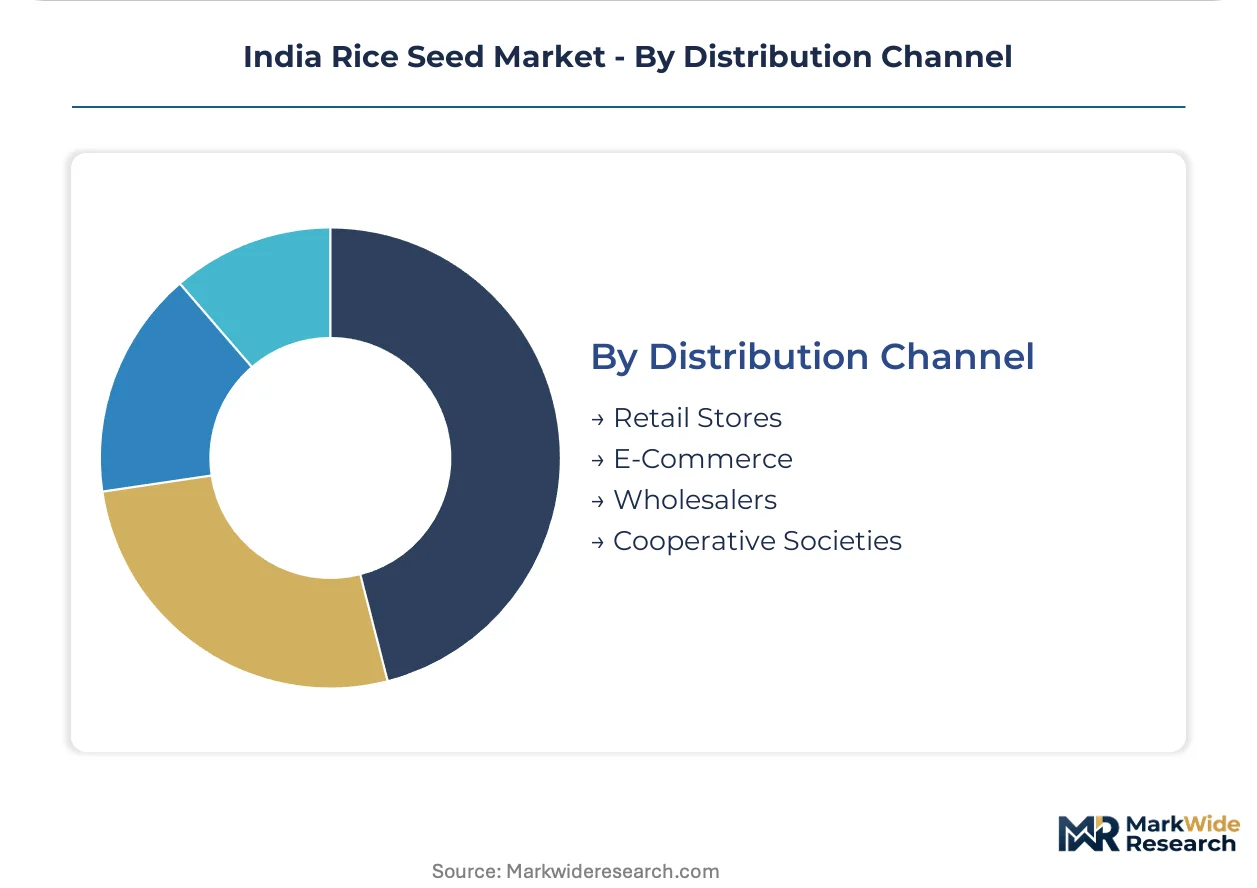
Distribution Channel:
Channel segmentation captures the displacement of traditional mandi intermediaries by digital platforms and cooperative-direct structures.
- Cooperative Societies:Farmer-owned procurement organizations with state-backed credit linkages. Maharashtra and Madhya Pradesh cooperatives anchor central Indian market access for Mahyco and similar breeders, offering volume concentration that reduces customer acquisition costs compared to fragmented retail networks.
- Wholesalers:Volume aggregators supplying sub-distributor networks across eastern rice belts. Odisha and West Bengal wholesale density remains underdeveloped, creating whitespace for Nuziveedu Seeds and volume-scale competitors to establish direct state seed corporation relationships.
- Retail Stores:Physical agri-input shops in mandi towns and rural centers.
- E-Commerce:Emerging agri-tech marketplaces enabling direct-to-farmer seed procurement.
Cooperative societies retain volume leadership in subsidized segments; e-commerce is expanding most quickly as Maharashtra and Madhya Pradesh farmers bypass traditional mandi networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial rice farmers with above-ten-hectare holdings concentrate procurement authority in Punjab and Haryana, while state agriculture departments drive volume through subsidized distribution schemes in Telangana and Andhra Pradesh. Smallholder economics favor saved-seed procurement across Odisha and West Bengal, fragmenting demand patterns across India's rice seed geography.
Punjab
Export-linked basmati cultivation anchors demand for traceable germplasm documentation among large commercial operators. BIS seed standards enforcement through the state Seed Inspectorate tightens certification requirements for aromatic specialty lines. The Amritsar-Jalandhar belt concentrates breeding investment toward Geographical Indication-protected varieties.
Haryana
Geographical Indication enforcement sustains premium margin pools that attract proprietary breeding programs. The Plant Variety Protection and Farmers' Rights Act creates dual pressure on royalty structures while enabling farmer-saved seed exemptions. Karnal and Kurukshetra districts host the highest density of certified basmati seed processing infrastructure.
Telangana
Subsidized distribution schemes through the state agriculture department accelerate replacement of open-pollinated varieties with certified hybrid seeds. Kharif sowing intensification across the Godavari delta concentrates demand for high-yield hybrid varieties suited to controlled water regimes. ICAR-linked research stations in Hyderabad anchor parental line development for cytoplasmic male sterile germplasm.
Andhra Pradesh
Irrigated acreage expansion in the Krishna basin drives procurement volume through state seed corporation channels. CDSCO biosafety protocols for transgenic trials impose extended field-evaluation timelines for stress-tolerant rice lines. The Guntur-Vijayawada corridor hosts expanding wholesale distributor density for volume-scale hybrid seed movement.
West Bengal
Smallholder saved-seed economics constrain proprietary breeder market access across marginal subsistence operations. Wholesale channel density remains underdeveloped, creating whitespace for volume-scale players to establish direct state seed corporation relationships. The Burdwan-Birbhum rice belt sustains open-pollinated variety dominance through multi-generation farmer seed saving.
India Rice Seed Market Competitive Landscape
Player mix skews toward domestic institutional breeders with ICAR-linked infrastructure and multinational agricultural science corporations with global germplasm libraries. Market structure concentrates breeding authority among certified nucleus seed producers while fragmenting downstream distribution through state seed corporations and cooperative societies. Two strategic archetypes dominate: proprietary hybrid developers defending germplasm control through parental line exclusivity, and volume-scale open-pollinated variety suppliers competing on wholesale channel density. Competitive moves center on backward integration into captive parental line development and geographic expansion through state agriculture department procurement relationships.
Within the domestic institutional tier, Kaveri Seeds and Nuziveedu Seeds occupy positions shaped by in-house breeding infrastructure and distribution reach across southern and eastern rice belts respectively. Mahyco represents the central Indian anchor archetype, with cooperative-linked distribution networks into Maharashtra and Madhya Pradesh. These three exemplify how germplasm control strategies diverge between proprietary hybrid concentration and volume-scale open-pollinated market presence.
| Leading Market Players |
|---|
| Kaveri Seeds |
| Nuziveedu Seeds Ltd |
| Maharashtra Hybrid Seeds Co. (Mahyco) |
| Rasi Seeds Private Limited |
| Advanta Seeds - UPL |
| Syngenta Group |
| Bayer AG |
| Corteva Agriscience |
| DCM Shriram Ltd (Bioseed) |
| Others |
Supply & Pricing Matrix
Ninety-day nucleus seed certification lead times compress breeder field-station capacity and concentrate pricing power among ICAR-linked institutional players with certified infrastructure. This temporal constraint reshapes margin capture across hybrid and basmati tiers while amplifying cost pass-through vulnerability for smaller processors lacking captive parental line development.
Pricing Analysis
Cost-plus contracts with BIS seed standard indexation dominate procurement between state seed corporations and certified breeders. Pricing stratifies across premium, standard, and economy tiers based on genetic purity certification grade and volume scale commitments. Cost compression in the standard tier is intensifying because farmer-saved seed exemptions under the Plant Variety Protection and Farmers' Rights Act constrain recurring hybrid monetization. Smallholder farmers in Odisha and West Bengal exhibit highest price sensitivity, while commercial operators above ten hectares in Punjab and Haryana absorb premium documentation costs for export-linked basmati traceability.
Supply Chain Analysis
Inbound logistics costs from Visakhapatnam and Kakinada port congestion strain seed movement into the Godavari delta and Krishna basin catchments. Parental line development concentrates in India, with cytoplasmic male sterile germplasm anchored at ICAR-linked research stations in Hyderabad and select university breeding programs. The supply chain draws from captive nucleus seed production, certified breeder seed multiplication, and commercial foundation seed processing as sequential inputs. Single-source vulnerability sits with concentrated cytoplasmic male sterile line supply among institutional breeders. Distribution runs through state seed corporations, cooperative societies, and emerging agri-tech marketplaces as parallel downstream structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement authority is concentrating among commercial farmers with expanding holding sizes and state agriculture departments with centralized subsidy schemes, fragmenting traditional mandi intermediary influence. This buyer-power shift rewards breeders with direct institutional relationships and traceable certification documentation.
For Market Incumbents: Fortify germplasm control through backward integration into captive parental line development, particularly cytoplasmic male sterile restorer systems that constrain new entrant replication. Expand certified field-station capacity in Telangana and Andhra Pradesh to compress ICAR Nucleus Seed Certification timelines and defend position against emerging genomic selection platforms that fragment traditional pedigree-based breeding programs. For New Entrants and Emerging Players: Digital traceability platform deployment represents a service-layer gap where incumbents under-serve smallholder verification needs in Odisha and West Bengal. Target wholesale channel density buildout in eastern rice belts where state seed corporation relationships remain underdeveloped. Pursue cooperative-direct procurement partnerships as the primary go-to-market angle, bypassing commission-based mandi intermediaries that lose volume to traceable agri-retail channels. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across certified laboratory testing infrastructure as BIS genetic purity threshold revisions elevate enforcement protocols. Long-term viability over the projection horizon favors acquisition targets with ICAR-accredited nucleus seed production capacity and established state agriculture department procurement relationships. Monitor Seed Bill amendment progression through parliamentary committee review as the critical inflection signal for variety registration timeline compression and enforcement mechanism shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Parental Line Development | Secures germplasm exclusivity against genomic selection platform disruption in South India. |
| State Seed Corporation Procurement Partnerships | Locks volume concentration through subsidized distribution schemes in Telangana and Andhra Pradesh. |
| ICAR-Accredited Laboratory Testing Consolidation | Captures BIS enforcement elevation as small processors outsource genetic purity verification. |
| Direct-to-Farmer Digital Platform Deployment | Bypasses mandi intermediary erosion in Maharashtra and Madhya Pradesh cooperative channels. |
| Climate-Adaptive Trait Certification Investment | Exploits BIS drought and salinity tolerance standards rewarding molecular marker capabilities. |
Research Methodology
Cross-validation between primary interviews with rice seed breeders, state seed corporation procurement officers, and cooperative society managers anchors the qualitative findings against secondary sources including BIS seed standard notifications, ICAR variety release registers, and state agriculture department subsidy disbursement records. Bottom-up triangulation from breeder production capacity and top-down validation from acreage conversion estimates frame the quantitative envelope.
Sensitivity analysis around Seed Bill amendment scenarios and farmer-saved seed exemption scope shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, end user procurement authority, packaging format scale, and distribution channel structure. CAGRs derive from breeder shipment tracking, state seed corporation offtake volumes, and kharif sowing intensity indices. Forecast inputs incorporate ICAR certification timeline elasticity and CDSCO biosafety protocol friction for transgenic trait commercialization.
Underlying assumptions cover stable BIS genetic purity enforcement intensity and continued state subsidy program scale, with deviation risk concentrated in Seed Inspectorate jurisdictional variability and Plant Variety Protection Act amendment outcomes. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Global Forage Sorghum Seed Market
Seeds
Middle East and Africa Cannabis Seeds Market
Seeds
Global Sunflower Seed (Seed for Sowing) Market
Seeds
Indonesia Seeds Market
Seeds
Hybrid Rice Seeds Market
Seeds
Global Onion Seed Market
Seeds
Asia-Pacific Onion Seed Market
Seeds
Sprouted Grains and Seeds Market
Seeds
Uganda Seeds Market
Seeds
Seed Health Market
Seeds
Mexico Vegetable Seed Market
Seeds
South America Seed Market
Seeds
South America Vegetable Seed Market
Seeds
Europe Sesame Seed Market
Seeds
Global Forage Seeds Market
Seeds
Dragon Fruit Seeds Market