
 Chia Seeds Market | 2026-2036
Chia Seeds Market Size, Share, and Industry Trends Forecast 2026-2036
Chia Seeds Market Analysis
USDA Organic certification is rotating competitive advantage toward processors with verified supply chain documentation. Nutiva leverages its vertically controlled sourcing network across Latin American growing regions. The Chia Co anchors its position through varietal specialization and strict cultivar traceability. Benexia competes on omega-3 content consistency achieved through proprietary seed selection protocols.
Chia seeds are the edible seeds of Salvia hispanica, an annual herb in the mint family containing approximately 30% oil by weight with alpha-linolenic acid comprising over 60% of total fatty acid content. These seeds function primarily as a functional food ingredient, delivering gel-forming soluble fiber and complete plant protein for human and animal nutrition applications. Organic chia seeds command premium positioning due to limited certified acreage and multi-year conversion requirements for farmland. The food and beverage application segment leads volume absorption, while nutraceuticals represent the fastest-growing margin pool as extraction technologies improve bioactive compound recovery. Distribution through online retail channels is accelerating, though supermarkets still control the majority of consumer touchpoints for packaged chia products.
The USDA National Organic Program governs labeling and import verification for organic chia entering the United States, while the EU Green Deal's deforestation regulation is reshaping traceability obligations for South American suppliers. India's FSSAI has tightened maximum residue limits for imported seeds, creating compliance hurdles for smaller exporters. Stakeholders must monitor evolving pesticide tolerance harmonization between major import jurisdictions and invest in blockchain-enabled provenance systems before regulatory divergence hardens into market access barriers.
Market Dynamics
EU Green Deal deforestation regulations are forcing traceability system upgrades across Latin American supply chains before the compliance deadline arrives. Certified organic acreage scarcity is concentrating negotiating power with established processors who control multi-year farmland conversion pipelines.
Growth Catalysts
- EU Deforestation Regulation:Mandatory geolocation tracking for agricultural imports is accelerating blockchain adoption among South American cooperatives seeking market access.
- Functional beverage formulation:Gel-forming hydrocolloid properties are driving chia integration into ready-to-drink smoothie and plant-milk product lines.
- Germany:Premium private-label manufacturers are expanding chia inclusion in fortified bakery and dairy-alternative portfolios.
Market Restraints
- Input cost volatility:Organic fertilizer and irrigation energy costs fluctuate with natural gas pricing in Argentina and Paraguay growing regions.
- Supply concentration:Over 80% of organic chia originates from a narrow band of Bolivian and Argentine highland farms.
- Substitution threat:Flaxseed and hemp seed processors are matching omega-3 claims at lower price points in mass-market retail.
Strategic Opportunities
- India:FSSAI import clearance bottlenecks favor early entrants who establish residue-testing protocols ahead of smaller competitors.
- Pet nutrition:Premium companion animal food brands are adopting chia for coat-conditioning claims in functional treat formulations.
- Clean-label convergence:Dual certification for organic and non-GMO verification opens shelf placement in European discounter chains.
Industry Challenges
- Certification timeline compression:USDA Organic and EU organic equivalence audits now require 18-24 months for new supplier onboarding.
- Genetic IP fragmentation:Proprietary cultivar development programs face patent thickets around Salvia hispanica varietal improvements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chia Seeds Market |
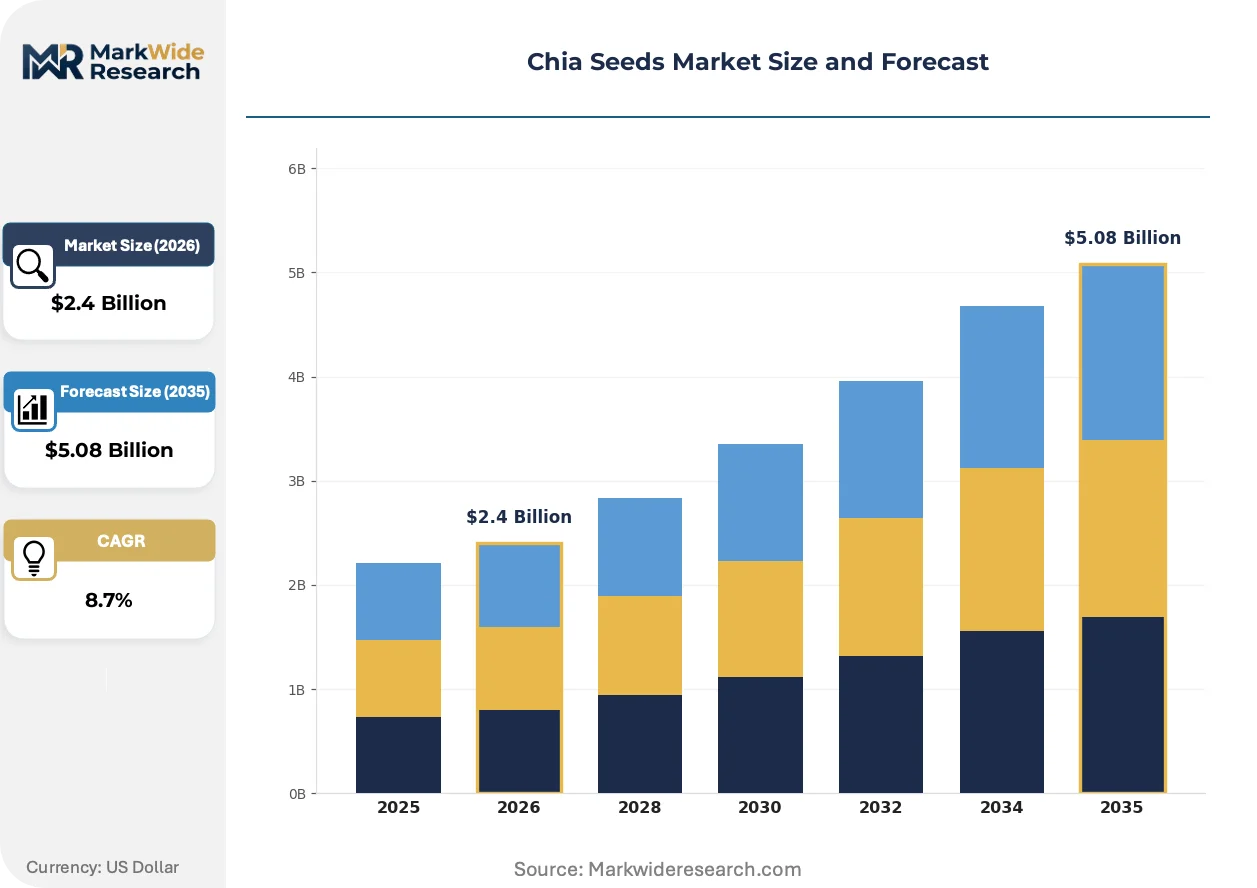
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Black Chia Seeds, White Chia Seeds, Organic Chia Seeds, Conventional Chia Seeds Application: Food & Beverage, Nutraceuticals, Personal Care, Animal Feed End User: Retail Consumers, Food Manufacturers, Health Food Stores, Restaurants Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Nutiva, The Chia Co, Benexia, Mamma Chia, Navitas Organics, Glanbia, Spectrum Organic Products, Salba Smart Natural Products, Healthworks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chia Seeds Market Emerging Trajectories
Processing technology advances are compressing extraction costs for bioactive compounds while regulatory traceability mandates reshape supplier qualification workflows. Demand-side experimentation with novel application formats is expanding beyond traditional food and beverage channels.
Supercritical CO2 extraction systems for chia oil are miniaturizing from industrial-scale installations to modular units suitable for mid-size processors. Nutraceutical contract manufacturers in Germany and California are adopting these compact systems to produce cold-pressed omega-3 concentrates for supplement encapsulation. The technology is miniaturizing capital barriers, enabling regional processors to bypass centralized oil refining infrastructure.
EU Green Deal deforestation regulations now require polygon mapping of all agricultural plots exceeding 4 hectares for imported commodities. Latin American exporters are deploying satellite-verified farm boundary documentation to satisfy EUDR due diligence obligations. German importers are consolidating supplier relationships to reduce audit burden, favoring cooperatives with pre-established traceability infrastructure.
Direct-to-consumer subscription models for chia-based meal kits are displacing conventional retail purchasing among urban health-conscious demographics. Specialty e-commerce platforms in the United States and United Kingdom are bundling recipe content with recurring seed deliveries. This channel shift is most pronounced in metropolitan areas where convenience positioning outweighs price sensitivity for pantry staples.
Chia Seeds Market Segmentation
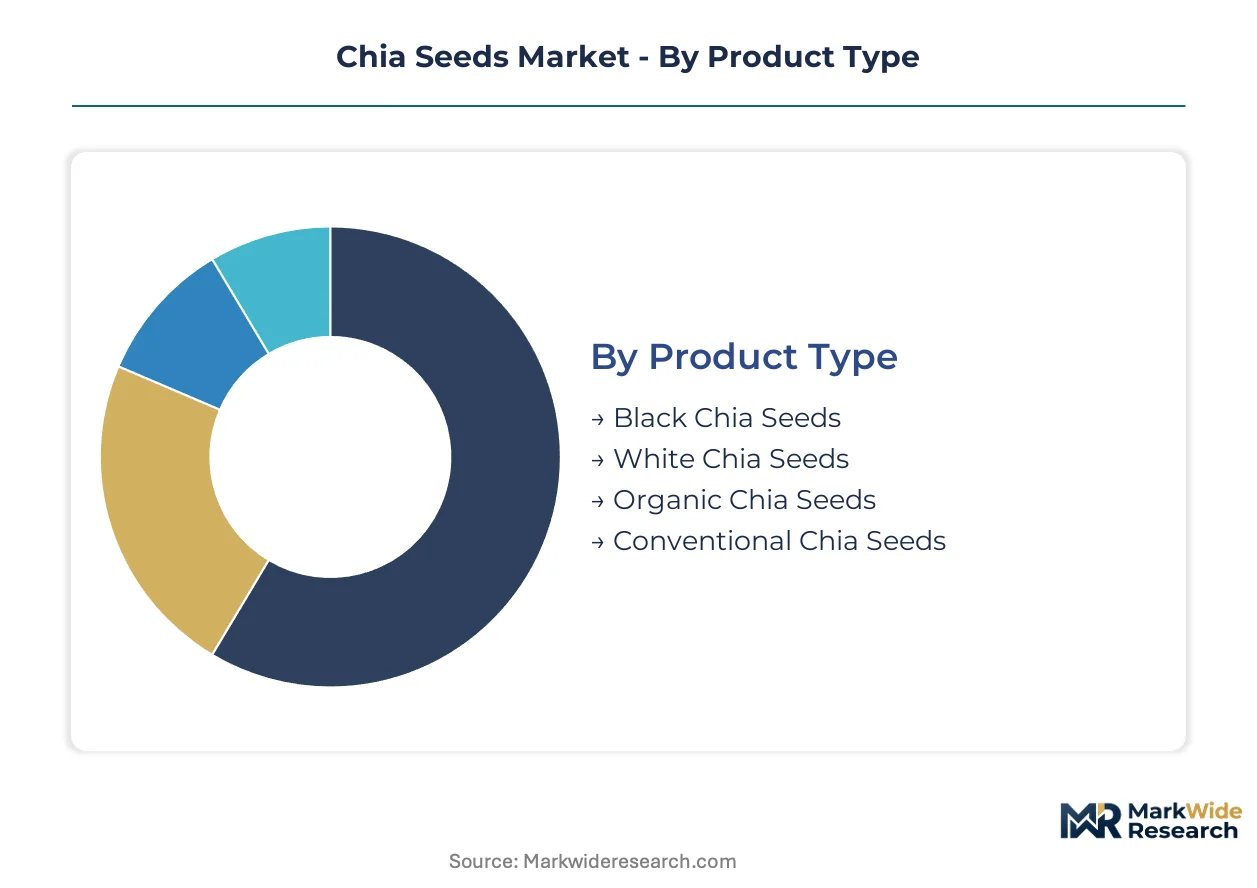
Chia seed commercialization splits across certification tiers, formulation requirements, and channel economics. Each segmentation axis carries distinct margin profiles and regulatory exposure that reshape supplier qualification workflows.
Product Type:
USDA Organic and EU organic equivalence protocols create divergent compliance burdens across seed categories, with multi-year farmland conversion timelines concentrating supply among established processors.
- Black Chia Seeds:Higher anthocyanin content delivers antioxidant positioning for nutraceutical extraction. German functional food manufacturers specify black chia for premium bakery lines targeting clean-label claims. Supply contracts now mandate EU deforestation regulation geolocation documentation.
- Organic Chia Seeds:Certified acreage scarcity in Bolivian and Argentine highlands limits volume expansion. Three-year conversion requirements for farmland lock in supply relationships with processors controlling multi-year pipelines. FSSAI residue testing in India favors early entrants with established protocols.
- White Chia Seeds:Neutral color profile suits beverage applications where visual clarity matters. California smoothie brands specify white chia for ready-to-drink formulations.
- Conventional Chia Seeds:Price-competitive positioning for mass-market retail and animal feed applications. Argentine processors dominate volume supply.
Black chia handles the majority of throughput in premium positioning; organic certification is climbing the fastest on share as clean-label requirements harden.
Application:
Formulation technology advances and extraction cost compression are redrawing segment boundaries as hydrocolloid properties find novel deployment channels.
- Food & Beverage:Gel-forming soluble fiber integrates into plant-milk, smoothie, and fortified bakery applications. Supercritical CO2 extraction miniaturization enables regional omega-3 concentrate production. German private-label manufacturers expand inclusion rates in dairy-alternative portfolios.
- Nutraceuticals:Bioactive compound recovery from chia oil targets supplement encapsulation and functional ingredient markets. Modular extraction systems reduce capital barriers for mid-size processors in Germany and California.
- Personal Care:Omega-3 content supports skin barrier function claims in clean-label cosmetic formulations.
- Animal Feed:Premium companion animal brands adopt chia for coat-conditioning positioning in functional treat lines.
Food and beverage handles the majority of throughput; nutraceuticals is expanding most quickly as extraction yields improve.
End User:
Procurement scale and specification stringency separate institutional buyers from fragmented retail demand, with certification requirements tightening fastest among manufacturers.
- Food Manufacturers:Volume contracting with multi-year supply security requirements and dual organic-non-GMO verification. German and US processors consolidate supplier relationships to reduce audit burden under EU Green Deal traceability mandates.
- Health Food Stores:Shelf space expansion for chia-based products tracks consumer interest in plant-based nutrition. Staff training on omega-3 bioavailability claims differentiates specialty retail from mass-market positioning.
- Retail Consumers:Direct-to-consumer subscription models displace conventional purchasing among urban health-conscious demographics in US and UK metropolitan areas.
- Restaurants:Menu innovation with chia pudding and beverage applications concentrates in premium urban dining clusters.
Food manufacturers handle the majority of throughput; health food stores are gaining share fastest as specialty retail expands chia-dedicated shelf space.
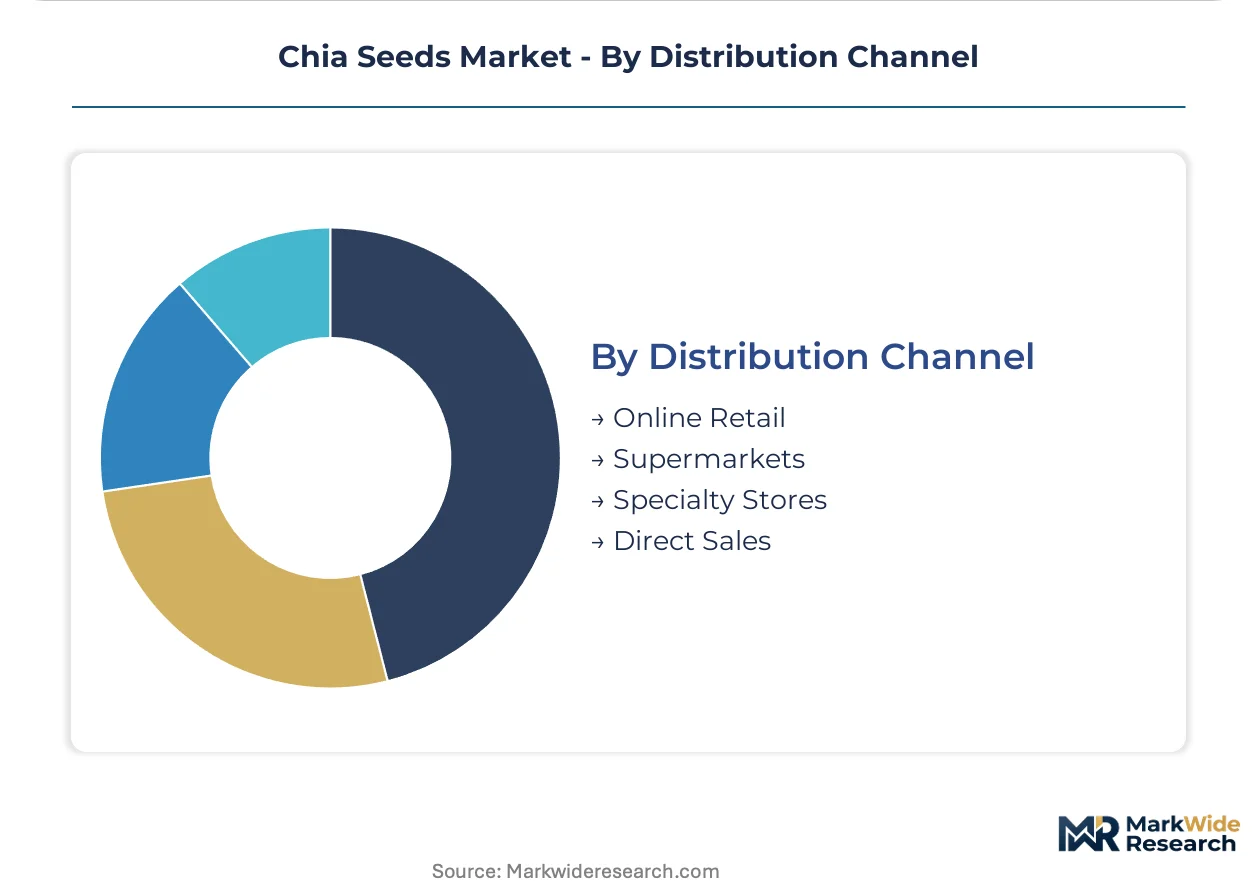
Distribution Channel:
Channel economics reflect fulfillment cost structures and consumer touchpoint control, with digital adoption accelerating fastest where convenience positioning outweighs price sensitivity.
- Supermarkets:Majority consumer touchpoint control for packaged chia products. Category management decisions on shelf placement increasingly favor dual-certified organic and non-GMO SKUs.
- Online Retail:Subscription bundling with recipe content displaces conventional purchasing among urban demographics. Specialty e-commerce platforms in US and UK metropolitan areas lead channel shift.
- Specialty Stores:Staff expertise on cultivar traceability and omega-3 content consistency supports premium pricing.
- Direct Sales:Cooperative and farm-gate purchasing concentrates in community-supported agriculture networks.
Supermarkets handle the majority of throughput; online retail is climbing the fastest on share as subscription models lock in recurring revenue.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health-conscious food manufacturers and premium private-label brands concentrate procurement in Germany, the United States, and India, with regulatory compliance emerging as the primary supplier selection filter across all three markets.
Germany
Premium functional food manufacturers drive demand for black chia with anthocyanin-specific antioxidant claims. EU Green Deal deforestation regulations mandate polygon mapping for all agricultural plots exceeding four hectares. The Baden-Württemberg cluster hosts private-label innovators expanding chia inclusion in fortified bakery and dairy-alternative portfolios.
United States
Direct-to-consumer subscription models and health food store shelf expansion accelerate volume absorption. USDA National Organic Program governs labeling and import verification, with certification timelines now requiring eighteen to twenty-four months for new supplier onboarding. California nutraceutical contract manufacturers adopt modular supercritical CO2 extraction systems for regional omega-3 concentrate production.
India
FSSAI has tightened maximum residue limits for imported seeds, creating compliance hurdles that favor early entrants with established testing protocols. The Maharashtra and Gujarat food processing corridors attract contract manufacturers seeking organic ingredient supply security. Mumbai-based importers consolidate supplier relationships to reduce audit burden under tightening tolerance harmonization.
Argentina
Highland farming regions in the northwestern provinces dominate organic chia acreage, with certified land scarcity concentrating negotiating power among established processors. Organic fertilizer and irrigation energy costs fluctuate with natural gas pricing, pressuring farm-gate economics. The Salta-Tucumán axis anchors multi-year farmland conversion pipelines controlled by vertically integrated exporters.
Bolivia
Andean highland cooperatives deploy satellite-verified farm boundary documentation to satisfy EU deforestation regulation due diligence obligations. The Santa Cruz-Cochabamba corridor supplies the majority of EU-bound organic certified volume. Blockchain-enabled provenance systems differentiate cooperative offerings as German importers consolidate supplier relationships.
Chia Seeds Market Vendor Landscape
Player mix skews toward vertically integrated processors with captive Latin American supply networks and specialized nutraceutical extractors with modular production technology. Three archetypes dominate: established organic certifiers with multi-year farmland conversion pipelines, regional oil processors with supercritical extraction capabilities, and direct-to-consumer brands with subscription-driven recurring revenue models. Competitive moves center on backward integration into highland farming cooperatives and strategic partnerships with German private-label manufacturers seeking dual organic-non-GMO verification.
Within the certified organic tier, Nutiva anchors North American supply security through its vertically controlled sourcing network, while The Chia Co exemplifies varietal specialization with strict cultivar traceability protocols. Benexia occupies a position defined by omega-3 content consistency achieved through proprietary seed selection, representing the extraction-technology-driven competitive vector.
| Leading Market Players |
|---|
| Nutiva |
| The Chia Co |
| Benexia |
| Mamma Chia |
| Navitas Organics |
| Glanbia |
| Spectrum Organic Products |
| Salba Smart Natural Products |
| Healthworks |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts with Argentine and Bolivian cooperatives lock in multi-year supply access while capping price volatility for German and US processors navigating EU deforestation regulation compliance costs. These arrangements tether organic chia premiums to certified acreage scarcity and energy-indexed irrigation inputs.
Pricing Analysis
Cost-plus contracts with natural gas-indexed irrigation energy components dominate Argentine farm-gate arrangements. Three-tier pricing structure across USDA Organic, EU organic equivalence, and conventional grades reflects certification audit burden and farmland conversion timelines. Pricing pressure stems from flaxseed and hemp seed substitution at mass-market retail. Food manufacturers exhibit lowest price sensitivity due to formulation lock-in requirements, while conventional animal feed buyers face highest elasticity.
Supply Chain Analysis
Strategic stockpiling of certified organic inventory precedes EU Green Deal compliance deadlines, while just-in-time logistics serve conventional tier buyers. Bolivia, Argentina, and Paraguay anchor upstream supply. Organic fertilizer, diesel-powered irrigation equipment, and satellite-verified geolocation documentation constitute critical input dependencies. Single-source vulnerability concentrates in the Salta-Tucumán axis. Distribution runs through vertically integrated processors with captive cooperative networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Processors commanding certified organic supply pipelines possess durable advantage as farmland conversion timelines stretch and EU deforestation regulation enforcement hardens. The capability gap sits with blockchain-enabled provenance systems and supercritical extraction infrastructure.
For Market Incumbents: Fortify backward integration into Bolivian highland cooperatives before EU Green Deal audit consolidation accelerates. Expand modular supercritical CO2 extraction capacity in California and Germany to capture nutraceutical margin expansion. Defend against flaxseed substitution by locking in dual organic-non-GMO verification with German private-label manufacturers. For New Entrants and Emerging Players: Differentiate on FSSAI pre-clearance protocols for Indian market entry ahead of residue limit harmonization. Target pet nutrition white space with coat-conditioning formulation partnerships. Pursue direct-to-consumer subscription bundling with recipe content in UK metropolitan corridors. For Investors and Strategic Acquirers: Regional processors with satellite-verified farm boundary documentation and established EU importer relationships represent priority acquisition archetypes. Long-term viability hinges on traceability infrastructure amortization across tightening regulatory jurisdictions. Watch for FSSAI clearance bottlenecks as inflection signal for early-entrant premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Highland Cooperatives | Captures scarce certified organic acreage ahead of EU Green Deal consolidation. |
| Modular Supercritical CO2 Extraction Deployment | Enables regional omega-3 concentrate production for German nutraceutical contract manufacturers. |
| Blockchain-Enabled Provenance System Implementation | Differentiates cooperative offerings under EUDR polygon mapping requirements. |
| FSSAI Pre-Clearance Protocol Establishment | Secures Indian market access ahead of residue limit harmonization deadlines. |
| Direct-to-Consumer Subscription Platform Launch | Locks in recurring revenue from urban health-conscious demographics in US and UK. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across the chia seed value chain, including functional food formulators at German private-label manufacturers, procurement leads at US health food retailers, Bolivian cooperative agronomists, and Indian FSSAI compliance officers. Secondary validation drew from USDA National Organic Program certification databases, EU Green Deal regulatory filings, FSSAI residue limit notifications, and customs trade records. Bottom-up acreage and yield estimates were triangulated against top-down processor volume disclosures.
Across the projection horizon, the analytical framework modeled volume and value outputs by certification tier, application segment, and regional regulatory cluster. CAGRs were derived from segmented growth rate reconciliation against macroeconomic consumption drivers. Forecast inputs incorporated organic farmland conversion pipeline timelines, supercritical extraction technology adoption curves, and EU deforestation regulation compliance cost pass-through assumptions.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement or FSSAI tolerance harmonization trajectories would require recalibration. Forecasts reflect documented assumptions on certified acreage expansion, input cost indexation, and substitution elasticity. Practitioners should keep alternative scenarios live as regulatory divergence and extraction technology miniaturization evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Glycine Soja (Soybean) Seed Extract Market
Seeds
South Africa Forage Seed Market
Seeds
United States Vegetable Seed Market
Seeds
E. Angustifolium Market
Seeds
Myanmar Rice Seed Market
Seeds
China Seed Market
Seeds
Cannabis Seeds Market
Seeds
Guar Market
Seeds
China Vegetable Seed Market
Seeds
India Maize Seed Market
Seeds
Nepal Seeds Market
Seeds
Global Rice Seed Market
Seeds
Flax Crop Market
Seeds
Organic Chia Seeds Market
Seeds
Morocco Seed Market
Seeds
North America Tomato Seed Market