
 Vegetable Seed Protein Market | 2026-2036
Vegetable Seed Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Vegetable Seed Protein Market Analytics
ISO 22000 certification for food safety management systems is collapsing the supplier base as smaller seed processors fail to meet audit requirements. ADM leverages its North American crushing infrastructure to sustain bulk supply contracts with multinational food manufacturers. Roquette Frères anchors European pea protein output through its Vic-sur-Aisne facility, while Cargill competes on global origination networks for non-GMO soybean streams.
Vegetable seed protein denotes protein isolates and concentrates extracted from legume, oilseed, and cucurbit seeds through aqueous or dry-fractionation methods, typically achieving protein contents of 80-90% in isolate form. These ingredients function as emulsifiers, gelling agents, and nutritional fortifiers in formulated foods. Soy protein occupies the largest existing volume pool given decades of infrastructure investment, though pea protein represents the fastest-expanding category as food manufacturers seek allergen-friendly alternatives to soybean. The dietary supplements channel captures premium pricing relative to commodity animal feed applications, with margin concentration in branded isolate grades targeting sports nutrition formulators.
EFSA novel food authorizations govern European market entry for emerging seed sources such as pumpkin and sunflower protein isolates, while FDA GRAS self-determination pathways shape US commercialization timelines for new extraction processes. USDA organic certification and Non-GMO Project verification increasingly function as de facto market access requirements for North American retail placement. Stakeholders must monitor evolving protein digestibility scoring methodologies as FAO guidelines recalibrate nutritional claims frameworks across jurisdictions.
Market Dynamics
ISO 22000 certification requirements are compressing the supplier base for vegetable seed protein, as smaller processors abandon the market rather than absorb food safety audit costs. This concentration dynamic favors capitalized multinationals with existing crushing infrastructure and quality management systems already deployed.
Growth Catalysts
- EFSA Novel Food Pathways:Regulatory clarity for pumpkin and sunflower protein isolates is accelerating European commercialization timelines for emerging seed sources.
- Plant-Based Dairy Formulation:German and Dutch food manufacturers are expanding procurement of pea and fava protein concentrates for clean-label alternative milk products.
- Allergen Substitution Demand:Soy protein displacement in pediatric and sports nutrition applications is pulling volume toward hypoallergenic legume isolates.
Market Restraints
- Input Cost Volatility:Yellow pea and fava bean prices fluctuate with Canadian and Australian harvest cycles, compressing isolate margins unpredictably.
- Supply Concentration Risk:North American crushing capacity for non-GMO soybean streams sits with a handful of integrated processors, creating origination bottlenecks.
- Technical Limitation:Current aqueous fractionation methods struggle to reduce beany off-flavors in pea protein below detection thresholds for neutral applications.
Strategic Opportunities
- Underpenetrated Geographies:Brazilian and Argentine food manufacturers remain reliant on imported soy isolates, creating white space for regional pea protein crushing investment.
- Regulatory Tailwind:USDA organic certification and Non-GMO Project verification are becoming de facto requirements for North American retail placement, rewarding early certifiers.
- Technology Convergence:Dry-fractionation advances combined with enzymatic debittering are opening high-protein concentrate applications previously reserved for isolates.
Industry Challenges
- Protein Digestibility Recalculation:FAO guideline revisions on DIAAS scoring are forcing reformulation of nutritional claims across sports nutrition portfolios.
- Capex Intensity:Aqueous fractionation lines for 90% protein isolates require membrane filtration systems that smaller processors cannot finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegetable Seed Protein Market |
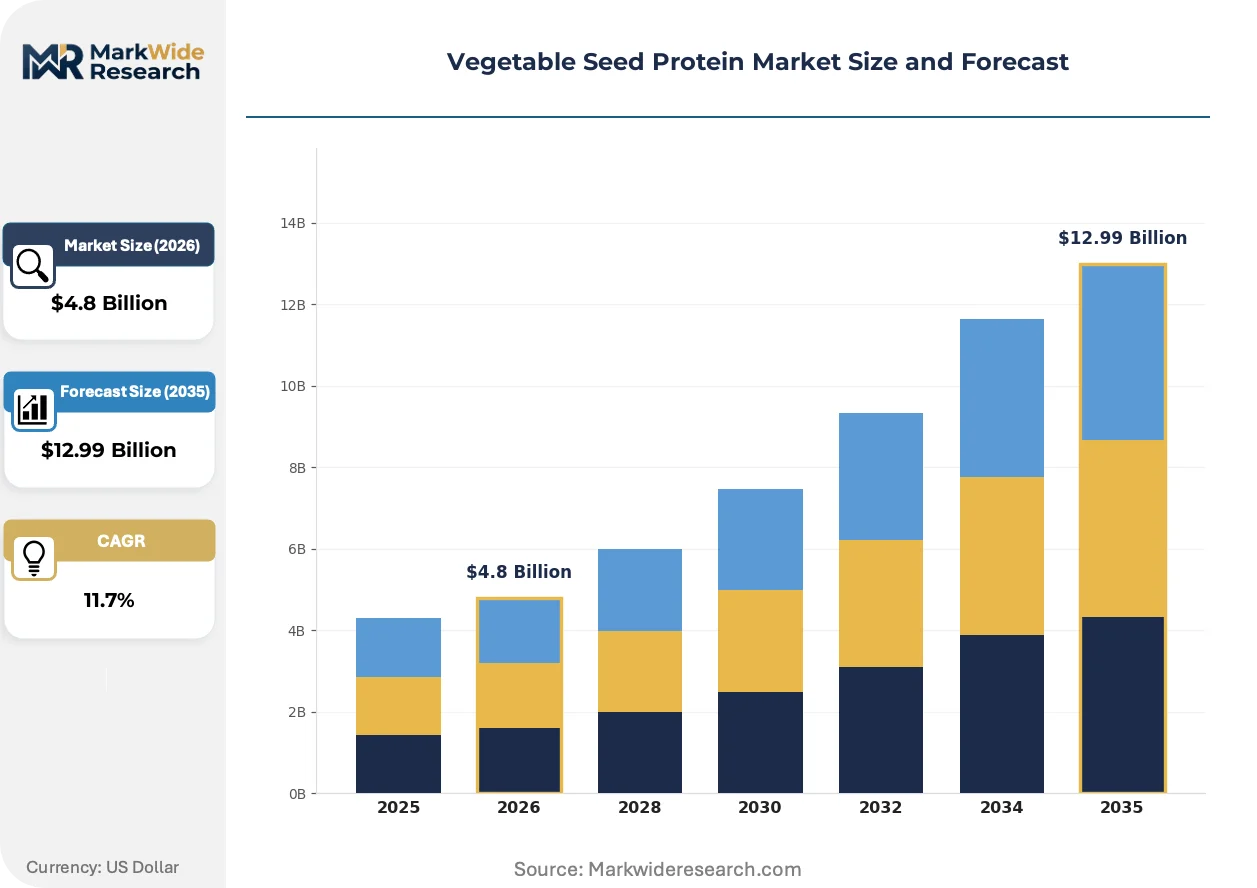
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pea Protein, Soy Protein, Sunflower Protein, Pumpkin Protein Application: Dietary Supplements, Food & Beverages, Animal Feed, Cosmetics End User: Nutritionists, Food Manufacturers, Fitness Experts, Health Enthusiasts Distribution Channel: Online Retail, Supermarkets, Health Stores, Direct Sales |
| Companies Covered | ADM, Roquette Frères, Axiom Foods, Ingredion, DuPont, dsm-firmenich, Cargill, Beneo, PURIS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegetable Seed Protein Market Evolving Landscape
Enzymatic and fermentation-based processing routes are decomposing long-standing barriers between commodity concentrate grades and premium isolate specifications. These technologies are compressing the traditional tiering of protein ingredients.
Precision fermentation of yeast and fungal biomass is decomposing the cost structure of complete protein production. Alternative protein startups in California and Singapore are adopting this route for animal-free whey analogues. The technology is decomposing the historical advantage of soy and pea isolates in amino acid completeness, forcing seed protein suppliers to emphasize sustainability credentials and clean-label positioning rather than nutritional parity alone.
EFSA's tightened novel food evaluation timelines under the 2023 transparency regulation are accelerating dossier preparation costs for emerging seed sources. European applicants now face consolidated scientific opinions that compress technical data requirements into single submissions. Pumpkin and sunflower protein isolates are experiencing the most significant procedural impact, with several German and Dutch ingredient firms restructuring regulatory affairs teams to manage parallel track submissions.
Food manufacturers are consolidating supplier relationships around vertically integrated processors capable of delivering certified organic and non-GMO grades from single origination points. This pattern compresses the vendor list for multinational dairy alternative brands. The shift is most visible in Western European procurement, where clean-label sourcing has become a procurement priority rather than a marketing afterthought.
Vegetable Seed Protein Market Segmentation
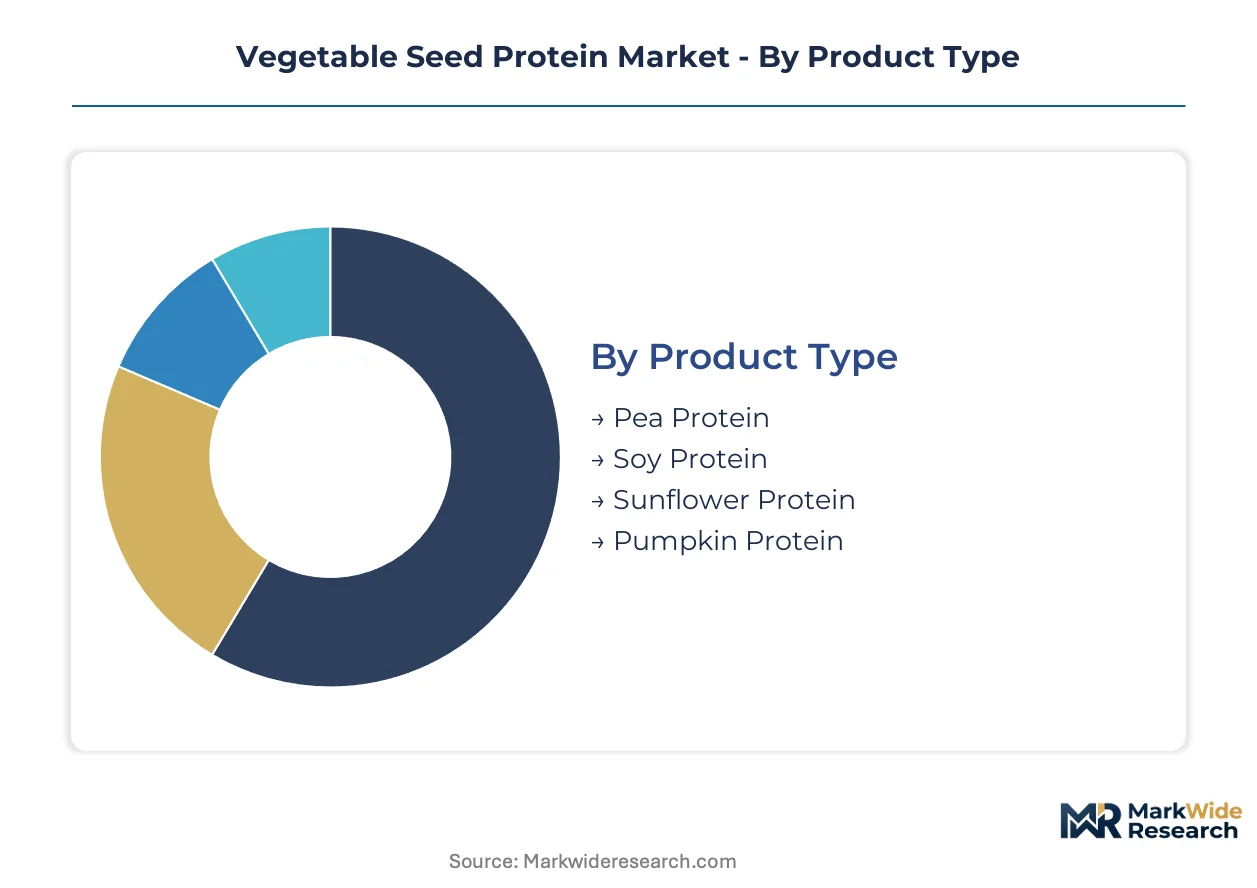
Segmentation in vegetable seed protein markets reveals divergent margin structures across extraction grades and end-use channels. Protein isolate specifications command premium positioning in sports nutrition, while commodity concentrates serve cost-sensitive animal feed applications. Understanding these tiered value pools enables targeted capacity deployment and certification investments.
Product Type:
Margin concentration in vegetable seed protein skews heavily toward isolate grades with 80-90% protein content and documented amino acid profiles.
- Soy Protein:Decades of crushing infrastructure investment have entrenched soy isolates and concentrates as the volume baseline. North American non-GMO origination networks and FDA GRAS determinations sustain bulk supply contracts with multinational food manufacturers. Soy protein occupies the largest existing volume pool, though allergen concerns are displacing share in pediatric and clean-label applications.
- Pea Protein:Aqueous fractionation methods now achieve 80-85% protein concentrates with improved solubility profiles. German and Dutch food manufacturers are expanding procurement for plant-based dairy alternatives amid tightening EFSA novel food pathways. Pea protein represents the fastest-expanding category as manufacturers seek hypoallergenic alternatives to soybean.
- Sunflower Protein:EFSA novel food authorizations are accelerating European commercialization timelines for this emerging isolate source.
- Pumpkin Protein:Dry-fractionation advances are opening high-protein concentrate applications previously reserved for isolates.
Soy protein holds installed capacity across North American crushing infrastructure. Pea protein is rotating up the share rankings in Western European clean-label procurement.
Application:
Application segmentation tracks divergent certification requirements and pricing power across human nutrition versus industrial use cases.
- Dietary Supplements:Branded isolate grades targeting sports nutrition formulators capture premium pricing through USDA organic certification and Non-GMO Project verification. FAO guideline revisions on DIAAS scoring are forcing reformulation of nutritional claims across protein powder portfolios. This channel concentrates margin in precision-blended formulations with documented digestibility metrics.
- Food & Beverages:Plant-based dairy alternatives in Western Europe are driving procurement of pea and fava protein concentrates. Clean-label ingredient sourcing has become a procurement priority rather than a marketing afterthought for German and Dutch manufacturers. ISO 22000 certification requirements are compressing the supplier base as smaller processors abandon food safety audit costs.
- Animal Feed:Commodity concentrate grades serve price-sensitive livestock and aquaculture formulations with minimal certification overhead.
- Cosmetics:Hydrolyzed protein fractions function as film-forming agents in hair and skin care applications with modest volume contribution.
Dietary supplements hold pricing power through certification stacking. Food & beverages is rotating up the share rankings as dairy alternative brands consolidate supplier relationships.
End User:
End user segmentation reflects divergent technical sophistication in protein specification and formulation requirements.
- Food Manufacturers:Multinational dairy alternative brands are consolidating procurement around vertically integrated processors capable of delivering certified organic and non-GMO grades from single origination points. These stakeholders demand aqueous fractionation lines with membrane filtration systems for 90% protein isolates.
- Nutritionists:Clinical and sports nutrition professionals specify protein ingredients based on amino acid completeness and digestibility scoring methodologies.
- Fitness Experts:Influencer-driven recommendation patterns favor branded isolate grades with transparent supply chain documentation.
- Health Enthusiasts:Direct-to-consumer purchasing concentrates in online retail channels with preference for allergen-friendly legume sources.
Food manufacturers hold procurement volume concentration. Health enthusiasts are rotating up the influence rankings through direct-to-consumer channel growth.
Distribution Channel:
Channel segmentation tracks the shift from traditional wholesale toward certified direct relationships and digital commerce.
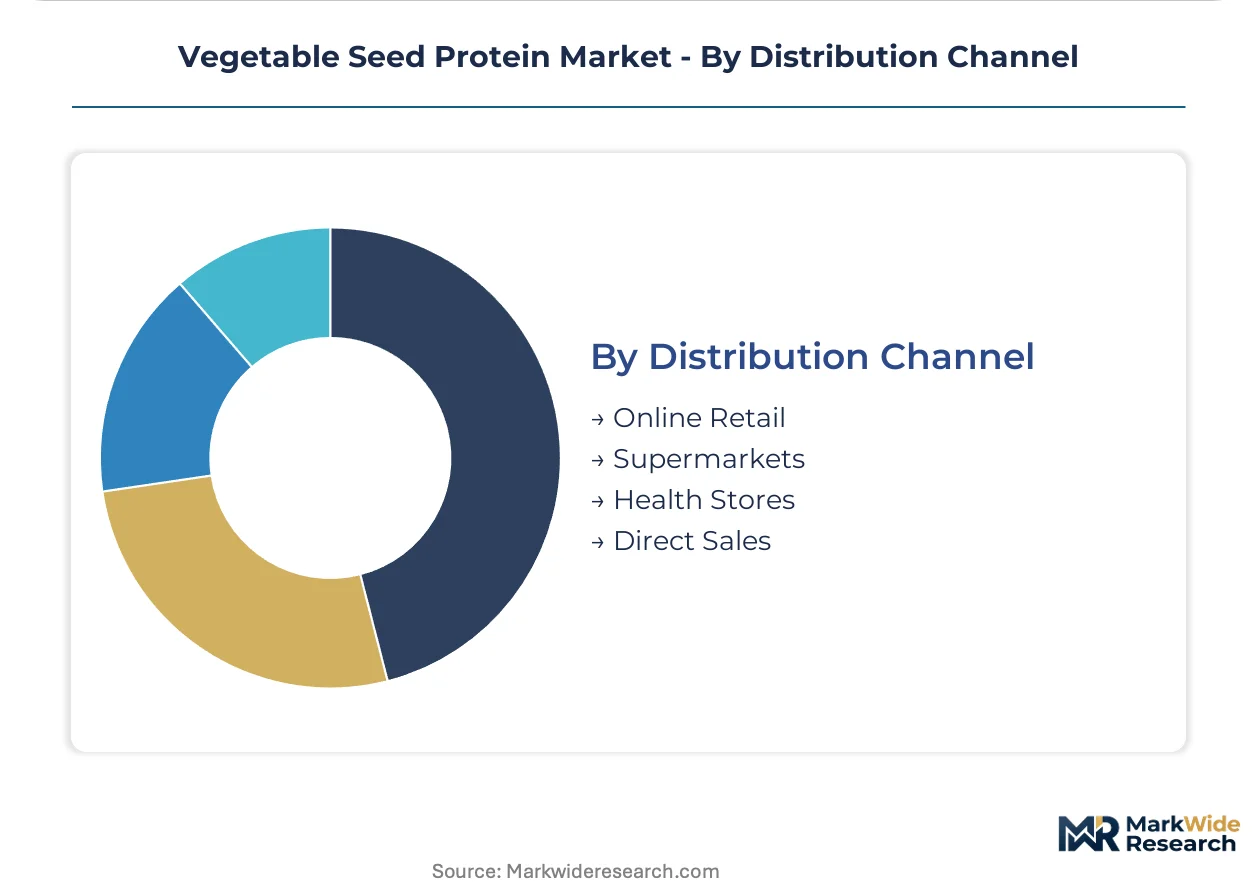
- Direct Sales:Bulk supply contracts with integrated processors bypass intermediary margins for multinational food manufacturers with volume commitments and quality management systems already deployed.
- Online Retail:Amazon and specialized nutrition platforms are capturing sports nutrition and health enthusiast demand with subscription models for branded isolate grades.
- Supermarkets:Mass retail placement requires Non-GMO Project verification as a de facto market access requirement in North American grocery.
- Health Stores:Independent retailers concentrate premium positioning for organic-certified and specialty allergen-free protein products.
Direct sales hold contract value concentration. Online retail is rotating up the growth trajectory through subscription model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government clean-label procurement mandates in Germany and the Netherlands are accelerating vegetable seed protein adoption, while EFSA novel food pathways reshape commercialization timelines across Western Europe. Brazil and Argentina present underpenetrated demand pools reliant on imported soy isolates. Canadian harvest volatility drives input cost uncertainty for North American pea protein processors.
Germany
Food manufacturers in Berlin and Hamburg are expanding formulation work with pea and fava protein concentrates for plant-based dairy alternatives. EFSA's 2023 transparency regulation has compressed novel food dossier preparation timelines, forcing ingredient firms to restructure regulatory affairs teams. The Vic-sur-Aisne supply corridor extends into German procurement networks, anchoring regional clean-label sourcing.
Netherlands
Dutch dairy alternative brands are consolidating supplier relationships around single-origination organic and non-GMO grades. EFSA novel food authorizations for pumpkin and sunflower protein isolates are accelerating commercialization timelines for emerging seed sources. Rotterdam and Amsterdam clusters concentrate procurement decision-making for multinational plant-based formulations.
United States
FDA GRAS self-determination pathways shape commercialization timelines for new extraction processes targeting sports nutrition applications. USDA organic certification and Non-GMO Project verification function as de facto market access requirements for retail placement. California and Midwest crushing infrastructure sustains bulk supply contracts with integrated food manufacturers.
Brazil
Food manufacturers in São Paulo remain reliant on imported soy isolates, creating white space for regional pea protein crushing investment. The country's national food safety regulator enforces standards that favor established international suppliers with ISO 22000 systems. Southern agricultural regions concentrate oilseed processing infrastructure awaiting diversification into legume fractionation.
Canada
Yellow pea and fava bean prices fluctuate with Prairie harvest cycles, compressing isolate margins unpredictably for North American processors. Canadian Grain Commission oversight shapes origination quality standards for export-bound protein concentrates. Manitoba and Saskatchewan crushing capacity anchors supply contracts with US dietary supplement formulators.
Vegetable Seed Protein Market Competitive Landscape
Listed leaders compete with private specialists across certification and origination capabilities, creating a tiered structure where scale and compliance separate winners. The supplier base compresses as ISO 22000 audit requirements eliminate smaller seed processors. Three archetypes dominate: integrated agribusiness giants with crushing infrastructure, European ingredient specialists with novel food regulatory expertise, and North American organic certifiers with single-origination traceability. Competitive moves concentrate on backward integration into seed origination and capacity expansion for aqueous fractionation lines.
Within the integrated agribusiness tier, ADM leverages North American crushing infrastructure to sustain bulk supply relationships, while Cargill competes on global origination networks for non-GMO streams. Roquette Frères anchors European pea protein output through its Vic-sur-Aisne facility, representing the specialist archetype with deep regulatory affairs capabilities.
| Leading Market Players |
|---|
| ADM |
| Roquette Frères |
| Axiom Foods |
| Ingredion |
| DuPont |
| dsm-firmenich |
| Cargill |
| Beneo |
| PURIS |
| Others |
Value Network & Pricing Analysis
Crushing capacity utilization at North American facilities anchors both supply concentration and minimum viable pricing floors for vegetable seed protein. Scale economies in membrane filtration systems for 90% isolates compress the supplier base while sustaining premium tier margins for certified organic grades.
Pricing Analysis
Certification level creates the primary spread between commodity concentrate grades and premium isolate positioning. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 22000 audit status, Non-GMO Project verification, and organic certification stacking. Pricing pressure stems from Canadian yellow pea harvest volatility compressing input costs unpredictably. Animal feed buyers exhibit highest price sensitivity, while sports nutrition formulators absorb premiums for documented DIAAS scores.
Supply Chain Analysis
Strait of Hormuz transit vulnerability underscores energy cost exposure for European aqueous fractionation operations. Supply concentrates in the United States, Canada, and France, with Prairie harvest cycles and Vic-sur-Aisne processing anchoring regional origination. Raw material dependencies center on yellow pea, fava bean, and non-GMO soybean streams. Single-source vulnerability concentrates in North American non-GMO crushing capacity. Distribution runs through direct bulk contracts with integrated processors serving multinational food manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as German and Dutch dairy alternative brands consolidate procurement around single-origination suppliers capable of delivering stacked certifications from unified origination points.
For Market Incumbents: Fortify backward integration into Prairie seed origination to secure non-GMO and organic streams before harvest volatility escalates. Expand Vic-sur-Aisne aqueous fractionation capacity to capture EFSA novel food tailwinds for pumpkin and sunflower isolates. Precision fermentation startups threaten nutritional parity claims, forcing seed protein suppliers to emphasize sustainability credentials and clean-label traceability rather than amino acid completeness alone. For New Entrants and Emerging Players: Regulatory affairs service gaps in EFSA novel food dossier preparation present immediate white-space opportunity for specialist consultancies supporting pumpkin and sunflower protein authorizations. Brazilian food manufacturers in São Paulo remain dependent on imported soy isolates, creating entry path for regional pea protein crushing with ISO 22000 certification. Target direct sales relationships with mid-sized dairy alternative brands seeking second-source security beyond ADM and Cargill supply contracts. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors processors with deployed membrane filtration infrastructure over fermentation-based alternative protein plays. Long-term viability hinges on origination control and certification stacking rather than extraction technology alone. Acquisition target archetype: European ingredient specialists with EFSA regulatory expertise and existing novel food approvals. Watch FAO DIAAS scoring methodology revisions as inflection indicator for sports nutrition formulation demand shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seed Origination | Captive supply of non-GMO and organic yellow pea streams secures margin stability against Prairie harvest volatility. |
| EFSA Novel Food Dossier Investment | Parallel-track submissions for pumpkin and sunflower isolates accelerate European commercialization timelines ahead of competitors. |
| Aqueous Fractionation Capacity Expansion | Membrane filtration line deployment at Vic-sur-Aisne anchors supply contracts with consolidating Dutch dairy alternative brands. |
| Certification Stacking Program | USDA organic plus Non-GMO Project verification unlocks North American retail placement as de facto market access requirement. |
| Enzymatic Debittering R&D Partnership | Collaboration with biotechnology specialists reduces beany off-flavor thresholds below detection limits for neutral applications. |
Research Methodology
Operator-level perspectives from seed processing plant managers, regulatory affairs directors at ingredient firms, procurement leads at German dairy alternative brands, and sports nutrition formulators anchored the qualitative base. Primary interview data combined with secondary validation from EFSA novel food submission databases, USDA organic certification records, Canadian Grain Commission harvest reports, and FDA GRAS determination filings. Bottom-up capacity modeling and top-down demand estimation triangulated volume and value outputs.
Sensitivity analysis across protein content tiers, certification levels, and regional regulatory clusters shaped the analytical framework throughout the projection horizon. Segmentation dimensions modeled include extraction grade, end-use channel, geographic origination, and certification status. CAGRs derived from capacity deployment schedules, EFSA approval timelines, and buyer consolidation patterns in Western European procurement. Forecast inputs incorporated Prairie harvest yield variance and membrane filtration technology diffusion curves.
Material uncertainties — regulatory delays in EFSA novel food evaluations, precision fermentation cost breakthroughs, and FAO DIAAS scoring recalibrations — sit outside the modeled envelope. Forecasts reflect documented assumptions about buyer consolidation trajectories and certification adoption rates. Practitioners should keep alternative scenarios live as precision fermentation economics and European regulatory transparency requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
South America Vegetable Seed Market
Seeds
Global Alfalfa Seed Market
Seeds
United States Garden Seeds Market
Seeds
Garlic Chive Seeds Market
Seeds
India Rice Seed Market
Seeds
Asia-Pacific Cannabis Seeds Market
Seeds
Uganda Seeds Market
Seeds
Canary Seeds Market
Seeds
Cherry Tomato Seeds Market
Seeds
Perilla Seed Oil Market
Seeds
North America Vegetable Seed Market
Seeds
Americas Seeds Market
Seeds
Spain Forage Seed Market
Seeds
Flax Seed Market
Seeds
Fruit Seed Waste Market
Seeds
Europe Seed Market