
 Global Maize Seed Market | 2026-2036
Global Maize Seed Market Size, Share, and Industry Trends Forecast 2026-2036
Global Maize Seed Market Foresight
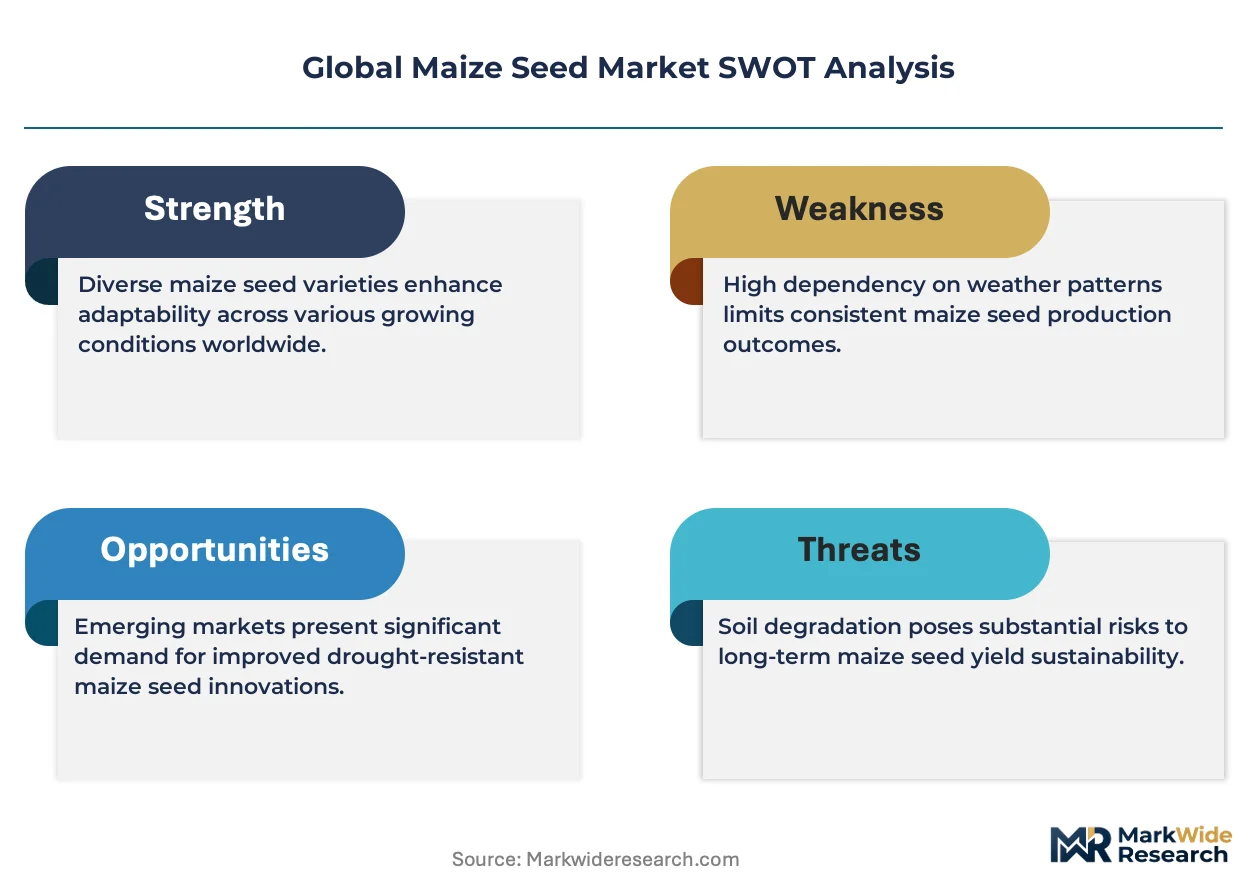
Multi-source germplasm licensing is realigning competitive dynamics across the value chain. Bayer AG leverages its proprietary trait platforms to sustain technology premiums in stacked-gene hybrids. KWS SAAT SE & Co. KGaA anchors its position through deep specialization in European mid-maturity segments. Syngenta Group competes via integrated crop solution bundling that extends beyond seed into digital agronomy services.
Maize seed comprises the reproductive grain of Zea mays, typically processed into certified units with minimum germination rates of 80% and treated with polymer coatings for pest resistance and moisture retention; its primary purpose is to establish commercial stands for grain, silage, and industrial feedstock production. Hybrid seed types dominate value capture due to proprietary trait stacking and farmer loyalty programs, while genetically modified categories face structural bifurcation between markets with open regulatory pathways and those enforcing strict labeling or cultivation bans. Open-pollinated varieties retain stable demand among subsistence operators and organic-certified farms where seed-saving rights reduce input costs.
USDA germplasm export licensing, EU REACH protocols for seed treatment chemistry, and China's GB standards for biotech crop labeling collectively shape product registration timelines and market access conditions. India's BIS certification requirements for minimum seed standards and the PLI scheme for agri-input manufacturing are redirecting procurement toward domestically produced certified stock. Stakeholders must monitor divergence between gene-editing regulatory frameworks in major producing jurisdictions to anticipate trait approval asymmetries that will determine competitive positioning.
Market Dynamics
CRISPR-based gene editing is compressing varietal development timelines from eight years to three, forcing seed companies to restructure R&D budgets and trait licensing strategies around accelerated regulatory submissions rather than conventional breeding cycles.
Growth Catalysts
- China's state-backed irrigation investments:The North China Plain is absorbing higher-value hybrid seed as provincial water infrastructure upgrades enable reliable double-cropping systems.
- Brazilian livestock expansion:Cattle and dairy producers in Mato Grosso and Paraná are prioritizing silage-quality hybrids with enhanced digestibility scores for feedlot operations.
- Evolving biosafety protocols:Streamlined gene-editing classification frameworks in Argentina and the United States are reducing regulatory uncertainty for CRISPR-derived traits.
Market Restraints
- Input cost volatility:Polymer coating chemistries face price instability from petrochemical feedstock fluctuations, squeezing margin structures on treated certified units.
- Regulatory friction:The European Union's REACH protocols for seed treatment active ingredients extend registration timelines by 18-24 months compared to jurisdictions with hazard-based cutoffs.
- Substitution threat:Open-pollinated varieties retain cost advantages among subsistence operators in Sub-Saharan Africa where seed-saving rights eliminate annual input purchases.
Strategic Opportunities
- Underpenetrated geography:Nigeria's commercial maize sector offers white-space expansion as the Central Bank of Nigeria's anchor borrower program expands credit access for certified hybrid adoption.
- Technology convergence:Digital agronomy platforms are integrating with trait performance databases to enable predictive seed selection based on micro-climate soil mapping.
- Regulatory tailwind:India's PLI scheme for agri-input manufacturing is redirecting public and private procurement toward domestically produced certified stock, displacing informal seed channels.
Industry Challenges
- Skill scarcity in gene-editing regulation:Few regulatory affairs specialists possess dual expertise in molecular biology and jurisdiction-specific biosafety submission protocols.
- Capex intensity of trait stacking:Proprietary multi-gene platforms require sustained capital deployment for backcrossing infrastructure and molecular marker laboratories.
- IP licensing complexity:Germplasm access agreements span multiple patent estates across CRISPR nucleases, selectable markers, and event-specific regulatory data packages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Maize Seed Market |
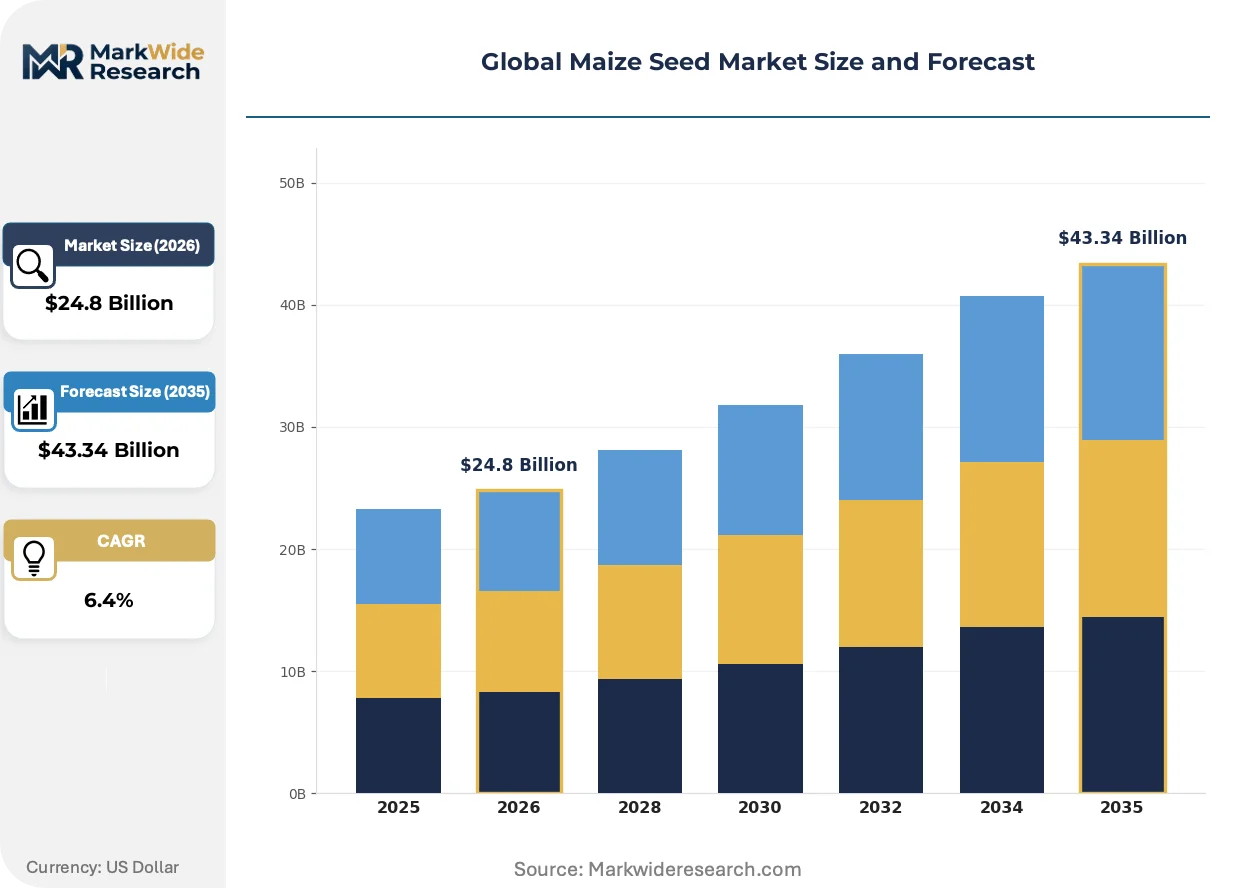
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $43.34 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
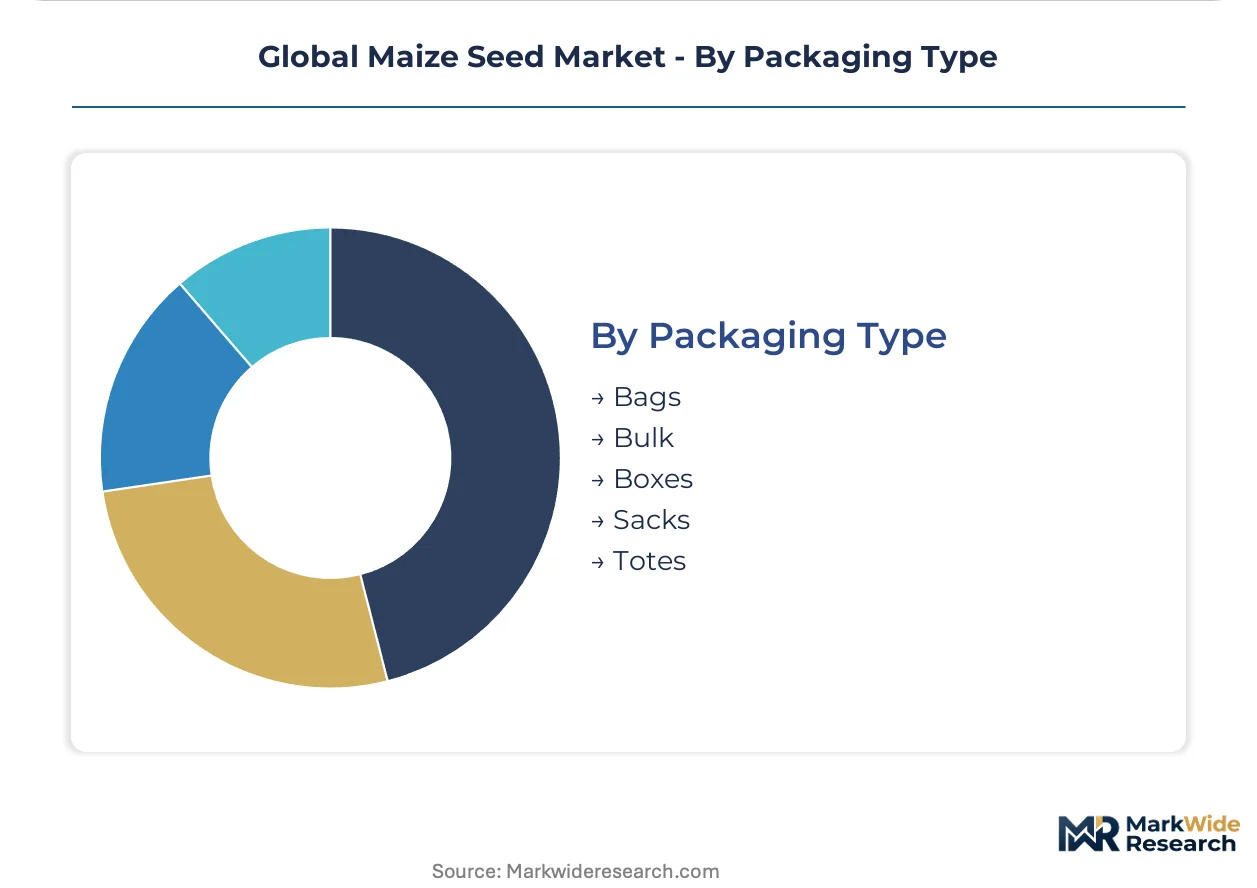
| Segmentation | Seed Type: Hybrid, Open-Pollinated, Genetically Modified, Organic, Synthetic Application: Animal Feed, Biofuel Production, Food Products, Industrial Starch, Seed Production End User: Farmers, Agricultural Cooperatives, Seed Distributors, Research Institutions, Agri-businesses Packaging Type: Bags, Bulk, Boxes, Sacks, Totes |
| Companies Covered | Corteva Agriscience, Bayer AG, Syngenta Group, Advanta Seeds - UPL, Groupe Limagrain, KWS SAAT SE & Co. KGaA, Hefei Fengle Seed Industry Co. Ltd, Kaveri Seeds, Charoen Pokphand Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Maize Seed Market Shifts & Advancements
Gene-editing workflows and digital phenotyping platforms are converging to compress product development cycles, while regulatory divergence between jurisdictions is fragmenting trait approval pathways and forcing region-specific portfolio architectures.
CRISPR-Cas12a systems with multiplexed guide RNA arrays are unifying disease-resistance and drought-tolerance edits within single transformation events. Large-scale row-crop operators in the US Corn Belt are piloting these stacked edits for the 2026-2027 planting window. The technology is unifying previously separate breeding pipelines for biotic and abiotic stress traits, collapsing timeline advantages held by conventional stacked-transgenic approaches.
The EU's evolving stance on gene-edited crops under the Sustainable Use of Pesticides Regulation is creating regulatory asymmetry with Argentina's streamlined notification system for site-directed nucleases. Seed companies now maintain parallel regulatory dossiers for identical edits depending on destination market classification. European organic-certified farms remain excluded from gene-edited adoption, perpetuating demand bifurcation between regulatory zones.
Farmer loyalty programs are migrating from volume rebates to outcome-guarantee structures tied to verified yield performance against local benchmarks. Input retailers in Brazil's Cerrado region are displacing traditional commission-based sales with digital platforms that bundle seed, fertility, and crop protection into per-hectare performance contracts. This shift is most visible among 5,000+ hectare operations where risk transfer to suppliers aligns with balance-sheet optimization goals.
Global Maize Seed Market Segmentation
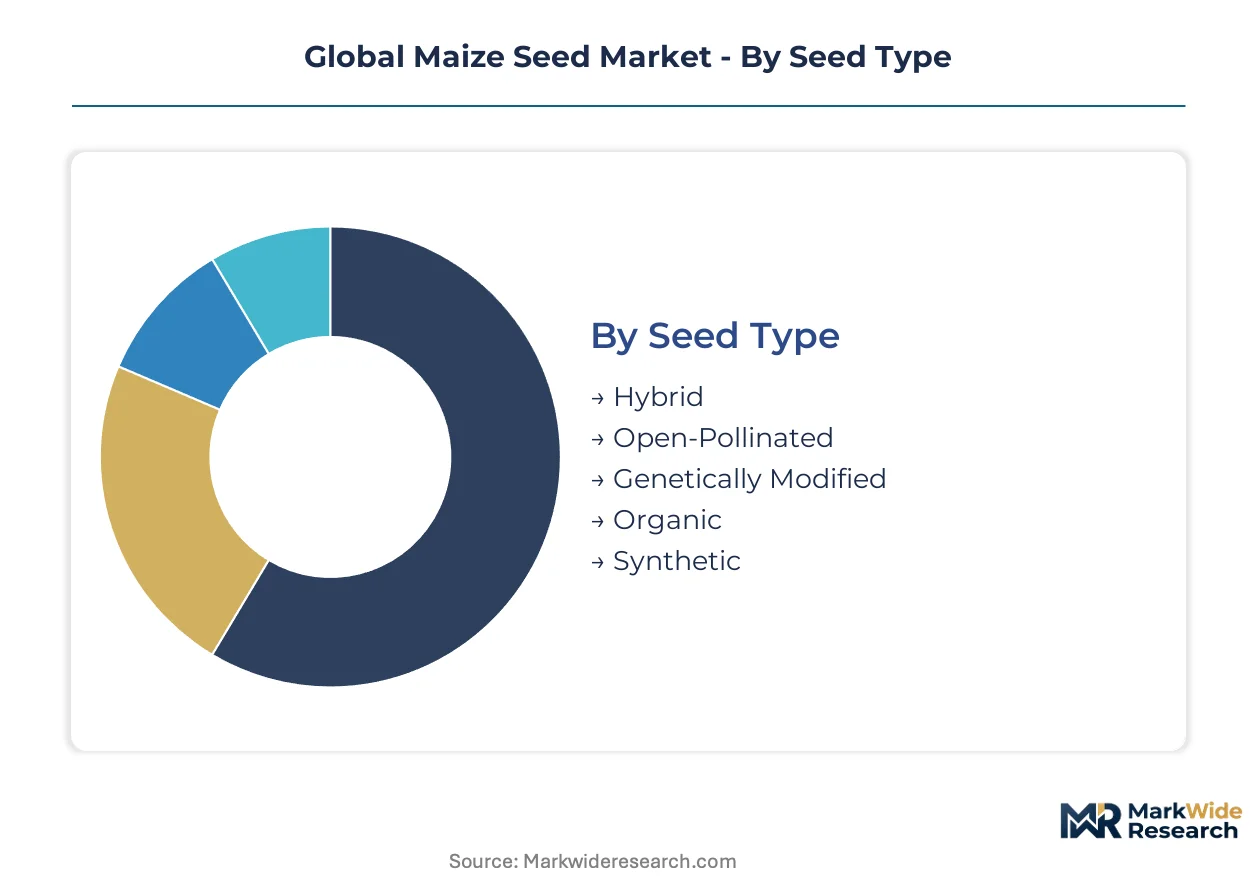
Seed type determines farmer willingness to pay recurring technology fees versus one-time acquisition costs. Application segments drive trait stacking priorities, with digestibility scores commanding premiums in Brazilian feedlot corridors. Packaging configurations reflect mechanized planting density and on-farm storage infrastructure.
Seed Type:
Farmers replace seed stock based on trait performance depreciation and regulatory access to newer genetics.
- Hybrid:Proprietary crosses of inbred parental lines deliver heterosis effects for yield stability and stress tolerance. Demand concentrates in Mato Grosso and Paraná, where livestock producers prioritize silage-quality hybrids with enhanced digestibility scores for feedlot operations.
- Genetically Modified:Stacked-trait events combine herbicide tolerance with insect resistance through Agrobacterium-mediated transformation. Procurement is shifting toward CRISPR-derived alternatives in Argentina and the United States as streamlined biosafety classifications reduce regulatory uncertainty.
- Open-Pollinated:Natural pollination preserves farmer seed-saving rights and eliminates annual input costs. Subsistence operators in Sub-Saharan Africa rely on retained grain from prior harvests, perpetuating demand outside certified channels.
- Organic:Certified non-GMO stock meets EU organic regulation and USDA National Organic Program standards for synthetic input exclusion. European organic-certified farms remain excluded from gene-edited adoption, perpetuating demand bifurcation between regulatory zones.
- Synthetic:Laboratory-assembled genomes bypass traditional breeding bottlenecks through computational design of optimized metabolic pathways. Research institutions pilot these systems for abiotic stress tolerance in controlled environments.
Volume placements concentrate in Hybrid; the faster expansion belongs to Genetically Modified.
Application:
End-use specifications dictate minimum protein content, oil composition, and starch extraction efficiency.
- Animal Feed:Silage and grain rations for cattle, poultry, and swine operations require optimized energy density and amino acid profiles. Brazilian livestock expansion in Mato Grosso drives hybrid purchases prioritizing feed conversion ratios.
- Biofuel Production:Ethanol fermentation demands high fermentable starch content and reduced fiber fractions. US Corn Belt processors specify moisture-tolerant varieties for dry-grind facilities.
- Food Products:White maize for human consumption requires mycotoxin compliance and uniform kernel size for milling. Mexico's tortilla industry maintains identity-preserved supply chains for landrace varieties.
- Industrial Starch:Modified starches for paper, textile, and adhesive applications need specific amylose-amylopectin ratios. Wet-milling facilities in Iowa and Illinois contract dedicated acreage for high-extraction hybrids.
- Seed Production:Foundation and certified seed multiplication requires genetic purity standards and isolation distances from contaminating pollen. China's GB standards for biotech crop labeling shape product registration timelines for export-oriented multiplication.
Revenue gravity sits with Animal Feed; Food Products command the steepest price premiums per unit.
End User:
Procurement scale and technical sophistication determine access to performance-guarantee contracts versus spot-market purchases.
- Farmers:Individual operators below 500 hectares rely on dealer recommendations and volume rebate programs. India's PLI scheme for agri-input manufacturing redirects procurement toward domestically produced certified stock.
- Agricultural Cooperatives:Pooled purchasing power enables direct negotiation with seed companies for customized trait packages. Brazilian cooperatives in the Cerrado region bundle seed, fertility, and crop protection into per-hectare performance contracts.
- Seed Distributors:Inventory risk intermediaries maintain regional warehousing and treatment facilities for certified stock. EU REACH protocols for seed treatment active ingredients extend registration timelines for polymer coating chemistries.
- Research Institutions:Germplasm banks and breeding programs require access to diverse genetic backgrounds for trait introgression. USDA germplasm export licensing shapes international collaboration frameworks.
- Agri-businesses:Vertically integrated operators from input retail through grain handling optimize seed selection against elevator pricing algorithms. Large-scale row-crop operators in the US Corn Belt pilot CRISPR-Cas12a stacked edits for the 2026-2027 planting window.
Transaction volume flows through Farmers; Agri-businesses capture the fastest margin expansion through outcome-based contracting.
Packaging Type:
Unit size and material specifications align with planting equipment calibration and climatic storage conditions.
- Bags:Laminated polypropylene units of 25-50 kilograms suit smallholder manual planting and on-farm treated seed storage. Nigeria's Central Bank anchor borrower program expands credit access for certified hybrid adoption in bagged configurations.
- Bulk:Loose seed in dedicated hopper trucks serves mechanized operations with pneumatic planting systems above 2,000 hectares. North China Plain irrigation upgrades enable reliable double-cropping systems demanding bulk delivery logistics.
- Boxes:Corrugated containers with moisture barriers protect pre-treated seed for high-value specialty markets. Organic-certified farms in Germany specify box packaging to prevent cross-contamination during transport.
- Sacks:Woven polypropylene of 10-20 kilograms accommodates manual sowing in terrain unsuitable for mechanization. Subsistence operators in Sub-Saharan Africa favor sack sizes matching household labor availability.
- Totes:Intermediate bulk containers of 500-1,000 kilograms bridge manual and fully automated handling systems. Research institutions utilize totes for controlled trial plot distribution across multiple locations.
Shipment volume concentrates in Bulk; Bags retain the broadest geographic penetration across smallholder markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China absorbs the largest share of higher-value hybrid seed as state-backed irrigation investments transform the North China Plain into reliable double-cropping territory. Brazil and the United States anchor commercial demand through divergent end-use specializations—silage quality versus grain export efficiency.
United States
USDA germplasm export licensing frameworks shape international collaboration access for research institutions across the Corn Belt. EPA oversight of seed treatment chemistries influences polymer coating registration timelines for certified units. Iowa and Illinois wet-milling clusters contract dedicated acreage for high-extraction hybrids serving industrial starch processors.
Brazil
Livestock producers in Mato Grosso and Paraná prioritize silage-quality hybrids with enhanced digestibility scores for feedlot operations. ANVISA protocols for biotech crop commercialization diverge from EU hazard-based cutoffs, accelerating trait approval pathways. The Cerrado region anchors outcome-guarantee contracting models that bundle seed, fertility, and crop protection into per-hectare performance agreements.
China
Provincial water infrastructure upgrades across the North China Plain enable reliable double-cropping systems demanding bulk delivery logistics. GB standards for biotech crop labeling shape product registration timelines for export-oriented multiplication operations. Shandong and Hebei provinces concentrate foundation seed production serving domestic hybrid adoption campaigns.
India
The PLI scheme for agri-input manufacturing redirects public and private procurement toward domestically produced certified stock. BIS certification requirements for minimum seed standards displace informal channels in Maharashtra and Gujarat. Haryana's commercial maize belt absorbs hybrid seed through cooperative purchasing structures tied to credit access programs.
Argentina
Streamlined notification systems for site-directed nucleases reduce regulatory uncertainty for CRISPR-derived trait commercialization. The Pampas region sustains open regulatory pathways for gene-edited varieties that face cultivation bans in European markets. Buenos Aires province anchors comparative advantage in accelerated varietal development timelines.
Global Maize Seed Market Competitive Landscape
Trait licensing partnerships dominate the current landscape as compressed development timelines force restructuring of R&D budgets and regulatory submission strategies. The vendor base concentrates around integrated technology platforms with proprietary germplasm access, creating tiered access to stacked-gene hybrids. Three archetypes define competitive positioning: multi-crop conglomerates with digital agronomy bundling, regional specialists with deep mid-maturity segmentation, and emerging Asian producers leveraging domestic manufacturing incentives. M&A activity and technology licensing agreements represent the primary competitive moves reshaping market share distribution.
Within the multi-crop conglomerate tier, Bayer AG and Syngenta Group exemplify integrated crop solution architectures that extend beyond seed into predictive agronomy platforms. Corteva Agriscience anchors the North American technology premium segment through proprietary trait stacking. KWS SAAT SE & Co. KGaA occupies a specialist position in European mid-maturity hybrid development, while Advanta Seeds - UPL represents emerging-market expansion archetypes with diversified germplasm licensing portfolios.
| Leading Market Players |
|---|
| Corteva Agriscience |
| Bayer AG |
| Syngenta Group |
| Advanta Seeds - UPL |
| Groupe Limagrain |
| KWS SAAT SE & Co. KGaA |
| Hefei Fengle Seed Industry Co. Ltd |
| Kaveri Seeds |
| Charoen Pokphand Group |
| Others |
Supply & Pricing Matrix
EU REACH protocols for seed treatment chemistry gate qualified supply and premium-tier pricing access, forcing seed companies to maintain parallel manufacturing lines for coated versus uncoated certified units. Polymer coating chemistries face petrochemical feedstock volatility, squeezing margin structures and redirecting procurement toward untreated open-pollinated varieties among price-sensitive subsistence operators.
Pricing Analysis
Volume placements concentrate in standard-tier hybrid seed while margin capture belongs to stacked-trait genetically modified categories with proprietary technology fees. Price differentiation rests on certification grade—EU organic regulation and USDA National Organic Program standards command 15-30% premiums—and volume scale, with agricultural cooperatives negotiating customized trait packages below list rates. Cost compression in polymer-coated certified units is intensifying because petrochemical feedstock volatility squeezes treatment margins. Subsistence operators below 500 hectares exhibit highest price sensitivity, deferring to retained open-pollinated grain; large-scale agri-businesses above 5,000 hectares demonstrate lowest sensitivity, absorbing technology premiums for outcome-guarantee contracts.
Supply Chain Analysis
Certification and qualification requirements for minimum germination rates and genetic purity standards fragment supplier bases across foundation seed multiplication networks. Geographic supply concentrates in the United States, Brazil, and China, with Iowa and Illinois wet-milling clusters, Mato Grosso feedlot corridors, and Shandong foundation seed farms anchoring respective regional flows. Raw material dependencies draw from petrochemical feedstocks for polymer coatings, laboratory-grade reagents for molecular marker screening, and controlled-environment infrastructure for backcrossing programs. Single-source vulnerability runs through proprietary CRISPR nuclease licensing estates held by concentrated patent holders. Distribution runs through seed distributors maintaining regional warehousing and treatment facilities, with bulk hopper trucks serving mechanized operations and laminated polypropylene bags reaching smallholder manual planting systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race, with players pursuing backward integration into foundation seed multiplication to secure germplasm access and compress licensing costs.
For Market Incumbents: Hedge regulatory asymmetry by maintaining parallel regulatory dossiers for identical CRISPR-derived edits across Argentina's streamlined notification system and the European Union's evolving hazard-based classifications. Deepen captive supply of foundation seed production in Shandong and Hebei provinces to reduce dependence on third-party multiplication agreements. Channel control through digital agronomy platform bundling displaces traditional commission-based sales in Brazil's Cerrado region. For New Entrants and Emerging Players: The price-point gap between premium stacked-trait hybrids and economy open-pollinated varieties creates entry space for mid-tier certified hybrids with localized performance guarantees. Nigeria's commercial maize sector offers white-space expansion as the Central Bank of Nigeria's anchor borrower program expands credit access. A cooperative purchasing structure go-to-market angle aligns with India's PLI scheme redirecting procurement toward domestically produced certified stock. For Investors and Strategic Acquirers: India's notification of expanded PLI scheme disbursement thresholds is the leading indicator that domestic manufacturing incentives are reshaping competitive positioning. Long-term viability over the coming decade rests on regulatory affairs capabilities spanning multiple biosafety submission protocols. Acquisition targets should emphasize gene-editing regulatory specialists with dual expertise in molecular biology and jurisdiction-specific frameworks. Watch for divergence between gene-editing regulatory frameworks in major producing jurisdictions as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Trait Licensing Partnership | Multi-source germplasm agreements with Bayer AG and KWS SAAT SE reduce R&D cycle dependency. |
| Regulatory Dossier Parallelization | Simultaneous submissions to ANVISA and EPA compress approval timelines for CRISPR-derived varieties. |
| Backward Integration into Multiplication | Captive foundation seed production in Hebei province secures genetic purity standards for export-oriented operations. |
| Digital Platform Bundling | Integration of seed, fertility, and crop protection into per-hectare performance contracts displaces traditional retail commissions in Mato Grosso. |
| Outcome-Guarantee Contracting | Risk transfer to suppliers aligns with balance-sheet optimization goals among 5,000+ hectare operators in the Cerrado. |
Research Methodology
Document review covered USDA germplasm export licensing frameworks, EU REACH protocols for seed treatment chemistry, China's GB standards for biotech crop labeling, and India's BIS certification requirements, complemented by interviews with seed company regulatory affairs leads, agricultural cooperative procurement managers, foundation seed multiplication facility operators, and digital agronomy platform engineers. Secondary validation drew from customs and trade data for certified seed movements, SEC filings of listed agri-input manufacturers, and national seed certification authority disclosures. Bottom-up segment sizing and top-down macroeconomic triangulation reconciled volume placements across hybrid, genetically modified, and open-pollinated categories.
Cross-referencing historical adoption curves against expert panel input on CRISPR regulatory pathway timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include seed type, application end-use, end-user procurement scale, and packaging configuration aligned with mechanized versus manual planting systems. CAGRs were derived from trend extrapolation moderated by policy inflection points. Industry-specific forecast inputs encompassed provincial water infrastructure investment flows in the North China Plain and Brazilian livestock herd expansion projections in Mato Grosso and Paraná.
Underlying measurement precision varies by segment; hybrid and genetically modified categories carry tighter precision than open-pollinated varieties where informal seed-saving channels escape formal tracking. Forecasts reflect assumptions around regulatory pathway convergence, petrochemical feedstock stability, and credit access program continuation. A model refresh is warranted upon material change in gene-editing biosafety classification frameworks across major producing jurisdictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Asia-Pacific Cannabis Seeds Market
Seeds
South Africa Seed Market
Seeds
Caraway Seeds Market
Seeds
Americas Seeds Market
Seeds
Europe Vegetable Seed Market
Seeds
Asia-Pacific Vegetable Seed Market
Seeds
Cotton Seed Treatment Market
Seeds
Ghana Seeds Market
Seeds
Global Vegetable Seed Market
Seeds
Lupin Market
Seeds
North America Forage Seed Market
Seeds
Flax Seed Market
Seeds
Commercial Seed Market
Seeds
Ghana Seed Extract Market
Seeds
Mexico Seed Market
Seeds
Indonesia Seeds Market