
 Lupin Market | 2026-2036
Lupin Market Size, Share, and Industry Trends Forecast 2026-2036
Lupin Market Intelligence
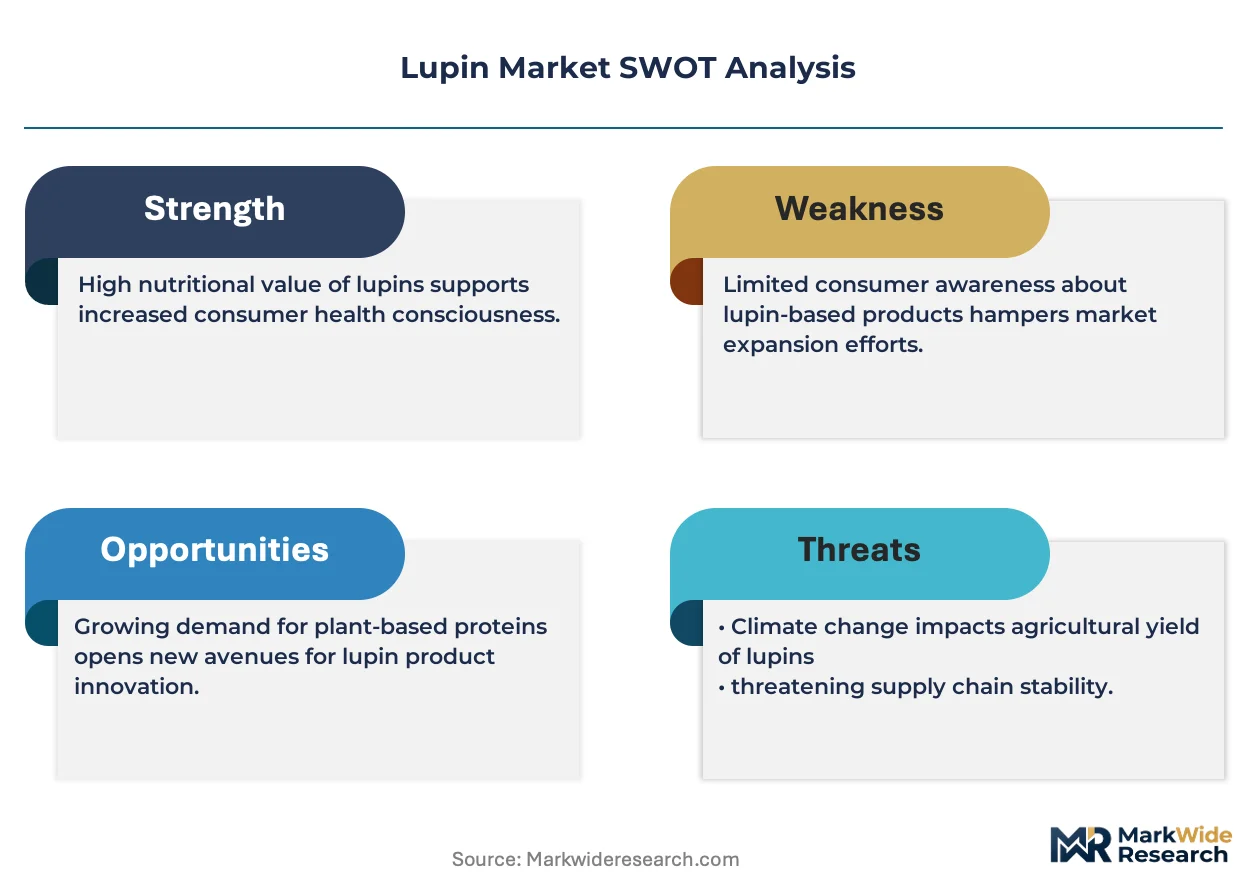
The European Union's Green Deal, which promotes sustainable protein sources, is expanding the addressable market for lupin-derived ingredients. Groupe Limagrain leverages its extensive seed breeding expertise to develop higher-yield lupin varieties. Meanwhile, BASF SE competes through its agricultural solutions portfolio, offering crop protection and seed treatments tailored for lupin cultivation.
Lupins are legumes belonging to the Lupinus genus, characterized by their high protein content, often exceeding 30-40%, and a favorable amino acid profile. Their primary commercial purpose is as a protein-rich ingredient for both human food and animal feed applications. Lupin flour and protein isolates represent the fastest-growing product types, driven by their versatility in food formulation. The animal feed segment remains a high-volume, mature end-use category, particularly for ruminant and aquaculture diets.
Product safety and market access are governed by food safety authorities like the U.S. FDA and the European Food Safety Authority (EFSA). Regulations concerning allergen labeling are particularly stringent, as certain lupin varieties can trigger allergic reactions, shaping processing and labeling requirements. Future success hinges on developing low-alkaloid lupin cultivars and managing allergen risks across the supply chain.
Market Dynamics
The central force shaping the lupin market is the convergence of consumer demand for plant-based nutrition with policy support for sustainable agriculture. Regulatory frameworks like the EU Green Deal actively promote protein-rich crops, creating structural demand beyond traditional end-uses.
Growth Catalysts
- Sustainable Food Systems Policy:The EU Green Deal's Farm to Fork strategy encourages protein crop cultivation, creating policy-driven demand for lupin as a rotational crop that improves soil health and as a food ingredient.
- Plant-Based Food Formulation:Consumer preference for non-soy, non-GMO protein sources in the food and beverage sector boosts demand for lupin flour and isolates in products like baked goods, pasta, and meat analogs.
- Aquaculture Feed Innovation:The aquaculture industry seeks sustainable protein alternatives to fishmeal, driving adoption of lupin kernel meal in feed formulations for carnivorous species like salmon and trout in Europe and Australia.
Market Restraints
- Alkaloid Content Variability:The presence of bitter quinolizidine alkaloids in many lupin varieties necessitates costly debittering processes and strict cultivar selection, increasing overall production costs for food-grade ingredients.
- Allergenicity Concerns:Mandatory allergen labeling requirements under regulations from bodies like the European Food Safety Authority and the U.S. FDA create market access hurdles and processing complexities due to cross-reactivity with peanut allergies.
- Concentrated Australian Supply:Heavy reliance on Western Australia for the global supply of sweet lupin (Lupinus angustifolius) exposes the value chain to climate-related production risks, such as drought, and potential trade disruptions.
Strategic Opportunities
- North American Market Penetration:Significant opportunity exists in the United States and Canada for lupin-fortified foods, supported by a growing flexitarian consumer base seeking novel, high-protein, and gluten-free ingredients.
- Development of Low-Alkaloid Cultivars:Genetic breeding programs focused on developing new sweet lupin varieties with minimal alkaloid content offer a path to bypass expensive processing steps and improve food safety profiles.
- Cosmetic and Nutraceutical Applications:Exploring the functional properties of lupin peptides for use in anti-aging skincare formulations or as dietary supplements represents an emerging, high-value application beyond traditional food and feed.
Industry Challenges
- Agronomic Expertise Gap:Cultivating lupin effectively requires specialized knowledge of soil acidity management, rhizobia inoculation, and pest control, which is lacking among many farmers outside of established regions.
- Processing Infrastructure Investment:Scaling the production of lupin protein isolates and concentrates requires significant capital expenditure on specialized milling, air classification, and aqueous extraction facilities.
- Standardization of Protein Quality:Establishing industry-wide standards for protein content, functionality, and purity is a key challenge for ensuring consistent quality and performance in diverse food ingredient applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lupin Market |
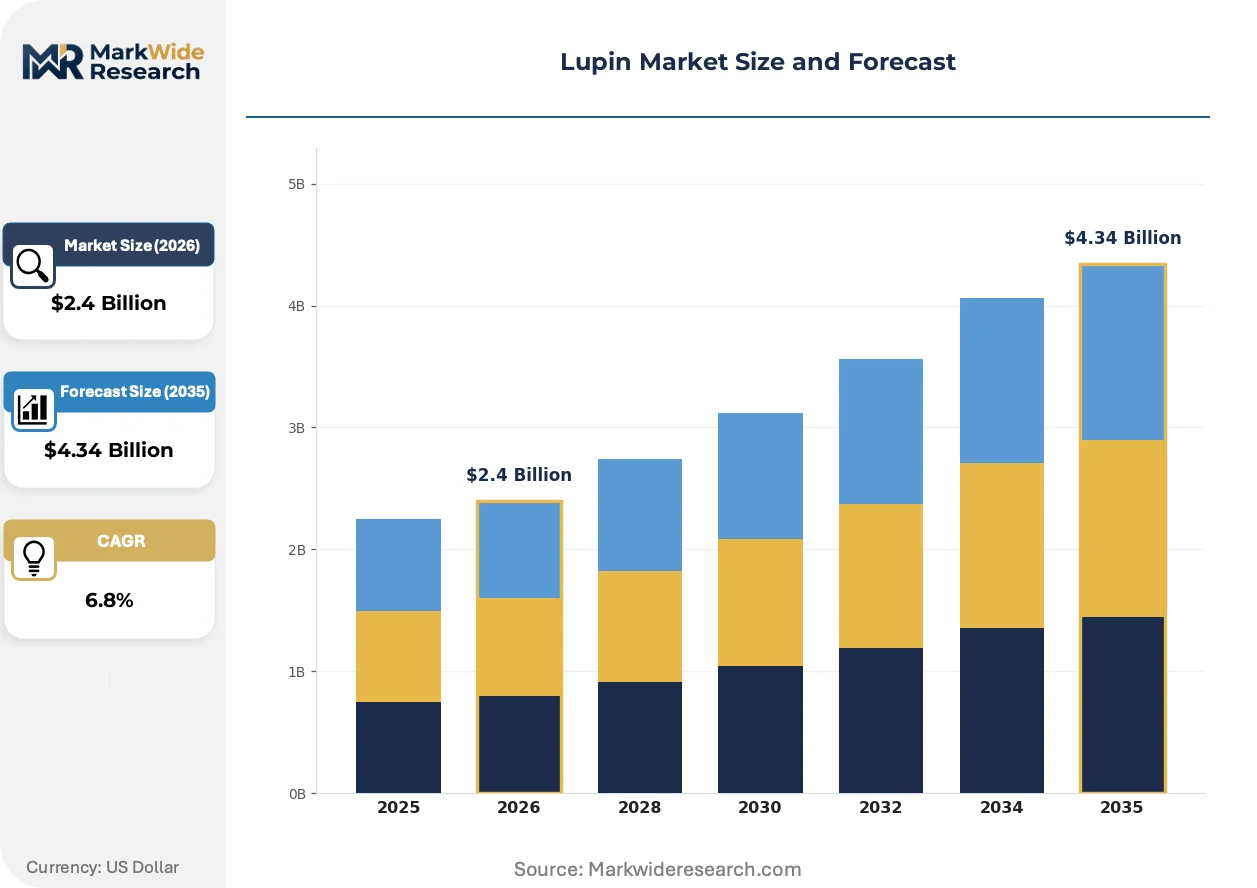
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Lupin, Lupin Flour, Lupin Protein, Lupin Snacks End Use: Food & Beverages, Animal Feed, Nutraceuticals, Personal Care Form: Whole Seed, Powder, Extract, Granule Distribution Channel: Online Retail, Supermarkets, Health Stores, Specialty Shops |
| Companies Covered | Groupe Limagrain, Dunstan Nutrition, Lupin Pharmaceuticals, Hemp Foods Australia, Sakata Seed Corporation, BASF SE, Agro-100, Lupin Limited, Cargill, Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lupin Market Strategic Shifts & Innovations
Agricultural technology and food science are creating new commercial pathways for lupin. Innovations in crop breeding are enhancing yield and safety, while advanced processing techniques are expanding the ingredient's applicability in high-value consumer product segments.
CRISPR gene-editing technology allows for precise modifications to the lupin genome, targeting traits like alkaloid reduction, disease resistance, and yield improvement. Agricultural research institutes and specialized seed companies are adopting this tool in their breeding programs. This advanced breeding capability is integrating with traditional crop science to accelerate the development of commercially viable, climate-resilient lupin cultivars.
The European Union's Green Deal, particularly its Farm to Fork strategy, creates strong incentives for cultivating nitrogen-fixing legumes like lupin. This policy directly supports reduced synthetic fertilizer use and promotes crop diversification, aligning with sustainable agriculture goals. The food and beverage segment is most affected, responding by formulating with lupin to meet sustainability targets and appeal to environmentally conscious consumers.
A demand-side shift is occurring toward clean-label ingredients, where consumers scrutinize product labels for simple, recognizable, and minimally processed components. This trend disrupts the market for complex, chemically derived texturizers and emulsifiers, favoring natural ingredients like lupin flour. This preference is most visible across the European and North American baked goods, plant-based dairy, and snack food sectors.
Lupin Market Segmentation
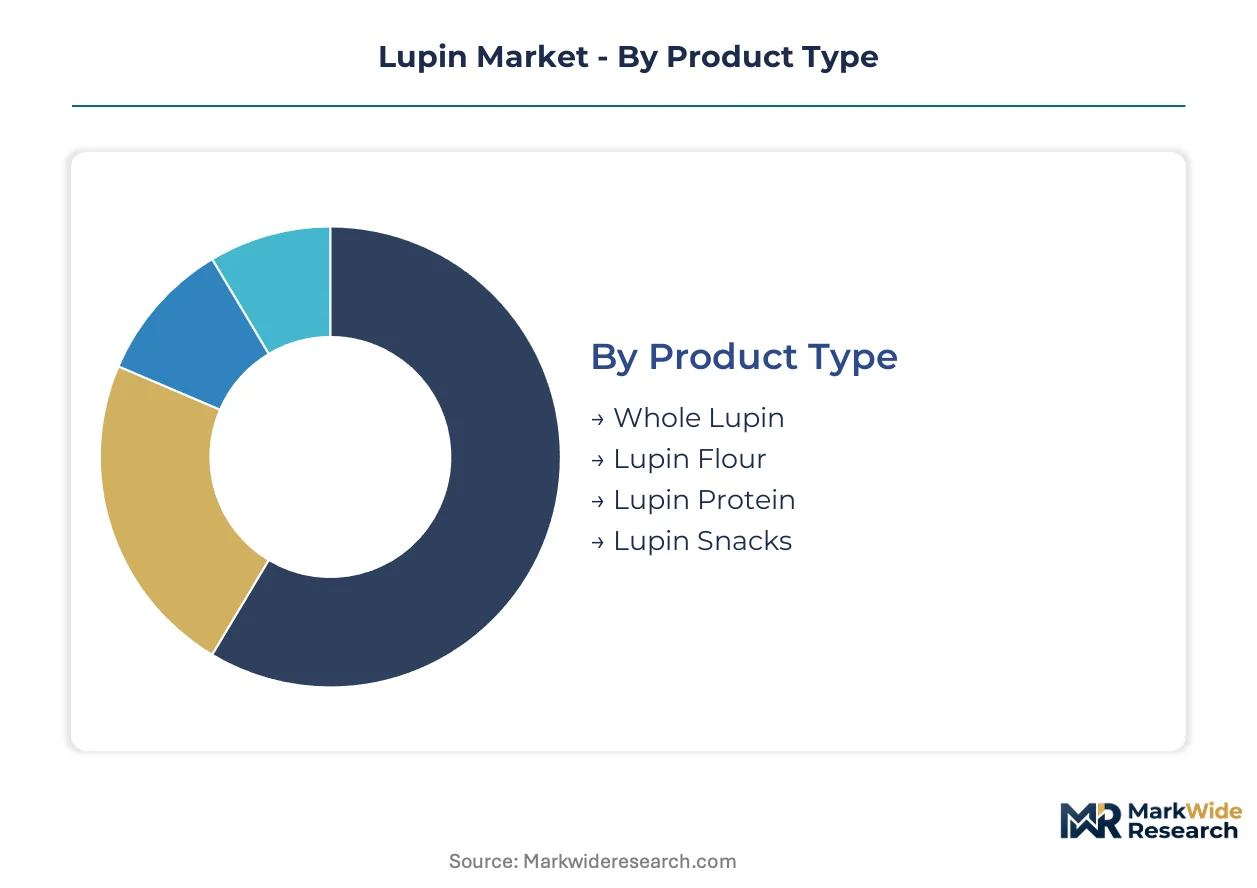
Lupin market segmentation reflects diverse applications and consumer preferences. Understanding these segments helps stakeholders identify high-growth areas and tailor product development strategies. The market's evolution is driven by specific product forms and end-use requirements.
Product Type:
Buyers prioritize specific lupin product types based on their functional requirements and processing capabilities.
- Lupin Protein:Lupin protein, often isolated or concentrated, offers a high-purity, plant-based protein source with excellent emulsifying and gelling properties. Demand concentrates in North American and European food and beverage sectors, driven by the expanding market for meat alternatives and dairy-free products.
- Lupin Flour:Lupin flour, a finely milled powder from dehulled lupin seeds, provides a gluten-free, high-protein, and high-fiber ingredient for diverse food applications. Its use is expanding rapidly in European baked goods and pasta, appealing to consumers seeking non-soy, low-carb alternatives.
- Whole Lupin:Whole lupin seeds are primarily used in traditional culinary dishes and as a direct protein source in animal feed formulations.
- Lupin Snacks:Lupin snacks include roasted seeds or extruded products, gaining traction among health-conscious consumers in Australia seeking high-protein, convenient options.
Whole Lupin leads on scale; Lupin Protein leads on momentum.
End Use:
Application versatility dictates the adoption rates for lupin ingredients across various industries.
- Food & Beverages:The food and beverage sector utilizes lupin flour, protein, and isolates in plant-based dairy, meat analogs, baked goods, and pasta for nutritional enhancement. This segment experiences significant growth in European and North American markets due to surging consumer demand for sustainable, high-protein alternatives.
- Animal Feed:Animal feed incorporates lupin kernel meal as a cost-effective, protein-rich ingredient for livestock, poultry, and aquaculture diets. Australia's extensive agricultural industry drives high-volume demand for lupin in ruminant and aquaculture feed formulations.
- Nutraceuticals:Nutraceutical applications explore lupin peptides and extracts for their potential health benefits, targeting functional food and dietary supplement markets.
- Personal Care:Personal care products integrate lupin extracts and proteins into skincare and haircare formulations for their moisturizing and anti-aging properties.
The Food & Beverages segment represents the fastest-growing trajectory, while Animal Feed maintains its high-volume position.
Form:
Supply concentration influences the availability and processing requirements for different lupin forms.
- Powder:Powdered lupin forms, including flour and protein isolates, offer ease of incorporation into diverse food and feed matrices due to fine particle size. This form is crucial for industrial food formulation in Europe and North America, enabling precise ingredient blending and functional properties.
- Extract:Lupin extracts, derived through solvent-based or aqueous processes, concentrate specific bioactive compounds like peptides or alkaloids for specialized applications. Demand for these high-value forms is emerging in the nutraceutical and personal care industries, particularly in France and Germany.
- Whole Seed:Whole lupin seeds are primarily traded as raw agricultural commodities for direct consumption, animal feed, or further processing into other forms.
- Granule:Granulated lupin products, such as textured protein or feed pellets, provide specific textural properties and facilitate handling in industrial applications.
Powdered lupin forms capture broad market utility, while extracts command higher value margins.
Distribution Channel:
Customer types and purchasing habits define the prevalent distribution channels for lupin products.
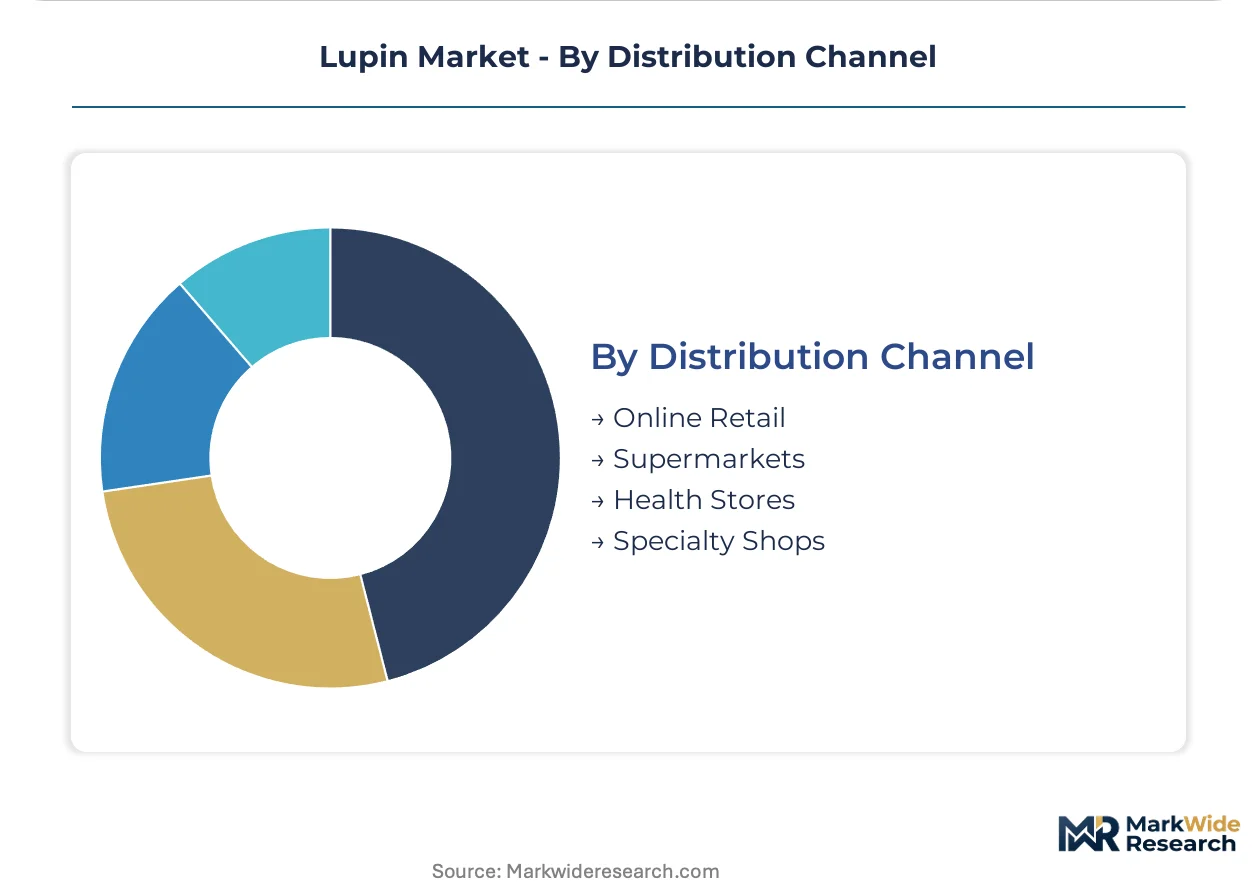
- Online Retail:Online retail platforms facilitate direct-to-consumer sales of lupin flour, snacks, and specialty products, offering broad geographical reach and convenience. This channel is expanding rapidly in the United States and Canada, catering to flexitarian consumers seeking niche plant-based ingredients.
- Supermarkets:Supermarkets provide mainstream access to lupin-fortified products like baked goods, pasta, and plant-based alternatives through established grocery supply chains. European consumers frequently encounter lupin ingredients in everyday products stocked in major supermarket chains across Germany and the UK.
- Health Stores:Health stores focus on natural and organic products, offering specialized lupin items to health-conscious consumers seeking specific dietary benefits.
- Specialty Shops:Specialty shops, including artisanal bakeries and ethnic food stores, cater to niche markets with unique lupin-based products and traditional preparations.
Supermarkets represent a mature distribution channel for lupin, while Online Retail exhibits dynamic market penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia has historically anchored the global lupin market as a primary producer and exporter of sweet lupin varieties. European policy initiatives and evolving consumer preferences for plant-based nutrition have since expanded the market's geographic reach. This expansion now drives demand across diverse regions.
Australia
Australia's lupin market thrives on high-volume animal feed applications and the growing popularity of lupin-based snacks. The country's Department of Agriculture, Fisheries and Forestry supports research into drought-resistant cultivars. Western Australia remains the primary hub for sweet lupin cultivation and processing, supplying global export markets.
Germany
Germany exhibits strong demand for lupin flour and protein isolates in plant-based dairy alternatives and gluten-free baked goods. European Food Safety Authority guidelines influence ingredient approval and labeling for new food products. Food innovation clusters in cities like Munich are actively integrating lupin into novel food formulations.
France
French demand for lupin extracts and peptides is emerging in high-value nutraceutical and personal care applications. The country's national health agency (ANSM) oversees the safety and marketing of dietary supplements and cosmetic ingredients. Research institutions in the Paris region are exploring advanced extraction techniques for lupin bioactives.
United States
United States consumers drive demand for lupin in gluten-free baked goods and plant-based meat analogs. The U.S. FDA mandates clear allergen labeling for lupin-containing food products. California's vibrant plant-based food industry actively incorporates lupin into new product development.
Canada
Canada sees rising interest in lupin flour and protein for non-soy, plant-based snacks and specialty food items. Health Canada provides guidelines for novel food ingredients and allergen declarations. Toronto's burgeoning food tech scene is exploring lupin's versatility in functional food applications.
Lupin Market Key Industry Players
Premium-margin players sit above commodity-margin players across processing sophistication and product purity in the lupin market. The market structure features specialized seed breeders focused on yield and alkaloid reduction, alongside advanced ingredient processors creating high-value protein isolates. Integrated agricultural solution providers also compete by offering comprehensive crop protection and seed treatments. Companies frequently engage in strategic partnerships to expand their geographical reach and invest heavily in genetic breeding programs to enhance cultivar performance.
Within the specialized breeding and agricultural solutions tiers, Groupe Limagrain, a French agricultural cooperative, exemplifies expertise in developing enhanced lupin cultivars with improved yield and reduced alkaloid content. BASF SE, a German chemical giant, occupies a position among providers of comprehensive crop protection and seed treatments essential for optimizing lupin cultivation across various geographies. Cargill, Incorporated, a globally diversified agricultural conglomerate, represents large-scale ingredient processing capabilities within the broader plant-based protein sector, facilitating market access for lupin-derived products. These entities collectively drive innovation in lupin genetics and processing technologies.
| Leading Market Players |
|---|
| Groupe Limagrain |
| Dunstan Nutrition |
| Lupin Pharmaceuticals |
| Hemp Foods Australia |
| Sakata Seed Corporation |
| BASF SE |
| Agro-100 |
| Lupin Limited |
| Cargill, Incorporated |
| Others |
Cost & Logistics Intelligence
Specialized agricultural expertise in Western Australia, crucial for high-yield sweet lupin cultivation, directly influences input costs. These labor-cost differentials contribute to the pricing tiers observed across raw commodities and processed ingredients.
Pricing Analysis
Contract-based long-term offtake agreements define pricing for bulk lupin commodities. Price differentiation stems from alkaloid content reduction and specific protein purity levels. Pricing softness reflects increasing competition from other plant-based proteins in the food ingredient sector. Animal feed manufacturers exhibit higher price sensitivity compared to premium nutraceutical formulators.
Supply Chain Analysis
The availability of skilled agricultural labor in Western Australia heavily influences lupin seed production capacity. Supply concentration centers on Australia for raw lupin seeds, with advanced processing for isolates occurring in Europe. Raw material dependencies include specialized lupin seeds and processing enzymes. Single-source vulnerability to climate-related production risks in Australia represents a structural risk, while distribution runs through agricultural commodity traders and specialized ingredient distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lupin market presents a compelling margin-expansion story, driven by the shift towards high-value protein isolates and flour. Genetic breeding programs for low-alkaloid cultivars offer a significant cost-down driver by reducing processing needs.
For Market Incumbents: Hedge against climate-related production risks by diversifying sourcing beyond Western Australia into new cultivation regions. Invest in advanced processing infrastructure to reduce reliance on commodity-grade sales, mitigating margin pressure from price-sensitive animal feed segments. Develop proprietary low-alkaloid lupin varieties through R&D to counter allergenicity concerns and expand market access.
For New Entrants and Emerging Players: Enter via specialized nutraceutical and personal care applications, leveraging lupin peptides and extracts for high-value formulations. The North American market, particularly the United States, represents a highly penetrable geography for novel lupin-fortified foods. Focus on clean-label, non-soy protein claims to differentiate products and appeal to flexitarian consumers.
For Investors and Strategic Acquirers: Large food and beverage conglomerates are the most active acquirers in this space, seeking to integrate plant-based protein sources. The market exhibits strong long-term viability over the next decade, driven by sustainable food system policies. Target acquisition archetypes include specialized lupin processing facilities with advanced protein extraction capabilities. Watch for regulatory approvals of novel lupin cultivars as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Genetic Breeding Program Investment | Reduces alkaloid content, enhancing food safety and expanding market acceptance for lupin ingredients. |
| Geographic Cultivation Diversification | Mitigates supply chain risks from climate variability in Western Australia, ensuring consistent raw material flow. |
| Advanced Protein Extraction Facilities | Scales production of high-purity lupin protein isolates for premium plant-based food formulations. |
| Allergen Management Protocol Development | Ensures compliance with U.S. FDA and EFSA labeling regulations, facilitating broader market access. |
| North American Market Entry Strategy | Captures flexitarian consumer demand for novel, gluten-free protein sources in the United States and Canada. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary insights with secondary validation. Primary research involved discussions with seed breeders, food formulators, agricultural commodity traders, and regulatory specialists. Secondary data sources included EFSA reports, U.S. FDA guidelines, agricultural department publications, and academic research. A bottom-up data aggregation and top-down market sizing approach ensured robust triangulation.
Historical performance across the reference period anchored the forecast framework, projecting market evolution over the analysis window. Segmentation dimensions modeled included product type, end-use, form, and geographic region. Compound Annual Growth Rates were derived from historical growth trends and projected demand-side shifts. Key forecast inputs included plant-based food adoption rates and sustainable agriculture policy impacts.
The model holds under current regulatory stability and consumer preference trends; deviation in allergenicity breakthroughs or major climate events would shift projections. Forecasts reflect assumptions regarding agricultural policy support and protein innovation. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Europe Amaranth Market
Seeds
Europe Seed Market
Seeds
China Seed Market
Seeds
North America Alfalfa Seed Market
Seeds
Europe Flaxseeds Market
Seeds
Chamomile Seeds Market
Seeds
Global Packaged Chia Seeds Market
Seeds
Sweet Corn Seeds Market
Seeds
Safflower Seeds Market
Seeds
Australia Oilseed Market
Seeds
Dragon Fruit Seeds Market
Seeds
Celery Seed Oil Market
Seeds
Agricultural Seeder Market
Seeds
Punnet Market
Seeds
Southeast Asia Vegetable Seed Market
Seeds
Seed Cracker Market