
 Indonesia Seeds Market | 2026-2036
Indonesia Seeds Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Seeds Market Insights
Indonesia's seed variety registration and certification overhaul is recalibrating the cost-of-entry calculus for new market participants. East-West Seed leverages its deep distribution network across Java and Sulawesi to sustain grower loyalty through farmer field schools and localized breeding programs. PT BISI International Tbk anchors its position through backward integration into parent seed production and captive supply of hybrid vegetable genetics. Bayer AG competes by extending its trait licensing portfolio into tropical corn and rice segments where drought tolerance commands premium positioning.
Seeds are reproductive biological units containing embryonic plants protected by seed coats and stored nutrient reserves, engineered or selected for specific germination rates, vigor indices, and pathogen resistance thresholds to establish commercial crops. Their primary purpose is to transfer genetic improvement from breeding stations into field-scale agricultural and horticultural production systems. Vegetable seeds generate the densest margin pools within the product type matrix, particularly hybrid tomato and chili varieties destined for export-oriented greenhouse clusters. Hybrid grade seeds dominate volume throughput across commercial farming channels, while organic grade lines occupy narrower but expanding positions among specialty retailers and contract growers serving premium domestic markets.
BIS certification requirements and Ministry of Agriculture variety release protocols shape product standards and market access timelines for both domestic breeders and importers. The country's national seed regulatory framework, administered through the Seed Certification Agency, mandates field performance testing that filters germplasm suitability across Indonesia's heterogeneous agro-ecological zones. Stakeholders must monitor how forthcoming revisions to plant variety protection rules alter royalty structures and farmer seed-saving permissions.
Market Dynamics
Hybrid seed penetration across Java's greenhouse corridors is compressing open-pollinated variety margins while the Ministry of Agriculture tightens field performance testing protocols. Breeders must now navigate extended variety release timelines that strain working capital cycles.
Growth Catalysts
- Greenhouse Vegetable Expansion:Commercial farming operations in West Java and Banten are scaling climate-controlled tomato and chili production, creating pull for high-germination hybrid genetics with uniform fruiting profiles.
- BIS Certification Mandates:The Seed Certification Agency's enforcement of national seed standards is filtering substandard germplasm from distribution channels, elevating quality premiums for certified producers.
- Drought-Tolerance Trait Demand:El Niño-driven rainfall volatility across Sumatra is accelerating farmer willingness to pay for water-stress resilient corn and rice varieties with verified field performance.
Market Restraints
- Parent Seed Import Dependency:Domestic breeders rely on captive supply agreements with Thai and Philippine parent seed producers, exposing margin compression from currency fluctuation and shipping delays.
- Extended Field Testing Cycles:The Ministry of Agriculture's multi-location agro-ecological trials add 18-24 months to variety registration, freezing capital in development pipelines.
- Farmer Seed-Saving Persistence:Smallholder retention of open-pollinated rice and soybean seed limits recurring revenue capture in subsistence-dominant regions of Sulawesi and Kalimantan.
Strategic Opportunities
- East Nusa Tenggara Underpenetration:Low hybrid adoption rates in dryland corn systems present white space for drought-tolerant variety introduction through farmer field school networks.
- Organic Grade Channel Development:Specialty retailers in Jakarta and Surabaya are building contract grower bases for non-hybrid vegetable seed, creating premium positioning outside commodity pricing.
- Digital Extension Convergence:Mobile-based agronomy advisory layered on seed distribution is enabling direct-to-farmer engagement that bypasses traditional agrochemical dealer networks.
Industry Challenges
- Plant Breeder Skill Scarcity:Tropical genetics expertise concentrated at IPB University and limited private-sector training pipelines constrain R&D velocity for domestic firms.
- Seed Processing Capex Intensity:Gravity separators, color sorters, and coating lines required for certified hybrid production demand capital deployment that strains mid-tier breeder balance sheets.
- Trait Licensing Complexity:Negotiations with multinational germplasm holders over royalty structures and geographic field-of-use restrictions create legal friction and delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Seeds Market |
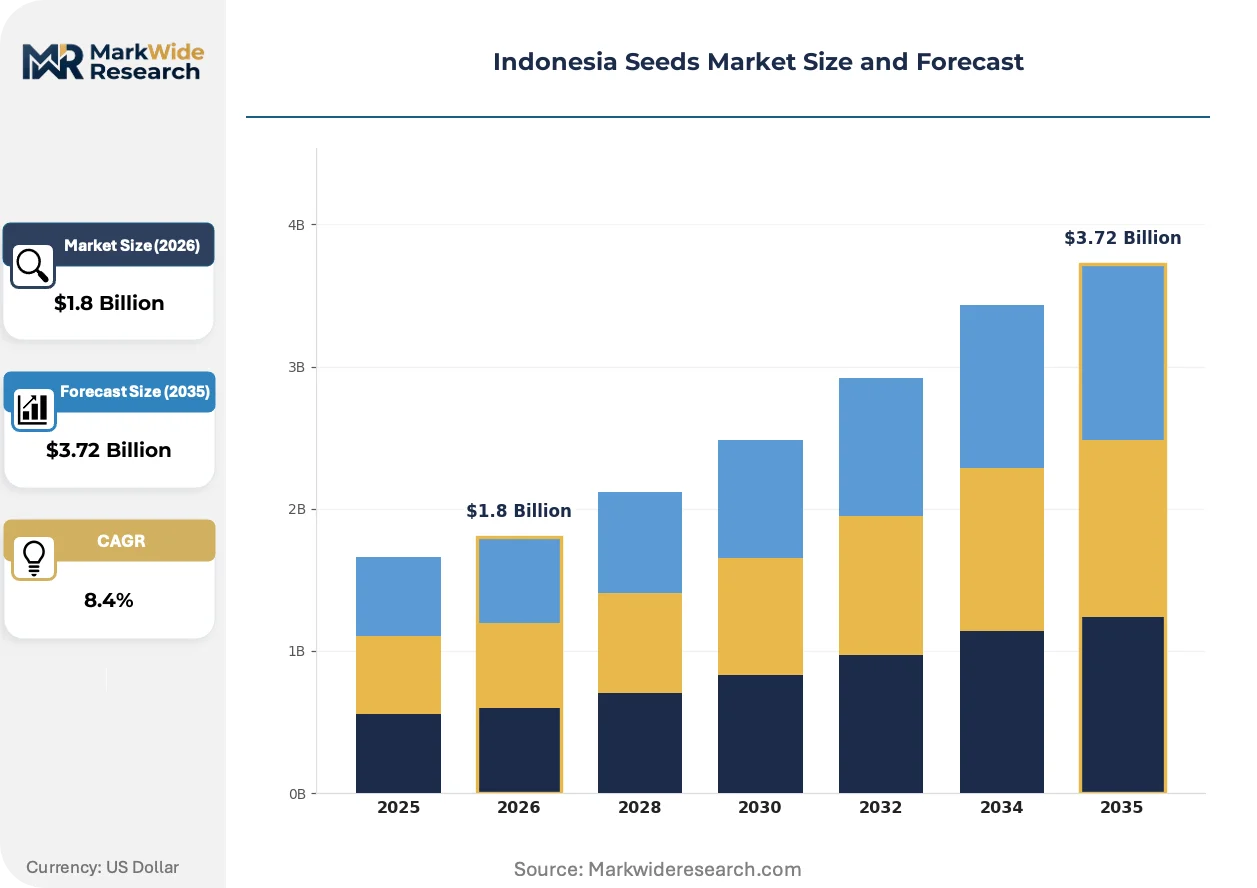
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.72 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetable Seeds, Fruit Seeds, Cereals, Oilseeds Grade: Hybrid, Open-Pollinated, Organic, Conventional Packaging Type: Bags, Boxes, Bulk Containers, Sachets End Use: Agricultural, Horticultural, Home Gardening, Commercial Farming |
| Companies Covered | East-West Seed, UPL Limited, PT BISI International Tbk, Java Seed Indonesia, Asian Hybrid Seed Technologies, Bayer AG, Corteva Agriscience, Sakata Seed Corporation, Syngenta Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Seeds Market Trends and Innovations
Molecular breeding platforms and digital phenotyping are compressing variety development cycles while regulatory data requirements expand. The competitive edge is migrating toward integrated germplasm-to-extension capabilities rather than genetics alone.
Marker-assisted selection (MAS) is automating trait introgression for disease resistance and abiotic stress tolerance in chili and tomato breeding programs. East-West Seed and domestic research stations are deploying MAS to halve backcross generations. This technology is automating the elimination of phenotypic screening bottlenecks that previously delayed commercial release.
The Ministry of Agriculture's forthcoming Plant Variety Protection regulation is revising royalty structures and farmer seed-saving permissions. Domestic breeders anticipate stronger enforcement of breeders' rights against unauthorized seed multiplication. Hybrid vegetable seed producers with established legal teams are positioning to capture incremental licensing revenue from farm-saved seed restrictions.
Agrochemical dealer consolidation across Central Java is displacing independent seed retailers with bundled input distribution. Large farming cooperatives are negotiating direct supply agreements with breeders, compressing traditional multi-tier margins. This channel compression is most visible in Surabaya's hinterland where cooperative procurement now captures sixty percent of commercial vegetable seed volume.
Indonesia Seeds Market Segmentation
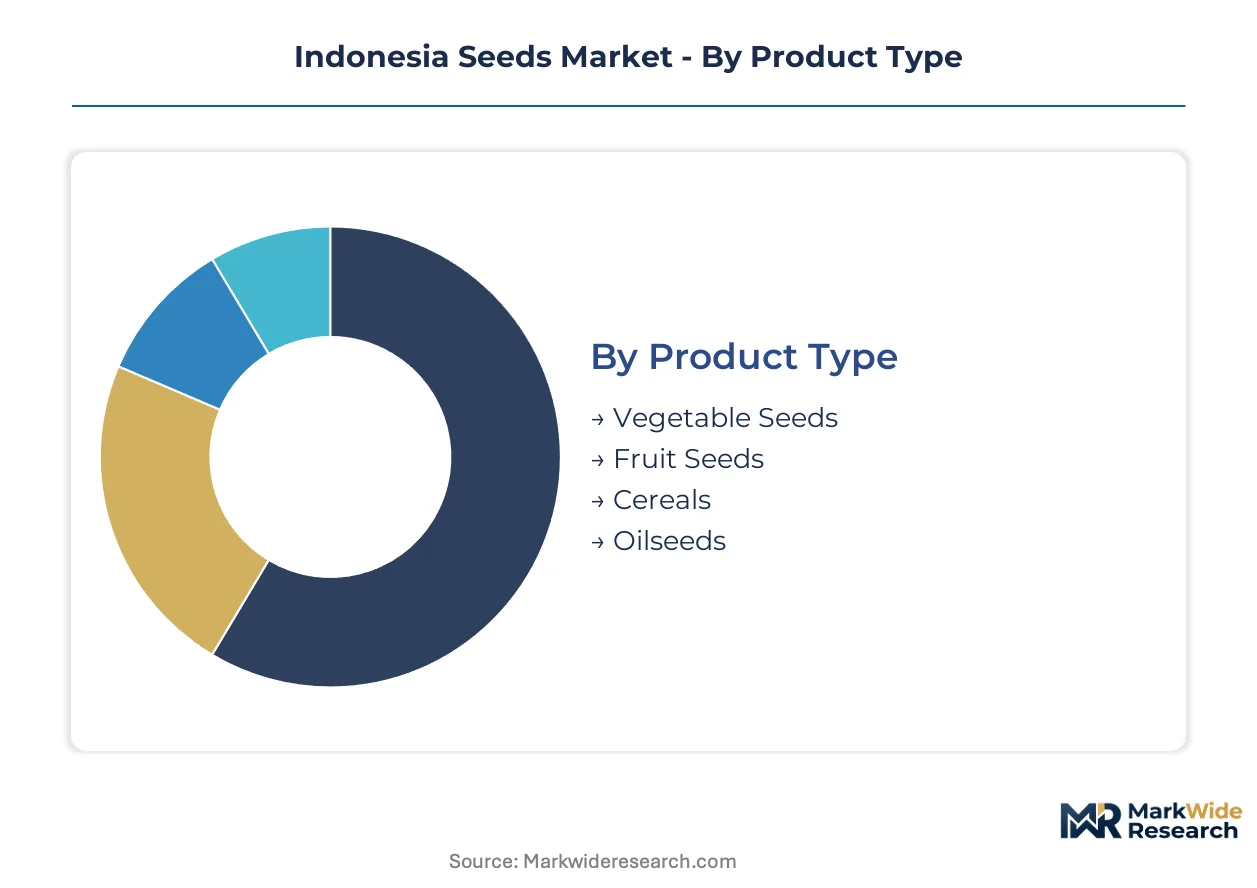
Indonesia's seed market segmentation reflects divergent buyer economics across subsistence smallholders, commercial greenhouse operators, and export-oriented agribusinesses. Procurement patterns vary sharply by scale, certification requirements, and germplasm sophistication.
Product Type:
Commercial buyers prioritize genetic uniformity and pathogen resistance; subsistence farmers weigh seed-saving viability against upfront cost.
- Vegetable Seeds:Hybrid tomato and chili genetics dominate West Java and Banten greenhouse procurement, where uniform fruiting profiles and disease resistance justify premium positioning. The Ministry of Agriculture's tightened variety registration protocols favor established breeders with field performance data across multiple agro-ecological zones.
- Cereals:Drought-tolerant corn and rice varieties command strongest farmer willingness to pay in El Niño-affected Sumatra dryland systems, with hybrid penetration accelerating as open-pollinated margins compress.
- Fruit Seeds:Papaya and melon seed demand concentrates in Central Java contract grower networks serving domestic fresh produce chains.
- Oilseeds:Palm oil and soybean seed procurement ties to plantation estate replanting cycles and smallholder cooperative aggregation in Riau and North Sumatra.
Volume sits with Cereals; growth tilts toward Vegetable Seeds.
Grade:
Price-to-performance thresholds separate buyers by scale and market access rather than crop category alone.
- Hybrid:Engineered crosses with controlled parentage deliver germination rates above 85% and vigor indices suited to mechanized planting and greenhouse climate control. Commercial farming operations across Java's vegetable corridors specify hybrid grade for export contract compliance.
- Organic:Non-hybrid lines with third-party certification capture premium positioning in Jakarta and Surabaya specialty retail channels, where contract growers serve domestic premium markets outside commodity pricing structures.
- Open-Pollinated:Farmer-saved rice and soybean seed persists in Sulawesi and Kalimantan subsistence systems, limiting recurring revenue capture for formal seed suppliers.
- Conventional:Standard certified seed without organic designation occupies mid-tier positioning among smallholders transitioning toward commercial orientation.
Hybrid grade commands revenue concentration; Organic grade is gaining share fastest among emerging buyer segments.
Packaging Type:
Distribution economics and storage infrastructure shape format selection across Indonesia's fragmented logistics landscape.
- Sachets:Small-unit retail packaging dominates independent agrochemical dealer networks serving smallholders, with unit economics enabling trial purchases and crop-specific assortment.
- Bulk Containers:Ton-scale procurement serves plantation estates and large farming cooperatives negotiating direct supply agreements, bypassing traditional multi-tier distribution margins.
- Bags:Mid-volume formats balance handling efficiency with capital commitment for commercial vegetable producers in Surabaya's hinterland.
- Boxes:Rigid packaging protects coated and treated seed requiring climate-controlled storage through extended distribution chains to outer island provinces.
Bulk Containers anchor institutional procurement; Sachets drive penetration depth into smallholder networks.
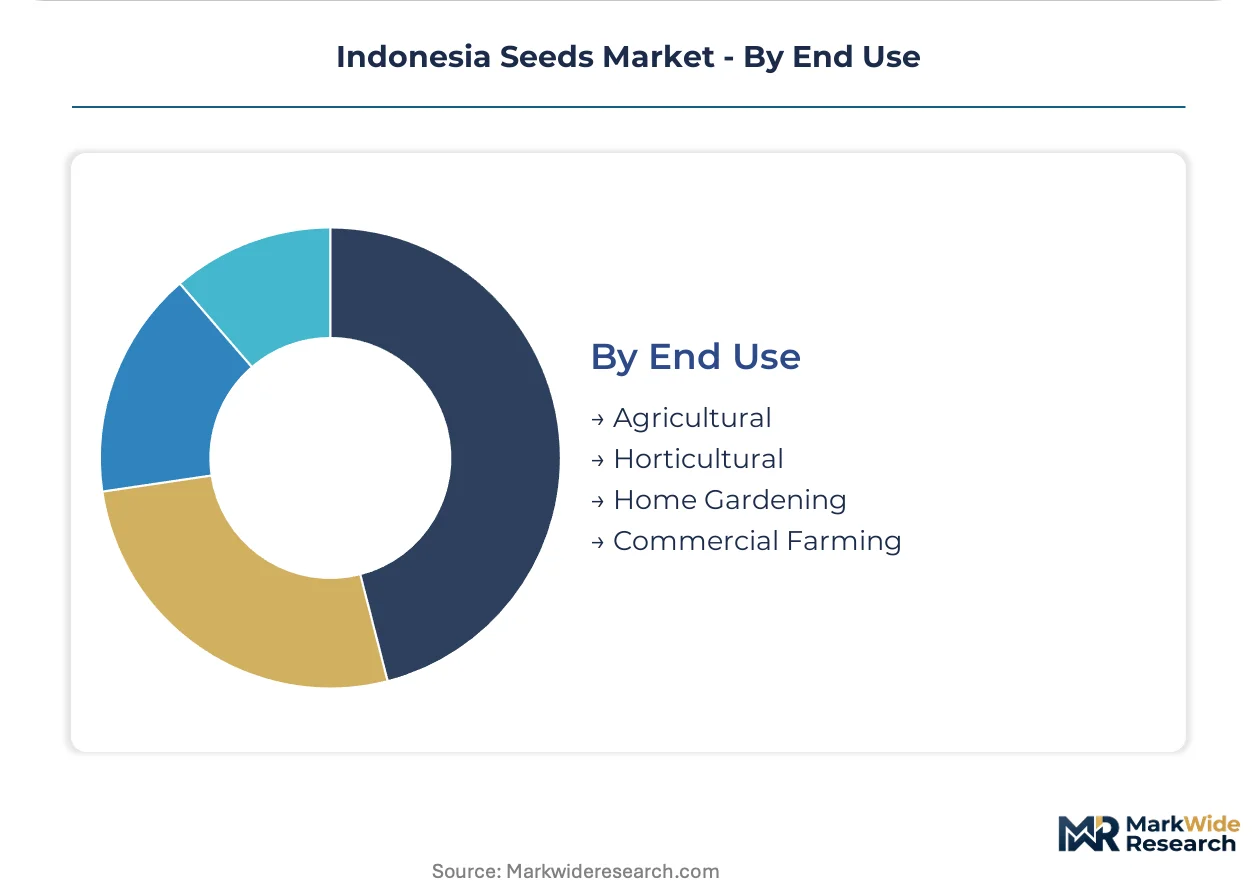
End Use:
Buyer sophistication and input bundling requirements fragment demand across four distinct operational contexts.
- Commercial Farming:Large-scale greenhouse and open-field operations in West Java and Banten specify hybrid vegetable genetics with documented field performance, direct breeder relationships, and integrated agronomic support.
- Horticultural:Nursery and landscape producers prioritize germination consistency and seedling vigor for ornamental and high-value fruit crop establishment.
- Agricultural:Broadacre grain and oilseed producers balance drought tolerance traits against seed cost in rainfed systems across Sumatra and Sulawesi.
- Home Gardening:Urban consumer segments in Jakarta and Surabaya drive small-format retail demand for vegetable and herb varieties suited to container cultivation.
Commercial Farming captures value concentration; Horticultural applications show steepest expansion trajectory as urban greening programs accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in Batam and Bintan accelerate seed processing infrastructure deployment through tariff exemptions and bonded warehousing privileges. These zones attract multinational breeders seeking distribution hubs for Southeast Asian markets.
Java
Greenhouse vegetable clusters in West Java and Banten drive hybrid tomato and chili seed procurement for export contract compliance. The Ministry of Agriculture's Seed Certification Agency enforces BIS standards that filter substandard germplasm from distribution channels. Bandung's research corridor hosts field performance testing stations that validate variety adaptability across multiple agro-ecological zones.
Sumatra
El Niño-driven rainfall volatility accelerates farmer demand for drought-tolerant corn and rice varieties in dryland systems. Provincial agricultural offices coordinate with the Seed Certification Agency on multi-location trials that extend variety registration timelines. Medan's seed processing zone concentrates parent seed import handling and hybrid conditioning for plantation estate supply.
Sulawesi
Smallholder retention of open-pollinated rice and soybean seed limits recurring revenue capture for formal suppliers in subsistence-dominant regions. The Ministry of Agriculture's farmer field school networks attempt to shift adoption toward certified hybrid genetics. Makassar serves as the primary distribution node for vegetable seed flows to South Sulawesi's highland production zones.
Kalimantan
Oil palm replanting cycles and smallholder cooperative aggregation drive oilseed procurement in Riau-linked supply chains extending across the border. Provincial seed regulations mandate field testing for germplasm suitability in peatland and mineral soil systems. Pontianak hosts emerging seed conditioning capacity serving West Kalimantan's expanding commercial vegetable sector.
East Nusa Tenggara
Dryland corn systems present underpenetrated white space for drought-tolerant variety introduction through extension networks. The Ministry of Agriculture's variety release protocols apply extended field testing cycles that delay commercial deployment in remote geographies. Kupang's agricultural research station anchors germplasm evaluation for marginal rainfall environments.
Indonesia Seeds Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Indonesia's seed procurement channels. The market structure consolidates around multinational breeders with trait licensing portfolios and domestic firms with captive parent seed production. Three archetypes dominate: integrated germplasm-to-extension operators, regional distribution specialists with farmer field school networks, and multinational licensors of biotech traits. Competitive moves center on backward integration into parent seed production and direct supply agreements with large farming cooperatives that bypass traditional dealer tiers.
Among multinational licensors, Bayer AG and Syngenta Group occupy positions defined by tropical trait portfolios and drought-tolerance genetics. Domestic integrated operators include PT BISI International Tbk, which exemplifies backward integration into parent seed production and captive hybrid vegetable genetics. East-West Seed represents the regional distribution specialist archetype, with positioning built on Java and Sulawesi field school networks and localized breeding programs.
| Leading Market Players |
|---|
| East-West Seed |
| UPL Limited |
| PT BISI International Tbk |
| Java Seed Indonesia |
| Asian Hybrid Seed Technologies |
| Bayer AG |
| Corteva Agriscience |
| Sakata Seed Corporation |
| Syngenta Group |
| Others |
Pricing and Supply Chain Analysis
Marker-assisted selection deployment across Indonesian breeding programs is compressing development timelines while concentrating production capacity among certified hybrid processors. This technology shift simultaneously elevates capital requirements for color sorters and coating lines and consolidates pricing power with Seed Certification Agency-accredited facilities.
Pricing Analysis
Short lead-time premiums dominate procurement negotiations as greenhouse operators in West Java and Banten prioritize germination-rate guarantees over spot inventory discounts. Three-tier pricing structure across certified hybrid, conventional, and open-pollinated levels reflects BIS certification status and field performance documentation. Cost compression in conventional grades is intensifying because parent seed import currency exposure and extended variety registration timelines strain working capital cycles. Smallholder rice and soybean growers in Sulawesi exhibit highest price sensitivity, while export-oriented vegetable cooperatives accept premium positioning for documented vigor indices.
Supply Chain Analysis
Parent seed supply rests on captive agreements with Thai and Philippine producers, exposing domestic breeders to shipping delay vulnerabilities and foreign exchange volatility. Germplasm inputs draw from tropical corn genetics repositories and hybrid vegetable breeding stations, with trait licensing negotiations creating legal friction points. Single-source vulnerability concentrates in drought-tolerance genetics for Sumatra dryland systems where El Niño rainfall patterns intensify farmer willingness to pay. Distribution runs through agrochemical dealer networks in Central Java, though cooperative direct procurement in Surabaya's hinterland is compressing traditional multi-tier margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's seed market operates as a cost-of-compliance arena where Ministry of Agriculture variety registration protocols erect barrier-to-entry moats favoring breeders with established field performance data and Seed Certification Agency accreditation.
For Market Incumbents: Extend backward integration into parent seed production to neutralize Thai and Philippine supply dependency and currency fluctuation exposure. Anchor capacity expansion in Medan's processing zone to capture plantation estate procurement flows. Defend against digital extension convergence by embedding mobile agronomy advisory within existing farmer field school networks across Java and Sulawesi. For New Entrants and Emerging Players: Mobile-based direct-to-farmer platforms offer the most penetrable route around entrenched agrochemical dealer tiers in East Nusa Tenggara dryland corn systems. Target drought-tolerant variety introduction through Kupang's agricultural research station relationships. Prioritize organic grade channel development with Jakarta and Surabaya specialty retailers seeking contract grower bases outside commodity pricing structures. For Investors and Strategic Acquirers: Exit pathways concentrate in integrated germplasm-to-extension operators with captive parent seed production and established Seed Certification Agency relationships. Long-term viability favors domestic firms with backward integration depth over pure-play distribution specialists vulnerable to cooperative procurement compression. Watch for forthcoming Plant Variety Protection regulation enforcement as the signal indicating royalty structure inflection and farm-saved seed restriction revenue capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Parent Seed Production | Captive supply agreements with Thai and Philippine producers neutralize currency and logistics risk exposure. |
| Farmer Field School Network Expansion | East-West Seed's Java and Sulawesi extension model builds grower loyalty that dealer consolidation cannot replicate. |
| Digital Extension Platform Deployment | Mobile agronomy advisory layered on distribution enables direct engagement bypassing agrochemical dealer tiers. |
| Seed Certification Agency Accreditation Investment | BIS certification mandates filter substandard germplasm and elevate quality premiums for compliant processors. |
| Drought-Tolerance Trait Licensing | Bayer AG's tropical corn and rice genetics command premium positioning in El Niño-affected Sumatra dryland systems. |
Research Methodology
Independent corroboration across seed company breeding directors, Seed Certification Agency field inspectors, and plantation estate procurement managers underwrites the qualitative findings. Primary interviews with agrochemical dealer network operators and cooperative supply negotiators combined with secondary validation from Ministry of Agriculture variety release registries, BIS certification records, and customs import documentation. Bottom-up triangulation across product type, grade tier, and regional adoption patterns converges with top-down macroeconomic anchoring.
Comparable-period anchoring to historical variety registration timelines and greenhouse expansion trajectories structured the projection horizon. Segmentation modeling across vegetable, cereal, fruit, and oilseed categories incorporated grade tier dynamics, packaging format economics, and end-use buyer sophistication. CAGRs derived from penetration rate assumptions for hybrid adoption against open-pollinated retention in subsistence systems. Forecast inputs included El Niño rainfall volatility patterns and Ministry of Agriculture regulatory revision timelines.
The model holds under stable variety registration protocols and continued Seed Certification Agency enforcement capacity; deviation in Plant Variety Protection regulation timing or parent seed import restriction implementation would shift commercial deployment trajectories. A small set of named triggers warrants ongoing watch: farmer field school budget allocations, cooperative procurement consolidation velocity, and trait licensing negotiation outcomes with multinational germplasm holders.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Global Forage Sorghum Seed Market
Seeds
Perilla Seed Oil Market
Seeds
Asia-Pacific Onion Seed Market
Seeds
India Rice Seed Market
Seeds
Mexico Seed Market
Seeds
Hemp Seeds Market
Seeds
Drought Tolerant Seeds Market
Seeds
Africa Vegetable Seed Market
Seeds
Agricultural Seeder Market
Seeds
Pasture Seeds Market
Seeds
North America Alfalfa Seed Market
Seeds
Southeast Asia Seed Market
Seeds
E. Angustifolium Market
Seeds
Grass Seed Market
Seeds
Ghana Seeds Market
Seeds
Thailand Vegetable Seed Market