
 Sprouted Grains and Seeds Market | 2026-2036
Sprouted Grains and Seeds Market Size, Share, and Industry Trends Forecast 2026-2036
Sprouted Grains and Seeds Market Analytics
Specialty ingredient distribution is tilting toward direct partnerships between sprouted-grain mills and regional bakery chains, bypassing traditional broadline distributors. Bay State Milling Company leverages its East Coast milling infrastructure to supply customized sprouted-wheat blends to artisan bakeries. Bob's Red Mill Natural Foods Inc. sustains consumer pull through health-food store shelf dominance and transparent sourcing narratives. Ardent Mills competes on volume scale, operating multi-facility sprouting and milling networks that service national bread manufacturers.
Sprouted grains and seeds are cereal grains or oilseeds germinated under controlled moisture and temperature conditions until the enzymatic activity transforms starches into simpler sugars and raises amino acid bioavailability, typically reaching 0.5–2 mm rootlet length before drying or milling. This germination process enhances digestibility, reduces antinutrient content such as phytic acid, and elevates folate and gamma-aminobutyric acid concentrations for functional food and nutritional supplement applications. Whole grains and flours anchor the product mix, with flours commanding stronger margin pools due to ingredient-brand premiums in clean-label baking. Snacks represent the fastest-growing product type, propelled by portable protein positioning and sprouted-lentil or sprouted-quinoa crisp formulations targeting nutritional supplement adjacencies.
The FDA enforces gluten-free labeling standards and updated dietary fiber definitions that shape how sprouted-grain products communicate nutritional claims to retail consumers. USDA organic certification and FSMA preventive controls for human food govern sprouting facility sanitation, seed sourcing traceability, and pathogen mitigation protocols that determine market access for domestic and imported suppliers. Stakeholders must monitor evolving FDA enforcement priorities on sprouted-seed safety alerts and emerging state-level seed preemption disputes that could reshape interstate commerce rules for raw sprouted ingredients.
Market Dynamics
Controlled-atmosphere sprouting technology is compressing production cycles from 72 hours to 18 hours, forcing legacy batch facilities to retool or exit as enzymatic consistency becomes the baseline for bakery-chain procurement.
Growth Catalysts
- FSMA Preventive Controls:The FDA's hazard analysis mandates are consolidating sprouting operations toward HACCP-certified facilities, accelerating food safety investment and creating barrier-to-entry advantages for compliant mills.
- Clean-label bakery procurement:North American artisan bakery chains are specifying sprouted-wheat flour for bread programs, pulling volume through direct supplier relationships that bypass commodity distributors.
- Germination biotechnology:Precision moisture and temperature sensors are optimizing enzymatic conversion rates, reducing input waste and improving amino acid bioavailability yields for nutritional supplement applications.
Market Restraints
- Organic seed supply concentration:Certified organic wheat and quinoa seed stocks cluster in the Pacific Northwest and Saskatchewan, exposing processors to weather-driven input volatility and single-origin contamination risks.
- Phytic acid testing costs:Laboratory validation of antinutrient reduction claims adds per-batch expense that erodes margin on standard-grade sprouted flour.
- Raw sprout safety liability:FDA safety alerts on pathogen contamination in raw sprouted seeds are chilling foodservice demand and shifting buyer preference toward heat-treated or milled formats.
Strategic Opportunities
- German health-food retail expansion:dm-drogerie markt and Alnatura are dedicating shelf space to sprouted-seed snacks, creating premium positioning for imported sprouted-lentil and sprouted-buckwheat crisp products.
- USDA Organic certification arbitrage:EU-based sprouting facilities can capture US market access by dual-certifying under USDA organic and EU organic standards, exploiting transatlantic supply gaps.
- Sprouted-lupin protein isolation:Convergence of wet-milling technology and plant-protein extraction is opening functional food applications in sports nutrition and meat alternatives.
Industry Challenges
- Enzymologist talent scarcity:Facilities require specialists who can calibrate sprouting protocols for specific grain varieties, and compensation wars with biotech and brewing sectors are inflating payroll costs.
- Legacy ERP integration:Seed-to-shelf traceability mandates are forcing mid-sized mills to replace paper-based batch records with FSMA-compliant digital systems, stretching IT budgets and implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sprouted Grains and Seeds Market |
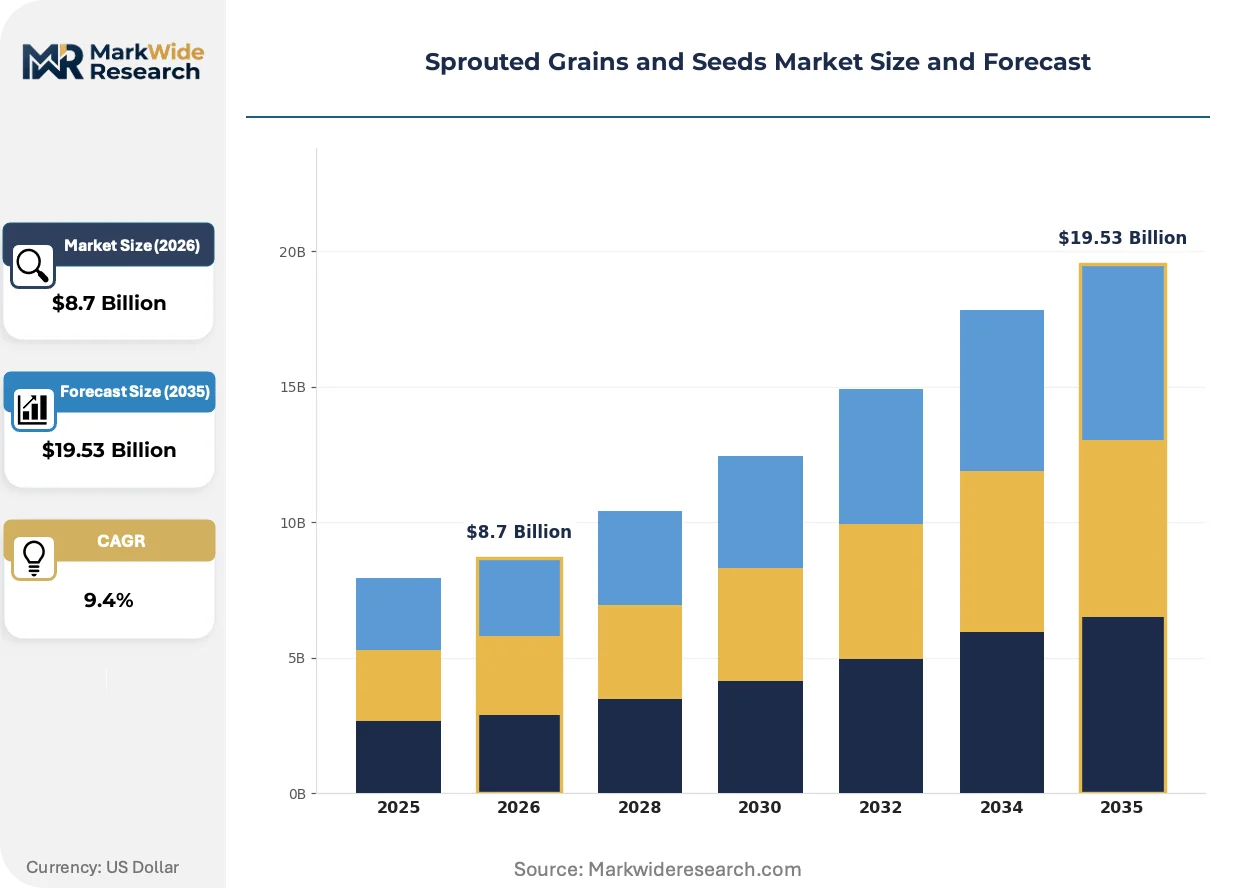
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Grains, Flours, Snacks, Beverages Application: Baking, Breakfast Foods, Salad Toppings, Nutritional Supplements End User: Retail Consumers, Food Service, Health Food Stores, Wholesalers Packaging Type: Bulk Packaging, Resealable Bags, Pouches, Glass Containers |
| Companies Covered | Food For Life Baking Company Inc., Bay State Milling Company, General Mills Inc., To Your Health Sprouted Flour Co., Everspring Farms, Archer Daniels Midland Company, MGP Ingredients Inc., Ardent Mills, Bob's Red Mill Natural Foods Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sprouted Grains and Seeds Market Evolving Landscape
Biotechnology and regulatory precision are converging to transform how sprouted grains move from seed sourcing to finished ingredient, with automation and certification protocols becoming primary competitive differentiators.
Continuous-flow sprouting chambers equipped with real-time spectroscopic monitoring are collapsing the quality variance between production batches. National bread manufacturers in the United States are retrofitting facilities with these systems to secure consistent enzymatic profiles for clean-label product lines. The technology is collapsing the historical trade-off between throughput and nutritional consistency that favored small-batch artisan producers.
EFSA's novel food guidance on sprouted hemp and chia seeds is tightening safety dossier requirements for European market entry. The regulation is forcing non-EU sprouting facilities to invest in clinical bioavailability studies and toxicology data packages. German and Dutch ingredient importers are responding by consolidating supplier audits and demanding pre-submitted EFSA compliance documentation.
Bakery-chain procurement teams are bypassing broadline distributors to contract directly with regional sprouted-grain mills, compressing price discovery cycles and demanding lot-specific certificates of analysis. This disintermediation is most visible in the Northeastern United States, where Bay State Milling and similar regional operators are building captive supply relationships with fast-casual sandwich chains.
Sprouted Grains and Seeds Market Segmentation
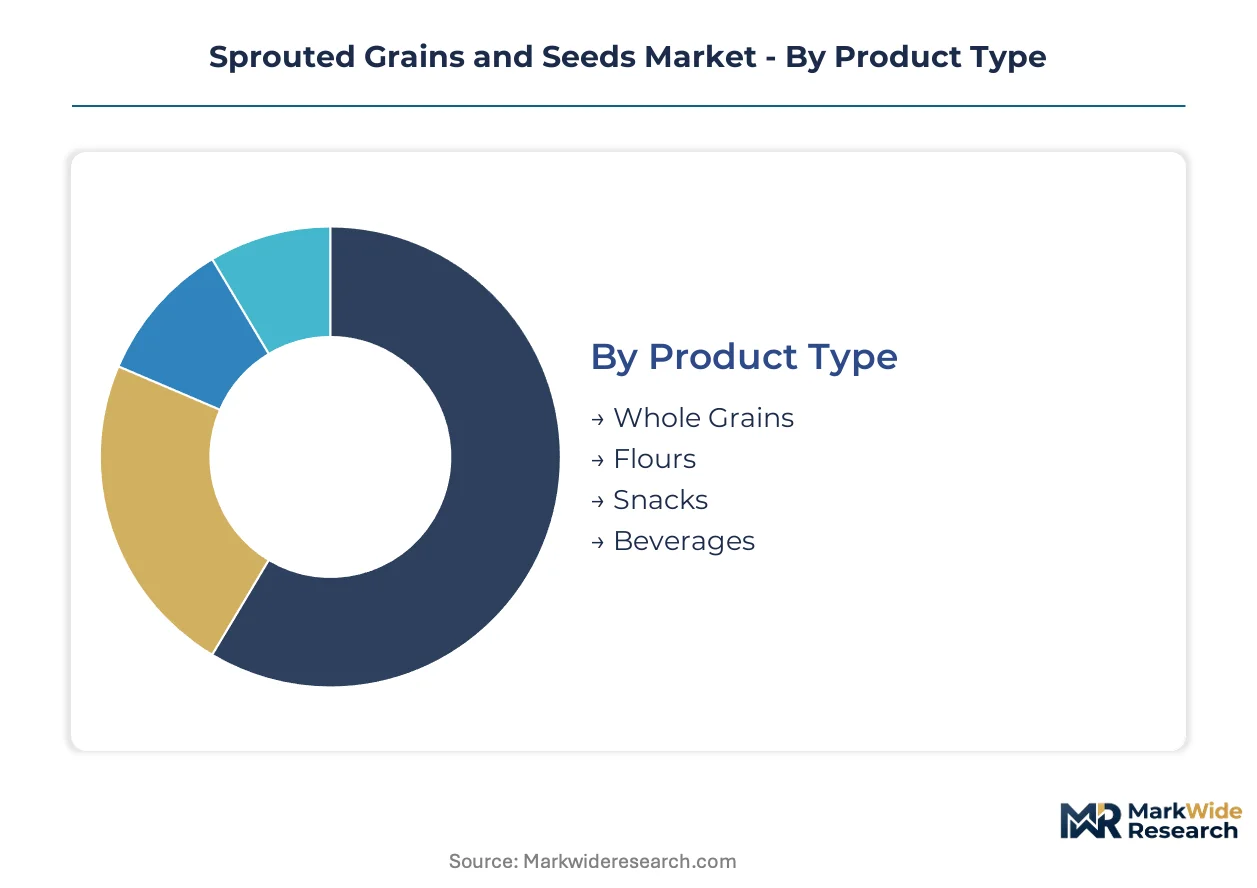
Segmentation in sprouted grains and seeds reveals divergent margin profiles and inventory velocities. Product format determines enzymatic stability windows, while packaging and channel choices dictate regulatory exposure and pathogen mitigation costs.
Product Type:
Cycle times compress from days for snacks to months for stabilized flours, reshaping working capital requirements across the value chain.
- Whole Grains:Germinated seeds dried at 0.5–2 mm rootlet length retain live enzymes requiring refrigerated distribution. Bay State Milling and Ardent Mills dominate procurement contracts with artisan bakeries seeking intact kernel texture for clean-label bread programs.
- Flours:Milled and heat-stabilized sprouted wheat and quinoa command ingredient-brand premiums in commercial baking. German health-food retail chains and North American bakery chains specify these for enzymatic consistency and extended shelf stability.
- Snacks:Sprouted-lentil and sprouted-quinoa crisps target portable protein positioning. dm-drogerie markt and Alnatura in Germany are expanding shelf space for these formats.
- Beverages:Sprouted-seed milks and functional drinks leverage elevated GABA and folate concentrations for nutritional supplement adjacencies.
Flours dominate installed base. Snacks are where expansion concentrates.
Application:
Margin tiers separate commodity baking from premium nutritional positioning, with regulatory scrutiny intensifying for raw-format applications.
- Baking:Clean-label bread programs at North American artisan bakery chains specify sprouted-wheat flour for enzymatic conversion of starches to simpler sugars. FDA gluten-free labeling standards and updated dietary fiber definitions shape claim language on packaging.
- Breakfast Foods:Cereals and granolas incorporate sprouted buckwheat and amaranth for digestibility positioning. Heat-treated formats predominate given FSMA preventive controls for human food.
- Salad Toppings:Raw sprouted seeds face chilled demand from FDA safety alerts on pathogen contamination. Foodservice buyers are shifting preference toward heat-treated or milled formats to mitigate liability exposure.
- Nutritional Supplements:Sprouted-lupin protein isolation and amino acid bioavailability concentrates target sports nutrition and meat alternative applications. EFSA novel food guidance on sprouted hemp and chia seeds is tightening European market entry requirements.
Baking commands volume share. Nutritional supplements follow the steepest expansion trajectory.
End User:
Channel concentration determines traceability investment intensity, with direct procurement relationships bypassing traditional distribution layers.
- Retail Consumers:Health-food store shelf dominance by Bob's Red Mill and transparent sourcing narratives drive pull-through. USDA organic certification governs purchase decisions.
- Food Service:Fast-casual sandwich chains in the Northeastern United States contract directly with regional sprouted-grain mills, compressing price discovery cycles and demanding lot-specific certificates of analysis.
- Health Food Stores:dm-drogerie markt and Alnatura in Germany dedicate expanding shelf space to sprouted-seed products, creating premium positioning for imported formats.
- Wholesalers:Traditional broadline distributors face disintermediation as bakery-chain procurement teams source directly from sprouted-grain mills for customized blends.
Health food stores anchor premium positioning. Food service is where procurement pattern disruption concentrates.
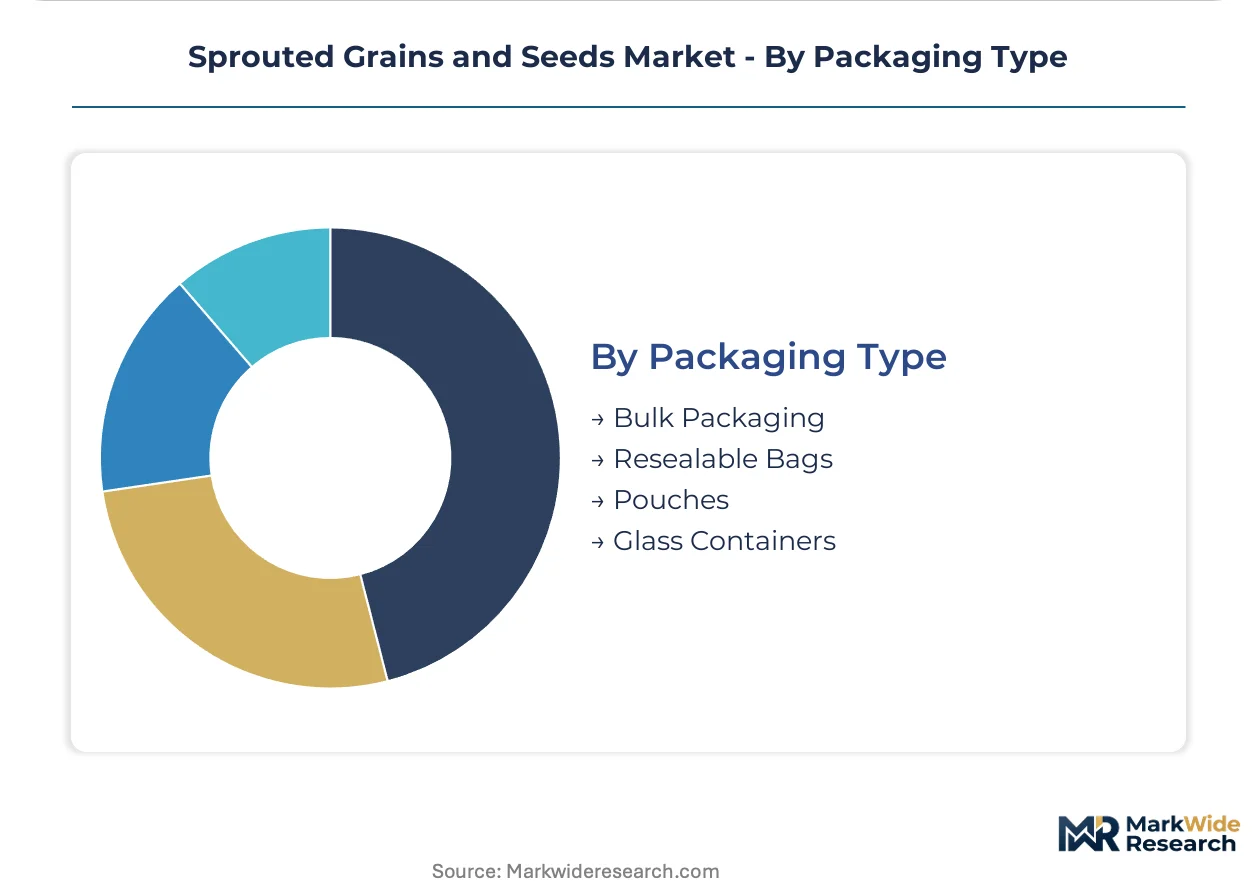
Packaging Type:
Packaging investment correlates with moisture sensitivity and pathogen risk, driving format selection across the value chain.
- Bulk Packaging:Industrial-scale flour shipments to national bread manufacturers prioritize cost efficiency over shelf-life extension. Multi-facility sprouting and milling networks service these contracts.
- Resealable Bags:Consumer-facing whole grains and snacks require oxygen barrier properties to preserve enzymatic activity. Health-food retail chains specify these for premium positioning.
- Pouches:Lightweight formats for sprouted-seed snacks target portability and reduced shipping cost. German health-food retail expansion favors this format for shelf efficiency.
- Glass Containers:Beverage applications and high-value nutritional supplements leverage perceived quality and chemical inertness. EFSA compliance documentation requirements add regulatory overhead for European market entry.
Bulk packaging dominates industrial volume. Pouches are where format innovation concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA enforcement of gluten-free labeling standards and FSMA preventive controls is reshaping procurement patterns across multiple jurisdictions. Germany's health-food retail chains are driving premium sprouted-wheat flour demand. North American bakery chains are expanding direct supplier relationships with regional mills.
United States
Artisan bakery chains in the Northeast specify sprouted-wheat flour for clean-label bread programs. FDA updated dietary fiber definitions tighten ingredient disclosure requirements for nutritional claims. Bay State Milling leverages East Coast milling infrastructure to supply customized blends to fast-casual sandwich chains.
Germany
dm-drogerie markt and Alnatura dedicate expanding shelf space to sprouted-seed snacks and premium flours. EFSA novel food guidance on sprouted hemp and chia seeds tightens safety dossier requirements for European market entry. Artisan bakeries in Bavaria and Baden-Württemberg drive regional procurement of sprouted-wheat flour.
Canada
Certified organic wheat and quinoa seed stocks concentrate in Saskatchewan, exposing processors to weather-driven input volatility. Health Canada enforces preventive controls for sprouting facility sanitation and pathogen mitigation. Prairie-based milling operations service cross-border demand from US bread manufacturers.
United Kingdom
Health-food retailers specify USDA organic certification for imported sprouted-grain products. FSA allergen labeling requirements intersect with gluten-free claim verification. London and Southeast England clusters concentrate distribution infrastructure for premium sprouted-seed formats.
India
FSSAI food safety standards govern sprouting facility licensing and seed sourcing traceability for domestic and export markets. Rising consumer awareness of digestibility benefits drives urban demand in Mumbai and Delhi-NCR. Maharashtra and Gujarat house emerging processing capacity for sprouted-lentil and quinoa value-added products.
Sprouted Grains and Seeds Market Competitive Landscape
On the supply side, the industry is consolidating toward HACCP-certified facilities with multi-facility sprouting and milling networks. Three archetypes dominate: regional specialty mills with direct bakery-chain relationships, national-scale ingredient suppliers with volume contracts, and health-food brands with consumer pull-through dominance. Competitive moves concentrate on disintermediation of traditional distributors and retrofitting legacy batch facilities with continuous-flow sprouting technology.
Within the regional specialty tier, Bay State Milling Company and Bob's Red Mill Natural Foods Inc. exemplify divergent positioning strategies. Ardent Mills anchors the scale-driven segment with multi-facility operational footprints. These three entities collectively illustrate how geographic concentration, certification portfolios, and channel access define competitive boundaries in sprouted-grain procurement.
| Leading Market Players |
|---|
| Food For Life Baking Company Inc. |
| Bay State Milling Company |
| General Mills Inc. |
| To Your Health Sprouted Flour Co. |
| Everspring Farms |
| Archer Daniels Midland Company |
| MGP Ingredients Inc. |
| Ardent Mills |
| Bob's Red Mill Natural Foods Inc. |
| Others |
Value Network & Pricing Analysis
Overcapacity in Pacific Northwest organic seed processing is compressing margins across standard-grade sprouted flour tiers while tightening premiums for certified organic and HACCP-validated supply. This utilization asymmetry rewards mills with backward integration into controlled-atmosphere sprouting technology and punishes legacy batch operators facing stranded asset risk.
Pricing Analysis
Volume-discount tiering separates national bread manufacturer contracts from artisan bakery direct procurement. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and enzymatic consistency validation. Price differentiation hinges on USDA organic certification and FSMA preventive control documentation. Cost compression in standard-grade tiers is intensifying because phytic acid testing adds per-batch laboratory expense. Foodservice buyers exhibit highest price sensitivity due to raw sprout safety liability chilling demand.
Supply Chain Analysis
Upstream feedstock concentration in Saskatchewan, the Pacific Northwest, and Germany shapes procurement risk profiles for North American and European mills. Certified organic wheat and quinoa seed stocks draw from weather-exposed prairie regions. Input dependencies center on germination biotechnology equipment, moisture sensors, and spectroscopic monitoring systems. Single-origin contamination risk in concentrated organic seed regions threatens supply continuity. Distribution runs through direct mill-to-bakery relationships that disintermediate traditional broadline distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
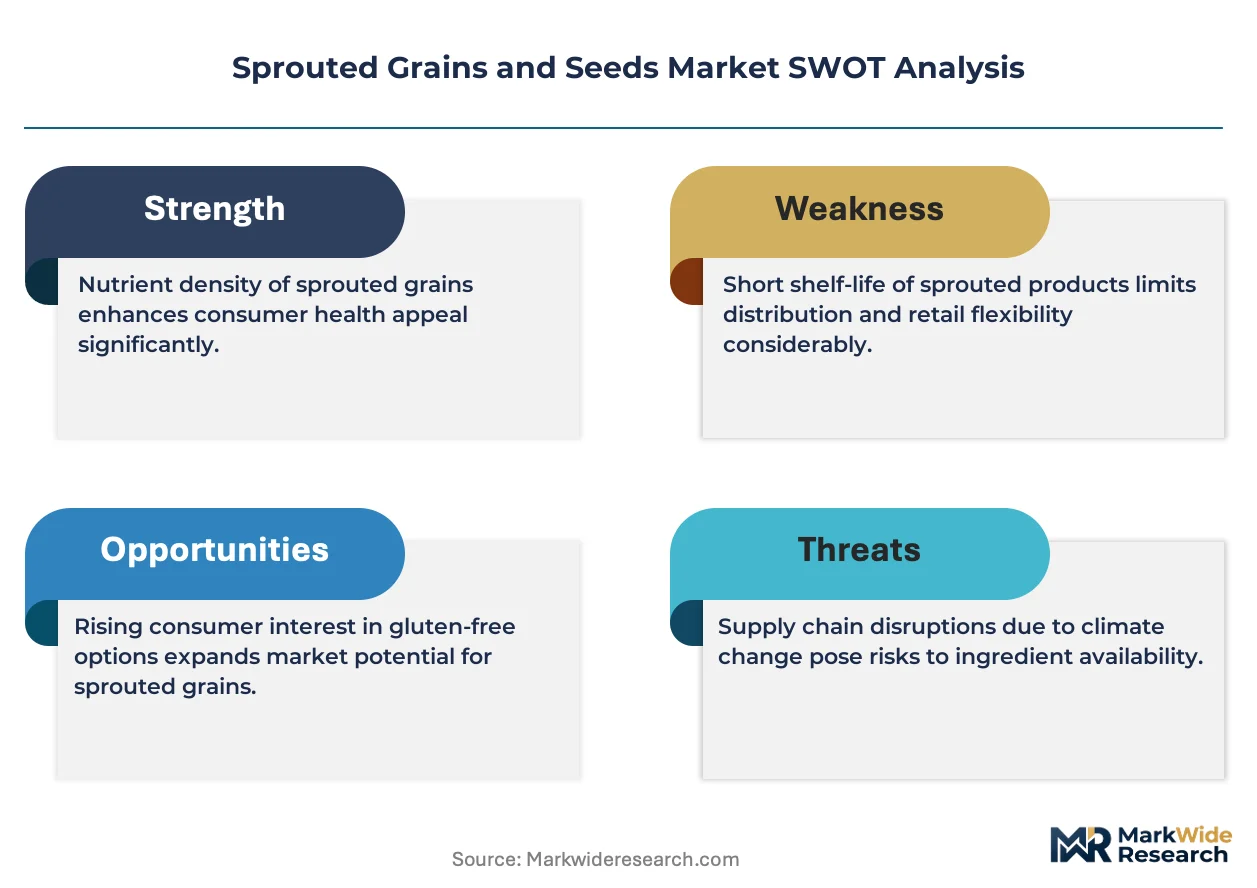
This market is recovering from a cyclical trough driven by FDA enforcement waves on sprouted-seed safety alerts. The enforcement cycle is now moderating, creating window for capacity rationalization and certification arbitrage.
For Market Incumbents: Insulate margin pools by retrofitting legacy batch facilities with continuous-flow sprouting chambers before enzymatic consistency becomes non-negotiable in bakery-chain procurement. Lock in captive supply relationships with fast-casual sandwich chains through lot-specific certificate of analysis programs. Prioritize HACCP certification investment to exploit consolidation toward compliant facilities.
For New Entrants and Emerging Players: Build out sprouted-lupin protein isolation capabilities targeting sports nutrition and meat alternative white space. German health-food retail chains represent the most penetrable channel given dm-drogerie markt and Alnatura shelf expansion. Lead with EFSA pre-submitted compliance documentation to bypass incumbent documentation advantages.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among regional specialty mills with direct bakery-chain relationships and multi-facility operational footprints. Long-term viability favors acquisition targets with backward integration into organic seed sourcing and digital traceability infrastructure. Watch FDA enforcement priority shifts on interstate commerce preemption disputes as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous-Flow Sprouting Retrofit | Collapses quality variance between batches for national bread manufacturers seeking enzymatic consistency. |
| Dual USDA-EU Organic Certification | Enables EU-based facilities to capture transatlantic supply gaps in premium sprouted-wheat flour procurement. |
| Sprouted-Lupin Protein Isolation | Opens functional food applications in sports nutrition through wet-milling technology convergence. |
| Direct Mill-to-Retailer Partnership | Bypasses broadline distributors for customized blends with fast-casual sandwich chains in the Northeast. |
| FSMA-Compliant Digital Traceability | Replaces paper-based batch records to satisfy seed-to-shelf mandates and secure foodservice market access. |
Research Methodology
Initial hypotheses were tested against primary input from sprouting facility operations managers, bakery-chain procurement directors, health-food retail category buyers, and FSMA compliance consultants and refined through secondary validation. Primary fieldwork drew from FDA enforcement action databases, USDA organic certification registries, EFSA novel food guidance documentation, and customs trade records. Bottom-up volume modeling triangulated against top-down category spend analysis.
Demand-supply-balance framing anchored the analytical framework across the analysis window. Segmentation dimensions modeled include product format, application end-use, channel concentration, and certification tier. CAGRs were derived from curve-fitting historical volume trajectories against projected bakery-chain procurement expansion and nutritional supplement adjacency penetration. Industry-specific inputs incorporated enzymatic conversion rate benchmarks and pathogen mitigation protocol adoption curves.
Sensitivities concentrate around FDA enforcement priority shifts, organic seed harvest volatility, and EFSA novel food dossier approval timelines. Cross-checking against USDA National Organic Program certification flow data and bakery-chain earnings call commentary on clean-label procurement is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Cannabis Seeds Market
Seeds
Safflower Seeds Market
Seeds
Sweet Corn Seeds Market
Seeds
Psyllium Market
Seeds
China Forage Seed Market
Seeds
Avena Sativa Market
Seeds
Eucommia Seed Oil Market
Seeds
Global Vegetable Seed Market
Seeds
Hemp Seed Oil Market
Seeds
Europe Grain Seed Market
Seeds
Russia Forage Seed Market
Seeds
Russia Seed Market
Seeds
Europe Flaxseeds Market
Seeds
Celery Seed Oil Market
Seeds
Indonesia Seeds Market
Seeds
Global Wheat Seed Market