
 China Rice Seed Market | 2026-2036
China Rice Seed Market Size, Share, and Industry Trends Forecast 2026-2036
China Rice Seed Market Outlook
Premium germination-grade certification is unwinding across the China rice seed landscape as downstream millers and cooperatives enforce stricter purity thresholds. Yuan Longping High-Tech Agriculture leverages its breeder-to-field pipeline to dominate southern hybrid markets. Anhui Tsuen Yin Hi-Tech Seed Industry anchors its position through specialized two-line hybrid systems. Beidahuang Kenfeng Seed controls distribution depth across the northeastern plains with captive cold-climate breeding stations.
China rice seed comprises genetically stabilized or hybridized Oryza sativa propagules, typically field-tested for minimum germination rates, moisture content below thirteen percent, and varietal purity exceeding ninety-eight percent, serving as the foundational biological input for national grain security and commercial milling supply chains. Hybrid seed captures the dominant value pool due to yield superiority and recurring replacement demand, while inbred lines retain structural importance in government reserve programs and price-sensitive provincial tenders. Direct sales channels to agricultural cooperatives concentrate margin capture, whereas e-commerce platforms extend reach into remote county-level markets.
China's Ministry of Agriculture and Rural Affairs enforces GB standards for seed labeling and field performance testing, while the National Development and Reform Commission coordinates strategic reserve seed stockpiles under food security mandates. SAMR monitors anti-competitive practices in varietal licensing and royalty structures. Stakeholders must track how evolving carbon-intensity benchmarks for agricultural inputs reshape breeding priorities and certification costs.
Market Dynamics
China's dual carbon goals are forcing seed producers to reengineer breeding pipelines around carbon-intensity benchmarks, tightening certification costs and favoring varietals with lower input footprints.
Growth Catalysts
- GB Standards Compliance:China's Ministry of Agriculture and Rural Affairs enforces stricter field performance testing, accelerating replacement of uncertified seed stocks with labeled hybrid varieties.
- Commercial Farming Consolidation:Agricultural cooperatives in the Yangtze River Delta are pooling procurement to demand premium germination-grade certification at volume scale.
- Food Security Stockpiling:The National Development and Reform Commission coordinates strategic reserve mandates, sustaining baseline demand for inbred lines in government tenders.
Market Restraints
- Input Cost Volatility:Cold-climate breeding station operations face rising energy costs for controlled-environment seed multiplication in Heilongjiang.
- Supply Concentration Risk:Three-line and two-line hybrid parent stock availability concentrates among a narrow base of certified foundation seed producers.
- Regulatory Friction:SAMR scrutiny of varietal licensing and royalty structures creates uncertainty for technology transfer agreements between breeders and distributors.
Strategic Opportunities
- E-Commerce Channel Expansion:County-level digital platforms are penetrating remote agricultural markets previously served only by physical supply cooperatives.
- Carbon-Intensity Varietal Development:Breeding programs targeting reduced fertilizer-responsive hybrids align with national dual carbon goal incentives.
- Specialized Two-Line Systems:Photo-thermo-sensitive male sterile line technology offers yield stability advantages in southern double-cropping zones.
Industry Challenges
- Certification Timeline Compression:Field testing protocols for GB standard compliance extend variety release cycles, delaying commercialization of newly developed hybrids.
- Parent Stock Purity Maintenance:Biological contamination risks in foundation seed multiplication require continuous genetic monitoring investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Rice Seed Market |
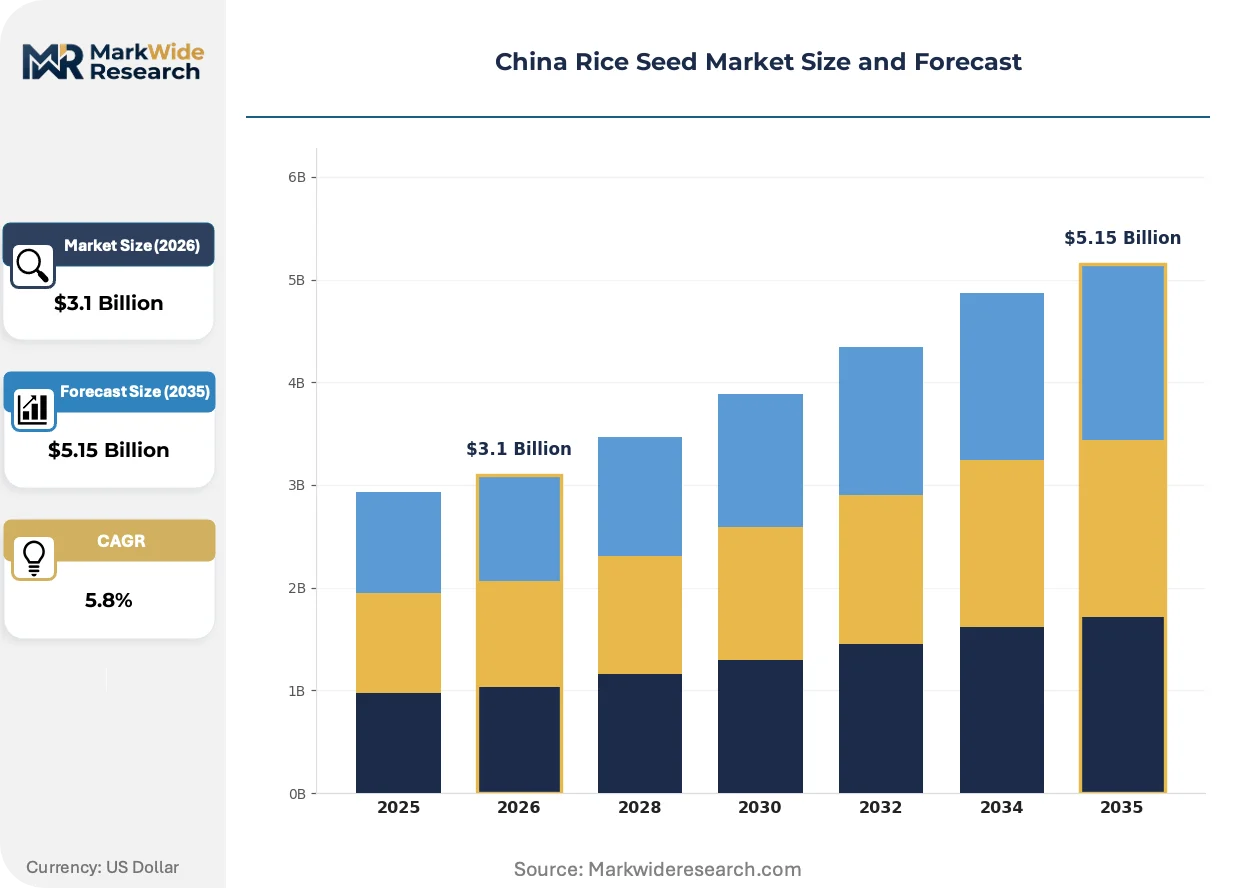
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.15 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hybrid, Inbred, Organic, Traditional Application: Commercial Farming, Research, Seed Production, Home Gardening Distribution Channel: Direct Sales, Retail, E-commerce, Wholesale End User: Farmers, Agricultural Companies, Research Institutions, Government Bodies |
| Companies Covered | Yuan Longping High-Tech Agriculture Co. Ltd, Anhui Tsuen Yin Hi-Tech Seed Industry Co. Ltd, Beidahuang Kenfeng Seed Co. Ltd, Hefei Fengle Seed Industry Co. Ltd, Zhongnongfa Seed Industry Group Co. Ltd, Beijing Golden Nonghua Seed Industry Technology Co. Ltd, Jiangsu Hongqi Seed Industry Co. Ltd, Jiangsu Zhongjiang Seed Industry Co. Ltd, Kehuiseed Co. Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Rice Seed Market Strategic Shifts
Gene-editing tools and digital phenotyping platforms are compressing traditional breeding cycles while regulatory frameworks scramble to classify novel varietal development pathways.
CRISPR-based targeted mutagenesis is displacing conventional backcrossing methods for trait introgression in japonica and indica subspecies. State-backed research institutes in Hunan and Hainan are deploying these platforms for blast resistance and drought tolerance stacking. This acceleration is compressing the historical ten-year variety development window toward five-year commercialization timelines.
China's GB standards for seed labeling and the national dual carbon goals are tightening input requirements for certified hybrid production. The Ministry of Agriculture and Rural Affairs now mandates traceability documentation from breeder seed through certified seed stages. Northeastern plains operators are responding by retrofitting cold-climate breeding stations with energy monitoring systems to document carbon intensity per propagation cycle.
Agricultural cooperatives are consolidating procurement decisions and unbundling after-sales technical support from seed purchase contracts. County-level buyers in the Yangtze River Delta are negotiating direct varietal performance guarantees from breeders, bypassing traditional distributor intermediaries. This disintermediation is most visible in Jiangsu and Zhejiang provinces where cooperative membership density supports pooled bargaining power.
China Rice Seed Market Segmentation
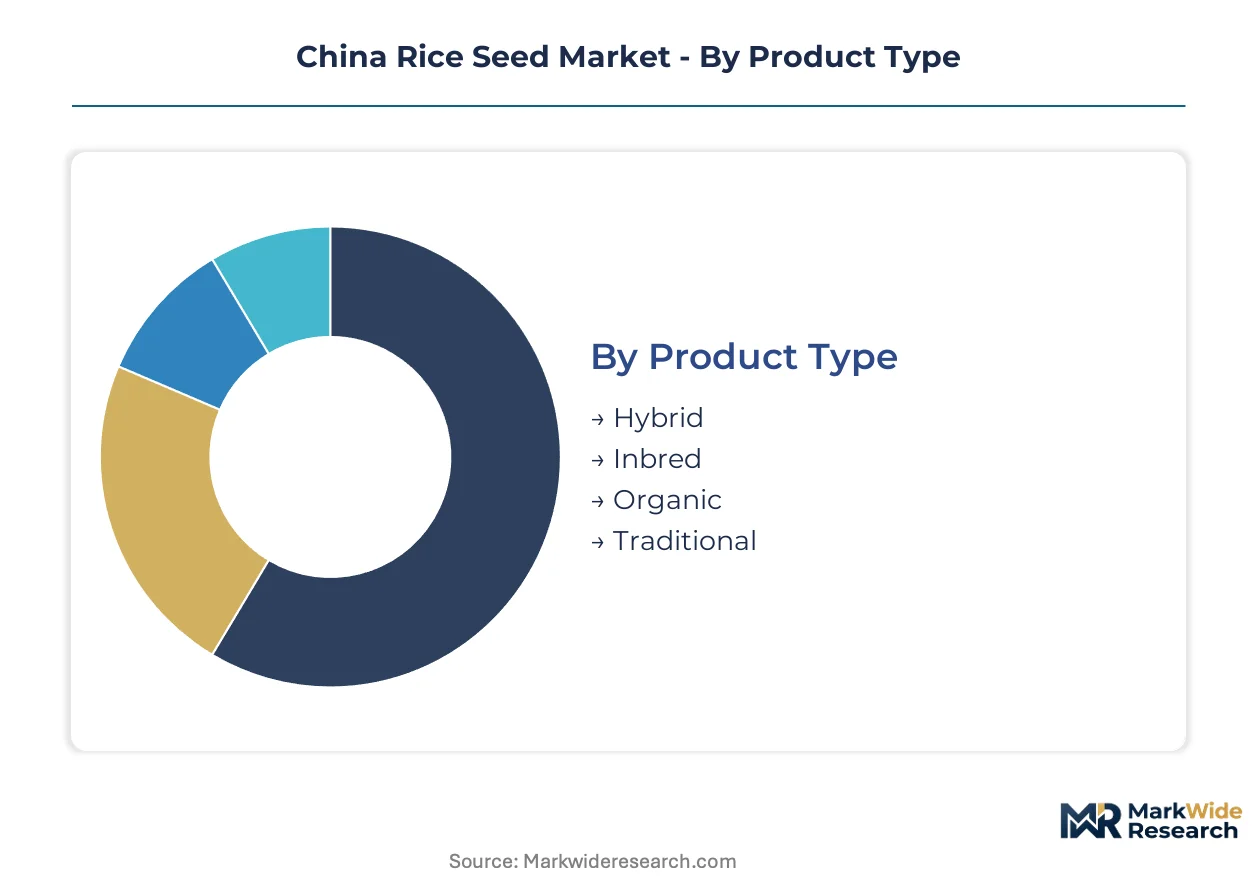
China rice seed market segmentation reveals how breeding technology, procurement scale, and regulatory certification intersect to shape commercial flows. Distinct product tiers serve divergent end-use requirements from state reserve programs to precision commercial operations.
Product Type:
Hybrid varieties dominate domestic cultivation while inbred lines anchor government stockpiling mandates; organic and traditional segments serve specialized export and heritage preservation niches.
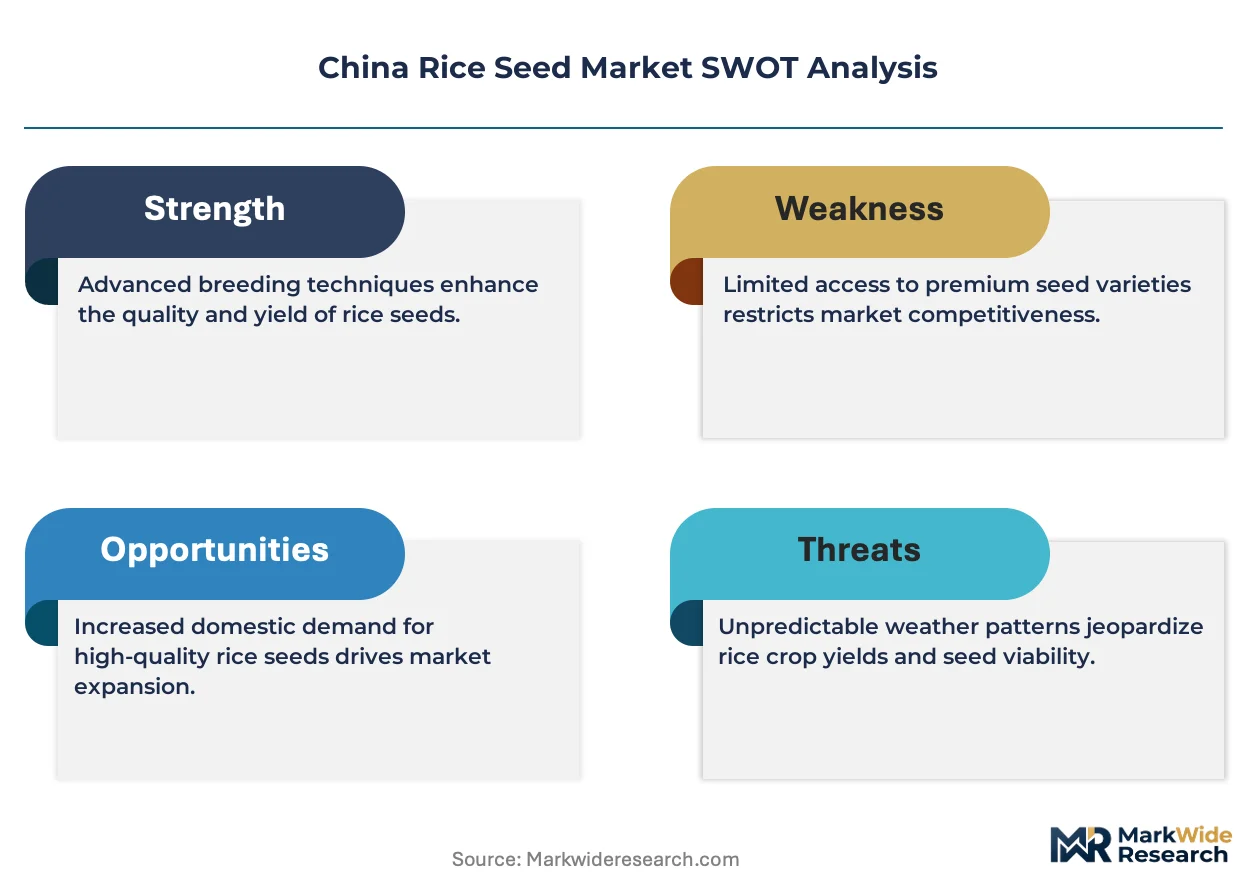
- Hybrid:Genetically stabilized three-line and two-line systems deliver yield superiority through heterosis exploitation. Demand concentrates in the Yangtze River Delta where agricultural cooperatives enforce premium germination-grade certification at pooled procurement scale. GB standards compliance and recurring replacement cycles sustain revenue concentration.
- Inbred:Open-pollinated lines maintain genetic stability across generations without commercial hybridization. Heilongjiang grain belt operators rely on these varieties for cold-climate adaptability and lower input costs. Government reserve tenders sustain structural demand despite yield disadvantages against hybrid alternatives.
- Organic:Certified chemical-free propagation systems command specialized pricing in export-oriented and premium domestic channels.
- Traditional:Heritage landrace preservation serves biodiversity conservation mandates and cultural gastronomy supply chains.
Hybrid captures the largest share; momentum sits with organic certification tiers as export protocols tighten.
Application:
Commercial farming drives volume procurement while research applications concentrate investment in gene-editing platforms; seed production and home gardening occupy residual capacity tiers.
- Commercial Farming:Large-scale cooperative and corporate operations purchase certified hybrid varieties through direct breeder relationships. Northeastern plains and Yangtze Delta geographies dominate procurement concentration. Carbon-intensity benchmarking under dual carbon goals is reshaping varietal selection criteria.
- Seed Production:Foundation seed multiplication and certified seed propagation operate through captive breeding stations. Heilongjiang cold-climate facilities and Hainan winter nurseries anchor the geographic footprint. Parent stock purity maintenance requires continuous genetic monitoring investment.
- Research:State-backed institutes deploy CRISPR platforms for blast resistance and drought tolerance stacking in japonica and indica subspecies.
- Home Gardening:Small-scale residential cultivation absorbs traditional and heritage variety distribution through e-commerce channels.
Commercial farming holds the largest share; research applications are climbing the fastest as breeding cycle compression accelerates.
Distribution Channel:
Direct sales capture margin concentration with agricultural cooperatives while e-commerce extends reach into county-level markets previously served only by physical supply networks.
- Direct Sales:Breeder-to-field pipelines eliminate distributor intermediaries for large cooperative procurement. Jiangsu and Zhejiang provinces exhibit dense cooperative membership enabling pooled bargaining power. Technical support unbundling from purchase contracts is compressing traditional margin structures.
- E-commerce:County-level digital platforms penetrate remote agricultural markets with traceability documentation mandated by Ministry of Agriculture and Rural Affairs protocols. Logistics integration with cold-chain seed handling sustains germination rate guarantees.
- Retail:Physical supply cooperatives serve smallholder farmers with limited digital access or credit infrastructure.
- Wholesale:Aggregated volume distribution connects breeding stations to provincial-level agricultural input depots.
Direct sales holds the largest share; e-commerce is gaining share fastest through county-level penetration.
End User:
Farmers and agricultural companies drive commercial demand while government bodies sustain baseline inbred line procurement for strategic reserves.
- Farmers:Individual and cooperative cultivators select varieties based on yield performance, input responsiveness, and local climate adaptation. Double-cropping zones in southern provinces favor photo-thermo-sensitive male sterile line technology.
- Agricultural Companies:Corporate farming operations and integrated food processors contract directly with breeders for varietal performance guarantees. Carbon-intensity documentation requirements are tightening supplier qualification criteria.
- Research Institutions:State-backed breeding programs in Hunan and Hainan deploy gene-editing platforms for trait introgression acceleration.
- Government Bodies:National Development and Reform Commission coordinates strategic reserve seed stockpiles under food security mandates.
Farmers hold the largest share; agricultural companies show steepest expansion trajectory as commercial farming consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundation seed multiplication concentrates in climate-controlled breeding corridors. The Ministry of Agriculture and Rural Affairs coordinates varietal release protocols across provincial agricultural commissions. GB standards enforcement tightens field performance documentation requirements nationwide.
Yangtze River Delta
Agricultural cooperatives in Jiangsu and Zhejiang provinces pool procurement volumes to demand premium germination-grade certification. The Ministry of Agriculture and Rural Affairs mandates traceability documentation from breeder seed through certified seed stages. Nanjing and Hangzhou anchor distribution networks where direct sales channels disintermediate traditional distributors.
Heilongjiang Grain Belt
Cold-climate adaptability drives demand for inbred lines with lower input costs in northeastern plains operations. The National Development and Reform Commission coordinates strategic reserve seed stockpiles under food security mandates. Harbin-based breeding stations retrofit energy monitoring systems to document carbon intensity per propagation cycle.
Sichuan-Chongqing
Photo-thermo-sensitive male sterile line technology supports double-cropping zone yield stability. SAMR monitors anti-competitive practices in varietal licensing across southwestern provincial markets. Chengdu research institutes deploy gene-editing platforms for blast resistance stacking in indica subspecies.
Guangdong-Fujian Coastal Belt
Export-oriented rice milling operations demand certified hybrid varieties with documented purity thresholds. GB standards for seed labeling require moisture content below thirteen percent and varietal purity exceeding ninety-eight percent. Fuzhou and Guangzhou logistics hubs integrate cold-chain seed handling for germination rate guarantees.
Hainan Winter Nursery Corridor
Accelerated breeding cycles exploit tropical photoperiods for foundation seed multiplication. The Ministry of Agriculture and Rural Affairs enforces field performance testing protocols for accelerated variety release. Sanya research stations compress historical ten-year development windows toward five-year commercialization timelines.
China Rice Seed Market Competitive Environment
Concentration sits with state-affiliated breeding enterprises and specialized hybrid seed developers. Three operational archetypes dominate: breeder-to-field pipeline operators controlling southern hybrid markets, two-line system specialists anchoring photo-thermo-sensitive technology, and northeastern plains distributors with captive cold-climate stations. Competitive moves center on direct cooperative procurement relationships and carbon-intensity documentation capabilities.
Within the breeder-to-field tier, Yuan Longping High-Tech Agriculture Co. Ltd exemplifies integrated pipeline control. Anhui Tsuen Yin Hi-Tech Seed Industry Co. Ltd and Beidahuang Kenfeng Seed Co. Ltd occupy positions spanning specialized two-line systems and northeastern distribution depth. These three entities represent the dominant competitive archetypes: southern hybrid dominance, technological specialization, and geographic captive supply.
| Leading Market Players |
|---|
| Yuan Longping High-Tech Agriculture Co. Ltd |
| Anhui Tsuen Yin Hi-Tech Seed Industry Co. Ltd |
| Beidahuang Kenfeng Seed Co. Ltd |
| Hefei Fengle Seed Industry Co. Ltd |
| Zhongnongfa Seed Industry Group Co. Ltd |
| Beijing Golden Nonghua Seed Industry Technology Co. Ltd |
| Jiangsu Hongqi Seed Industry Co. Ltd |
| Jiangsu Zhongjiang Seed Industry Co. Ltd |
| Kehuiseed Co. Ltd |
| Others |
Value Chain & Pricing Dynamics
Captive breeding station scale economies in Heilongjiang and Hainan concentrate foundation seed multiplication among operators with energy-controlled propagation cycles, compressing cost floors for certified hybrid output while elevating barriers for uncertified competitors. This concentration amplifies pricing power for GB-compliant producers serving Yangtze River Delta cooperatives.
Pricing Analysis
GB standards for seed labeling dictate the pricing tier structure across China's rice seed landscape, separating premium germination-grade certified hybrids from uncertified commodity propagation. Three-tier pricing structure across premium, standard, and economy levels reflects varietal purity thresholds, moisture content compliance, and bundled technical support. Pricing pressure stems from agricultural cooperative procurement consolidation demanding performance guarantees at volume scale. Smallholder farmers in remote county markets exhibit highest price sensitivity, while corporate farming operations in Jiangsu and Zhejiang prioritize certification grade over unit cost.
Supply Chain Analysis
Inventory cycles spanning breeder seed through certified seed stages extend lead times for new varietal commercialization, constraining supply responsiveness to demand shifts. Foundation seed multiplication draws from captive breeding stations in Heilongjiang, Hainan, and Hunan, with parent stock purity maintenance resting on continuous genetic monitoring. Single-source vulnerability concentrates in three-line and two-line hybrid parent stock availability among narrow certified producer bases. Distribution runs through direct breeder-to-cooperative channels in dense membership regions, supplemented by e-commerce platforms penetrating remote county markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as carbon-intensity documentation requirements and GB compliance timelines create specialist niches between state-affiliated incumbents and uncertified regional suppliers. Agricultural cooperative procurement consolidation accelerates demand-side niche formation for differentiated varietal performance.
For Market Incumbents: Shield market position by deepening captive breeding station control in climate-critical geographies and accelerating carbon-intensity certification documentation ahead of dual carbon goal enforcement timelines. SAMR scrutiny of varietal licensing structures threatens royalty revenue streams; preemptive transparency in technology transfer agreements reduces regulatory friction exposure. Investment in photo-thermo-sensitive male sterile line R&D defends yield stability advantages against gene-editing platform competitors. For New Entrants and Emerging Players: GB standards fast-track compliance for two-line hybrid systems offers entry pathway into southern double-cropping zones where Yuan Longping High-Tech Agriculture dominance remains incomplete. County-level e-commerce channels in Sichuan-Chongqing and Guangdong-Fujian present most penetrable distribution architecture, bypassing cooperative procurement concentration. Direct technical support bundling with seed sales creates differentiation against incumbent disintermediation trends. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors breeders with CRISPR platform deployment capability and established Hainan winter nursery access. Five-to-ten year viability hinges on carbon-intensity varietal development pipelines aligning with national emission benchmarks. Acquisition target archetype: specialized two-line system operators with photo-thermo-sensitive technology and underutilized cold-climate breeding capacity. Signal to watch: Ministry of Agriculture and Rural Affairs acceleration of field testing protocol timelines compressing variety release cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon-Intensity Certification Program | Dual carbon goal compliance documentation secures cooperative procurement qualification in Yangtze River Delta. |
| Two-Line Hybrid System Expansion | Photo-thermo-sensitive male sterile line technology captures yield stability premiums in southern double-cropping zones. |
| E-Commerce Channel Penetration | County-level digital platforms extend reach into remote agricultural markets previously served only by physical cooperatives. |
| Gene-Editing Platform Investment | CRISPR-based trait introgression compresses historical breeding cycles toward accelerated commercialization timelines. |
| Direct Cooperative Procurement Relationship | Breeder-to-field pipeline control eliminates distributor intermediaries and captures margin concentration in Jiangsu and Zhejiang. |
Study Parameters
A standing panel of breeding station operations managers, agricultural cooperative procurement officers, seed quality certification auditors, and provincial agricultural commission regulators provided ongoing calibration across the study period. Primary interviews with foundation seed multiplication specialists and certified hybrid distributors combined with secondary validation from Ministry of Agriculture and Rural Affairs field performance testing protocols, National Development and Reform Commission strategic reserve documentation, SAMR varietal licensing records, and GB standards compliance databases. Bottom-up volume aggregation across breeding station capacity and top-down demand triangulation through cooperative procurement surveys ensured convergence.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including breeding technology tier, procurement scale band, certification grade level, distribution channel type, and regional climatic adaptation cluster. CAGRs were derived from trend extrapolation of breeder seed multiplication rates, certified seed replacement cycle frequencies, and cooperative procurement volume trajectories. Industry-specific forecast inputs incorporated dual carbon goal implementation timelines and GB standards enforcement phase-in schedules.
The analysis sits within stated boundaries; outcomes outside sustained GB compliance enforcement, stable parent stock genetic purity maintenance, and continued agricultural cooperative consolidation would require recalibration. Forecasts reflect documented assumptions regarding breeding cycle compression rates and carbon-intensity benchmarking adoption curves. Revision becomes warranted when SAMR regulatory intervention intensity or energy cost volatility in cold-climate propagation crosses thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Guar Market
Seeds
Global Rice Seed Market
Seeds
India Vegetable Seed Market
Seeds
South and Southeast Asia Seed Market
Seeds
Australia Forage Seed Market
Seeds
Tomato Seed Market
Seeds
Psyllium Seed Market
Seeds
Thailand Vegetable Seed Market
Seeds
Asia-Pacific Vegetable Seed Market
Seeds
Sesame Seeds Market
Seeds
Dragon Fruit Seeds Market
Seeds
North America Maize Seed Treatment Market
Seeds
China Forage Seed Market
Seeds
China Seed Market
Seeds
Asia-Pacific Cannabis Seeds Market
Seeds
South America Chia Seeds Market