
 Asia-Pacific Maize Seed Market | 2026-2036
Asia-Pacific Maize Seed Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Maize Seed Market Outlook
The R&D-to-field capability gap between multinational breeders and domestic seed houses is unwinding as technology transfer agreements mature. Bayer AG leverages its molecular marker platforms to accelerate trait introgression cycles across tropical germplasm. Syngenta Group anchors its position through integrated crop solution bundles that pair seed with crop protection protocols. Yuan Longping High-Tech Agriculture Co. Ltd dominates the hybrid rice-to-corn pivot with proprietary inbred lines developed for subtropical stress tolerance.
Asia-Pacific maize seed comprises sexually propagated reproductive material of Zea mays L. selected for heterotic performance, typically conditioned to exceed 80% germination under controlled moisture and temperature protocols, serving as the foundational input for grain production, silage, and industrial starch extraction. Hybrid seeds command the dominant value share where double-cross and single-cross configurations deliver 15-40% yield advantages over open-pollinated alternatives, while GMO seeds face fragmented adoption due to country-level trait approval heterogeneity. Non-hybrid seeds retain residual demand among subsistence operators in Myanmar and Laos where saved-seed practices persist despite yield penalties.
China's Ministry of Agriculture and Rural Affairs enforces variety registration under the Seed Law revision, while India's Central Seed Committee operates under the Seeds Act to certify genetic purity and physical quality parameters. Australia's Office of the Gene Technology Regulator and New Zealand's EPA impose additional biosafety assessments on transgenic events, creating multi-layered compliance architectures that favor breeders with dedicated regulatory affairs capacity. Stakeholders must monitor evolving national biosafety frameworks and trait stewardship obligations as stacked-gene varieties approach commercialization timelines across Southeast Asian markets.
Market Dynamics
The Asia-Pacific maize seed market is being fundamentally restructured by the accelerating formalization of seed distribution channels as government certification regimes displace informal seed-saving networks across India, China, and Southeast Asia.
Growth Catalysts
- India's PLI scheme for agricultural inputs:Production-linked incentives are channeling capital into domestic breeding infrastructure and expanding certified seed penetration among Gujarat and Maharashtra commercial growers.
- Livestock feed sector expansion:Indonesia and Vietnam dairy and poultry operations are scaling hybrid corn procurement for silage and grain rations, creating sustained pull for high-yield varieties.
- Molecular marker-assisted selection:Accelerated trait introgression cycles are compressing variety development timelines from 8-10 years toward 5-7 years for tropical germplasm adaptation.
Market Restraints
- Phosphorus and nitrogen input cost volatility:Fertilizer price swings compress margins for seed-corn growers who must maintain isolation distances and detasseling labor.
- Trait approval heterogeneity:China's SAMR biosafety assessments operate on timelines misaligned with Australia's OGTR and New Zealand's EPA, fragmenting stacked-gene variety deployment.
- Open-pollinated variety persistence:Subsistence operators in Myanmar and Laos continue saved-seed practices despite 15-40% yield penalties relative to hybrid alternatives.
Strategic Opportunities
- Laos and Myanmar formal channel penetration:Underdeveloped regulatory infrastructure creates first-mover advantage for breeders establishing certified distribution before national seed laws mature.
- Silage-specific hybrid development:Dairy expansion across Vietnam's Central Highlands and Thailand's Nakhon Ratchasima corridor demands varieties optimized for whole-plant digestibility rather than grain yield alone.
- Dual carbon goals alignment:China's MEE carbon intensity targets for agriculture are creating preferential procurement pathways for seed varieties with documented nitrogen-use efficiency traits.
Industry Challenges
- Regulatory affairs capacity scarcity:Multi-layered compliance across China's Seed Law, India's Seeds Act, and ASEAN national biosafety frameworks requires dedicated staffing that domestic seed houses struggle to fund.
- Detasseling labor cost inflation:Manual hybrid seed production depends on seasonal agricultural workers whose wages are rising 8-12% annually across India's seed production belts.
- Genetic purity certification bottlenecks:India's Central Seed Committee and China's variety registration offices face inspection backlogs that delay commercial launch timelines by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Maize Seed Market |
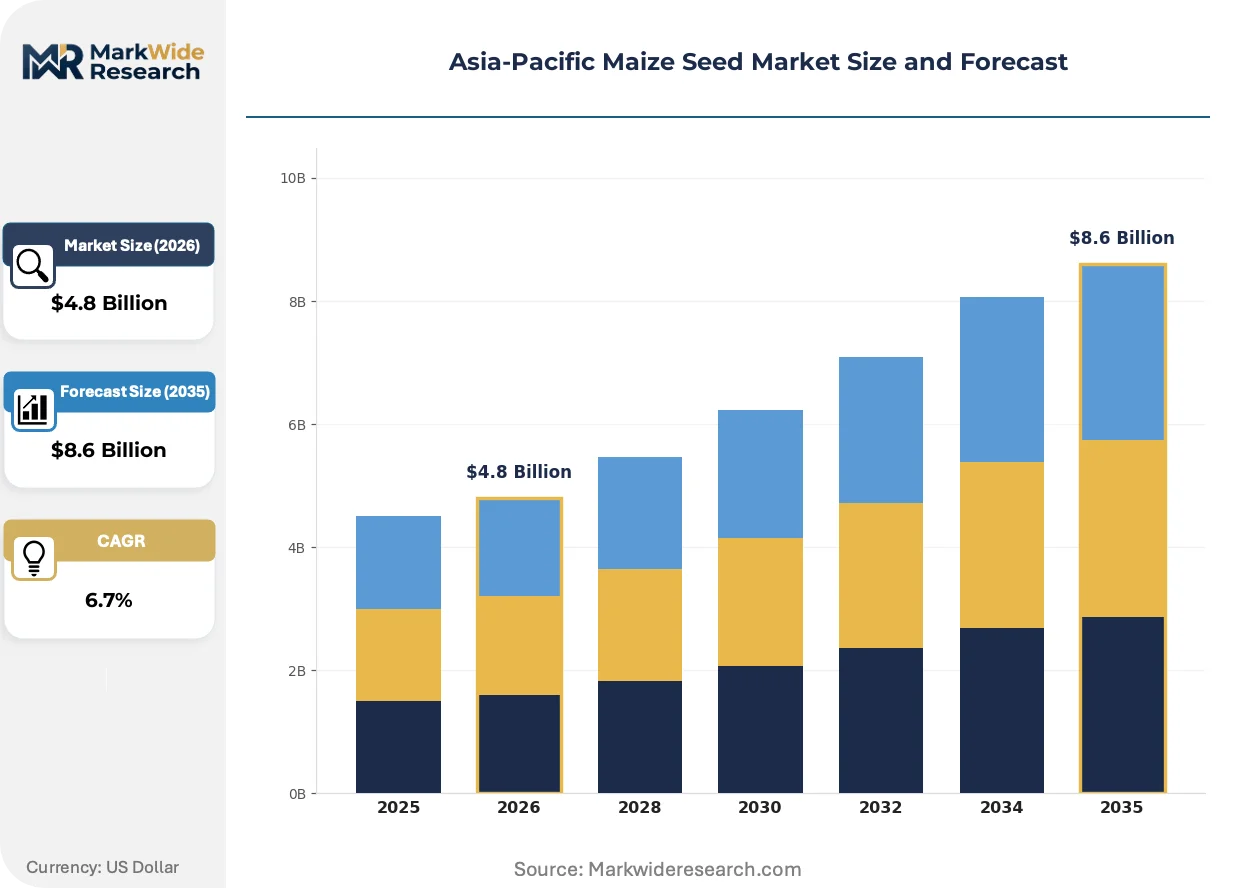
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hybrid Seeds, Non-Hybrid Seeds, GMO Seeds, Organic Seeds End Use Industry: Agriculture, Animal Feed, Biofuel, Food Processing Distribution Channel: Online Retail, Agro-dealers, Cooperatives, Direct Sales Packaging Type: Bags, Bulk, Boxes, Seed Tapes |
| Companies Covered | Advanta Seeds - UPL, Bayer AG, Beidahuang Kenfeng Seed Co. Ltd, Corteva Agriscience, Syngenta Group, KWS SAAT SE & Co. KGaA, Charoen Pokphand Group, Yuan Longping High-Tech Agriculture Co. Ltd, East-West Seed, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Maize Seed Market Strategic Shifts
Biotechnology deployment and digital breeding platforms are actively fragmenting competitive advantage sources, separating breeders with integrated trait-stewardship capabilities from those dependent on public germplasm pools.
Gene editing via CRISPR-Cas9 is bifurcating the regulatory pathway landscape for novel traits. Multinational breeders with established regulatory affairs teams in Beijing and New Delhi are pursuing edited varieties outside GMO classification, while domestic houses lacking equivalent capacity remain anchored to conventional hybrid development. The technology is compressing the competitive window for trait deployment before stacked-gene varieties achieve commercial scale.
China's Seed Law revision is mandating variety registration with DUS (distinctness, uniformity, stability) testing for all commercial releases. The regulation is elevating fixed costs for market entry and consolidating advantage toward breeders with dedicated testing stations in Hainan and Yunnan. Smaller domestic houses are responding through consortia arrangements to share DUS trial infrastructure.
Feed mill procurement consolidation is displacing fragmented trader networks across Vietnam and Indonesia. Large integrated livestock operators in Ho Chi Minh City and Jakarta are establishing direct offtake agreements with seed companies for identity-preserved grain, bypassing traditional commodity channels. The shift is most visible in Vietnam's Mekong Delta, where dairy cooperatives now specify hybrid variety and provenance in supply contracts.
Asia-Pacific Maize Seed Market Segmentation
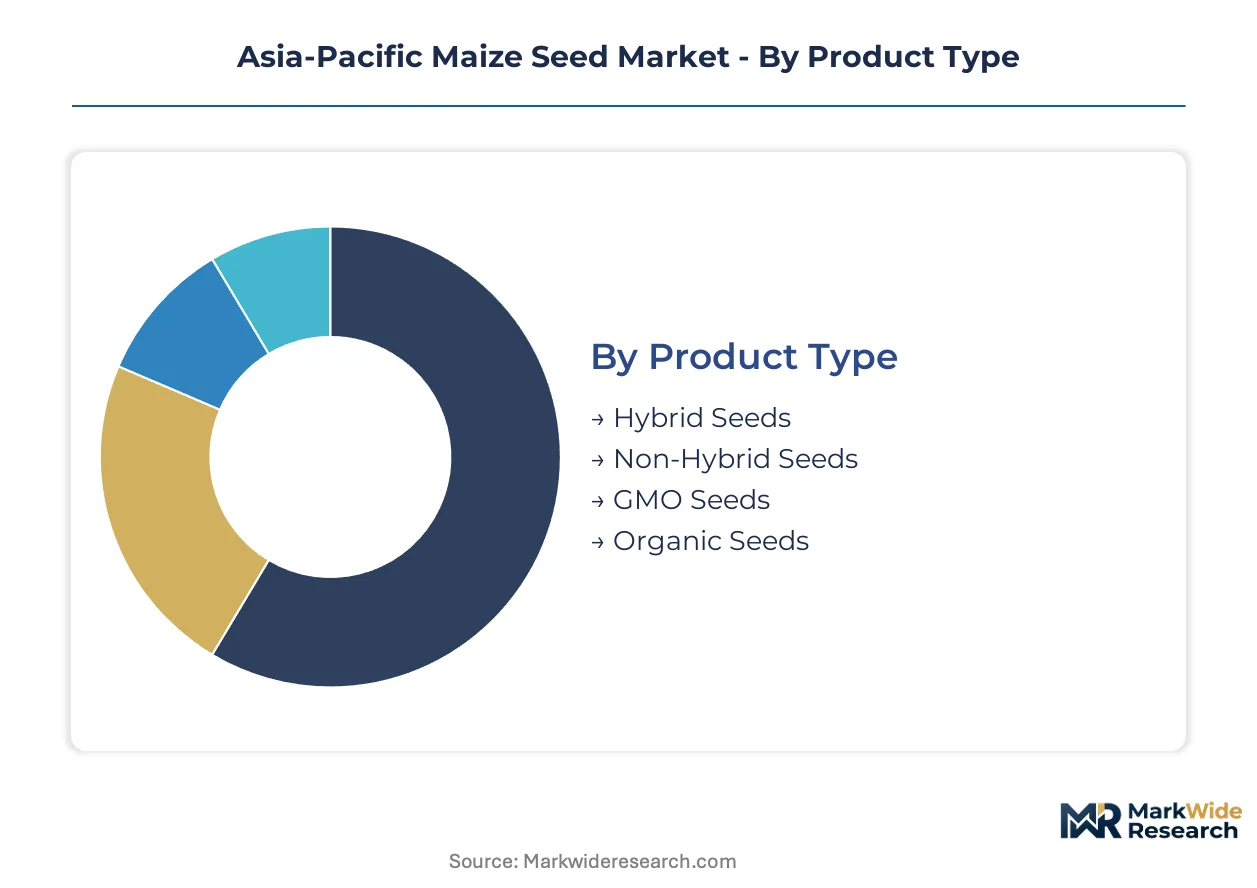
Maize seed segmentation in Asia-Pacific reflects divergent commercialization pathways across tropical and subtropical production belts. Breeders must align product portfolios with distinct regulatory maturity, input intensity, and channel infrastructure across India, China, and Southeast Asian markets.
Product Type:
Domestic breeding programs anchor hybrid and non-hybrid supply, while GMO and organic varieties depend on cross-border trait licensing and export certification protocols.
- Hybrid Seeds:Double-cross and single-cross configurations deliver heterotic yield advantages through controlled pollination and detasseling operations. Demand concentrates in India's Gujarat-Maharashtra corridor and China's Northeast Plain, where commercial growers prioritize yield stability over seed cost. The PLI scheme and Seed Law revision accelerate certified hybrid penetration.
- Non-Hybrid Seeds:Open-pollinated varieties retain viability across multiple planting cycles through farmer-saved seed practices. Myanmar and Laos subsistence operators dominate procurement despite documented yield penalties, constrained by limited agro-dealer reach and weak variety registration enforcement.
- GMO Seeds:Stacked-gene varieties face fragmented commercialization due to misaligned biosafety timelines across China's SAMR, Australia's OGTR, and New Zealand's EPA.
- Organic Seeds:Certified organic propagation material serves niche export-oriented operations in Thailand's Chiang Mai province and India's Madhya Pradesh organic clusters.
Hybrid seeds command the established base. The steepest expansion runs through GMO seeds pending regulatory harmonization.
End Use Industry:
Application segmentation tracks the shift from subsistence grain production toward vertically integrated feed and industrial value chains.
- Agriculture:Grain production for human consumption and local starch processing represents the foundational demand pool. Smallholder operators across Indonesia's East Java and the Philippines' Cagayan Valley drive volume procurement of mid-yield hybrids.
- Animal Feed:Silage and grain rations for dairy and poultry operations create premium positioning for whole-plant digestibility varieties. Vietnam's Central Highlands dairy cooperatives and Thailand's Nakhon Ratchasima broiler integrators specify hybrid provenance in direct offtake contracts.
- Biofuel:Industrial starch-to-ethanol pathways in China's Jilin province and India's Punjab pull high-amylose varieties with documented fermentation efficiency.
- Food Processing:Specialty corn for snack and beverage manufacturing demands specific kernel texture and moisture profiles, concentrated in Malaysia's Port Klang processing zone.
Animal feed applications are gaining share fastest. Agriculture retains volume dominance.
Distribution Channel:
Channel structure varies with grower scale, credit access, and regulatory enforcement intensity across national seed laws.
- Agro-dealers:Licensed rural retailers with certified seed stocking authority serve as the primary interface for commercial growers. India's state-level seed corporation networks and China's county agricultural technology stations anchor physical distribution.
- Direct Sales:Breeder-to-grower contracts bypass intermediaries for identity-preserved grain programs. Vietnam's Mekong Delta dairy cooperatives and Indonesia's Jakarta-based feed mills negotiate variety-specific procurement directly with Bayer and Syngenta.
- Online Retail:E-commerce platforms penetrate where last-mile logistics and digital payment infrastructure mature, notably in China's Taobao Agricultural channel and India's AgriApp networks.
- Cooperatives:Member-owned purchasing bodies aggregate smallholder demand for volume discounts, prevalent in Thailand's corn belt and the Philippines' Mindanao production clusters.
Agro-dealers command the established base. Direct sales are climbing the fastest.
Packaging Type:
Packaging selection reflects operational scale, storage infrastructure, and mechanized planting adoption rates.
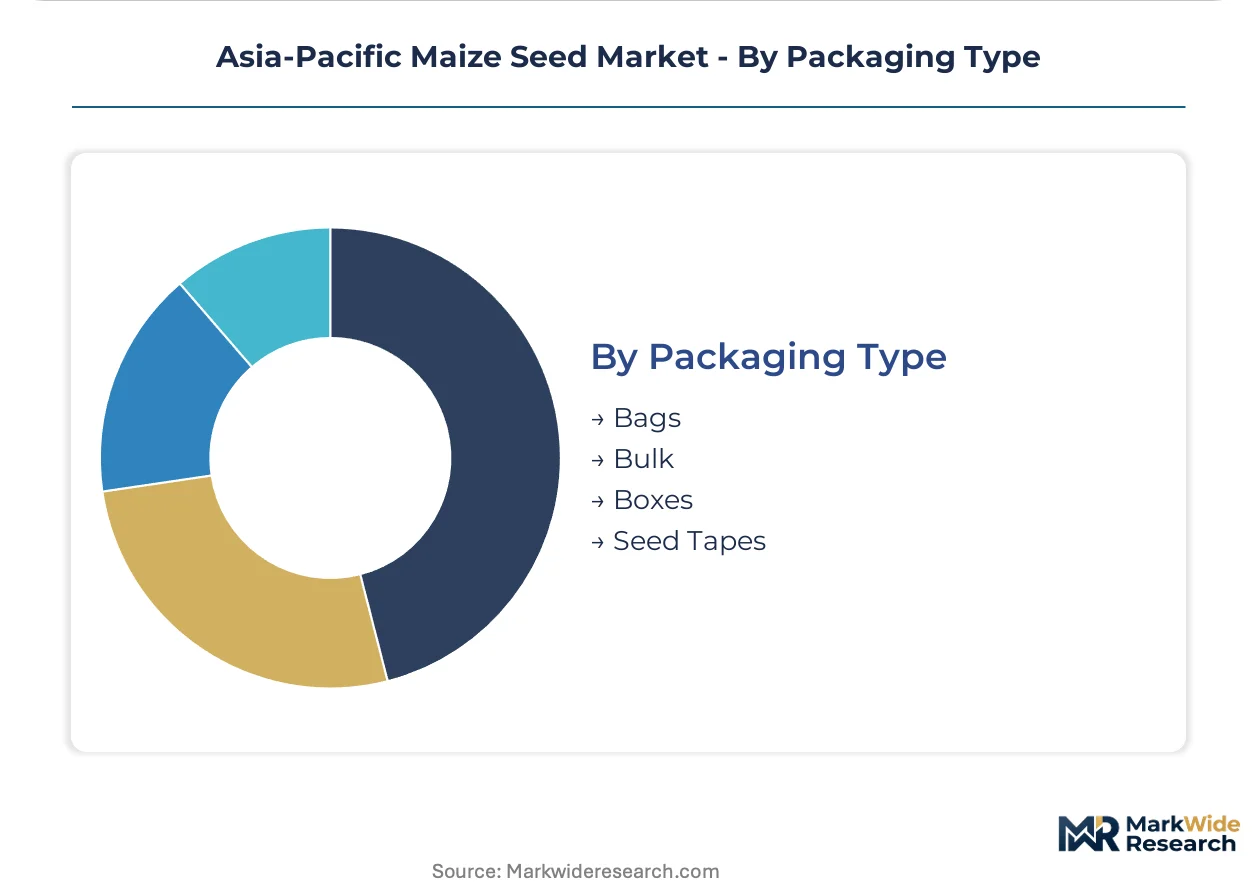
- Bags:Woven polypropylene sacks of 5-50 kg capacity dominate smallholder procurement across India's Deccan Plateau and Indonesia's outer island production zones.
- Bulk:Loose seed delivery to commercial operations with on-farm treating and storage infrastructure, standard for China's Heilongjiang mechanized farms and Australia's Queensland broadacre operations.
- Boxes:Rigid container packaging protects high-value hybrid and organic varieties during extended supply chain transit to remote distribution points.
- Seed Tapes:Pre-spaced seed embedding in biodegradable strips enables precision planting adoption among Vietnam's Central Highlands vegetable-corn intercropping systems.
Bags command the established base. Bulk packaging is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across the region, with China's Northeast Plain prioritizing grain yield for industrial starch while Vietnam's Central Highlands optimizes whole-plant digestibility for dairy silage operations.
China
Industrial starch-to-ethanol demand in Jilin province and mechanized broadacre farming in Heilongjiang drive hybrid procurement. The Ministry of Agriculture and Rural Affairs enforces DUS testing under revised Seed Law protocols. Variety registration backlogs in Beijing delay commercial launches by 12-18 months.
India
Commercial feed mill expansion across Gujarat and Maharashtra creates sustained pull for high-yield single-cross hybrids. The PLI scheme for agricultural inputs channels capital into domestic breeding infrastructure. Seed production belts in Karnataka face detasseling labor cost inflation of 8-12% annually.
Vietnam
Dairy cooperative procurement in the Central Highlands and broiler integrator demand in Nakhon Ratchasima corridor specify hybrid provenance in direct contracts. Feed mill consolidation across Ho Chi Minh City displaces fragmented trader networks. Silage-specific variety development outpaces grain-focused alternatives.
Indonesia
Poultry and dairy operations in Jakarta and East Java scale hybrid corn procurement for grain rations and silage. Weak variety registration enforcement permits informal seed-saving persistence among outer island smallholders. Agro-dealer networks in Java anchor certified distribution.
Thailand
Broiler integration in Nakhon Ratchasima and organic export clusters in Chiang Mai create segmented demand pools. Member-owned cooperatives aggregate smallholder demand for volume discounts across the corn belt. Dual-purpose varieties serving both grain and silage applications gain share.
Asia-Pacific Maize Seed Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with multinational breeders leveraging molecular platforms and regulatory affairs capacity against domestic houses dependent on public germplasm pools. Bayer AG and Syngenta Group anchor the integrated tier through trait-stewardship capabilities and crop protection bundling. Yuan Longping High-Tech Agriculture Co. Ltd and Beidahuang Kenfeng Seed Co. Ltd occupy positions within the domestic specialist tier. Competitive moves concentrate on technology transfer agreements compressing variety development timelines and direct offtake contracts with feed mill consolidators bypassing commodity channels.
Within the integrated multinational tier, Bayer AG and Syngenta Group exemplify breeders with dedicated regulatory affairs teams positioned for stacked-gene variety deployment. Among China-based domestic houses, Yuan Longping High-Tech Agriculture Co. Ltd and Beidahuang Kenfeng Seed Co. Ltd represent specialists leveraging subtropical germplasm adaptation and mechanized production belt proximity respectively. Corteva Agriscience and KWS SAAT SE & Co. KGaA occupy positions bridging both tiers through regional licensing arrangements and hybrid platform access.
| Leading Market Players |
|---|
| Advanta Seeds - UPL |
| Bayer AG |
| Beidahuang Kenfeng Seed Co. Ltd |
| Corteva Agriscience |
| Syngenta Group |
| KWS SAAT SE & Co. KGaA |
| Charoen Pokphand Group |
| Yuan Longping High-Tech Agriculture Co. Ltd |
| East-West Seed |
| Others |
Value Chain & Pricing Dynamics
China's Seed Law revision and India's Seeds Act certification protocols simultaneously gate supply qualification and stratify price tiers across the Asia-Pacific maize seed market. Regulatory compliance costs compress margins for domestic houses while multinational breeders leverage dedicated regulatory affairs capacity to command premium positioning.
Pricing Analysis
Long-term offtake contracts between feed mill consolidators and integrated breeders anchor pricing stability across Vietnam's Mekong Delta and Indonesia's Jakarta corridor. Three-tier pricing structure across premium, standard, and economy levels reflects germplasm pedigree, trait complexity, and bundled crop protection protocols. Cost compression in standard-tier hybrids intensifies because detasseling labor wages rise annually across India's Karnataka seed production belts. Subsistence operators in Myanmar and Laos exhibit highest price sensitivity, while Vietnam's dairy cooperatives prioritize provenance documentation over unit cost.
Supply Chain Analysis
India and China anchor commercial hybrid seed production, with Myanmar and Laos supplying residual open-pollinated varieties through informal channels. Parent line development draws from tropical germplasm banks, molecular marker platforms, and Hainan winter nursery infrastructure. Single-source vulnerability concentrates in proprietary inbred lines controlled by multinational breeders. Distribution runs through licensed agro-dealer networks, county agricultural technology stations, and direct breeder-to-grower contracts for identity-preserved programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific maize seed market functions as a service-attach opportunity where crop protection bundling and agronomic advisory layers expand faster than standalone seed revenue. Recurring service relationships lock in grower loyalty beyond germplasm performance alone.
For Market Incumbents: Fortify regulatory affairs capacity across Beijing and New Delhi to accelerate stacked-gene variety deployment before biosafety timelines harmonize. Deepen backward integration into parent line production across Hainan and Yunnan testing stations to reduce germplasm licensing exposure. Channel control through direct offtake contracts with Vietnam's feed mill consolidators defends margin position against commodity trader displacement. For New Entrants and Emerging Players: Anchor in Laos and Myanmar formal channel penetration before national seed laws mature, exploiting underdeveloped variety registration enforcement. Target silage-specific hybrid development for Vietnam's Central Highlands dairy cooperatives, where whole-plant digestibility specifications outpace generic grain yield positioning. Pursue consortia arrangements to share DUS trial infrastructure costs with domestic breeding houses lacking standalone testing capacity. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across gene-edited variety development as CRISPR-Cas9 platforms demand specialized regulatory staffing and IP prosecution capacity. Acquisition targets with established subtropical germplasm adaptation and mechanized production belt proximity offer viable five-to-ten-year positioning. Monitor China's MEE carbon intensity targets for agriculture as the inflection signal for nitrogen-use efficiency trait premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Affairs Capacity Expansion | Dedicated Beijing and New Delhi teams accelerate SAMR and OGTR stacked-gene approvals. |
| Direct Offtake Contracting | Bypassing commodity traders locks in identity-preserved grain premiums with Vietnam's dairy cooperatives. |
| Silage-Specific Hybrid Development | Whole-plant digestibility optimization captures Vietnam Central Highlands dairy expansion demand. |
| Gene Editing Platform Investment | CRISPR-Cas9 capabilities compress trait introgression cycles outside GMO classification pathways. |
| Consortia DUS Infrastructure Sharing | Smaller domestic houses pool Hainan and Yunnan testing station costs under China's Seed Law mandates. |
Study Parameters
A standing panel of breeding program directors, regulatory affairs leads at multinational seed houses, feed mill procurement managers, and agro-dealer network operators provided ongoing calibration across primary fieldwork. Secondary validation drew from China's Ministry of Agriculture variety registration databases, India's Central Seed Committee certification records, ASEAN national biosafety framework filings, and customs trade data on parent line imports. Bottom-up acreage and pricing estimates triangulated against top-down breeder revenue disclosures and feed industry consumption surveys.
Consistency checks validated volume and value outputs against external benchmarks including seed replacement rate assumptions, hybrid penetration curves by state, and feed grain demand projections from livestock sector reports. Segmentation modeling spanned product type, end-use application, distribution channel, and packaging format across the projection horizon. CAGRs derived from logistic curve fitting on technology adoption patterns, with explicit inputs for PLI scheme capital deployment trajectories and Seed Law revision compliance cost schedules.
Decision-makers should treat outputs as directional under assumptions of continued regulatory fragmentation and feed sector consolidation; material deviation in biosafety harmonization timelines or fertilizer cost volatility would warrant model refresh. Recalibration cycles align with material shifts in national seed law enforcement intensity and feed mill procurement consolidation milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Tomato Seed Market
Seeds
Garlic Chive Seeds Market
Seeds
Hemp Seed Oil Market
Seeds
Africa Sorghum Seed Market
Seeds
Asia-Pacific Rice Seed Market
Seeds
United States Forage Seed Market
Seeds
Europe Quinoa Seed Market
Seeds
Nepal Seeds Market
Seeds
Eucommia Seed Oil Market
Seeds
Global Oilseed Market
Seeds
Thailand Vegetable Seed Market
Seeds
Mustard Seeds Market
Seeds
Drought Tolerant Seeds Market
Seeds
South America Chia Seeds Market
Seeds
Africa Seed Market
Seeds
North America Forage Seed Market