
 Global Oleate Esters Market | 2026-2036
Global Oleate Esters Market Size, Share, and Industry Trends Forecast 2026-2036
Global Oleate Esters Market Foresight
Project finance tied to bio-refinery expansions is reconfiguring capital barriers for mid-scale oleochemical producers. KLK Oleo leverages integrated palm oil supply chains to sustain feedstock cost advantages across Southeast Asian operations. Emery Oleochemicals anchors its competitiveness through backward integration into fatty acid distillation. BASF SE differentiates via R&D intensity in high-purity pharmaceutical-grade esters.
Oleate esters comprise fatty acid esters derived from oleic acid, typically exhibiting iodine values between 80-95 g I₂/100g and pour points below -10°C, synthesized through acid-catalyzed esterification or transesterification of oleic acid with alcohols. These compounds function primarily as lubricity additives, emollients, and plasticizers across industrial and consumer formulations. Methyl oleate dominates volume production due to its established use in biodiesel lubricity enhancement and metalworking fluids. Isopropyl oleate captures expanding share in cosmetic applications where dry-touch emollients command premium positioning. Ethyl oleate maintains mature demand in pharmaceutical solvent systems, though margin pools are thinning amid generic competition.
REACH registration requirements and the EU Green Deal bio-based content mandates are elevating compliance costs for oleate ester importers into Europe. FDA pharmaceutical excipient standards and EPA bio-preferred procurement guidelines shape product specifications for US-bound shipments. China's GB standards on industrial lubricant formulations and NMPA cosmetic ingredient filings add further regulatory layering for multinational suppliers. Stakeholders must monitor evolving carbon border adjustment mechanisms and bio-feedstock certification schemes to preserve market access across jurisdictions.
Market Dynamics
REACH registration tiers and EU Green Deal bio-based mandates are forcing oleate ester suppliers to reconfigure certification pipelines and feedstock traceability systems across European value chains.
Growth Catalysts
- REACH compliance premiums:Registered oleate esters command preferential placement in EU cosmetic and pharmaceutical formulations, tightening procurement standards for non-registered imports.
- Biodiesel lubricity additives:Methyl oleate incorporation into ultra-low sulfur diesel formulations is accelerating across US and European fuel blending operations.
- Cosmetic emollient specialization:Isopropyl oleate demand concentrates in German and French personal care manufacturing clusters seeking dry-touch sensory profiles.
Market Restraints
- Palm oil price volatility:Feedstock cost swings in Malaysian and Indonesian palm oil markets compress margin predictability for non-integrated oleochemical processors.
- Technical substitution pressure:Synthetic esters and silicones compete in high-performance lubricant and cosmetic applications where oxidative stability thresholds exceed oleate ester specifications.
- Regulatory friction:China's NMPA cosmetic ingredient filing requirements extend approval timelines for new oleate ester variants entering personal care supply chains.
Strategic Opportunities
- Indian pharmaceutical excipient demand:CDSCO-aligned manufacturing investments create entry pathways for ethyl oleate suppliers serving domestic generic injectable production.
- EU carbon border adjustment mechanisms:Certified bio-based oleate esters gain tariff advantages over petrochemical alternatives in European industrial lubricant procurement.
- Enzymatic esterification convergence:Lipase-catalyzed production routes paired with continuous processing equipment enable pharmaceutical-grade purity at reduced energy intensity.
Industry Challenges
- Pharmaceutical-grade certification timelines:FDA and EMA excipient master file preparation demands 18-24 month documentation cycles that strain working capital for mid-scale producers.
- Feedstock traceability system integration:RSPO and ISCC certification requirements force legacy oleochemical operations to rebuild procurement databases and supplier audit protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Oleate Esters Market |
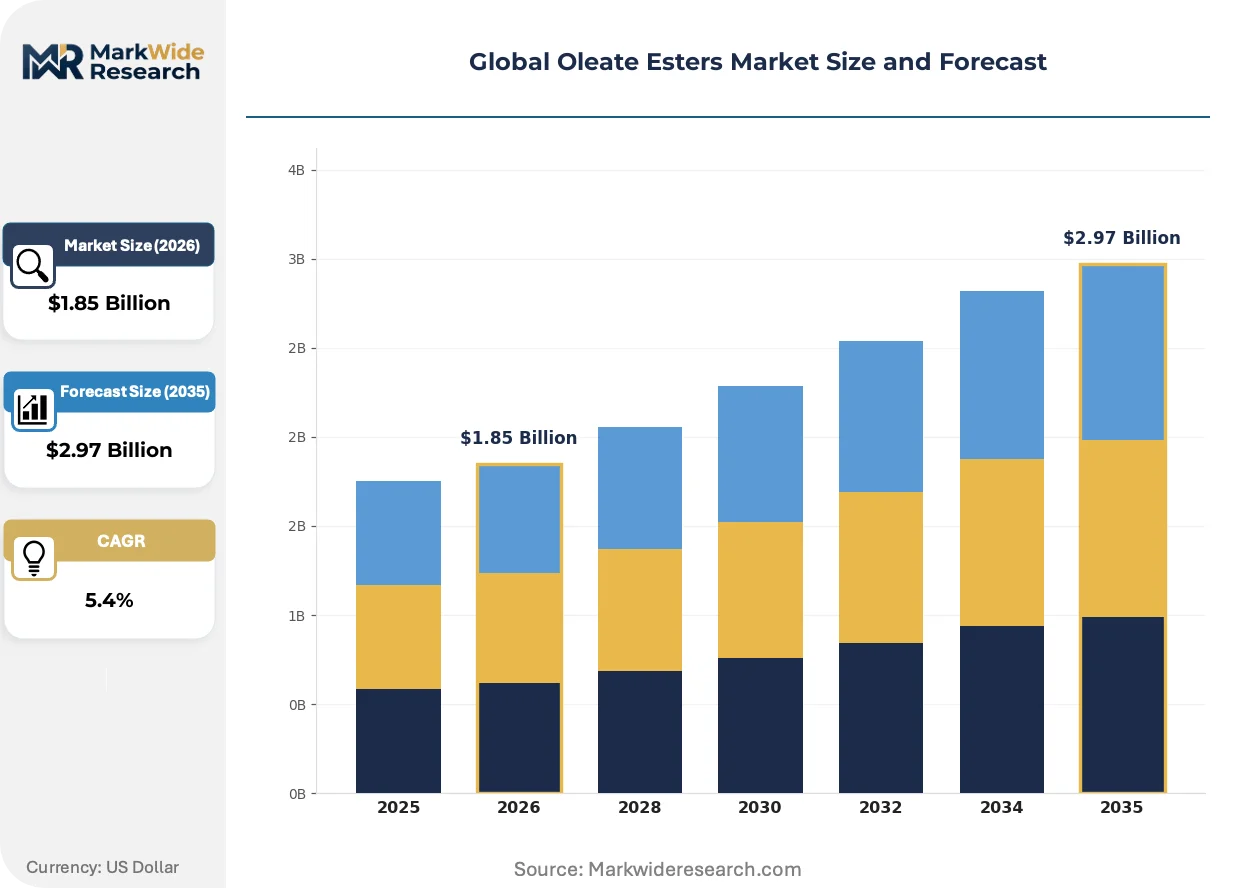
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ethyl Oleate, Isopropyl Oleate, Methyl Oleate, Butyl Oleate, Propyl Oleate Application: Lubricants, Cosmetics, Pharmaceuticals, Food Additives, Plasticizers, Textile Finishing End User: Personal Care Manufacturers, Pharmaceutical Companies, Chemical Processors, Food Producers, Textile Mills Packaging Type: Drums, Intermediate Bulk Containers, Bottles, Totes, Carboys |
| Companies Covered | Kao Corporation, Emery Oleochemicals, BASF SE, Italmatch Chemical, IOI Oleochemical, Croda International, KLK Oleo, Cayman Chemical, Wilmar International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Oleate Esters Market Shifts & Advancements
Process intensification and regulatory data architectures are compressing production economics while fragmenting competitive advantage between integrated feedstock controllers and specialized purity-grade refiners.
Continuous flow enzymatic esterification is collapsing batch reactor economics for pharmaceutical-grade oleate esters. European and North American custom manufacturers are adopting immobilized lipase systems to halve solvent use and energy consumption. This technology is collapsing the capital barrier between commodity oleochemical producers and high-margin pharmaceutical excipient suppliers.
ECHA's SCIP database requirements and EU Green Deal bio-based content verification protocols are mandating molecular-level feedstock documentation. Chemical processors must now maintain blockchain-traceable certification from plantation to formulation. German cosmetic ingredient clusters near Frankfurt are deploying digital product passports to preempt compliance penalties.
Direct long-term contracting between bio-refinery operators and personal care formulators is displacing traditional oleochemical distributor networks. Procurement teams at French and Italian cosmetic houses are negotiating three-year supply agreements with Malaysian integrated producers to lock in RSPO-certified volumes. This pattern concentrates most visibly in premium emollient segments where certification premiums exceed spot market volatility.
Global Oleate Esters Market Segmentation
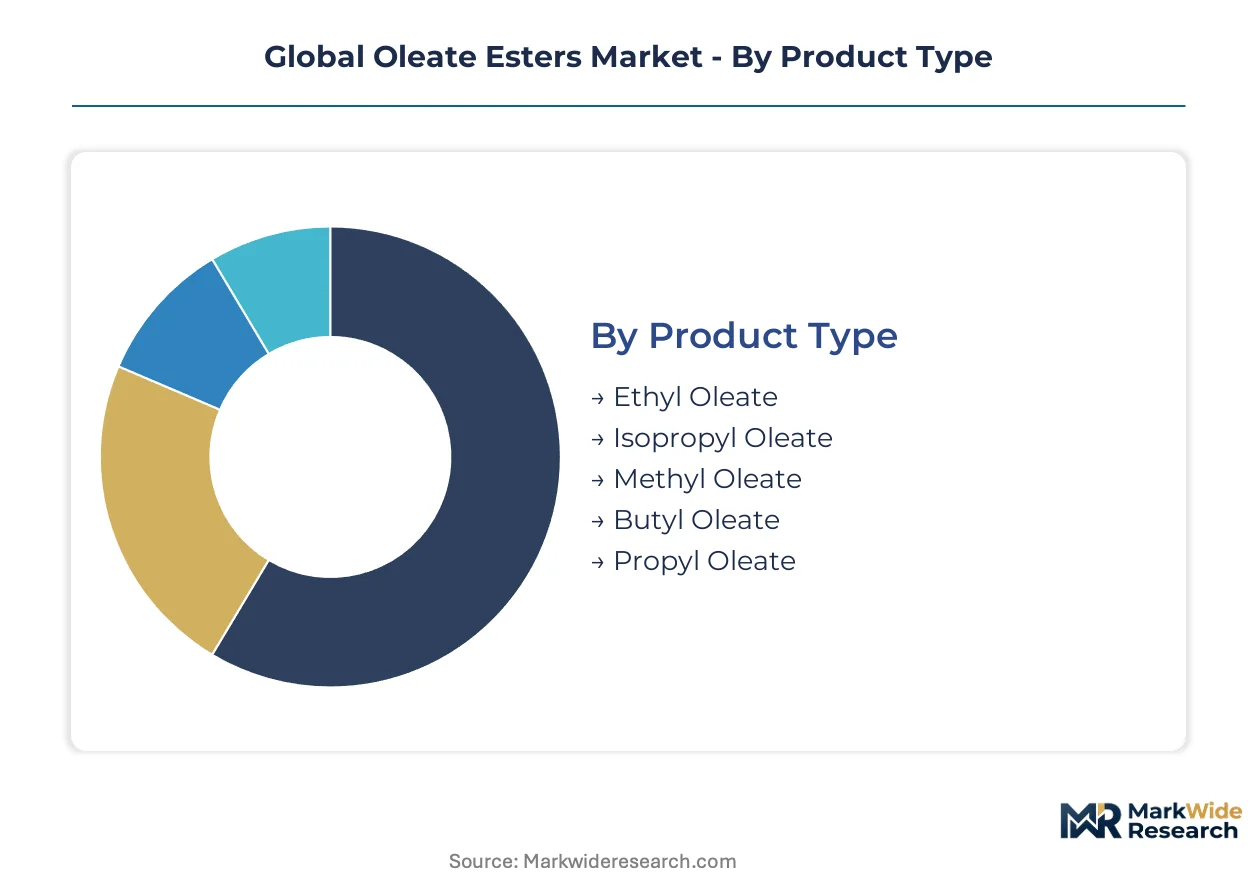
Oleate ester procurement patterns diverge sharply across product chemistries and end-use specifications. Pharmaceutical-grade purity requirements, cosmetic sensory profiles, and industrial lubricity thresholds each demand distinct molecular architectures and certification pipelines.
Product Type:
Mature commodity esters dominate volume flows while specialized variants capture expanding premium niches across pharmaceutical and cosmetic applications.
- Methyl Oleate:The simplest oleate ester formed from methanol transesterification, characterized by low viscosity and excellent cold-flow properties. Demand concentrates in US and European biodiesel lubricity enhancement where ultra-low sulfur diesel mandates require additive incorporation at 250-500 ppm treatment rates. REACH-registered grades command procurement preference among fuel blenders seeking regulatory compliance certainty.
- Isopropyl Oleate:Branched-chain ester delivering dry-touch emollient properties with rapid spreadability and non-greasy after-feel. German and French cosmetic formulators near Frankfurt and Paris manufacturing clusters specify this grade for premium skincare and sun care applications where sensory differentiation supports price positioning. NMPA cosmetic ingredient filings in China extend approval timelines for new entrants.
- Ethyl Oleate:Low-viscosity solvent ester meeting USP and Ph.Eur. excipient monographs for parenteral drug delivery systems. FDA pharmaceutical master file documentation demands 18-24 month preparation cycles.
- Butyl Oleate:Higher molecular weight ester functioning as polyvinyl chloride plasticizer and metalworking fluid lubricity additive. Industrial processors value its oxidative stability in high-temperature applications.
- Propyl Oleate:Intermediate-chain ester bridging cosmetic emollient and industrial lubricant applications. Limited commercial penetration relative to isopropyl and methyl variants.
Methyl oleate retains volume leadership; isopropyl oleate holds the steepest expansion curve.
Application:
Cost tier stratification separates commodity industrial uses from certification-intensive pharmaceutical and food-grade segments.
- Lubricants:Metalworking fluids, hydraulic systems, and biodiesel additives incorporate oleate esters for boundary lubrication and friction reduction. US EPA bio-preferred procurement guidelines favor bio-based content in federal fleet fueling operations. Pour point depression and lubricity enhancement drive specification in cold-climate diesel distribution.
- Cosmetics:Emollient and solubilizer functions in skincare, haircare, and color cosmetic formulations. EU Green Deal bio-based content mandates elevate certified sustainable palm derivative procurement requirements.
- Pharmaceuticals:Solvent and carrier systems for intramuscular and subcutaneous injectables. EMA excipient master file alignment enables European market access for ethyl oleate suppliers.
- Food Additives:Lubricant and release agent applications in food processing equipment. FDA food contact substance notifications required for indirect additive status.
- Plasticizers:Polymer flexibility enhancement in PVC compounding and coating formulations. Technical substitution pressure from phthalate alternatives shapes competitive dynamics.
- Textile Finishing:Softening agents and lubricants in fiber processing and fabric treatment. Chinese GB standards on textile chemical formulations govern import specifications.
Lubricant applications retain volume leadership; cosmetics holds the steepest expansion curve.
End User:
Customer type determines procurement scale, certification burden, and contract structure across the value chain.
- Personal Care Manufacturers:Formulators of skincare, haircare, and sun care products specifying emollient sensory profiles and RSPO certification. Direct long-term contracting with integrated bio-refinery operators is displacing traditional distributor networks.
- Pharmaceutical Companies:Generic injectable producers and innovator drug developers requiring USP-grade excipients with documented supply chain traceability. CDSCO-aligned manufacturing investments in India create regional demand concentration.
- Chemical Processors:Industrial lubricant blenders, plasticizer compounders, and specialty chemical manufacturers. REACH registration tiers force reconfiguration of European procurement standards.
- Food Producers:Processing equipment lubrication and food-grade release agent applications. National food safety authority approvals vary by jurisdiction.
- Textile Mills:Fiber lubrication and fabric finishing operations. Environmental discharge regulations constrain formulation choices in water-scarce production regions.
Chemical processors retain volume leadership; personal care manufacturers hold the steepest expansion curve.
Packaging Type:
Volume scale and handling economics dictate packaging selection across supply chain configurations.
- Intermediate Bulk Containers:275-gallon to 330-gallon totes enabling efficient bulk transfer to chemical processors and lubricant blenders. Reduced drum handling costs support procurement preference at scale.
- Drums:55-gallon steel and fiber containers serving mid-volume pharmaceutical and cosmetic manufacturers. UN certification required for hazardous material transport.
- Totes:Flexible intermediate bulk containers for non-hazardous industrial applications. Collapsible return logistics reduce environmental footprint.
- Bottles:Laboratory and pilot-scale quantities for pharmaceutical R&D and cosmetic formulation development. Amber glass options protect light-sensitive esters.
- Carboys:High-density polyethylene containers for food-grade and pharmaceutical-grade applications requiring dedicated handling protocols.
Intermediate bulk containers retain volume leadership; totes hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Personal care manufacturers in Germany and pharmaceutical compounders in the United States concentrate procurement of high-purity oleate esters. Chemical processors across Southeast Asia dominate industrial-grade volume flows. Regulatory divergence between REACH-registered European supply chains and FDA-aligned North American excipient standards fragments procurement strategies.
Germany
Cosmetic formulators near Frankfurt and Hamburg drive specialized isopropyl oleate procurement for premium emollient applications. REACH registration tiers and EU Green Deal bio-based mandates force suppliers to maintain blockchain-traceable certification from plantation to formulation. The Rhine-Main cluster anchors demand for RSPO-certified sustainable palm derivatives in skincare manufacturing.
United States
Biodiesel blenders incorporate methyl oleate at 250-500 ppm treatment rates to meet ultra-low sulfur diesel lubricity requirements. EPA bio-preferred procurement guidelines favor bio-based content in federal fleet fueling operations. Gulf Coast petrochemical corridors host lubricant additive compounding operations serving domestic fuel distribution networks.
China
Industrial lubricant manufacturers absorb butyl oleate volumes for metalworking fluid formulations under GB standards compliance. NMPA cosmetic ingredient filing requirements extend approval timelines for new oleate ester variants entering personal care supply chains. Yangtze River Delta chemical processors dominate domestic esterification capacity expansion.
India
Generic injectable producers generate ethyl oleate demand for parenteral drug delivery systems aligned with CDSCO manufacturing investments. The country's national pharmaceutical regulator tightens excipient documentation requirements for domestic and export markets. Maharashtra-based pharmaceutical clusters concentrate sterile formulation capacity serving global generic supply chains.
Malaysia
Integrated palm oil processors leverage captive feedstock supply to sustain cost advantages across oleochemical esterification operations. RSPO certification requirements from European personal care buyers force plantation-to-refinery traceability system investments. Klang Valley oleochemical complexes anchor Southeast Asian export capacity for biodiesel lubricity additives.
Global Oleate Esters Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent margin pools in the oleate esters market. Integrated bio-refinery operators leverage backward integration into fatty acid distillation to defend feedstock cost positions. Three archetypes dominate: palm oil conglomerates with captive plantation supply, European chemical majors with pharmaceutical-grade certification infrastructure, and regional oleochemical processors serving industrial lubricant blenders. Capacity expansion in enzymatic esterification and direct long-term contracting with cosmetic formulators represent the dominant competitive moves reshaping procurement relationships.
Among integrated Southeast Asian producers, KLK Oleo and Wilmar International exemplify the plantation-to-ester supply chain archetype. BASF SE anchors the European premium-grade segment through R&D intensity in high-purity pharmaceutical-grade esters. These three companies occupy positions that reflect the market's structural split between commodity volume flows and certification-intensive specialty segments.
| Leading Market Players |
|---|
| Kao Corporation |
| Emery Oleochemicals |
| BASF SE |
| Italmatch Chemical |
| IOI Oleochemical |
| Croda International |
| KLK Oleo |
| Cayman Chemical |
| Wilmar International |
| Others |
Supply & Pricing Matrix
Palm oil price volatility in Malaysian and Indonesian futures markets compresses margin predictability for non-integrated processors while simultaneously widening spreads between RSPO-certified premium tiers and uncertified economy grades. This feedstock risk vector forces buyers into longer-term contracting structures that reshape procurement geography and inventory positioning across the value chain.
Pricing Analysis
Cost-plus contracts indexed to BMD crude palm oil futures dominate procurement between Southeast Asian integrated producers and European cosmetic formulators. Three-tier pricing structure across pharmaceutical-grade, cosmetic-certified, and industrial-standard levels separates feedstock-traceable premiums from commodity spot material. Pricing pressure stems from synthetic ester substitution in high-performance lubricant applications where oxidative stability thresholds exceed oleate ester specifications. Chemical processors in metalworking fluids exhibit highest price sensitivity; pharmaceutical excipient buyers accept certification premiums.
Supply Chain Analysis
EU Green Deal bio-based content verification protocols function as de facto export controls limiting uncertified palm derivative flows into European cosmetic supply chains. Production gravity centers on Malaysia, Indonesia, and Germany, with captive plantation supply anchoring Southeast Asian cost positions. Raw material dependencies span crude palm oil, methanol feedstock, and immobilized lipase biocatalysts. Single-source vulnerability concentrates in RSPO-certified plantation supply contracted to personal care manufacturers. Distribution runs through direct long-term agreements displacing traditional oleochemical distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain-traceable certification systems are transforming oleate ester procurement into platform economics where feedstock provenance data interoperability determines supplier viability. German cosmetic ingredient clusters near Frankfurt exemplify this shift through digital product passport deployment.
For Market Incumbents: Insulate margin positions by deepening backward integration into fatty acid distillation and securing captive RSPO-certified plantation supply. Synthetic ester substitution in high-temperature lubricant applications threatens volume retention in industrial segments; counter through enzymatic esterification R&D investments that collapse pharmaceutical-grade purity costs. For New Entrants and Emerging Players: Pursue white-space opportunities in Indian pharmaceutical excipient supply serving CDSCO-aligned generic injectable production. The most penetrable segment lies in ethyl oleate for parenteral drug delivery systems where documentation cycles strain incumbent working capital. Establish go-to-market positioning through partnerships with Maharashtra-based sterile formulation facilities. For Investors and Strategic Acquirers: EU carbon border adjustment mechanism implementation reshapes the acquisition landscape toward certified bio-based oleochemical assets with integrated plantation supply. Long-term viability favors integrated Southeast Asian producers with blockchain-traceable certification infrastructure. The signal to watch is RSPO certification penetration rates among European personal care procurement teams.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Supply | Captive RSPO-certified feedstock secures margin defense against Malaysian palm oil futures volatility. |
| Enzymatic Esterification Scale-Up | Immobilized lipase systems halve solvent use and energy consumption for pharmaceutical-grade production. |
| Long-Term Supply Agreement | Direct three-year contracting with Frankfurt cosmetic clusters locks in certification premiums above spot volatility. |
| Digital Product Passport Deployment | Blockchain-traceable certification from plantation to formulation preempts ECHA SCIP database penalties. |
| EMA Excipient Master File Investment | Eighteen-to-twenty-four month documentation cycles create competitive moats in European pharmaceutical access. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs/trade data, SEC filings from listed oleochemical producers, and ECHA registration databases. Primary interviews engaged plant managers at integrated bio-refinery operations, procurement leads at German cosmetic formulators, technical R&D directors in enzymatic esterification, and distribution channel partners in industrial lubricant supply. Bottom-up volume modeling triangulated against top-down value chain analysis across the projection horizon.
Forecast inputs span grade tier segmentation, end-use industry demand patterns, packaging format economics, and regional production hub capacity utilization. Modeled dimensions include product chemistry, application specification, and certification level across the analysis window. CAGRs derived from regression against feedstock price indices, regulatory compliance cost trajectories, and substitution elasticity estimates for synthetic ester competitors.
Macroeconomic conditions sit as an overlay; deviation in crude palm oil futures, euro-dollar exchange rates, or EU carbon border adjustment implementation timelines would shift the trajectory. Material shifts in REACH registration tier enforcement or RSPO certification adoption rates among European buyers would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Europe Food Coating Ingredients Market
Food Additives and Ingredients
Europe Food Emulsifiers Market
Food Additives and Ingredients
Middle East and Africa Clean Label Ingredients Market
Food Additives and Ingredients
Asia-Pacific Fermented Ingredient Market
Food Additives and Ingredients
Bread Preservatives Market
Food Additives and Ingredients
Neohesperidine DC Market
Food Additives and Ingredients
Africa Food Emulsifiers Market
Food Additives and Ingredients
Microencapsulated Food Ingredient Market
Food Additives and Ingredients
Emulsified Shortenings Market
Food Additives and Ingredients
Europe Leavening Agents Market
Food Additives and Ingredients
Organic Food Additives Market
Food Additives and Ingredients
India Food Preservatives Market
Food Additives and Ingredients
Food Protein Ingredient Market
Food Additives and Ingredients
Egypt Feed Additives Market
Food Additives and Ingredients
Brazil Food Enzymes Market
Food Additives and Ingredients
Global Cereal Ingredients Market