
 Bread Preservatives Market | 2026-2036
Bread Preservatives Market Size, Share, and Industry Trends Forecast 2026-2036
Bread Preservatives Market Outlook
ISO 22000 certification is unwinding the competitive set in bread preservatives, filtering out suppliers lacking integrated food safety management systems. DSM leverages its biotechnology platform to sustain leadership in fermentation-derived preservation. BASF anchors its position through backward integration into acetic acid feedstocks for vinegar-based solutions. Corbion N.V. differentiates via specialized propionic acid bacteria cultivation for clean-label calcium propionate.
Bread preservatives comprise chemical and biological additives that inhibit mold growth, retard staling, and extend shelf life in yeast-leavened baked goods, typically dosed at 0.1% to 0.4% flour weight depending on water activity and pH. Calcium propionate dominates volume due to cost efficiency and broad pH tolerance, while vinegar and ascorbic acid represent the fastest-expanding margin pools as bakeries reformulate around consumer clean-label preferences. Application demand skews heavily toward sandwich breads where industrial scale and extended distribution cycles mandate robust preservation, whereas artisan breads command premium positioning with minimal additive declarations.
EFSA additive re-evaluations and EU Regulation 1333/2008 on food enzymes are tightening permissible preservative categories and maximum levels, compelling manufacturers to validate novel preservation mechanisms. The US FDA maintains Generally Recognized As Safe listings for calcium propionate and sorbic acid under 21 CFR, though clean-label pressure is driving voluntary substitution even where chemical preservatives remain legally permitted. Stakeholders must monitor regulatory divergence between jurisdictions and calibrate R&D pipelines toward biopreservation platforms that satisfy both compliance frameworks and shifting consumer sentiment.
Market Dynamics
EFSA's additive re-evaluation protocols are forcing bakeries across Germany, France, and Italy to abandon calcium propionate in favor of fermentation-derived alternatives, compressing reformulation timelines from years to months.
Growth Catalysts
- EU Regulation 1333/2008:Tightened maximum residue levels for synthetic preservatives in packaged bread are redirecting R&D budgets toward biopreservation platforms.
- Artisan bakery expansion:Craft bread consumption in Germany and the Netherlands is creating parallel demand streams for minimal-declaration preservation systems.
- Fermentation biotechnology:Propionic acid bacteria cultivation is achieving cost parity with chemical synthesis at industrial scale.
Market Restraints
- Acetic acid feedstock volatility:Natural vinegar-based solutions face input cost swings tied to agricultural commodity cycles.
- Clean-label certification scarcity:ISO 22000-accredited suppliers concentrate in Western Europe, creating bottleneck risk for reformulating bakeries elsewhere.
- pH sensitivity of biological preservatives:Fermentation-derived alternatives lose efficacy below 5.5 pH, limiting application in sourdough-dominant product lines.
Strategic Opportunities
- Eastern European bakery modernization:Poland and Romania present underpenetrated demand as industrial baking capacity upgrades to Western shelf-life standards.
- EU Green Deal bioeconomy incentives:Horizon Europe funding streams favor carbon-negative fermentation processes for food preservation.
- Direct-to-retailer channel expansion:Bypassing traditional ingredient distributors allows preservative suppliers to capture margin from clean-label premiums.
Industry Challenges
- Fermentation scale-up talent gap:Industrial microbiology expertise concentrates at biotechnology firms, not legacy chemical suppliers.
- Dual certification burden:Simultaneous ISO 22000 and organic compliance timelines stretch 18-24 months for new production facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bread Preservatives Market |
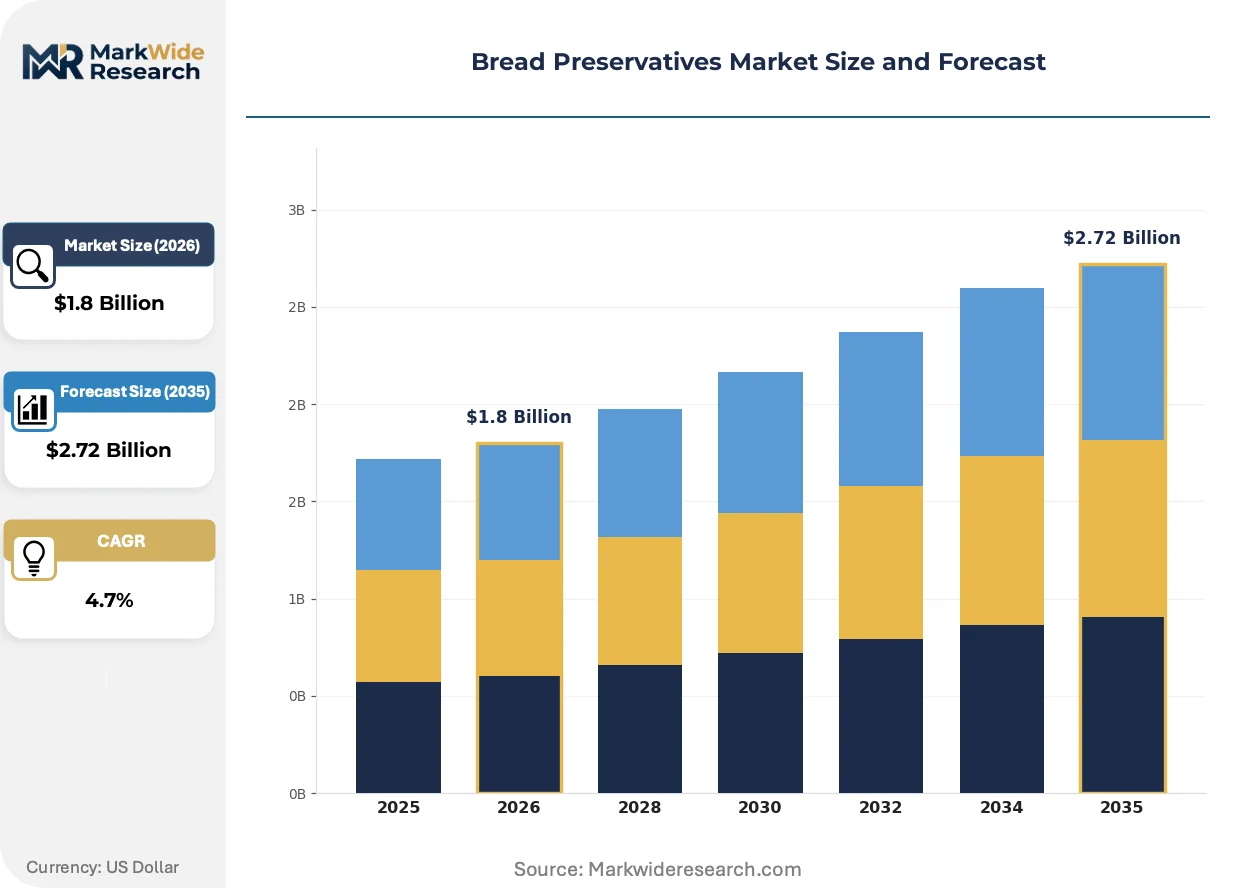
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calcium Propionate, Sorbic Acid, Vinegar, Ascorbic Acid Application: Bakery Products, Sandwich Breads, Sweet Breads, Artisan Breads End User: Bakeries, Food Service Chains, Retailers, Home Bakers Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Wholesale |
| Companies Covered | DSM, BASF, Celanese, DuPont, Kerry Group, Corbion N.V., Kemin Industries, Galactic, Lesaffre, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bread Preservatives Market Strategic Shifts
Biopreservation platforms are displacing chemical additive paradigms across European industrial baking, with regulatory pressure and consumer transparency demands converging to accelerate technology substitution cycles.
Encapsulated vinegar systems are miniaturizing active acetic acid delivery into microsphere formats that protect efficacy through high-temperature baking. Industrial sandwich bread manufacturers in Germany and the Netherlands are adopting these systems at pilot scale. The technology is miniaturizing preservation dosage precision, enabling bakers to maintain shelf life while reducing total additive declarations by half.
REACH authorization amendments for food-contact substances are tightening purity specifications on propionic acid derivatives used in bread applications. Chemical manufacturers face reformulation costs to eliminate residual impurities below new threshold limits. Artisan bread segments in France and Italy are responding fastest, having already eliminated synthetic propionates from ingredient decks.
Buyer concentration among European supermarket private-label bakeries is compressing supplier negotiation cycles from annual to quarterly frameworks. Ingredient procurement teams at centralized retail baking operations now demand real-time reformulation support and joint shelf-life testing protocols. This pattern is most visible in Germany, where Aldi and Lidl baking cooperatives dictate preservation specifications across hundreds of regional production sites.
Bread Preservatives Market Segmentation
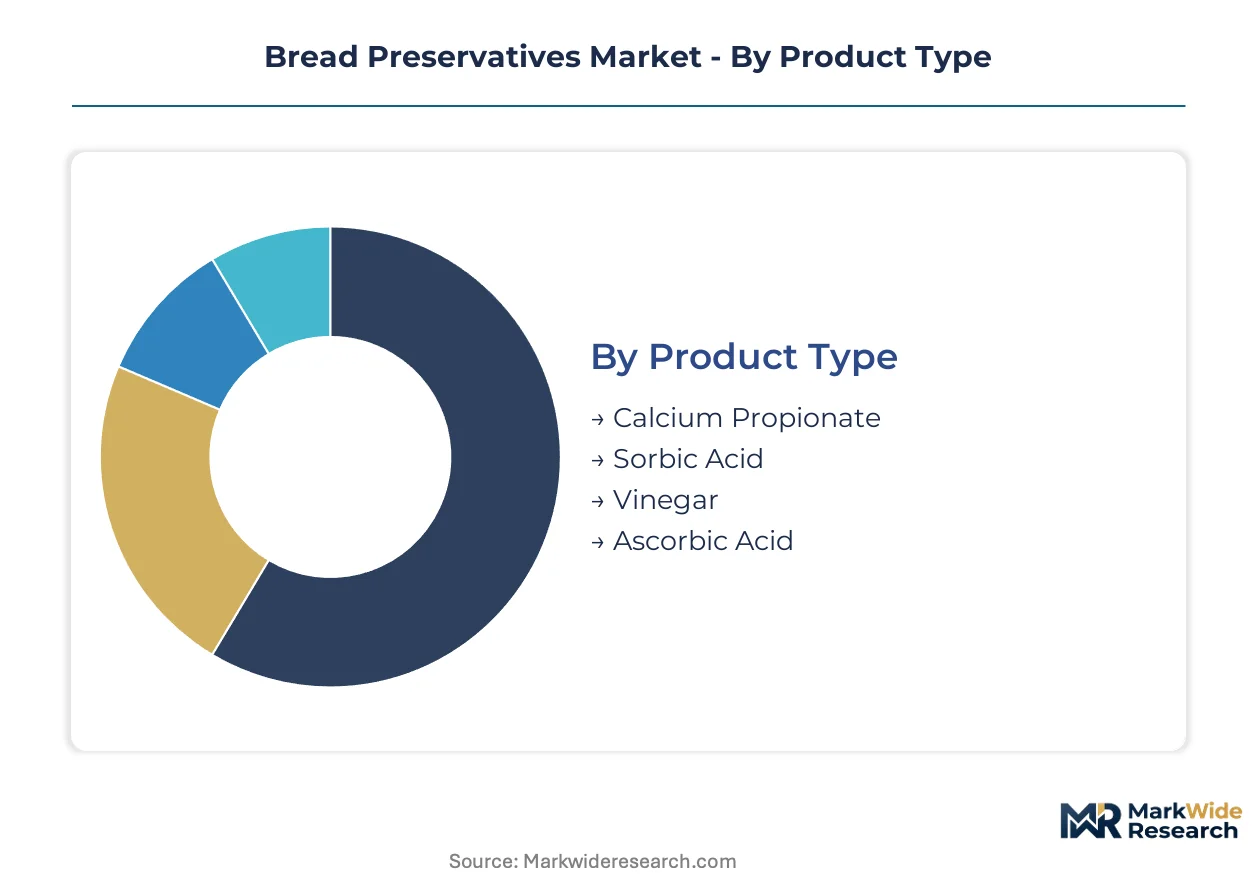
Preservative selection in bread manufacturing now hinges on reformulation economics rather than legacy performance metrics. EFSA additive re-evaluations have fragmented the competitive map, forcing suppliers to defend position across divergent cost and clean-label tiers simultaneously.
Product Type:
Substitution pressure from fermentation-derived alternatives is reshaping the competitive hierarchy most acutely among synthetic preservatives, while natural acidulants face input cost volatility rather than regulatory displacement.
- Calcium Propionate:Synthetic propionate salt inhibits mold across broad pH ranges with minimal dosage requirements. Industrial sandwich bread lines in Germany and the Netherlands rely on established supply contracts, though EFSA maximum level reductions are compressing allowable application windows.
- Vinegar:Fermentation-derived acetic acid delivers clean-label positioning with consumer-transparent ingredient declarations. Artisan bakeries across France and Italy are adopting concentrated vinegar systems fastest, driven by retailer private-label specifications mandating zero synthetic additive content.
- Sorbic Acid:Potassium salt derivative effective against yeast and mold in high-moisture applications.
- Ascorbic Acid:Vitamin C-based antioxidant retarding staling through gluten network strengthening.
Calcium propionate anchors the volume base while vinegar gains share at the steepest rate.
Application:
Cost tier differentiation separates industrial-scale preservation needs from premium minimal-declaration positioning, with margin structure diverging sharply across production volumes.
- Sandwich Breads:High-volume industrial loaves require maximum shelf-life extension through distribution cycles exceeding fourteen days. Centralized retail baking operations in Germany specify dual-preservation systems combining calcium propionate with encapsulated vinegar to balance cost and clean-label demands.
- Artisan Breads:Craft sourdough and heritage grain varieties command premium positioning through minimal ingredient decks. French and Italian producers have largely eliminated synthetic propionates, relying instead on pH management and fermentation-derived acidity for preservation.
- Bakery Products:Rolls, buns, and specialty items with variable water activity profiles.
- Sweet Breads:High-sugar formulations where osmotic pressure supplements chemical preservation.
Sandwich breads concentrate procurement volume while artisan breads expand the addressable margin pool fastest.
End User:
Customer type determines specification authority, with centralized retail chains wielding reformulation mandates that fragmented bakery operators cannot match.
- Retailers:Supermarket private-label baking cooperatives dictate preservation standards across hundreds of production sites. Aldi and Lidl procurement teams in Germany now require quarterly specification reviews, accelerating substitution timelines for synthetic additives.
- Bakeries:Independent and cooperative baking operations span industrial, craft, and hybrid production models. Eastern European facilities in Poland and Romania are modernizing toward Western shelf-life standards, creating parallel demand for both conventional and clean-label preservation systems.
- Food Service Chains:Centralized procurement for restaurant and catering operations with frozen-distribution requirements.
- Home Bakers:Consumer-packaged preservation solutions for small-batch production.
Retailers command specification authority while bakeries present the broadest geographic expansion opportunity.
Distribution Channel:
Supply concentration in Western Europe creates bottleneck risk for reformulating bakeries elsewhere, with channel selection directly tied to certification access.
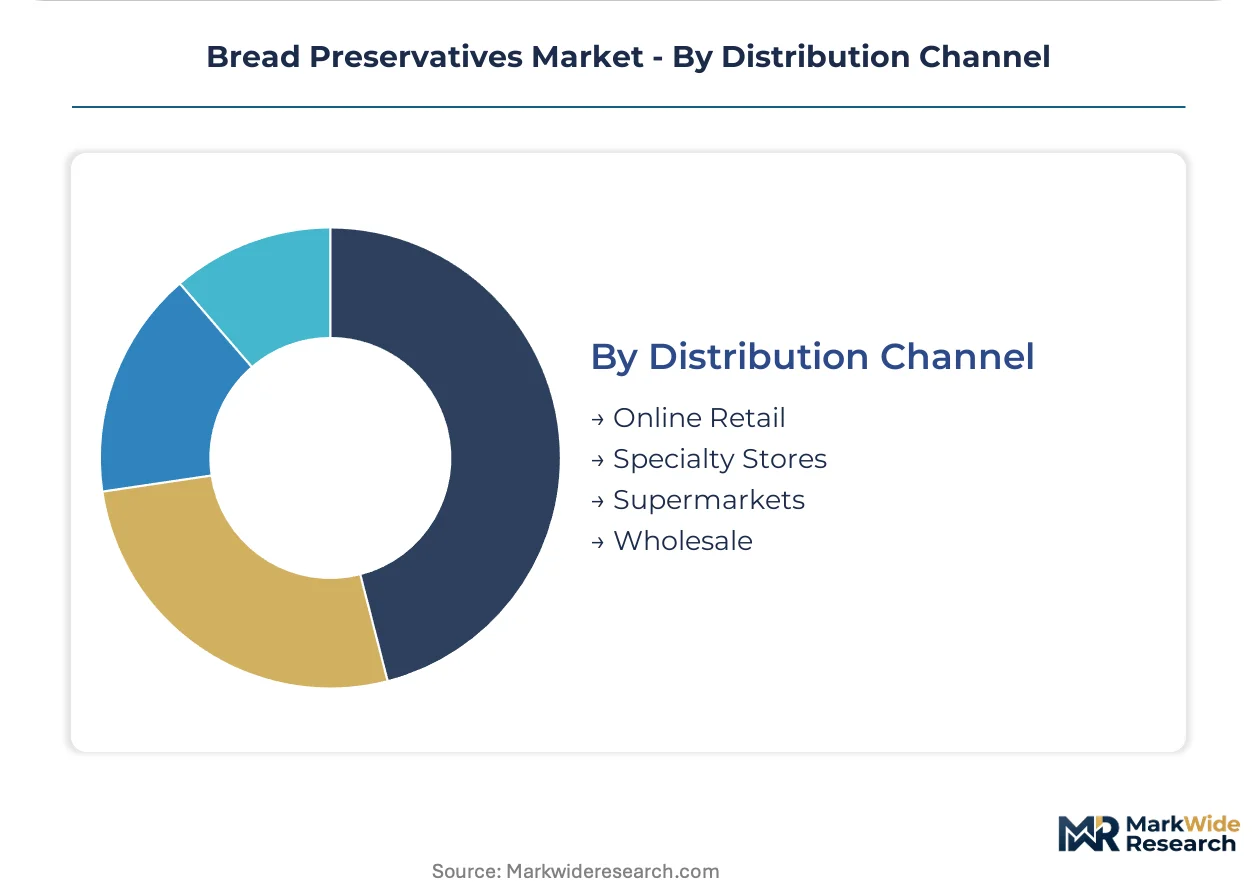
- Wholesale:Bulk ingredient supply to industrial baking operations with integrated quality management systems. ISO 22000-accredited wholesalers concentrate in Germany, France, and the Netherlands, filtering supplier access for large-volume accounts.
- Online Retail:Direct-to-customer platforms enabling smaller bakeries to source specialized fermentation-derived preservatives. Digital procurement is expanding fastest among craft operators seeking clean-label alternatives unavailable through traditional distributors.
- Supermarkets:Ingredient retail for home bakers and small commercial operations.
- Specialty Stores:Professional baking supply outlets with technical consultation services.
Wholesale channels dominate volume throughput while online retail climbs the fastest among emerging customer segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal bioeconomy incentives are redirecting fermentation-derived preservative investment toward jurisdictions with established biotechnology infrastructure. National regulatory divergence is fragmenting formulation standards across jurisdictions.
Germany
Industrial sandwich bread manufacturers in Lower Saxony and Bavaria are modernizing production lines to meet Aldi and Lidl private-label specifications. EFSA additive re-evaluations are compressing allowable calcium propionate application windows. The Munich-Stuttgart corridor concentrates biopreservation R&D facilities serving Central European bakery cooperatives.
France
Artisan sourdough producers in Île-de-France and Auvergne-Rhône-Alpes have largely eliminated synthetic propionates from ingredient declarations. ANSM monitoring of clean-label claims is tightening enforcement against misleading preservation marketing. Lyon-based ingredient distributors are expanding fermentation-derived acidulant portfolios for heritage grain bakeries.
Italy
Craft bread consumption in Lombardy and Emilia-Romagna is driving demand for minimal-declaration preservation systems. EU Regulation 1333/2008 on food enzymes is accelerating validation timelines for novel biopreservation mechanisms. Bologna's food technology cluster hosts pilot-scale propionic acid bacteria cultivation facilities.
Netherlands
Encapsulated vinegar system adoption is advancing fastest among industrial bakers in Randstad provinces. REACH authorization amendments for food-contact substances are tightening purity specifications on acetic acid derivatives. Wageningen's agri-food research hub is scaling microsphere delivery technologies for high-temperature baking applications.
Poland
Bakery modernization in Warsaw and Kraków metropolitan areas is creating demand for Western shelf-life standards. The country's national food safety regulator is aligning additive maximum levels with EFSA protocols. Poznań-based industrial baking facilities are upgrading to ISO 22000 quality management systems for EU market access.
Bread Preservatives Market Competitive Environment
Listed leaders compete with private specialists across certification tiers and geographic reach. The vendor base fragments across fermentation biotechnology platforms, chemical synthesis operations, and integrated food safety management systems. Three archetypes dominate: diversified chemical conglomerates with backward integration into feedstocks, specialized biotech firms with proprietary bacterial cultivation, and regional ingredient distributors with ISO 22000 accreditation. Capacity expansion and strategic partnerships represent the dominant competitive moves as reformulation timelines compress.
Within the biotechnology tier, DSM and Corbion N.V. exemplify fermentation-derived preservation platforms. BASF anchors the chemical synthesis segment with captive acetic acid supply chains. Kerry Group occupies a position bridging clean-label formulation expertise with industrial scale manufacturing. These three entities represent distinct strategic postures: biotech specialization, feedstock integration, and application-focused service models.
| Leading Market Players |
|---|
| DSM |
| BASF |
| Celanese |
| DuPont |
| Kerry Group |
| Corbion N.V. |
| Kemin Industries |
| Galactic |
| Lesaffre |
| Others |
Value Chain & Pricing Dynamics
Fermentation-derived calcium propionate displacing synthetic alternatives is redrawing supplier geography toward biotechnology clusters while compressing price premiums for clean-label systems. EFSA maximum level reductions and ISO 22000 certification scarcity in Eastern Europe are simultaneously elevating input costs and delivery premiums for reformulating bakeries.
Pricing Analysis
Certification level creates the primary spread across preservative tiers, with ISO 22000-accredited fermentation-derived products commanding substantial premiums over conventional chemical grades. Three-tier pricing structure separates premium biopreservation platforms from standard synthetic propionates and economy-grade vinegar concentrates. Pricing pressure stems from acetic acid feedstock volatility tied to agricultural commodity cycles, squeezing margins on natural acidulant portfolios. Industrial sandwich bread manufacturers exhibit highest price sensitivity due to volume procurement and thin margins, while artisan bakeries absorb premiums for minimal-declaration systems.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg port corridors fluctuate with container availability and Baltic trade lane congestion, elevating landed costs for fermentation feedstocks. Supply concentrates in Germany, the Netherlands, and France, with propionic acid bacteria cultivation facilities clustering near Wageningen and Munich-Stuttgart. Raw material dependencies include agricultural substrates for fermentation, acetic acid derivatives, and specialized bacterial strains. Single-source vulnerability runs through concentrated biotechnology expertise at DSM and Corbion. Distribution runs through wholesale channels with ISO 22000 accreditation filtering access for large-volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biopreservation platform economics are reaching an inflection where interoperability between fermentation technology and retail private-label specifications creates winner-take-most dynamics. Ecosystem control over bacterial strain IP and joint shelf-life testing protocols is becoming the primary value capture mechanism.
For Market Incumbents: Secure captive fermentation capacity through backward integration into propionic acid bacteria cultivation or exclusive strain licensing agreements. DSM and Corbion's biotechnology platforms threaten chemical synthesis incumbents; BASF must accelerate acetic acid feedstock integration to defend margin position. ISO 22000 certification investment represents the critical lever for maintaining specification authority with Aldi and Lidl procurement teams. For New Entrants and Emerging Players: Lead with encapsulated vinegar microsphere systems targeting Poland and Romania bakery modernization, where Western shelf-life standards create immediate demand without entrenched supplier relationships. Direct-to-retailer channel expansion bypassing legacy distributors captures clean-label premiums fastest. Eastern European industrial baking cooperatives present the most penetrable white-space for fermentation-derived alternatives lacking local supply. For Investors and Strategic Acquirers: The market sits at a substitution-acceleration phase that favors biotechnology specialists with scalable bacterial cultivation platforms. Long-term viability over the coming decade hinges on carbon-negative fermentation process validation under EU Green Deal funding criteria. Acquisition targets should demonstrate Horizon Europe grant capture and joint development agreements with centralized retail baking operations. The signal to watch is quarterly specification review adoption by additional supermarket private-label cooperatives beyond Germany.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bacterial Strain Cultivation | Captures margin from fermentation-derived calcium propionate while securing supply continuity for EFSA-compliant reformulation cycles. |
| Encapsulated Vinegar Microsphere Scale-Up | Enables high-temperature baking applications for industrial sandwich bread lines in Germany and the Netherlands. |
| ISO 22000 Certification Expansion | Unlocks procurement access to Aldi and Lidl baking cooperatives dictating preservation standards across hundreds of production sites. |
| Direct-to-Retailer Channel Development | Bypasses traditional ingredient distributors to capture clean-label premiums from artisan bakery segments in France and Italy. |
| Horizon Europe Bioeconomy Partnership | Secures funding for carbon-negative fermentation processes aligned with EU Green Deal incentives. |
Study Parameters
A spread of perspectives from biotechnology R&D directors, industrial bakery procurement managers, fermentation plant engineers, and retail private-label specification teams converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through EFSA additive re-evaluation documentation, EU Regulation 1333/2008 implementation records, and customs trade data on acetic acid derivatives. Bottom-up volume modeling from individual production facilities triangulated against top-down expenditure analysis from centralized retail baking cooperatives.
Segmentation dimensions modeled include preservative chemistry type, application format across sandwich and artisan bread lines, end-user procurement authority, and geographic regulatory cluster. CAGRs were derived through regression analysis of historical substitution patterns and forward projection of EFSA compliance timelines. Industry-specific forecast inputs encompassed fermentation scale-up cost curves and encapsulated delivery technology adoption rates.
Forecasts assume regulatory continuity in EFSA additive authorization protocols and EU Green Deal bioeconomy incentive structures; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
China Food Emulsifiers Market
Food Additives and Ingredients
Emulsifiers Market
Food Additives and Ingredients
Gardenia Food Color Market
Food Additives and Ingredients
South Africa Food Enzymes Market
Food Additives and Ingredients
Australia Feed Additives Market
Food Additives and Ingredients
Cocoglycerides Market
Food Additives and Ingredients
Food Acidulants Market
Food Additives and Ingredients
North America Food Starch Market
Food Additives and Ingredients
Vietnam Food Additives Market
Food Additives and Ingredients
Potassium Polymetaphosphate Food Additives Market
Food Additives and Ingredients
Africa Food Preservatives Market
Food Additives and Ingredients
Ascorbyl Palmitate Market
Food Additives and Ingredients
Bakery Release Agents Market
Food Additives and Ingredients
Food Enzymes Market
Food Additives and Ingredients
Europe Feed Anti-Caking Agents Market
Food Additives and Ingredients
Asia-Pacific Food Enzymes Market