
 Europe Food Emulsifiers Market | 2026-2036
Europe Food Emulsifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Food Emulsifiers Market Foresight
Modular emulsifier blends is decoupling single-ingredient procurement patterns across European food manufacturers. Kerry Group plc leverages its integrated taste and nutrition platform to bundle emulsifier systems with texture solutions for bakery clients. Corbion N.V. specializes in microbial fermentation-derived emulsifiers, sustaining premium positioning amid tightening palm oil scrutiny. Palsgaard A/S anchors its competitive stance through application-specific innovation centers in Denmark and the Netherlands.
Europe food emulsifiers are surface-active compounds, typically esters of fatty acids and polyols or phospholipids, that reduce interfacial tension between immiscible phases such as oil and water in processed foods. Mono- and diglycerides dominate volume flows across baked goods and dairy applications due to cost efficiency and established GRAS status, though lecithin segments are capturing margin expansion as non-GMO and organic certifications command price premiums. Polyglycerol esters represent the fastest-growing product category, displacing traditional emulsifiers in clean-label confectionery where E-number reduction drives reformulation mandates.
EFSA's systematic re-evaluation of food additives under Regulation (EU) No 257/2010 is compressing approval timelines and elevating toxicological data requirements for novel emulsifier submissions. REACH compliance and the EU Green Deal's sustainable chemistry benchmarks are redirecting capital toward bio-based feedstock supply chains and enzymatic processing routes with lower carbon intensity. Stakeholders must monitor EFSA's pending opinions on polyglycerol ester safety margins while calibrating R&D pipelines to anticipated restrictions on synthetic emulsifier categories.
Market Dynamics
EFSA's systematic re-evaluation of food additives under Regulation (EU) No 257/2010 is compressing approval timelines and forcing manufacturers to accelerate reformulation cycles. This regulatory pressure is restructuring competitive advantage toward firms with integrated bio-based R&D capabilities.
Growth Catalysts
- Clean-label bakery reformulation:German and French manufacturers are replacing synthetic additives with plant-derived lecithin in premium bread and pastry lines to meet retailer E-number reduction mandates.
- EU Green Deal bio-based mandates:The sustainable chemistry benchmarks are redirecting capital toward enzymatic esterification processes with verified lower carbon intensity.
- Polyglycerol ester adoption:Confectionery formulators in Benelux are deploying these emulsifiers to achieve clean-label positioning while maintaining texture stability in chocolate and coatings.
Market Restraints
- Palm oil feedstock concentration:Southeast Asian supply dominance exposes European processors to price volatility and sustainability audit complexity under REACH traceability requirements.
- Novel emulsifier toxicological data costs:EFSA's elevated safety margin requirements for new submissions impose multi-year testing burdens that freeze SME pipeline development.
- Enzymatic process capex intensity:Continuous fermentation infrastructure for microbial emulsifier production demands capital deployment that mid-scale manufacturers cannot access.
Strategic Opportunities
- Northern Italian formulation hub expansion:The Parma and Modena clusters offer co-manufacturing partnerships for clean-label dairy emulsifier systems targeting Mediterranean exports.
- CSRD-driven supply chain disclosure:The Corporate Sustainability Reporting Directive creates competitive differentiation for emulsifier producers with verified Scope 3 carbon accounting.
- Plant protein convergence:Hybrid emulsifier-stabilizer blends for oat and pea milk applications are capturing formulation slots in Scandinavian dairy alternatives.
Industry Challenges
- Cross-functional formulation talent scarcity:Food chemists with simultaneous expertise in enzymatic catalysis and sensory science command premiums that strain R&D staffing.
- Legacy equipment retrofit complexity:Batch reactor systems designed for chemical esterification require costly reconfiguration to handle continuous enzymatic processes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Food Emulsifiers Market |
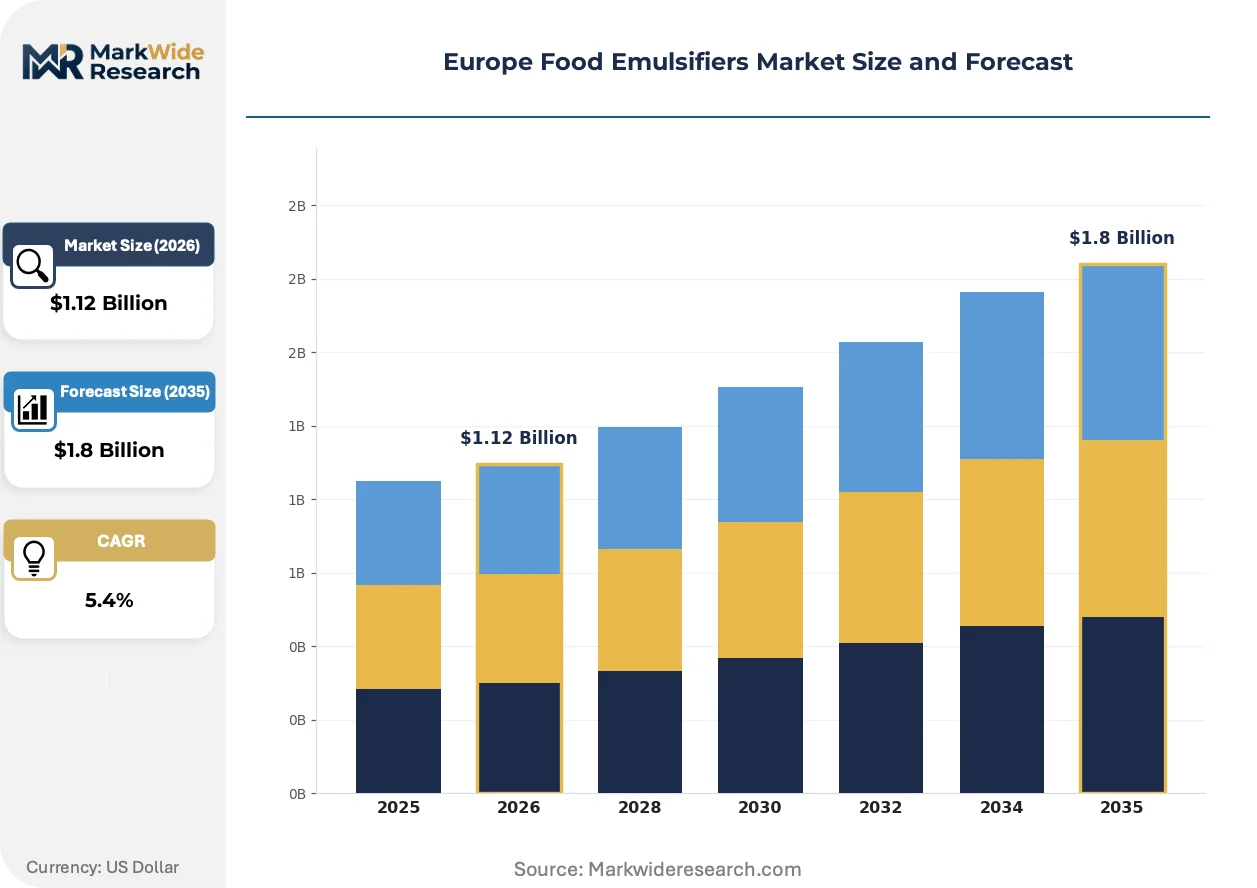
| Market Size in 2026 | $1.12 Billion |
| Market Size in 2035 | $1.8 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lecithins, Mono- and Diglycerides, Polyglycerol Esters, Sorbitan Esters Application: Baked Goods, Dairy Products, Confectionery, Sauces Source: Plant-Based, Animal-Based, Synthetic, Other End User: Food Manufacturers, Retailers, Foodservice, Households |
| Companies Covered | Kerry Group plc, Corbion N.V., BASF SE, Ingredion Incorporated, Palsgaard A/S, DuPont de Nemours, Inc., Archer Daniels Midland Company, Puratos Group NV, Cargill, Incorporated, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Food Emulsifiers Market Shifts & Advancements
Modular emulsifier systems are decoupling single-ingredient procurement across European food manufacturing, enabling application-specific optimization rather than commodity purchasing. This architectural shift is compressing supplier margins while rewarding integrated solution providers.
Enzymatic esterification technology is integrating into commercial-scale production lines across Dutch and Danish processing facilities. Bakery and confectionery manufacturers are adopting these routes to secure non-GMO certification and palm-free positioning. The technology is integrating process water reduction and energy savings into standard cost structures, reshaping capital allocation toward fermentation infrastructure.
REACH compliance and the EU Green Deal's sustainable chemistry benchmarks are tightening feedstock traceability requirements for all imported vegetable oils. Processors must now document deforestation-free supply chains through geolocation verification and mass balance certification. Northern European dairy and margarine producers are most affected, accelerating partnerships with domestic oilseed cooperatives to shorten supply chains.
Buyer concentration among European retail private-label programs is compressing emulsifier supplier negotiation leverage. Large bakery and dairy manufacturers are consolidating procurement into multi-year framework agreements with technical service bundling. This pattern is most visible in German discount retail supply chains, where Aldi and Lidl specifications now dictate emulsifier blend composition across tier-one suppliers.
Europe Food Emulsifiers Market Segmentation
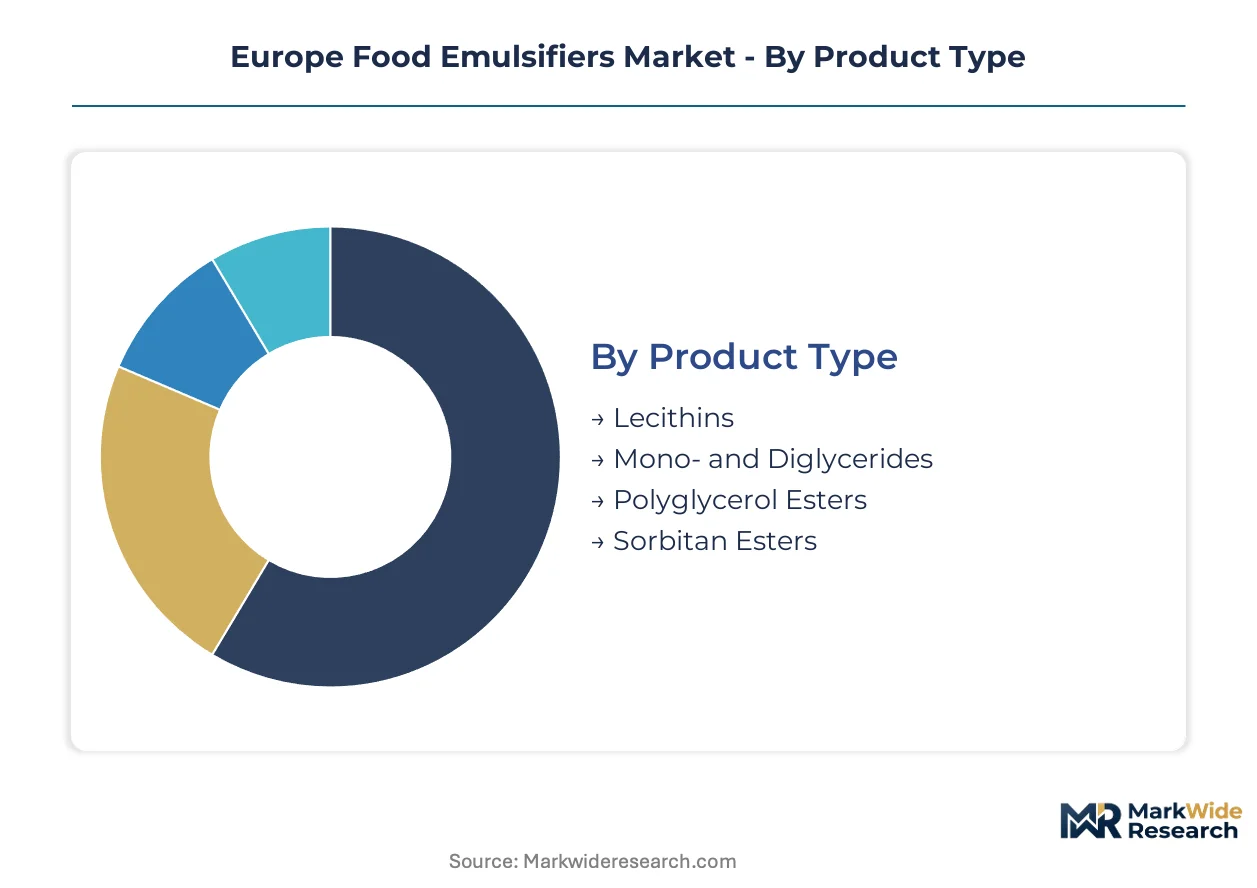
Emulsifier procurement patterns in Europe diverge sharply across product chemistry and end-use specifications. EFSA's additive re-evaluation under Regulation (EU) No 257/2010 imposes distinct toxicological data burdens on each segment, reshaping competitive positioning toward categories with established safety dossiers.
Product Type:
Certification intensity varies by molecular origin—plant-derived phospholipids face lighter novel food scrutiny than synthetic esters requiring full toxicological packages.
- Mono- and Diglycerides:Fatty acid esters produced through glycerolysis of triglycerides dominate volume flows across German and French industrial bakeries. Cost efficiency and decades of GRAS recognition insulate this segment from EFSA's tightening safety margin reviews.
- Polyglycerol Esters:Complex esters of polymerized glycerol with fatty acids are displacing traditional emulsifiers in Benelux confectionery clean-label reformulations. E-number reduction mandates from Aldi and Lidl specifications accelerate adoption despite pending EFSA toxicological opinions.
- Lecithins:Phospholipid mixtures from soy or sunflower sources command organic and non-GMO price premiums in Scandinavian dairy alternatives.
- Sorbitan Esters:Sorbitol-derived surfactants retain niche positions in chocolate coatings requiring specific polymorphic control.
Leading the category by volume: Mono- and Diglycerides. Growing fastest: Polyglycerol Esters.
Application:
Margin structures diverge by processing intensity—thermal-stable emulsifiers for baked goods tolerate commodity pricing, while cold-process dairy applications reward premium functional blends.
- Baked Goods:Bread, pastry, and industrial bakery applications consume standardized mono- and diglyceride volumes with limited differentiation leverage.
- Dairy Products:Margarine, spreads, and processed cheese demand precise crystallization control, concentrating procurement among Dutch and Danish suppliers with integrated texture laboratories.
- Confectionery:Chocolate and coating manufacturers in Northern Italy specify polyglycerol esters for clean-label positioning without sacrificing snap and gloss.
- Sauces:Mayonnaise and dressing emulsions require high-HLB systems where lecithin-egg hybrid blends dominate premium positioning.
Highest volume concentration: Baked Goods. Steepest expansion trajectory: Dairy Products.
Source:
Feedstock traceability under REACH and EU Green Deal benchmarks creates tiered compliance costs—mass balance certification adds 8-12% overhead to palm-derived inputs.
- Plant-Based:Soy, sunflower, and rapeseed lecithins anchor clean-label positioning, with Northern European oilseed cooperatives shortening supply chains for domestic dairy processors.
- Synthetic:Petrochemical-derived sorbitan esters face margin compression from bio-based substitution mandates in German retail private-label programs.
- Animal-Based:Egg and milk-derived phospholipids retain kosher and halal-sensitive niches despite limited scalability.
- Other:Microbial fermentation routes from Corbion and specialty suppliers occupy premium positioning amid tightening palm oil scrutiny.
Dominant by procurement value: Plant-Based. Gaining share fastest: Other (fermentation-derived).
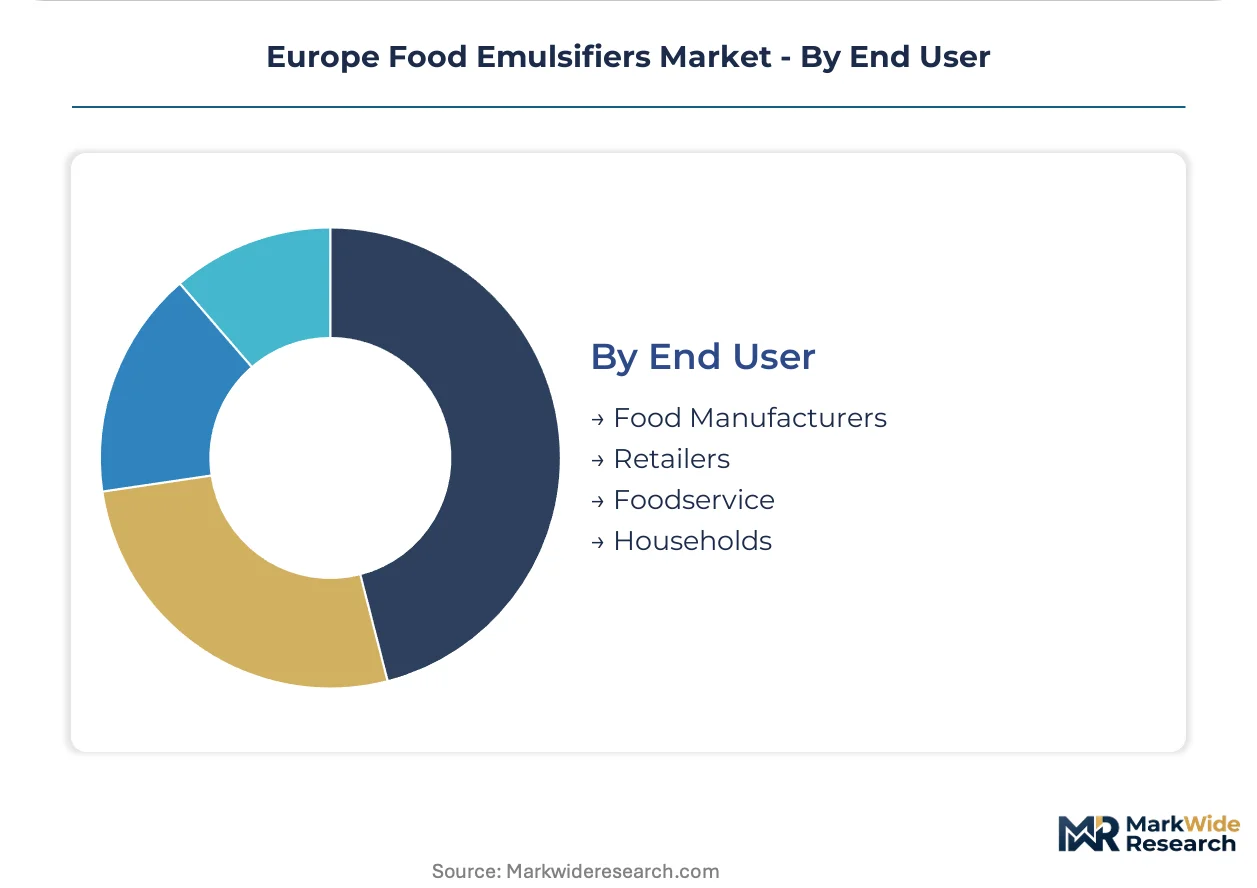
End User:
Buyer concentration patterns reshape contract structures—framework agreements with technical service bundling now standard among consolidated food manufacturers.
- Food Manufacturers:Industrial bakery and dairy processors in Germany, France, and Benelux consolidate procurement into multi-year supply agreements with formulation support.
- Retailers:Aldi and Lidl specifications dictate emulsifier blend composition across tier-one suppliers, compressing negotiation leverage for specialty producers.
- Foodservice:Institutional catering and QSR chains specify cost-optimized mono- and diglyceride systems with limited clean-label premiums.
- Households:Consumer-packaged emulsifiers for home baking represent marginal volume with distribution concentrated through specialty retailers.
Largest procurement volume: Food Manufacturers. Contract value expansion: Retailers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in Northern Europe while consumption concentrates in Western European manufacturing belts. German and Dutch processors supply emulsifier systems across the continent. Southern Europe's specialty food traditions drive differentiated formulation demand.
Germany
Industrial bakery chains and discount retail private-label programs absorb standardized mono- and diglyceride volumes. EFSA's additive re-evaluation under Regulation (EU) No 257/2010 pressures reformulation timelines for synthetic emulsifier categories. The Rhine-Ruhr corridor hosts formulation laboratories serving Aldi and Lidl supplier networks with bundled technical service agreements.
France
Premium pastry and traditional bread sectors demand clean-label lecithin systems with organic certification. The EU Green Deal's sustainable chemistry benchmarks redirect R&D investment toward enzymatic processing routes. The Paris basin and Northern France dairy clusters integrate plant-derived emulsifiers into AOC-protected cheese production lines.
Netherlands
Margarine and spreads manufacturers require precise crystallization control for tropical fat substitution. REACH compliance mandates geolocation verification for palm oil feedstocks entering Rotterdam port terminals. The Wageningen food valley anchors collaborative research between processors and oilseed cooperatives on domestic rapeseed lecithin extraction.
Italy
Confectionery formulators in the Emilia-Romagna cluster specify polyglycerol esters for clean-label chocolate coatings. CSRD-driven supply chain disclosure requirements elevate procurement scrutiny for Scope 3 carbon accounting. Parma and Modena host co-manufacturing partnerships targeting Mediterranean export markets with hybrid emulsifier-stabilizer blends.
Denmark
Scandinavian dairy alternative producers drive demand for oat and pea protein-compatible emulsifier systems. ECHA's REACH enforcement tightens mass balance certification requirements for imported vegetable oils. Copenhagen-based innovation centers develop microbial fermentation routes to circumvent palm oil dependency in premium positioning strategies.
Europe Food Emulsifiers Market Competitive Landscape
The competitive structure tilts toward integrated solution providers with bundled formulation capabilities. Three tiers emerge: multinational ingredient platforms with taste and nutrition integration, regional specialists in microbial fermentation, and application-focused innovators with dedicated technical centers. Dominant competitive moves include portfolio diversification into clean-label certification tiers and geographic expansion through distributor partnerships in emerging formulation hubs.
Among integrated nutrition platforms, Kerry Group plc and Ingredion Incorporated occupy positions emphasizing bundled texture and taste solutions. Corbion N.V. and Palsgaard A/S exemplify the specialist archetype with concentrated expertise in bio-based processing routes. BASF SE anchors the diversified chemical conglomerate tier, leveraging scale advantages across multiple food additive categories.
| Leading Market Players |
|---|
| Kerry Group plc |
| Corbion N.V. |
| BASF SE |
| Ingredion Incorporated |
| Palsgaard A/S |
| DuPont de Nemours, Inc. |
| Archer Daniels Midland Company |
| Puratos Group NV |
| Cargill, Incorporated |
| Others |
Supply & Pricing Matrix
Food chemists with simultaneous expertise in enzymatic catalysis and sensory science concentrate in the Rhine-Ruhr corridor and Wageningen food valley, creating labor-cost differentials that widen pricing-tier spreads between premium formulation services and commodity emulsifier supply.
Pricing Analysis
Cost-down pressure on standard-grade mono- and diglycerides accelerates because Aldi and Lidl procurement specifications compress supplier margins through multi-year framework agreements. Three-tier pricing structure across premium, standard, and economy levels separates organic-certified lecithin from mass-market glyceride esters from unbranded commodity blends. Price differentiation traces to certification grade and volume scale, with clean-label premiums widening as EFSA safety reviews elevate compliance costs. Small and mid-scale manufacturers exhibit highest price sensitivity, while integrated nutrition platforms absorb margin compression through bundled technical service offerings.
Supply Chain Analysis
Direct-to-industrial-bakery channels handle standardized glyceride volumes, while formulation-integrated distributors serve premium dairy and confectionery accounts. Feedstock supply concentrates in Malaysia, Indonesia, and Germany, with palm oil dominance creating single-source vulnerability under REACH geolocation verification mandates. Raw material dependencies rest on crude palm oil, rapeseed and sunflower phospholipids, and fermentation-derived microbial oils. Distribution runs through Rotterdam port terminals for imported vegetable oils, with Northern European oilseed cooperatives shortening domestic supply chains for dairy processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EFSA's additive re-evaluation timeline functions as a consolidation forcing function, eliminating formulation specialists lacking capital reserves for multi-year toxicological dossier preparation.
For Market Incumbents: Anchor market position through captive supply of enzymatic processing capacity in Denmark and the Netherlands, while accelerating backward integration into Northern European oilseed cooperatives to circumvent palm oil traceability risks. Kerry Group plc and Corbion N.V. demonstrate how bundled technical service platforms defend against commodity margin erosion from private-label procurement concentration. For New Entrants and Emerging Players: Enter via microbial fermentation-derived emulsifier niches where EFSA's pending safety opinions have frozen incumbent R&D pipelines, targeting Scandinavian oat and pea milk alternative formulators with hybrid emulsifier-stabilizer blends. Co-manufacturing partnerships in Parma and Modena offer the most penetrable entry point for Mediterranean export-focused positioning. For Investors and Strategic Acquirers: The window for entry favors regional specialists with established EFSA safety dossiers and demonstrated enzymatic scale-up capabilities. Watch for EFSA's final opinions on polyglycerol ester safety margins as the inflection signal determining which bio-based processing routes achieve regulatory clearance acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Supply | Domestic rapeseed and sunflower sourcing insulates processors from REACH palm oil traceability audits. |
| Enzymatic Processing Scale-Up | Continuous fermentation infrastructure secures non-GMO certification and EU Green Deal carbon benchmarks. |
| Co-Manufacturing Partnership | Parma and Modena clusters enable clean-label dairy emulsifier access to Mediterranean export channels. |
| EFSA Safety Dossier Investment | Established toxicological packages accelerate approval timelines as novel emulsifier submissions face multi-year freezes. |
| Hybrid Emulsifier-Stabilizer Development | Plant protein convergence in Scandinavian dairy alternatives captures formulation slots from single-function competitors. |
Research Methodology
Multi-period observation of EFSA opinion publication timelines, enzymatic processing capacity announcements, and private-label procurement specification changes anchored the trend analysis, supplemented by interviews with formulation R&D directors, bakery procurement managers, dairy processing engineers, and oilseed cooperative supply planners. Secondary validation drew from EFSA additive re-evaluation registers, REACH compliance disclosure databases, EU Green Deal sustainable chemistry benchmark publications, and customs trade data for vegetable oil feedstock flows. Bottom-up emulsifier volume modeling and top-down food manufacturing value-chain triangulation cross-verified segment-level estimates.
Input-output matrices mapped emulsifier demand across product chemistry, application processing intensity, feedstock origin, and end-user procurement concentration dimensions over the projection horizon. CAGRs derived from segmented growth rate calibration against EFSA regulatory timeline scenarios and bio-based substitution elasticity assumptions. Industry-specific forecast inputs incorporated enzymatic esterification technology diffusion curves and palm oil price volatility bands.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EFSA restriction scenarios or breakthrough microbial fermentation yield improvements. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Low-Sodium Salt Substitute Market
Food Additives and Ingredients
Vinasse Market
Food Additives and Ingredients
Antistaling Agent Market
Food Additives and Ingredients
Italy Food Additives Market
Food Additives and Ingredients
Ammonia Caramel Market
Food Additives and Ingredients
Nisin for Food Market
Food Additives and Ingredients
Japan Food Additives Market
Food Additives and Ingredients
Glandular Ingredients Market
Food Additives and Ingredients
Egg Wash Substitute Market
Food Additives and Ingredients
Australia Anti Caking Market
Food Additives and Ingredients
Amaranth (E123) Market
Food Additives and Ingredients
Beta Agonist Feed Additive Market
Food Additives and Ingredients
Global Cereal Ingredients Market
Food Additives and Ingredients
Africa Food Emulsifiers Market
Food Additives and Ingredients
Asia-Pacific Anti-Caking Market
Food Additives and Ingredients
Food Supplement Ingredients Market