
 Africa Food Emulsifiers Market | 2026-2036
Africa Food Emulsifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Food Emulsifiers Market Outlook
Modular emulsifier blends for clean-label reformulation is repositioning buyer choice across African food manufacturing. Cargill Incorporated leverages its regional oilseed processing footprint to supply lecithin derivatives at scale. Kerry Inc anchors its position through application-specific technical service bundled with ingredient supply. Palsgaard A/S competes on emulsifier stabilization systems tailored for tropical climate distribution challenges.
Food emulsifiers are surface-active agents that reduce interfacial tension between immiscible phases such as oil and water, typically comprising molecules with both hydrophilic and lipophilic moieties that stabilize dispersions through micelle formation and electrostatic repulsion. Their primary commercial purpose lies in extending shelf stability, controlling texture, and enabling fat reduction in processed foods without sensory degradation. Mono- and diglycerides dominate volume flows due to cost-efficient production from hydrogenated vegetable oils and broad regulatory acceptance across African jurisdictions. Lecithin commands premium positioning in natural-positioned product lines where non-GMO and allergen-free certifications justify higher ingredient spending. Polysorbates sustain growth in confectionery and frozen dessert segments where thermal stability requirements exceed the performance envelope of simpler glyceride systems.
FSSAI-aligned standards in Nigeria and South Africa's Department of Health food additive regulations shape product registration pathways and label claim permissibility for imported emulsifier systems. CODEX Alimentarius provisions referenced by multiple African national food safety agencies further harmonize maximum usage levels for polysorbates and sorbitan esters across cross-border trade corridors. Manufacturers must monitor evolving additive approval schedules and local testing requirements to avoid customs detention and reformulation costs.
Market Dynamics
Modular emulsifier blends designed for clean-label reformulation are repositioning procurement priorities across African food manufacturing, forcing suppliers to bundle technical service capabilities with base ingredient supply.
Growth Catalysts
- Processed Dairy Expansion:Industrial dairy clusters in Nigeria and South Africa are consolidating procurement volumes for mono- and diglyceride systems to standardize shelf stability across UHT milk and spreadable fat applications.
- South Africa's Updated Food Additive Regulations:The Department of Health's revised additive schedules are accelerating product registration for compliant emulsifier imports, reducing customs detention risk for lecithin derivative suppliers.
- Tropical Climate Distribution Requirements:Extended heat-humidity exposure during African supply chain transit is concentrating demand for polysorbate-based thermal stabilization systems in confectionery and frozen dessert segments.
Market Restraints
- Vegetable Oil Input Volatility:Hydrogenated vegetable oil feedstock costs for glyceride production fluctuate with palm and soybean commodity markets, compressing margin predictability for emulsifier blenders.
- Import Dependency Concentration:Technical-grade lecithin supply concentrates among regional oilseed processors with captive crushing capacity, limiting second-source options for natural-positioned product lines.
- CODEX Alignment Friction:Divergent national implementation timelines for CODEX Alimentarius maximum usage levels create label claim inconsistencies across Nigeria-South Africa trade corridors.
Strategic Opportunities
- East African Industrial Bakery Growth:Kenya and Ethiopia's expanding bread and biscuit manufacturing clusters present underpenetrated demand for cost-optimized distilled monoglyceride systems.
- FSSAI-Aligned Reformulation Services:Nigeria's adoption of FSSAI-equivalent standards creates white space for suppliers offering bundled regulatory navigation and clean-label emulsifier substitution.
- Enzymatic Esterification Convergence:Lipase-catalyzed production methods are converging with solvent-free processing to enable non-GMO certification pathways for premium lecithin positioning.
Industry Challenges
- Application-Specific Technical Talent Scarcity:Food manufacturers lack in-house formulation chemists capable of optimizing emulsifier ratios for tropical climate stability, forcing reliance on supplier technical service.
- Multi-Jurisdiction Registration Timelines:Separate approval pathways under South Africa's Department of Health and Nigeria's national food safety agencies extend product launch cycles for imported emulsifier systems.
- Legacy Equipment Compatibility:Existing African dairy and bakery processing lines require retrofitting to handle higher-viscosity modular emulsifier blends, elevating capital requirements for clean-label transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Food Emulsifiers Market |
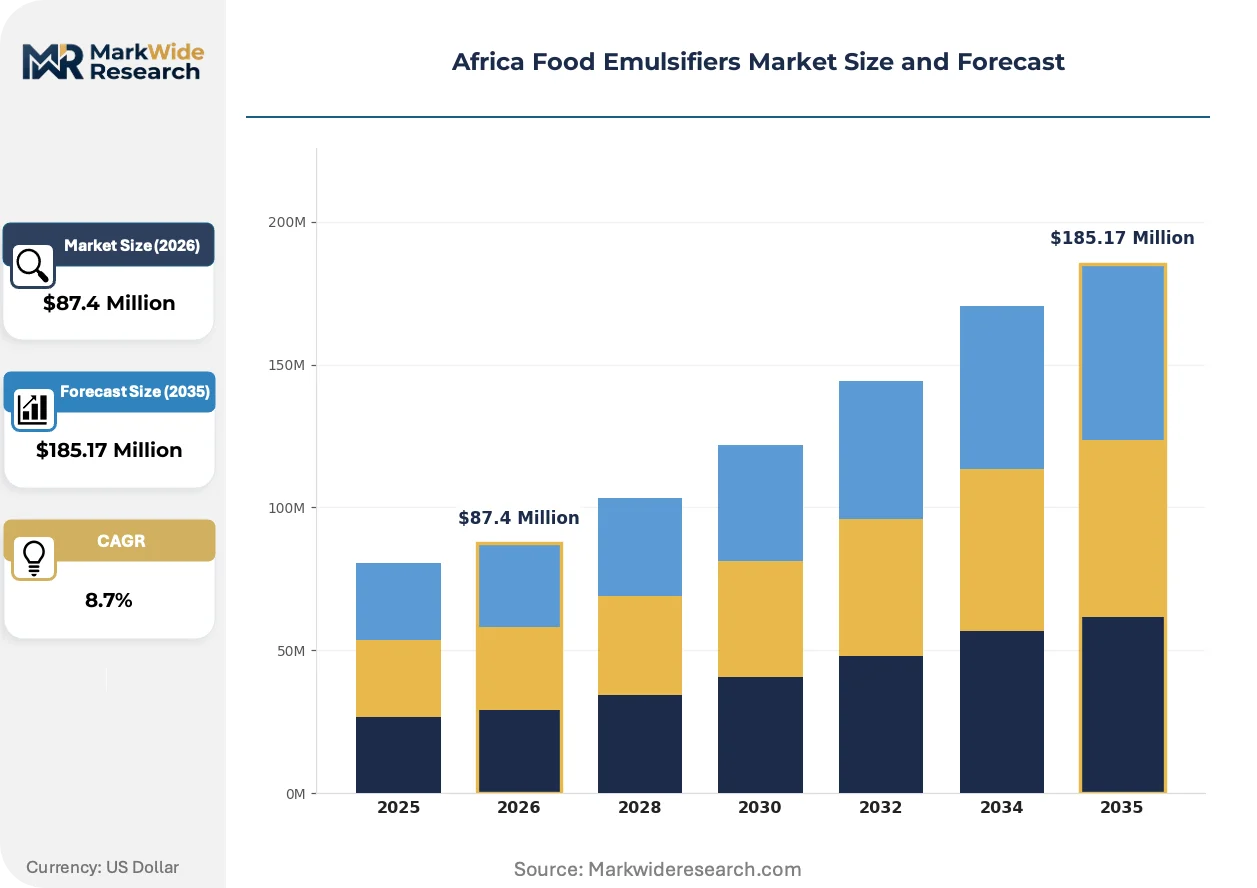
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $185.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lecithin, Mono- and Diglycerides, Polysorbates, Sorbitan Esters Application: Baked Goods, Dairy Products, Confectionery, Sauces End User: Food Manufacturers, Beverage Producers, Bakery Businesses, Catering Services Distribution Channel: Direct Sales, Online Retail, Wholesale, Specialty Stores |
| Companies Covered | Cargill Incorporated, DuPont de Nemours Inc, BASF SE, Corbion NV, Archer Daniels Midland Company, Kerry Inc, Tate & Lyle, Palsgaard A/S, Ingredion Incorporated, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Food Emulsifiers Market Strategic Shifts
Clean-label positioning and climate-adapted stabilization systems are reshaping emulsifier specification priorities across African food manufacturing, with procurement patterns increasingly favoring bundled technical service over commodity ingredient supply.
Enzymatic interesterification technology for producing mono- and diglycerides is converging with non-GMO certification requirements to enable premium positioning in natural-product lines. Industrial dairy processors in South Africa are adopting these systems at accelerated rates to meet retailer clean-label mandates. The technology is converging with solvent-free processing standards to compress cost differentials between conventional and certified-emulsifier supply tiers.
South Africa's Department of Health has tightened maximum usage level enforcement for polysorbates in frozen dessert applications, aligning inspection protocols with CODEX Alimentarius reference standards. This regulatory compression is forcing reformulation toward sorbitan ester alternatives in ice cream manufacturing. Nigerian confectionery producers are responding by accelerating technical trials of glycerol monostearate systems ahead of anticipated FSSAI-aligned adoption.
Buyer concentration among industrial bakery clusters is compressing switching cycles for emulsifier suppliers, with procurement teams demanding application-specific stabilization guarantees rather than commodity-grade ingredient supply. Technical service bundling is displacing price-only tendering in Nigeria's bread manufacturing sector. Kenya's emerging biscuit export industry exhibits the most visible demand for outcome-based supplier partnerships covering shelf-life validation.
Africa Food Emulsifiers Market Segmentation
Emulsifier specification choices in African food manufacturing hinge on climate stability requirements, clean-label positioning, and regulatory alignment across multiple national jurisdictions. Procurement teams segment supply by functional performance tier rather than commodity grade alone.
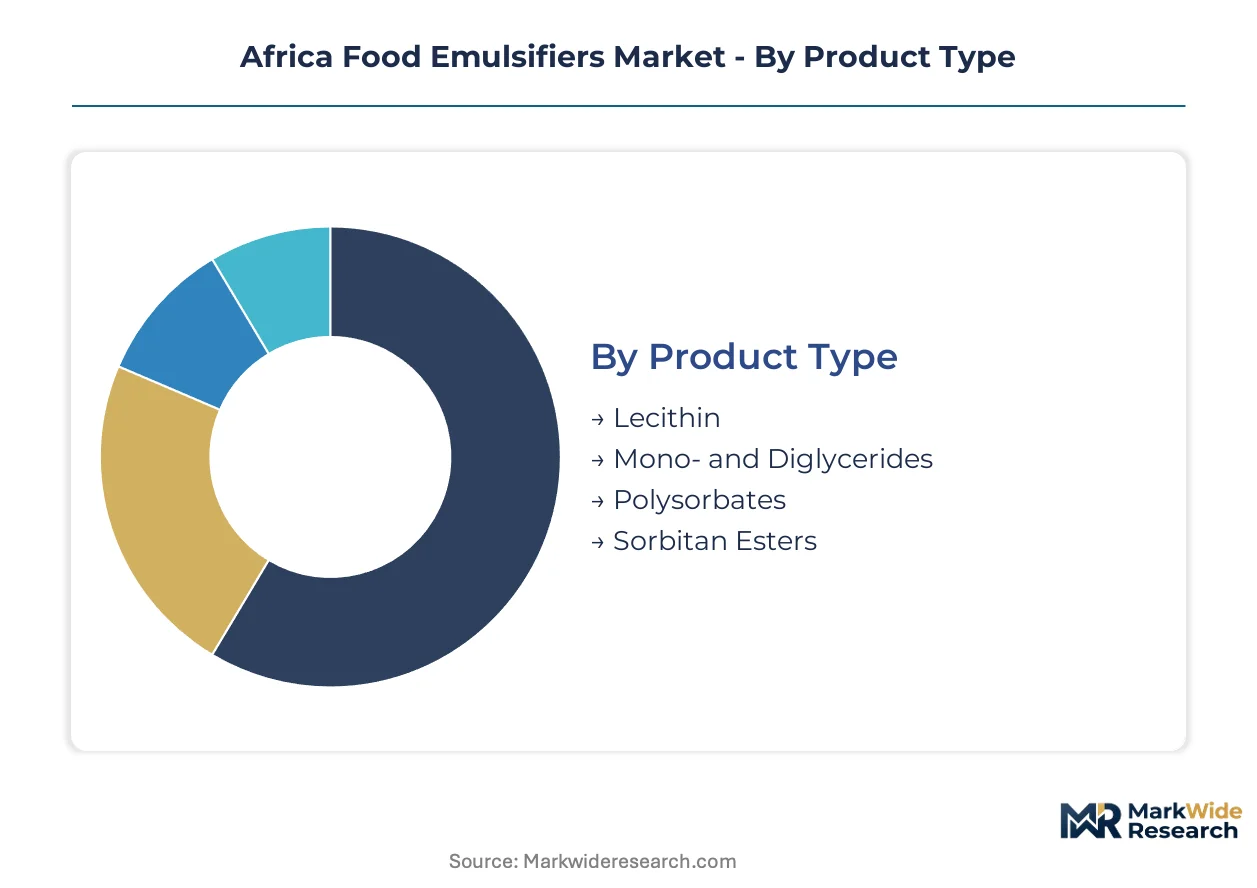
Product Type:
Molecular architecture determines thermal tolerance and label claim permissibility under CODEX-aligned national standards.
- Mono- and Diglycerides:Hydrogenated vegetable oil derivatives produced through glycerolysis dominate volume flows due to cost-efficient manufacturing and broad regulatory acceptance across South Africa and Nigeria. Industrial dairy clusters in these markets standardize procurement around distilled monoglyceride systems for UHT milk shelf stability.
- Lecithin:Phospholipid complexes extracted from soy or sunflower oil command premium positioning where non-GMO and allergen-free certifications justify higher ingredient spending. Kenyan biscuit exporters prioritize enzymatically processed lecithin for clean-label export compliance.
- Polysorbates:Ethoxylated sorbitan esters deliver superior thermal stability for confectionery and frozen dessert applications facing extended heat-humidity exposure during African distribution.
- Sorbitan Esters:Lipophilic surfactants function as polysorbate alternatives where South Africa's Department of Health has tightened maximum usage enforcement in frozen dessert categories.
Mature deployment sits with mono- and diglycerides. Newer deployment is concentrated in enzymatically processed lecithin systems.
Application:
End-use thermal stress profiles and shelf-life extension targets reshape emulsifier specification priorities.
- Dairy Products:UHT milk and spreadable fat applications in Nigerian and South African industrial clusters drive concentrated demand for distilled monoglyceride stabilization systems with standardized performance envelopes.
- Baked Goods:Bread and biscuit manufacturing across Kenya and Ethiopia requires cost-optimized emulsifier blends that maintain dough conditioning through variable ambient temperatures without refrigeration.
- Confectionery:Chocolate and candy producers prioritize polysorbate-based thermal stabilization to prevent fat bloom during uncontrolled temperature exposure in cross-border transit.
- Sauces:Mayonnaise and dressing applications utilize lecithin and modified diglyceride systems for emulsion stability under tropical storage conditions.
Volume concentration centers on dairy processing. Steepest expansion trajectory appears in biscuit export manufacturing.
End User:
Scale and technical capability determine whether buyers source commodity ingredients or bundled formulation services.
- Food Manufacturers:Large-scale processed food operations in South Africa's industrial corridors demand application-specific stabilization guarantees with shelf-life validation protocols.
- Bakery Businesses:Nigeria's bread manufacturing sector exhibits accelerating demand for outcome-based supplier partnerships covering technical service and ingredient supply.
- Beverage Producers:Juice and dairy drink formulators require emulsifier systems compatible with aseptic filling lines and extended ambient distribution.
- Catering Services:Institutional food service operators source smaller volumes through wholesale channels with less stringent performance specifications.
Procurement sophistication concentrates with food manufacturers. Emerging demand clusters appear among export-oriented bakery businesses.
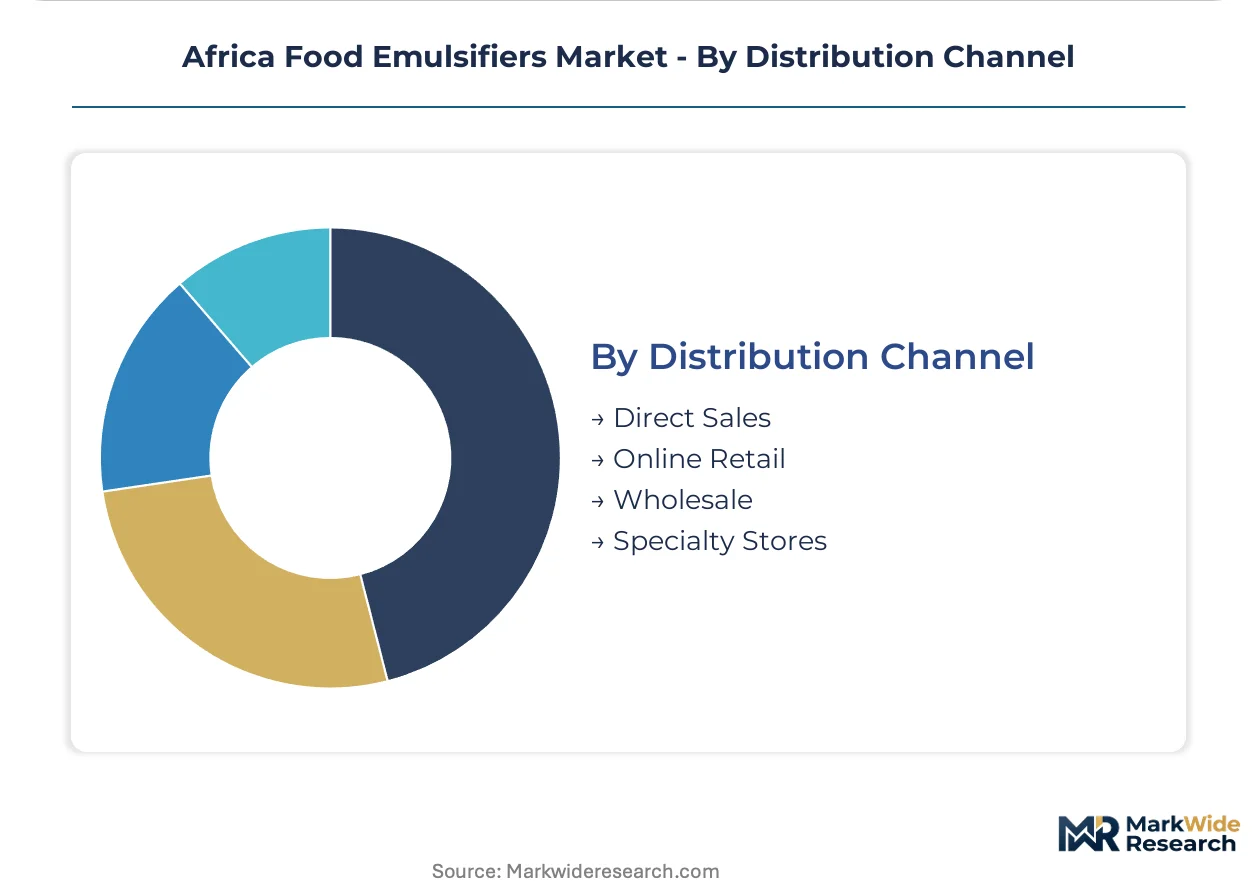
Distribution Channel:
Channel selection reflects order scale, technical service requirements, and regulatory documentation needs.
- Direct Sales:Major industrial dairy and bakery clusters negotiate direct supply agreements with regional oilseed processors for lecithin derivatives and emulsifier blenders for glyceride systems.
- Wholesale:Aggregated distribution serves mid-tier manufacturers across East African markets where order volumes do not justify direct supplier relationships.
- Online Retail:Digital procurement channels gain traction among smaller bakery businesses and catering services seeking rapid access to standard-grade emulsifier formulations.
- Specialty Stores:Ingredient distributors with technical consultation capabilities serve niche clean-label reformulation projects requiring non-GMO certification documentation.
Transaction value concentrates through direct sales. Channel experimentation is most visible among smaller bakery businesses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in South Africa and Nigeria while East African markets absorb rising import volumes. Consumption growth outpaces domestic manufacturing expansion across the continent.
South Africa
Industrial dairy clusters in Gauteng and KwaZulu-Natal drive concentrated demand for distilled monoglyceride stabilization systems. The Department of Health's revised food additive schedules accelerate product registration timelines for compliant emulsifier imports. Cape Town's expanding processed food corridor attracts technical service-intensive supplier partnerships.
Nigeria
Bread manufacturing clusters in Lagos and Kano exhibit accelerating procurement volumes for cost-optimized emulsifier blends. FSSAI-aligned national food safety standards reshape label claim permissibility for imported ingredient systems. The Aba industrial zone's biscuit export manufacturers prioritize bundled reformulation services.
Kenya
Nairobi's emerging biscuit export industry generates underpenetrated demand for enzymatically processed lecithin with clean-label certification. Kenya Bureau of Standards implementation of CODEX-aligned maximum usage levels harmonizes cross-border trade documentation. Mombasa's logistics hub facilitates regional distribution of thermal-stabilization systems.
Ethiopia
Addis Ababa's industrial bakery expansion creates procurement opportunities for distilled monoglyceride systems compatible with variable ambient temperatures. The Ethiopian Food and Drug Authority's evolving additive approval schedules require active monitoring by import-dependent manufacturers. Hawassa's agro-industrial park attracts regional oilseed processors seeking captive lecithin supply.
Egypt
Alexandria's confectionery producers prioritize polysorbate-based stabilization for cross-border distribution through heat-exposed transit corridors. The Egyptian Organization for Standardization and Quality references CODEX Alimentarius provisions for emulsifier maximum usage enforcement. Cairo's processed dairy sector consolidates procurement around standardized shelf-life validation protocols.
Africa Food Emulsifiers Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the African emulsifier supply base. Regional oilseed processors leverage captive crushing capacity to anchor lecithin derivative supply. Three strategic archetypes dominate: integrated agribusiness operators with backward feedstock control, application-technical service bundlers, and climate-specialized stabilization system developers. Competitive intensity centers on M&A-driven portfolio expansion and direct distribution network buildout in industrial dairy corridors.
Among diversified agribusiness operators, Cargill Incorporated and Archer Daniels Midland Company represent integrated supply archetypes with regional oilseed processing footprints. Kerry Inc and Palsgaard A/S occupy positions emphasizing application-specific technical service and climate-adapted stabilization systems respectively. BASF SE and Corbion NV exemplify specialty chemical positioning focused on enzymatic processing certification pathways. DuPont de Nemours Inc, Tate & Lyle, and Ingredion Incorporated sit within the ingredient innovation tier targeting clean-label reformulation demand.
| Leading Market Players |
|---|
| Cargill Incorporated |
| DuPont de Nemours Inc |
| BASF SE |
| Corbion NV |
| Archer Daniels Midland Company |
| Kerry Inc |
| Tate & Lyle |
| Palsgaard A/S |
| Ingredion Incorporated |
| Others |
Value Chain & Pricing Dynamics
Hydrogenated vegetable oil feedstock costs cascade through African emulsifier pricing tiers, with palm and soybean commodity volatility compressing margin predictability for glyceride blenders while enzymatically processed lecithin commands premium positioning through non-GMO certification pathways.
Pricing Analysis
Cost-down pressure on standard-grade mono- and diglyceride systems accelerates because Nigerian bread manufacturers consolidate procurement volumes around price-only tendering. Three-tier pricing structure across premium enzymatic lecithin, standard distilled monoglycerides, and economy-grade polysorbates reflects certification grade and volume scale differentiation. Margin tightening in the standard tier traces to vegetable oil input volatility. Small-scale catering services exhibit highest price sensitivity; South African industrial dairy clusters demonstrate lowest sensitivity due to shelf-life validation requirements.
Supply Chain Analysis
Non-GMO and allergen-free certification gates access to premium lecithin positioning in Kenyan biscuit export channels. Supply concentrates in South Africa's oilseed processing corridors, Nigeria's industrial bakery clusters, and Kenya's emerging export manufacturing. Raw material dependencies rest on palm oil from Southeast Asian sources, soybean crushing capacity in regional agro-industrial parks, and ethoxylated sorbitan precursors. Single-source vulnerability concentrates in technical-grade lecithin among captive crushing operators. Distribution runs through direct sales agreements for major industrial clusters and wholesale aggregation for mid-tier East African manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic esterification technology is displacing solvent-based glyceride production across African food manufacturing, forcing suppliers to reposition around clean-label certification capabilities or cede premium positioning.
For Market Incumbents: Cement backward integration into regional oilseed crushing to secure captive lecithin supply against import dependency concentration. Expand technical service teams in Lagos and Johannesburg to defend against modular blend suppliers bundling formulation support. The threat of FSSAI-aligned regulatory compression in Nigeria demands pre-emptive reformulation partnerships. For New Entrants and Emerging Players: Digital procurement platforms targeting smaller Nigerian bakery businesses offer rapid market access without direct sales infrastructure investments. East African biscuit export manufacturing presents the most penetrable white space, with Kenya Bureau of Standards alignment creating documentation advantages. A regulatory navigation service bundled with standard-grade emulsifier supply provides differentiated go-to-market positioning. For Investors and Strategic Acquirers: Distressed-cycle entries favor application-technical service bundlers with established South African dairy relationships during margin compression phases. Long-term viability centers on clean-label transition exposure across the analysis window. Acquisition targets should demonstrate enzymatic processing capabilities or tropical climate stabilization expertise. The signal to watch is Kenya's CODEX implementation timeline accelerating cross-border trade harmonization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Crushing | Captive lecithin supply secures margin control against import dependency concentration in South Africa. |
| Technical Service Team Expansion | Application-specific formulation support displaces price-only tendering in Nigerian bread manufacturing. |
| Enzymatic Processing Certification | Non-GMO pathway enables premium positioning in Kenyan biscuit export compliance requirements. |
| Regulatory Navigation Service Launch | FSSAI-aligned reformulation bundling captures white space in Nigeria's evolving additive approval environment. |
| Tropical Climate Stabilization R&D | Polysorbate alternative development addresses South Africa's tightened frozen dessert enforcement. |
Study Parameters
Multi-period observation of emulsifier procurement volumes, regulatory approval timelines, and industrial cluster expansion anchored the trend analysis, supplemented by interviews with food manufacturing procurement directors, regulatory affairs specialists at national food safety agencies, technical service managers at ingredient suppliers, and plant engineers at dairy processing facilities. Secondary validation drew from CODEX Alimentarius provisions, South Africa Department of Health additive schedules, Nigeria's national food safety agency filings, and Kenya Bureau of Standards documentation. Bottom-up segment sizing triangulated against top-down industry value estimates.
Segment-weighting across product type, application, end user, and distribution channel dimensions structured the analytical framework over the projection horizon. CAGRs were derived from trend extrapolation of procurement volume patterns and regulatory alignment trajectories. Industry-specific forecast inputs included enzymatic processing adoption rates in South African dairy and FSSAI implementation pace in Nigerian confectionery.
Inputs from national food safety agency officials and industrial procurement directors were available through the study window; gaps in real-time customs detention data for non-compliant emulsifier shipments introduce uncertainty bands around import volume estimates. Forecasts reflect documented assumptions regarding regulatory alignment timelines and clean-label certification adoption curves. Vegetable oil commodity volatility and divergent CODEX implementation schedules represent specific revision risks. A model refresh is warranted upon material change in Kenya's export biscuit manufacturing expansion trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Food Grade Sodium Citrate Market
Food Additives and Ingredients
Africa Food Acidulants Market
Food Additives and Ingredients
France Anti Caking Market
Food Additives and Ingredients
Spain Food Colorants Market
Food Additives and Ingredients
Japan Food Preservatives Market
Food Additives and Ingredients
Monosodium Glutamate Market
Food Additives and Ingredients
Food Grade Calcium Lactate Market
Food Additives and Ingredients
Mexico Anti Caking Market
Food Additives and Ingredients
South Africa Food Enzymes Market
Food Additives and Ingredients
Europe Feed Anti-Caking Agents Market
Food Additives and Ingredients
Emulsifiers Market
Food Additives and Ingredients
Brazil Feed Additives Market
Food Additives and Ingredients
Natural Solubilizers Market
Food Additives and Ingredients
Tara Gum Market
Food Additives and Ingredients
Clean Labelled Food Additives Market
Food Additives and Ingredients
Food Grade Calcium Phosphate Market