
 Brazil Food Enzymes Market | 2026-2036
Brazil Food Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Food Enzymes Market Outlook
Direct sales channels for industrial enzyme procurement is fragmenting as Brazilian food manufacturers diversify supplier relationships beyond traditional importers. Novozymes AS leverages its fermentation technology leadership to anchor premium protease supply to dairy processors in Minas Gerais. BASF SE competes through backward integration into specialty enzyme production, sustaining cost advantages for mid-tier baking applications. DuPont de Nemours Inc. navigates regulatory complexity by positioning its amylase portfolios for ANVISA-compliant clean-label formulations.
Food enzymes comprise protein-based biocatalysts, typically operating at temperatures between 30°C and 60°C and pH ranges of 4.0 to 8.0, that accelerate specific biochemical reactions in food matrices without becoming consumed in the process. These catalysts derive from microbial fermentation, plant extraction, or recombinant DNA technology, and serve primarily to modify texture, extend shelf life, or enhance nutritional profiles in processed foods. Proteases command substantial margin pools in dairy processing applications where cheese yield optimization drives purchasing decisions. Amylases experience accelerated uptake in baking as Brazilian millers seek enzyme blends that reduce chemical additive dependency. Lipases retain niche but high-value positioning in specialty fat modification for confectionery manufacturers.
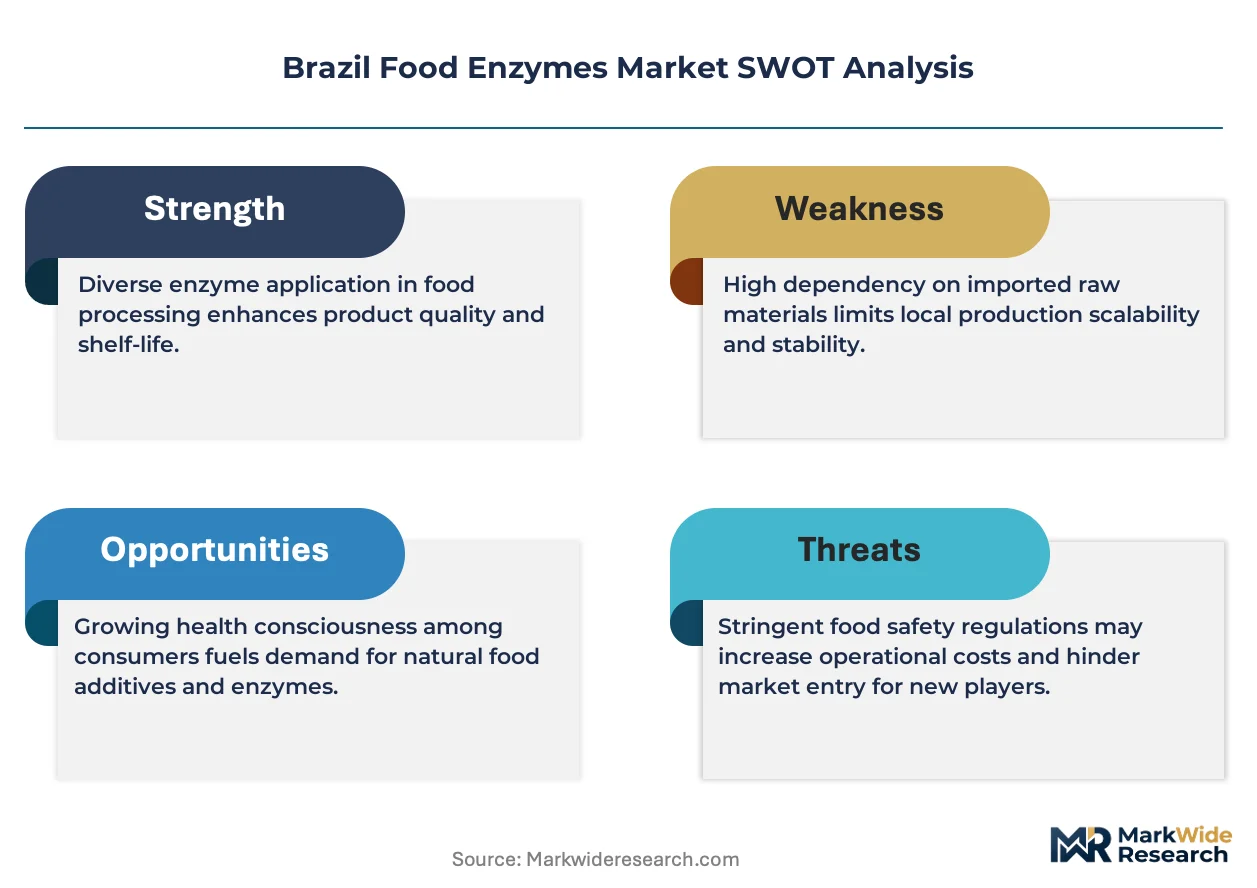
ANVISA governs enzyme safety assessments and maximum usage levels under Brazil's food additive framework, while the national biotechnology regulator oversees genetically modified microorganism approvals for recombinant enzyme production. The PLI scheme's biotechnology incentives reduce import dependency by subsidizing domestic fermentation capacity expansion. Stakeholders must monitor how ANVISA's evolving enzyme classification protocols intersect with state-level environmental licensing for new production facilities. Decisive capital allocation toward locally validated enzyme strains will separate market participants as regulatory timelines compress.
Market Dynamics
ANVISA's evolving enzyme classification protocols and the PLI scheme's biotechnology incentives are compressing regulatory timelines while forcing domestic fermentation capacity decisions. São Paulo and Minas Gerais bakery clusters now drive protease and amylase specification changes that ripple through supplier qualification processes.
Growth Catalysts
- Clean-label bakery demand:São Paulo industrial bakers specify enzyme blends that eliminate chemical additives from bread formulations. This specification pull forces supplier reformulation cycles.
- PLI biotechnology subsidies:Domestic fermentation capacity expansion reduces import dependency for dairy processors in Minas Gerais. Capital allocation now favors locally validated enzyme strains.
- Cheese yield optimization:Protease margin pools expand as Brazilian dairy cooperatives prioritize enzyme performance over unit cost in purchasing decisions.
Market Restraints
- Recombinant strain approval delays:Brazil's national biotechnology regulator extends genetically modified microorganism timelines, trapping imported enzyme volumes in port clearance bottlenecks.
- Specialty lipase supply concentration:High-value confectionery fat modification enzymes concentrate among three fermentation technology leaders, constraining price negotiation leverage for mid-tier buyers.
- State-level environmental licensing:New production facilities face overlapping municipal and state permits that extend facility commissioning by 18-24 months versus benchmark jurisdictions.
Strategic Opportunities
- Amazon-region feedstock access:Northern Brazil's agricultural expansion creates localized substrate supply for cellulase and hemicellulase production targeting biofuel adjunct markets.
- Direct procurement platform emergence:Industrial food manufacturers in the Southeast corridor bypass traditional importers through digital enzyme specification tools that compress supplier discovery cycles.
- ANVISA fast-track pathways:Pre-submission consultation protocols for GRAS-equivalent enzyme dossiers reduce regulatory uncertainty for first-mover domestic producers.
Industry Challenges
- Fermentation scale-up talent scarcity:Brazil's biotechnology programs produce insufficient downstream processing engineers to staff multiple simultaneous PLI-funded facility expansions.
- Legacy ERP integration complexity:Food manufacturers' existing inventory systems struggle to track lot-specific enzyme activity units, forcing manual reconciliation workflows that delay production scheduling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Food Enzymes Market |
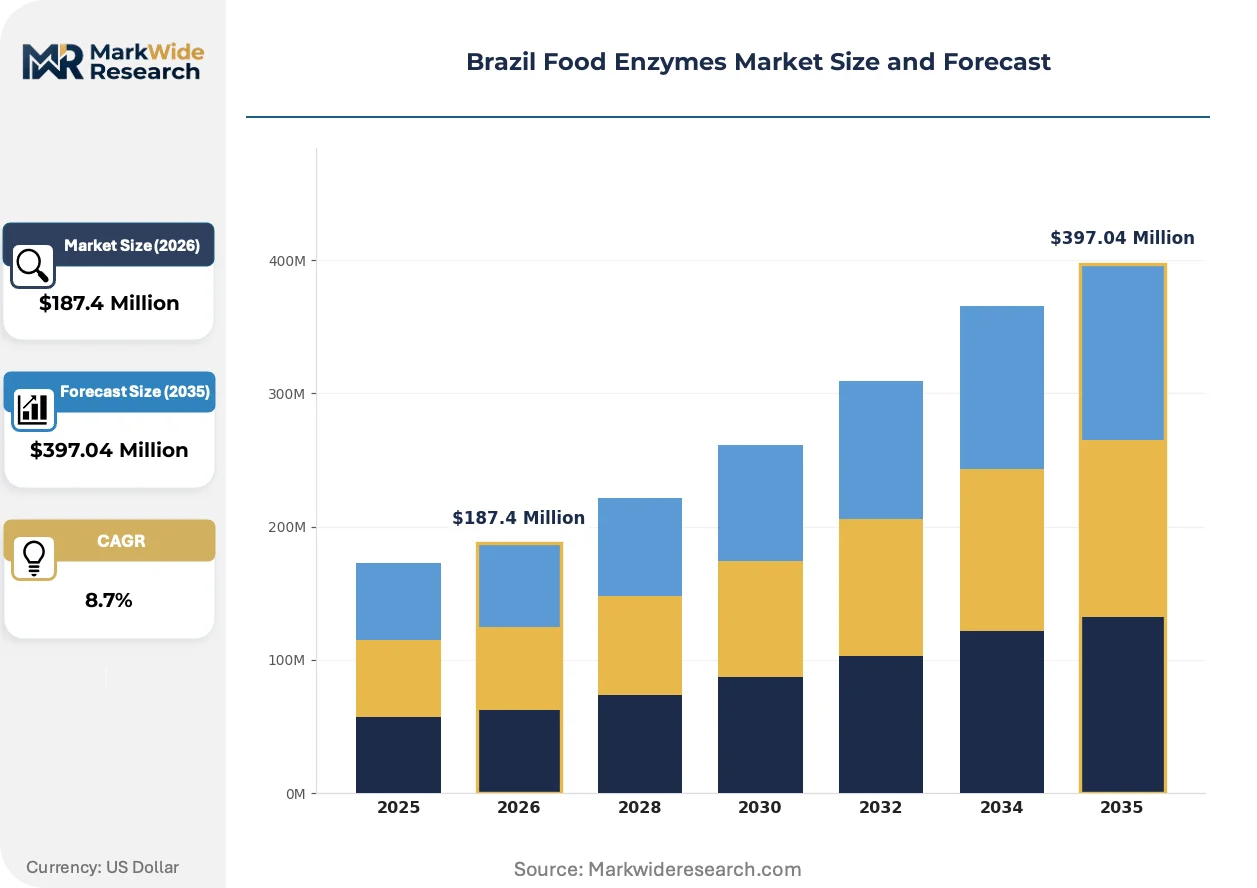
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Proteases, Amylases, Lipases, Cellulases Application: Baking, Dairy Processing, Beverages, Meat Processing End User: Food Manufacturers, Beverage Companies, Retailers, Food Service Providers Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors |
| Companies Covered | Chr. Hansen Holding AS, BASF SE, DuPont de Nemours Inc., Advanced Enzymes, Biogenoci Co Ltd, Novozymes AS, ABF Ingredients, International Flavors & Fragrances Inc., Koninklijke DSM NV, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Food Enzymes Market Strategic Shifts
Enzyme engineering and regulatory data science are compressing traditional development cycles while reshaping how Brazilian food manufacturers qualify and procure biocatalysts. Three forces now dominate supplier strategy.
Protein engineering platforms using machine-guided directed evolution are collapsing the traditional 24-month strain development timeline into 8-12 month cycles. Minas Gerais dairy processors now demand customized protease variants with pH activity profiles matched to specific cheese vat configurations. This compression forces fermentation technology providers to restructure R&D service contracts around milestone-based deliverables rather than royalty structures.
ANVISA's 2023 food additive framework revision introduces enzyme-specific maximum usage levels tied to dietary exposure assessments rather than technological necessity. Industrial bakery applications face the tightest constraints, with amylase formulations now requiring submission of processing condition data that links enzyme inactivation to final product residual activity. São Paulo millers respond by consolidating supplier relationships around dossier-complete enzyme portfolios that preempt regulatory questioning.
Specification-driven purchasing now dominates enzyme procurement for Brazil's top-20 food manufacturers, displacing the traditional spot-market buying that characterized the 2015-2020 period. Technical service teams from enzyme suppliers embed directly into customer formulation labs, converting transactional supply relationships into co-development partnerships. This shift concentrates procurement influence among food manufacturers with dedicated biotechnology liaison functions, most visible in the Southeast industrial corridor's consolidated bakery and dairy processing clusters.
Brazil Food Enzymes Market Segmentation
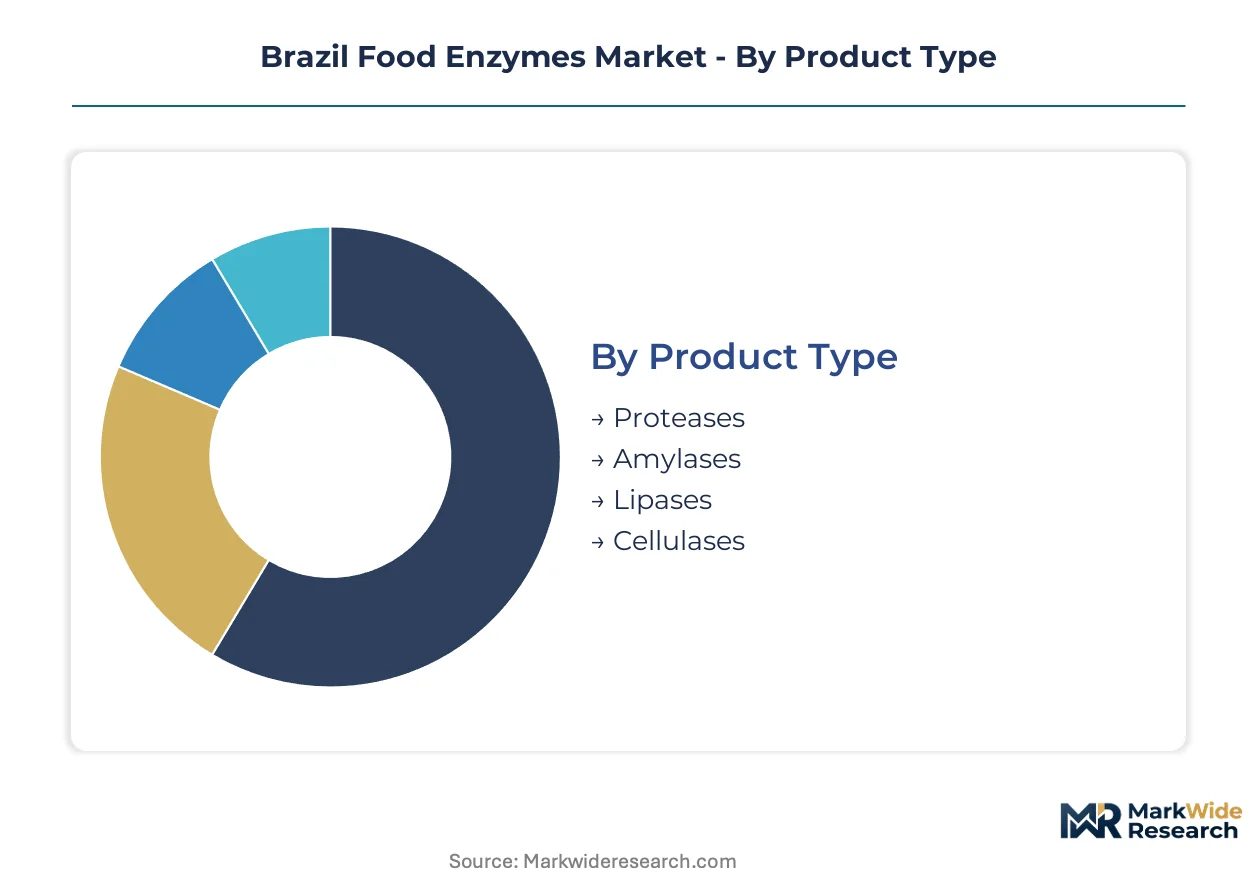
Enzyme procurement cycles vary dramatically across product categories and end-use applications in Brazil's food processing sector. Specification complexity, regulatory validation requirements, and formulation integration timelines create distinct velocity profiles that reshape supplier relationship structures.
Product Type:
Reformulation cycles compress fastest for commodity biocatalysts while specialty enzymes lock in multi-year supply agreements. Proteases and amylases turn over quarterly as bakery and dairy processors optimize for shifting input costs, whereas lipases and cellulases cycle annually due to strain validation overhead.
- Proteases:These protein-cleaving biocatalysts operate optimally at pH 4.0-8.0 and temperatures of 30-60°C, with microbial-derived variants dominating commercial supply. São Paulo industrial bakers specify protease blends that reduce chemical additive dependency in clean-label bread formulations, compressing supplier qualification timelines to under 90 days.
- Amylases:Starch-hydrolyzing enzymes catalyze dextrinization and saccharification in dough conditioning applications. Minas Gerais dairy cooperatives prioritize amylase performance for cheese yield optimization over unit cost in purchasing decisions, expanding margin pools for fermentation technology providers.
- Lipases:Ester-hydrolyzing enzymes enable specialty fat modification for confectionery manufacturers in Brazil's Southeast corridor.
- Cellulases:Cell wall-degrading biocatalysts target emerging biofuel adjunct applications leveraging Amazon-region agricultural feedstock expansion.
Proteases anchor the volume base while cellulases gain share at the steepest rate.
Application:
Margin structures diverge sharply across processing categories, with dairy and baking commanding premium pricing for validated enzyme portfolios while beverage and meat applications compete on throughput efficiency.
- Baking:Enzyme blends modify dough rheology, extend shelf life, and enable clean-label positioning without chemical preservatives. ANVISA's 2023 framework revision tightens amylase maximum usage levels for industrial bakery applications, forcing São Paulo millers to consolidate supplier relationships around dossier-complete portfolios.
- Dairy Processing:Protease-driven cheese yield optimization dominates purchasing criteria for Minas Gerais cooperatives, with technical service teams embedding directly into customer formulation labs.
- Beverages:Enzymatic clarification and filtration acceleration targets juice and brewing applications in Brazil's Southeast industrial corridor.
- Meat Processing:Tenderization and flavor development applications concentrate among large-scale food manufacturers with dedicated biotechnology liaison functions.
Baking commands the largest procurement volumes while dairy processing delivers the highest margin realization per activity unit.
End User:
Procurement sophistication stratifies sharply, with integrated food manufacturers driving specification complexity while food service operators prioritize spot-market flexibility.
- Food Manufacturers:Large-scale processors in São Paulo and Minas Gerais dominate enzyme volume absorption, with consolidated bakery and dairy clusters converting transactional supply relationships into co-development partnerships through embedded technical service teams.
- Beverage Companies:Juice and brewing processors specify enzyme blends for clarification and filtration acceleration, with ANVISA compliance requirements compressing supplier discovery cycles.
- Retailers:Private-label food producers leverage digital enzyme specification tools to bypass traditional importers.
- Food Service Providers:Commercial kitchen and catering operators prioritize spot procurement for limited enzymatic preparation applications.
Food manufacturers absorb the dominant share of industrial enzyme volumes while beverage companies expand specification requirements most aggressively.
Distribution Channel:
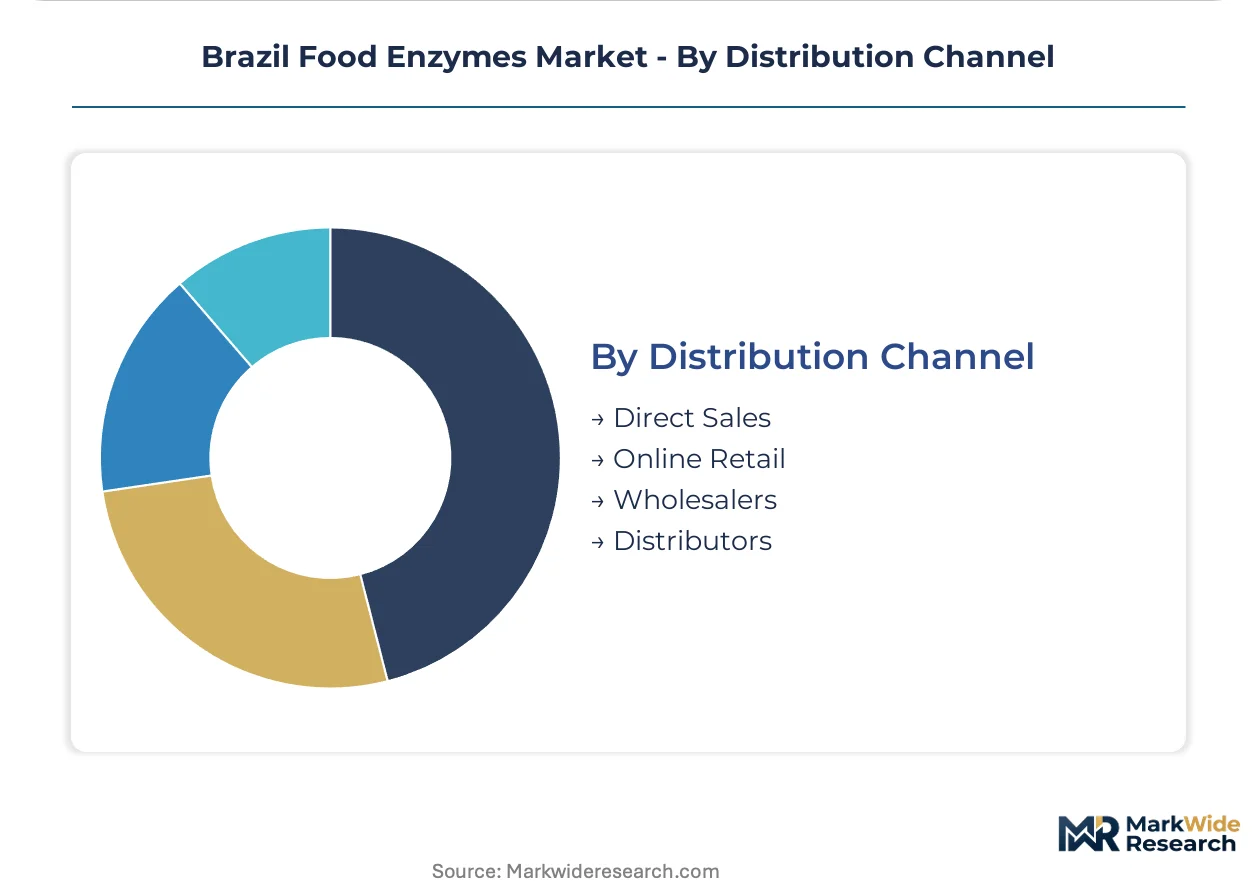
Channel economics reflect inventory carrying cost tolerance and technical service intensity, with direct sales capturing high-specification accounts and distributors serving fragmented mid-tier demand.
- Direct Sales:Fermentation technology leaders anchor premium protease and amylase supply through technical service contracts with Brazil's top-20 food manufacturers, displacing traditional spot-market buying that characterized the 2015-2020 period.
- Online Retail:Digital procurement platforms enable industrial food manufacturers in the Southeast corridor to compress supplier discovery cycles and bypass traditional importers.
- Wholesalers:Bulk enzyme intermediaries serve mid-tier baking applications with standardized activity unit specifications.
- Distributors:Regional logistics networks extend reach to smaller dairy processors and meat packers outside consolidated industrial clusters.
Direct sales channels capture the highest-value accounts while online retail expands most rapidly among digitally mature procurement functions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Santos anchors Brazil's food enzyme logistics, handling concentrated imports of fermentation-derived biocatalysts for Southeast industrial processors while PLI-subsidized domestic capacity expands through Minas Gerais biotechnology corridors.
São Paulo
Industrial bakers in São Paulo's ABC manufacturing belt specify protease-amylase blends for clean-label bread formulations. ANVISA's 2023 additive framework revision tightens maximum usage levels, forcing millers to consolidate supplier relationships around dossier-complete portfolios. The São Paulo metropolitan corridor concentrates procurement influence among food manufacturers with dedicated biotechnology liaison functions.
Minas Gerais
Dairy cooperatives in Minas Gerais prioritize protease performance for cheese yield optimization over unit cost in purchasing decisions. The PLI scheme's biotechnology incentives subsidize domestic fermentation capacity expansion, reducing import dependency for recombinant enzyme strains. Technical service teams from fermentation technology providers embed directly into customer formulation labs across the state's dairy processing clusters.
Rio Grande do Sul
Meat processing facilities in Rio Grande do Sul specify enzymatic tenderization systems for export-oriented beef operations. State-level environmental licensing protocols extend facility commissioning timelines for new production assets. The state's southern industrial corridor attracts mid-tier enzyme distributors serving fragmented meat packers outside consolidated Southeast clusters.
Paraná
Grain processors in Paraná's agricultural heartland drive cellulase demand for biofuel adjunct applications leveraging localized feedstock supply. ANVISA's evolving enzyme classification protocols intersect with municipal permitting requirements for new fermentation facilities. The Curitiba metropolitan area anchors logistics coordination for enzyme shipments to southern Brazil's expanding food manufacturing base.
Bahia
Juice processors in Bahia's citrus belt specify enzyme blends for clarification and filtration acceleration in beverage applications. The national biotechnology regulator's genetically modified microorganism approval timelines trap imported enzyme volumes in port clearance bottlenecks. Salvador's industrial district hosts emerging distribution networks extending reach to Northeast food manufacturers.
Brazil Food Enzymes Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream, supplying validated strain libraries and fermentation infrastructure to regional formulators. The Brazil food enzyme market structures around three tiers: global fermentation technology leaders anchoring premium supply contracts, mid-scale regional producers capturing PLI-subsidized capacity expansions, and specialized distributors serving fragmented end-users outside industrial corridors. Consolidation pressures intensify as specification-driven purchasing displaces spot-market procurement. Dominant competitive moves include backward integration into captive strain development and geographic co-location with Southeast dairy and baking clusters.
Within the global fermentation technology tier, Novozymes AS and BASF SE exemplify platform-scale supply architecture, while DuPont de Nemours Inc. occupies a position emphasizing regulatory-compliant formulation portfolios. These Denmark-based and Germany-based entities anchor premium protease and amylase supply through technical service contracts with Brazil's top-20 food manufacturers, representing the archetype of fermentation technology leadership that dominates high-specification accounts in the Southeast industrial corridor.
| Leading Market Players |
|---|
| Chr. Hansen Holding AS |
| BASF SE |
| DuPont de Nemours Inc. |
| Advanced Enzymes |
| Biogenoci Co Ltd |
| Novozymes AS |
| ABF Ingredients |
| International Flavors & Fragrances Inc. |
| Koninklijke DSM NV |
| Others |
Value Chain & Pricing Dynamics
Denmark-based fermentation technology leaders anchor global protease and amylase supply, concentrating margin capture in Brazil's Southeast dairy and baking clusters where specification complexity commands premium pricing. This upstream concentration funnels pricing power toward validated strain portfolios while compressing margins for undifferentiated commodity enzyme intermediaries.
Pricing Analysis
Volume-discount tiering structures dominate enzyme procurement, with three-tier pricing separating dossier-complete premium strains from standard activity-unit formulations and economy-grade bulk intermediates. Price differentiation hinges on ANVISA validation status and embedded technical service intensity. Pricing pressure stems from PLI-subsidized domestic capacity expansion eroding import premiums. Mid-tier baking applications exhibit highest price sensitivity, while Minas Gerais dairy cooperatives prioritize performance over unit cost.
Supply Chain Analysis
Tariff exposure between Denmark and Brazil concentrates supply chain risk for recombinant enzyme strains awaiting ANVISA clearance at Port of Santos. Fermentation capacity concentrates in Denmark, Germany, and the Netherlands, drawing from corn-derived substrate feedstocks and specialized bioreactor components. Single-source vulnerability runs through genetically modified microorganism approval bottlenecks. Distribution runs through direct technical service contracts with top-20 food manufacturers, displacing traditional importer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's food enzyme market is recovering from regulatory approval delays as ANVISA fast-track protocols compress dossier evaluation cycles. This cyclical recovery is anchored to PLI biotechnology incentive disbursement timelines accelerating domestic fermentation capacity commissioning.
For Market Incumbents: Harden regulatory dossier completeness to preempt ANVISA questioning on maximum usage level submissions. Deepen backward integration into captive strain development to offset recombinant approval delay risks. Anchor technical service teams permanently within São Paulo and Minas Gerais formulation labs to convert transactional supply into co-development partnerships.
For New Entrants and Emerging Players: Establish a beachhead in Amazon-region cellulase production leveraging localized agricultural feedstock access for biofuel adjunct markets. Target mid-tier meat processors in Rio Grande do Sul with enzymatic tenderization systems bypassing Southeast corridor concentration. Deploy digital enzyme specification platforms to compress supplier discovery cycles for digitally mature procurement functions.
For Investors and Strategic Acquirers: Capital is best deployed toward domestic fermentation specialists with validated GRAS-equivalent enzyme portfolios and state-level environmental licenses in progress. Long-term viability centers on PLI subsidy capture and ANVISA pre-submission consultation track records. Monitor genetically modified microorganism approval velocity as the inflection indicator for import substitution momentum.
| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Fermentation Capacity Expansion | PLI-subsidized facilities in Minas Gerais reduce import dependency for dairy processors. |
| Regulatory Dossier Pre-Submission Consultation | ANVISA fast-track pathways compress approval timelines for first-mover domestic producers. |
| Technical Service Team Embedding | Supplier personnel stationed in customer labs convert transactions into co-development partnerships. |
| Backward Integration into Strain Development | In-house recombinant microorganism libraries reduce port clearance bottleneck exposure. |
| Digital Procurement Platform Deployment | Specification tools enable Southeast manufacturers to bypass traditional enzyme importers. |
Study Parameters
Desk research of ANVISA regulatory filings, PLI scheme disbursement records, and customs import data preceded structured interviews with fermentation technology R&D directors, dairy cooperative procurement leads, industrial bakery formulation managers, and biotechnology facility commissioning engineers. Primary fieldwork combined with secondary validation from SEC filings of global enzyme suppliers, Brazilian biotechnology program graduate placement data, and state-level environmental licensing databases. Bottom-up enzyme activity unit demand modeling triangulated against top-down food processing sector value-chain analysis.
Assumptions around ANVISA regulatory timeline compression and PLI subsidy disbursement velocity were held fixed across scenarios, while domestic capacity commissioning rates and recombinant strain approval velocities were varied. Segmentation dimensions modeled include enzyme product type, application category, end-user procurement sophistication, and distribution channel structure. CAGRs derived from logarithmic interpolation of annual value estimates across the projection horizon, incorporating cheese yield optimization performance metrics and clean-label formulation substitution elasticities specific to Brazilian bakery and dairy processing.
Sensitivities concentrate around genetically modified microorganism approval delays, state-level environmental licensing timeline extensions, and PLI incentive disbursement schedule shifts. Forecasts reflect documented assumptions on regulatory pathway efficiency and domestic fermentation talent pipeline development. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Vinasse Market
Food Additives and Ingredients
Asia-Pacific Malt Ingredient Market
Food Additives and Ingredients
Granulated Tapioca Market
Food Additives and Ingredients
Food Stabilizer Systems Market
Food Additives and Ingredients
Australia Food Emulsifiers Market
Food Additives and Ingredients
Carrageenan Gum Market
Food Additives and Ingredients
Japan Food Acidulants Market
Food Additives and Ingredients
Food Fungal Enzyme Market
Food Additives and Ingredients
South Africa Food Enzymes Market
Food Additives and Ingredients
Pet Food Emulsifier Market
Food Additives and Ingredients
Cream Emulsifier Market
Food Additives and Ingredients
South America Brewing Enzymes Market
Food Additives and Ingredients
Annatto Food Colors Market
Food Additives and Ingredients
Food Grade Dipotassium Phosphate Market
Food Additives and Ingredients
Phosphated Distarch Phosphate Market
Food Additives and Ingredients
United Kingdom Food Preservatives Market