
 Asia-Pacific Fermented Ingredient Market | 2026-2036
Asia-Pacific Fermented Ingredient Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Fermented Ingredient Market Outlook
Microbial strain engineering talent is rotating toward industrial biotechnology hubs in China and Japan, tightening the specialist labor pool available to smaller fermenters across Southeast Asia. Ajinomoto Co., Inc. leverages its integrated fermentation complexes in Thailand and Indonesia to anchor regional amino acid supply. Angel Yeast Co., Ltd. dominates yeast extract capacity through captive molasses sourcing and continuous bioreactor operations. Kyowa Hakko Bio Co., Ltd. differentiates its nucleotide portfolio via proprietary Corynebacterium strains refined at its Yamaguchi research center.
Fermented ingredients comprise metabolites, whole-cell biomass, and enzymatic extracts produced through controlled submerged or solid-state fermentation of bacteria, yeast, or filamentous fungi, typically requiring pH 4.5–7.0, temperatures between 28°C and 37°C, and dissolved oxygen monitoring across 50,000–400,000 liter vessels. These outputs serve as flavor potentiators, nutritional fortifiers, feed efficiency enhancers, and biocatalytic intermediates across food, pharmaceutical, and agricultural value chains. Yeast-derived extracts and nucleotides command the widest application footprint in food and beverages, while enzymes represent the fastest-expanding product category as textile and biofuel sectors in Vietnam and Indonesia adopt enzymatic processing. Lactic acid bacteria concentrates retain mature, margin-compressed positions in dairy starter cultures, whereas mold-fermented citric acid and itaconic acid increasingly occupy higher-margin pharmaceutical and biopolymer niches.
Japan's Ministry of Health, Labour and Welfare (MHLW) and Food Safety Commission enforce stringent specifications for fermented food additives, compelling exporters to maintain dual certification protocols for Japanese market access. China's SAMR implements GB standards for fermented feed additives that restrict unapproved strain introductions, directly shaping R&D pipelines and import substitution strategies. India's FSSAI and BIS jointly regulate novel fermented nutraceutical claims, creating compliance complexity for entrants from ASEAN free-trade partners. Stakeholders must monitor evolving strain patent thickets and carbon-intensity disclosure requirements as sustainability-linked procurement criteria harden across Japanese and South Korean buyer specifications.
Market Dynamics
China's SAMR is tightening strain registration requirements for fermented feed additives, forcing domestic suppliers to redirect R&D budgets toward compliance documentation and away from novel strain development pipelines.
Growth Catalysts
- Clean-label food reformulation:Southeast Asian food processors are replacing synthetic flavor enhancers with yeast-derived nucleotides and fermented amino acids to meet retailer clean-label mandates.
- India's PLI scheme for biotechnology:Production-linked incentives for fermentation-based nutraceuticals are attracting capacity investments from domestic and multinational feed producers.
- Enzymatic textile processing:Vietnam's apparel sector is adopting cellulase and pectinase enzymes to reduce water consumption and chemical discharge in fabric finishing operations.
Market Restraints
- Molasses supply volatility:Sugar crop fluctuations in Thailand and Indonesia are squeezing yeast extract margins and forcing spot-market purchasing of alternative carbohydrate feedstocks.
- Strain patent thickets:Corynebacterium and Bacillus subtilis engineering IP held by Japanese and Chinese research consortia is blocking second-tier fermenters from commercializing improved lysine and enzyme variants.
- Dual certification burden:Japan's MHLW specifications for fermented food additives require parallel testing protocols that extend time-to-market by 8-14 months for ASEAN exporters.
Strategic Opportunities
- Philippines nutraceutical underpenetration:Fermented nucleotide and probiotic ingredient penetration in Filipino functional foods remains below regional averages, creating first-mover positioning for compliant suppliers.
- South Korea's biofuel enzyme mandate:Renewable fuel standards are accelerating demand for lipase and amylase enzymes in waste-oil transesterification, with domestic blenders seeking ASEAN supply partnerships.
- Carbon-intensity disclosure requirements:Japanese and South Korean buyer specifications for scope 3 emissions data are creating premium pricing tiers for fermenters with verified low-carbon production.
Industry Challenges
- Microbial strain engineering talent scarcity:Specialist biochemists are concentrating in Shanghai and Tokyo industrial biotechnology hubs, leaving Southeast Asian facilities dependent on contracted R&D services.
- Continuous bioreactor capex requirements:Transitioning from batch to continuous fermentation demands vessel and control system investments that strain mid-tier balance sheets.
- GB standard compliance timelines:China's SAMR approval pathways for novel fermented feed strains extend 24-36 months, compressing product lifecycle returns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Fermented Ingredient Market |
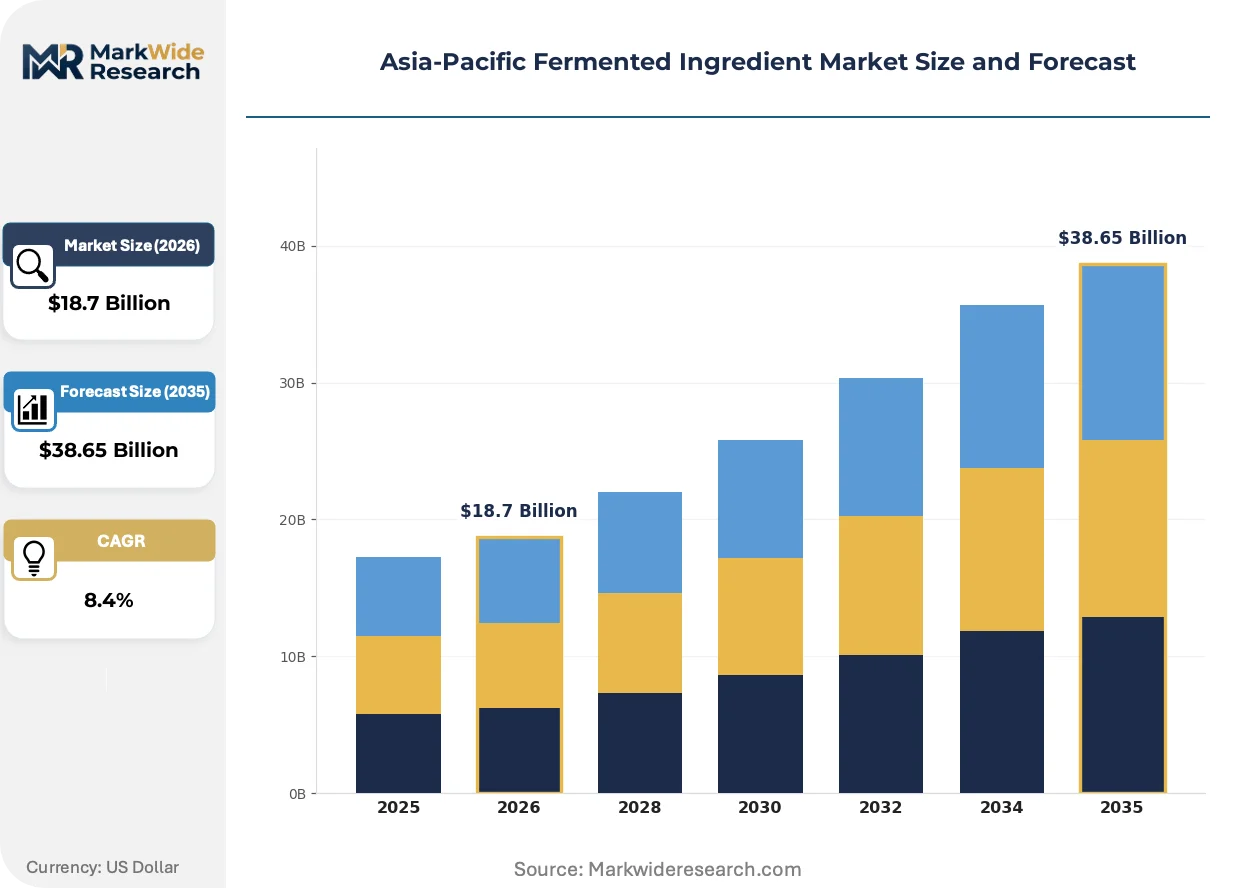
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Yeast, Lactic Acid Bacteria, Mold, Enzymes Application: Food & Beverages, Dietary Supplements, Pharmaceutical, Animal Feed End User: Food Processors, Beverage Manufacturers, Feed Producers, Nutraceutical Companies Form: Liquid, Powder, Granules, Tablets |
| Companies Covered | Ajinomoto Co., Inc., Angel Yeast Co., Ltd., Fufeng Group Ltd., Cargill, Inc., Kyowa Hakko Bio Co., Ltd., Tate & Lyle, Archer-Daniels Midland Co., DSM, Amano Corp., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Fermented Ingredient Market Strategic Shifts
Bioprocess automation and regulatory disclosure requirements are splitting competitive advantage between capital-heavy continuous fermenters and agile specialty batch producers across Asia-Pacific value chains.
Precision fermentation for high-value metabolites is bifurcating the ingredient landscape. Food-grade nucleotides and pharmaceutical intermediates now deploy dedicated 50,000-liter stainless steel vessels with real-time dissolved oxygen and pH telemetry. Japanese pharmaceutical offtakers are specifying single-use bioreactor lines for nucleotide APIs to eliminate cross-contamination risk. This technology compression is squeezing margin from commodity lysine while concentrating returns in contract-manufactured specialty extracts.
China's SAMR GB standards for fermented feed additives are tightening strain traceability requirements. Domestic suppliers must now document full genome sequences and stability data across 20+ generations for novel introductions. This regulatory friction is accelerating import substitution as local players gain approval advantages over ASEAN competitors. Thai and Indonesian lysine exporters are responding by pre-registering legacy strains under transitional provisions before full sequencing mandates take effect.
Buyer concentration among Japanese and South Korean feed compounders is shortening procurement cycles and unbundling technical service contracts. Large-scale purchasers now negotiate direct strain supply agreements that bypass traditional distributor markups, while demanding embedded carbon accounting and third-party sustainability verification. This channel compression is most visible in Vietnam's poultry sector, where integrated processors are consolidating nucleotide sourcing through single-supplier frameworks with penalty clauses for scope 3 disclosure failures.
Asia-Pacific Fermented Ingredient Market Segmentation
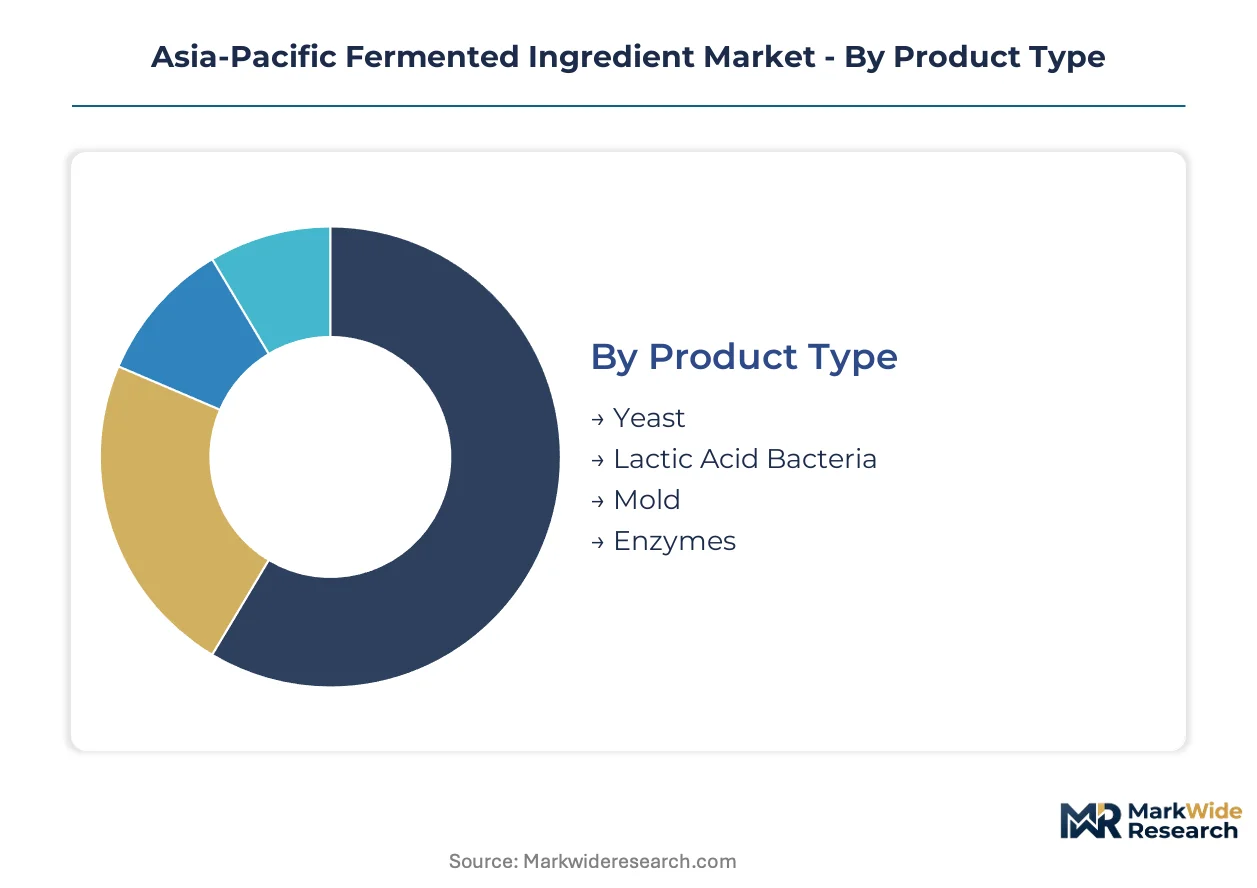
Segmentation in the Asia-Pacific fermented ingredient market reveals where substitution pressures and regulatory compliance costs concentrate competitive advantage. Distinct product categories face divergent fates from synthetic alternatives and precision fermentation technologies.
Product Type:
Yeast-derived ingredients confront the most acute substitution threat from chemical flavor enhancers in cost-sensitive Southeast Asian food processing, while enzyme portfolios gain defensive moats through process-specific performance claims.
- Yeast:Whole-cell biomass and autolysates supply nucleotides and yeast extracts for umami enhancement. Vietnamese and Indonesian instant noodle manufacturers are the dominant offtakers, though price volatility in Thai molasses squeezes margin.
- Enzymes:Cellulase, amylase, and protease preparations catalyze textile desizing, biofuel transesterification, and feed digestibility improvements. South Korean renewable fuel blenders are scaling procurement of lipase variants for waste-oil processing.
- Lactic Acid Bacteria:Starter culture concentrates for dairy fermentation face margin compression from commoditized supply.
- Mold:Aspergillus-derived citric acid and itaconic acid serve pharmaceutical and biopolymer intermediates with narrower substitution exposure.
Yeast retains volume leadership; enzymes hold the steepest expansion curve.
Application:
Application segments diverge sharply in certification burden, with pharmaceutical and nutraceutical pathways demanding multi-year approval timelines that filter out smaller suppliers.
- Food & Beverages:Clean-label reformulation across Thai and Indonesian processed foods drives nucleotide and yeast extract incorporation. Retailer mandates for ingredient transparency are displacing synthetic MSG in premium sauce and seasoning lines.
- Animal Feed:Fermented lysine and nucleotide supplementation improves feed conversion ratios in Vietnam's integrated poultry operations. SAMR strain registration requirements are redirecting procurement toward pre-approved domestic Chinese suppliers.
- Dietary Supplements:Probiotic concentrates and postbiotic extracts face FSSAI claim substantiation complexity in India.
- Pharmaceutical:Nucleotide APIs and fermentation-derived intermediates require MHLW-compliant manufacturing for Japanese market access.
Food & Beverages commands the largest revenue pool; Animal Feed is expanding most quickly.
End User:
End user concentration patterns reflect channel consolidation, with integrated feed compounders and multinational beverage groups squeezing distributor margins through direct sourcing frameworks.
- Feed Producers:Large-scale compounders in Vietnam and South Korea negotiate single-supplier nucleotide agreements with embedded carbon accounting requirements. Scope 3 disclosure failures trigger penalty clauses.
- Food Processors:Southeast Asian sauce, seasoning, and instant noodle manufacturers drive yeast extract volume, though spot purchasing of alternative carbohydrates destabilizes cost planning.
- Beverage Manufacturers:Fermented flavor modulation and enzyme clarification applications concentrate in Japanese and South Korean premium positioning.
- Nutraceutical Companies:Indian PLI scheme beneficiaries are scaling fermented ingredient procurement for functional food launches.
Feed Producers dominate procurement volume; Nutraceutical Companies show the sharpest growth acceleration.
Form:
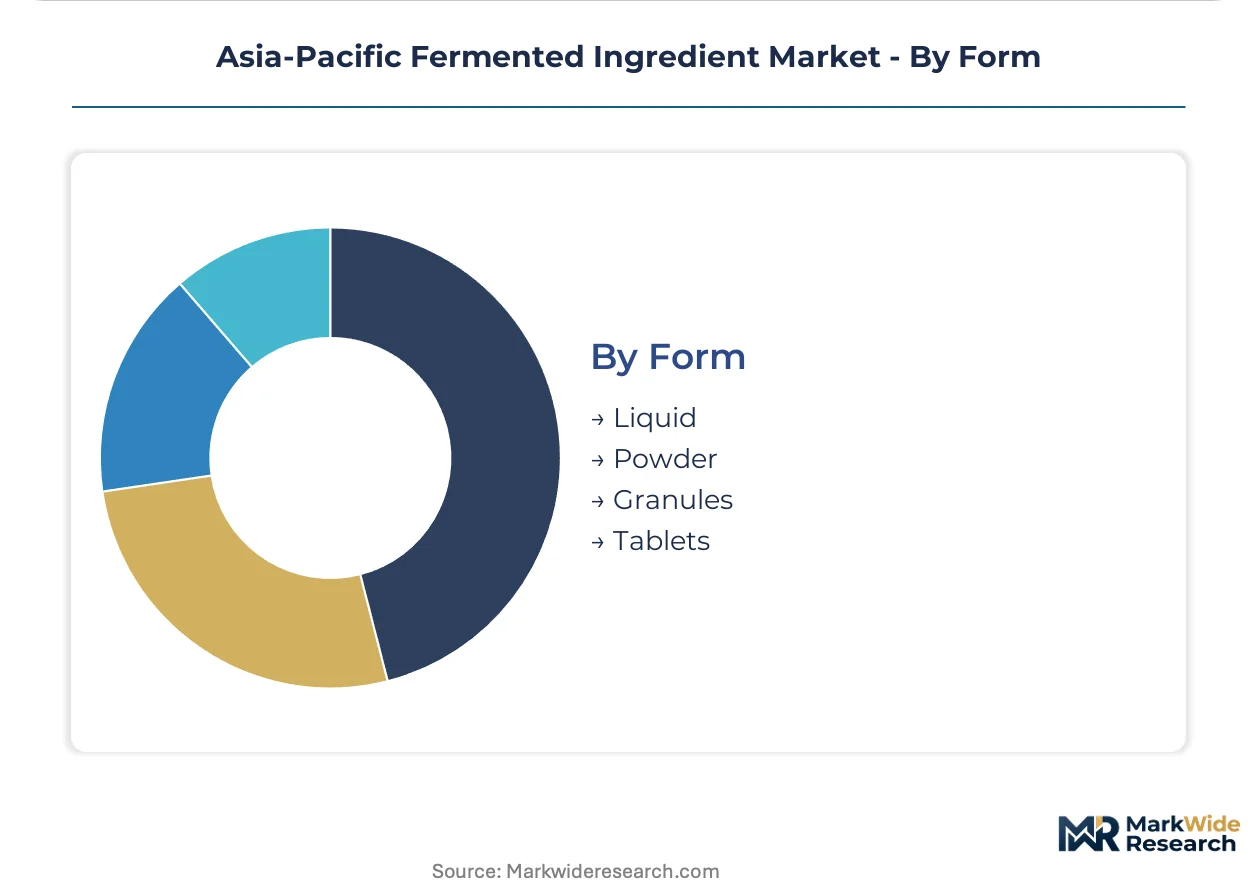
Form selection tracks logistics economics and dissolution performance requirements, with powder formats benefiting from established handling infrastructure across ASEAN distribution networks.
- Powder:Spray-dried yeast extracts and enzyme preparations offer shelf stability and bulk shipping efficiency. Thai and Indonesian port infrastructure favors powder handling for regional re-export.
- Liquid:High-activity enzyme concentrates and probiotic suspensions require cold chain integrity that limits penetration beyond Japanese and South Korean manufacturing clusters.
- Granules:Intermediate dissolution profiles serve feed pelleting operations with reduced dust generation.
- Tablets:Direct-compression probiotic and postbiotic formats target Indian nutraceutical contract manufacturing.
Powder maintains shipment dominance; Liquid is gaining share fastest in premium enzyme applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across Asia-Pacific diverge sharply: China and Japan prioritize pharmaceutical-grade nucleotides and precision fermentation, while Southeast Asian markets concentrate on cost-optimized yeast extracts and feed amino acids.
China
Fermented lysine and nucleotide demand concentrates in Shandong and Jiangsu provinces, where integrated feed compounders scale procurement. SAMR's GB standards for strain registration are redirecting R&D budgets toward compliance documentation. Shanghai and Tianjin biotechnology clusters are absorbing microbial strain engineering talent from regional competitors.
Japan
Pharmaceutical nucleotide APIs and premium food-grade extracts dominate consumption, with MHLW specifications enforcing dual certification protocols for importers. Kansai region fermentation facilities are upgrading to single-use bioreactor lines for contamination-sensitive production. Osaka and Kyoto industrial biotech hubs are refining proprietary Corynebacterium strains for high-value metabolite output.
India
Fermented nutraceutical ingredients and feed additives are scaling rapidly under the PLI scheme for biotechnology, with Maharashtra and Gujarat hosting capacity investments. FSSAI and BIS joint oversight of novel health claims is creating compliance complexity for ASEAN entrants. Hyderabad and Bengaluru biotech corridors are attracting contract manufacturing for probiotic concentrates.
Vietnam
Enzymatic textile processing and poultry feed nucleotides drive demand, with integrated processors consolidating sourcing through single-supplier frameworks. Apparel sector adoption of cellulase and pectinase enzymes is reducing water consumption in fabric finishing. Ho Chi Minh City and Binh Duong industrial zones are anchoring feed compounder procurement with embedded carbon accounting requirements.
Indonesia
Yeast extract consumption for instant noodle and seasoning manufacturing dominates, though molasses supply volatility is forcing spot-market purchasing of alternative carbohydrates. Jababeka and MM2100 industrial estates in West Java are concentrating food processor demand. Jakarta-based distributors are managing cost planning instability from Thai sugar crop fluctuations.
Asia-Pacific Fermented Ingredient Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with the upper layer commanding captive feedstock sourcing and continuous bioreactor infrastructure. Mid-tier fermenters compete on batch flexibility and regional regulatory navigation. Three archetypes define positioning: vertically integrated amino acid suppliers, yeast extract specialists with molasses security, and precision fermentation contract manufacturers. Dominant competitive moves include backward integration into carbohydrate feedstocks and pre-registration of legacy strains under transitional regulatory provisions.
Within the integrated amino acid tier, Ajinomoto Co., Inc. and Fufeng Group Ltd. exemplify scale-driven positioning, while Angel Yeast Co., Ltd. and Kyowa Hakko Bio Co., Ltd. occupy distinct specialist positions. These four entities represent the competitive spectrum from diversified fermentation complexes to focused metabolite portfolios, with geographic origins spanning Japan, China, and regional Southeast Asian production bases.
| Leading Market Players |
|---|
| Ajinomoto Co., Inc. |
| Angel Yeast Co., Ltd. |
| Fufeng Group Ltd. |
| Cargill, Inc. |
| Kyowa Hakko Bio Co., Ltd. |
| Tate & Lyle |
| Archer-Daniels Midland Co. |
| DSM |
| Amano Corp. |
| Others |
Value Chain & Pricing Dynamics
Continuous bioreactor scale economies at Thai and Indonesian fermentation complexes compress unit costs while anchoring regional price floors for yeast extracts and amino acids. This concentration of large-vessel capacity tightens supply-side control over nucleotide and enzyme pricing, forcing smaller batch fermenters into specialty niches or contract manufacturing arrangements.
Pricing Analysis
Long-term offtake agreements dominate procurement between Vietnamese poultry integrators and Chinese lysine suppliers, embedding volume-commitment discounts and scope 3 carbon-disclosure requirements. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade certification levels separates MHLW-compliant Japanese nucleotide APIs from commodity Indonesian yeast extracts. Pricing pressure stems from molasses feedstock volatility in Thai sugar belts, squeezing margin on standard yeast autolysates. Feed compounders in Vietnam and South Korea exhibit highest price sensitivity, while Japanese pharmaceutical offtakers absorb premiums for single-use bioreactor compliance.
Supply Chain Analysis
China and Thailand anchor fermentation capacity, with Shandong province hosting integrated lysine complexes and Thai facilities commanding regional yeast extract output. Carbohydrate feedstocks draw from Indonesian molasses streams and Indian sugar byproduct channels, while stainless steel vessel fabrication rests on Japanese and South Korean equipment supply. Single-source vulnerability concentrates in Corynebacterium strain IP held by Japanese research consortia, blocking second-tier fermenters from improved nucleotide variants. Distribution runs through Jakarta and Ho Chi Minh City-based distributors for ASEAN food processors, with direct-supplier frameworks bypassing intermediaries for large-scale Vietnamese feed compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific fermented ingredient market is recovering from a cyclical trough driven by China's SAMR compliance surge redirecting procurement toward pre-approved domestic suppliers. This regulatory cycle is compressing margins for ASEAN exporters while creating entry windows for compliant local players.
For Market Incumbents: Fortify captive molasses sourcing through backward integration into Thai and Indonesian sugar processing operations. Defend nucleotide pricing power by pre-registering legacy Corynebacterium strains under SAMR transitional provisions before full genome-sequencing mandates take effect. Channel control through direct-supplier frameworks with Vietnamese poultry integrators protects volume against spot-market competitors.
For New Entrants and Emerging Players: Anchor in Philippine nutraceutical formulation, where fermented nucleotide and postbiotic penetration trails regional benchmarks by a significant margin. Target enzymatic textile processing partnerships with Vietnamese apparel manufacturers adopting cellulase and pectinase for water-reduction compliance. Lead with carbon-accounting verification to meet Japanese and South Korean buyer specifications for scope 3 disclosure.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among precision fermentation contract manufacturers serving pharmaceutical nucleotide APIs with multi-year MHLW-compliant supply agreements. Long-term viability across the analysis window favors specialists with single-use bioreactor infrastructure and proprietary strain libraries. Acquisition target archetype: mid-tier Thai or Indonesian fermenters with SAMR-registered strain portfolios and underutilized continuous vessel capacity. The signal to watch is acceleration in South Korean renewable fuel enzyme mandates driving lipase procurement from ASEAN suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Strain Pre-registration Under Transitional Provisions | Locks in SAMR approval advantages before full genome-sequencing mandates compress product lifecycle returns for ASEAN exporters. |
| Backward Integration into Molasses Supply | Captive carbohydrate sourcing insulates Thai yeast extract margins from sugar crop volatility and spot-market feedstock purchasing. |
| Single-use Bioreactor Line Installation | Eliminates cross-contamination risk for Japanese pharmaceutical nucleotide offtakers specifying MHLW-compliant manufacturing protocols. |
| Carbon-intensity Verification Program | Unlocks premium pricing tiers with Japanese and South Korean buyers embedding scope 3 disclosure requirements in procurement contracts. |
| Precision Fermentation Capacity Expansion | Captures contract manufacturing demand for high-value metabolites as commodity lysine margins compress under continuous fermentation scale economies. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with fermentation plant managers, SAMR regulatory affairs specialists, Vietnamese feed compounder procurement leads, and Japanese pharmaceutical quality assurance directors; and secondary validation through GB standards documentation, FSSAI nutraceutical claim filings, MHLW food additive specifications, and ASEAN customs trade records. Bottom-up triangulation across vessel capacity utilization rates and top-down reconciliation against end-use consumption patterns anchored volume estimates.
Across the analysis window, the forecasting framework modeled product type segmentation against application pathways, with pharmaceutical-grade nucleotides, food-grade yeast extracts, feed-grade amino acids, and industrial enzymes as distinct margin tiers. CAGRs derived from capacity expansion announcements, PLI scheme beneficiary lists, and buyer concentration indices in Vietnamese poultry and South Korean biofuel blending. Strain registration timelines under SAMR GB standards and MHLW dual-certification protocols shaped adoption curve assumptions.
Decision-makers should treat outputs as directional under sustained SAMR enforcement intensity and molasses supply stability assumptions; material deviation in regulatory approval velocity or Thai sugar crop yields would warrant model refresh. Specific risk factors include Corynebacterium strain patent thickets blocking commercialization, continuous bioreactor capex constraints on mid-tier balance sheets, and carbon-accounting verification cost inflation. Recalibration cycles align with material shifts in SAMR GB standard implementation phases and South Korean renewable fuel mandate expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Europe Food Additives Market
Food Additives and Ingredients
Polyglycerol Esters of Fatty Acids Market
Food Additives and Ingredients
Africa Food Enzymes Market
Food Additives and Ingredients
Edible and Soluble Films Market
Food Additives and Ingredients
Egg Emulsifier Market
Food Additives and Ingredients
Low-Sodium Salt Substitute Market
Food Additives and Ingredients
Activated Cake Emulsifier Market
Food Additives and Ingredients
France Food Emulsifiers Market
Food Additives and Ingredients
Canada Food Enzymes Market
Food Additives and Ingredients
Locust Bean Gum Market
Food Additives and Ingredients
Flour Whiteners Market
Food Additives and Ingredients
Global Food Release Agents Market
Food Additives and Ingredients
Tara Gum Market
Food Additives and Ingredients
Food Protein Ingredient Market
Food Additives and Ingredients
Global Food Bulking Agents Market
Food Additives and Ingredients
Acetylated Distarch Adipate Market