
 Global Oilfield Communications Market | 2026-2036
Global Oilfield Communications Market Size, Share, and Industry Trends Forecast 2026-2036
Global Oilfield Communications Market Outlook
Modular service bundling is hardening as the dominant procurement pattern across offshore and remote onshore operations. SLB leverages its integrated drilling-communication platforms to anchor long-term contracts with national oil companies. Huawei Technologies competes on 5G private network deployments, while Speedcast sustains its maritime satellite dominance through fleet-wide managed service agreements.
Oilfield communications encompasses the transmission infrastructure, protocols, and terminal equipment enabling real-time data exchange between wellheads, rigs, processing facilities, and remote operations centers, typically operating across Ku-band satellite links, fiber-optic trunk lines, and licensed radio frequency bands with latency requirements under 250 milliseconds for directional drilling control. The primary purpose is to maintain continuous telemetry for automated well intervention, production optimization, and emergency shutdown systems in environments lacking terrestrial connectivity. Network services capture the largest margin pool due to recurring subscription structures, while edge computing delivery modes are expanding fastest as operators push analytics closer to wellheads to reduce satellite backhaul costs. Fiber optic technology leads in greenfield developments, though microwave retains stronghold status in mature basins where trenching costs prove prohibitive.
The FCC governs spectrum allocation for private industrial networks in the United States, directly shaping which radio technologies operators may deploy, while Brazil's ANP mandates redundant communication paths for offshore platforms under its operational safety regulations. The EU's Cyber Resilience Act is introducing baseline security requirements for connected industrial equipment, affecting vendor certification burdens for European deployments. Stakeholders must monitor evolving spectrum policy and cybersecurity mandates as these will determine which technology portfolios retain market access across major producing regions.
Market Dynamics
Offshore drilling contractors are consolidating procurement around integrated communication suites, forcing equipment vendors to bundle satellite, fiber, and radio systems under single-vendor contracts rather than selling discrete components.
Growth Catalysts
- FCC Spectrum Reallocation:The FCC's private LTE band assignments in the United States are accelerating equipment replacement cycles as operators retool for licensed cellular networks.
- Pre-Salt Basin Developments:Brazil's ANP safety mandates for redundant offshore communication paths are driving dual-network infrastructure investments across floating production facilities.
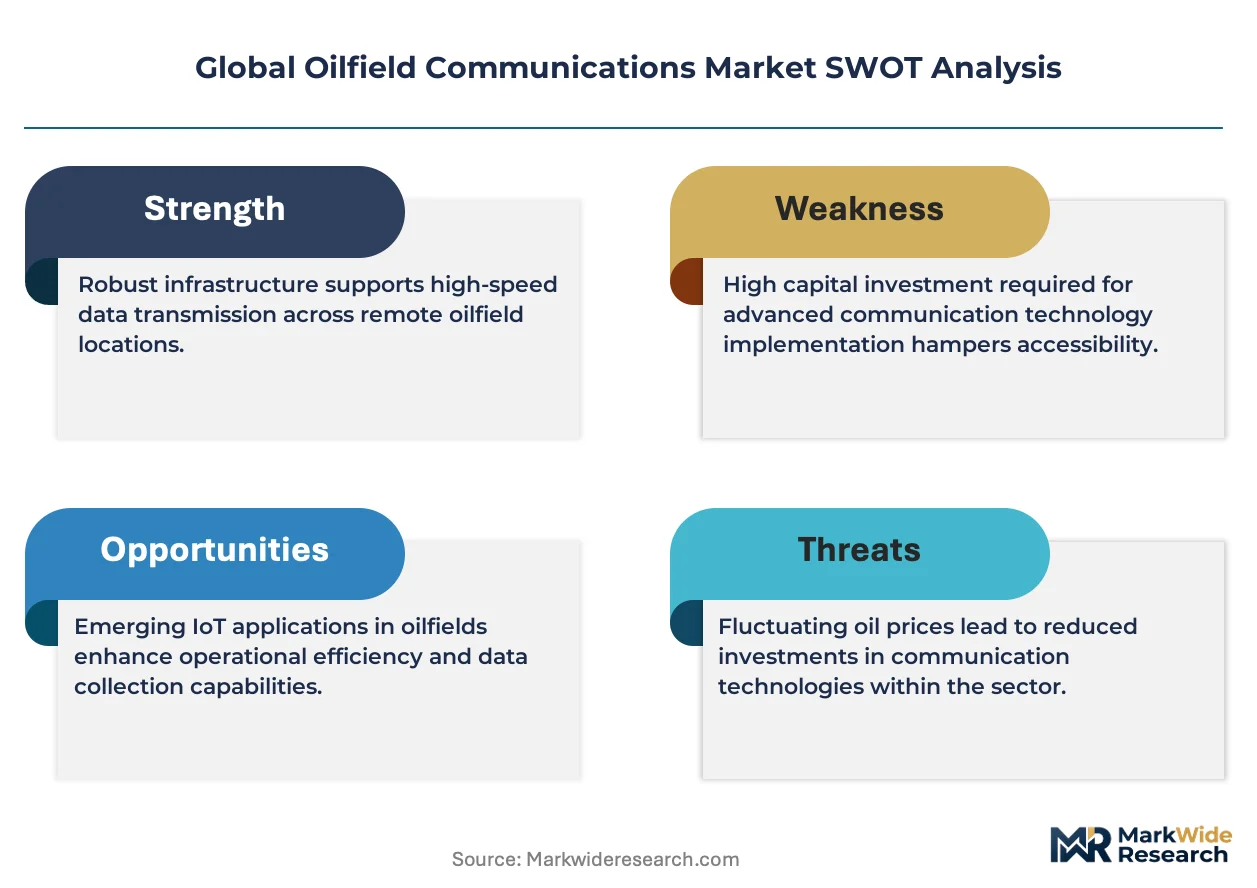
- Edge Computing Architectures:Wellsite analytics localization is compressing satellite backhaul requirements and expanding on-rig server deployments.
Market Restraints
- Specialized Component Concentration:High-frequency radio amplifiers and marine-grade antennas rely on a limited supplier base concentrated in Northern European industrial clusters.
- Trenching Cost Barriers:Fiber deployment in mature onshore basins faces prohibitive civil engineering expenses where existing microwave networks suffice.
- Cybersecurity Certification Burden:The EU Cyber Resilience Act is extending vendor compliance timelines and raising entry barriers for non-European equipment manufacturers.
Strategic Opportunities
- West African Deepwater:Underpenetrated offshore zones off Nigeria and Angola lack terrestrial backhaul, creating demand for fully integrated satellite-fiber hybrid networks.
- 5G Private Network Convergence:Integration of millimeter-wave terrestrial links with geostationary satellite backup is opening new service tiers for ultra-low-latency drilling control.
- Managed Service Bundling:Fleet-wide communication outsourcing is displacing capital-intensive equipment purchases among mid-size offshore contractors.
Industry Challenges
- Subsea Network Integration:Retrofitting fiber-optic links to existing subsea production systems requires specialized vessel time and complex seabed engineering.
- Multi-Band Certification Complexity:Equipment must simultaneously satisfy FCC, ANP, and EU cybersecurity standards, fragmenting product development roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Oilfield Communications Market |
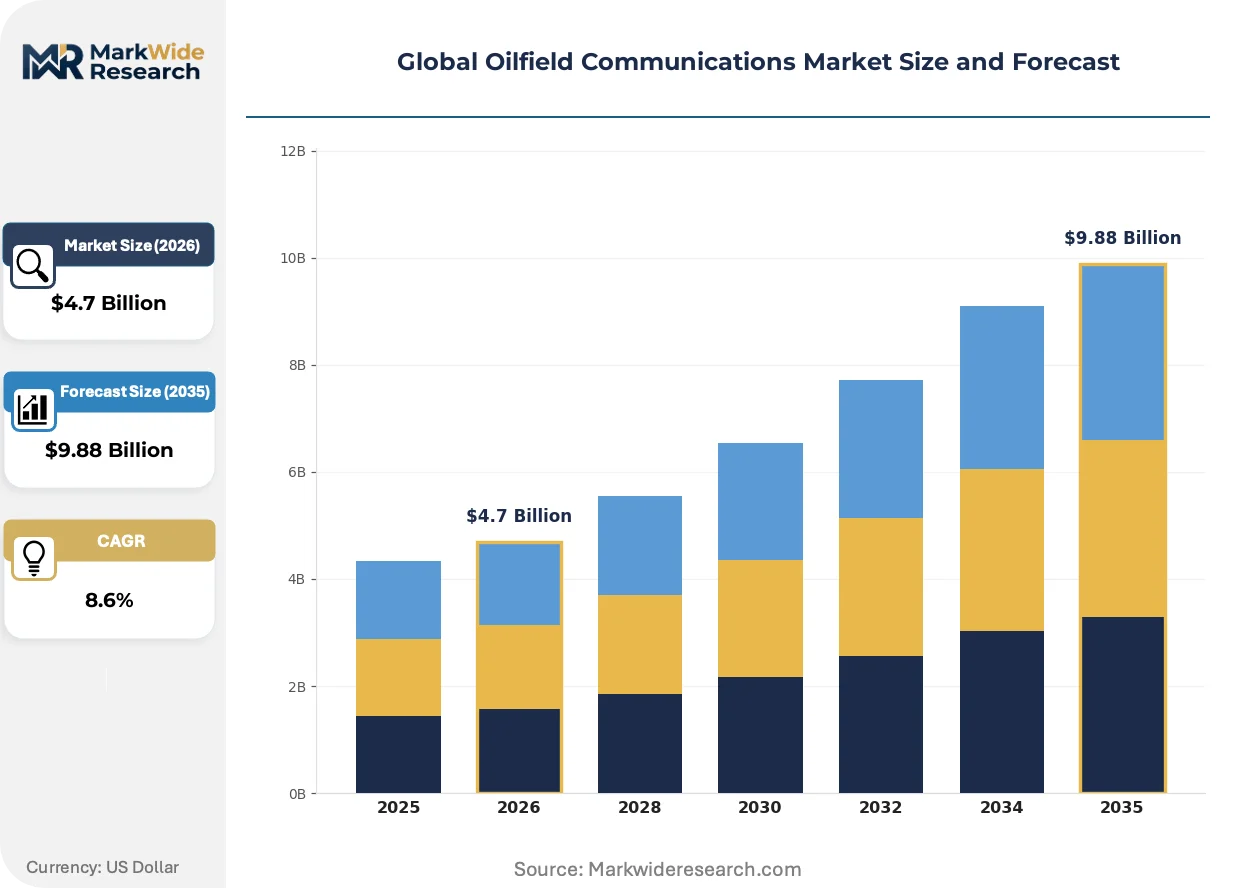
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $9.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Data Transmission, Voice Communication, Remote Management, Network Services End User: Exploration Companies, Drilling Contractors, Production Firms, Service Providers Technology: Satellite, Fiber Optic, Radio Frequency, Microwave Delivery Mode: Cloud-Based, On-Premise, Hybrid, Edge Computing |
| Companies Covered | Huawei Technologies, Siemens Energy, Halliburton, SLB, Baker Hughes, ABB, RigNet, Speedcast, Inmarsat, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Oilfield Communications Market Strategic Shifts
Real-time telemetry requirements are compressing latency tolerances below 100 milliseconds for directional drilling, forcing infrastructure investments toward fiber-rich and low-earth-orbit satellite architectures.
Private 5G networks using 3.5 GHz CBRS spectrum are electrifying rig-site connectivity by replacing legacy Wi-Fi and unlicensed radio meshes. Offshore contractors in the Gulf of Mexico are deploying these systems within 18-month procurement cycles. The technology is electrifying competitive positioning among network integrators who can deliver end-to-end licensed spectrum solutions.
The EU Cyber Resilience Act is mandating baseline security requirements for connected industrial equipment sold across European Economic Area member states. Vendors must now embed hardware security modules and software bill-of-materials disclosure into terminal devices. Offshore platform operators in the North Sea are prioritizing pre-certified equipment to avoid deployment delays.
Modular service contracts are displacing capital-heavy equipment purchases among drilling contractors seeking operational expenditure predictability. National oil companies in Brazil and Nigeria are favoring vendors offering satellite bandwidth, maintenance, and hardware refresh under single recurring agreements. This pattern concentrates contract value with integrators capable of spanning multiple transmission technologies.
Global Oilfield Communications Market Segmentation
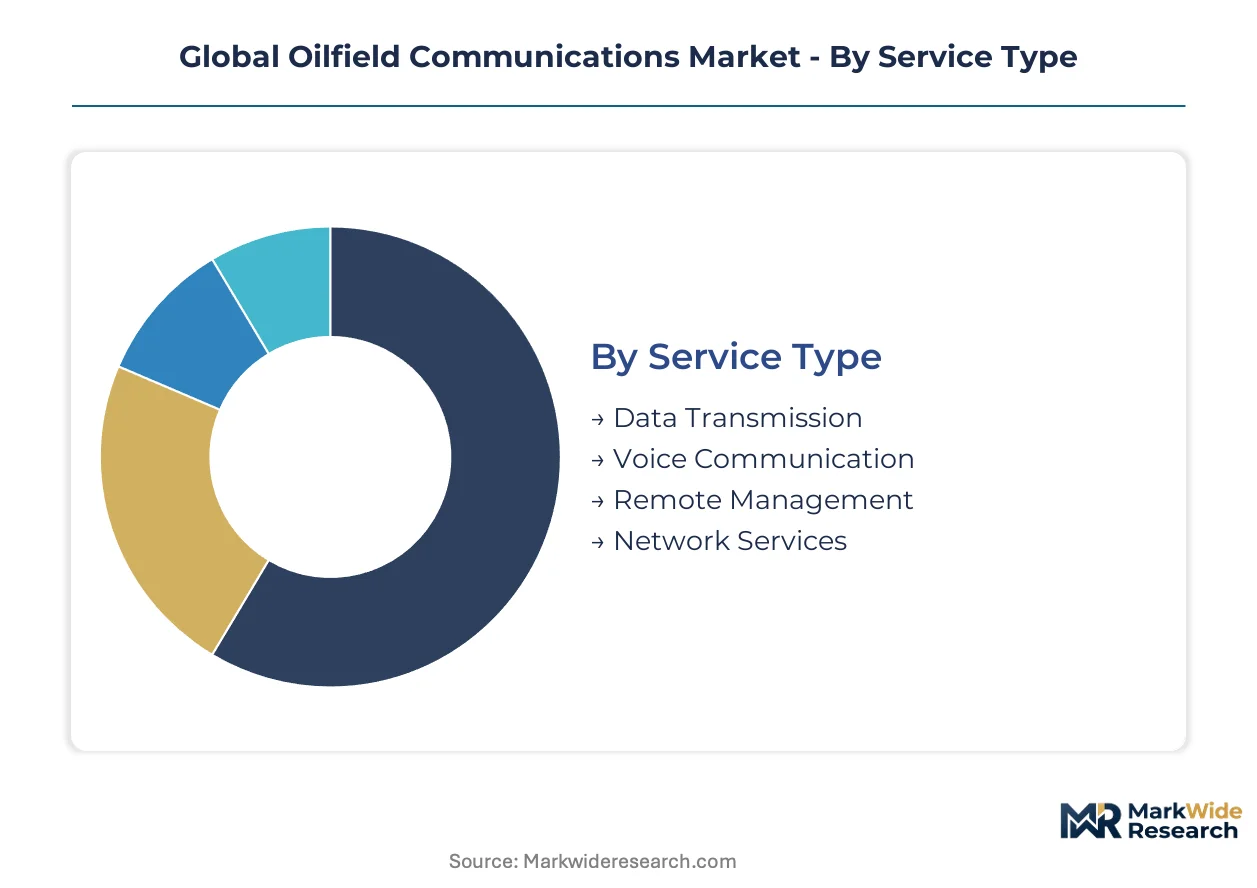
Segmentation in oilfield communications reveals how procurement decisions split between capital-intensive infrastructure and recurring service models. Technology choices vary sharply by basin maturity and regulatory environment, while delivery architectures increasingly favor operational expenditure structures over asset ownership.
Service Type:
Service differentiation follows the latency-sensitivity hierarchy of upstream operations, with critical control functions commanding premium pricing against administrative traffic.
- Network Services:Bundled connectivity subscriptions spanning satellite bandwidth, terrestrial backhaul, and maintenance protocols. Brazilian pre-salt operators favor multi-year agreements integrating hardware refresh cycles to satisfy ANP redundancy mandates.
- Data Transmission:High-throughput telemetry for directional drilling and well intervention, typically operating under 250-millisecond latency ceilings. Gulf of Mexico contractors are consolidating procurement around integrated suites combining fiber, microwave, and satellite failover.
- Voice Communication:Push-to-talk and VoIP systems for crew coordination, now migrating from legacy radio to VoLTE over private LTE networks.
- Remote Management:Platform oversight and SCADA integration, expanding fastest where labor access constraints drive automation priorities.
Network Services leads on scale; Remote Management leads on momentum.
End User:
Procurement authority concentrates with entities controlling drilling schedules and regulatory compliance exposure.
- Drilling Contractors:Fleet-wide communication standardization across jack-up rigs and drillships. Integrated suite adoption is displacing discrete component purchasing as contractors seek single-vendor accountability.
- Production Firms:Subsea tieback and floating facility operators requiring redundant paths for emergency shutdown systems. North Sea platforms prioritize pre-certified equipment under EU Cyber Resilience Act timelines.
- Exploration Companies:Seismic survey and wildcat drilling operators with intermittent, high-mobility connectivity needs.
- Service Providers:Third-party well intervention and logging specialists requiring temporary network access at client facilities.
Drilling Contractors anchor contract value; Production Firms drive specification stringency.
Technology:
Physical layer selection hinges on terrain, existing infrastructure, and latency requirements for automated control systems.
- Fiber Optic:Terrestrial and subsea trunk lines delivering sub-10-millisecond latency for real-time drilling control. Greenfield developments in West African deepwater favor fiber-satellite hybrids where terrestrial backhaul remains absent.
- Satellite:Geostationary and low-earth-orbit constellations serving remote basins lacking terrestrial infrastructure. Ku-band dominates legacy installations; LEO adoption is climbing where latency compression justifies equipment refresh.
- Microwave:Point-to-point radio links in mature onshore basins where trenching costs prohibit fiber deployment.
- Radio Frequency:Licensed and unlicensed spectrum for last-mile rig-site connectivity, now migrating toward private LTE under FCC band assignments.
Fiber Optic commands margin premiums; Satellite spans geographic coverage.
Delivery Mode:
Architecture decisions determine capital allocation between operator-owned infrastructure and outsourced service layers.
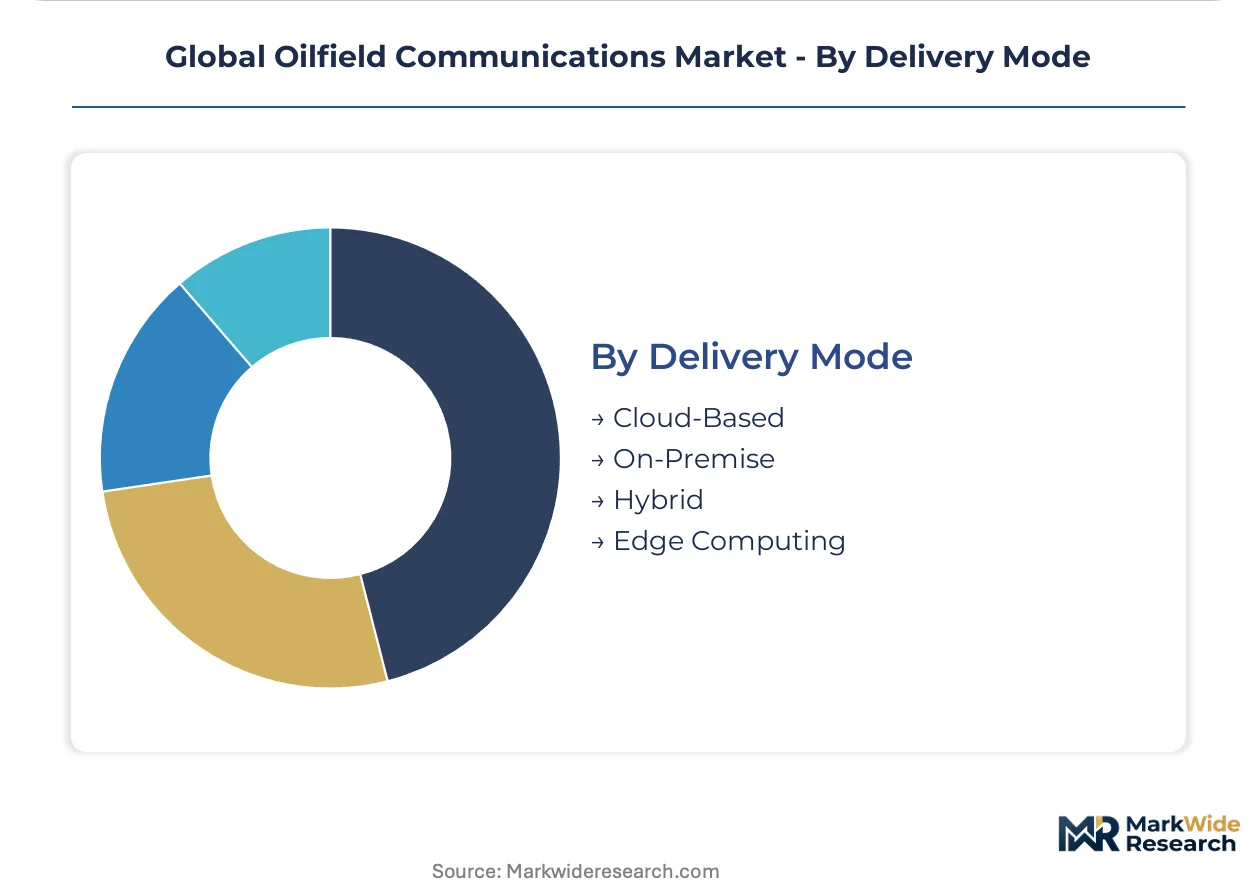
- Edge Computing:On-rig server deployments localizing analytics to compress satellite backhaul costs. Pre-salt developments in Brazil are expanding edge node counts to handle production optimization algorithms.
- Hybrid:Combinations of cloud core processing with local data residency for regulatory compliance. EU operators favor this model to satisfy data sovereignty requirements under national implementations of GDPR.
- Cloud-Based:Fully centralized processing with satellite uplink dependency, declining share as latency requirements tighten.
- On-Premise:Legacy dedicated infrastructure, persisting where cybersecurity air-gapping remains mandatory.
Edge Computing gains share fastest; Hybrid architectures balance compliance with flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The oilfield communications industry traces its modern infrastructure roots to North Sea offshore developments in the 1970s, where satellite telemetry first enabled remote platform management. Today, procurement patterns concentrate in jurisdictions with active deepwater licensing rounds and stringent safety mandates.
United States
Gulf of Mexico deepwater operators drive demand for private LTE networks and low-latency drilling control systems. The FCC's CBRS spectrum reallocation accelerates equipment replacement cycles among offshore contractors. Houston anchors the vendor ecosystem, with integrators clustering around the Energy Corridor to serve Permian Basin and offshore clients.
Brazil
Pre-salt basin floating production facilities require redundant communication paths under ANP operational safety regulations. Dual-network infrastructure investments dominate procurement for drillships and FPSO units. Rio de Janeiro hosts the primary contractor concentration, with local integrators partnering with international satellite operators to satisfy local content requirements.
Norway
North Sea platform electrification and subsea tieback projects demand fiber-optic trunk lines with sub-10-millisecond latency specifications. The country's national petroleum regulator enforces cybersecurity standards that predate EU-wide mandates. Stavanger and Bergen harbor specialized vessel operators and subsea engineering clusters serving Barents Sea developments.
United Kingdom
Decommissioning timelines and remaining field life extensions reshape communication infrastructure refresh decisions in mature basins. The HSE maintains offshore safety case requirements that incorporate communication system redundancy. Aberdeen retains its position as the North Sea's primary service hub, though vendor consolidation pressures local independents.
China
Deepwater exploration in the South China Sea and shale gas development in Sichuan basin expand demand for integrated satellite-fiber hybrids. MIIT spectrum policies favor domestic equipment certification for private industrial networks. Shenzhen and Beijing concentrate 5G private network integrators targeting offshore oilfield deployments.
Global Oilfield Communications Market Competitive Environment
Premium-margin players sit above commodity-margin players across technology integration depth and service bundling scope. The market structure exhibits tiered concentration, with a handful of integrated energy service conglomerates commanding long-term national oil company contracts alongside specialized satellite operators and regional radio equipment vendors. Three archetypes dominate: full-stack drilling-communication integrators, pure-play satellite bandwidth providers, and licensed spectrum equipment specialists. Competitive moves center on multi-year managed service outsourcing agreements and private 5G network deployment partnerships.
Within the integrated energy services tier, SLB and Halliburton exemplify the drilling-communication platform model, bundling telemetry infrastructure with directional drilling services. Speedcast represents the maritime satellite bandwidth archetype, sustaining market presence through fleet-wide subscription structures. Huawei Technologies occupies a position among licensed spectrum equipment specialists, competing on private 5G and LTE network deployments for industrial environments.
| Leading Market Players |
|---|
| Huawei Technologies |
| Siemens Energy |
| Halliburton |
| SLB |
| Baker Hughes |
| ABB |
| RigNet |
| Speedcast |
| Inmarsat |
| Others |
Value Chain & Pricing Dynamics
Drilling contractors consolidating procurement around integrated communication suites are compressing vendor margins and forcing subscription-based pricing models over discrete equipment sales. National oil companies in Brazil and Nigeria favor multi-year managed service agreements that bundle hardware, bandwidth, and maintenance into predictable operational expenditure structures.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the market, with differentiation driven by certification grade under EU Cyber Resilience Act timelines and volume scale across fleet-wide deployments. Cost compression in the economy tier is intensifying because mid-size offshore contractors are displacing capital purchases with outsourced service bundles. Exploration companies exhibit the highest price sensitivity due to intermittent project cycles, while production firms in the North Sea accept premium pricing for pre-certified equipment that avoids regulatory delays.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from integrated drilling contractors, while specialized distributors serve regional radio equipment procurement in mature onshore basins. Manufacturing concentrates in the United States for FCC-compliant private LTE equipment, Norway for subsea fiber-optic trunk systems, and China for 5G private network infrastructure under MIIT certification. Component sourcing draws from Northern European clusters for marine-grade antennas, Taiwanese fabs for high-frequency radio amplifiers, and Japanese suppliers for industrial-grade optical transceivers. Single-source vulnerability in specialized marine antenna production creates supply chain risk, particularly for pre-salt basin developments requiring ANP-mandated redundant paths.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in oilfield communications rests on the shift from capital equipment sales toward recurring managed service revenue, with edge computing localization reducing satellite backhaul costs as the primary cost-down driver.
For Market Incumbents: Acquire specialized subsea engineering capabilities to control the integration bottleneck for fiber-optic retrofit projects. Secure long-term spectrum leasing positions in Brazil and the United States ahead of ANP and FCC licensing rounds. Backward integration into marine-grade antenna production mitigates single-source concentration risk from Northern European suppliers. For New Entrants and Emerging Players: Cloud-based service marketplaces offer lower-friction entry paths for drilling contractors seeking modular communication procurement without legacy vendor lock-in. West African deepwater zones off Nigeria and Angola represent the most penetrable geography, lacking terrestrial backhaul and incumbent saturation. Target fleet-wide managed service outsourcing among mid-size offshore contractors as the primary go-to-market angle. For Investors and Strategic Acquirers: Integrated energy service conglomerates are the most active acquirer in this space, seeking to anchor national oil company relationships through drilling-communication platform bundling. Vertically specialized satellite bandwidth providers with fleet-wide subscription structures represent the optimal acquisition target archetype. Watch for FCC spectrum auction outcomes and ANP local content requirement tightening as inflection indicators for vendor competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Managed Service Bundling | Recurring revenue structures displace capital sales among Brazilian pre-salt operators under ANP mandates. |
| Private 5G Network Deployment | FCC CBRS spectrum assignments accelerate rig-site connectivity replacement cycles in Gulf of Mexico. |
| Edge Computing Localization | On-rig server deployments compress satellite backhaul costs for production optimization algorithms. |
| Subsea Fiber Integration | Specialized vessel partnerships control retrofit timelines for existing production system upgrades. |
| Cybersecurity Certification Investment | EU Cyber Resilience Act pre-certification avoids deployment delays on North Sea platforms. |
Study Parameters
Bottom-up drilling contractor and production firm modeling reconciled against top-down satellite bandwidth and equipment shipment tracking forms the analytical core of this study. Primary interviews with offshore platform engineers, telecommunications procurement leads at national oil companies, subsea integration specialists, and FCC regulatory affairs directors combined with secondary validation from ANP operational safety filings, FCC spectrum allocation records, EU Cyber Resilience Act implementation guidance, and customs data on marine-grade antenna imports. Cross-referencing bottom-up contract value estimates against top-down vendor revenue disclosures ensures segmentation accuracy.
Input-output matrices map infrastructure investment flows across service type, end user, technology, and delivery mode dimensions throughout the forecast period. CAGRs derive from regression analysis of historical procurement cycles against regulatory milestone timelines and basin licensing round schedules. Industry-specific inputs include satellite bandwidth pricing indices, private LTE equipment refresh cycles, and subsea vessel day-rate trends.
The model assumes a particular technology adoption path; alternative pathways for low-earth-orbit satellite constellation deployment would alter the outlook for latency-sensitive directional drilling applications. Forecasts reflect documented assumptions regarding FCC spectrum reallocation timing, ANP local content enforcement intensity, and EU cybersecurity certification adoption rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
CO2 EOR Market
Oil & Gas
Drones for Oil & Gas Market
Oil & Gas
Middle-East Completion Equipment and Services Market
Oil & Gas
Europe Wireline Logging Services Market
Oil & Gas
Vietnam Oil and Gas Midstream Market
Oil & Gas
United Kingdom Oil and Gas Midstream Market
Oil & Gas
Oil and Gas EPC Market
Oil & Gas
Wellhead Equipment Market
Oil & Gas
South America Intelligent Pigging Market
Oil & Gas
United States Coiled Tubing Market
Oil & Gas
Drilling and Completion Fluids Market
Oil & Gas
United States Oil and Gas Separation Market
Oil & Gas
Smart Pigging Market
Oil & Gas
United Arab Emirates Oil and Gas Downstream Market
Oil & Gas
Southeast Asia Oil and Gas Upstream Market
Oil & Gas
Brazil Oil and Gas Midstream Market