
 Vietnam Oil and Gas Upstream Market | 2026-2036
Vietnam Oil and Gas Upstream Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Oil and Gas Upstream Market Analytics
Vietnam's Cuu Long and Nam Con Son basins is rewriting investment priorities for international operators seeking production growth in Southeast Asia. PetroVietnam anchors domestic output through its operated fields and joint-venture partnerships across multiple offshore licenses. PTTEP leverages Thai upstream expertise to sustain production at key Block 15-1/2 developments. ExxonMobil competes at the high-complexity end with its Ca Voi Xanh gas development positioned for LNG export integration.
Vietnam oil and gas upstream encompasses the exploration, drilling, and production of crude oil and natural gas from subsurface reservoirs, typically involving well depths from 1,500 to 4,000 meters and reservoir pressures requiring subsea or platform-based extraction systems. The primary purpose is to supply feedstock to domestic refineries, power plants, and industrial gas consumers while generating export revenue through crude sales and LNG offtake. Exploration and drilling services command premium margins due to technical complexity in Vietnam's fractured carbonate and clastic reservoirs, while production operations represent the largest revenue pool given the country's maturing field base requiring continuous intervention. Enhanced oil recovery applications are gaining structural importance as natural decline rates at legacy fields create demand for gas injection and chemical flooding technologies.
Vietnam's Ministry of Industry and Trade and the National Assembly's petroleum legislation framework shape licensing terms, local content requirements, and fiscal stability for upstream investors. The country's national petroleum regulator enforces safety and environmental standards aligned with ASEAN offshore protocols, while the central bank's foreign exchange rules affect repatriation structures for international consortiums. Stakeholders must monitor how Vietnam's evolving gas master plan reconciles domestic supply obligations against emerging LNG import competition.
Market Dynamics
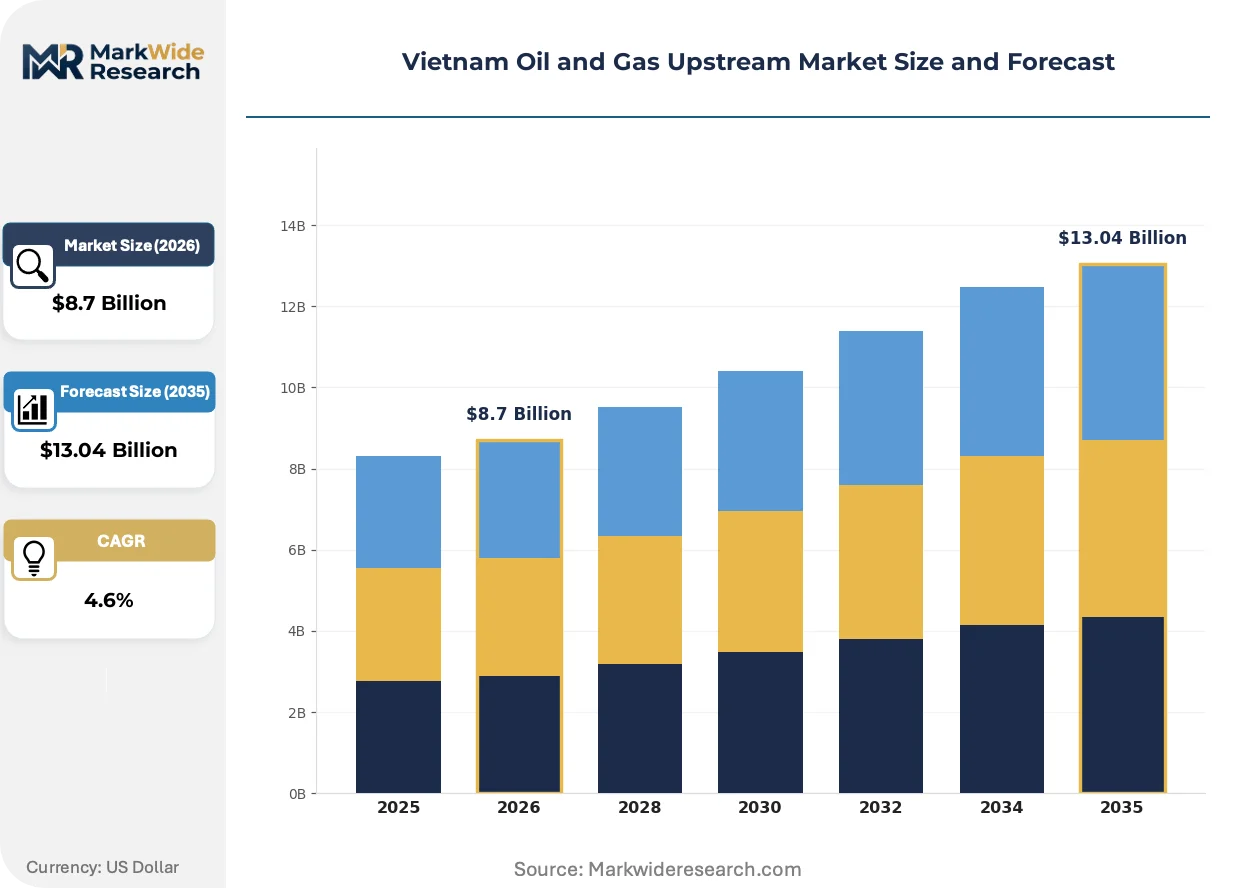
Vietnam's upstream sector faces structural pressure from maturing reservoir performance and the Ministry of Industry and Trade's revised petroleum legislation accelerating licensing rounds for marginal field blocks. Operators must balance enhanced recovery investments against domestic gas supply obligations while navigating foreign exchange repatriation constraints.
Growth Catalysts
- Power generation expansion:Gas-fired baseload capacity additions across the Ca Mau–Bassein Shelf corridor create sustained offtake demand for offshore production.
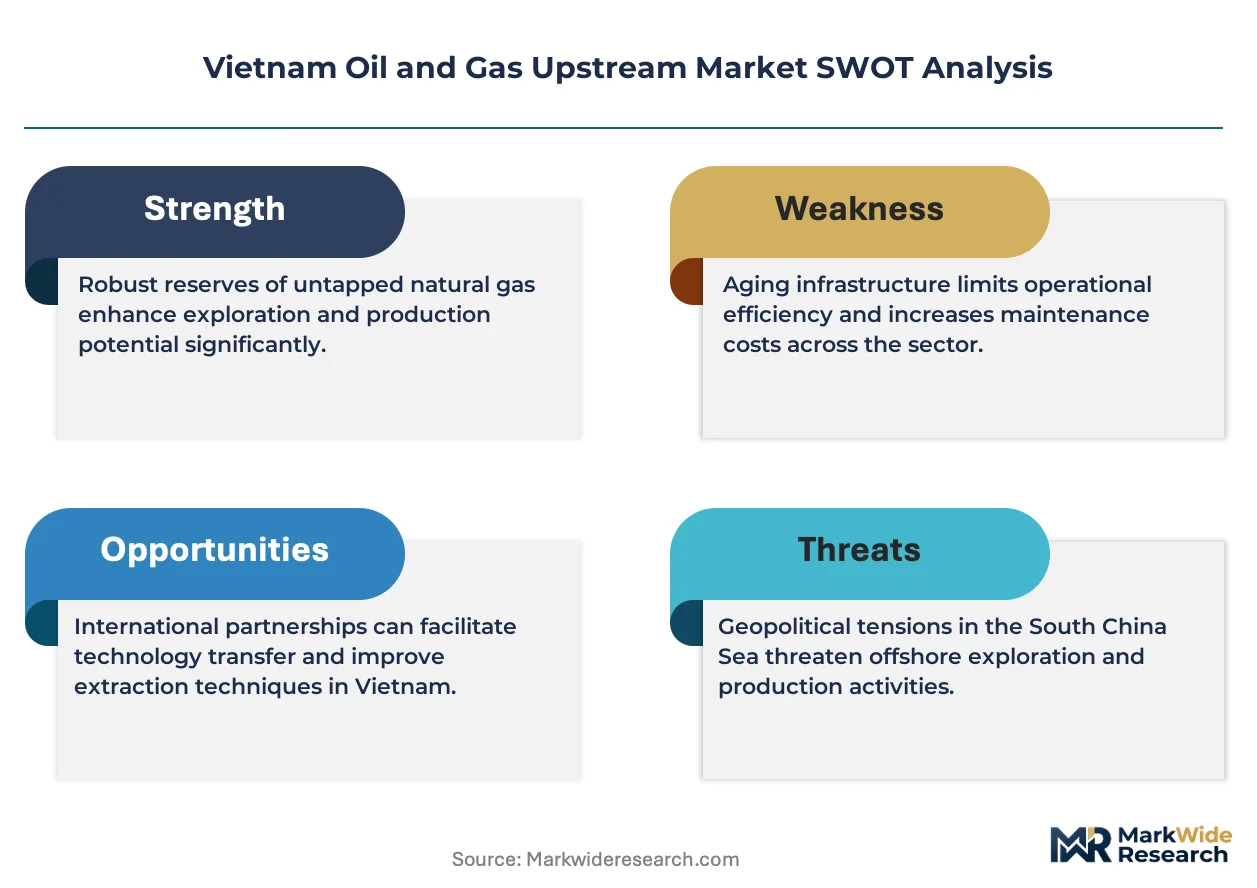
- Petroleum Law revisions:Vietnam's National Assembly framework improves fiscal terms and licensing clarity for international consortium participation in marginal field developments.
- Enhanced recovery deployment:Gas injection and chemical flooding technologies unlock stranded reserves in fractured carbonate reservoirs across the Cuu Long basin.
Market Restraints
- Reservoir complexity:Fractured carbonate and clastic formations at 1,500–4,000 meter depths require specialized drilling services with limited regional supplier availability.
- Foreign exchange controls:The State Bank of Vietnam's repatriation rules create working capital friction for international joint-venture operators.
- LNG import competition:Emerging regasification terminal capacity threatens domestic gas price realization for upstream producers.
Strategic Opportunities
- Nam Con Son basin extensions:Underexplored deepwater blocks offer material volume potential for operators with subsea production system expertise.
- Carbon capture integration:Associated gas reinjection for enhanced oil recovery aligns with Vietnam's energy transition commitments under revised petroleum legislation.
- Specialized service localization:Domestic content requirements create partnership openings for drilling and subsea engineering capabilities.
Industry Challenges
- Subsea engineering talent scarcity:Limited domestic pipeline of professionals capable of managing high-pressure reservoir interventions constrains project execution timelines.
- Legacy platform integration:Brownfield tiebacks require complex engineering to connect new subsea developments to aging offshore infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Oil and Gas Upstream Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Exploration, Drilling, Production, Well Services Technology: Seismic Surveying, Horizontal Drilling, Hydraulic Fracturing, Enhanced Oil Recovery End User: National Oil Companies, Independent Producers, Service Contractors, Consortiums Application: Offshore Production, Onshore Production, Enhanced Recovery, Asset Management |
| Companies Covered | Vietnam Oil & Gas Group (PetroVietnam), PTTEP, ExxonMobil, Jadestone Energy, TotalEnergies, Eni, Rosneft, CNOOC, Petronas Carigali, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Oil and Gas Upstream Market Evolving Landscape
Digital reservoir characterization and automation are compressing exploration timelines while regulatory pressure on domestic content reshapes contractor relationships. Three developments merit particular attention.
Advanced seismic processing and digital twin technology is digitizing subsurface interpretation workflows for Vietnam's fractured carbonate formations. International operators at Block 15-1/2 and Ca Voi Xanh deployments are adopting real-time drilling analytics to reduce non-productive time. The structural consequence is compressing exploration-to-production cycles from legacy multi-year horizons toward accelerated phased development models.
Vietnam's Ministry of Industry and Trade has tightened local content enforcement through revised petroleum legislation implementing graduated domestic participation mandates. The industrial consequence is forcing international operators to restructure procurement toward Vietnamese-registered service companies. Offshore drilling and subsea construction segments are responding through joint-venture formations with PetroVietnam affiliates to meet contractual local content thresholds.
Integrated service contracting is displacing discrete equipment procurement across marginal field developments in the Cuu Long basin. Operators now bundle drilling, completion, and production maintenance under single-source agreements to transfer reservoir performance risk. This pattern concentrates most visibly at enhanced recovery projects where service providers assume subsurface outcome accountability in exchange for production-linked compensation structures.
Vietnam Oil and Gas Upstream Market Segmentation
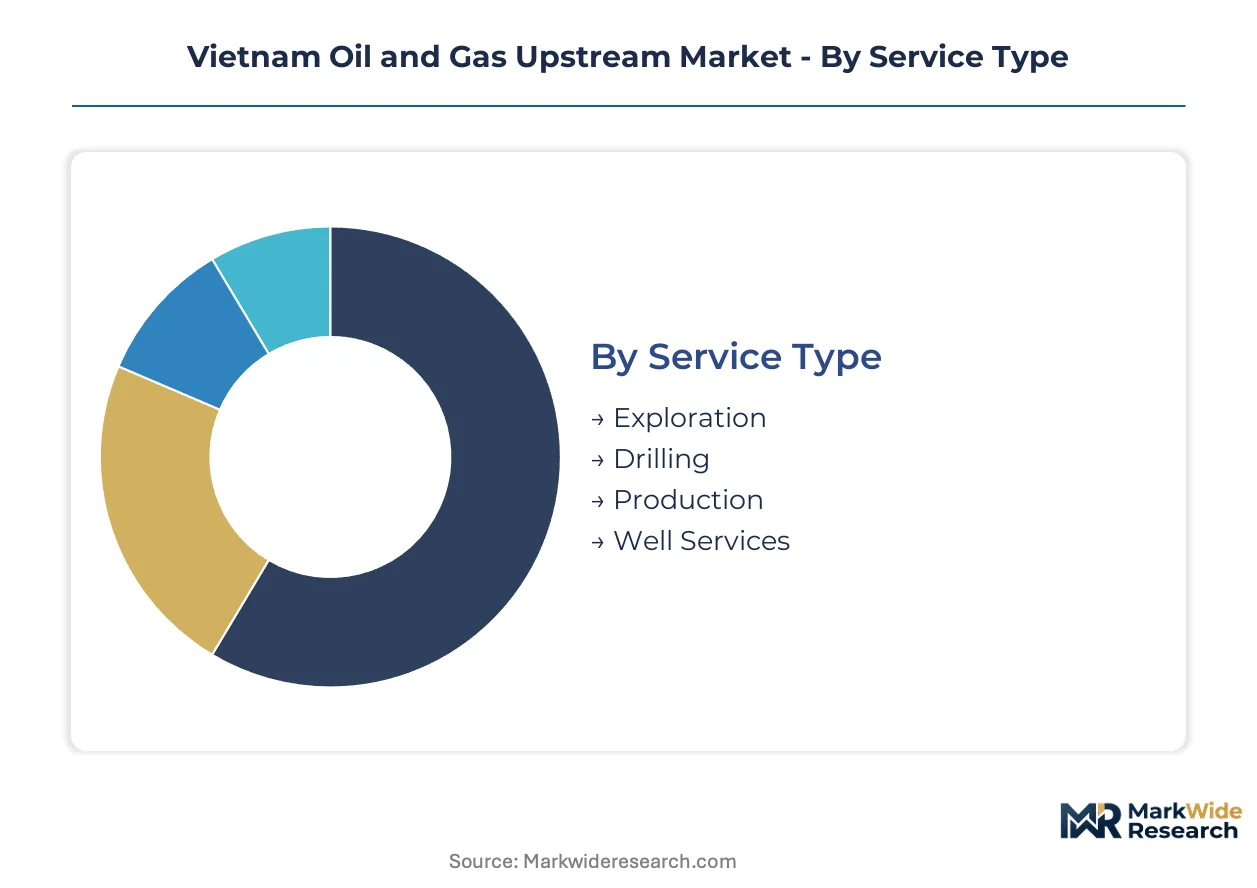
Vietnam's upstream market segments reflect distinct technical capabilities and contractual relationships. Each dimension shapes how operators allocate capital across exploration, development, and production phases in the Cuu Long and Nam Con Son basins.
Service Type:
Mature production operations anchor revenue stability while exploration services command premium margins in frontier blocks.
- Exploration:Seismic acquisition and subsurface interpretation for fractured carbonate reservoirs at 1,500–4,000 meter depths. Licensing rounds under revised petroleum legislation concentrate demand in the Ca Mau–Bassein Shelf corridor where block awards require accelerated appraisal timelines.
- Drilling:Extended-reach and high-pressure well construction for clastic formations. Operators at Block 15-1/2 and Ca Voi Xanh drive specification requirements for managed pressure drilling systems capable of handling narrow pressure windows.
- Production:Platform-based and subsea extraction systems for maturing fields. PetroVietnam joint ventures sustain continuous intervention demand across legacy Cuu Long basin assets.
- Well Services:Completion, workover, and intervention operations. Marginal field developments require cost-efficient recompletion packages to extend economic field life.
Production handles the majority of throughput; exploration is the fastest mover on share.
Technology:
Cost tier differentiation separates proven conventional methods from capital-intensive advanced recovery systems.
- Seismic Surveying:3D and 4D seismic for reservoir characterization. Digital twin integration at Nam Con Son developments compresses interpretation cycles and reduces exploration risk capital deployment.
- Horizontal Drilling:Extended-reach laterals for thin oil columns. Cuu Long basin operators apply multilateral architectures to maximize reservoir contact in heterogeneous carbonate zones.
- Hydraulic Fracturing:Stimulation treatments for tight clastic intervals. Limited regional pumping capacity constrains deployment scale outside consortium-operated blocks.
- Enhanced Oil Recovery:Gas injection and chemical flooding for mature fields. The Ministry of Industry and Trade's domestic supply obligations accelerate CO2-EOR pilots aligned with carbon management frameworks.
Seismic surveying dominates capital allocation; enhanced oil recovery is expanding most quickly as natural decline rates intensify.
End User:
Customer type determines contract structure and local content compliance intensity.
- National Oil Companies:PetroVietnam anchors procurement through operated fields and joint-venture equity positions. Revised petroleum legislation mandates graduated domestic participation thresholds across all service categories.
- Independent Producers:Smaller operators holding marginal field licenses. These entities prioritize bundled service contracts to transfer subsurface performance risk.
- Service Contractors:International drilling and subsea engineering firms. Local content enforcement drives joint-venture formations with Vietnamese-registered affiliates.
- Consortiums:International operator groupings under production sharing contracts. Foreign exchange repatriation rules from the State Bank of Vietnam shape working capital structures for these entities.
National oil companies control the largest contract volume; consortiums are gaining share fastest as licensing rounds attract international participation.
Application:
Geography within Vietnam's basins drives specification differentiation between offshore and onshore requirements.
- Offshore Production:Platform and subsea systems for Nam Con Son and Ca Mau developments. Deepwater blocks require subsea production system expertise where regional supplier availability remains constrained.
- Onshore Production:Mature fields in the Mekong Delta and southern coastal regions. Brownfield optimization focuses on artificial lift and surface facility debottlenecking.
- Enhanced Recovery:Gas and chemical injection projects for legacy assets. Power generation utilities' baseload expansion creates offtake pull for associated gas reinjection schemes.
- Asset Management:Integrated operations and maintenance contracts. Operators bundle drilling, completion, and production maintenance under single-source agreements to reduce interface risk.
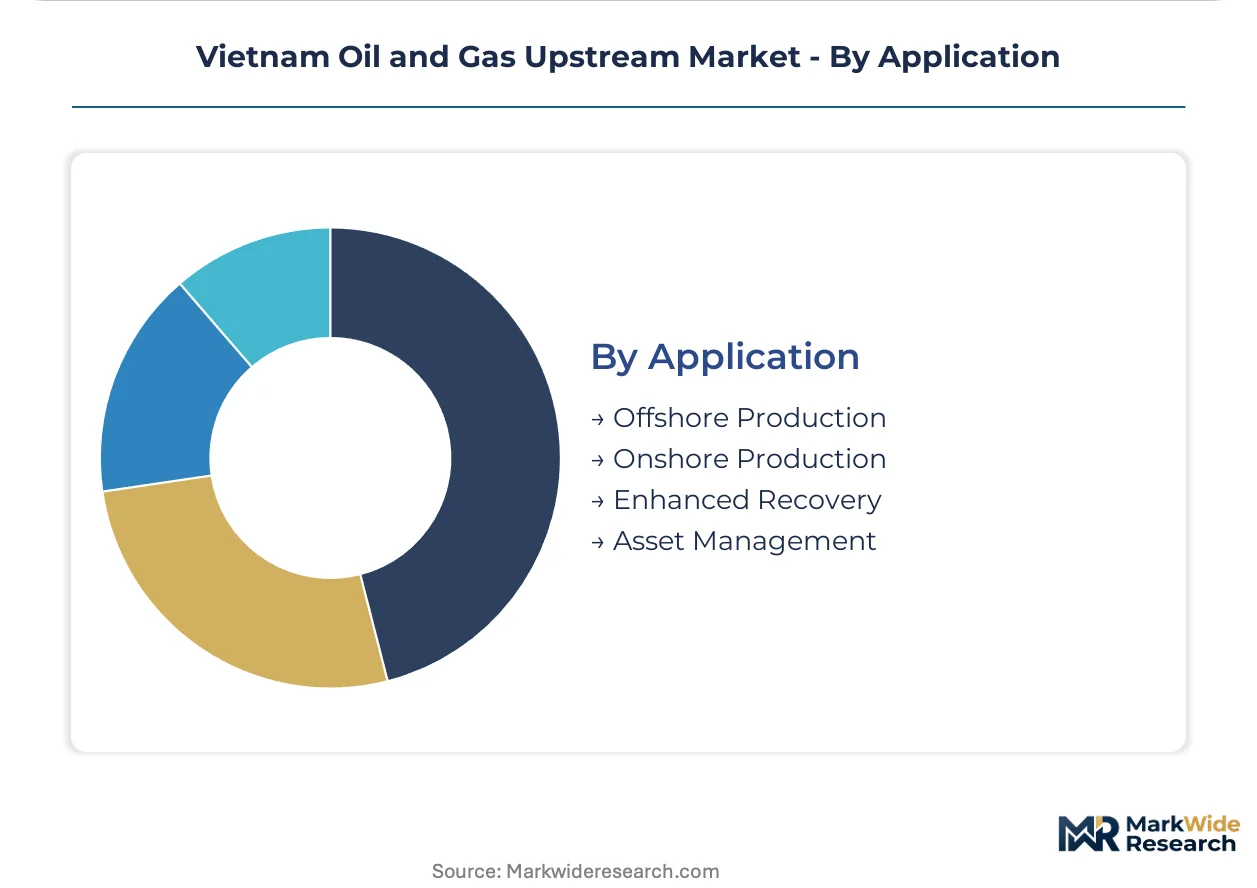
Offshore production absorbs the dominant share of upstream investment; enhanced recovery is climbing the fastest as reservoir maturity deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Upstream investment clusters along Vietnam's southern continental shelf where the Cuu Long and Nam Con Son basins host the majority of producing assets. Licensing activity concentrates in the Ca Mau–Bassein Shelf corridor under revised petroleum legislation.
Ho Chi Minh City Metropolitan Area
Power generation utilities anchor gas demand through baseload capacity expansion across the southeastern grid. Vietnam's Ministry of Industry and Trade enforces graduated local content mandates through production sharing contracts. The metropolitan area hosts PetroVietnam headquarters and service company joint ventures managing procurement for offshore developments.
Ca Mau Peninsula
Marginal field developments and enhanced recovery projects drive specialized service investment in this southwestern extremity. The National Assembly's petroleum legislation framework establishes fiscal terms for block awards in adjacent shelf areas. The peninsula's industrial zone supports logistics for Nam Con Son basin production operations.
Ba Ria–Vung Tau Province
Deepwater exploration blocks attract international consortium participation requiring subsea production system expertise. The State Bank of Vietnam's foreign exchange rules shape working capital structures for joint-venture operators. Vung Tau city functions as the primary supply base for offshore drilling and construction campaigns.
Khanh Hoa and South Central Coast
Frontier basin evaluation targets underexplored structures beyond established producing areas. Vietnam's national petroleum regulator applies ASEAN-aligned safety and environmental standards to licensing applications. Nha Trang hosts technical service providers supporting seismic acquisition and subsurface interpretation.
Vietnam Oil and Gas Upstream Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the contracting chain. National oil companies anchor equity positions through operated fields and production sharing arrangements. Three archetypes dominate: state-backed integrated operators, international majors with deepwater expertise, and specialized independents targeting marginal assets. Competitive positioning hardens through joint-venture formations with local affiliates and bundled service contracting that transfers reservoir performance risk.
Within the national operator tier, Vietnam Oil & Gas Group (PetroVietnam) anchors domestic output through its equity positions across multiple offshore licenses. PTTEP exemplifies regional upstream specialists leveraging Thai basin experience to sustain production at key developments. ExxonMobil occupies a position at the high-complexity end with gas developments positioned for LNG export integration.
| Leading Market Players |
|---|
| Vietnam Oil & Gas Group (PetroVietnam) |
| PTTEP |
| ExxonMobil |
| Jadestone Energy |
| TotalEnergies |
| Eni |
| Rosneft |
| CNOOC |
| Petronas Carigali |
| Others |
Value Network & Pricing Analysis
Commodity price volatility in global LNG benchmarks determines both the contract pricing tier spreads for Vietnamese gas offtake and the procurement geography for subsea equipment suppliers. State Bank of Vietnam foreign exchange repatriation constraints compress working capital availability for international joint-ventures, forcing pricing adjustments across service contract structures while reshaping supplier selection toward locally-registered joint-venture entities.
Pricing Analysis
Vietnam's National Assembly petroleum legislation dictates the pricing tier structure for upstream service contracts through graduated local content thresholds. Three-tier pricing structure across premium, standard, and economy levels separates integrated project management from discrete equipment procurement and bareboat rig charters. Cost compression in standard-tier drilling services is intensifying because regional supplier capacity constraints limit competitive pressure. National oil companies exhibit lowest price sensitivity due to domestic supply obligations, while independent marginal field operators face acute margin pressure from bundled service negotiations.
Supply Chain Analysis
Export control restrictions on subsea production systems and managed pressure drilling technology limit equipment flows from US and EU jurisdictions to Vietnamese offshore developments. Supply concentration rests on Singapore, South Korea, and Japan for subsea trees, blowout preventers, and dynamic positioning rigs. High-grade steel forgings, synthetic drilling fluids, and subsea umbilicals constitute critical input dependencies. Single-source vulnerability around subsea engineering talent constrains project execution timelines. Distribution runs through Vung Tau supply bases and Ho Chi Minh City procurement offices for final mile logistics to offshore installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Vietnam upstream market rewards operators who control scarce subsea engineering capabilities and maintain joint-venture relationships with PetroVietnam affiliates. Subsurface interpretation talent and high-pressure drilling system access constitute the binding constraints on production growth.
For Market Incumbents: Entrench position through backward integration into drilling services and artificial lift manufacturing to capture margin from bundled contract structures. Deepen PetroVietnam joint-venture equity positions to secure preferential block access under revised petroleum legislation licensing rounds. Counter LNG import competition by accelerating gas field development timelines to anchor domestic baseload contracts before regasification terminal capacity expands.
For New Entrants and Emerging Players: Pursue marginal field development opportunities in the Cuu Long basin where legacy infrastructure enables lower-capital brownfield tiebacks. Target enhanced oil recovery service contracts where production-linked compensation structures reduce upfront capital requirements. Enter through specialized subsea engineering partnerships with Vietnamese-registered affiliates to satisfy local content mandates while transferring technical capability.
For Investors and Strategic Acquirers: The market sits at a licensing acceleration phase that favors operators with proven deepwater execution and existing regulator relationships. Long-term viability hinges on portfolio exposure to gas-weighted assets with power utility offtake agreements rather than oil-dependent export volumes. Watch State Bank of Vietnam foreign exchange policy adjustments as the inflection signal for international consortium capital deployment appetite.
| Strategic Initiative | Industry Significance |
|---|---|
| Joint Venture Formation with Local Affiliates | PetroVietnam partnership structures satisfy revised petroleum legislation domestic participation mandates for block awards. |
| Enhanced Oil Recovery Technology Deployment | Gas injection and chemical flooding unlock stranded reserves in Cuu Long basin fractured carbonate reservoirs. |
| Subsea Engineering Talent Development | Vietnamese technical university partnerships address pipeline constraints for high-pressure reservoir intervention capabilities. |
| Integrated Service Contracting | Single-source agreements transfer reservoir performance risk while reducing interface complexity for marginal field operators. |
| Power Purchase Agreement Structuring | Long-term offtake contracts with EVN and industrial gas consumers anchor project finance for Nam Con Son developments. |
Research Methodology
A spread of perspectives from upstream project managers, subsea engineering directors, procurement leads at international operators, and regulatory affairs specialists at PetroVietnam converged on the working assumptions for this analysis. Primary interview findings were validated against secondary sources including Vietnam Ministry of Industry and Trade licensing round announcements, National Assembly petroleum legislation amendments, State Bank of Vietnam foreign exchange circulars, and ASEAN offshore safety protocol documentation. Bottom-up field-level production estimates were triangulated with top-down basin-wide capacity assessments.
Demand-supply balance modeling across the projection horizon incorporated service type segmentation, technology deployment trajectories, and end-user contract structures. The analytical framework modeled exploration, drilling, production, and well services as distinct revenue pools with differential growth profiles. Segmentation dimensions included service type, technology tier, end-user category, and geographic application across Vietnam's southern continental shelf. CAGRs were derived from production decline curve analysis, licensing round timing assumptions, and power generation capacity expansion schedules. Forecast inputs integrated reservoir maturity profiles, domestic gas supply obligation enforcement intensity, and LNG import terminal development timelines.
Sensitivities concentrate around State Bank of Vietnam foreign exchange repatriation rule adjustments, Ministry of Industry and Trade local content enforcement intensity, and global LNG price benchmark movements. Forecasts reflect assumptions regarding licensing round award timing, power utility offtake contract finalization, and subsea equipment supplier capacity availability. Material shifts in petroleum legislation fiscal terms or ASEAN regional safety protocol harmonization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Netherlands LNG Bunkering Market
Oil & Gas
Perforating Gun Market
Oil & Gas
Oil and Gas Accumulators Market
Oil & Gas
Wellhead Equipment Market
Oil & Gas
Asia-Pacific AI in Oil and Gas Market
Oil & Gas
Oilfield Equipment Rental Services Market
Oil & Gas
Coal Seam Gas Market
Oil & Gas
Shale Gas Hydraulic Fracturing Market
Oil & Gas
Seismic Survey Equipment Market
Oil & Gas
Land Drilling Rig Market
Oil & Gas
LNG Storage Tank Market
Oil & Gas
Small Scale LNG (SSLNG) Market
Oil & Gas
Drilling Fluids Market
Oil & Gas
Romania Oil and Gas Market
Oil & Gas
Thermal Spray Coating for Oil and Gas Market
Oil & Gas
Enhanced Gas Recovery (EGR) Market