
 Fluoro Enzymatic Assays Market | 2026-2036
Fluoro Enzymatic Assays Market Size, Share, and Industry Trends Forecast 2026-2036
Fluoro Enzymatic Assays Market Analysis
The capability gap between integrated platform providers and reagent-only suppliers is unwinding competitive stability in fluoro enzymatic assays. Thermo Fisher Scientific leverages its fluorescence microscopy and detection kit portfolios to anchor North American lab contracts. Bio-Rad Laboratories specializes in flow cytometry-based assay workflows for clinical diagnostics customers. Merck KGaA controls European distribution of high-purity assay reagents through its life science chemicals network.
Fluoro enzymatic assays employ fluorophore-conjugated substrates or antibodies that emit quantifiable light signals upon enzymatic cleavage or binding, achieving detection limits in the picomolar range for protein and nucleic acid targets. These systems serve pharmaceutical screening, clinical biomarker detection, and environmental contaminant monitoring where sensitivity and throughput requirements exceed colorimetric methods. Detection kits capture the largest margin pool due to recurring consumable demand and proprietary formulation lock-in, while high-throughput screening applications in drug discovery represent the fastest-expanding revenue segment. Flow cytometry technology leads clinical adoption for multiplexed cellular analysis, whereas ELISA-format fluoro assays dominate regulated diagnostic environments requiring standardized workflows.
FDA 510(k) clearance pathways and EMA in vitro diagnostic regulations shape product development timelines and validation costs for assay manufacturers seeking clinical market access. ISO 13485 quality management standards and EU MDR technical documentation requirements further constrain market entry for reagent producers without established regulatory infrastructure. Stakeholders must monitor evolving companion diagnostic labeling requirements and decentralized testing reimbursement policies to align R&D portfolios with addressable demand.
Market Dynamics
Companion diagnostic validation requirements from FDA and EMA are compressing development timelines for assay developers while simultaneously raising the performance threshold for market entry. This regulatory tightening is forcing consolidation among reagent suppliers lacking in-house quality infrastructure.
Growth Catalysts
- EMA In Vitro Diagnostic Regulation:The EU MDR framework mandates higher analytical sensitivity standards for clinical biomarker assays, accelerating replacement of colorimetric methods with fluorescence-based detection in European reference laboratories.
- Pharmaceutical R&D Concentration:Centralized high-throughput screening facilities in the United States, Germany, and China are expanding fluorescence detection capacity to support biologics pipeline growth.
- Flow Cytometry Multiplexing:Clinical laboratories are adopting multi-parameter cellular analysis workflows that integrate fluoro enzymatic readouts for simultaneous cytokine quantification and cell surface marker detection.
Market Restraints
- Fluorophore Supply Concentration:High-purity reactive dyes for assay conjugation are manufactured by a limited supplier base in Switzerland and Germany, creating input cost volatility and batch-to-batch consistency risks.
- ISO 13485 Certification Burden:Small reagent producers without established quality management systems face 18-24 month compliance timelines and substantial documentation costs to serve clinical diagnostic customers.
- Digital PCR Substitution:Absolute nucleic acid quantification methods are displacing fluoro enzymatic approaches in oncology companion diagnostic applications where copy number precision is critical.
Strategic Opportunities
- Decentralized Testing Infrastructure:Point-of-care diagnostic networks in India and Brazil present untapped demand for lyophilized, ambient-stable fluoro assay formats that bypass cold-chain distribution requirements.
- Environmental Contaminant Monitoring:Water utilities and agricultural regulators are adopting enzyme-linked fluorescence assays for pesticide and mycotoxin detection where rapid field screening replaces laboratory send-out.
- Artificial Intelligence-Assisted Analysis:Machine learning algorithms for fluorescence signal deconvolution are enabling multiplexed assay panels that were previously analytically intractable, opening new clinical application areas.
Industry Challenges
- Cross-Functional Talent Scarcity:Assay developers struggle to recruit scientists with combined expertise in enzymology, fluorophore chemistry, and regulatory submission writing.
- Legacy Instrument Compatibility:Hospital laboratories with installed bases of 5-10 year old fluorescence plate readers demand assay formats backward-compatible with obsolete optical specifications.
- Reagent Stability Validation:Extended shelf-life claims require real-time aging studies that extend product launch timelines by 12-18 months for clinical diagnostic applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluoro Enzymatic Assays Market |
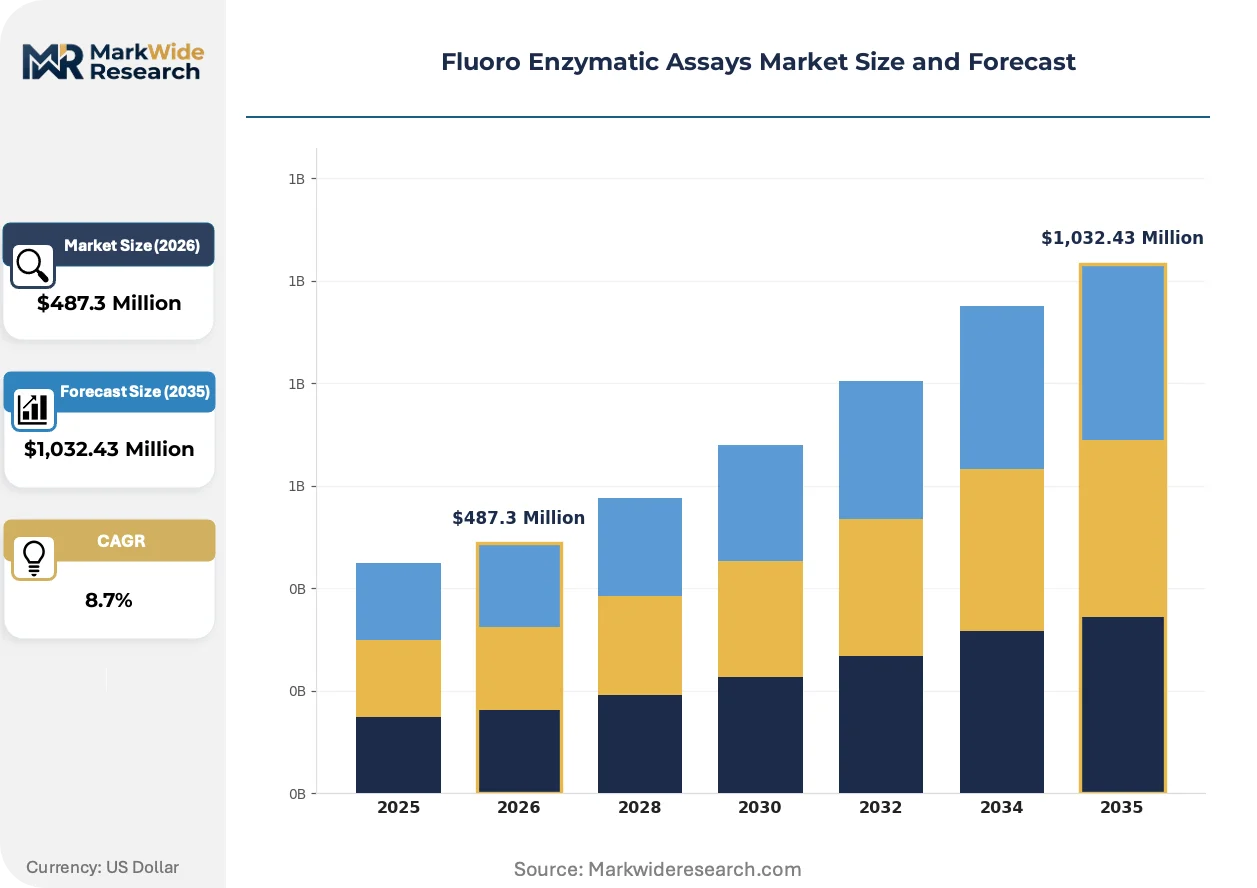
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fluorescent Probes, Detection Kits, Assay Reagents, Control Samples Application: Clinical Diagnostics, Drug Discovery, Environmental Testing, Food Safety End User: Clinical Laboratories, Research Institutions, Pharmaceutical Companies, Biotechnology Firms Technology: Fluorescence Microscopy, Flow Cytometry, ELISA, High-Throughput Screening |
| Companies Covered | Thermo Fisher Scientific, Bio-Rad Laboratories, Merck KGaA, PerkinElmer, Promega Corporation, Siemens Healthineers, Abbott Laboratories, Danaher Corporation, Becton, Dickinson and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluoro Enzymatic Assays Market Emerging Trajectories
Fluorescence detection architectures are fragmenting into specialized modalities optimized for distinct throughput and sensitivity requirements. This specialization is eroding the dominance of general-purpose platforms and creating distinct competitive arenas.
Time-resolved fluorescence resonance energy transfer (TR-FRET) is bifurcating the homogeneous assay segment from traditional heterogeneous ELISA workflows. Biopharma screening groups are adopting TR-FRET for kinase and protease inhibitor profiling where wash-free protocols accelerate compound evaluation. The technology is compressing assay development timelines from weeks to days while displacing radiometric methods in safety pharmacology panels.
REACH authorization requirements for novel fluorophore chemistries are constraining molecular innovation in European reagent supply chains. Manufacturers are reformulating with pre-registered dye scaffolds rather than pursuing new chemical entity approvals. Clinical diagnostic kit producers are responding by standardizing on established fluorescein and rhodamine derivatives, accepting performance trade-offs to secure supply continuity.
Hospital procurement committees are consolidating vendor relationships to reduce qualification overhead and streamline service contracts. Integrated platform providers capturing multi-year reagent supply agreements are displacing standalone detection kit suppliers in United States health system tenders. This concentration is most visible in academic medical centers where capital equipment and consumable budgets have merged under single sourcing committees.
Fluoro Enzymatic Assays Market Segmentation
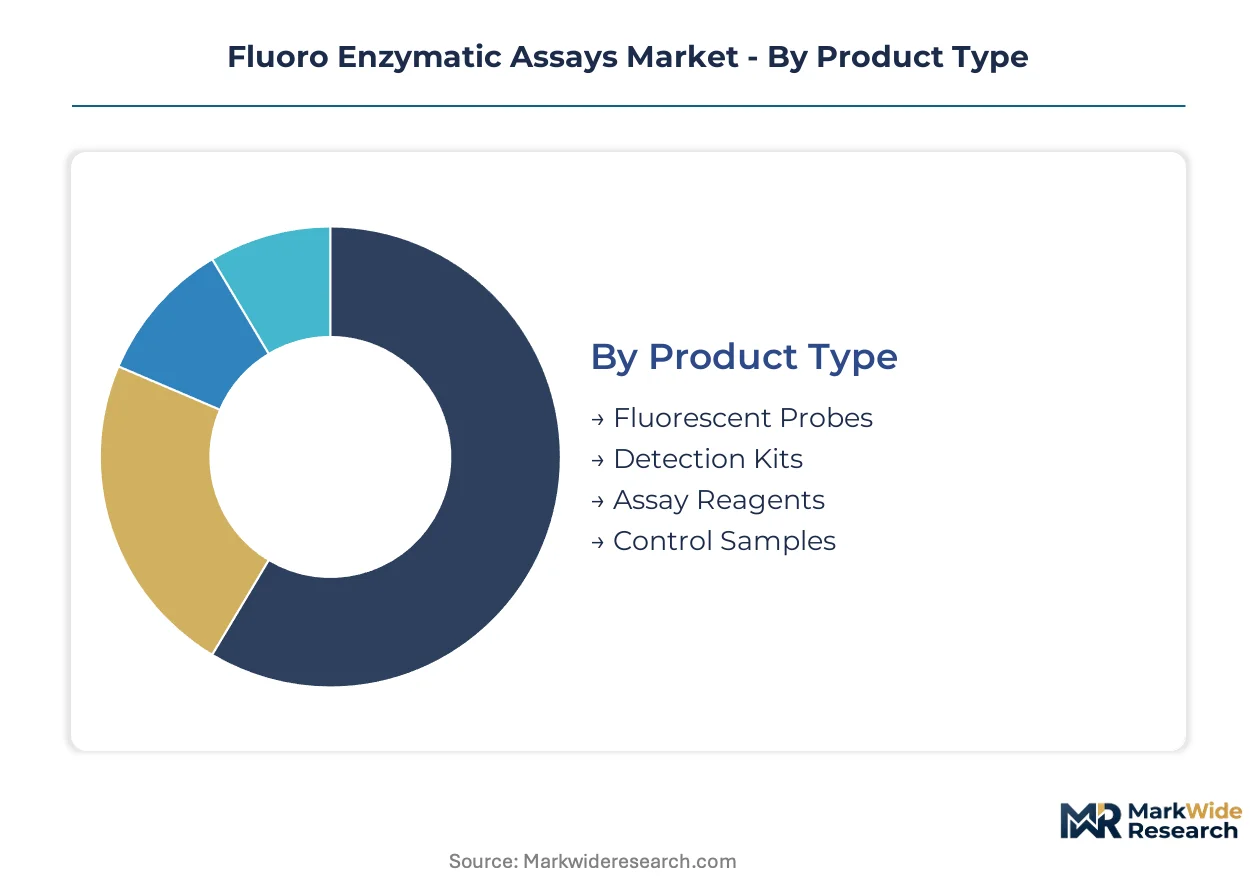
Segmentation in fluoro enzymatic assays reveals how regulatory complexity, end-use workflows, and optical platform requirements fragment purchasing decisions across customer types. Each dimension carries distinct margin profiles and validation burdens that shape supplier positioning.
Product Type:
FDA 510(k) clearance pathways and EMA MDR technical documentation requirements create divergent commercial barriers across product formats, with clinical-grade consumables demanding substantially higher quality infrastructure than research-use offerings.
- Detection Kits:Proprietary buffer formulations and pre-optimized fluorophore-antibody conjugates command recurring revenue streams through locked-in reagent contracts. Hospital laboratory consolidation in the United States and centralized reference labs in Germany favor integrated kit suppliers over component vendors.
- Fluorescent Probes:Reactive dye chemistries for custom assay development require REACH-registered scaffolds in Europe, constraining molecular innovation. Academic research institutions in China and contract research organizations in the United States drive spot purchasing of high-purity, lot-consistent probe libraries.
- Assay Reagents:Enzyme substrates, cofactors, and stabilization buffers support in-house assay development workflows with lower regulatory overhead.
- Control Samples:Certified reference materials for assay calibration and validation carry ISO 17034 accreditation requirements that limit supplier base.
Established volume favors Detection Kits; emerging adoption favors Fluorescent Probes.
Application:
Cost tier differentiation separates regulated diagnostic environments requiring extensive validation documentation from exploratory research settings prioritizing speed and flexibility.
- Clinical Diagnostics:FDA-cleared and EMA-authorized assays for infectious disease, oncology biomarkers, and cardiac markers demand ISO 13485 quality systems and real-time stability studies. United States health system procurement committees and European hospital networks concentrate purchasing among qualified suppliers with established regulatory track records.
- Drug Discovery:High-throughput screening of kinase inhibitors, protease targets, and GPCR modulators favors homogeneous assay formats that compress compound evaluation timelines. Biopharma R&D facilities in the United States, Germany, and China are expanding fluorescence detection capacity to support biologics pipeline growth.
- Environmental Testing:Water utilities and agricultural regulators adopt enzyme-linked fluorescence for pesticide and mycotoxin field screening where rapid detection replaces laboratory send-out.
- Food Safety:Pathogen detection and contaminant quantification in processing facilities require ruggedized assay formats with simplified workflows for non-specialist operators.
Margin concentration sits with Clinical Diagnostics; steepest expansion trajectory belongs to Drug Discovery.
End User:
Customer type determines purchasing authority structure, with consolidated health systems and multinational pharmaceutical companies exerting substantially different negotiation leverage than fragmented academic buyers.
- Clinical Laboratories:Hospital-based and reference laboratories in the United States, Germany, and China drive demand for standardized, FDA-cleared or EMA-authorized assay workflows. These customers prioritize instrument-reagent compatibility and multi-year service contracts over component pricing.
- Pharmaceutical Companies:Centralized screening facilities and safety pharmacology groups require high-throughput compatible formats with validated performance across compound libraries. Thermo Fisher Scientific and Bio-Rad Laboratories anchor North American contracts through integrated platform offerings.
- Research Institutions:Academic laboratories with federal funding constraints favor modular, open-architecture reagent systems that support publication-driven assay customization.
- Biotechnology Firms:Emerging biologics developers with pipeline-stage programs prioritize rapid assay development timelines over regulatory pre-certification.
Contract value concentrates with Clinical Laboratories; procurement flexibility favors Research Institutions.
Technology:
Platform maturity creates distinct competitive arenas, with established optical specifications in installed hospital instruments constraining assay format innovation.
- Flow Cytometry:Multi-parameter cellular analysis integrating fluoro enzymatic readouts enables simultaneous cytokine quantification and surface marker detection. Clinical laboratories in the United States and academic medical centers in Germany lead adoption for immunophenotyping and minimal residual disease monitoring.
- ELISA:Heterogeneous sandwich and competitive assay formats dominate regulated diagnostic environments requiring standardized, FDA-cleared workflows. The format's established validation templates and extensive clinical evidence base sustain preference in hospital laboratories with 5-10 year old fluorescence plate readers.
- High-Throughput Screening:Homogeneous TR-FRET and AlphaScreen formats displace radiometric methods in biopharma safety pharmacology panels.
- Fluorescence Microscopy:Imaging-based quantification supports spatial biology applications and subcellular localization studies in research settings.
Installed base dominance favors ELISA; capability expansion favors Flow Cytometry.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity in fluoro enzymatic assays diverges sharply across geographies. Academic laboratories in India and Brazil negotiate aggressively on reagent costs, while United States health systems prioritize multi-year service contracts over unit pricing.
United States
Hospital laboratory consolidation and biopharma R&D concentration drive premium-tier demand. FDA 510(k) clearance pathways shape product development timelines for clinical diagnostic suppliers. The Boston-Cambridge biotech cluster anchors high-throughput screening facility expansion for kinase inhibitor programs.
Germany
Centralized reference laboratory networks and stringent analytical standards sustain demand for EMA-authorized assay workflows. EU MDR technical documentation requirements compress the qualified supplier base. The Rhine-Main metropolitan region concentrates fluorescence detection platform manufacturing and reagent distribution infrastructure.
China
Domestic biologics pipeline growth and hospital laboratory automation investments accelerate fluorescence detection capacity expansion. NMPA in vitro diagnostic regulations are tightening quality management requirements for imported reagents. The Yangtze River Delta biopharma corridor hosts expanding contract research organizations adopting TR-FRET screening formats.
Switzerland
High-purity fluorophore manufacturing and precision chemical supply chains anchor the reagent input tier. REACH authorization requirements for novel dye chemistries constrain molecular innovation among European formulators. The Basel pharmaceutical cluster sustains demand for certified reference materials and assay validation services.
India
Point-of-care diagnostic network expansion and federal health program procurement create volume opportunities for ambient-stable assay formats. CDSCO medical device regulations are converging with international standards for clinical biomarker tests. The Hyderabad-Genome Valley life sciences cluster attracts contract manufacturing organizations serving Middle Eastern and African export markets.
Fluoro Enzymatic Assays Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in fluoro enzymatic assays. Platform providers with captive reagent portfolios capture multi-year hospital contracts through bundled instrumentation and consumable agreements. Specialist reagent suppliers compete on custom conjugation services and rapid turnaround for research-use applications. Consolidation pressures mount as ISO 13485 certification requirements and FDA validation costs favor scaled quality infrastructure. Geographic expansion into decentralized testing markets and technology licensing partnerships represent the dominant competitive moves reshaping vendor positioning.
Within the integrated platform tier, Thermo Fisher Scientific exemplifies North American market anchoring through fluorescence microscopy and detection kit portfolios. Bio-Rad Laboratories occupies a specialist position in flow cytometry-based assay workflows. Merck KGaA represents European reagent supply chain control through life science chemicals distribution networks. These three entities illustrate how geographic origin and corporate structure correlate with competitive archetype in this market.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| Merck KGaA |
| PerkinElmer |
| Promega Corporation |
| Siemens Healthineers |
| Abbott Laboratories |
| Danaher Corporation |
| Becton, Dickinson and Company |
| Others |
Supply Flow & Price Mechanics
Twenty-four to thirty-six month reagent stability validation timelines compress inventory turns and amplify working capital intensity, concentrating pricing power with integrated platform vendors that amortize regulatory costs across multi-year hospital contracts while fragmenting margin pools among standalone detection kit suppliers.
Pricing Analysis
After-sales reagent supply agreements capture the dominant lifetime value share in this market, with multi-year consumable contracts generating recurring revenue streams that dwarf initial instrument placement economics. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared clinical diagnostics from research-use reagents and unvalidated probe libraries. Price differentiation hinges on ISO 13485 certification tier and after-sales service bundling. Cost compression in the research-use probe segment is intensifying because academic buyers negotiate aggressively on spot purchases. Biotechnology firms and contract research organizations exhibit the highest price sensitivity, while United States health systems prioritize instrument-reagent compatibility over unit pricing.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for fluorophore raw materials, compressing margins for reagent formulators without captive dye manufacturing. High-purity reactive dye production concentrates in Switzerland and Germany, with enzyme substrate synthesis anchored in the United States and China. Supply chains draw from rhodamine derivatives, fluorescein scaffolds, and rare-earth cryptates as critical inputs. Single-source vulnerability in Swiss fluorophore manufacturing creates structural risk for European assay developers. Distribution runs through life science chemicals networks, direct hospital procurement committees, and academic purchasing consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as TR-FRET screening formats displace radiometric methods across biopharma safety pharmacology panels, opening penetration headroom in high-throughput drug discovery workflows.
For Market Incumbents: Consolidate regulatory infrastructure advantages by acquiring ISO 13485-certified reagent specialists in Germany and Switzerland, neutralizing emerging entrants that lack quality management scale. Deepen backward integration into high-purity fluorophore manufacturing to offset supply concentration risk from Swiss and German dye suppliers. Channel control through multi-year hospital system contracts remains the priority lever against standalone kit vendors.
For New Entrants and Emerging Players: Anchor in decentralized testing networks across India and Brazil where ambient-stable lyophilized formats bypass cold-chain requirements and incumbent platform bundling. Point-of-care diagnostic procurement by federal health programs represents the most penetrable demand tier. A go-to-market angle emphasizing simplified workflows for non-specialist operators unlocks volume in environmental monitoring and food safety applications.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across clinical-grade assay development as FDA 510(k) validation timelines extend and real-time stability studies consume R&D budgets. The five-to-ten year viability window favors scaled platform providers with captive reagent portfolios over standalone component suppliers. Acquisition targets should display established regulatory track records in multiple geographies. The signal to watch is NMPA authorization progress for imported reagents in China, which would validate geographic diversification strategies.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Certification Investment | ISO 13485 and FDA 510(k) infrastructure captures multi-year hospital contracts in United States health systems. |
| Fluorophore Manufacturing Integration | Backward integration into high-purity dye production neutralizes Swiss and German supply concentration risk. |
| Decentralized Testing Format Development | Ambient-stable lyophilized assays unlock point-of-care procurement in India and Brazil federal programs. |
| TR-FRET Platform Expansion | Homogeneous assay formats accelerate biopharma screening timelines and displace radiometric safety pharmacology methods. |
| AI-Assisted Signal Analysis Partnership | Machine learning deconvolution enables previously intractable multiplexed panels for clinical biomarker applications. |
Methodological Framework
The analysis maps detection kits, fluorescent probes, assay reagents, and control samples, each validated through assay development scientists, clinical laboratory directors, regulatory affairs specialists, and hospital procurement managers. Primary interviews with these stakeholders combined with secondary validation from FDA 510(k) filings, EMA MDR technical documentation, ClinicalTrials.gov assay utilization data, and ISO 13485 certification databases. Bottom-up and top-down triangulation cross-checks segment-level revenue estimates against instrument placement counts and reagent consumption rates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models product type, application workflow, end-user purchasing authority, and technology platform specifications as core segmentation dimensions. CAGRs were derived from regression analysis of historical adoption curves and forward projection of biopharma R&D facility expansion. Forecast inputs include fluorescence detection instrument shipment data and companion diagnostic validation pipeline tracking.
Material uncertainties — regulatory timeline delays, fluorophore supply disruptions, digital PCR substitution acceleration — sit outside the modeled envelope. Forecasts reflect assumptions about EMA MDR enforcement consistency and NMPA authorization pathway stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Global Neuroscience Antibodies and Assays Market
Biomedical Technology
Austria Flow Cytometry Market
Biomedical Technology
In Vitro Protein Expression Market
Biomedical Technology
ST2 Biomarker Market
Biomedical Technology
Global Cell Based Assays Market
Biomedical Technology
Cell Disrupters Market
Biomedical Technology
North America Exosome Research Products Market
Biomedical Technology
Global Immunofluorescence Assay Market
Biomedical Technology
Needle Based Biopsy Guns Market
Biomedical Technology
Polymerase Chain Reaction (PCR) Market
Biomedical Technology
Global Protein Crystallization and Crystallography Market
Biomedical Technology
Global Primary Cell Culture Market
Biomedical Technology
Global Plant Stem Cell Market
Biomedical Technology
Global Ligation Market
Biomedical Technology
Biochips Market
Biomedical Technology
Asia-Pacific Biomedical Sensors Market