
 RNA Transcriptome Profiling Test Market | 2026-2036
RNA Transcriptome Profiling Test Market Size, Share, and Industry Trends Forecast 2026-2036
RNA Transcriptome Profiling Test Market Analytics
Modular assay panels is broadening buyer choice in the RNA transcriptome profiling test market. Thermo Fisher Scientific leverages its end-to-end platform ecosystem to anchor clinical research workflows. Illumina dominates high-throughput sequencing instrumentation, while QIAGEN specializes in sample preparation and bioinformatics pipelines that sustain recurring revenue streams.
RNA transcriptome profiling tests measure the complete set of RNA transcripts in a biological sample using next-generation sequencing or hybridization-based detection, typically requiring nanogram-scale RNA input and library preparation workflows to quantify gene expression, splicing variants, and non-coding RNA species for disease characterization and therapeutic guidance. Oncology applications command the deepest installed base and reimbursement coverage, though single-cell sequencing exhibits the steepest adoption curve as researchers dissect tumor heterogeneity. Research laboratories represent the most mature end-user channel with established procurement budgets, while diagnostic centers are emerging as a higher-margin growth pocket where regulatory clearance creates pricing power.
The FDA, EMA, and ISO 15189 standards collectively shape analytical validation requirements, reimbursement pathways, and laboratory accreditation for clinical transcriptome testing. These frameworks determine which platforms gain market access and which assays qualify for companion diagnostic labeling. Stakeholders must track evolving regulatory precedents for liquid biopsy transcriptome applications and anticipate how payer coverage policies will partition between research-use-only and clinically validated test categories.
Market Dynamics
The FDA's expanding companion diagnostic guidance is compressing validation timelines while academic medical centers build dedicated transcriptomics infrastructure, creating a bifurcation between research-grade and clinically validated assay tiers.
Growth Catalysts
- Companion diagnostic mandates:The FDA's guidance on RNA-based companion diagnostics pushes laboratories toward validated assays, expanding reimbursable testing volumes in oncology workflows.
- Single-cell resolution demand:Cancer researchers dissecting tumor heterogeneity are driving adoption of higher-complexity transcriptome platforms requiring specialized bioinformatics pipelines.
- Integrated health networks:United States-based academic medical centers are constructing dedicated transcriptomics infrastructure, anchoring procurement budgets for end-to-end platform ecosystems.
Market Restraints
- Reagent supply concentration:Critical enzymes and modified nucleotides for library preparation concentrate among a handful of specialized chemical suppliers, exposing workflows to input volatility.
- Bioinformatics bottleneck:The scarcity of computational biologists capable of clinical-grade pipeline validation constrains assay commercialization timelines regardless of sequencing hardware availability.
- ISO 15189 accreditation friction:Clinical laboratories face extended timelines and capital requirements for accreditation, filtering which transcriptome tests achieve diagnostic-grade status.
Strategic Opportunities
- Liquid biopsy transcriptome expansion:Circulating tumor RNA profiling represents underpenetrated white space where regulatory precedents remain unsettled, offering first-mover positioning.
- Modular assay panel architectures:Configurable gene sets allowing laboratories to scale content breadth without platform switching are capturing procurement preference in mid-volume settings.
- EMA regulatory harmonization:Converging European Medicines Agency and FDA validation standards is reducing duplicate clinical studies for transatlantic assay commercialization.
Industry Challenges
- Multi-omics integration complexity:Combining transcriptome data with proteomic and genomic layers requires interoperable data standards that remain technically immature.
- Variant interpretation workforce scarcity:The gap between raw sequencing output and clinically actionable reports depends on molecular pathologists trained in RNA-specific variant classification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RNA Transcriptome Profiling Test Market |
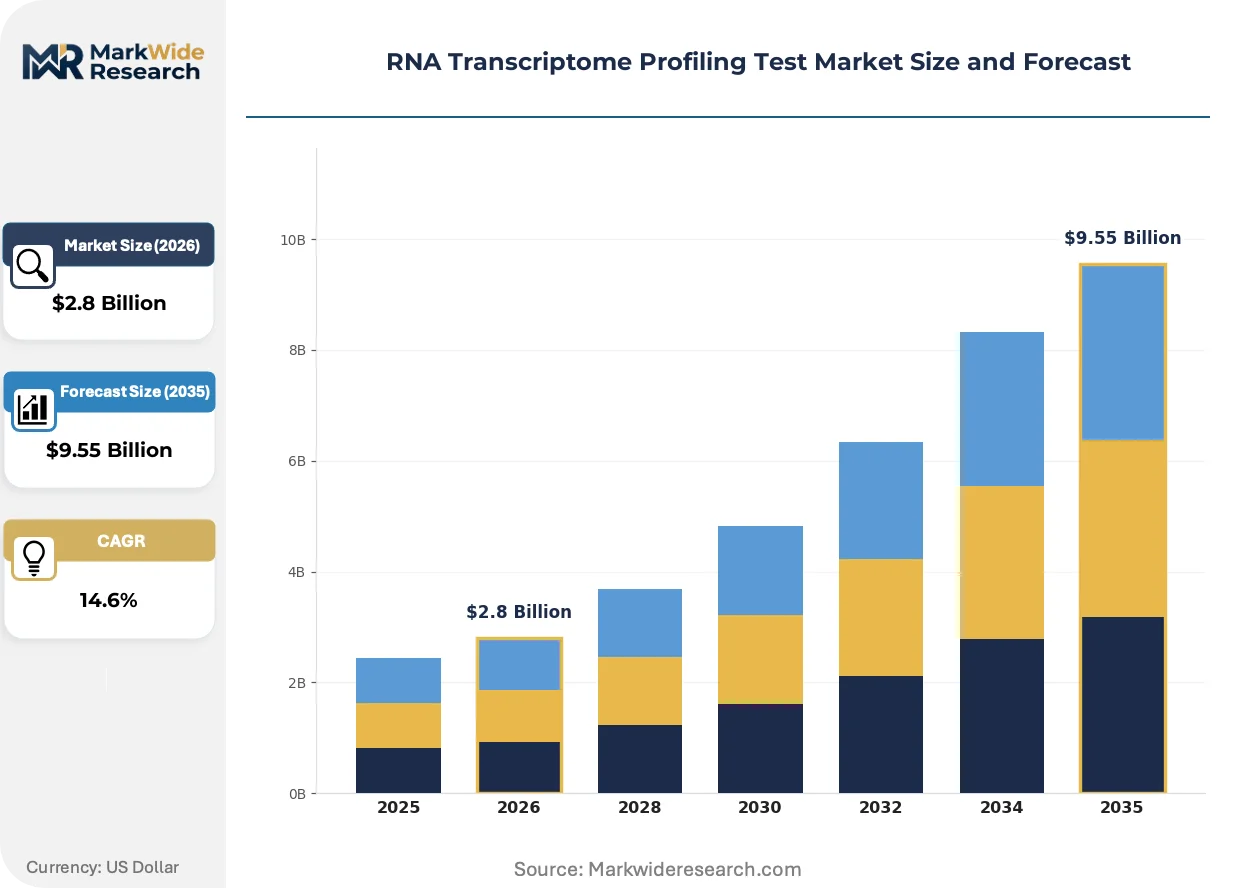
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microarrays, RNA-Seq, qPCR, Single-Cell Sequencing Application: Oncology, Neurology, Cardiology, Infectious Disease End User: Research Laboratories, Hospitals, Diagnostic Centers, Academic Institutions Technology: Next-Generation Sequencing, Real-Time PCR, Microarray Technology, Capillary Electrophoresis |
| Companies Covered | Thermo Fisher Scientific, F. Hoffmann-La Roche, Illumina, QIAGEN, Agilent Technologies, Bio-Rad Laboratories, Eurofins Scientific, Merck KGaA, 10x Genomics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RNA Transcriptome Profiling Test Market Evolving Landscape
Spatial transcriptomics is collapsing the resolution gap between tissue morphology and gene expression mapping, while regulatory pressure on analytical validation is forcing platform consolidation around interoperable standards.
Spatial transcriptomics technology is electrifying oncology research by preserving tissue architecture during RNA capture. Pathology departments at major cancer centers are adopting these platforms at compressed procurement cycles compared to prior sequencing generations. The technology is electrifying competitive positioning by enabling biomarker discovery programs that were technically inaccessible with bulk tissue methods.
The FDA's draft guidance on tumor mutational burden and microsatellite instability testing is tightening analytical validation requirements for RNA-based oncology assays. Clinical laboratories must now demonstrate traceable reference materials and cross-platform concordance before companion diagnostic labeling. This regulatory shift most directly affects transcriptome assay developers targeting non-small cell lung cancer and colorectal cancer indications.
Consolidated procurement by integrated delivery networks is displacing individual laboratory purchasing autonomy. Hospital systems are negotiating enterprise sequencing contracts that bundle instrumentation, reagents, and bioinformatics support across multiple sites. This buyer concentration is most visible in the United States, where academic medical centers and community hospital networks are converging on single-vendor platform ecosystems to reduce interoperability costs.
RNA Transcriptome Profiling Test Market Segmentation
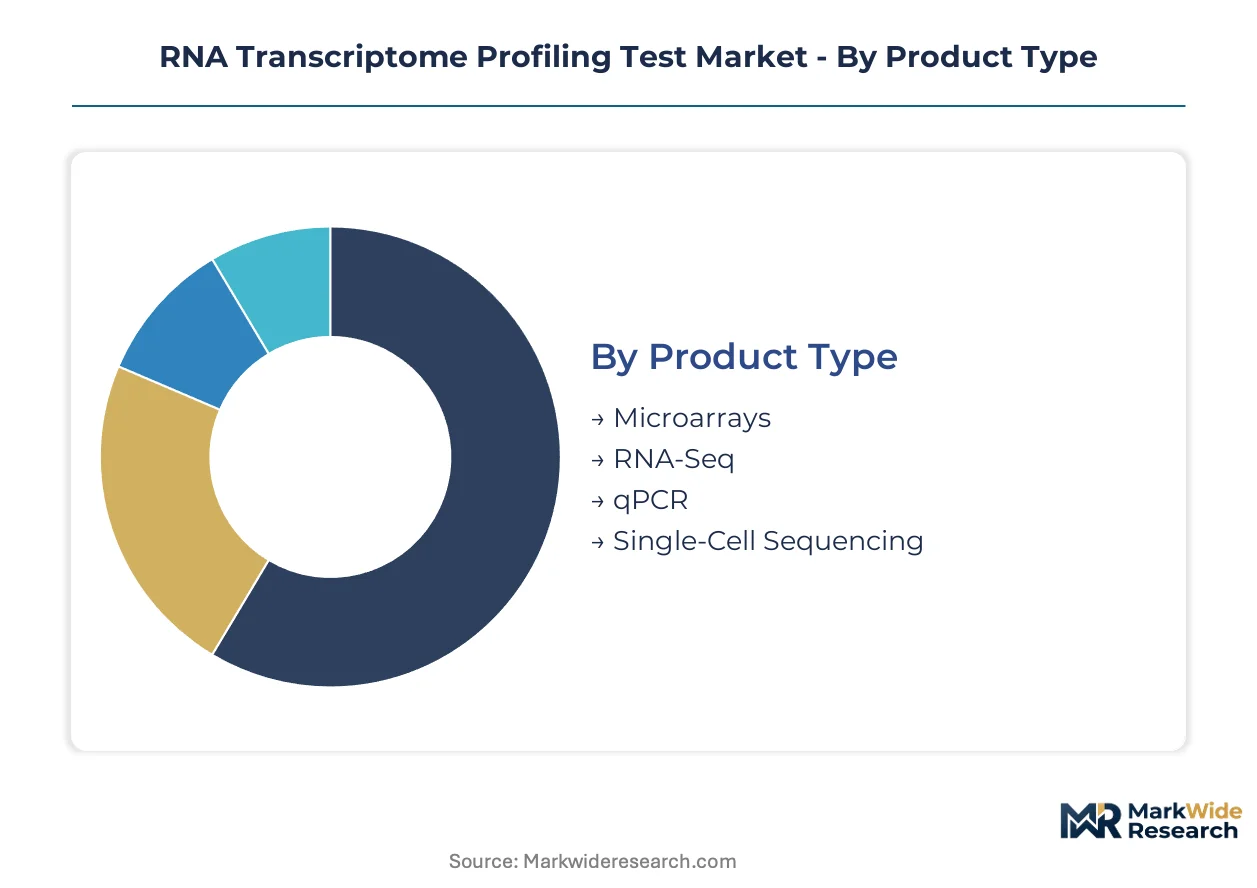
RNA transcriptome profiling test segmentation reveals distinct procurement patterns across technology platforms and clinical settings. Laboratories select instrumentation based on throughput requirements, regulatory status, and bioinformatics infrastructure capacity.
Product Type:
Customization versus standardization tension runs deepest in product type selection, with modular panel architectures challenging fixed-content platforms.
- Microarrays:Hybridization-based detection platforms quantify predefined gene sets using fluorescently labeled cDNA probes. Established clinical laboratories in the United States favor microarrays for validated oncology gene expression signatures where reimbursement pathways are codified.
- RNA-Seq:Next-generation sequencing approaches capture complete transcriptomes without probe design constraints, enabling novel isoform discovery. Academic medical centers in Germany and the United States drive RNA-Seq procurement for research-grade tumor profiling where discovery flexibility outweighs turnaround time.
- qPCR:Quantitative PCR delivers rapid, cost-effective expression analysis for targeted gene panels.
- Single-Cell Sequencing:Droplet-based and microwell platforms resolve transcriptomes at individual cell resolution.
Leading the category by volume: RNA-Seq. Growing fastest: Single-Cell Sequencing.
Application:
Oncology commands the deepest reimbursement coverage while infectious disease applications accelerate on pandemic-era infrastructure investments.
- Oncology:Tumor profiling for diagnostic classification, prognostic stratification, and therapeutic selection constitutes the primary revenue base. FDA companion diagnostic mandates for non-small cell lung cancer and colorectal cancer indications anchor clinical transcriptome adoption in United States health systems.
- Neurology:Neurodegenerative disease biomarker discovery and psychiatric pharmacogenomics represent emerging clinical translation opportunities. Research consortia in Switzerland and the Netherlands drive neuro-transcriptome platform procurement for longitudinal cohort studies.
- Cardiology:Cardiac transcriptome profiling supports heart failure subtyping and transplant rejection monitoring.
- Infectious Disease:Pathogen transcriptome detection and host response profiling gained regulatory traction during respiratory virus surveillance expansion.
Expanding most quickly: Infectious Disease. Anchoring revenue concentration: Oncology.
End User:
Capital intensity and accreditation requirements fragment procurement autonomy across institutional tiers.
- Research Laboratories:University and government facilities with established genomics cores represent the most mature channel. Laboratories in California and Massachusetts sustain multi-platform ecosystems through National Institutes of Health instrumentation grants.
- Hospitals:Integrated health networks are consolidating enterprise sequencing contracts across oncology, pathology, and precision medicine departments. Hospital systems in Texas and Florida negotiate bundled reagent and bioinformatics agreements.
- Diagnostic Centers:Independent reference laboratories pursue ISO 15189 accreditation for clinically validated transcriptome testing.
- Academic Institutions:Medical school-affiliated research centers bridge discovery and clinical translation.
Highest margin capture: Diagnostic Centers. Deepest installed base: Research Laboratories.
Technology:
Platform interoperability standards are displacing point-solution procurement as health systems consolidate vendor relationships.
- Next-Generation Sequencing:Massively parallel sequencing dominates high-complexity transcriptome analysis. Illumina instrument installations at major cancer centers in the United States and United Kingdom anchor platform ecosystem lock-in.
- Real-Time PCR:Quantitative amplification technology sustains clinical adoption for targeted expression panels. Diagnostic manufacturers in South Korea and Germany supply qPCR chemistries for regulated IVD workflows.
- Microarray Technology:Solid-phase hybridization platforms retain cost advantages for standardized gene sets.
- Capillary Electrophoresis:Fragment analysis supports targeted RNA sizing and quality control applications.
Steepest expansion trajectory: Next-Generation Sequencing. Maintaining steady replacement demand: Real-Time PCR.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Research Triangle Park in North Carolina and Kendall Square in Massachusetts anchor North American transcriptomics infrastructure investment through state-level life sciences tax credits and NIH instrumentation grants.
United States
Academic medical centers in Boston and Houston drive platform procurement for oncology companion diagnostic workflows. FDA guidance on RNA-based companion diagnostics compresses validation timelines for non-small cell lung cancer assays. The Texas Medical Center anchors enterprise sequencing contracts bundling instrumentation and bioinformatics support.
Germany
Research consortia in Heidelberg and Munich sustain multi-platform ecosystems for tumor heterogeneity studies. EMA regulatory harmonization with FDA standards reduces duplicate clinical studies for transatlantic assay commercialization. The BioRN network in the Rhine-Neckar region concentrates single-cell sequencing adoption.
United Kingdom
Cancer Research UK-funded centers in London and Cambridge drive RNA-Seq procurement for discovery-grade tumor profiling. MHRA alignment with FDA tumor mutational burden guidance tightens analytical validation requirements. The Cambridge cluster anchors spatial transcriptomics platform installations.
China
Hospital precision medicine programs in Shanghai and Beijing expand clinical transcriptome testing capacity. NMPA regulatory pathways for innovative diagnostic reagents create domestic commercialization opportunities. The Zhangjiang Hi-Tech Park concentrates next-generation sequencing instrument manufacturing.
Switzerland
Neurodegenerative disease research consortia in Zurich and Geneva drive neuro-transcriptome platform procurement. Swissmedic accreditation requirements for clinical laboratories filter diagnostic-grade assay status. The Basel region anchors pharmaceutical companion diagnostic development partnerships.
RNA Transcriptome Profiling Test Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across platform ecosystem and point-solution positioning. The market structure concentrates around three tiers: end-to-end platform providers, sample-to-data workflow specialists, and niche technology developers. Strategic archetypes include instrumentation-heavy conglomerates anchoring hospital procurement, bioinformatics-forward specialists capturing recurring revenue, and modular panel architects serving mid-volume laboratories. Competitive moves center on enterprise contract consolidation and regulatory co-development partnerships with pharmaceutical sponsors.
Within the instrumentation tier, Thermo Fisher Scientific and Illumina occupy positions as anchor vendors for integrated health network procurement. QIAGEN exemplifies the sample-to-data workflow specialist archetype, sustaining recurring revenue through reagent and bioinformatics pipelines. These three companies represent the dominant competitive positioning vectors shaping hospital system vendor selection criteria.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| F. Hoffmann-La Roche |
| Illumina |
| QIAGEN |
| Agilent Technologies |
| Bio-Rad Laboratories |
| Eurofins Scientific |
| Merck KGaA |
| 10x Genomics |
| Others |
Value Network & Pricing Analysis
ISO 15189 laboratory accreditation mandates gate qualified supply access for clinical-grade transcriptome assays, with only certified reagent manufacturers commanding premium-tier pricing in hospital procurement contracts. This regulatory filter concentrates pricing power among vendors whose modified nucleotides and library preparation enzymes carry validated quality documentation.
Pricing Analysis
Cost-down pressure on mid-volume diagnostic centers accelerates as integrated health networks consolidate enterprise sequencing contracts, compressing margins for point-solution vendors. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared companion diagnostic assays from research-use-only panels and unvalidated discovery-grade services. Price differentiation traces to certification grade and volume scale, with academic medical centers showing least price sensitivity due to NIH instrumentation grant coverage while independent reference laboratories face acute margin pressure.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and South Korea anchor hub-and-spoke patterns for temperature-controlled reagent logistics. Critical enzyme production concentrates in the United States, Germany, and Japan, while modified nucleotide synthesis draws from Switzerland and South Korea. Single-source vulnerability threatens workflows dependent on specialized T4 DNA ligase and reverse transcriptase suppliers. Distribution runs through direct vendor-to-laboratory channels for high-value instrumentation, with reagent consumables flowing via authorized distributors.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The RNA transcriptome profiling test market functions as a vertical-integration race where platform providers pursue captive control over bioinformatics pipelines to lock in recurring revenue streams.
For Market Incumbents: Anticipate margin compression from modular panel architects by deepening in-house production of critical library preparation chemistries and securing exclusive distribution agreements with academic medical center procurement committees. Defensive positioning requires ISO 15189 accreditation investment for service laboratories and cross-platform data standardization to neutralize interoperability threats from emerging bioinformatics specialists. For New Entrants and Emerging Players: Contract research organizations represent the most penetrable channel partner type for transcriptome assay validation services, offering foothold access to pharmaceutical companion diagnostic development programs. White-space targets include liquid biopsy transcriptome applications where regulatory precedents remain unsettled and neurodegenerative disease biomarker discovery consortia in Switzerland and the Netherlands. A focused go-to-market angle centers on spatial transcriptomics platform installations for pathology departments seeking tissue-architecture-preserving RNA capture capabilities. For Investors and Strategic Acquirers: FDA draft guidance publication on tumor mutational burden testing is the leading indicator that analytical validation requirements will tighten further, favoring acquisition targets with established clinical-grade pipeline documentation and reference material traceability. Long-term viability rests on platform ecosystem breadth rather than point-solution depth. Target acquisition candidates include bioinformatics-forward specialists with recurring revenue from reagent and software subscriptions, avoiding pure-play hardware manufacturers vulnerable to instrument replacement cycle volatility.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Regulatory Co-Development | Pharmaceutical sponsor partnerships with Illumina and Thermo Fisher secure FDA labeling for oncology assays. |
| Modular Panel Architecture Launch | QIAGEN's configurable gene sets capture mid-volume laboratory procurement preference without platform switching. |
| Single-Cell Sequencing Platform Expansion | 10x Genomics droplet-based systems electrify competitive positioning in tumor heterogeneity research programs. |
| Bioinformatics Pipeline Integration | End-to-end workflow specialists sustain recurring revenue through cloud-based variant interpretation software. |
| Liquid Biopsy Transcriptome Validation | First-mover positioning in circulating tumor RNA profiling awaits settled regulatory precedent from FDA guidance. |
Research Methodology
SEC 10-K filings, FDA 510(k) clearance databases, and EMA companion diagnostic guidance documents formed the secondary backbone, cross-referenced with primary interviews involving clinical laboratory directors, molecular pathologists, pharmaceutical regulatory affairs leads, and hospital GPO contracts managers. Bottom-up triangulation aggregated instrument installation data and reagent procurement volumes, while top-down validation checked against NIH funding allocations and cancer center capital expenditure disclosures.
Historical trendline analysis established baseline adoption curves for RNA-Seq and microarray platforms across the projection horizon. Segmentation modeling incorporated technology platform, application indication, end-user institution type, and regional regulatory cluster dimensions. CAGRs derived from weighted average of instrument replacement cycles, reimbursement pathway expansion rates, and pharmaceutical pipeline companion diagnostic pairing density.
Several conditions sit outside the modeled scope, including unforeseen regulatory reversals on liquid biopsy transcriptome categories and pandemic-era infrastructure repurposing decisions. Forecasts reflect documented assumptions regarding FDA guidance finalization timelines and EMA harmonization progress. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Rare Disease Genetic Testing Market
Genomics
Genetic Testing Market
Genomics
Global Molecular Cytogenetics Market
Genomics
Next Generation Sequencing (NGS) Informatics Market
Genomics
Nutrigenomics Testing Market
Genomics
Middle East and Africa Genetic Testing Market
Genomics
DNA Sequencing Services Market
Genomics
DNA Sequencing Market
Genomics
Europe Cancer Biomarkers Market
Genomics
Next-Generation Sequencing for Non-Invasive Prenatal Testing Market
Genomics
Alagille Syndrome Market
Genomics
Asia-Pacific Genetic Testing Market
Genomics
Global Whole Genome Sequencing (WGS) Market
Genomics
Molecular Breeding Market
Genomics
Global Hereditary Cancer Testing Market
Genomics
Sequencing Electrophoresis Systems Market