
 Global Plant Breeding and CRISPR Plant Market | 2026-2036
Global Plant Breeding and CRISPR Plant Market Size, Share, and Industry Trends Forecast 2026-2036
Global Plant Breeding and CRISPR Plant Market Foresight
A shortage of molecular breeders with CRISPR platform expertise is reorganizing talent acquisition across the agricultural biotechnology sector. Bayer CropScience leverages its germplasm libraries to anchor large-scale genome-editing programs for major row crops. Syngenta Group competes through integrated trait discovery pipelines that span CRISPR design to field validation. Corteva Agriscience differentiates by controlling proprietary delivery systems for plant transformation.
Plant breeding and CRISPR plants encompass the directed genetic improvement of crop species through conventional selection, marker-assisted backcrossing, and targeted nuclease editing with systems such as CRISPR-Cas9, base editing, and prime editing operating at single-nucleotide resolution. These technologies serve the commercial purpose of introducing herbicide tolerance, disease resistance, and abiotic stress tolerance traits without transgenic DNA integration, thereby shortening variety development cycles from a decade to roughly half that duration. CRISPR-Cas9 and base editing command the dominant share of active research pipelines due to their multiplexing capacity and precision, while prime editing remains the fastest-growing modality as seed developers pursue complex nucleotide substitutions. Disease resistance and yield improvement applications attract the deepest investment pools, though quality enhancement traits for oilseeds and vegetables are emerging as higher-margin segments.
The EPA regulates pesticidal plant-incorporated protectants derived from genome editing under the Federal Insecticide, Fungicide, and Rodenticide Act, while the USDA exercises streamlined oversight for products lacking foreign DNA. EFSA assesses novel genome-edited foods under the EU Green Deal sustainability criteria, creating divergent market access conditions across the Atlantic. Stakeholders must monitor how national regulators classify edited plants relative to transgenic organisms, as this classification determines field trial requirements, import approvals, and consumer labeling obligations that shape commercialization timelines.
Market Dynamics
The convergence of CRISPR-Cas9 multiplexing with automated phenotyping pipelines is compressing variety development timelines while regulatory divergence between Washington and Brussels fragments market access pathways.
Growth Catalysts
- USDA Streamlined Oversight:The USDA's exemption of genome-edited crops lacking foreign DNA from biotechnology regulation accelerates field trial approvals and commercialization timelines for US-based seed developers.
- Disease-Resistant Cereals:Fungal pathogen pressure on wheat and maize production drives investment in CRISPR-edited resistance traits that bypass lengthy transgenic regulatory pathways.
- EU Green Deal Sustainability Mandates:The European Commission's binding targets for pesticide reduction create pull-through demand for genome-edited crops with intrinsic pest resistance.
Market Restraints
- Regulatory Fragmentation:EFSA's classification of genome-edited foods under novel food regulations creates import barriers and labeling obligations absent in the US system.
- Guide RNA Synthesis Costs:Proprietary CRISPR reagent supply chains concentrate among limited specialized chemical suppliers, creating input cost volatility for breeding programs.
- Off-Target Editing Uncertainty:Unpredictable double-strand break repair outcomes in polyploid crops like wheat necessitate extensive validation screening, extending development cycles.
Strategic Opportunities
- Brazilian Regulatory Harmonization:ANVISA's evolving stance on genome-edited foods presents first-mover positioning for trait developers seeking South American market access.
- Prime Editing Convergence:The integration of reverse transcriptase with CRISPR-Cas9 enables precise nucleotide substitutions without double-strand breaks, opening complex trait engineering previously inaccessible.
- Direct-to-Farmer Distribution:Digital seed platforms bypass traditional distributor networks, enabling genome-edited variety developers to capture margin and accelerate farmer feedback loops.
Industry Challenges
- Molecular Breeder Scarcity:The shortage of professionals combining CRISPR platform expertise with quantitative genetics training forces wage inflation and poaching cycles across research institutes.
- Transformation Bottleneck:Proprietary Agrobacterium and biolistic delivery systems remain concentrated among few technology holders, creating licensing friction and IP disputes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Plant Breeding and CRISPR Plant Market |
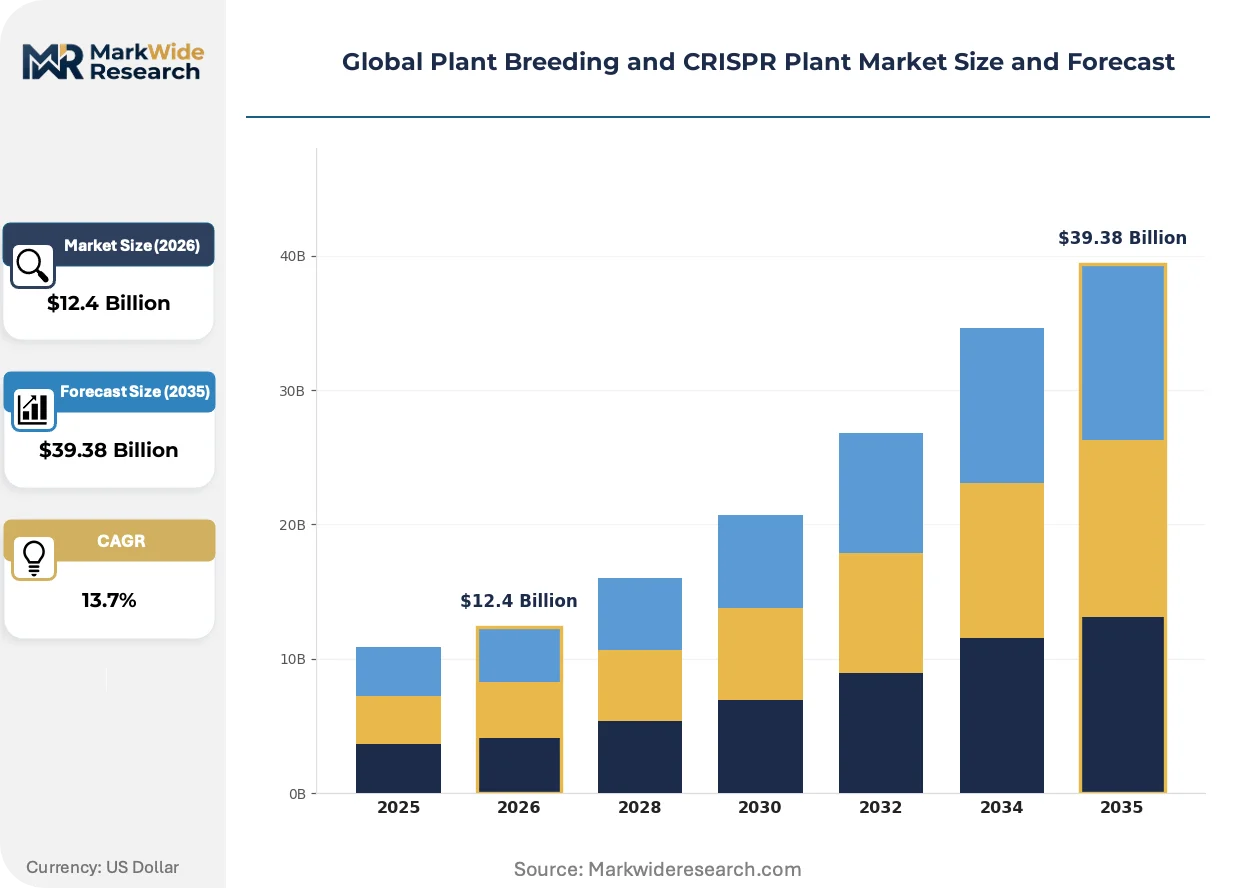
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $39.38 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: CRISPR-Cas9, TALENs, ZFNs, Meganucleases, Base Editing, Prime Editing Crop Type: Cereal Grains, Oilseeds, Fruits, Vegetables, Legumes, Fiber Crops Application: Disease Resistance, Herbicide Tolerance, Yield Improvement, Abiotic Stress Tolerance, Quality Enhancement, Shelf Life Extension End User: Seed Developers, Agricultural Biotech Firms, Research Institutes, Contract Breeders, Agrochemical Companies |
| Companies Covered | Corteva Agriscience, Bayer CropScience, Syngenta Group, BASF Agricultural Solutions, KWS Saat, Limagrain, Pairwise, Calyxt, Inari Agriculture, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Plant Breeding and CRISPR Plant Market Shifts & Advancements
Genome editing modalities are diversifying beyond Cas9 nucleases while regulatory frameworks crystallize around product-based rather than process-based classification schemes.
Base editing systems incorporating cytosine or adenine deaminases enable single-nucleotide conversions without double-strand break formation. Seed developers at research institutes in the United States and China are adopting base editors for herbicide tolerance trait introduction at unprecedented precision. The technology is miniaturizing delivery vectors, enabling transformation of previously recalcitrant cereal genotypes and expanding addressable crop scope.
The EU F-Gas Regulation and accompanying Farm-to-Fork Strategy impose binding sustainability verification requirements on agricultural biotechnology value chains. EFSA's implementation of EU Green Deal criteria for novel food assessments creates compliance complexity distinct from US EPA and USDA frameworks. European seed developers are responding by segregating breeding pipelines, maintaining CRISPR-edited variety development for export markets while conventional programs serve domestic regulatory requirements.
Farmer purchasing patterns are consolidating around bundled trait packages rather than single-gene solutions. Input distributors in the US Corn Belt are displacing standalone seed sales with integrated crop management contracts incorporating genome-edited varieties, precision application services, and outcome guarantees. This bundling concentrates procurement leverage among large-scale farming operations in Iowa, Illinois, and Nebraska, marginalizing smaller breeders lacking full-stack agronomic support capabilities.
Global Plant Breeding and CRISPR Plant Market Segmentation
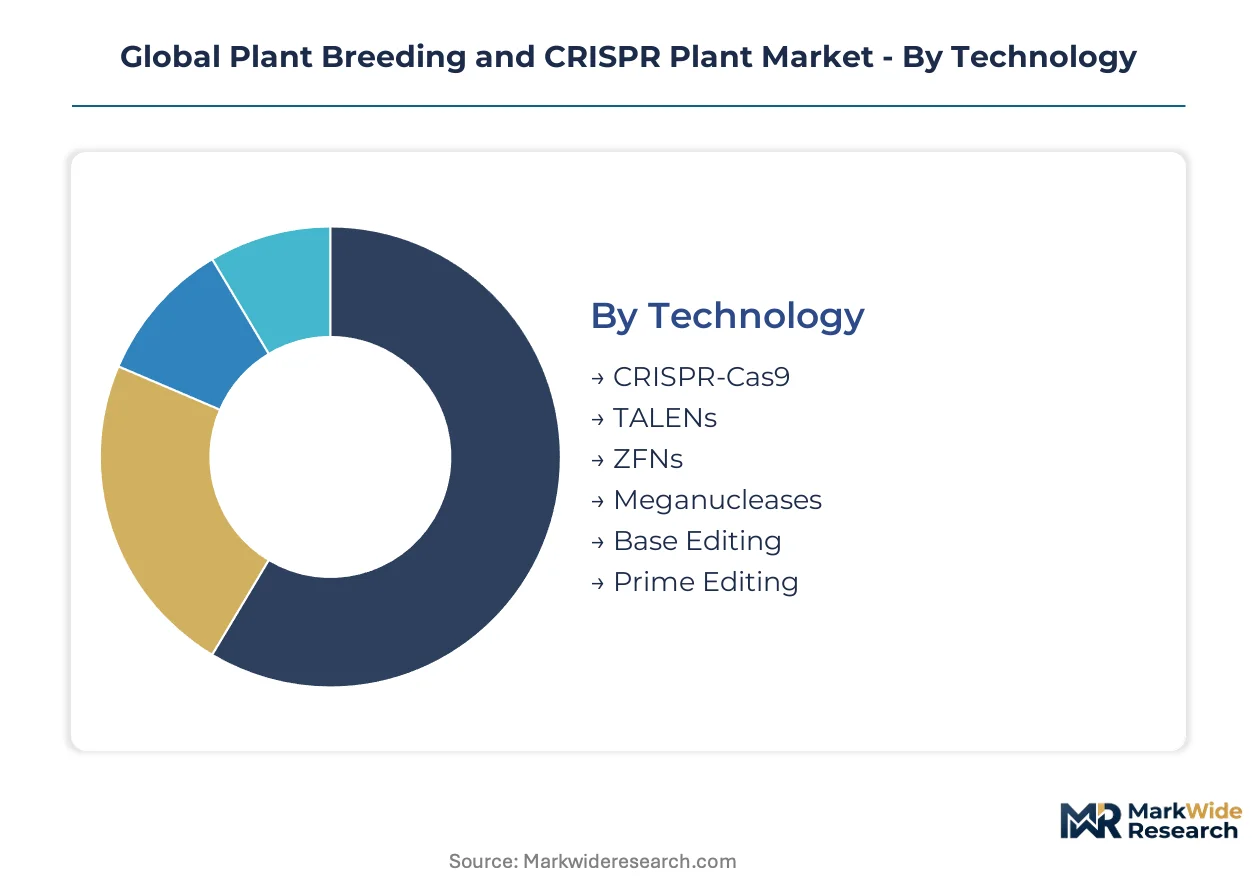
CRISPR plant breeding segments flow through distinct commercial channels. Technology platforms concentrate in research institutes and seed developers. Crop types and applications determine whether varieties reach farmers through direct licensing or bundled distributor contracts.
Technology:
Platform selection dictates transformation success rates and regulatory pathway complexity across breeding programs.
- CRISPR-Cas9:The dominant multiplexing platform enables simultaneous editing of multiple gene targets in polyploid cereals. Demand concentrates at Bayer CropScience and Corteva Agriscience for maize and soybean trait stacks, though off-target repair outcomes in wheat necessitate expanded validation screening.
- Base Editing:Cytosine and adenine deaminases execute precise single-nucleotide conversions without double-strand breaks. Research institutes in the United States and China deploy base editors for herbicide tolerance introduction, with miniaturized delivery vectors expanding transformation access to recalcitrant cereal genotypes.
- Prime Editing:Reverse transcriptase-Cas9 fusions enable complex nucleotide substitutions previously inaccessible through conventional nucleases.
- TALENs:Transcription activator-like effector nucleases retain utility in regulatory environments requiring established transformation histories.
- ZFNs:Zinc finger nucleases persist in legacy trait programs with extensive safety documentation.
- Meganucleases:Rare-cutting homing endonucleases serve specialized applications requiring single-site precision.
By volume, CRISPR-Cas9 leads. By growth pace, prime editing is expanding most quickly.
Crop Type:
Margin structures diverge sharply between commodity row crops and specialty vegetables, reshaping breeder investment allocation.
- Cereal Grains:Wheat, maize, and rice dominate field trial pipelines due to planted acreage scale and farmer price sensitivity. Disease-resistant wheat varieties attract concentrated investment from Syngenta Group and Bayer CropScience as fungal pressure intensifies across the US Corn Belt and European breadbasket regions.
- Oilseeds:Soybean and canola CRISPR programs target fatty acid profile modification for biofuel and food oil markets. Quality enhancement traits command premium pricing from processors in Iowa and Illinois seeking identity-preserved supply chains.
- Vegetables:Tomato, lettuce, and brassica editing focuses on shelf life extension and consumer-facing quality attributes.
- Fruits:Citrus and apple breeding programs target disease resistance against bacterial and fungal pathogens.
- Legumes:Soybean and pea protein content improvement serves plant-based food ingredient demand.
- Fiber Crops:Cotton trait development emphasizes drought tolerance and pest resistance for arid-zone production.
Cereal grains capture the deepest R&D investment pools. Vegetables generate the highest margin per edited event.
Application:
Trait value crystallizes around farmer pain points rather than incremental convenience features, concentrating commercial viability.
- Disease Resistance:Fungal and bacterial pathogen resistance in wheat, maize, and rice commands the deepest investment pools. The EU Green Deal pesticide reduction mandates create pull-through demand for varieties with intrinsic resistance traits, while US seed developers bypass lengthy transgenic regulatory timelines through USDA streamlined oversight.
- Yield Improvement:Photosynthetic efficiency and nitrogen fixation enhancement target input cost reduction for large-scale farming operations.
- Herbicide Tolerance:Non-transgenic resistance traits enable flexible weed management without foreign DNA regulatory burdens.
- Abiotic Stress Tolerance:Drought and salinity resistance address climate volatility in water-stressed growing regions.
- Quality Enhancement:Oilseed fatty acid profiles and vegetable nutritional content serve processor and consumer specifications.
- Shelf Life Extension:Post-harvest deterioration reduction targets food waste reduction and export logistics.
Disease resistance anchors current revenue. Quality enhancement is climbing the fastest as oilseed processors pay premiums for tailored fatty acid profiles.
End User:
Procurement authority is consolidating among integrated technology platforms with captive transformation and field validation capabilities.
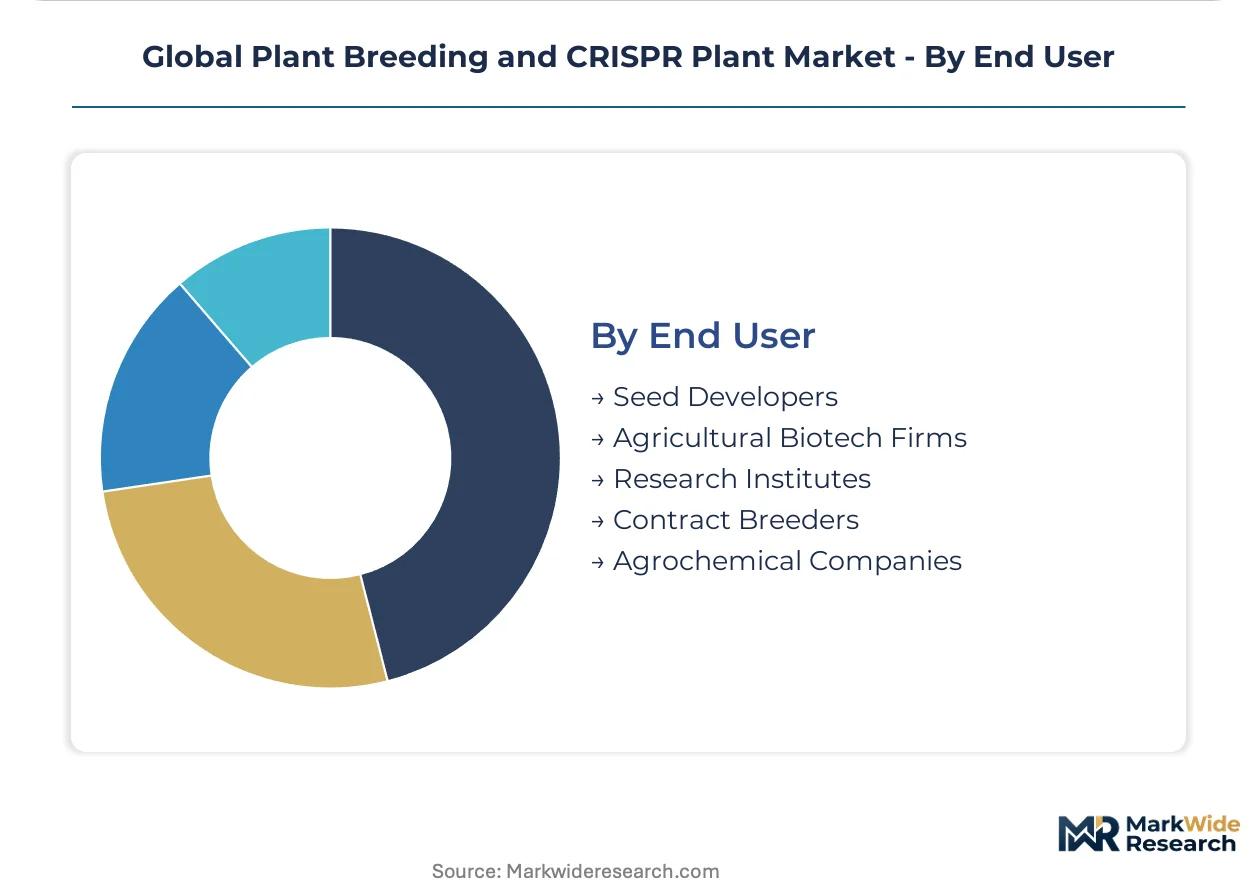
- Seed Developers:Bayer CropScience, Syngenta Group, and Corteva Agriscience anchor global CRISPR infrastructure through proprietary germplasm libraries and multiplexed editing pipelines. These firms capture margin by bundling genome-edited varieties with precision agronomy services across the US Corn Belt.
- Agricultural Biotech Firms:Specialized trait discovery shops license editing platforms to major seed developers, concentrating in research clusters around Boston and Research Triangle Park.
- Research Institutes:USDA-ARS facilities and university breeding programs advance pre-commercial trait validation.
- Contract Breeders:Third-party transformation service providers fill capacity gaps for mid-tier seed companies lacking in-house editing infrastructure.
- Agrochemical Companies:Input manufacturers seek trait-stacking partnerships to preserve chemical product relevance amid biological substitution pressures.
Seed developers command the largest procurement volumes. Contract breeders are gaining share fastest as mid-tier firms outsource transformation capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in genome-edited seeds concentrates in the United States, where USDA streamlined oversight accelerates commercialization timelines, while European developers absorb compliance premiums from EFSA novel food classifications that fragment market access.
United States
Contract breeders and research institutes in Iowa, Illinois, and Nebraska are building CRISPR infrastructure for disease-resistant maize and soybean trait stacks. The USDA exercises streamlined oversight for products lacking foreign DNA, compressing field trial approvals relative to transgenic pathways. The Research Triangle Park cluster in North Carolina anchors multiplexed editing pipelines serving major row crop programs.
Germany
BASF Agricultural Solutions and KWS Saat leverage domestic germplasm libraries for cereal genome-editing programs targeting EU export markets. The EU F-Gas Regulation and Farm-to-Fork Strategy impose binding sustainability verification requirements that elevate compliance costs. The Rhine-Ruhr and Lower Saxony regions concentrate transformation service providers serving segregated breeding pipelines.
China
State-backed research institutes deploy base editing systems for herbicide tolerance introduction in rice and wheat at unprecedented precision. National agricultural biotechnology policies prioritize food security applications with streamlined variety approval pathways. The Yangtze River Delta cluster around Shanghai and Jiangsu Province hosts the deepest concentration of CRISPR platform development capacity.
Brazil
ANVISA's evolving stance on genome-edited foods creates first-mover positioning for trait developers seeking South American market access beyond Argentina. The Cerrado and southern soybean belt drive demand for drought-tolerant varieties engineered through non-transgenic pathways. São Paulo-based contract breeders are acquiring transformation capacity to serve mid-tier seed companies lacking in-house editing infrastructure.
Australia
Research institutes in New South Wales and Victoria advance pre-commercial validation of abiotic stress tolerance traits for wheat and barley in water-stressed growing regions. The national gene technology regulator applies product-based classification schemes that distinguish genome-edited plants from transgenic organisms. The Grains Research and Development Corporation funds field trial networks concentrating in the Murray-Darling Basin.
Global Plant Breeding and CRISPR Plant Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the genome-edited seed sector. The market structure consolidates around integrated seed developers with captive germplasm libraries, while specialized trait discovery shops and contract transformation providers fragment the mid-tier. Two dominant archetypes emerge: multiplexed platform operators controlling end-to-end breeding pipelines, and modular service providers licensing editing capacity to resource-constrained breeders. Competitive moves concentrate on strategic partnerships for trait stacking and geographic licensing agreements that secure regulatory pathway expertise.
Within the integrated platform tier, Bayer CropScience, Syngenta Group, and Corteva Agriscience occupy positions defined by proprietary delivery systems and germplasm depth. These entities exemplify the scale-driven archetype through control of field validation networks and precision agronomy bundling capabilities. Pairwise and Inari Agriculture represent the specialized discovery segment, anchoring positions as technology licensors rather than full-stack seed marketers.
| Leading Market Players |
|---|
| Corteva Agriscience |
| Bayer CropScience |
| Syngenta Group |
| BASF Agricultural Solutions |
| KWS Saat |
| Limagrain |
| Pairwise |
| Calyxt |
| Inari Agriculture |
| Others |
Supply & Pricing Matrix
Multiplexed editing platform scale economies at Bayer CropScience and Corteva Agriscience compress per-event validation costs below mid-tier competitors, concentrating price-setting power among integrated seed developers while forcing contract breeders toward specialty crop niches with higher margin floors.
Pricing Analysis
The customization-premium spread separates standard trait licensing from configured-to-order genome-edited variety development. Three-tier pricing structure across premium, standard, and economy levels reflects germplasm depth, transformation success rates, and bundled agronomy services. Cost compression in economy tiers stems from USDA streamlined oversight accelerating field trial throughput. Large-scale farming operations in Iowa and Illinois exhibit lowest price sensitivity due to bundled procurement contracts, while mid-tier seed companies face acute margin pressure from guide RNA synthesis cost volatility.
Supply Chain Analysis
Inbound logistics costs for synthetic guide RNA and specialized deaminase enzymes concentrate supply risk at Rotterdam and Shanghai port clusters, with container availability constraints extending lead times for CRISPR reagent shipments to transformation facilities. Proprietary chemical synthesis capacity draws from Germany, Switzerland, and the United States, while germplasm repositories rest on captive seed banks in Iowa, Lower Saxony, and Jiangsu Province. Single-source vulnerability around Agrobacterium strain licensing creates IP friction points. Distribution runs through integrated seed developer direct sales forces and digital platforms bypassing traditional agricultural distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The genome-edited seed sector approaches a platform-economics inflection where control of multiplexed editing infrastructure and regulatory pathway expertise determines winner-take-most dynamics, accelerated by USDA-EFSA divergence fragmenting global variety approval workflows.
For Market Incumbents: Compound germplasm library depth with captive transformation capacity to outrun emerging biotech entrants lacking field validation networks. Defensive consolidation should target contract breeders in São Paulo and Sydney to secure Brazilian and Australian regulatory pathway expertise before ANVISA and TGA frameworks crystallize. Priority investment in prime editing delivery miniaturization preserves technology leadership against base editing commoditization. For New Entrants and Emerging Players: Differentiate on recalcitrant cereal genotype transformation services where Bayer and Corteva maintain patent thickets. White-space targets include direct-to-farmer digital platforms for specialty vegetable varieties and CRISPR-edited legume protein content improvement serving plant-based food ingredient demand. Brazil's Cerrado drought-tolerance segment offers the most penetrable geography given ANVISA regulatory uncertainty delaying incumbent commitment. For Investors and Strategic Acquirers: Specialized trait discovery shops with validated prime editing pipelines and regulatory dossier experience in multiple jurisdictions represent the highest-conviction acquisition archetype. Long-term viability hinges on platform economics concentration favoring integrated operators with end-to-end breeding infrastructure. The signal to watch is EFSA novel food classification harmonization with USDA product-based frameworks, which would eliminate European compliance premiums and reshape competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Prime Editing Platform Integration | Reverse transcriptase-Cas9 fusions enable complex nucleotide substitutions previously inaccessible through conventional nucleases. |
| Regulatory Dossier Expansion | Multi-jurisdiction approval expertise in USDA, EFSA, and ANVISA frameworks accelerates global variety commercialization timelines. |
| Germplasm Library Acquisition | Captive seed banks in maize, wheat, and soybean compress breeding cycles and raise rival transformation barriers. |
| Direct-to-Farmer Platform Launch | Digital seed distribution bypasses traditional agricultural input distributors and captures margin from bundled agronomy services. |
| Specialty Crop Transformation Capacity | Recalcitrant vegetable and fruit genotype editing addresses higher-margin quality enhancement segments underserved by row crop specialists. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, patent databases, and seed industry trade data through bottom-up and top-down triangulation. Primary interviews engaged molecular breeding directors at major seed developers, transformation service providers in Research Triangle Park and the Yangtze River Delta, USDA-ARS research scientists, and procurement officers at large-scale farming cooperatives in Iowa and Illinois. Secondary validation drew from EPA and USDA regulatory guidance documents, EFSA novel food assessment protocols, ANVISA consultation papers, and field trial registration databases.
Segmentation dimensions modeled span technology platform, crop type, application trait category, and end-user archetype across the analysis window. Value projections incorporate germplasm licensing fee structures, transformation service pricing, and bundled agronomy contract terms. CAGRs derive from trend extrapolation of CRISPR pipeline advancement rates, regulatory approval velocity differentials between jurisdictions, and farmer adoption curves for genome-edited varieties relative to conventional and transgenic alternatives. Industry-specific forecast inputs include guide RNA synthesis cost trajectories and EFSA-EFSA member state regulatory harmonization probability.
Material uncertainties — regulatory reclassification of genome-edited plants as transgenic organisms, guide RNA supply chain disruptions, and off-target editing liability frameworks — sit outside the modeled envelope. Forecasts reflect assumptions around continued USDA product-based oversight and EFSA novel food assessment stability. Practitioners should keep alternative scenarios live as EU Green Deal implementation timelines and Brazilian ANVISA final rulings evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gene Editing & CRISPR
Spain Gene Editing Market
Gene Editing & CRISPR
China Gene Editing Market
Gene Editing & CRISPR
Base Editing Market
Gene Editing & CRISPR
Global CRISPR and CRISPR-Associated (Cas) Genes Market
Gene Editing & CRISPR
DNA Modifying Agents Market
Gene Editing & CRISPR
North America Gene Synthesis Market
Gene Editing & CRISPR
Gene Editing Market
Gene Editing & CRISPR
Japan Gene Editing Market
Gene Editing & CRISPR
Klinefelter Syndrome Therapeutics Market
Gene Editing & CRISPR
Brazil Gene Editing Market
Gene Editing & CRISPR
CAS9 Technology Market
Gene Editing & CRISPR
South Korea Gene Editing Market
Gene Editing & CRISPR
US Gene Editing Market
Gene Editing & CRISPR
Cas9 Nuclease Market
Gene Editing & CRISPR
Genetic Engineering Market
Gene Editing & CRISPR
Germany Gene Editing Market