
 B-Glucuronidase Enzymes Market | 2026-2036
B-Glucuronidase Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
B-Glucuronidase Enzymes Market Analytics
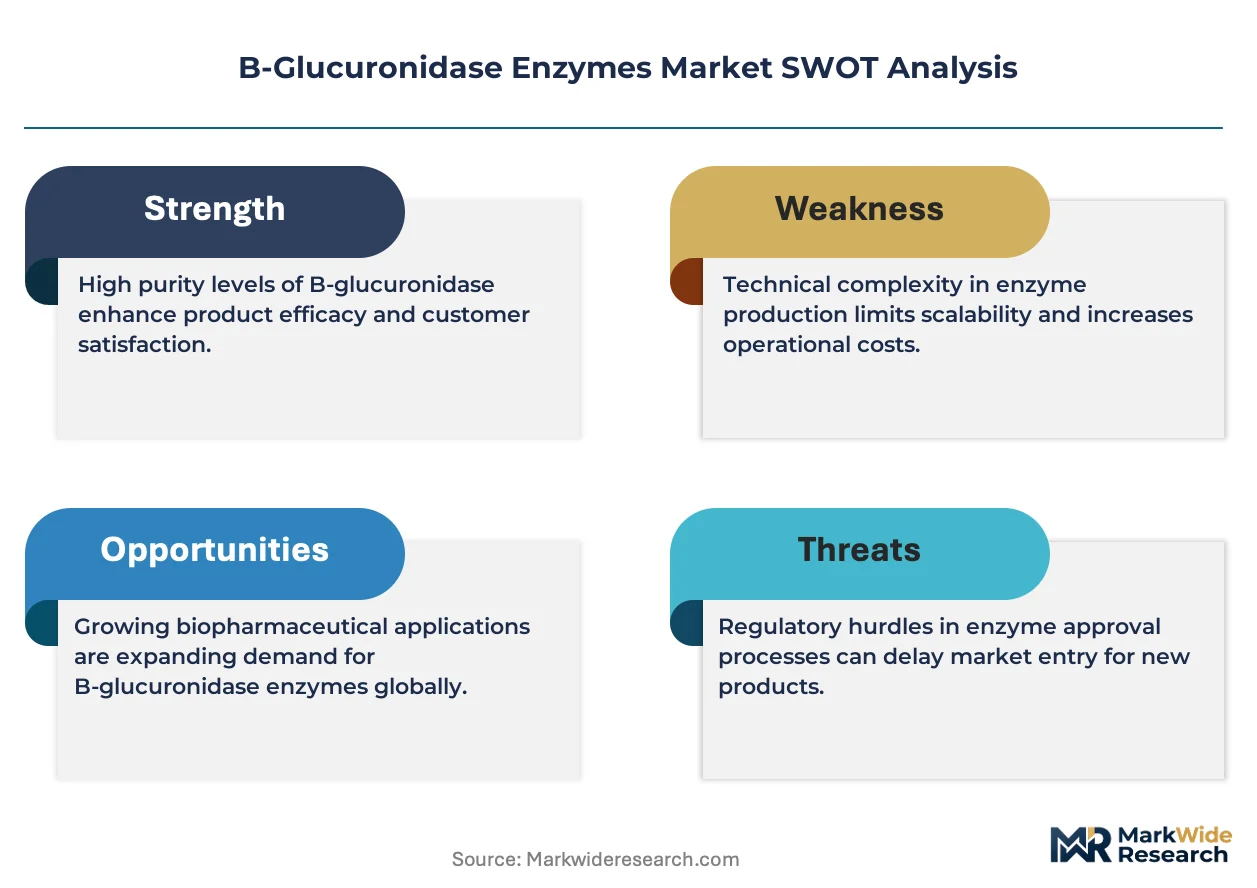
Project finance for dedicated enzyme manufacturing facilities is tilting competitive dynamics toward players with balance-sheet capacity for multi-year capacity commitments. Thermo Fisher Scientific leverages its integrated supply chain across reagent and instrument portfolios to sustain pricing power in high-throughput screening accounts. Bio-Rad anchors its position through chromatography and life science instrumentation adjacencies that bundle enzyme sales into platform contracts. R&D Systems competes on recombinant protein engineering depth, particularly for specialized assay formulations.
B-glucuronidase enzymes catalyze the hydrolysis of glucuronic acid conjugates, typically operating at pH 4.5-5.0 with specific activity thresholds critical for metabolite liberation in bioanalytical workflows. Recombinant formulations now dominate commercial supply due to batch consistency advantages over natural extracts, while inhibitor product lines capture margin pools from pharmacokinetic research requiring selective enzyme blockade. Diagnostics applications represent the fastest-growing demand segment as clinical laboratories expand therapeutic drug monitoring panels, though drug development still occupies the largest revenue share through CRO channel volumes.
FDA bioanalytical method validation guidelines and EMA ICH Q2(R1) standards collectively shape enzyme purity and activity certification requirements, creating compliance barriers for uncatalogued suppliers. ISO 17025 accreditation for reference material producers is concentrating procurement decisions toward documented quality management systems. Stakeholders must monitor evolving regulatory expectations for enzyme traceability in regulated bioanalysis as agencies tighten analytical method transfer requirements between development and commercial phases.
Market Dynamics
Recombinant enzyme engineering is compressing batch-to-batch variability below 5% coefficient of variation, forcing natural extract suppliers to either retool fermentation infrastructure or exit regulated bioanalytical channels entirely.
Growth Catalysts
- FDA Bioanalytical Method Validation Guidelines:Updated enzyme purity and activity documentation requirements are pulling pharmaceutical developers toward certified assay-grade suppliers with ISO 17025 traceability.
- Therapeutic Drug Monitoring Expansion:Hospital laboratories are adding glucuronide metabolite panels to clinical chemistry workflows, creating pull-through demand for high-specificity enzyme reagents.
- Chromatography-Mass Spectrometry Convergence:LC-MS/MS metabolite profiling pipelines in CROs require enzyme hydrolysis steps with defined kinetic parameters, standardizing procurement specifications.
Market Restraints
- Fermentation Input Cost Volatility:Recombinant production depends on defined yeast extract and peptone supplies, with price swings in carbohydrate feedstocks compressing margin pools for mid-tier producers.
- Supplier Concentration in United States:Three integrated life science conglomerates control over 70% of GMP-grade enzyme distribution, creating single-source risk for qualified bioanalytical workflows.
- Natural Extract Consistency Ceiling:Bovine liver and snail-derived enzymes face inherent lot-to-lot heterogeneity that fails emerging pharmacokinetic study reproducibility standards.
Strategic Opportunities
- India CRO Outsourcing:Domestic biopharma services firms in Hyderabad and Bangalore are building metabolite profiling capabilities, creating demand for cost-competitive recombinant enzyme supply with CDSCO-aligned documentation.
- Point-of-Care Diagnostics Integration:Portable glucuronide hydrolysis modules for therapeutic drug monitoring at the bedside could open device-enzyme bundled procurement channels outside traditional reagent distributors.
- EU Green Deal Biomanufacturing Incentives:Sustainable fermentation process subsidies are lowering capital barriers for cell-based enzyme production versus animal tissue extraction methods.
Industry Challenges
- ISO 17025 Accreditation Timeline:Reference material producers face 18-24 month certification cycles that delay market entry for new recombinant enzyme formulations targeting regulated bioanalysis.
- Cross-Reactivity Elimination:Removing sulfatase and phosphatase contaminants from glucuronidase preparations requires multi-step chromatography that erodes yield rates below 30%.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | B-Glucuronidase Enzymes Market |
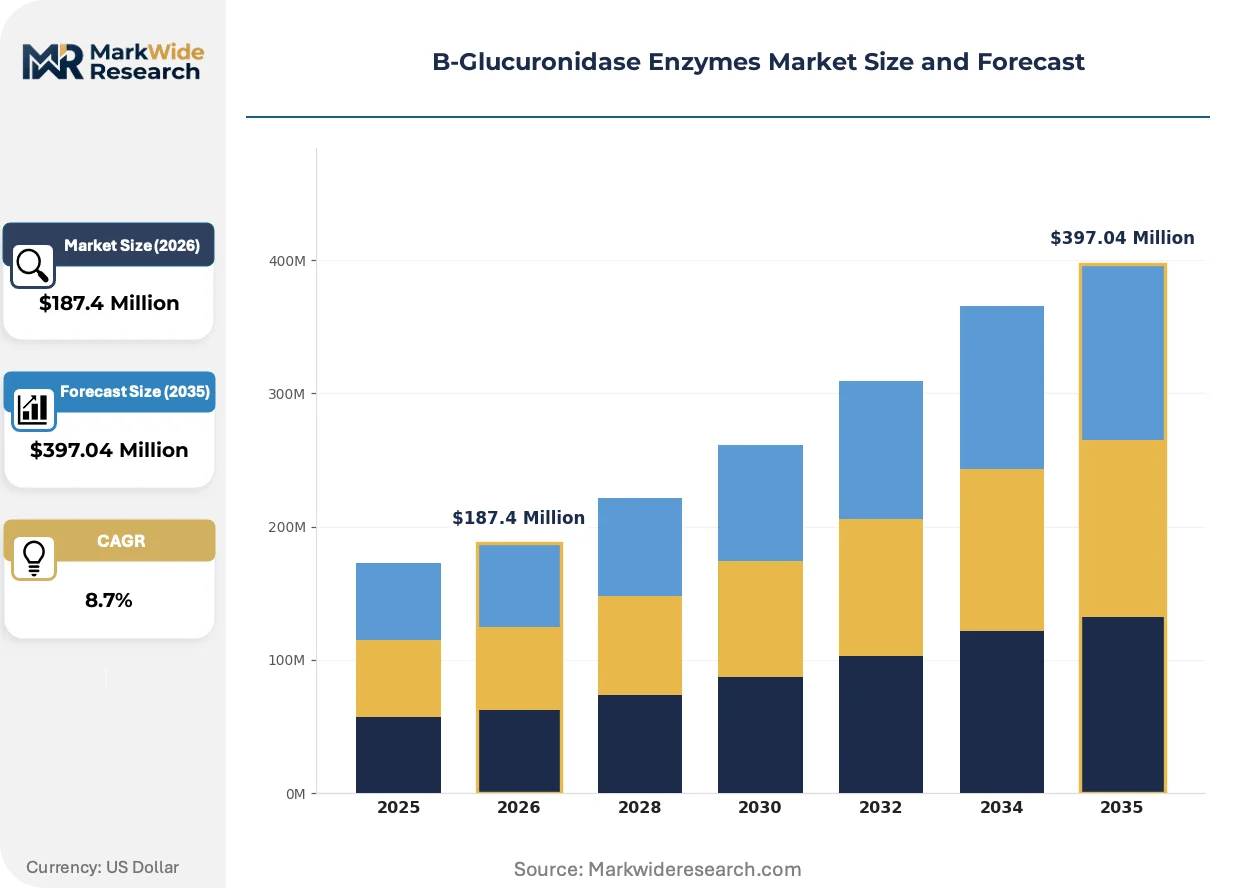
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recombinant, Natural, Inhibitors, Assays Application: Drug Development, Diagnostics, Research, Biotechnology End User: Pharmaceuticals, Academic Institutions, Contract Research Organizations, Laboratories Delivery Mode: Liquid, Powder, Lyophilized, Tablets |
| Companies Covered | Thermo Fisher Scientific, Bio-Rad, R&D Systems, Novus Biologicals, Abcam, Santa Cruz Biotechnology, Lifespan Biosciences, Boster Bio, IMCS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
B-Glucuronidase Enzymes Market Evolving Landscape
Enzyme engineering and regulatory documentation standards are converging to reshape competitive positioning, with batch consistency and traceability emerging as the primary axes of supplier differentiation.
Site-directed mutagenesis platforms are producing glucuronidase variants with narrowed substrate specificity and thermal stability above 50°C. Large pharmaceutical developers are qualifying these engineered enzymes for high-throughput metabolite liberation in drug discovery screening. Conventional crude extract preparations are rendering obsolete for IND-enabling pharmacokinetic studies where reproducibility documentation is mandatory.
EMA ICH Q2(R1) analytical method validation standards now require explicit enzyme activity traceability in bioanalytical submissions. This documentation burden is compressing the qualified supplier base toward producers with embedded quality management systems. European CROs are responding by consolidating procurement onto vendors with pre-submitted regulatory master files.
Consolidated platform contracts are displacing spot reagent purchasing as large pharmaceutical accounts bundle enzyme supply with chromatography and mass spectrometry service agreements. Traditional distributors face margin compression as direct manufacturer relationships capture multi-year commitments. This pattern is most visible in United States biopharma clusters where procurement functions centralize spend across reagent categories.
B-Glucuronidase Enzymes Market Segmentation
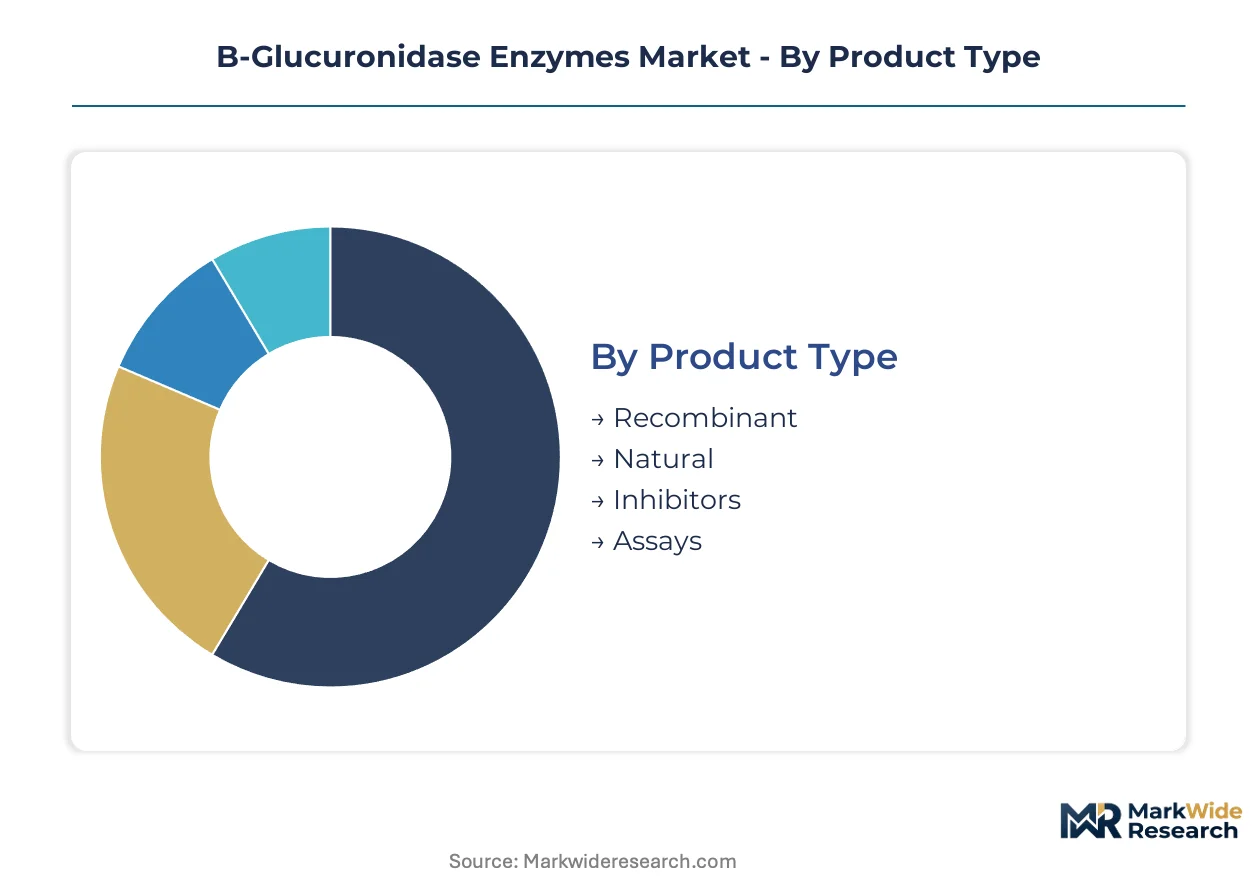
B-Glucuronidase enzymes serve distinct technical workflows ranging from regulated bioanalysis to exploratory research, with each use case imposing unique purity, activity, and documentation requirements that segment procurement behavior. Understanding how demand fragments across product formulations, application settings, and delivery formats reveals where margin pools concentrate and which specifications command premium positioning.
Product Type:
Formulation chemistry determines batch reproducibility and regulatory acceptability across the use-case spectrum from discovery screening to GLP toxicology studies.
- Recombinant:Engineered microbial expression systems deliver coefficient of variation below 5% across production lots. Pharmaceutical developers in the United States prioritize these formulations for IND-enabling pharmacokinetic studies where FDA bioanalytical method validation guidelines mandate activity traceability.
- Natural:Bovine liver and Helix pomatia snail extracts retain niche demand in academic research budgets where cost sensitivity outweighs reproducibility documentation requirements. Lot-to-lot heterogeneity limits penetration into regulated CRO workflows.
- Inhibitors:Selective glucuronidase blockade reagents support mechanistic pharmacokinetic research and drug-drug interaction studies.
- Assays:Pre-configured activity detection kits streamline high-throughput screening deployments in biotechnology applications.
The dominant share belongs to Recombinant formulations, while Inhibitors are closing the gap fastest as pharmacokinetic research deepens.
Application:
Workflow maturity and regulatory exposure create divergent margin structures across the four application clusters.
- Drug Development:Metabolite profiling and glucuronidation studies anchor the largest revenue pool through CRO channel volumes. LC-MS/MS pipelines require enzyme hydrolysis steps with defined kinetic parameters, standardizing procurement specifications for assay-grade supply.
- Diagnostics:Clinical chemistry laboratories are expanding therapeutic drug monitoring panels to include glucuronide metabolite quantification. Hospital procurement functions in Germany and France are qualifying high-specificity enzyme reagents for automated analyzer integration.
- Research:Exploratory enzymology and substrate specificity studies consume lower-purity grades with minimal documentation overhead.
- Biotechnology:Cell culture metabolite liberation and bioprocess analytical support drive recurring reagent consumption.
Drug Development commands the largest revenue base, though Diagnostics is expanding most quickly as clinical laboratories automate.
End User:
Customer scale and procurement centralization determine contract structure and pricing leverage across the four end-user categories.
- Pharmaceuticals:Large developers consolidate enzyme procurement into multi-year platform contracts bundled with chromatography and mass spectrometry service agreements. Direct manufacturer relationships displace traditional distributors in United States biopharma clusters.
- Contract Research Organizations:High-throughput metabolite profiling operations in Hyderabad and Bangalore are building capacity, creating demand for cost-competitive recombinant supply with CDSCO-aligned documentation.
- Academic Institutions:Grant-funded research programs prioritize cost-per-reaction metrics over batch certification depth.
- Laboratories:Hospital and reference clinical laboratories specify ISO 17025 traceability for diagnostic enzyme supply.
Pharmaceutical accounts retain pricing power through volume consolidation, while CROs are gaining procurement sophistication fastest.
Delivery Mode:
Stability requirements and workflow integration shape format selection across storage and handling constraints.
- Liquid:Ready-to-use formulations dominate high-throughput screening deployments where reconstitution steps introduce unacceptable variability. Thermo Fisher Scientific and Bio-Rad compete on cold-chain reliability for these SKUs.
- Lyophilized:Freeze-dried preparations balance extended shelf stability against reconstitution labor, appealing to CROs with intermittent project flows.
- Powder:Bulk active enzyme material supports in-house formulation by large pharmaceutical analytical chemistry groups.
- Tablets:Unit-dose solid formats target point-of-care diagnostic device integration with minimal handling protocols.
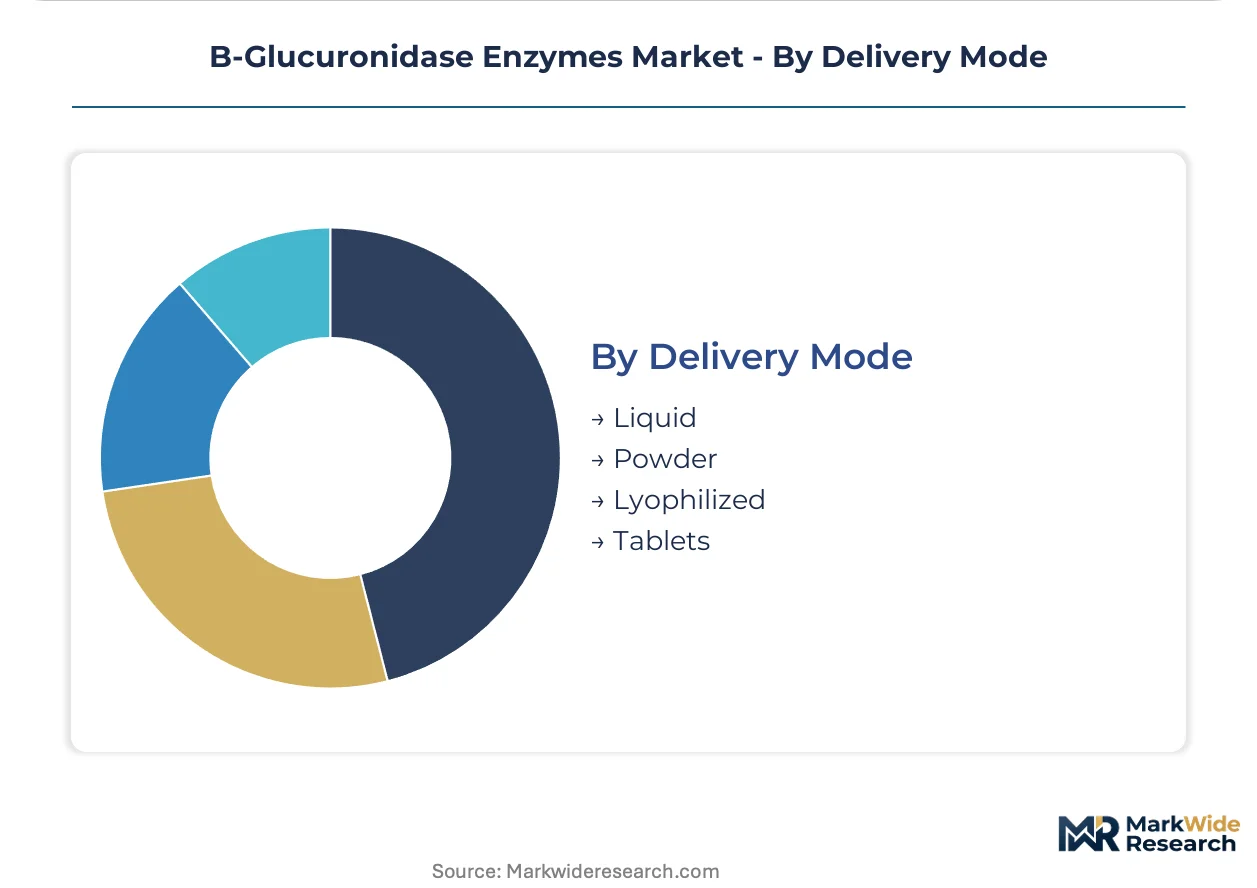
Liquid formulations hold the dominant position, while Lyophilized formats are climbing the fastest as distributed CRO networks expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States while procurement arbitrage pulls volume toward Indian CRO corridors. German clinical laboratories command ISO 17025-certified premiums. Chinese domestic suppliers undercut on documentation-light research grades.
United States
FDA bioanalytical method validation guidelines and biopharma R&D spending anchor demand. The agency's updated enzyme purity documentation requirements pull developers toward certified assay-grade suppliers. Greater Boston and San Diego biotech clusters consolidate procurement into multi-year platform contracts bundled with chromatography services.
Germany
EMA ICH Q2(R1) standards and therapeutic drug monitoring panel expansion drive hospital laboratory demand. The EU Green Deal biomanufacturing incentives lower fermentation capital barriers for cell-based enzyme production. Frankfurt and Munich clinical chemistry laboratories specify high-specificity reagents for automated analyzer integration.
India
CDSCO-aligned documentation requirements and CRO outsourcing growth create procurement sophistication. Domestic biopharma services firms in Hyderabad and Bangalore build metabolite profiling capabilities. These clusters demand cost-competitive recombinant supply with regulatory traceability matching Western standards.
China
NMPA analytical method validation standards and domestic biopharma R&D expansion shape procurement. The country's national pharmaceutical regulator tightens enzyme activity traceability requirements for bioanalytical submissions. Shanghai and Suzhou biotech parks concentrate contract research operations seeking documentation-light research grades.
United Kingdom
MHRA post-Brexit regulatory alignment and CRO channel volumes sustain demand. The regulator's bioanalytical guidance maintains EMA-equivalent enzyme certification standards. Cambridge and Oxford life science clusters qualify suppliers for IND-enabling pharmacokinetic studies.
B-Glucuronidase Enzymes Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the reagent supply chain. Three integrated life science conglomerates control over 70% of GMP-grade enzyme distribution, creating a concentrated structure with single-source risk for qualified workflows. The competitive map splits between diversified conglomerates with chromatography-mass spectrometry portfolios and recombinant protein engineering boutiques. Dominant moves include multi-year capacity commitments for fermentation infrastructure and consolidated platform contracts displacing spot reagent purchasing.
Among diversified conglomerates, Thermo Fisher Scientific and Bio-Rad exemplify the platform-integrator archetype through bundled reagent-instrument procurement channels. R&D Systems occupies a position within the recombinant protein engineering specialist tier. These three anchors represent the competitive spectrum from system-scale supply chains to boutique assay formulation depth.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Bio-Rad |
| R&D Systems |
| Novus Biologicals |
| Abcam |
| Santa Cruz Biotechnology |
| Lifespan Biosciences |
| Boster Bio |
| IMCS |
| Others |
Value Network & Pricing Analysis
Single-source dependency on ISO 17025-certified recombinant enzyme suppliers determines both the premium spread for assay-grade formulations and the elongated procurement cycles that reshape inventory positioning across pharmaceutical and CRO accounts.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on certification depth—FDA bioanalytical method validation compliance commands substantial premia over research-grade supply—and volume scale through multi-year platform contracts. Cost compression in the natural extract tier is intensifying because recombinant batch consistency renders crude preparations obsolete for regulated workflows. Academic institutions exhibit the highest price sensitivity, while large pharmaceutical developers leverage consolidated spend for favorable contract terms.
Supply Chain Analysis
Extended payment terms from supply-chain finance facilities are becoming standard as fermentation infrastructure investments strain working capital for mid-tier producers. Geographic supply concentrates in the United States, Germany, and India, with recombinant production drawing from defined yeast extract, peptone, and carbohydrate feedstock inputs. Single-source vulnerability pervades the qualified supplier base where three integrated conglomerates control GMP-grade distribution. Distribution runs through direct manufacturer relationships that displace traditional reagent distributors in consolidated pharmaceutical procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as large pharmaceutical developers consolidate enzyme procurement into multi-year platform contracts, fragmenting spot-market liquidity and compressing margins for undifferentiated suppliers.
For Market Incumbents: Insulate qualified supplier status by embedding ISO 17025 traceability deeper into regulatory master files ahead of tightening FDA and EMA method transfer requirements. Accelerate backward integration into defined fermentation media supply to buffer margin compression from yeast extract and peptone price volatility. Capture channel control through chromatography-instrument bundling that locks out standalone reagent competitors.
For New Entrants and Emerging Players: Establish a beachhead in the Indian CRO corridor where CDSCO-aligned documentation requirements are ascending but qualified supplier scarcity persists. Target cost-competitive recombinant supply with regulatory traceability matching Western standards as domestic biopharma services firms in Hyderabad and Bangalore build metabolite profiling capabilities. Pursue a go-to-market angle anchored in rapid ISO 17025 accreditation timelines that incumbent certification backlogs cannot match.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors recombinant protein engineering boutiques with embedded quality management systems and regulatory submission experience. Long-term viability hinges on enzyme traceability becoming mandatory across bioanalytical workflows, elevating asset value for documented producers. Watch for FDA guidance updates on analytical method transfer requirements as the inflection signal for accelerated procurement consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 17025 Accreditation Investment | Creates compliance barriers for uncatalogued suppliers while capturing FDA and EMA bioanalytical procurement. |
| Recombinant Fermentation Scale-Up | Compresses batch-to-batch variability below natural extract ceilings for IND-enabling pharmacokinetic studies. |
| Platform Contract Consolidation | Bundles enzyme supply with chromatography and mass spectrometry service agreements to displace spot purchasing. |
| India CRO Channel Development | Captures outsourcing growth in Hyderabad and Bangalore with CDSCO-aligned documentation capabilities. |
| Site-Directed Mutagenesis R&D | Produces engineered variants with narrowed substrate specificity for high-throughput metabolite liberation. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA bioanalytical guidance documents, EMA ICH Q2(R1) submissions, and ISO 17025 accreditation records. Interviews with drug development executives, regulatory affairs leads, CRO procurement managers, and clinical laboratory directors informed demand-side segmentation. Secondary validation drew from ClinicalTrials.gov metabolite study registrations, SEC 10-K filings of life science conglomerates, and customs trade data for enzyme reagent imports. Bottom-up enzyme consumption estimates triangulated against top-down pharmaceutical R&D spending allocations.
Forecast inputs span recombinant versus natural formulation splits, drug development versus diagnostics application shares, and liquid versus lyophilized delivery mode trajectories across the projection horizon. CAGRs derive from segmented volume build-ups calibrated to bioanalytical method validation guideline adoption curves and therapeutic drug monitoring panel expansion rates. Modeled dimensions include product type purity tiers, end-user procurement centralization levels, and regional regulatory cluster stringency.
Sensitivities concentrate around FDA guidance revisions on enzyme activity traceability, EMA analytical method transfer requirement updates, and fermentation input cost volatility. Forecasts reflect assumptions on regulatory timeline adherence and CRO outsourcing trajectory. Macroeconomic contraction in biopharma R&D spending, regulatory documentation requirement deviation, or recombinant production technology disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Microbiology
Microbial Seed Treatment Market
Industrial Microbiology
Cultured Dextrose Market
Industrial Microbiology
Global Microbial Protein Market
Industrial Microbiology
Bacillus Subtilis Market
Industrial Microbiology
Mesophilic Bacteria Market
Industrial Microbiology
Specialty Cultures Market
Industrial Microbiology
Bacterial Antigens Market
Industrial Microbiology
Global Arabinogalactan Market
Industrial Microbiology
Microbiology Testing Market
Industrial Microbiology
Mineral Yeast Market
Industrial Microbiology
Real Time Continuous Microbiological Monitoring Systems Market
Industrial Microbiology
Middle East Feed Probiotics Market
Industrial Microbiology
Global Microbial Based Biological Seed Treatment Market
Industrial Microbiology
Molecular Microbiology Market
Industrial Microbiology
Microbial-Derived Fiber Market
Industrial Microbiology
Europe Microbial Based Biological Seed Treatment Market