
 Sintered Soft Magnetic Material Market | 2026-2036
Sintered Soft Magnetic Material Market Size, Share, and Industry Trends Forecast 2026-2036
Sintered Soft Magnetic Material Market Analytics
Direct supply agreements between powder metallurgy houses and Tier-1 motor suppliers is reshaping how sintered soft magnetic materials reach end users. GKN Sinter Metals Engineering GmbH leverages captive powder production to secure feedstock continuity across European automotive programs. Sumitomo Electric Industries, Ltd. anchors high-frequency ferrite supply for telecom infrastructure throughout Asia. Arnold Magnetic Technologies competes on rare-earth-free alloy formulations that bypass supply chain bottlenecks.
Sintered soft magnetic materials are powder-compacted alloys, typically iron-silicon or iron-nickel compositions, fired below melting point to achieve controlled porosity and magnetic permeability in the range of 500 to 150,000 depending on alloy grade; these materials channel magnetic flux with minimal hysteresis loss in rotating machinery and power conversion equipment. Ferrite grades dominate volume in consumer electronics due to cost position, while nanocrystalline ribbons capture premium margin pools in high-frequency inductor applications. Electric motor laminations from iron powder compacts are gaining share as axial-flux motor architectures proliferate in automotive traction systems.
FCC efficiency standards for power supplies and NHTSA electric vehicle mandates in the United States, alongside REACH substance restrictions and RoHS compliance requirements in Europe, are elevating certification thresholds for magnetic core suppliers. Japan's METI energy conservation standards and China's GB motor efficiency regulations further fragment compliance obligations across manufacturing footprints. Stakeholders must track evolving efficiency tier definitions and material disclosure requirements to maintain market access across jurisdictions.
Market Dynamics
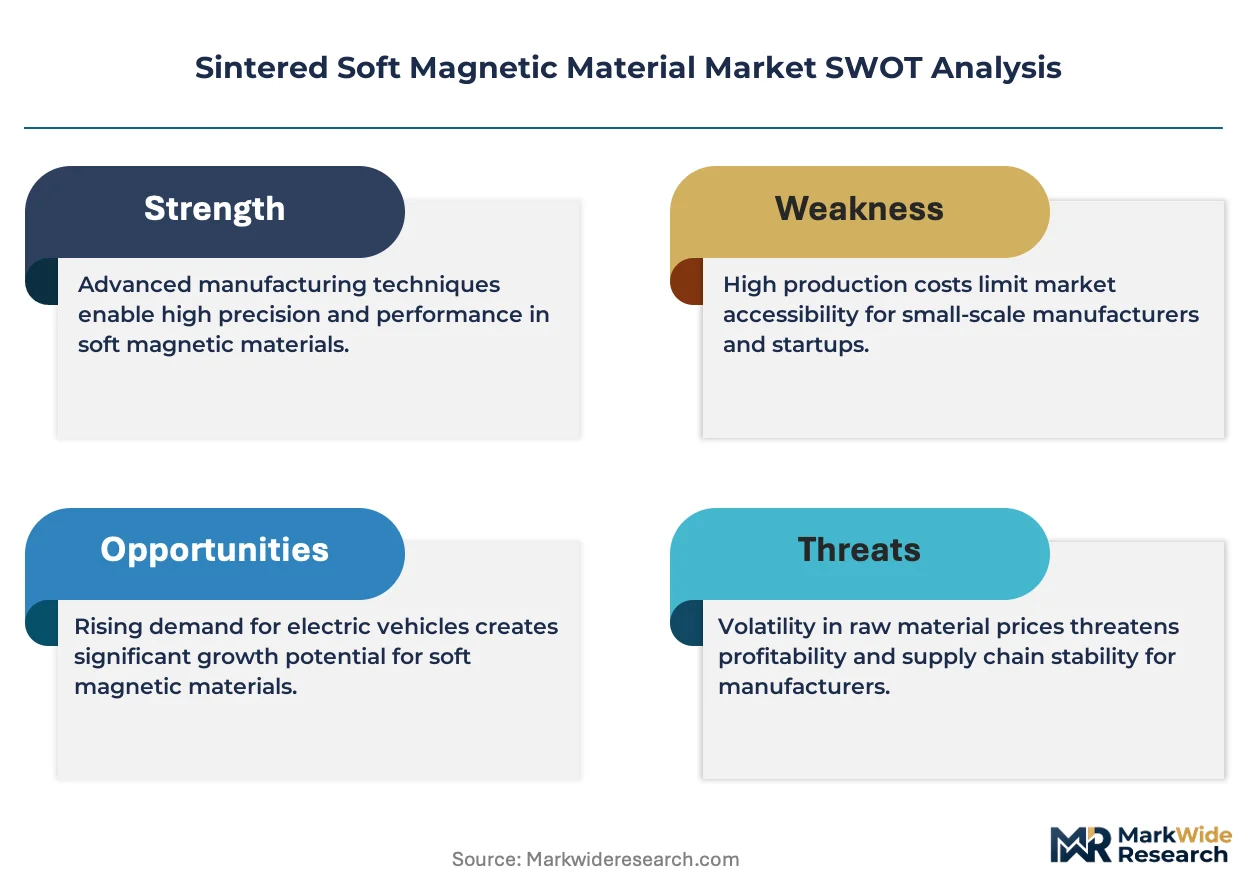
Axial-flux motor architectures in electric vehicles are compressing lamination stack heights and demanding powder-compacted cores with higher magnetic permeability at elevated frequencies, forcing powder metallurgy houses to requalify alloy grades faster than traditional automotive validation cycles permit.
Growth Catalysts
- NHTSA electric vehicle mandates:Federal efficiency requirements in the United States are mandating higher motor performance tiers, pulling sintered core volumes into traction motor supply chains.
- Iron-silicon nanocrystalline ribbons:These materials are capturing premium inductor applications in telecom base stations and data center power supplies.
- East Asian manufacturing clusters:Concentrated demand in Japan and South Korea is anchoring high-volume ferrite production for consumer electronics.
Market Restraints
- Rare-earth oxide price volatility:Neodymium and dysprosium input costs swing with Chinese export quota adjustments, compressing margin predictability for alloy formulators.
- European powder supply concentration:Specialty atomized iron feedstock for high-permeability grades depends on a limited set of German and Swedish producers.
- Permeability ceiling in ferrite grades:Intrinsic saturation flux density limits prevent ferrite cores from serving high-torque automotive traction motors above certain power thresholds.
Strategic Opportunities
- India's PLI scheme for advanced chemistry cell manufacturing:Domestic battery and motor production incentives are creating captive demand for localized sintered magnetic component supply.
- Silicon carbide power electronics convergence:Higher switching frequencies in SiC inverters pair with nanocrystalline cores to shrink magnetics volume in onboard chargers.
- Direct mill-to-motor supplier relationships:Powder houses are bypassing traditional distributor networks to secure long-term offtake agreements with Tier-1 motor assemblers.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous FCC, REACH, RoHS, and METI compliance documentation stretches product launch schedules.
- Powder atomization furnace capacity:Inert gas atomization lines for spherical iron powder require capital outlays with multi-year depreciation horizons.
- Legacy lamination press reconfiguration:Stamping equipment designed for electrical steel sheets demands retooling to handle powder compact feedstock.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sintered Soft Magnetic Material Market |
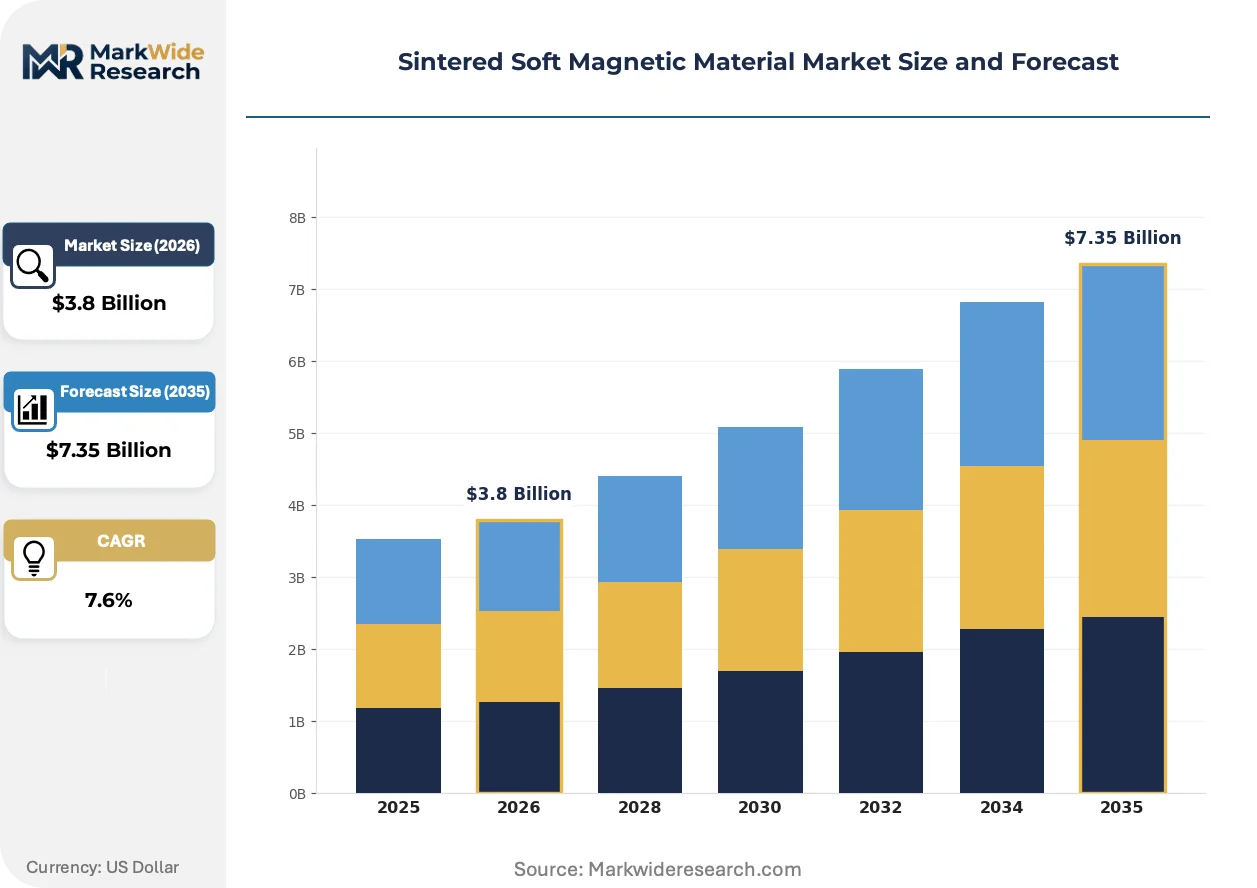
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ferrite, Amorphous, Nanocrystalline, Iron Powder End User: Automotive, Electronics, Telecom, Renewable Energy Application: Transformers, Inductors, Magnetic Sensors, Electric Motors Form: Compacts, Laminations, Cores, Shapes |
| Companies Covered | GKN Sinter Metals Engineering GmbH, Sumitomo Electric Industries, Ltd., Arnold Magnetic Technologies, Daido Steel Co. Ltd., Mate Co. Ltd., Meyer Sintermetall AG, Steward Advanced Materials LLC, Sintered Specialties, LLC, VACUUMSCHMELZE GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sintered Soft Magnetic Material Market Evolving Landscape
Computational alloy design and additive manufacturing of magnetic cores are collapsing traditional trial-and-error development cycles, while regulatory efficiency tiers fragment across major economies.
Additive manufacturing of soft magnetic composites is virtualizing conventional powder compaction and sintering workflows. Tier-1 motor suppliers in Germany and Japan are piloting laser powder bed fusion for prototype stator cores. This technology is virtualizing the tooling-intensive prototyping phase, compressing design iteration from months to weeks.
China's GB motor efficiency regulations and dual carbon goals are tightening material disclosure requirements for imported magnetic components. Manufacturers must now document alloy composition and embodied carbon across supply chains. High-frequency ferrite grades for industrial motor drives face the steepest compliance ramps.
Automotive buyers are consolidating magnetic core suppliers into approved vendor lists with multi-year volume commitments. Tier-1 motor assemblers in South Korea and the United States are displacing spot-market purchasing with direct mill relationships. This concentration is most visible in traction motor programs where traceability requirements exclude fragmented supplier bases.
Sintered Soft Magnetic Material Market Segmentation
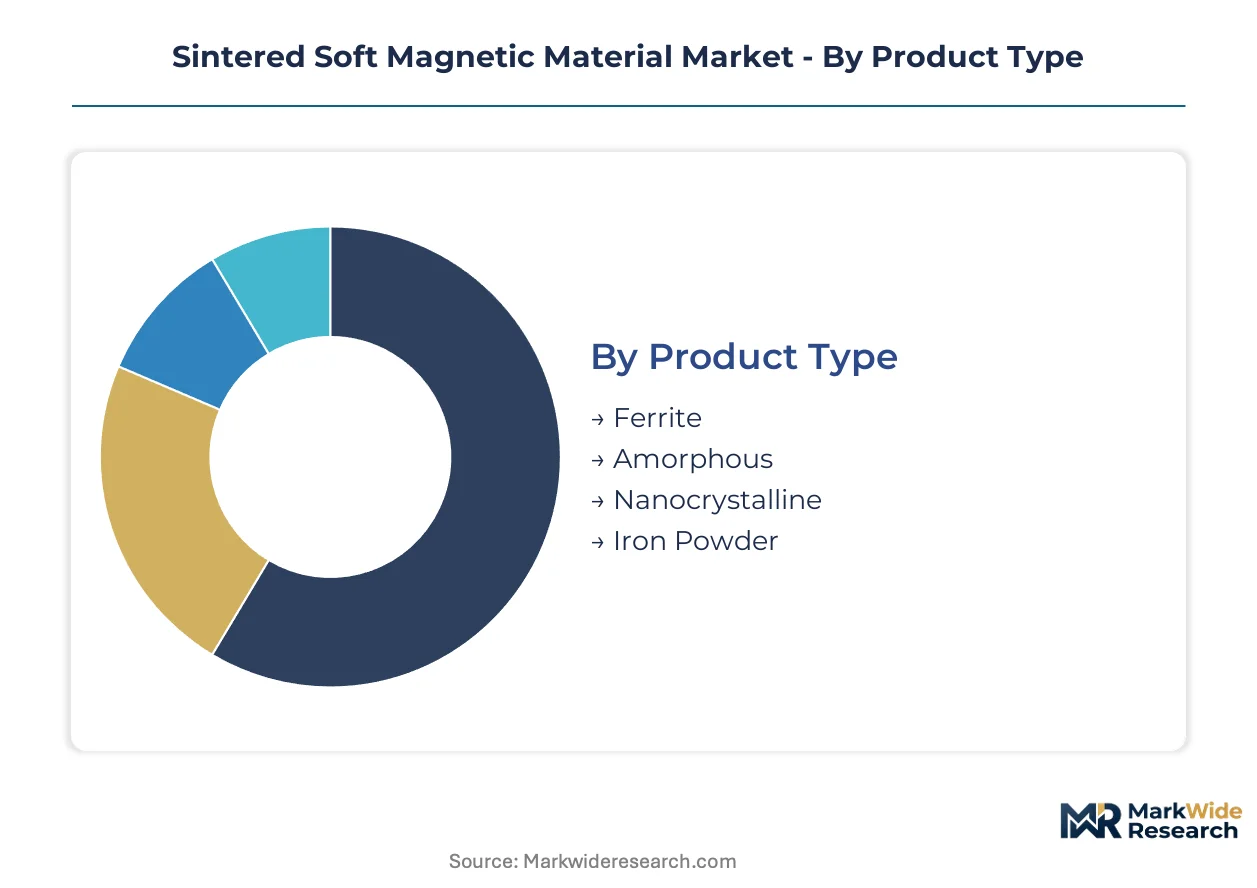
Sintered soft magnetic materials serve fundamentally different performance regimes across product grades, end-use sectors, and physical forms. Segmentation reveals where powder metallurgy houses must prioritize alloy development versus where cost-optimized ferrite volumes dominate procurement decisions.
Product Type:
Cost tier differentiation separates commodity ferrite volumes from premium nanocrystalline ribbons commanding specialized inductor applications.
- Ferrite:Manganese-zinc and nickel-zinc compositions deliver permeability ranges of 500-15,000 at unit costs below competing alloy systems. Consumer electronics procurement in Japan and South Korea anchors high-volume production for switch-mode power supplies and EMI suppression cores.
- Amorphous:Rapidly solidified iron-based alloys exhibit near-zero crystalline anisotropy, enabling core losses below 0.2 W/kg at 50 Hz. Distribution transformer deployments in India and utility-scale grid infrastructure in Germany absorb ribbon output from dedicated melt-spinning lines.
- Nanocrystalline:Controlled crystallization of amorphous precursors yields grain sizes below 20 nanometers, combining high permeability with saturation flux density approaching silicon steel levels. Telecom base station power supplies and onboard EV chargers drive specification tightening.
- Iron Powder:Atomized and reduced iron grades compacted with organic binders enable three-dimensional magnetic circuit designs impossible with laminated electrical steel. Axial-flux motor stators in European automotive programs exploit this formability advantage.
Ferrite commands the established base. The steepest expansion runs through nanocrystalline grades pairing with silicon carbide power electronics.
End User:
Application maturity varies sharply across sectors, with automotive traction systems demanding validation cycles far exceeding consumer electronics timelines.
- Automotive:Traction motor laminations and onboard charging magnetics now specify sintered cores with temperature stability to 180°C. NHTSA efficiency mandates and China's GB motor standards are synchronizing performance thresholds across export markets.
- Electronics:Ferrite cores for smartphones, laptops, and white goods represent the highest-volume outlet, though margin compression from Asian contract manufacturers limits pricing power. Surface-mount inductor miniaturization continues driving core geometry innovation.
- Telecom:5G infrastructure power amplifiers and base station rectifiers require high-frequency ferrite grades with stable permeability through the 1-100 MHz range. METI efficiency standards in Japan and FCC Part 15 emissions rules shape procurement specifications.
- Renewable Energy:Wind turbine generators and solar inverter magnetics favor amorphous and nanocrystalline cores where core loss minimization justifies material premiums. India's PLI scheme for domestic renewable manufacturing is localizing demand.
Electronics maintains volume leadership. Automotive is climbing the fastest as axial-flux architectures proliferate.
Application:
Functional requirements diverge between static flux-concentration devices and rotating machinery with cyclic magnetization.
- Transformers:Distribution and power transformer cores favor amorphous ribbons where no-load loss regulations in the US and EU create compliance-driven substitution from grain-oriented silicon steel. Core weight reduction of 60-70% versus conventional laminations supports total cost justification.
- Inductors:Power conversion magnetics for data centers and EV chargers specify nanocrystalline or high-frequency ferrite grades capable of operating above 100 kHz without excessive core heating. Silicon carbide inverter adoption is pushing switching frequencies upward.
- Magnetic Sensors:Fluxgate and Hall-effect sensor cores demand precise permeability control and temperature coefficient stability. Iron-nickel sintered compacts serve position sensing in automotive and industrial automation.
- Electric Motors:Sintered soft magnetic materials enable complex stator geometries for axial-flux and transverse-flux motor topologies. Powder compaction permits slot shapes and cooling channels impractical with stamped laminations.
Transformers anchor the incumbent revenue base. Electric motors are gaining share fastest as traction motor architectures diversify.
Form:
Manufacturing process selection determines achievable geometric complexity and magnetic property isotropy.
- Compacts:Uniaxial or isostatic pressing of atomized powders produces near-net-shape components with controlled density gradients. Automotive sensor housings and small motor stators exploit this forming flexibility.
- Laminations:Powder metal sheets compacted and sintered into strip form enable stacked core constructions mimicking electrical steel processing. Thickness control below 0.5 mm remains technically challenging versus rolled strip.
- Cores:Toroidal, E-core, and pot-core geometries dominate inductor and transformer applications. Ferrite cores for consumer electronics are produced in billion-unit annual volumes from automated pressing and sintering lines.
- Shapes:Custom-profiled components for specific magnetic circuit designs include arc segments for permanent magnet motor flux returns and complex three-dimensional stator geometries. Additive manufacturing is emerging for prototyping these specialized forms.
Cores dominate current output volumes. Compacts are expanding most quickly as motor designers explore topology optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Japanese and South Korean manufacturing clusters where ferrite production scales anchor cost curves, while European powder metallurgy houses command premiums on automotive-grade alloy formulations.
China
Dual carbon goals and GB motor efficiency regulations are tightening material disclosure requirements for imported magnetic components. The country's national standards body mandates embodied carbon documentation across supply chains. Yangtze River Delta manufacturing corridors host high-volume ferrite pressing operations serving domestic EV traction motor programs.
Japan
METI energy conservation standards shape procurement specifications for high-frequency ferrite grades in telecom infrastructure. The regulator's efficiency tiers fragment compliance obligations for magnetic core suppliers. Kanto region powder metallurgy houses anchor nanocrystalline ribbon production for data center power supplies.
Germany
REACH substance restrictions and RoHS compliance requirements elevate certification thresholds for magnetic core suppliers serving automotive programs. ECHA documentation protocols stretch product launch schedules for alloy formulators. Bavarian atomized iron feedstock producers supply specialty spherical powders to European motor manufacturers.
South Korea
Tier-1 motor assemblers are displacing spot-market purchasing with direct mill relationships for traction magnetics. The country's national industrial regulator synchronizes efficiency mandates with export market requirements. Seoul Capital Area manufacturing clusters concentrate ferrite core output for consumer electronics contract manufacturers.
United States
NHTSA electric vehicle mandates and FCC efficiency standards for power supplies pull sintered core volumes into traction motor supply chains. FERC grid modernization programs support amorphous ribbon deployment in distribution transformers. Midwest industrial corridors host powder compaction operations reconfiguring legacy lamination presses for automotive programs.
Sintered Soft Magnetic Material Market Competitive Landscape
Captive powder producers and independent alloy formulators split the market along feedstock control lines. Consolidation concentrates among German and Japanese houses with in-house atomization capacity, while North American and Chinese competitors rely on merchant powder supply. Three archetypes dominate: vertically integrated metallurgy houses, specialty magnetic component fabricators, and rare-earth-free alloy innovators. Capacity expansion and direct mill-to-motor supplier relationships represent the dominant competitive moves.
Within the captive supply tier, GKN Sinter Metals Engineering GmbH exemplifies European powder metallurgy integration, while Sumitomo Electric Industries, Ltd. anchors high-frequency ferrite positioning across Asian telecom infrastructure. Arnold Magnetic Technologies occupies a position representing rare-earth-free formulation strategies that bypass supply chain bottlenecks.
| Leading Market Players |
|---|
| GKN Sinter Metals Engineering GmbH |
| Sumitomo Electric Industries, Ltd. |
| Arnold Magnetic Technologies |
| Daido Steel Co. Ltd. |
| Mate Co. Ltd. |
| Meyer Sintermetall AG |
| Steward Advanced Materials LLC |
| Sintered Specialties, LLC |
| VACUUMSCHMELZE GmbH & Co. KG |
| Others |
Value Network & Pricing Analysis
Yangtze River Delta ferrite pressing corridors anchor global cost curves through billion-unit annual throughput, translating scale economics into pricing power that German atomized iron specialists cannot match without alloy premium positioning.
Pricing Analysis
Configured-to-order pricing for automotive-grade nanocrystalline ribbons commands spreads exceeding standard ferrite cores by multiples reflecting certification tier differentiation. Contract-based long-term offtake agreements dominate traction motor procurement, with NHTSA efficiency mandates and China's GB motor standards compressing margin buffers for non-compliant suppliers. Volume scale and vertical integration into captive powder production represent the primary price differentiation drivers. Spot-market buyers in consumer electronics exhibit highest price sensitivity, while automotive Tier-1s prioritize traceability and temperature stability to 180°C over unit cost.
Supply Chain Analysis
Tariff exposure between China and Western automotive markets dominates supply chain risk calculations for magnetic core suppliers. German and Swedish atomized iron feedstock producers, Japanese nanocrystalline ribbon melt-spinning lines, and Chinese ferrite pressing operations concentrate geographic supply. Spherical iron powder, rare-earth oxide inputs, and organic binder chemistries constitute critical raw material dependencies. Single-source vulnerability in specialty atomized grades threatens production continuity. Distribution runs through direct mill-to-motor supplier relationships displacing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of inert gas atomization furnace capacity for spherical iron powder constrains supply expansion, rewarding stakeholders who secure feedstock control before qualification cycles complete for axial-flux motor programs.
For Market Incumbents: Insulate market position by deepening backward integration into captive powder production and securing multi-year volume commitments with South Korean and United States Tier-1 motor assemblers. Rare-earth oxide price volatility and emerging rare-earth-free alloy competitors threaten margin predictability. Prioritize certification investment for simultaneous FCC, REACH, RoHS, and METI compliance to exclude fragmented supplier bases from approved vendor lists. For New Entrants and Emerging Players: India's PLI scheme for advanced chemistry cell manufacturing presents the most penetrable geographic entry point, with domestic battery and motor production incentives creating captive demand for localized sintered magnetic component supply. Target axial-flux motor stator prototyping services as a beachhead application, leveraging additive manufacturing to compress design iteration timelines before scaling to production volumes. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors powder metallurgy houses with in-house atomization capacity and established automotive qualification records over merchant powder-dependent competitors. Long-term viability hinges on silicon carbide power electronics convergence driving nanocrystalline core specification tightening. Monitor India's renewable energy manufacturing localization and China's dual carbon enforcement intensity as inflection indicators for regional demand shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Atomized Powder Production | GKN Sinter Metals Engineering GmbH exemplifies European feedstock security for automotive programs. |
| Direct Mill-to-Motor Supplier Relationships | Sumitomo Electric Industries anchors high-frequency ferrite supply across Asian telecom infrastructure. |
| Rare-Earth-Free Alloy Formulation Development | Arnold Magnetic Technologies bypasses neodymium and dysprosium supply chain bottlenecks. |
| Additive Manufacturing Prototyping Capability | German and Japanese Tier-1 suppliers compress stator core design iteration from months to weeks. |
| Multi-Jurisdiction Certification Investment | REACH, RoHS, FCC, and METI compliance documentation stretches launch schedules for alloy formulators. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and industry association publications. Powder metallurgy executives, Tier-1 motor supplier procurement leads, and automotive platform engineers provided operational perspective. Technical R&D directors at ferrite pressing operations and distribution channel partners contributed supply chain intelligence. Bottom-up volume modeling triangulates against top-down market sizing from production database analysis.
Forecast inputs span product type segmentation across ferrite, amorphous, nanocrystalline, and iron powder grades; end-use sectors including automotive, electronics, telecom, and renewable energy; and form factors from compacts through laminations and cores. CAGRs derive from regression analysis of historical penetration patterns and driver elasticity assessment. Axial-flux motor architecture proliferation and silicon carbide inverter switching frequency escalation constitute industry-specific demand inputs across the projection horizon.
Practitioners should monitor rare-earth oxide export quota adjustments, India's PLI scheme implementation pace, and European atomization furnace capacity expansion for early signals of supply-demand rebalancing. Forecasts reflect assumptions regarding regulatory efficiency tier synchronization and automotive validation cycle compression. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Magnetic Materials
Rare Earth Magnet Market
Magnetic Materials
Magnetorheological Fluid Market
Magnetic Materials
Magnetite Nanoparticles Market
Magnetic Materials
Europe Magnet Wire Market
Magnetic Materials
Magnet Wire Market
Magnetic Materials
Japan Neodymium Iron Boron Magnet Market
Magnetic Materials
North America Magnet Wire Market
Magnetic Materials
Neodymium-Iron-Boron Magnet Market
Magnetic Materials
Superconducting Magnets Market
Magnetic Materials
Middle East and Africa Magnet Wire Market
Magnetic Materials
Global Bonded Magnet Market
Magnetic Materials
Reduced Iron Powder Market
Magnetic Materials
Global Non Grain-Oriented Electrical Steel Market
Magnetic Materials
Asia-Pacific Magnet Wire Market
Magnetic Materials
Magnetic Plastics Market
Magnetic Materials
North America Samarium Cobalt Magnets Market