
 High Purity Carbonyl Iron Powder (CIP) Market | 2026-2036
High Purity Carbonyl Iron Powder (CIP) Market Size, Share, and Industry Trends Forecast 2026-2036
High Purity Carbonyl Iron Powder (CIP) Market Foresight
Market Context with Strategic Players
Advanced gas atomization and carbonyl decomposition techniques is rewriting how high-purity iron feedstock gets specified for electromagnetic and thermal applications. BASF leverages its integrated carbonyl chemistry infrastructure to sustain premium-grade output for European automotive inductor manufacturers. Jinchuan Group anchors Chinese domestic supply through captive nickel-iron refining complexes in Gansu province. Jiangsu Tianyi Super Fine Metal Powder competes on micronization scale, controlling sub-5-micron production lines that serve soft magnetic composite producers in East Asia.
Technical Definition and Structural Segments
High purity carbonyl iron powder refers to spherical metallic iron particles synthesized through thermal decomposition of iron pentacarbonyl, typically achieving purity levels exceeding 99.5% with controlled particle sizes from sub-micron to 45-micron ranges. Its primary industrial purpose centers on delivering consistent magnetic permeability, high saturation magnetization, and predictable thermal conductivity in electromagnetic cores, radar absorption coatings, and metal injection molding feedstocks. Micronized powder dominates current revenue pools due to entrenched demand from radio frequency shielding and inductive component manufacturers, while nanopowder represents the fastest-expanding category as additive manufacturing process developers validate finer grain structures for near-net-shape magnetic parts. Powder metallurgy as an end-use industry commands durable volume, though additive manufacturing applications are capturing disproportionate investment attention from CIP producers seeking margin expansion beyond conventional pressing-and-sintering workflows.
Regulatory Frame and Forward-Looking Close
China's SAMR enforces GB standards for powder metallurgy raw materials that mandate specific surface area and impurity thresholds, while REACH in Europe requires full substance registration for carbonyl-derived powders used in chemical catalyst and thermal management applications. The U.S. EPA oversees air emissions from carbonyl decomposition facilities under Clean Air Act provisions, constraining capacity expansion timelines for domestic producers. Stakeholders must monitor evolving purity certifications from ISO and IEC working groups, as next-generation electric drivetrain and 5G infrastructure specifications will likely impose stricter particle morphology requirements than current automotive or consumer electronics standards.
Market Dynamics
Carbonyl iron powder supply chains are tightening around additive manufacturing qualification timelines, as aerospace and medical device producers demand batch-to-batch consistency that exceeds legacy powder metallurgy specifications.
Growth Catalysts
- GB standards compliance:China's SAMR-mandated surface area and impurity thresholds for powder metallurgy raw materials are accelerating domestic producer upgrades, filtering substandard suppliers from Jiangsu and Zhejiang manufacturing clusters.
- Binder jetting adoption:Soft magnetic composite manufacturers are qualifying sub-5-micron CIP grades for near-net-shape inductor cores, displacing conventional pressed-and-sintered geometries in radio frequency shielding applications.
- REACH registration:Full substance registration requirements for carbonyl-derived powders in Europe are consolidating qualified supplier lists for chemical catalyst and thermal management compounders.
Market Restraints
- Iron pentacarbonyl feedstock concentration:Carbonyl decomposition facilities depend on limited merchant supply of the precursor chemical, constraining capacity expansion timelines for domestic CIP producers.
- EPA air emissions oversight:Clean Air Act provisions governing carbonyl decomposition emissions impose multi-year permitting cycles on new US production capacity.
- Gas atomization substitution:Water- and gas-atomized iron powders achieving comparable magnetic permeability at lower purity grades threaten CIP's position in cost-sensitive inductive component segments.
Strategic Opportunities
- 5G infrastructure buildout:Next-generation base station specifications from IEC working groups will impose stricter particle morphology requirements than current consumer electronics standards, opening premium-grade CIP demand.
- Laser powder bed fusion:Medical device producers in Germany and Switzerland are validating finer grain structures for patient-specific magnetic implants, creating white space beyond conventional metal injection molding.
- Dual carbon goals:China's MEE incentives for energy-efficient electromagnetic components are redirecting procurement toward high-saturation magnetization materials that reduce core losses in electric drivetrains.
Industry Challenges
- Particle morphology certification:ISO working groups have yet to finalize sphericality and surface roughness benchmarks for additive manufacturing-grade CIP, forcing producers to maintain multiple internal specification libraries.
- Carbonyl chemist scarcity:Thermal decomposition process expertise resides with a narrow cohort of specialists trained at legacy BASF and Jinchuan facilities, limiting workforce mobility for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Purity Carbonyl Iron Powder (CIP) Market |
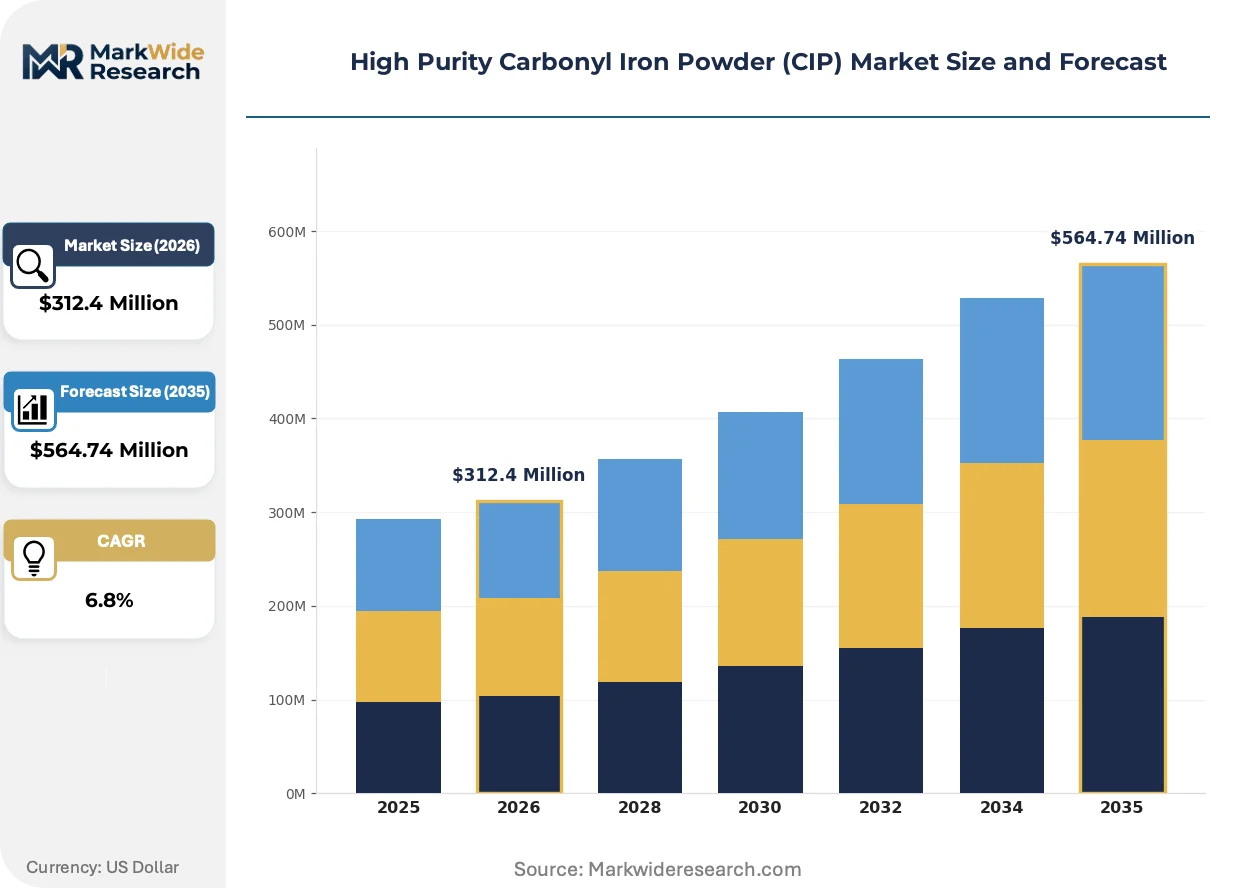
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Micronized Powder, Coarse Powder, Composite Powder, Nanopowder End Use Industry: Electronics, Automotive Components, Medical Device Manufacturing, Powder Metallurgy Application: Magnetic Materials, Chemical Catalysts, Thermal Management, Additive Manufacturing Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesale |
| Companies Covered | Jinchuan Group, Shaanxi Xinghua Chemistry, BASF, Reade Advanced Materials, Yuean Metal, Sintez-CIP, Jiangsu Tianyi Super Fine Metal Powder, Stanford Advanced Materials, CNPC Powder, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Purity Carbonyl Iron Powder (CIP) Market Shifts & Advancements
Digital process control and in-situ quality monitoring are compressing batch qualification cycles, allowing CIP producers to serve additive manufacturing's shorter development timelines without sacrificing electromagnetic consistency.
Plasma spheroidization post-processing is virtualizing traditional carbonyl decomposition as the sole pathway to sub-10-micron spherical iron powders. Gas atomization specialists in Japan and Germany are adopting this hybrid approach to penetrate soft magnetic composite markets previously locked by BASF's integrated carbonyl chemistry. The technology is virtualizing geographic supply concentration by enabling non-captive producers to meet aerospace inductor specifications.
REACH substance registration deadlines for carbonyl-derived powders are forcing European compounders to document full supply chain substance flows. The regulation is compressing qualified supplier lists to producers with pre-registered iron pentacarbonyl decomposition streams. Chemical catalyst manufacturers in the Netherlands and Belgium are consolidating procurement around SAMR-certified Chinese suppliers to preempt registration gaps.
Buyer concentration among aerospace tier-1s and medical device OEMs is compressing switching cycles from annual to quarterly batch qualification reviews. Long-term supply agreements with fixed purity bands are displacing spot-market CIP procurement for binder jetting applications. This pattern is most visible in Germany's Bavarian manufacturing corridor, where Siemens Healthineers and regional aerospace suppliers have synchronized supplier audit schedules.
High Purity Carbonyl Iron Powder (CIP) Market Segmentation
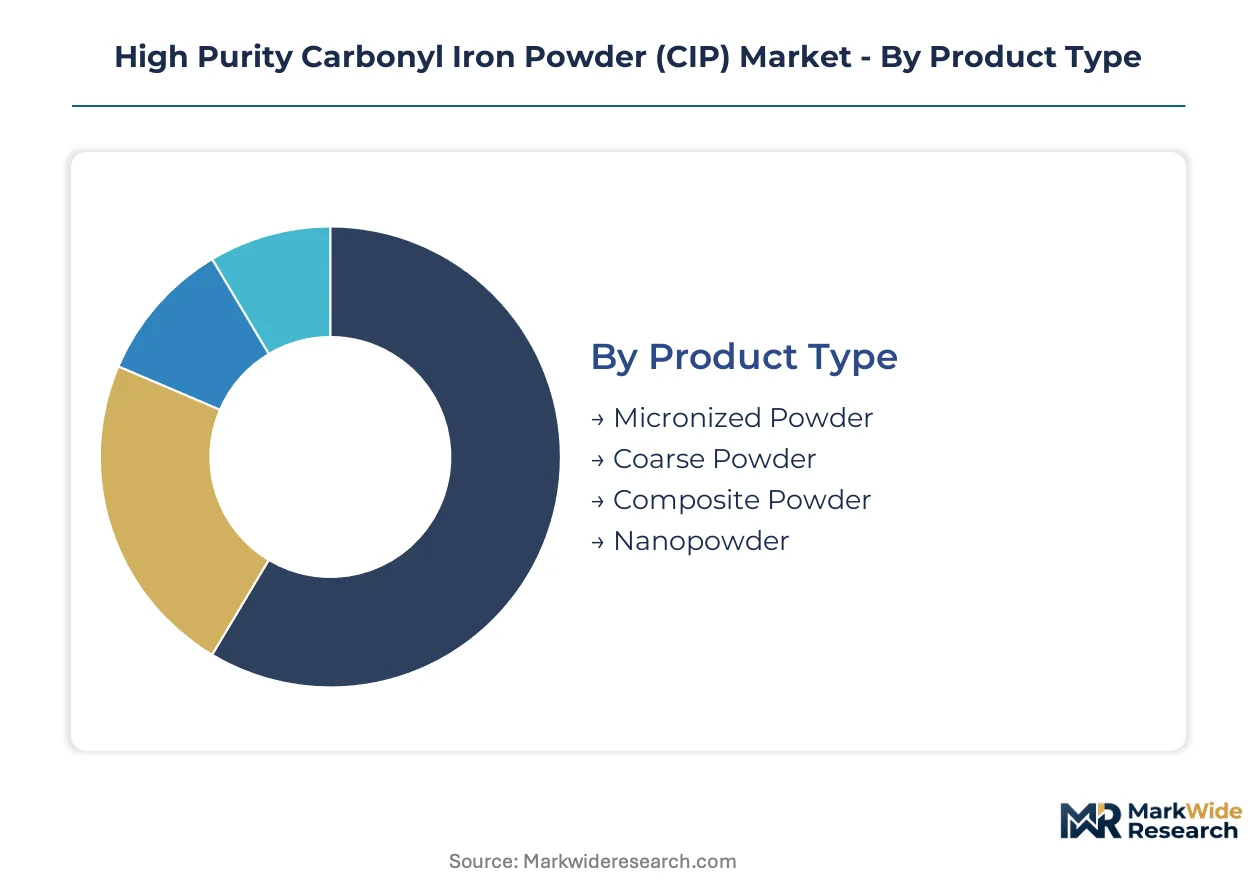
Carbonyl iron powder specifications diverge sharply across electromagnetic, thermal, and chemical applications, with purity thresholds and particle morphology dictating supplier qualification protocols. End-use industries impose incompatible certification requirements that fragment procurement patterns and reshape channel economics.
Product Type:
Particle size distribution determines magnetic permeability performance and manufacturing process compatibility across soft magnetic composite and additive manufacturing workflows.
- Micronized Powder:Sub-5-micron spherical particles deliver consistent saturation magnetization for radio frequency shielding and inductive component cores. Demand concentrates in East Asian manufacturing clusters serving 5G base station and consumer electronics producers, with Jiangsu and Zhejiang provinces controlling installed micronization capacity.
- Nanopowder:Sub-micron grain structures below 100 nanometers enable near-net-shape magnetic parts through laser powder bed fusion and binder jetting. German and Swiss medical device manufacturers are validating finer grades for patient-specific implants, displacing conventional metal injection molding in high-value segments.
- Coarse Powder:10-45 micron fractions serve legacy powder metallurgy pressing-and-sintering workflows with lower purity tolerances.
- Composite Powder:Surface-coated variants integrate polymer binders or ceramic layers for specialized thermal management compounds.
Micronized powder holds installed capacity. Nanopowder is rotating up the share rankings.
End Use Industry:
Application-specific purity certifications and batch consistency requirements segment procurement patterns across electromagnetic, automotive, and medical verticals.
- Electronics:Inductor and transformer manufacturers specify 99.5%+ purity grades with controlled surface area for core loss minimization. Radio frequency component producers in Bavaria and Shenzhen drive qualification timelines for sub-5-micron material, with IEC working groups imposing stricter particle morphology benchmarks than legacy consumer electronics standards.
- Automotive Components:Electric drivetrain producers prioritize high-saturation magnetization materials to reduce core losses in motor and inverter assemblies. China's MEE incentives for energy-efficient electromagnetic components redirect procurement toward premium-grade CIP, filtering substandard suppliers from domestic qualification lists.
- Medical Device Manufacturing:Implantable magnetic components require biocompatibility certification and batch traceability exceeding industrial grades.
- Powder Metallurgy:Structural parts producers utilize cost-optimized grades where magnetic performance is secondary to mechanical strength.
Electronics commands durable volume. Automotive components are climbing the fastest.
Application:
Functional performance requirements—magnetic, catalytic, thermal, or geometric—determine particle specification and supplier selection criteria.
- Magnetic Materials:Soft magnetic composites for inductor cores and electromagnetic shielding demand spherical particle morphology with narrow size distribution. Aerospace tier-1 suppliers have compressed batch qualification cycles from annual to quarterly reviews, locking in long-term supply agreements with fixed purity bands.
- Additive Manufacturing:Binder jetting and laser powder bed fusion processes validate finer grain structures for near-net-shape magnetic parts. Process developers in Germany and Switzerland are displacing conventional pressed-and-sintered geometries, creating white space beyond traditional metal injection molding markets.
- Chemical Catalysts:Iron pentacarbonyl-derived powders serve Fischer-Tropsch and hydrogenation processes with surface area specifications distinct from electromagnetic grades.
- Thermal Management:High-thermal-conductivity compounds utilize CIP as filler material in interface pads and gap fillers.
Magnetic materials holds installed capacity. Additive manufacturing is rotating up the share rankings.
Distribution Channel:
Volume scale and certification complexity segment channel economics, with qualified supplier lists consolidating around direct relationships for aerospace and medical applications.
- Direct Sales:Long-term supply agreements with fixed purity bands dominate aerospace and medical device procurement, displacing spot-market transactions. Siemens Healthineers and regional Bavarian aerospace suppliers have synchronized supplier audit schedules, compressing switching cycles and locking in multi-year contracts.
- Distributors:Regional stocking points serve mid-volume electronics and automotive producers with standardized grade portfolios.
- Online Retail:Small-lot procurement for research and development applications operates through specialized chemical supply platforms.
- Wholesale:Bulk material flows serve powder metallurgy compounders with lower certification requirements.
Direct sales holds installed capacity. Distributors are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German additive manufacturing equipment makers import sub-5-micron CIP grades from Jiangsu and Zhejiang province producers to supply Bavarian medical device manufacturers qualifying laser powder bed fusion processes for patient-specific magnetic implants.
China
Domestic electric vehicle producers specify high-saturation magnetization CIP grades for motor and inverter core assemblies. SAMR-enforced GB standards for powder metallurgy raw materials mandate surface area and impurity thresholds that filter substandard suppliers from Jiangsu and Zhejiang manufacturing clusters where micronization capacity has expanded significantly.
Germany
Siemens Healthineers and regional aerospace suppliers synchronize quarterly batch qualification reviews for binder jetting feedstocks. REACH substance registration requirements for carbonyl-derived powders consolidate qualified supplier lists for chemical catalyst compounders in the Netherlands and Belgium who procure from SAMR-certified Chinese sources.
United States
EPA Clean Air Act provisions governing carbonyl decomposition emissions impose multi-year permitting cycles that constrain domestic capacity expansion timelines. Aerospace tier-1 suppliers in California and Texas have compressed switching cycles from annual to quarterly reviews, locking in long-term supply agreements with fixed purity bands for radar absorption coatings.
Switzerland
Swissmedic biocompatibility certification requirements for implantable magnetic components exceed industrial-grade specifications. Medical device OEMs in the Basel-Zurich corridor validate finer grain structures for patient-specific implants, creating demand white space beyond conventional metal injection molding markets served by German process developers.
Japan
METI incentives for energy-efficient electromagnetic components redirect procurement toward premium-grade CIP that reduces core losses in next-generation electric drivetrains. Gas atomization specialists in the Chubu region adopt plasma spheroidization post-processing to penetrate soft magnetic composite markets previously locked by integrated carbonyl chemistry producers.
High Purity Carbonyl Iron Powder (CIP) Market Competitive Landscape
On the supply side, the industry is bifurcated between integrated carbonyl chemistry operators and specialized micronization houses. The vendor base clusters around two dominant production pathways: captive iron pentacarbonyl decomposition facilities and hybrid gas atomization-plus-spheroidization operations. Strategic archetypes include integrated chemical conglomerates with backward control over precursor supply, regional powder metallurgy specialists with sub-5-micron scale capabilities, and materials science distributors bridging qualification gaps for additive manufacturing end-users. Dominant competitive moves center on multi-year direct supply agreements with fixed purity bands and plasma spheroidization technology licensing to circumvent carbonyl decomposition capacity constraints.
Among integrated chemical operators, BASF represents the archetype of European carbonyl chemistry infrastructure serving automotive inductor manufacturers. Jinchuan Group anchors Chinese domestic supply through Gansu province refining complexes. Jiangsu Tianyi Super Fine Metal Powder occupies a position within the specialized micronization tier, controlling production lines that serve East Asian soft magnetic composite producers.
| Leading Market Players |
|---|
| Jinchuan Group |
| Shaanxi Xinghua Chemistry |
| BASF |
| Reade Advanced Materials |
| Yuean Metal |
| Sintez-CIP |
| Jiangsu Tianyi Super Fine Metal Powder |
| Stanford Advanced Materials |
| CNPC Powder |
| Others |
Supply & Pricing Matrix
The Shanghai-Rotterdam maritime corridor carries carbonyl iron powder shipments where container rate volatility amplifies price spreads between integrated producers and hybrid gas atomization specialists. BASF's Ludwigshafen complex and Jiangsu Tianyi's Zhejiang facilities leverage proximity to port infrastructure to compress landed costs for European additive manufacturers, while inland Chinese producers absorb rail freight premiums that widen their disadvantage against coastal competitors.
Pricing Analysis
Sub-micron nanopowder commands 40-60% premiums over micronized grades as laser powder bed fusion qualification timelines compress, while coarse 10-45 micron fractions face erosion from water-atomized substitutes. Pricing stratifies across aerospace-certified, automotive-grade, and industrial-economy tiers with differentiation driven by SAMR certification status and batch traceability depth. Cost compression in the coarse powder segment is intensifying as gas atomization rivals achieve comparable magnetic permeability at lower purity thresholds. Mid-volume electronics producers exhibit highest price sensitivity, whereas medical device OEMs in Switzerland and Germany prioritize specification adherence over unit economics.
Supply Chain Analysis
Iron pentacarbonyl feedstock availability centers on BASF's European carbonyl chemistry infrastructure and Jinchuan Group's Gansu refining complexes, with merchant supply scarcity constraining new entrant capacity additions. Downstream distribution runs through direct long-term agreements for aerospace and medical applications, while regional distributors serve mid-tier electronics and automotive producers with standardized grade portfolios. Single-source vulnerability pervades the sub-5-micron segment where plasma spheroidization capacity remains concentrated among Japanese and German equipment operators. Raw material dependencies extend to nickel-iron ore concentrates, high-purity carbon monoxide, and specialized micronization media.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The high purity carbonyl iron powder market functions as a regulatory-moat arena where SAMR certification and REACH pre-registration create switching costs that entrench qualified suppliers against unregistered competitors.
For Market Incumbents: Insulate market position by deepening backward integration into iron pentacarbonyl production to neutralize feedstock scarcity threats from limited merchant suppliers. Expand sub-5-micron capacity in Jiangsu and Zhejiang provinces ahead of IEC particle morphology standard finalization, locking in aerospace tier-1 relationships before plasma spheroidization rivals achieve qualification parity. For New Entrants and Emerging Players: Establish a beachhead in thermal management compounds where surface-coated composite powders face lower certification barriers than electromagnetic grades. Target European chemical catalyst compounders seeking SAMR-certified alternatives to REACH registration gaps, leveraging distributor relationships to bypass direct aerospace qualification timelines. For Investors and Strategic Acquirers: Specialized micronization houses with captive sub-5-micron lines and existing SAMR certification represent the most defensible acquisition archetype as additive manufacturing qualification cycles compress. Plasma spheroidization technology licensors in Japan's Chubu region offer exposure to hybrid production pathways that circumvent carbonyl decomposition capacity constraints. Monitor IEC working group publication schedules as the critical inflection signal for premium-grade demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Iron Pentacarbonyl | Neutralizes feedstock scarcity that constrains Jinchuan and BASF competitors. |
| Plasma Spheroidization Licensing | Enables Japanese gas atomization specialists to penetrate soft magnetic composite markets. |
| SAMR Certification Investment | Filters substandard Jiangsu and Zhejiang suppliers from European compounder procurement lists. |
| Long-term Supply Agreement with Fixed Purity Bands | Locks in Bavarian aerospace tier-1s against quarterly batch qualification compression. |
| Sub-5-Micron Capacity Expansion | Captures 5G infrastructure buildout before IEC morphology standards impose stricter benchmarks. |
Research Methodology
Operator-level perspectives from carbonyl decomposition plant managers, powder metallurgy procurement leads at automotive OEMs, additive manufacturing process engineers, and SAMR certification auditors anchored the qualitative base. Secondary validation drew from customs trade data for iron powder shipments, SEC filings of integrated chemical conglomerates, GB standards documentation, and REACH registration databases. Bottom-up capacity assessments across Jiangsu and Zhejiang manufacturing clusters were triangulated against top-down demand modeling from electronics and automotive end-use segments.
Scenario-bracketing framed projections across the analysis window with low, base, and high cases reflecting alternative IEC standard implementation timelines and iron pentacarbonyl supply disruption probabilities. Segmentation dimensions encompassed particle size tier, end-use industry, application function, and distribution channel structure. CAGRs were derived from elasticity-adjusted volume projections incorporating substitution effects from gas atomization technologies. Forecast inputs included electric vehicle motor core specifications from China's MEE incentive programs and 5G base station deployment schedules from German equipment manufacturers.
Stress conditions across iron pentacarbonyl feedstock availability, EPA permitting delays, and plasma spheroidization technology diffusion were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding SAMR enforcement consistency and REACH registration deadline adherence. Cross-checking against aerospace tier-1 supplier audit schedules and medical device OEM qualification timelines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Magnetic Materials
Sintered Soft Magnetic Material Market
Magnetic Materials
North America Ferrite Magnet Market
Magnetic Materials
Magnetorheological Fluid Market
Magnetic Materials
Nanocrystalline Soft Magnetic Material Market
Magnetic Materials
Europe Magnet Wire Market
Magnetic Materials
Ferromanganese Market
Magnetic Materials
Carbonyl Iron Powder Market
Magnetic Materials
Magnet Buffer Market
Magnetic Materials
Global Magnetic Beads Market
Magnetic Materials
Ferrite Magnet Market
Magnetic Materials
Global Soft Magnetic Composites (Smcs) Market
Magnetic Materials
Asia-Pacific Magnet Wire Market
Magnetic Materials
Sintered Magnet Market
Magnetic Materials
Soft Ferrite Core Market
Magnetic Materials
Cobalt Oxide Market
Magnetic Materials
Magnetic Plastics Market